
 Smart Network Interface Card (Smartnic) Market | 2026-2036
Smart Network Interface Card (Smartnic) Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Network Interface Card (Smartnic) Market Insights
EU energy efficiency directives for data centers is pivoting server architecture decisions toward offload-capable networking silicon. NVIDIA Corporation leverages its DPU-to-GPU integration to dominate AI training clusters. Intel Corporation sustains x86 ecosystem compatibility through programmable adapter roadmaps. Broadcom Inc. anchors high-volume supply through merchant silicon partnerships with hyperscalers.
A Smart Network Interface Card integrates programmable processors—typically FPGA or ASIC-based with onboard DRAM and dedicated packet processing pipelines—to execute network virtualization, encryption, and storage protocols independently of host server CPUs. The 100G SmartNIC product tier captures the dominant share of new data center buildouts as leaf-spine architectures scale to 400G core switching. FPGA-based technology leads in customization-intensive environments such as financial trading and telco edge nodes, while ASIC-based designs compete on power efficiency in cloud-scale deployments. Cloud computing application demand outpaces other segments as Amazon, Microsoft, and Google internalize network function virtualization to reduce CPU tax.
FCC equipment authorization requirements govern electromagnetic compliance for SmartNICs deployed in US telecommunications infrastructure, while NIST cybersecurity frameworks shape federal procurement standards for zero-trust network architectures. The EU AI Act and GDPR cross-border data transfer rules compel European operators to localize packet inspection and encryption offload within regional boundaries. Stakeholders must monitor whether MIIT domestic substitution mandates in China fragment global supply chains for programmable networking silicon.
Market Dynamics
Hyperscale cloud operators are internalizing network function virtualization to eliminate CPU tax, forcing merchant silicon vendors to rearchitect around DPU-to-accelerator integration rather than standalone NIC sales.
Growth Catalysts
- EU AI Act data localization mandates:European operators must deploy packet inspection and encryption offload within regional boundaries, creating captive demand for sovereign-compliant SmartNIC architectures.
- 100G leaf-spine buildouts:Data center architects are standardizing on 100G SmartNICs as the baseline for new server racks, displacing 25G and 50G legacy deployments.
- Financial trading latency arbitrage:FPGA-based SmartNICs capture order flow processing in Chicago, London, and Singapore co-location facilities where microsecond advantages determine profitability.
Market Restraints
- Advanced node wafer scarcity:TSMC and Samsung foundry allocation for 7nm and below process nodes constrains ASIC-based SmartNIC production ramps.
- MIIT domestic substitution mandates:China's push for indigenous programmable networking silicon fragments supply chains and locks foreign vendors out of state-owned carrier procurement.
- Host CPU integration threat:AMD and Intel are embedding equivalent network offload engines directly into server processor dies, compressing the attach rate for discrete cards.
Strategic Opportunities
- India data center localization:The country's digital sovereignty push and PLI scheme incentives create greenfield demand for domestic SmartNIC assembly and certification.
- Telecom edge node virtualization:Open RAN deployments at cell tower aggregation points require programmable packet processing for fronthaul timing and security.
- NIST zero-trust architecture compliance:Federal procurement standards for encrypted east-west traffic in civilian agencies mandate hardware offload for cryptographic operations.
Industry Challenges
- Embedded systems-to-networking talent gap:Vendors struggle to hire engineers fluent in both Verilog/VHDL and kernel-bypass networking stacks like DPDK and RDMA.
- FCC equipment authorization timelines:Electromagnetic compliance testing for 400G PAM4 signaling extends certification cycles by four to six months versus prior generations.
- Legacy orchestration integration:SmartNIC management APIs must map to existing VMware, Kubernetes, and OpenStack control planes without disrupting operational workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Network Interface Card (Smartnic) Market |
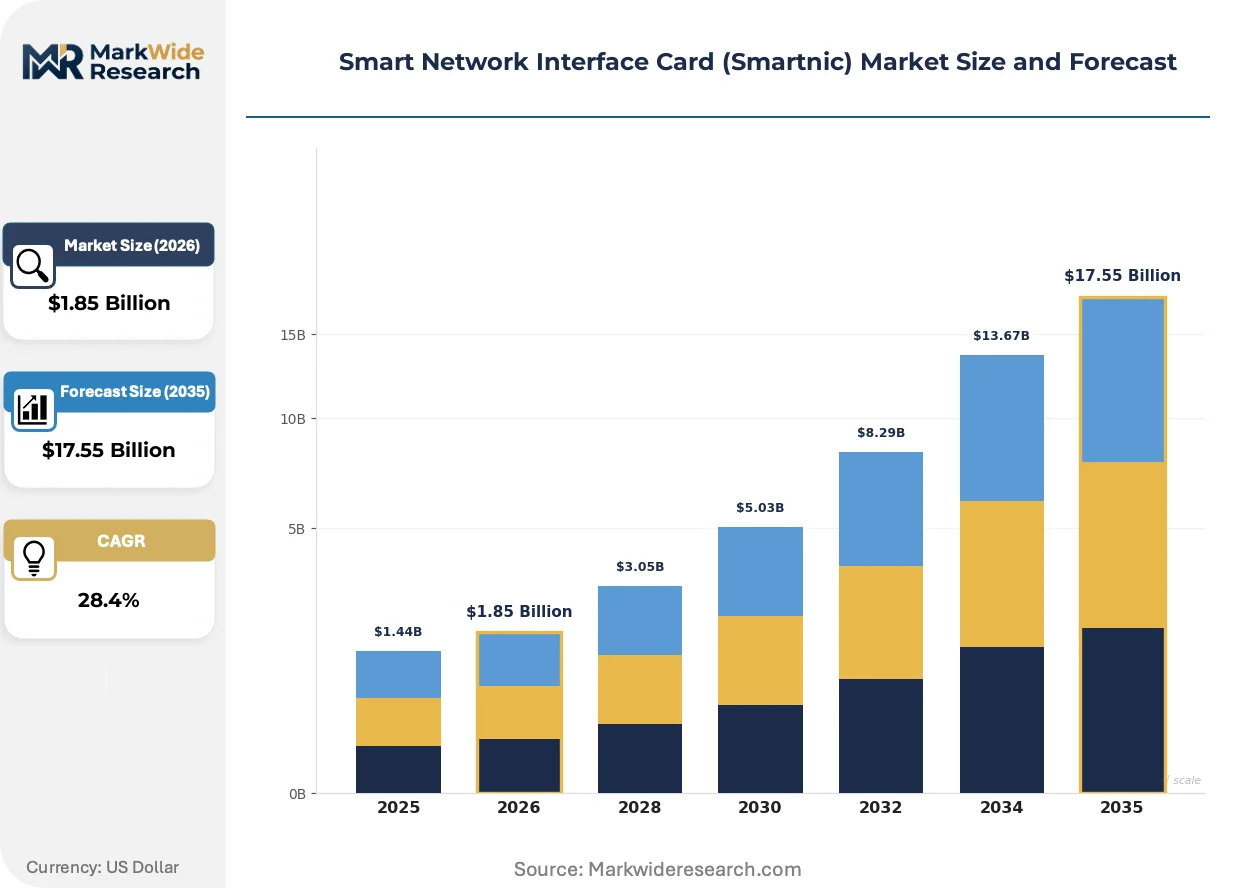
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $17.55 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 10G SmartNIC, 25G SmartNIC, 40G SmartNIC, 100G SmartNIC Technology: FPGA, ASIC, RDMA, TCP/IP Offload Application: Cloud Computing, Data Center, Virtualization, Edge Computing End User: Telecommunications, BFSI, Healthcare, Manufacturing |
| Companies Covered | NVIDIA Corporation, Intel Corporation, Broadcom Inc., AMD (Xilinx), Marvell Technology Group, Cisco Systems, Inc., Pensando Systems, Napatech A/S, Netronome Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Network Interface Card (Smartnic) Market Trends and Innovations
Programmable silicon architectures are bifurcating between customization-intensive FPGA deployments and power-optimized ASIC mass production, with the boundary shifting as hardened functions commoditize.
ASIC-based SmartNICs with fixed-function pipelines for RDMA, NVMe-oF, and IPsec are overtaking FPGA alternatives in cloud-scale deployments where workload predictability allows silicon specialization. Amazon Web Services, Microsoft Azure, and Google Cloud have each developed internal ASIC programs to displace merchant silicon. This compression is forcing FPGA vendors to retreat into financial services and defense applications where bitstream reprogrammability justifies power and cost premiums.
The EU AI Act's cross-border data transfer restrictions are mandating localized packet inspection and encryption offload within European member state boundaries. Operators in Frankfurt, Amsterdam, and Dublin are redesigning server architectures to keep sensitive inference traffic on regional silicon. GDPR Article 44 compliance now functions as a procurement filter that disqualifies SmartNICs without auditable supply chain provenance.
Hyperscalers are unbundling SmartNIC procurement from server OEM bundles and contracting directly with semiconductor vendors for multi-year volume commitments. Dell, HPE, and Lenovo are losing attach rate control as cloud operators specify bare-metal configurations and source networking silicon separately. This disintermediation is most advanced in the United States, where AWS, Azure, and Google operate captive integration labs that bypass traditional channel distribution.
Smart Network Interface Card (Smartnic) Market Segmentation
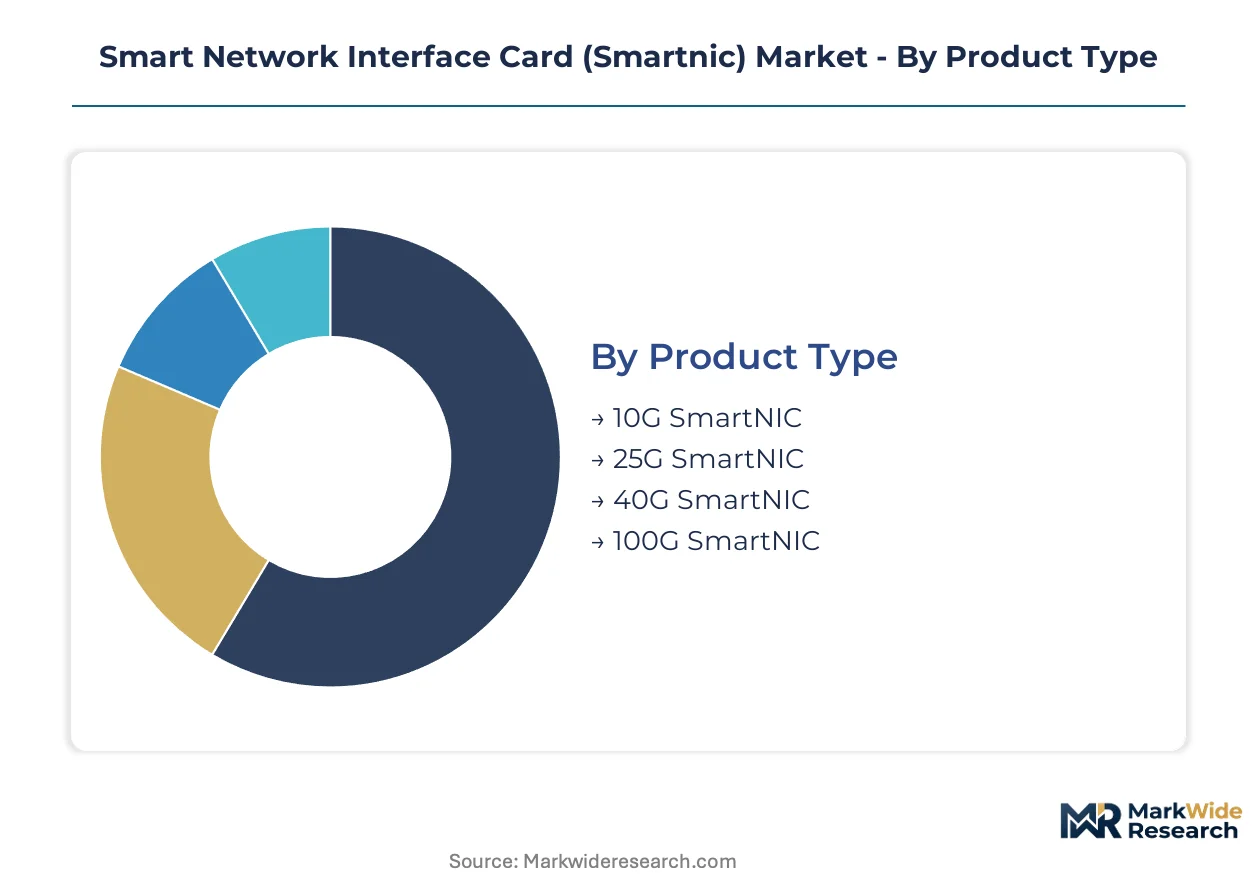
SmartNIC procurement decisions hinge on bandwidth requirements, workload predictability, and regulatory compliance scope. Buyers evaluate programmable versus fixed-function silicon based on whether network functions demand customization or standardization at scale.
Product Type:
Data center architects select port speed based on leaf-spine tier positioning and server refresh cycles.
- 100G SmartNIC:These adapters dominate new hyperscale rack deployments with PAM4 signaling and 400G upstream switching compatibility. Amazon Web Services, Microsoft Azure, and Google Cloud specify 100G as baseline for compute nodes in United States facilities, driven by CPU offload efficiency mandates.
- 25G SmartNIC:Legacy enterprise data centers continue 25G deployments where 100G switching backbones remain unprovisioned. Financial services firms in Chicago and London co-location facilities favor 25G FPGA variants for latency-sensitive trading stacks.
- 10G SmartNIC:Edge computing nodes and industrial IoT gateways deploy 10G variants where power budgets constrain higher-speed optics.
- 40G SmartNIC:Transitional tier bridging 25G server ports to 100G fabrics in mid-scale cloud deployments.
Volume sits with 100G SmartNIC; growth tilts toward 100G SmartNIC as hyperscale buildouts accelerate.
Technology:
Silicon architecture selection determines power efficiency against reprogrammability tradeoffs.
- ASIC:Fixed-function pipelines deliver lowest watts per gigabit for predictable RDMA and NVMe-oF workloads. Cloud operators in United States and European Union facilities standardize on ASIC-based designs where workload homogeneity justifies silicon specialization.
- FPGA:Bitstream reprogrammability enables protocol customization for defense and financial trading applications. FPGA deployments concentrate in Singapore and Frankfurt where microsecond latency arbitrage justifies power premiums.
- RDMA:Remote direct memory access technology eliminates CPU involvement in data transfers between server clusters.
- TCP/IP Offload:Dedicated engines handle packet processing for legacy applications without kernel bypass requirements.
ASIC captures the largest shipment volumes; FPGA maintains premium positioning in customization-intensive segments.
Application:
Workload location dictates whether SmartNICs process traffic in centralized facilities or distributed edge nodes.
- Cloud Computing:Hyperscale operators internalize network function virtualization to eliminate CPU tax on host processors. United States-based Amazon Web Services, Microsoft Azure, and Google Cloud drive dominant demand for high-volume ASIC procurement.
- Data Center:Enterprise colocation facilities deploy SmartNICs for software-defined networking and storage disaggregation.
- Virtualization:Network function virtualization platforms leverage SmartNIC programmability for multi-tenant isolation.
- Edge Computing:Cell tower aggregation points and factory floor nodes require low-power packet processing for latency-constrained workloads.
Cloud computing commands current procurement volumes; edge computing is climbing the fastest as Open RAN deployments expand.
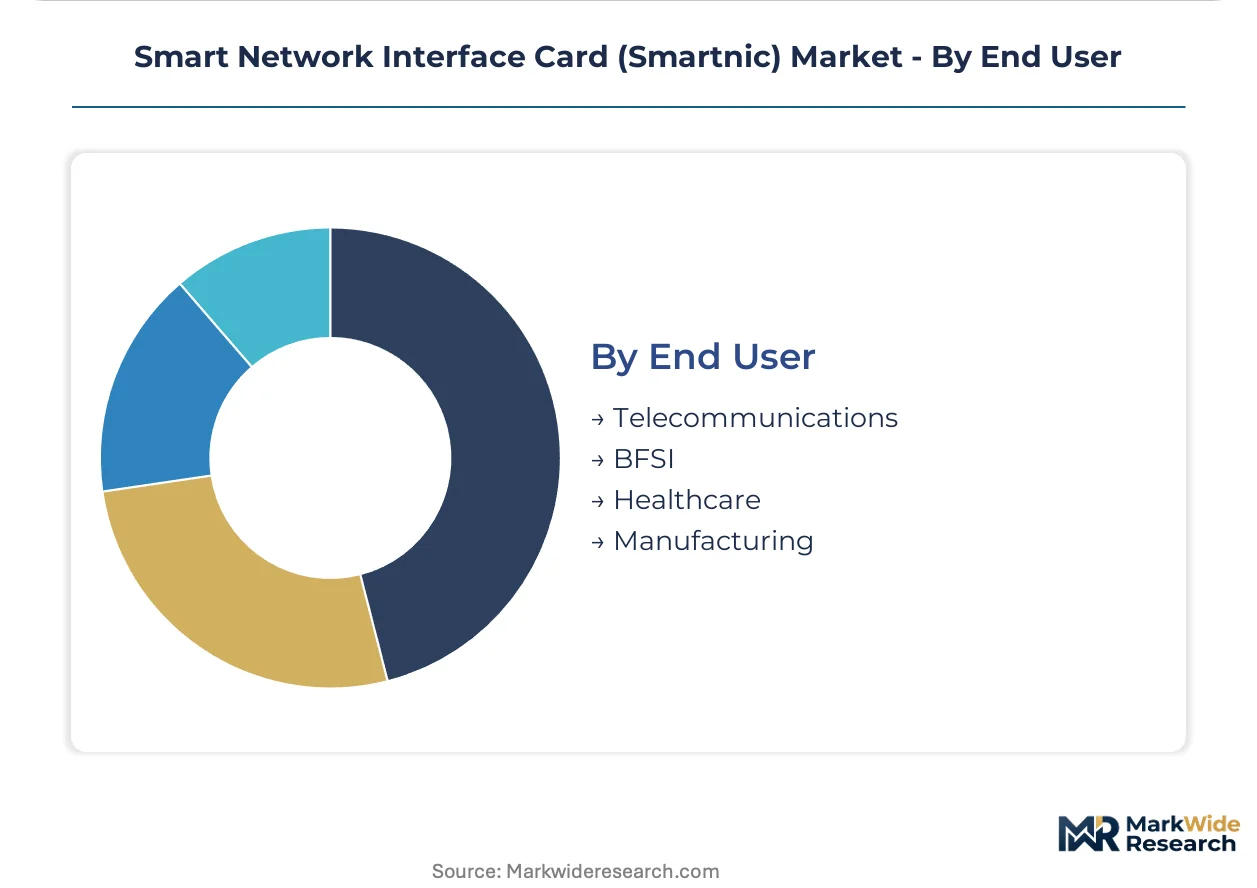
End User:
Industry verticals impose distinct compliance and performance requirements on networking silicon.
- Telecommunications:Carriers deploying Open RAN architectures require programmable fronthaul timing and security offload at cell tower aggregation points. European operators face EU AI Act data localization mandates that restrict cross-border traffic inspection.
- BFSI:Financial institutions in Chicago, London, and Singapore co-location facilities deploy FPGA SmartNICs for order flow processing where microsecond advantages determine profitability.
- Healthcare:HIPAA compliance drives encrypted east-west traffic requirements in United States hospital systems.
- Manufacturing:Industrial automation networks leverage SmartNICs for deterministic Ethernet and time-sensitive networking protocols.
Telecommunications generates the steepest expansion trajectory; BFSI maintains premium pricing tolerance for latency-optimized silicon.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco Bay Area hyperscaler campuses drive dominant procurement volumes for programmable networking silicon, with cloud operators specifying bare-metal server configurations that bypass traditional OEM channels.
United States
Amazon Web Services, Microsoft Azure, and Google Cloud operate the world's largest data center footprints across Northern Virginia, Oregon, and Iowa. NIST cybersecurity frameworks mandate hardware cryptographic offload for federal zero-trust architectures. Northern Virginia's Ashburn-Dulles corridor hosts the densest concentration of SmartNIC deployment for east-west traffic encryption in civilian agencies.
China
MIIT domestic substitution mandates accelerate indigenous DPU development for state-owned carrier networks. National data center clusters in Guizhou and Inner Mongolia prioritize programmable silicon with auditable supply chains. Shanghai's Pudong district anchors merchant silicon partnerships for cloud operators navigating localization requirements.
Germany
EU AI Act data localization rules compel Frankfurt and Munich operators to deploy packet inspection within regional boundaries. GDPR Article 44 compliance functions as a procurement filter for sovereign-compliant architectures. The Rhine-Main metropolitan region concentrates financial services demand for latency-optimized FPGA deployments in co-location facilities.
India
Data center localization requirements under the Digital Personal Data Protection Act create greenfield demand for domestic SmartNIC assembly. PLI scheme incentives attract semiconductor packaging investments for programmable networking silicon. Mumbai and Chennai metropolitan regions anchor hyperscaler buildouts requiring 100G leaf-spine compatibility.
Singapore
Financial trading latency arbitrage drives FPGA SmartNIC procurement for order flow processing in Marina Bay co-location facilities. MAS technology risk management guidelines mandate hardware security modules for cross-border payment infrastructure. The island-state's submarine cable landing points concentrate demand for programmable packet processing at financial exchange proximity.
Smart Network Interface Card (Smartnic) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across silicon architecture specialization, with DPU-to-accelerator integration commanding pricing power over standalone NIC sales. The vendor base organizes around three strategic archetypes: GPU-integrated platform vendors, merchant silicon specialists, and hyperscale captive designers. Consolidation pressure intensifies as cloud operators internalize ASIC programs and disintermediate traditional server OEM bundles. Dominant competitive moves include multi-year volume contracting directly with semiconductor foundries and backward integration into custom silicon design.
Within the GPU-integrated platform tier, NVIDIA Corporation anchors premium positioning through DPU-to-GPU ecosystem control. Intel Corporation and Broadcom Inc. occupy positions across the merchant silicon spectrum, with the former sustaining x86 compatibility advantages and the latter anchoring high-volume supply through hyperscaler partnerships. These three entities exemplify the competitive tension between platform integration and merchant silicon specialization reshaping procurement patterns.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Intel Corporation |
| Broadcom Inc. |
| AMD (Xilinx) |
| Marvell Technology Group |
| Cisco Systems, Inc. |
| Pensando Systems |
| Napatech A/S |
| Netronome Systems |
| Others |
Pricing and Supply Chain Analysis
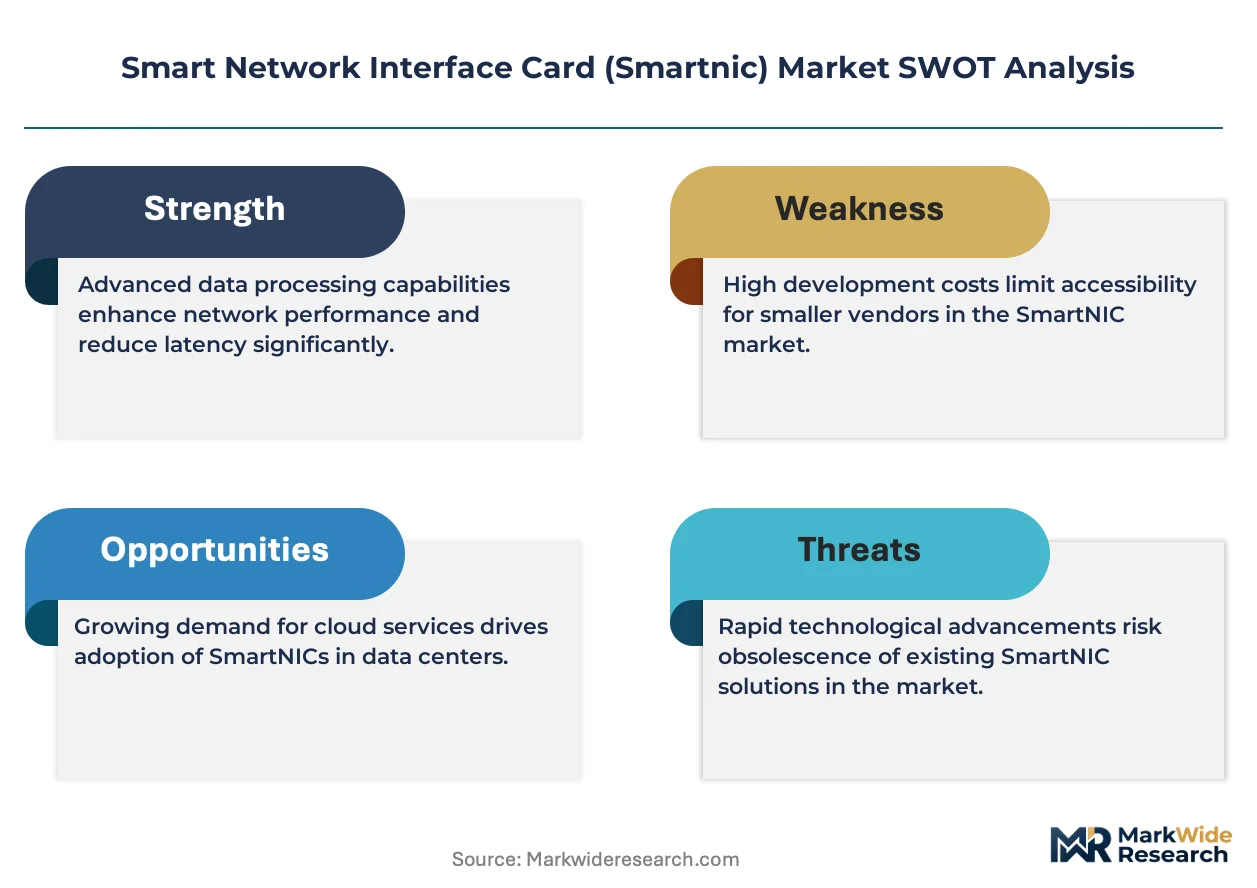
TSMC's 7nm wafer pricing index cascades through SmartNIC manufacturing tiers, compressing margins for ASIC-based designs while FPGA variants absorb cost premiums through customization value capture in financial trading and defense applications.
Pricing Analysis
Throughput-per-watt benchmarks anchor value-based pricing for hyperscale procurement contracts. Three-tier pricing structure across premium, standard, and economy levels separates DPU-GPU integrated platforms from merchant silicon adapters and legacy TCP/IP offload cards. Cost compression in standard-tier ASICs is intensifying because cloud operators internalize silicon design and disintermediate server OEM bundles. Hyperscale cloud operators exhibit lowest price sensitivity due to captive integration labs, while mid-tier enterprise colocation facilities face acute budget constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand, though cloud operators increasingly contract foundries directly for multi-year wafer commitments. Taiwan, South Korea, and the United States concentrate advanced node fabrication for programmable networking silicon. Supply chains draw from 7nm and 5nm wafer supply, high-bandwidth memory modules, and PAM4 optical transceivers. Single-source vulnerability at TSMC for sub-7nm production creates structural risk for merchant silicon vendors. Distribution runs through server OEM bundles, direct semiconductor procurement, and channel partners serving enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity constraints at TSMC and Samsung prop pricing power for vendors with secured wafer allocations, creating a supply-constrained market structure favoring incumbents with multi-year volume commitments.
For Market Incumbents: Acquire FPGA design teams with Verilog/VHDL and kernel-bypass networking expertise to close the embedded systems-to-networking talent gap. Secure 5nm wafer allocations through multi-year foundry contracts before capacity tightens further. AMD and Intel's embedded network offload engines threaten discrete card attach rates, demanding backward integration into custom silicon design to maintain differentiation. For New Entrants and Emerging Players: Enter via India's PLI scheme incentives for domestic SmartNIC assembly and certification under the Digital Personal Data Protection Act. Target telecom edge node virtualization for Open RAN deployments at cell tower aggregation points, where programmable fronthaul timing creates greenfield demand. Position around NIST zero-trust architecture compliance for federal civilian agency procurement. For Investors and Strategic Acquirers: The window for entry favors vertically integrated platform vendors with DPU-to-GPU ecosystem control over standalone merchant silicon specialists. Long-term viability hinges on securing foundry partnerships and hyperscaler design wins within the next capacity expansion cycle. Monitor MIIT domestic substitution mandates in China as fragmentation signal for global supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Foundry Volume Commitment | Secures 5nm wafer allocation from TSMC ahead of hyperscaler captive programs. |
| DPU-to-GPU Platform Integration | NVIDIA's ecosystem control commands premium pricing in AI training clusters. |
| EU AI Act Compliance Certification | GDPR Article 44 provenance requirements filter sovereign-compliant architectures in Frankfurt. |
| India PLI Scheme Localization | Domestic assembly incentives attract semiconductor packaging investments in Mumbai. |
| Open RAN Edge Node Virtualization | Programmable fronthaul timing captures cell tower aggregation point demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with data center architects, semiconductor procurement leads, network engineering directors, and cloud platform engineers validated demand assumptions. FCC equipment authorization databases, NIST cybersecurity framework documentation, EU AI Act regulatory texts, and hyperscaler capex disclosures provided secondary triangulation. Bottom-up server shipment models and top-down programmable silicon revenue estimates were reconciled to cross-check volume assumptions.
Shipment and revenue streams were reconciled across product type, technology architecture, application workload, and end-user vertical dimensions over the projection horizon. CAGRs were derived from installed base replacement cycles, hyperscale buildout pipelines, and edge computing deployment trajectories. Foundry capacity expansion schedules, EU data localization enforcement timelines, and Open RAN deployment roadmaps informed industry-specific forecast inputs.
Revisions become necessary when foundry allocation priorities shift, MIIT domestic substitution mandates expand, or host CPU integration accelerates beyond current roadmaps. Forecasts reflect assumptions about hyperscaler internalization trends, regulatory enforcement consistency, and talent availability for programmable silicon development. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
ISP Management Systems Market
Network Technology
Hyperconnectivity Market
Network Technology
DNS DHCP and IPAM Market
Network Technology
Global Network Probe Market
Network Technology
Europe Video Conferencing Hardware Market
Network Technology
Germany Residential Gateway Market
Network Technology
Fiber to the Home (FTTH) Market
Network Technology
Global Wireless Router Market
Network Technology
Structured Cabling Market
Network Technology
Europe Structured Cabling Market
Network Technology
Router and Switch Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
Global Intelligent Network Market
Network Technology
Small Cell Networks Market
Network Technology
Network Management Solutions Market
Network Technology
IT Connector Market