
 Bulk Bag Divider Market | 2026-2036
Bulk Bag Divider Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Bag Divider Market Outlook
ISO 21898 certification for flexible intermediate bulk containers is bifurcating the competitive landscape into qualified and non-qualified supplier tiers. Greif leverages its integrated manufacturing footprint across multiple continents to sustain bulk bag divider supply contracts with multinational chemical processors. Berry Global differentiates through advanced polymer science capabilities that extend product durability in multi-use configurations. LC Packaging anchors European demand with regional production hubs and established distributor relationships.
Bulk bag dividers are structural inserts or internal partitioning systems installed within flexible intermediate bulk containers to prevent cargo shifting, enable multi-product transport, and maintain load stability during handling; these components typically incorporate woven polypropylene fabric, corrugated plastic sheets, or composite laminates engineered to specific tensile strength and dimensional tolerances for industrial bulk logistics. Multi-use fabric dividers command premium positioning due to wash-down compatibility and extended duty cycles that reduce per-trip packaging costs for chemical and food-grade applications. Single-use plastic variants occupy high-volume, cost-sensitive segments in construction and agricultural distribution where contamination risks favor disposal over sanitation protocols.
FDA food-contact regulations and EU REACH chemical compliance frameworks shape material selection and surface treatment requirements for bulk bag dividers serving food processing and pharmaceutical ingredient supply chains. OSHA material handling standards in the United States and CE machinery directives in Europe further constrain design parameters for divider integration with automated filling and discharge equipment. Stakeholders must monitor evolving extended producer responsibility legislation in key manufacturing jurisdictions to anticipate retrofit obligations and qualification recertification cycles.
Market Dynamics
ISO 21898 certification mandates are bifurcating supplier tiers, forcing chemical processors and food manufacturers to requalify their entire bulk bag divider supply bases while non-certified producers face contract erosion.
Growth Catalysts
- REACH chemical compliance frameworks:European chemical processors must upgrade divider materials to eliminate restricted substances, creating replacement demand for certified woven polypropylene and composite laminate systems.
- Multi-product transport economics:Agricultural distributors in the United States are installing internal partitioning systems to consolidate mixed fertilizer shipments, reducing per-ton logistics costs.
- Wash-down compatible fabrics:Food-grade polymer science advances enable multi-use divider cycles exceeding fifty trips, cutting per-trip packaging expenditure for ingredient suppliers.
Market Restraints
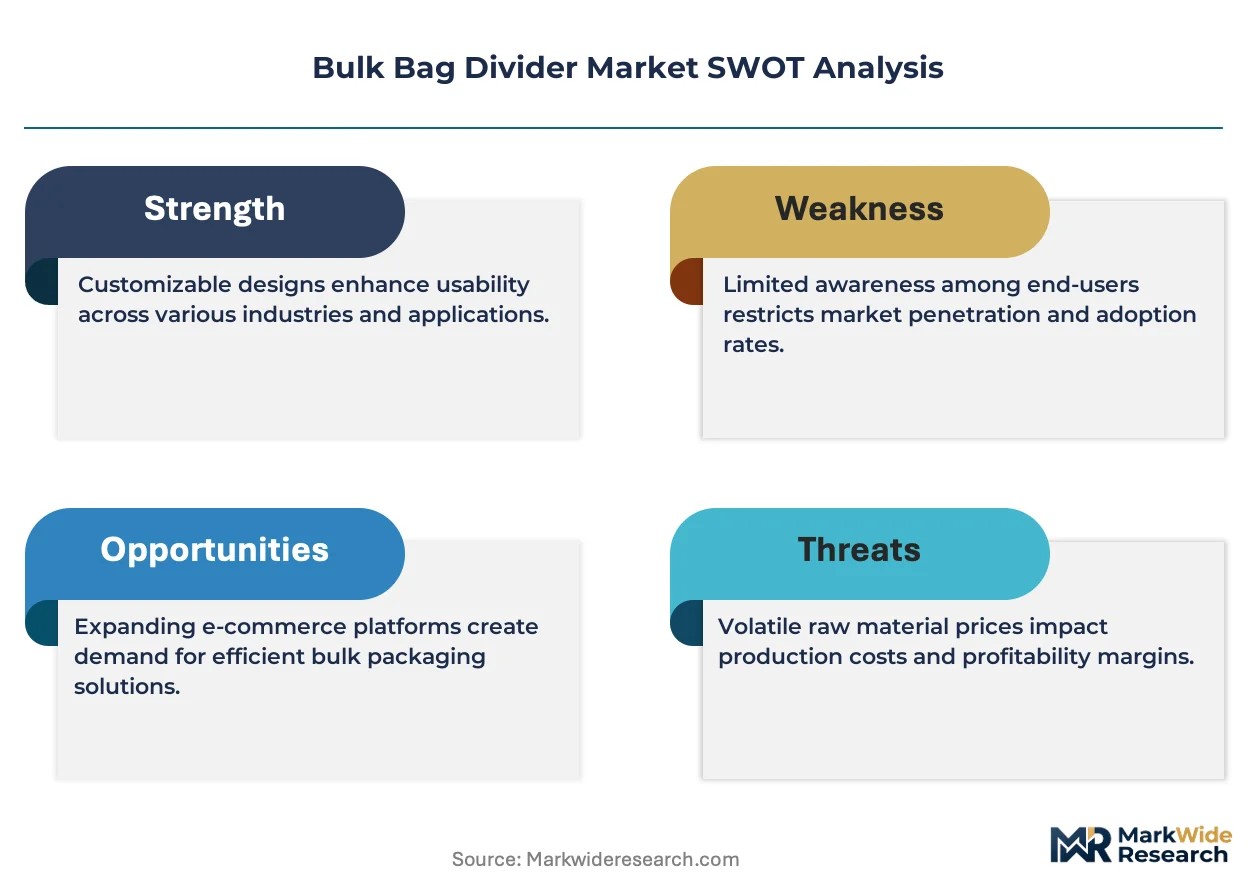
- Polypropylene resin price volatility:Feedstock cost swings compress margins for woven fabric producers who cannot pass through increases to long-term contract customers.
- Supplier concentration in German manufacturing clusters:Three integrated producers control regional ISO 21898 qualified capacity, creating allocation risk during demand surges.
- Corrugated plastic substitution limits:Rigid sheet dividers lack the flexibility for automated filling equipment integration, constraining adoption in high-speed chemical processing lines.
Strategic Opportunities
- Indian pharmaceutical ingredient export growth:CDSCO compliance requirements for bulk active pharmaceutical ingredient transport are creating first-mover advantage for certified divider suppliers establishing local production.
- RFID-embedded fabric tracking:Convergence of woven polypropylene with passive sensor technology enables lifecycle monitoring and predictive replacement scheduling for multi-use fleets.
- Extended producer responsibility legislation:EU Green Deal packaging waste directives will mandate take-back programs, favoring suppliers with closed-loop recycling infrastructure.
Industry Challenges
- ISO 21898 recertification timelines:Three-year qualification cycles demand sustained engineering documentation and third-party testing expenditure that strains mid-tier supplier cash flows.
- Automated filling equipment integration:Legacy mechanical handling systems in agricultural cooperatives require custom divider geometries that extend engineering lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Bag Divider Market |
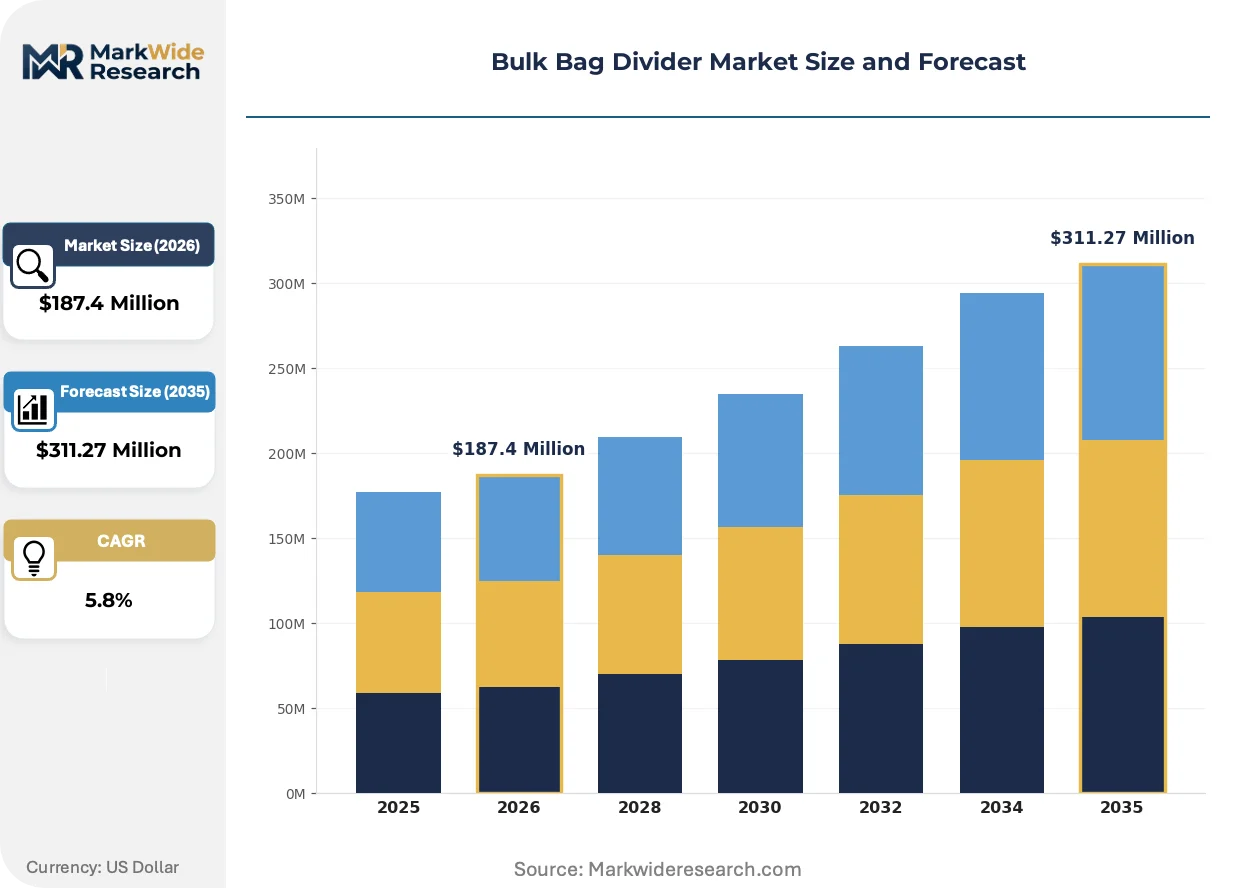
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Multi-Use, Custom, Standard Material: Plastic, Metal, Fabric, Composite Application: Agriculture, Food & Beverage, Chemical, Construction End User: Manufacturers, Distributors, Retailers, Wholesalers |
| Companies Covered | Greif, Berry Global, LC Packaging, Conitex Sonoco, BAG Corp, Bulk-Pack, Intertape Polymer Group, AmeriGlobe, Rishi FIBC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Bag Divider Market Strategic Shifts
Material science convergence with digital tracking systems is restructuring how bulk bag dividers are specified, procured, and managed across industrial supply chains.
Antimicrobial woven polypropylene treatments are decomposing the traditional separation between food-grade and chemical-grade divider specifications. Pharmaceutical ingredient suppliers in Switzerland and Germany are adopting these hybrid fabrics to simplify inventory management. The technology is decomposing established product category boundaries that previously required dedicated manufacturing lines.
EU REACH substance restriction updates are forcing reformulation of plasticizer additives in corrugated divider sheets. German chemical processors must validate alternative slip agents by Q3 2025 or risk supply interruption. Food-contact applications face the tightest compliance windows, with several ingredient distributors accelerating supplier audits.
Buyers are consolidating vendor relationships around full-service packaging system providers who design dividers concurrently with outer bag specifications. Agricultural cooperatives in the United States Midwest are abandoning component sourcing in favor of integrated FIBC assembly contracts. This pattern concentrates procurement authority with technical buyers who specify performance outcomes rather than material grades.
Bulk Bag Divider Market Segmentation
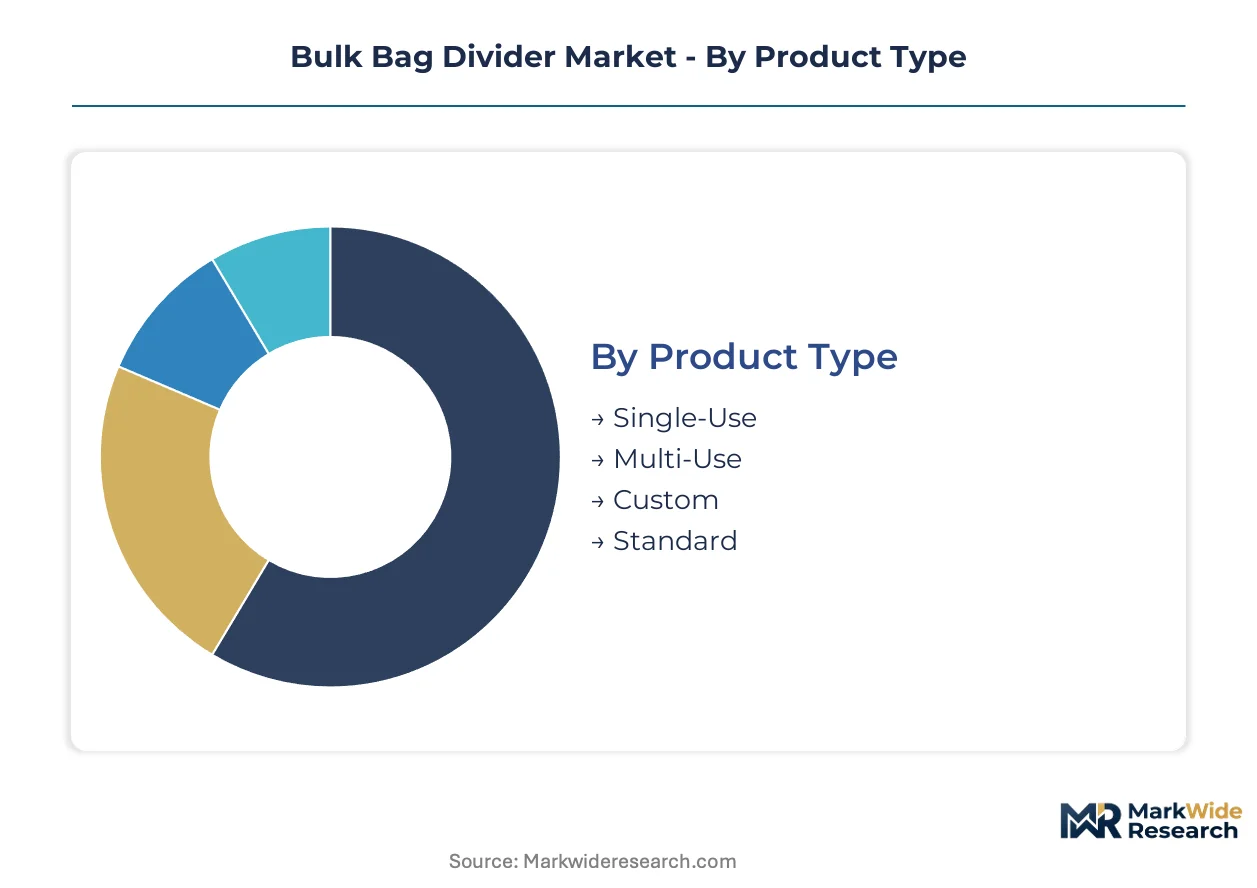
Segmentation in the bulk bag divider market reflects divergent compliance burdens and operational economics across industrial supply chains. Procurement teams specify product tiers based on wash-down protocols, chemical exposure profiles, and automated handling requirements rather than unit cost alone.
Product Type:
Regulatory differentiation separates single-use disposables from validated multi-use systems, with ISO 21898 certification acting as the primary gating mechanism for supplier qualification.
- Multi-Use:Engineered woven polypropylene fabrics with reinforced seam welding withstand fifty-plus duty cycles with full wash-down sanitation. Chemical processors in Germany and food ingredient suppliers in Switzerland are consolidating procurement around these systems to amortize qualification costs across extended service lives.
- Single-Use:Extruded corrugated plastic or non-woven fabric variants designed for contamination-sensitive agricultural chemicals and construction aggregates where disposal costs undercut sanitation infrastructure investment. Distributors in the United States Midwest favor these for seasonal fertilizer campaigns with unpredictable volume spikes.
- Custom:Geometric adaptations for automated filling equipment integration, typically specified by pharmaceutical ingredient manufacturers requiring precise dimensional tolerances for active pharmaceutical ingredient containment.
- Standard:Off-the-shelf rectangular or circular partition geometries serving high-volume commodity chemical transport with minimal equipment interface complexity.
Multi-Use handles the majority of throughput; Single-Use is expanding most quickly in agricultural distribution networks.
Material:
Cost tier stratification aligns material selection with end-use durability requirements and regulatory exposure, with premium composites commanding three-to-four times the unit economics of commodity plastics.
- Fabric:Woven polypropylene with UV-stabilized masterbatch dominates food-grade and chemical applications requiring flexibility for automated handling systems. REACH-compliant formulations from German compounders are displacing Asian-sourced alternatives in European pharmaceutical supply chains.
- Composite:Laminated structures combining fabric substrates with moisture barriers or conductive layers for electrostatic-sensitive chemical powders. Swiss pharmaceutical packaging specialists specify these for high-value active pharmaceutical ingredient transport.
- Plastic:Extruded corrugated polypropylene sheets serving construction aggregate and agricultural markets where rigidity and moisture resistance outweigh flexibility requirements.
- Metal:Stainless steel or aluminum framing inserts for extreme load stabilization in heavy mineral processing, limited to niche mining and metallurgical applications with specialized handling infrastructure.
Fabric commands the dominant procurement volume; Composite is climbing the fastest on share as pharmaceutical compliance requirements tighten.
Application:
Volume concentration in chemical processing creates procurement scale effects that reshape supplier capacity allocation and certification investment priorities.
- Chemical:Acid-resistant fabric treatments and conductive composite formulations for hazardous material containment. OSHA process safety management mandates in the United States and Seveso III directives in Europe require documented divider compatibility with emergency response protocols.
- Agriculture:Seasonal demand spikes for fertilizer and seed partitioning drive spot purchasing patterns. Agricultural cooperatives in Iowa and Illinois are consolidating around integrated FIBC assembly contracts rather than component sourcing.
- Food & Beverage:FDA food-contact substance compliance and EU Regulation 1935/2004 frame material selection for ingredient transport. Dairy powder and starch distributors specify antimicrobial woven treatments validated for repeated wash-down cycles.
- Construction:Cost-optimized corrugated plastic dividers for cement, lime, and aggregate shipment where moisture protection and disposal economics outweigh multi-use sanitation requirements.
Chemical handles the majority of throughput; Food & Beverage is gaining share fastest as clean-label supply chain documentation requirements proliferate.
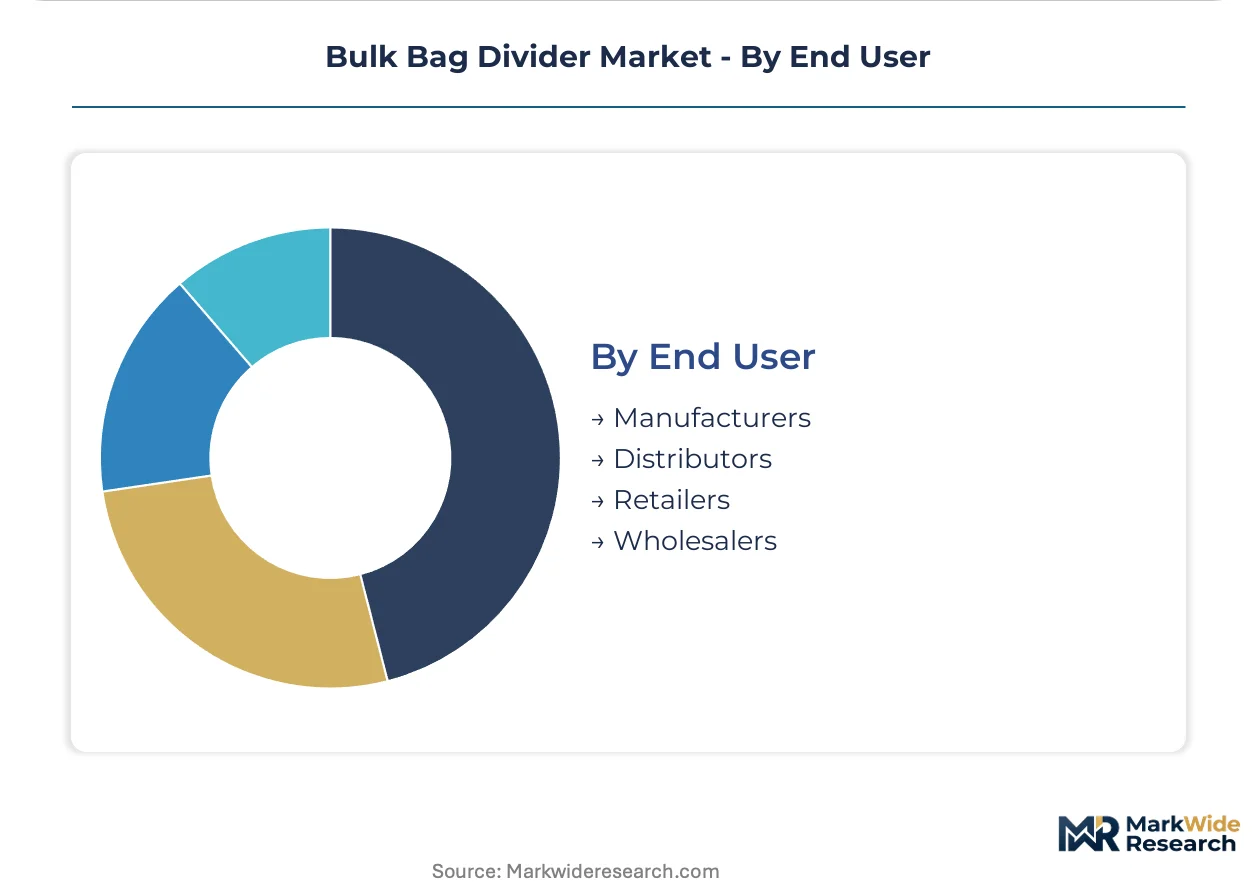
End User:
Customer type determines specification authority, with technical buyers at integrated manufacturers exercising tighter control over material grades and certification documentation than procurement generalists at trading intermediaries.
- Manufacturers:Direct specification of divider performance parameters concurrent with outer FIBC design, typical of multinational chemical and pharmaceutical producers with captive packaging engineering teams.
- Distributors:Consolidated vendor relationships favoring full-service packaging system providers who assume design liability and regulatory documentation burdens.
- Wholesalers:Transactional procurement of standard geometries with minimal customization, serving spot market demand from smaller agricultural and construction customers.
- Retailers:Limited direct involvement in bulk bag divider specification, typically delegating packaging decisions to private-label contract manufacturers or co-packers.
Manufacturers handle the majority of throughput; Distributors are expanding most quickly as agricultural supply chains consolidate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical processors and agricultural distributors concentrate procurement authority in manufacturing clusters where ISO 21898 qualified capacity sits closest to filling operations. Buyers in Germany, the United States, and China exercise specification control over divider geometries and material grades.
Germany
REACH substance restrictions and Seveso III emergency response mandates compel chemical processors to requalify divider materials quarterly. The country's national chemical regulator enforces documented compatibility protocols for hazardous powder containment. The Rhine-Ruhr industrial corridor hosts BASF and Bayer facilities that specify conductive composite laminates for electrostatic-sensitive active pharmaceutical ingredients.
United States
OSHA process safety management standards and seasonal fertilizer distribution spikes drive divergent procurement patterns between chemical and agricultural end users. FDA food-contact substance regulations constrain material selection for dairy powder and starch transport. The Iowa-Illinois agricultural belt consolidates around integrated FIBC assembly contracts rather than component sourcing.
China
Dual carbon goals and GB standards for hazardous material packaging redirect state-owned chemical enterprises toward qualified multi-use fabric systems. The Ministry of Ecology and Environment enforces stricter waste reduction targets on bulk packaging. The Yangtze River Delta chemical cluster in Jiangsu and Zhejiang provinces scales domestic production of REACH-compliant woven polypropylene.
Switzerland
Swissmedic pharmaceutical transport guidelines and clean-label supply chain documentation requirements elevate divider specifications for high-value active pharmaceutical ingredients. The national pharmaceutical regulator mandates batch-level traceability for ingredient packaging. Basel's pharmaceutical packaging specialists specify antimicrobial woven treatments that decompose traditional food-grade and chemical-grade boundaries.
India
CDSCO compliance requirements for bulk active pharmaceutical ingredient export create first-mover advantage for certified suppliers establishing local production. The national pharmaceutical regulator tightens packaging validation protocols for European and North American shipments. Gujarat's pharmaceutical manufacturing cluster in Ahmedabad and Vadodara accelerates supplier audits for ISO 21898 qualified dividers.
Bulk Bag Divider Market Competitive Environment
Player mix skews toward integrated packaging conglomerates with captive FIBC manufacturing and regional fabric specialists serving spot agricultural demand. Three integrated producers control German ISO 21898 qualified capacity, creating allocation risk during demand surges. Strategic archetypes include multinational full-service providers, regional fabric specialists, and polymer science innovators. Capacity expansion and strategic partnerships dominate competitive moves as suppliers defend long-term chemical processor contracts.
Within the integrated packaging tier, Greif and Berry Global exemplify multinational scale advantages through continental manufacturing footprints and polymer science capabilities. LC Packaging anchors European demand with regional production positioning. Among fabric specialists, Rishi FIBC represents the regional archetype serving agricultural spot markets with standardized geometries. These named entities occupy positions across the supplier qualification spectrum without specific product or technology claims beyond market-visible archetype patterns.
| Leading Market Players |
|---|
| Greif |
| Berry Global |
| LC Packaging |
| Conitex Sonoco |
| BAG Corp |
| Bulk-Pack |
| Intertape Polymer Group |
| AmeriGlobe |
| Rishi FIBC |
| Others |
Value Chain & Pricing Dynamics
Sixty-day engineering lead times for custom ISO 21898 qualified dividers concentrate pricing power with German and Chinese integrated producers who control REACH-compliant polypropylene compound formulations. This inventory compression amplifies buyer vulnerability during seasonal agricultural demand surges when spot purchasers compete for allocated fabric capacity.
Pricing Analysis
Cost-plus contracts indexed to polypropylene resin futures dominate procurement between multinational chemical processors and integrated FIBC manufacturers. Three-tier pricing structure across premium certified multi-use, standard single-use, and economy corrugated plastic levels separates qualified from non-qualified supplier tiers. Pricing pressure stems from resin volatility that woven fabric producers cannot fully pass through to long-term contract customers. Agricultural distributors exhibit highest price sensitivity, while Swiss pharmaceutical ingredient suppliers absorb premiums for antimicrobial hybrid fabrics.
Supply Chain Analysis
Inbound logistics costs from Shanghai to Rotterdam spiked during container availability crunches, compressing margins for Asian fabric exporters serving European chemical processors. Supply concentrates in Germany, China, and the United States where integrated producers control ISO 21898 qualified capacity. Raw material dependencies center on polypropylene resin masterbatch, UV stabilizer additives, and conductive carbon black for electrostatic-sensitive applications. Single-source vulnerability runs through German REACH-compliant compounders. Distribution runs through full-service packaging system providers who assume design liability and regulatory documentation burdens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bulk bag divider procurement is shifting toward platform-based integrated FIBC assembly contracts that bundle outer bag specifications with internal partitioning systems. This interoperability convergence favors suppliers who engineer dividers concurrently with automated filling equipment interfaces.
For Market Incumbents: Shield long-term chemical processor contracts by deepening backward integration into REACH-compliant polypropylene compounding in the Rhine-Ruhr corridor. Accelerate RFID-embedded fabric tracking development to lock in multi-use fleet management relationships before sensor-technology specialists enter the market.
For New Entrants and Emerging Players: Differentiate on CDSCO compliance infrastructure for Indian pharmaceutical ingredient export corridors. Gujarat's pharmaceutical cluster presents the most penetrable white-space opportunity. Pursue joint-venture production with established woven fabric specialists to bypass three-year ISO 21898 qualification timelines.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because ISO 21898 certification creates durable supplier moats that compound with each recertification cycle. Target regional fabric specialists with established distributor relationships in agricultural belts. Watch RFID-embedded divider adoption rates as the inflection signal for fleet-management platform economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Compounding | REACH-compliant masterbatch production in Germany secures supply during resin volatility spikes. |
| RFID-Enabled Fabric Tracking Development | Passive sensor convergence with woven polypropylene enables predictive replacement scheduling for multi-use fleets. |
| CDSCO-Certified Production in India | Local ISO 21898 qualified capacity captures pharmaceutical ingredient export growth to European and North American markets. |
| Integrated FIBC Assembly Contracts | Concurrent divider and outer bag design consolidates procurement authority with technical buyers at multinational manufacturers. |
| Antimicrobial Hybrid Fabric Scale-Up | Swiss pharmaceutical packaging specialists are decomposing traditional food-grade and chemical-grade category boundaries. |
Study Parameters
The analysis maps multi-use fabric, single-use plastic, custom geometric, and standard partition configurations, each validated through procurement directors at chemical processors, packaging engineers at pharmaceutical manufacturers, agricultural cooperative logistics managers, and woven fabric compounder technical leads. Primary interview findings triangulated against customs trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from integrated packaging conglomerates, and ISO 21898 certification registry databases. Bottom-up volume estimates from individual facility throughput cross-checked against top-down addressable market calculations.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation modeling incorporated product type durability tiers, material grade compliance levels, application-specific handling requirements, and end-user specification authority patterns. CAGRs derived from weighted average of historical trajectory and forward-looking capacity expansion announcements. Forecast inputs included polypropylene resin price elasticity coefficients and ISO 21898 recertification cycle frequencies.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement, polypropylene supply stability, and automated filling equipment adoption rates would require recalibration. Forecasts reflect documented assumptions about regulatory compliance timelines and material science advancement curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Shrink Bags Market
Bags and Containers
Bin Liners Market
Bags and Containers
Foam Tube Mailer Market
Bags and Containers
Anti-Corrosion Bags Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Vacuum Sealer Bags Market
Bags and Containers
Zipper Bags Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Compression Bags Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Bag Making Machine Market
Bags and Containers
Wicketed Bags Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Bakery Bread Bag Market
Bags and Containers
Nonwoven Containers Market