
 Japan Dangerous Goods Logistics Market | 2026-2036
Japan Dangerous Goods Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Dangerous Goods Logistics Market Insights
Kansai region capacity expansion is tilting toward integrated multimodal dangerous goods terminals. Nippon Express leverages its nationwide depot network to dominate pharmaceutical and chemical flows. Yusen Logistics anchors high-value sea-air transshipment through Yokohama and Kansai airports. LOGISTEED Japan specializes in temperature-controlled hazardous warehousing for the healthcare sector.
Dangerous goods logistics encompasses the specialized transport, storage, and handling of substances classified under international codes for explosive, flammable, toxic, corrosive, or radioactive properties, requiring UN-certified packaging, segregation protocols, and trained personnel certification. Flammable liquids shipments absorb the largest value share due to Japan's petroleum refining and chemical manufacturing base. Air cargo compliance with IATA Dangerous Goods regulations commands premium pricing as pharmaceutical cold-chain volumes rise. Road freight retains volume leadership for last-mile delivery to manufacturing plants and construction sites across Honshu.
METI enforces the Chemical Substances Control Law and Fire Service Act, mandating carrier licensing and route pre-approval for hazardous loads. JIS standards for packaging and vehicle specification create compliance barriers that favor established operators with certified fleets. Stakeholders must weigh capital deployment toward automated dangerous goods sorting against regulatory uncertainty from potential alignment with EU REACH-style transport disclosure rules.
Market Dynamics
METI's Chemical Substances Control Law revisions are compressing carrier certification timelines while pharmaceutical cold-chain volumes surge through Osaka and Tokyo corridors, forcing asset reallocation toward temperature-controlled hazardous infrastructure.
Growth Catalysts
- Pharmaceutical cold-chain expansion:Osaka and Tokyo manufacturers are routing temperature-sensitive biologics through certified dangerous goods channels, requiring UN-certified packaging and trained handlers.
- Keihin industrial corridor concentration:Tokyo Bay port linkages to inland distribution hubs generate sustained demand for multimodal hazardous cargo terminals with bonded warehousing capacity.
- METI enforcement tightening:Revised transport documentation mandates under the Chemical Substances Control Law are filtering out uncertified operators and consolidating volume with licensed carriers.
Market Restraints
- Certified fleet scarcity:JIS-compliant vehicle specifications and driver hazmat credentials create supply bottlenecks that limit rapid capacity scaling.
- Route pre-approval friction:Fire Service Act mandates for hazardous load path clearance add planning lag and reduce operational flexibility for time-sensitive shipments.
- Specialized warehousing capex:Temperature-controlled hazardous storage requires explosion-proof climate systems that carry construction cost premiums over standard cold-chain facilities.
Strategic Opportunities
- Kansai multimodal terminal development:Integrated sea-rail-air dangerous goods hubs around Osaka Bay offer underutilized capacity for pharmaceutical transshipment.
- Healthcare sector verticalization:Temperature-controlled hazardous warehousing for cell therapies and radiopharmaceuticals commands premium positioning.
- Sea-air transshipment corridor expansion:Yokohama and Kansai airport linkages enable high-value pharmaceutical routing that bypasses pure ocean freight transit times.
Industry Challenges
- Certified operator pipeline gaps:Hazmat handler training programs under METI guidelines face enrollment shortfalls that constrain workforce scaling.
- Legacy depot retrofit complexity:Existing Nippon Express and LOGISTEED facilities require segregation system upgrades to meet evolving pharmaceutical segregation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Dangerous Goods Logistics Market |
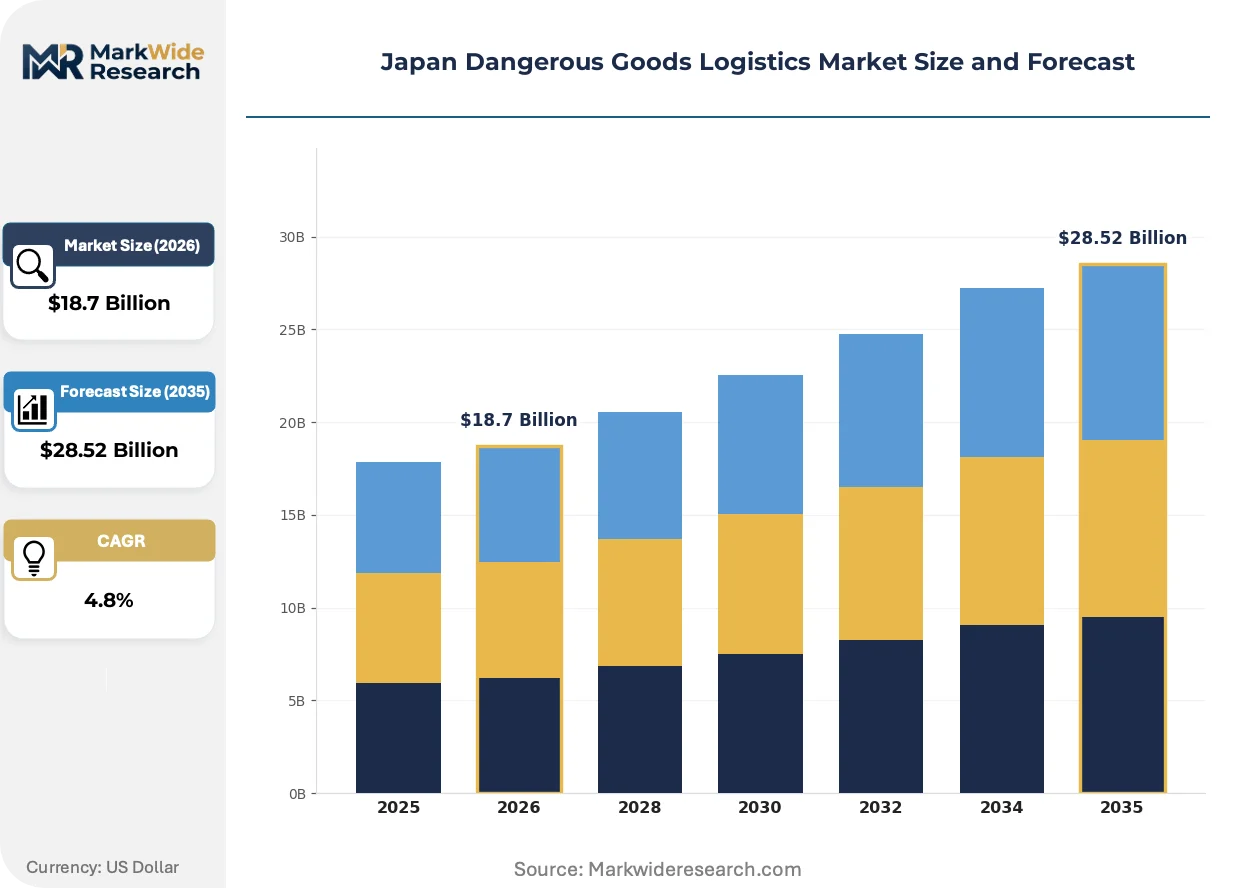
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Explosives, Flammable Liquids, Toxic Substances, Radioactive Materials Transport Method: Road Freight, Air Cargo, Rail Transport, Sea Freight End User: Manufacturing, Healthcare, Construction, Energy Compliance Standard: IMDG Code, ADR Regulations, IATA Dangerous Goods, DOT Hazardous Materials |
| Companies Covered | Kokusai Express, K Line Logistics, KATO Transport, Nippon Express, Yusen Logistics, Yamato Transport, ICL Logistics Japan, LOGISTEED Japan, SAGAWA Global Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Dangerous Goods Logistics Market Trends and Innovations
Automation and regulatory digitization are compressing documentation cycles while rerouting investment toward sensor-enabled compliance infrastructure across Japan's hazardous logistics networks.
Real-time temperature and shock monitoring systems with blockchain-anchored chain-of-custody records are rendering obsolete paper-based dangerous goods declarations for pharmaceutical shipments. Osaka and Tokyo pharmaceutical manufacturers are mandating these systems for contract logistics tenders. The shift is compressing carrier selection criteria toward integrated digital compliance platforms.
METI's alignment discussions with EU REACH-style transport disclosure rules are forcing documentation system overhauls across Japanese chemical logistics operators. The industrial consequence is accelerated IT spending on substance-tracking databases. Pharmaceutical and fine chemical segments are responding by pre-positioning inventory to buffer potential customs clearance delays.
Shippers are consolidating hazardous cargo volumes with single-source logistics providers to reduce handoff liability exposure. Direct contracts with Nippon Express and Yusen Logistics are displacing fragmented broker arrangements. This concentration is most visible in Tokyo Bay pharmaceutical corridors where manufacturers prioritize end-to-end custody control.
Japan Dangerous Goods Logistics Market Segmentation
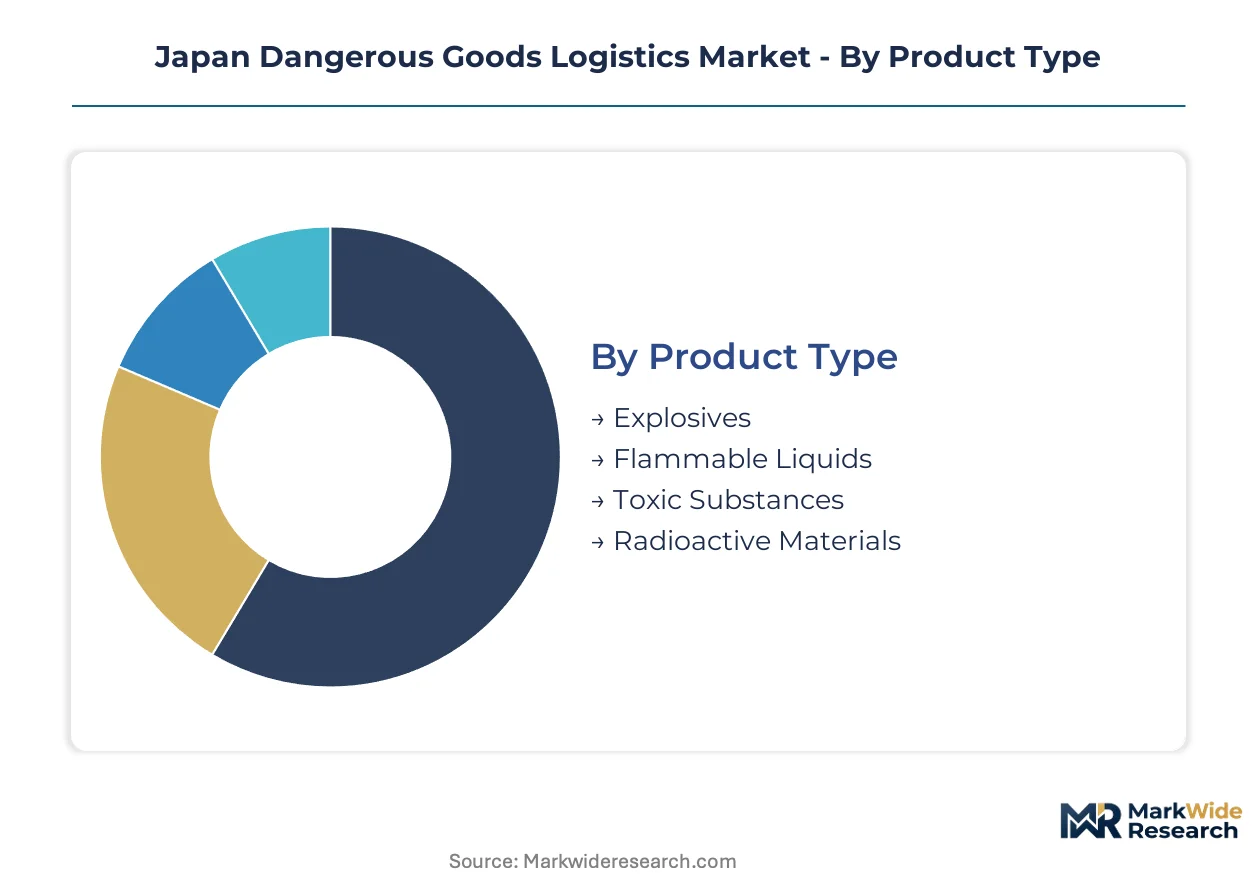
Japan's dangerous goods logistics market segments across four critical dimensions that shape carrier certification requirements, infrastructure investment priorities, and pricing structures. Each segmentation axis reveals distinct operational constraints and margin profiles that determine competitive positioning within the Keihin and Kansai industrial corridors.
Product Type:
Use-case spectrum spans industrial feedstocks through specialized medical isotopes, with each hazard class demanding unique packaging protocols and segregation infrastructure.
- Flammable Liquids:Petroleum derivatives, solvents, and chemical intermediates constitute the foundational volume base. Keihin corridor refineries and Osaka Bay petrochemical complexes generate continuous throughput requiring JIS-certified tanker fleets and vapor-recovery loading systems.
- Toxic Substances:Industrial chemicals and agrochemical precursors drive specialized warehousing demand. METI's Chemical Substances Control Law mandates substance-specific tracking databases that filter carrier eligibility to operators with integrated compliance platforms.
- Explosives:Mining, construction, and defense applications require dedicated blast-resistant storage and route clearance protocols under Fire Service Act jurisdiction.
- Radioactive Materials:Medical isotopes for diagnostic imaging and cancer therapy command premium positioning through temperature-controlled hazmat channels with real-time chain-of-custody verification.
Established volume favors Flammable Liquids; emerging adoption favors Radioactive Materials.
Transport Method:
Cost tier structures separate capital-intensive air cargo from volume-scalable sea and rail alternatives, with modal choice driven by transit time sensitivity and hazard class restrictions.
- Road Freight:Dominates last-mile delivery to manufacturing plants and construction sites across Honshu. JIS-compliant vehicle specifications and driver hazmat credentials create supply bottlenecks that constrain rapid capacity scaling for time-sensitive pharmaceutical shipments.
- Air Cargo:IATA Dangerous Goods regulations command premium pricing as pharmaceutical cold-chain volumes rise through Narita and Kansai airports. Temperature-controlled hazmat infrastructure at these hubs enables high-value biologics routing that bypasses ocean transit times.
- Sea Freight:IMDG Code compliance anchors bulk chemical movements through Tokyo Bay and Osaka Bay ports. Bonded warehousing integration supports inventory pre-positioning strategies for customs clearance buffering.
- Rail Transport:Emerging multimodal integration through Kansai corridor terminals offers underutilized capacity for containerized hazardous cargo with reduced carbon intensity versus pure trucking.
Margins concentrate in Air Cargo; volume scaling favors Sea Freight.
End User:
Application maturity varies across industrial verticals, with healthcare sector digitization outpacing legacy manufacturing procurement patterns.
- Healthcare:Pharmaceutical manufacturers in Osaka and Tokyo are expanding cold-chain hazardous shipments for biologics and radiopharmaceuticals. Temperature-controlled hazmat warehousing commands premium positioning through certified depots with explosion-proof climate systems.
- Manufacturing:Chemical and electronics feedstock logistics generate baseline demand across Keihin industrial corridor linkages. Just-in-time delivery requirements favor road freight consolidation with single-source providers to reduce handoff liability exposure.
- Construction:Explosives and flammable materials for infrastructure projects require seasonal capacity flexibility and site-specific delivery coordination.
- Energy:Petroleum product distribution and battery materials logistics are gaining share fastest as electrification accelerates hazardous cargo complexity.
Customer concentration favors Manufacturing; margin expansion favors Healthcare.
Compliance Standard:
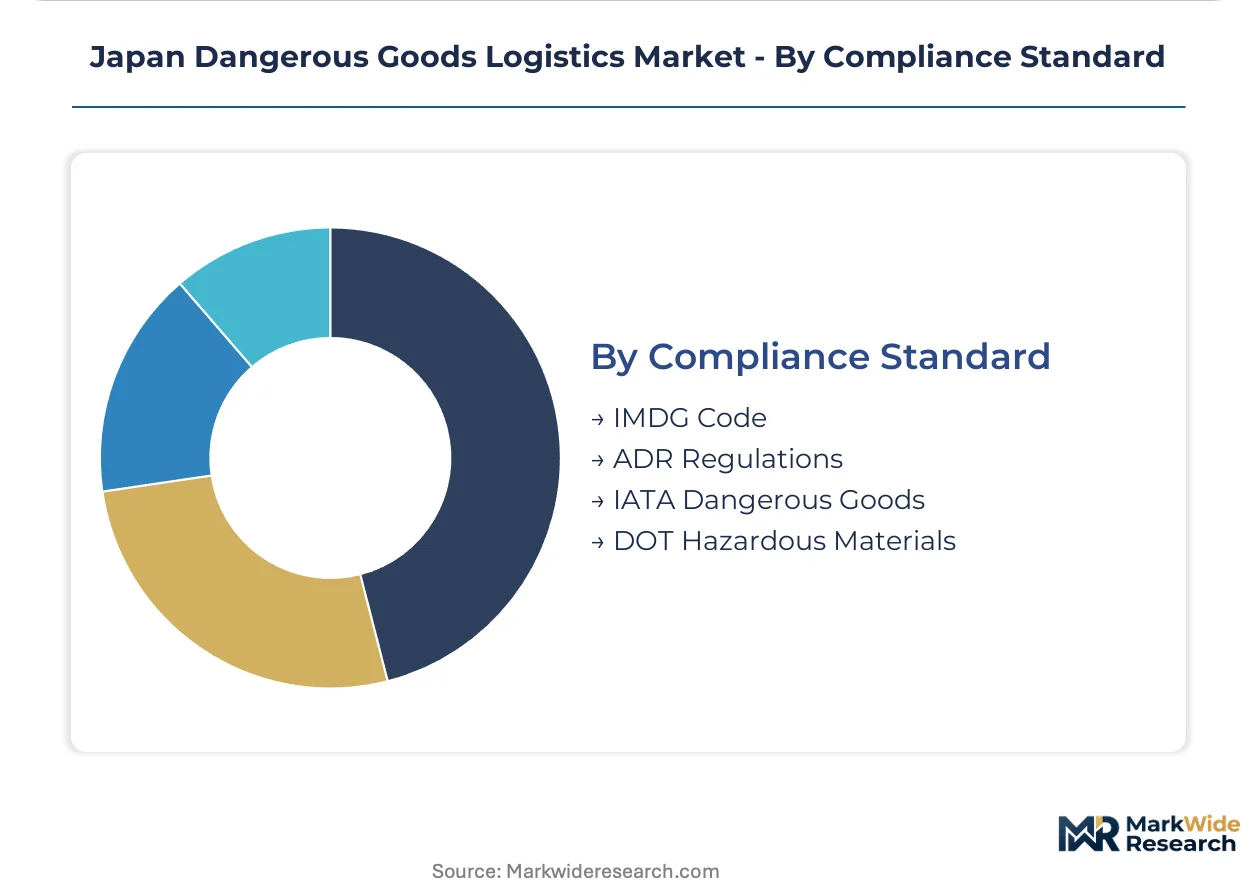
Regulatory geography determines documentation system architecture, with Japanese operators navigating overlapping international codes for multimodal shipments.
- IMDG Code:Governs sea freight classification and stowage for chemical exports through Tokyo Bay. Carrier certification under this UN framework enables access to Asia-Pacific transshipment corridors.
- IATA Dangerous Goods:Air cargo compliance mandates specialized handler training and packaging validation that filters carrier participation to established operators with dedicated pharmaceutical infrastructure.
- ADR Regulations:European road transport standards influence Japanese operators serving EU-bound exports, with METI alignment discussions forcing documentation system overhauls.
- DOT Hazardous Materials:US-bound shipments require dual certification pathways that add compliance overhead for trans-Pacific pharmaceutical and chemical flows.
Operational complexity peaks at IATA Dangerous Goods; regulatory convergence pressure concentrates on ADR Regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI anchors Japan's dangerous goods logistics framework through the Chemical Substances Control Law and Fire Service Act, creating regulatory density that shapes capacity deployment across industrial corridors.
Kanto/Tokyo
Pharmaceutical cold-chain volumes surge through Narita and Haneda corridors, demanding temperature-controlled hazmat infrastructure. The Keihin industrial belt links Tokyo Bay ports to inland distribution hubs via JIS-certified road fleets. Chiba and Kawasaki petrochemical complexes generate continuous flammable liquids throughput requiring vapor-recovery systems.
Kansai/Osaka
Biologics manufacturers route radiopharmaceuticals through Kansai Airport's certified dangerous goods terminals. Osaka Bay's sea-air transshipment capacity remains underutilized relative to pharmaceutical demand growth. Sakai and Amagasaki chemical clusters drive multimodal terminal investment toward integrated rail linkages.
Chubu/Nagoya
Automotive battery material flows concentrate through Port of Nagoya's IMDG-compliant bulk handling facilities. Toyota supply chain nodes require just-in-time hazardous feedstock delivery with pre-approved routing under Fire Service Act jurisdiction. Yokkaichi petrochemical refineries anchor solvent distribution networks across Honshu.
Kyushu
Semiconductor fabrication materials generate specialty gas and chemical logistics demand through Fukuoka and Kitakyushu industrial zones. LNG import terminals at Hakata Bay feed regional energy distribution requiring cryogenic hazmat handling certification. Oita's integrated steelworks drive explosives and flammable materials procurement.
Hokkaido
Agricultural chemical distribution peaks seasonally through Sapporo-based consolidation points. Mining operations in Kushiro and Tomakomai require dedicated blasting agent logistics with route clearance protocols. Cold-chain pharmaceutical reach remains constrained by certified depot scarcity relative to northern healthcare demand.
Japan Dangerous Goods Logistics Market Competitive Landscape
Capability concentration sits with integrated multimodal specialists; scale advantage sits with nationwide depot network operators. The market structures around three tiers: global freight forwarders with pharmaceutical certification, domestic logistics conglomerates with JIS-compliant fleets, and regional specialists in construction or energy verticals. Dominant competitive moves include bonded warehousing expansion near Tokyo Bay and Osaka Bay ports, plus automated dangerous goods sorting system deployment to compress documentation cycles under METI enforcement tightening.
Within the integrated multimodal tier, Nippon Express and Yusen Logistics occupy positions as anchors for pharmaceutical and chemical flow consolidation. LOGISTEED Japan represents the temperature-controlled hazardous warehousing specialization vector serving healthcare sector verticalization. These three operators exemplify the carrier archetype that METI's revised certification timelines are filtering volume toward, displacing fragmented broker arrangements through direct shipper contracts.
| Leading Market Players |
|---|
| Kokusai Express |
| K Line Logistics |
| KATO Transport |
| Nippon Express |
| Yusen Logistics |
| Yamato Transport |
| ICL Logistics Japan |
| LOGISTEED Japan |
| SAGAWA Global Logistics |
| Others |
Pricing and Supply Chain Analysis
Petrochemical feedstock concentration in Saudi Arabia and Kuwait funnels margin capture toward JIS-certified tanker operators and bonded warehousing providers along the Keihin corridor, with pharmaceutical cold-chain premiums commanding the widest spreads.
Pricing Analysis
Tokyo-Osaka spreads for temperature-controlled hazmat runs exceed Chubu corridor benchmarks by substantial margins. Three-tier pricing structure across IATA-certified premium, JIS-compliant standard, and uncertified economy segments anchors the market. Cost compression in standard-tier road freight is intensifying because METI's tightened certification timelines are filtering volume toward licensed carriers. Pharmaceutical manufacturers show least price sensitivity; construction material distributors exhibit highest elasticity.
Supply Chain Analysis
Japan's Chemical Substances Control Law restrictions on precursor chemical flows constrain sourcing flexibility for domestic chemical manufacturers. Supply concentrates in China, South Korea, and Singapore for specialty solvents and pharmaceutical intermediates. Raw material dependencies span ethylene derivatives, lithium battery electrolytes, and medical isotope feedstocks. Single-source vulnerability sits with semiconductor-grade chemical imports. Distribution runs through Nippon Express and Yusen Logistics depot networks with bonded warehousing at Tokyo Bay and Osaka Bay ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's dangerous goods logistics market is approaching a platform-economics inflection as pharmaceutical manufacturers mandate integrated digital compliance platforms, with blockchain-anchored chain-of-custody verification becoming the interoperability standard for contract logistics tenders.
For Market Incumbents: Pre-empt certification bottlenecks by accelerating automated dangerous goods sorting deployment at Keihin corridor depots before METI's revised timelines take full effect. Vertical integration into temperature-controlled hazardous warehousing for cell therapies will defend against healthcare sector verticalization by LOGISTEED Japan and emerging specialists.
For New Entrants and Emerging Players: Hokkaido's certified depot scarcity relative to northern healthcare demand offers the most penetrable white-space for regional hazardous logistics buildout. Target agricultural chemical distributors and mining explosives procurement as anchor clients with seasonal flexibility pricing. A go-to-market angle through Fire Service Act route pre-approval specialization can bypass incumbent scale advantages.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional construction logistics specialists holding JIS-compliant fleets but lacking pharmaceutical certification. Five-to-ten year viability hinges on METI enforcement trajectory and EU REACH alignment outcomes. The signal to watch is pharmaceutical manufacturer tender consolidation toward single-source providers with end-to-end digital compliance platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Dangerous Goods Sorting Deployment | Compresses documentation cycles under METI's tightened Chemical Substances Control Law enforcement timelines. |
| Temperature-Controlled Hazardous Warehousing Expansion | Captures premium positioning from Osaka and Tokyo biologics manufacturers routing radiopharmaceuticals. |
| Blockchain-Anchored Chain-of-Custody Integration | Meets pharmaceutical tender requirements for real-time temperature and shock monitoring systems. |
| Kansai Multimodal Terminal Development | Utilizes underutilized sea-air transshipment capacity for high-value pharmaceutical routing. |
| Single-Source Logistics Provider Consolidation | Reduces handoff liability exposure for Tokyo Bay pharmaceutical corridor manufacturers. |
Research Methodology
A standing panel of pharmaceutical supply chain directors, chemical plant logistics managers, METI compliance officers, and JIS certification auditors provided ongoing calibration throughout this study. Primary interviews with Nippon Express operations heads, Yusen Logistics sea-air coordinators, and LOGISTEED Japan warehouse supervisors combined with secondary validation from Japan Chemical Industry Association trade data, METI regulatory filings, IATA Dangerous Goods guidance updates, and customs hazardous cargo movement statistics. Bottom-up depot capacity modeling and top-down corridor throughput estimates underwent triangulation across these sources.
Scenario-bracketing around METI enforcement intensity and EU REACH alignment probability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include hazard class, transport mode, end-use vertical, and compliance standard tier. CAGRs derived from capacity-constrained growth assumptions reflecting JIS-certified fleet scarcity and pharmaceutical cold-chain expansion trajectories. Industry-specific forecast inputs encompassed Fire Service Act route pre-approval lag estimates and temperature-controlled warehousing construction cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cross-border logistics entrants or platform-based freight marketplaces would shift outcomes. Material shifts in METI's Chemical Substances Control Law enforcement cadence or EU REACH-style transport disclosure rule adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
Mexico Containerized Shipping Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
Delivery Tracking Platform Market
Logistics and Shipping
Texas Freight and Logistics Market
Logistics and Shipping
Halal Logistics Market
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
Netherlands Freight and Logistics Market
Logistics and Shipping
GCC Event Logistics Market
Logistics and Shipping
Spain 3PL Market
Logistics and Shipping
Egypt Freight and Logistics Market
Logistics and Shipping
Philippines Freight and Logistics Market
Logistics and Shipping
Renewable Resources Logistics Market
Logistics and Shipping
Europe Courier Market