
 India Domestic Courier, Express, and Parcel (CEP) Market | 2026-2036
India Domestic Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
India Domestic Courier, Express, and Parcel (CEP) Market Insights
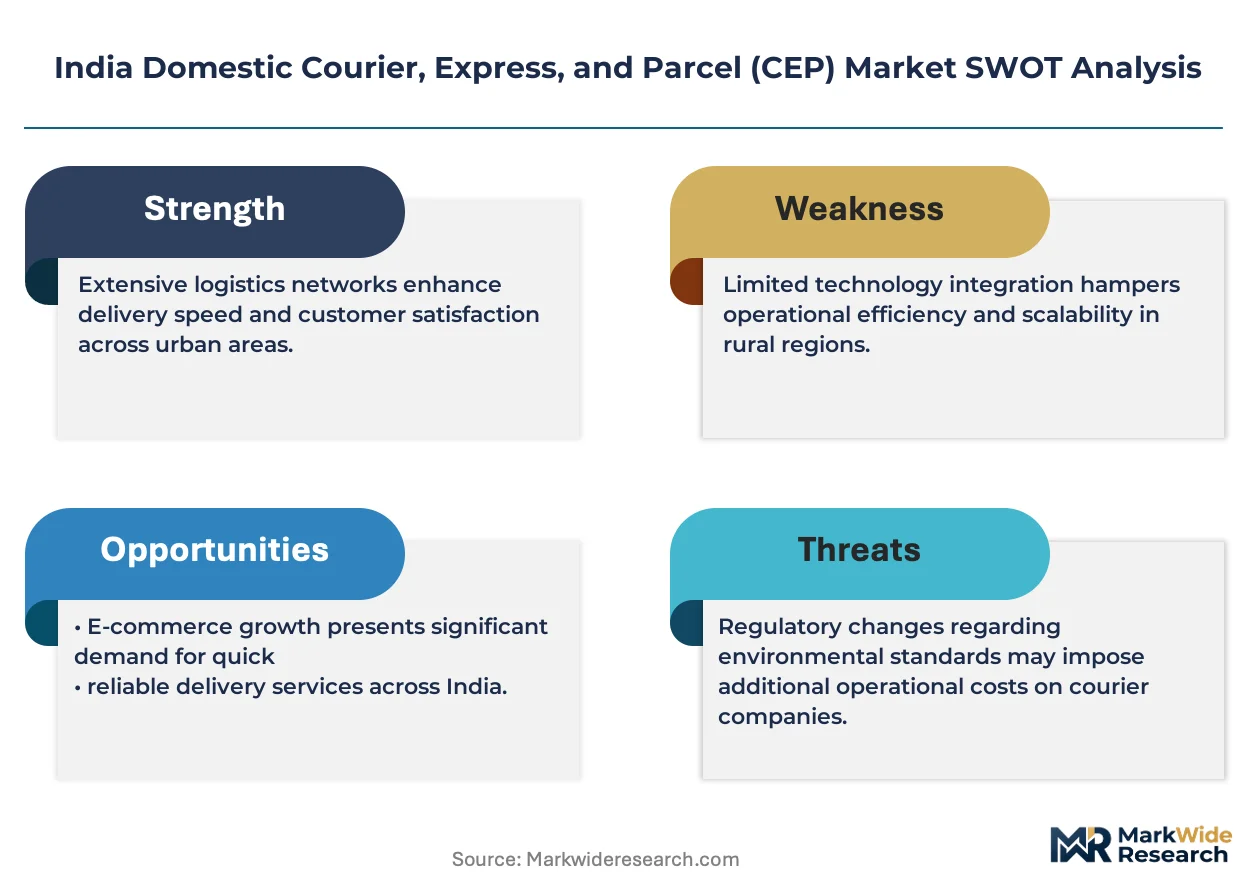
India is tilting its logistics capacity toward highway-linked industrial corridors and dedicated freight zones. Blue Dart Express Ltd leverages its air-cargo infrastructure to dominate time-definite deliveries across metros. Delhivery Ltd anchors its position through proprietary warehouse management systems and last-mile density in 18,000-plus pin codes. Ecom Express Private Limited specializes in deep rural penetration where conventional networks struggle to operate profitably.
Domestic courier, express, and parcel services constitute a time-sensitive logistics system handling shipments from documents to palletized freight, with delivery speed measured in hours for express tiers and days for standard tiers. The primary commercial purpose is bridging inventory-to-consumer gaps across fragmented Indian geography where rail and road modes handle over ninety percent of tonnage. Next-day delivery and same-day delivery segments command premium pricing as e-commerce fulfillment expectations tighten, while standard delivery retains volume leadership in non-urban pin codes. Road mode under delivery mode classification absorbs the bulk of parcel traffic, though air mode captures express margins on high-value routes between Delhi, Mumbai, Bangalore, and Hyderabad.
BIS standards for packaging integrity and the CEA's electrical-safety mandates for battery-powered delivery fleets shape product specifications and fleet procurement decisions. The PLI scheme administered by DPIIT directs capital toward automated sortation and electric vehicle adoption, conditioning market access on technology compliance. Stakeholders must monitor how TRAI's emerging drone regulations rewrite last-mile economics for remote and hilly terrain coverage.
Market Dynamics
E-commerce fulfillment density in tier-2 and tier-3 Indian cities is compressing delivery windows and forcing capital redeployment toward automated sortation and electric last-mile fleets. The PLI scheme for logistics infrastructure accelerates this transition by conditioning subsidies on technology compliance.
Growth Catalysts
- E-commerce penetration:Online retail platforms drive parcel volume into tier-2 and tier-3 cities where fulfillment infrastructure previously lagged. Delivery expectations now compress from days to hours.
- PLI scheme incentives:DPIIT-administered production-linked incentives direct capital toward automated sortation hubs and electric vehicle procurement, lowering unit economics for compliant operators.
- Highway corridor development:Dedicated freight corridors along Delhi-Mumbai and Chennai-Bangalore industrial belts reduce transit times and enable next-day surface delivery across 2,000-plus kilometer spans.
Market Restraints
- Diesel price volatility:Road-based parcel networks remain exposed to fuel cost swings that comprise 25-35 percent of last-mile operating expenditure, compressing margins on standard delivery tiers.
- Air cargo slot scarcity:Time-definite express services face capacity constraints at Mumbai Chhatrapati Shivaji and Delhi Indira Gandhi airports during peak e-commerce windows.
- Address standardization gaps:Non-urban pin codes lack geocoded delivery points, forcing manual address verification that adds 12-18 hours to standard transit times.
Strategic Opportunities
- Drone delivery corridors:TRAI's emerging unmanned aerial vehicle regulations for beyond-visual-line-of-sight operations open remote and hilly terrain coverage where road infrastructure is sparse.
- Reverse logistics monetization:E-commerce return volumes create a secondary revenue stream through refurbishment and resale channel integration.
- Cross-border CEP adjacency:Domestic network density positions operators to capture SAARC corridor freight as regional trade agreements deepen.
Industry Challenges
- Workforce retention in last-mile:Delivery partner churn exceeds 40 percent annually in major metros, forcing continuous recruitment and training expenditure.
- BIS packaging compliance:Standards for packaging integrity require material upgrades that add 8-12 percent to shipper-facing packaging costs.
- Legacy warehouse management integration:Proprietary WMS platforms resist interoperability with third-party logistics APIs, creating data silos that fragment shipment visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Domestic Courier, Express, and Parcel (CEP) Market |
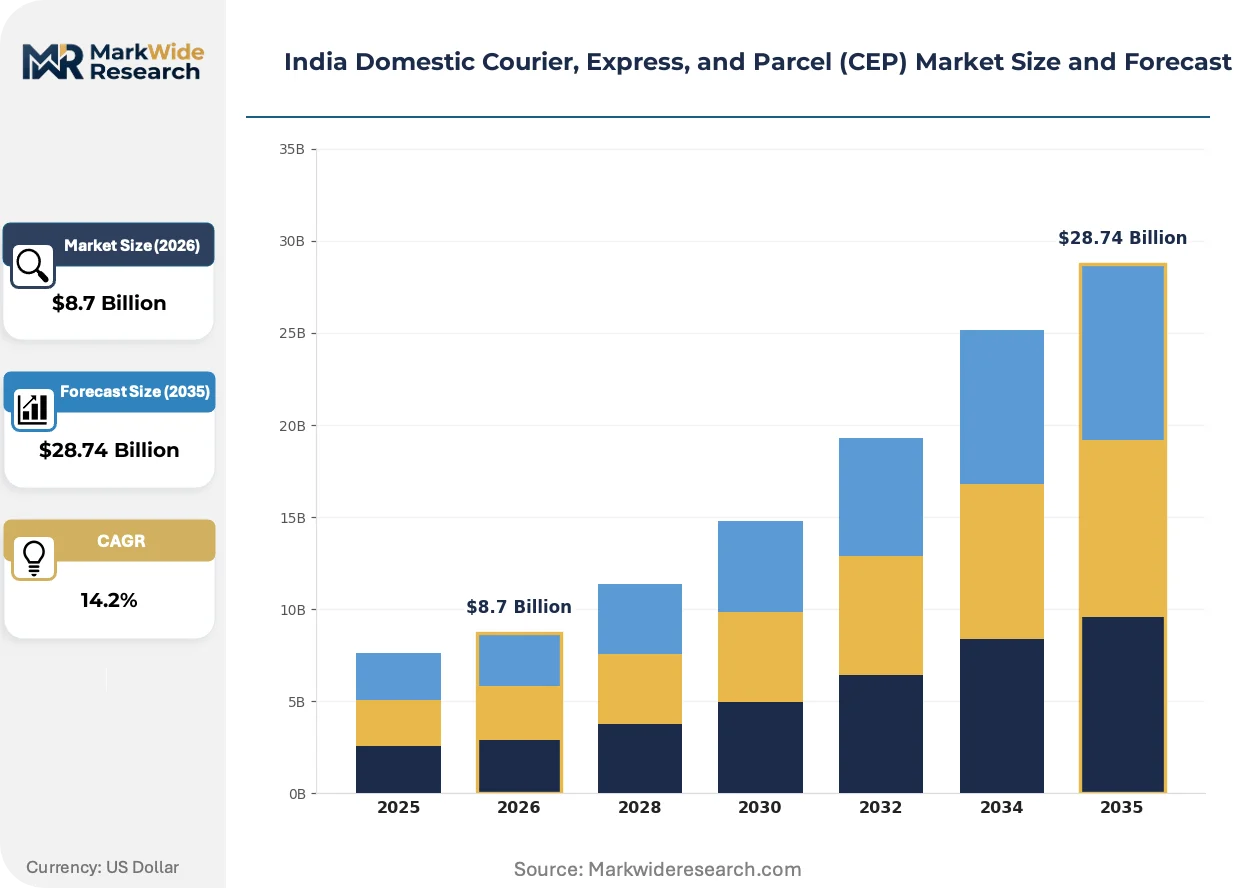
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Next-Day Delivery, Same-Day Delivery, Standard Delivery, Scheduled Delivery Delivery Mode: Road, Air, Rail, Sea End User: E-Commerce, Retail, Enterprises, Healthcare Package Type: Letters, Parcels, Pallets, Freight |
| Companies Covered | India Post, Blue Dart Express Ltd, Delhivery Ltd, DHL Express (India) Pvt Ltd, FedEx Express, DTDC Express Ltd, Ecom Express Private Limited, Shadowfax Technologies, XpressBees Logistics Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Domestic Courier, Express, and Parcel (CEP) Market Trends and Innovations
Parcel networks are converging on predictive routing and automated sortation to compress cost per shipment. Three developments dominate capital allocation and strategic planning across the sector.
Machine-learning dispatch engines are digitizing route optimization across last-mile operations. Tier-1 operators deploy these systems across 18,000-plus pin codes, cutting kilometers per delivery by 15-22 percent. The technology is digitizing how dispatch centers allocate capacity during demand spikes, replacing static zone-based routing with dynamic load balancing.
BIS standards for lithium-ion battery safety in electric delivery fleets reshape procurement specifications. The CEA's electrical-safety mandates require thermal runaway containment systems and charging infrastructure certification. Fleet operators in Maharashtra and Karnataka face accelerated replacement timelines for non-compliant vehicles, compressing depreciation schedules.
Consolidation of e-commerce fulfillment expectations compresses delivery windows from 48 hours to same-day in top 50 Indian cities. Direct-to-consumer brands bypass distributor networks, forcing parcel operators to absorb inventory positioning costs previously borne by wholesalers. This pattern concentrates in Delhi-NCR and Mumbai metropolitan regions where dark store density enables sub-4-hour fulfillment.
India Domestic Courier, Express, and Parcel (CEP) Market Segmentation
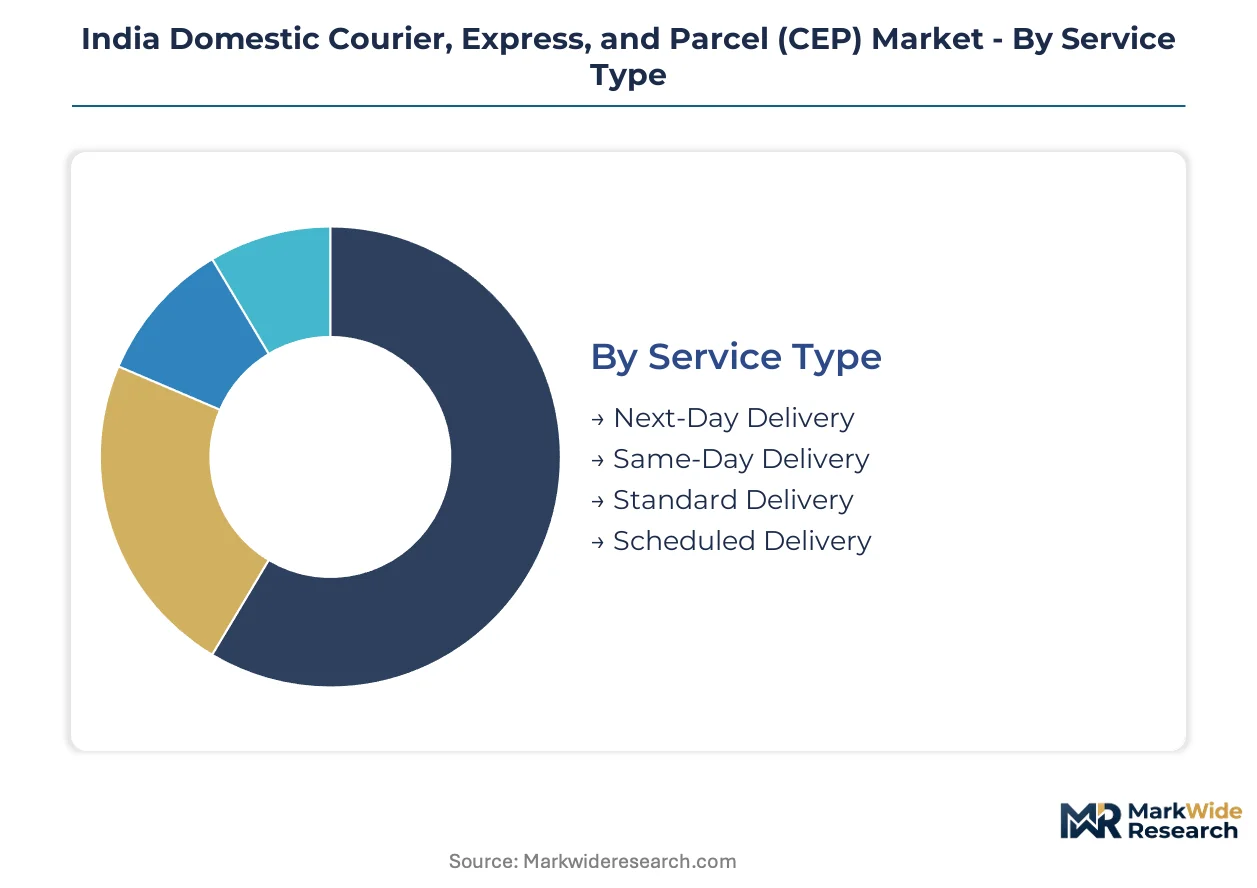
Service differentiation across the Indian CEP landscape determines capital allocation, network topology, and margin structure. Segment boundaries increasingly blur as e-commerce platforms demand hybrid service tiers and multimodal fulfillment.
Service Type:
Mature express tiers now compete with emerging scheduled formats as fulfillment expectations stratify across urban density gradients.
- Next-Day Delivery:Time-definite surface and air networks guarantee 24-hour transit between metro pairs. Maharashtra and Karnataka enterprises pay premiums for inventory velocity in electronics and apparel verticals.
- Same-Day Delivery:Hyperlocal fulfillment through dark stores and micro-warehouses compresses final-mile windows to under four hours. Delhi-NCR and Mumbai density enables this tier's economics.
- Standard Delivery:Surface-dominant networks serve tier-2 and tier-3 pin codes with 48-72 hour commitments. Cost sensitivity here drives consolidation and line-haul optimization.
- Scheduled Delivery:Appointment-based windows suit furniture, appliances, and bulk shipments requiring recipient presence. This emerging tier leverages predictive routing to minimize failed attempts.
Standard Delivery retains volume leadership; Same-Day Delivery holds the steepest expansion curve.
Delivery Mode:
Cost tier differentiation separates premium air corridors from economy surface infrastructure as fuel volatility reshapes modal economics.
- Road:Absorbs over ninety percent of parcel tonnage through national highway corridors. The Delhi-Mumbai Industrial Corridor and Chennai-Bangalore belt anchor this mode's density.
- Air:Captures express margins on high-value routes linking Delhi, Mumbai, Bangalore, and Hyderabad. Slot scarcity at Chhatrapati Shivaji and Indira Gandhi airports constrains peak-season capacity.
- Rail:Dedicated freight corridors offer bulk pallet movement at lower unit costs than road for distances exceeding 1,500 kilometers.
- Sea:Coastal shipping handles intercity palletized freight between Mumbai, Chennai, Kochi, and Visakhapatnam where road distances exceed rail efficiency.
Road retains volume leadership; Air holds the steepest expansion curve.
End User:
Application concentration varies sharply between digital-native demand generators and traditional verticals undergoing fulfillment modernization.
- E-Commerce:Platform-driven parcel generation dominates volume, with tier-2 and tier-3 city penetration now matching metro density. Return logistics integration creates secondary revenue streams.
- Retail:Brick-and-mortar networks increasingly adopt ship-from-store models, converting inventory into distributed fulfillment nodes.
- Enterprises:B2B document and sample movement sustains contractual relationships with manufacturing and services firms across Gujarat and Tamil Nadu industrial clusters.
- Healthcare:Temperature-controlled and time-critical pharmaceutical distribution requires specialized fleet certification under CDSCO guidelines.
E-Commerce retains volume leadership; Healthcare holds the steepest expansion curve.
Package Type:
Physical form factor dictates handling infrastructure, from automated letter sorting to palletized freight requiring dock-level equipment.
- Letters:Document-centric shipments declining in absolute terms as digitization displaces paper workflows. Banking and legal verticals sustain residual demand.
- Parcels:The core revenue unit spanning e-commerce fulfillment, with dimensional weight pricing optimizing trailer cube utilization.
- Pallets:B2B inventory movement between manufacturing plants and distribution centers, concentrated in automotive and FMCG supply chains.
- Freight:Loose cargo and full-truckload consolidation for enterprises bypassing parcel network density constraints.
Parcels retain volume leadership; Freight holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS standards for packaging integrity and the CEA's electrical-safety mandates for battery-powered delivery fleets shape operational compliance across Indian states. The PLI scheme administered by DPIIT directs capital toward automated sortation and electric vehicle adoption, conditioning market access on technology compliance.
Maharashtra
Mumbai's e-commerce fulfillment density drives demand for same-day and next-day delivery tiers. The state's logistics parks under the Maharashtra Industrial Development Corporation accelerate warehouse clustering along the Mumbai-Pune corridor. Thane and Bhiwandi anchor dark store networks serving metropolitan delivery windows.
Karnataka
Bangalore's technology sector generates high-value express document and sample movements. The Karnataka Industrial Areas Development Board facilitates freight corridor connectivity to Chennai and Hyderabad. Electronic City and Whitefield concentration demands sub-4-hour fulfillment cycles from parcel operators.
Gujarat
Surat's textile and diamond processing clusters sustain B2B palletized freight volumes. The state's Dedicated Freight Corridor integration reduces transit times to Delhi and Mumbai. Ahmedabad and Vadodara industrial belts require scheduled delivery tiers for manufacturing supply chains.
Delhi-NCR
Gurugram and Noida's e-commerce platform headquarters compress delivery expectations across North India. The region's air cargo connectivity through Indira Gandhi International Airport enables time-definite express services. Farukhnagar and Kundli logistics hubs concentrate automated sortation infrastructure.
Tamil Nadu
Chennai's automotive and electronics manufacturing sustains enterprise document and component logistics. The state's port connectivity enables coastal shipping integration for palletized freight. Sriperumbudur and Oragadam industrial corridors demand just-in-time delivery compliance from parcel networks.
India Domestic Courier, Express, and Parcel (CEP) Market Competitive Landscape
Capability concentration sits with integrated air-cargo operators; scale advantage sits with surface-network specialists. The market structures around three tiers: national postal infrastructure, private express integrators, and regional last-mile specialists. Dominant competitive moves include automated sortation hub deployment and electric fleet procurement under PLI scheme compliance.
Within the integrated express tier, Blue Dart Express Ltd and Delhivery Ltd occupy positions defined by infrastructure ownership patterns. Ecom Express Private Limited exemplifies the rural penetration archetype where conventional network economics fail. These three entities represent distinct strategic postures: air-cargo leverage, proprietary technology platforms, and deep non-urban density.
| Leading Market Players |
|---|
| India Post |
| Blue Dart Express Ltd |
| Delhivery Ltd |
| DHL Express (India) Pvt Ltd |
| FedEx Express |
| DTDC Express Ltd |
| Ecom Express Private Limited |
| Shadowfax Technologies |
| XpressBees Logistics Pvt Ltd |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Maharashtra's automated sortation infrastructure is compressing margins and forcing operators to redeploy assets toward tier-2 corridors where utilization rates sustain pricing power. The PLI scheme's technology compliance conditions are accelerating this geographic repricing as subsidy-eligible players absorb depreciation costs differently than non-compliant competitors.
Pricing Analysis
Geographic price spreads between Delhi-NCR and tier-3 pin codes exceed three-to-one for same-day delivery tiers. Pricing stratifies across premium express, standard surface, and economy deferred tiers, with diesel cost pass-through and address standardization gaps as primary differentiation drivers. Cost compression in standard delivery is intensifying because fuel comprises over one-quarter of last-mile operating expenditure. E-commerce platforms exhibit lowest price sensitivity for express tiers; small retailers in non-urban pin codes face highest sensitivity.
Supply Chain Analysis
Tariff exposure between India and ASEAN trading partners dominates supply chain risk planning for cross-border CEP adjacency strategies. Fleet procurement draws from China, South Korea, and domestic assembly for electric vehicle components. Lithium-ion battery cells, automated sortation equipment, and telematics hardware constitute critical input dependencies. Single-source vulnerability concentrates in battery management systems from Chinese suppliers. Distribution runs through highway-linked industrial corridors and dedicated freight zones anchored by DPIIT-subsidized logistics parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Domestic CEP Market is reshaping under drone delivery corridor authorization and PLI-mandated fleet electrification. These regulatory and technological inflections are compressing legacy network economics while opening new terrain coverage models.
For Market Incumbents: Entrench air-cargo slot control at Chhatrapati Shivaji and Indira Gandhi airports against emerging drone network substitutes. Deepen proprietary warehouse management system integration with e-commerce platform APIs to lock in data visibility. Automated sortation hub deployment in Farukhnagar and Kundli logistics clusters anchors capacity defense against regional specialists.
For New Entrants and Emerging Players: Establish a beachhead in scheduled delivery tiers for furniture and appliance verticals where appointment-based windows minimize failed-attempt costs. Target tier-3 pin codes in Gujarat and Tamil Nadu where address standardization gaps have deterred national operators. Partner with dark store networks in Thane and Bhiwandi for hyperlocal fulfillment density without captive real estate investment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric last-mile fleets as CEA thermal runaway containment mandates accelerate depreciation schedules. Viable acquisition targets combine rural pin code density with PLI compliance certification. Watch TRAI beyond-visual-line-of-sight drone authorization timelines as the signal indicating last-mile economics inflection for remote terrain coverage.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sortation Hub Deployment | DPIIT PLI subsidies reduce unit economics for compliant operators in Maharashtra and Karnataka logistics parks. |
| Electric Fleet Procurement | CEA battery safety mandates force thermal runaway containment investment ahead of legacy vehicle replacement cycles. |
| Drone Delivery Corridor Establishment | TRAI beyond-visual-line-of-sight regulations enable remote and hilly terrain coverage where road infrastructure fails. |
| Reverse Logistics Integration | E-commerce return volumes create refurbishment revenue streams through resale channel partnerships with platform operators. |
| Dark Store Network Expansion | Micro-warehouse density in Thane and Bhiwandi enables sub-4-hour fulfillment cycles for Delhi-NCR and Mumbai demand. |
Research Methodology
Cross-validation between primary interviews with logistics park operators and secondary analysis of DPIIT subsidy disbursement records anchors the qualitative findings. Conversations with fleet procurement managers, last-mile delivery partners, e-commerce platform supply chain directors, and BIS certification auditors informed operational assumptions. Secondary sources include TRAI regulatory filings, CEA electrical safety notifications, highway corridor development authority reports, and customs data on electric vehicle component imports. Bottom-up pin code density modeling and top-down industrial corridor freight flow estimates were triangulated.
Calibration against historical CEP volume trajectories and PLI scheme uptake rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type tier, delivery mode, end user vertical, package form factor, and state-level logistics infrastructure maturity. CAGRs were derived from elasticity-adjusted demand curves incorporating e-commerce penetration rates and highway corridor completion timelines. Forecast inputs include diesel price volatility scenarios and drone authorization regulatory milestones.
Stress conditions across fuel cost swings, air cargo slot scarcity events, and workforce retention churn were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about PLI scheme continuity and TRAI regulatory timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Tank Container Shipping Market
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
Europe Automotive Logistics Market
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Baggage Handling System Market
Logistics and Shipping
Latin America Air Freight Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
Asia Pacific Automotive Logistics Market
Logistics and Shipping
Central and Eastern Europe Freight and Logistics Market
Logistics and Shipping
Texas Freight and Logistics Market
Logistics and Shipping
United States Automotive Logistics Market
Logistics and Shipping
Japan Logistics Market
Logistics and Shipping
France Freight and Logistics Market