
 North America Shipping Supplies Market | 2026-2036
North America Shipping Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
North America Shipping Supplies Market Analytics
Modular kit configurations is repositioning how mid-size warehouses specify shipping supplies, bundling corrugated boxes with void fill and tape into single-SKU procurement packages. Uline leverages its massive Midwest distribution footprint to dominate same-day fulfillment for standard stock-keeping units. International Paper sustains cost advantages through captive containerboard production integrated with box plant operations. WestRock differentiates via automated packaging design services that reduce dimensional weight charges for parcel shippers.
North America shipping supplies encompass the consumable materials and containment systems used to protect, unitize, and identify goods during transit, including corrugated fiberboard containers with Edge Crush Test ratings from 23 ECT to 55 ECT, polyethylene air pillows, pressure-sensitive carton-sealing tapes, and wood or plastic pallets engineered for racking loads and fork entry. The product-type dimension shows boxes commanding the largest volume share due to e-commerce parcelization, while bubble wrap and inflatable void fill are expanding fastest as electronics and pharmaceutical shippers prioritize damage reduction. The industry-vertical split reveals e-commerce and logistics as the twin demand engines, with retail consolidation pushing buyers toward vendor-managed inventory programs that shift working capital upstream.
The US EPA and OSHA shape shipping supplies through recycled-content mandates and workplace ergonomic standards for manual material handling, while the FTC's Green Guides constrain environmental marketing claims on biodegradable or compostable labels. Health Canada and the US Department of Agriculture enforce phytosanitary requirements on wood packaging materials crossing the border, directing pallet demand toward heat-treated or plastic alternatives. Stakeholders must monitor how state-level extended producer responsibility legislation in California and New York reconfigures accountability for corrugated recovery.
Market Dynamics
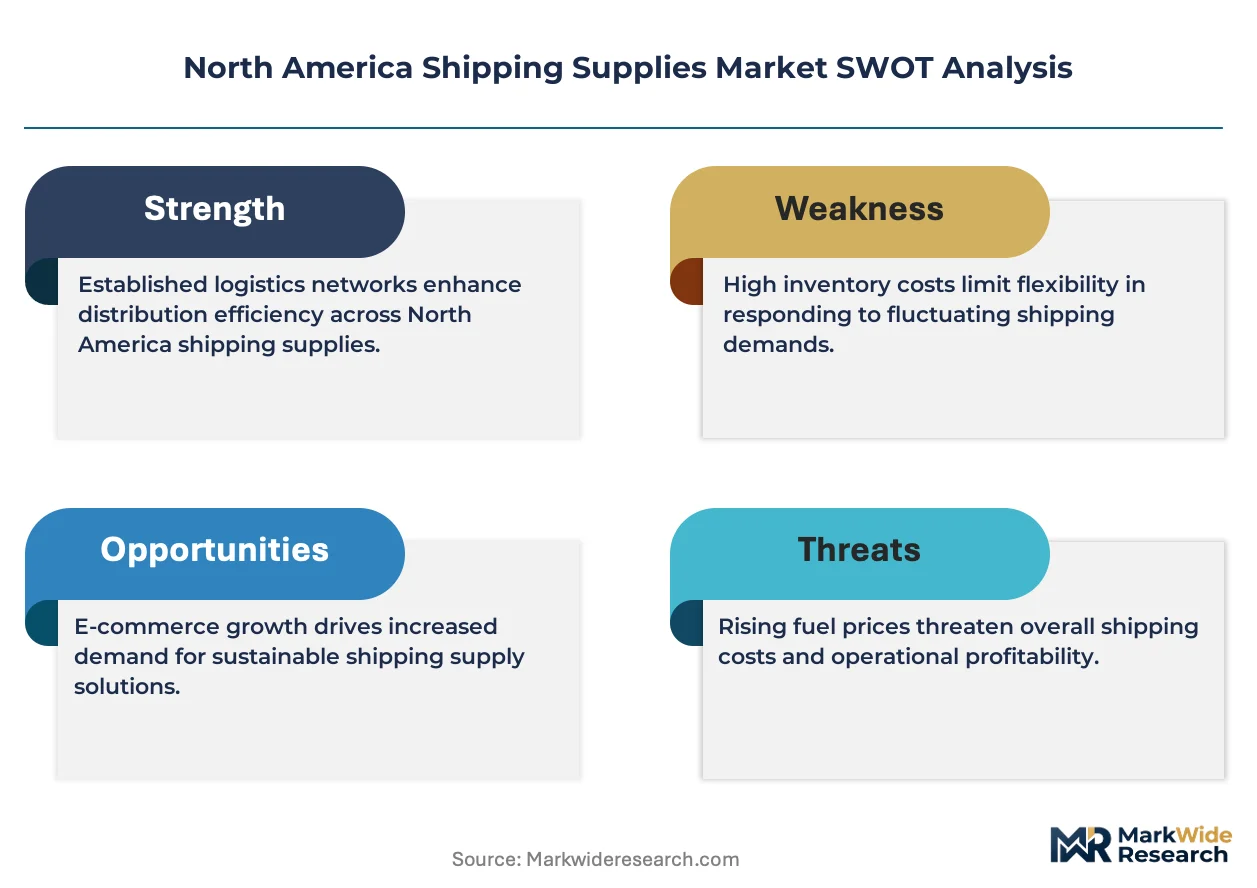
E-commerce parcelization is compressing order cycles and forcing converters to hold finished-goods inventory closer to Midwest fulfillment clusters, reshaping working capital deployment across the corrugated supply chain.
Growth Catalysts
- EPA Sustainable Materials Management:Federal procurement mandates for recycled-content packaging are pulling post-consumer fiber into specification-grade containerboard, expanding addressable supply for certified converters.
- Electronics fulfillment:Semiconductor and consumer electronics distributors are specifying Edge Crush Test 44+ boxes with inflatable void fill to reduce damage claims on high-value shipments.
- Great Lakes corridor concentration:Michigan-Ohio-Illinois industrial density creates 48-hour ground coverage to 60% of US manufacturing, lowering freight-in costs for inbound linerboard.
Market Restraints
- OCC price volatility:Old corrugated container feedstock swings with Chinese import policy, compressing mill margins when export demand spikes.
- Containerboard supply concentration:Four integrated producers control 70% of North American kraft linerboard capacity, limiting buyer leverage in contract negotiations.
- Plastic pallet substitution:Heat-treated wood phytosanitary requirements under USDA-APHIS are pushing cross-border shippers toward higher-unit-cost plastic alternatives.
Strategic Opportunities
- California EPR legislation:Extended producer responsibility for corrugated recovery creates first-mover advantage for converters offering closed-loop takeback programs.
- Automated packaging design:Convergence of CAD-based box optimization with parcel carrier dimensional weight algorithms is opening subscription-based engineering services.
- Vendor-managed inventory:Retail consolidation is enabling upstream working capital shifts where converters own floor-stock at distribution centers.
Industry Challenges
- Die-cutting tooling lead times:Custom box programs face 6-8 week steel-rule die procurement cycles that conflict with e-commerce SKU proliferation.
- ERP integration complexity:Legacy warehouse management systems require middleware development to accept real-time packaging specification feeds from converter portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Shipping Supplies Market |
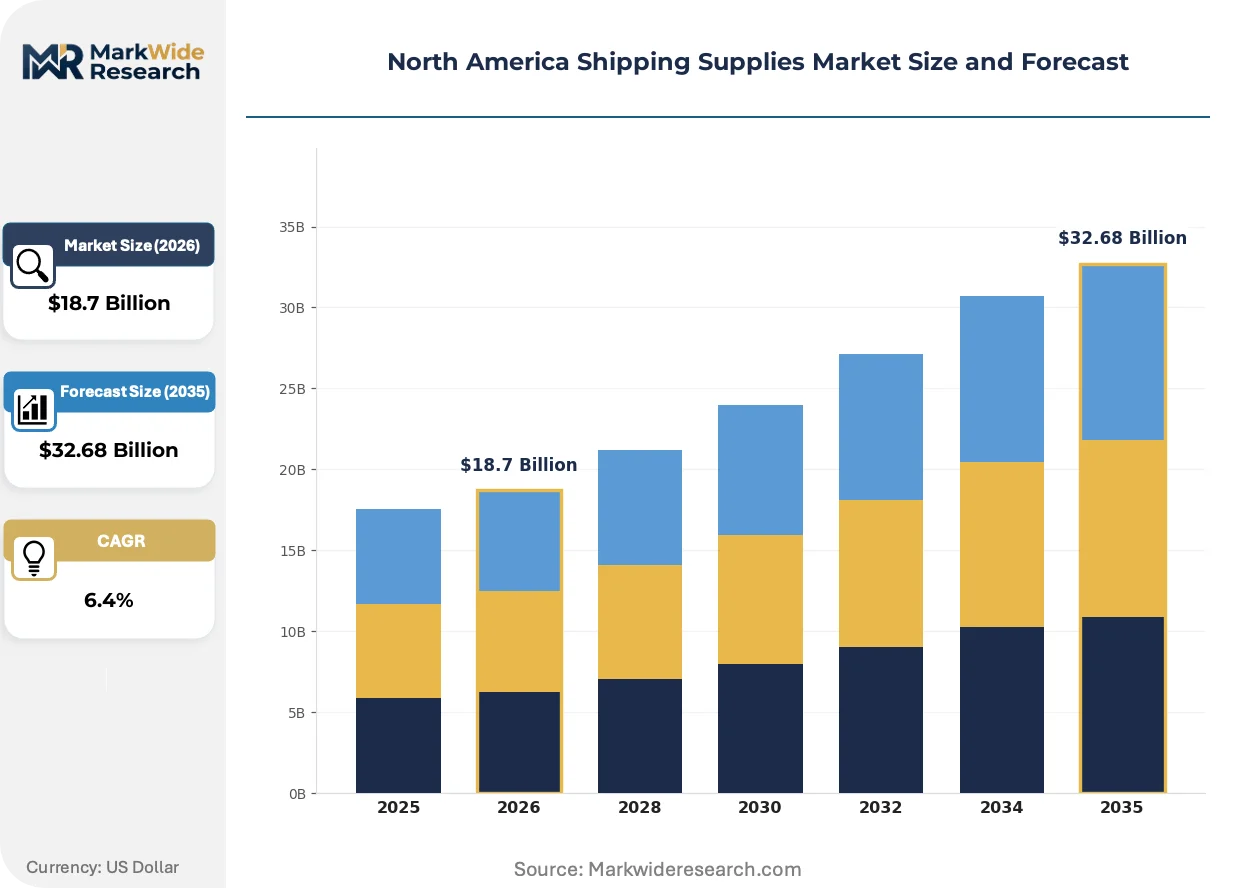
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Envelopes, Pallets, Packing Tape Material: Cardboard, Plastic, Bubble Wrap, Paper Industry Vertical: E-Commerce, Retail, Manufacturing, Logistics End User: Small Businesses, Corporations, Online Retailers, Warehouses |
| Companies Covered | Uline, Packaging Corporation of America, International Paper, Sealed Air Corporation, WestRock, Staples, Inc., Veritiv Corporation, Berry Global Group, Inc., Graphic Packaging Holding Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Shipping Supplies Market Evolving Landscape
Digital print direct-to-corrugate and AI-driven dimensional optimization are collapsing the traditional separation between structural design and brand execution, compressing concept-to-production timelines.
Water-based flexographic inkjet is overtaking pre-print litho lamination for short-run retail-ready packaging. E-commerce pure-play brands are adopting digital print at run lengths below 5,000 units to enable seasonal graphic refreshes without plate costs. This technology is overtaking conventional analog workflows in the 1,000-10,000 unit sweet spot, fragmenting volume across more SKUs and press changeovers.
The US EPA's recycled-content procurement guidelines are tightening specification windows for federal contractors. Containerboard mills must now document post-consumer fiber percentages through chain-of-custody certification. Food-contact corrugated applications face the steepest compliance burden, driving integration of recycled pulp lines with FDA-compliant barrier coatings.
Consolidated buying desks at third-party logistics providers are unbundling packaging from freight contracts. Large 3PLs now specify corrugated and void fill separately from transportation rates, forcing converters to bid direct against specialized distributors. This pattern is most visible in the Ohio River Valley, where automotive parts fulfillment centers have shifted 40% of packaging spend to direct mill relationships.
North America Shipping Supplies Market Segmentation
Shipping supplies procurement diverges sharply across buyer profiles, with federal contractors facing recycled-content mandates under EPA guidelines while e-commerce pure-plays prioritize damage-rate reduction over certification compliance. Understanding these segment-specific requirement sets enables converters to align specification-grade production with addressable demand pools.
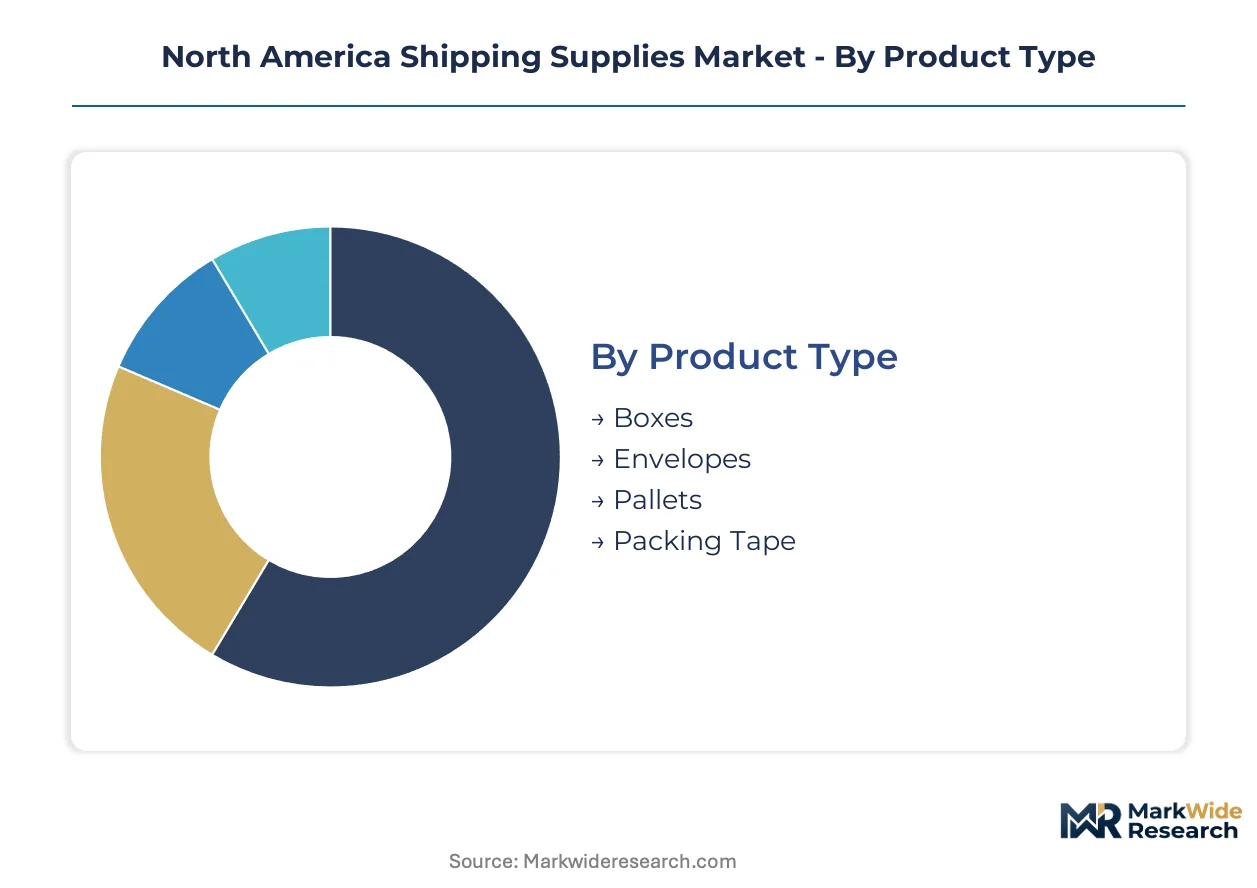
Product Type:
EPA recycled-content procurement guidelines apply differentially: federal contractors must document post-consumer fiber percentages for boxes and envelopes, while pallets fall under USDA-APHIS phytosanitary rules for cross-border movement.
- Boxes:Corrugated fiberboard containers span Edge Crush Test ratings from 23 ECT to 55 ECT, with 44+ specifications dominating electronics and pharmaceutical fulfillment due to damage-claim sensitivity. Michigan-Ohio-Illinois industrial density drives 48-hour ground coverage procurement patterns for standard stock-keeping units.
- Packing Tape:Pressure-sensitive carton-sealing adhesives face FTC Green Guides constraints on biodegradable marketing claims. Demand concentrates at third-party logistics buying desks that unbundle packaging from freight contracts in the Ohio River Valley automotive corridor.
- Envelopes:Paper-based and poly bubble mailers serve document and small-item parcelization with lighter certification burdens than corrugated.
- Pallets:Wood platforms require heat-treatment documentation under USDA-APHIS for cross-border movement, pushing substitution toward plastic alternatives with higher unit costs.
Leading the category by volume: Boxes. Growing fastest: Packing Tape.
Material:
Cost tier stratification separates specification-grade certified materials from commodity grades, with food-contact applications commanding premium positioning due to FDA-compliant barrier coating requirements.
- Cardboard:Containerboard mills integrate recycled pulp lines with chain-of-custody certification documentation. Old corrugated container feedstock price volatility tied to Chinese import policy compresses margins during export demand spikes.
- Bubble Wrap:Polyethylene air pillows and inflatable void fill are expanding most quickly as semiconductor distributors prioritize damage reduction on high-value shipments. E-commerce fulfillment centers specify these materials separately from corrugated in vendor-managed inventory programs.
- Plastic:Pallet and void-fill applications face extended producer responsibility pressure under California and New York state legislation.
- Paper:Kraft and recycled-content grades serve envelope and protective wrapping applications with lighter regulatory burden than food-contact corrugated.
Highest certification overhead: Cardboard. Steepest expansion trajectory: Bubble Wrap.
Industry Vertical:
Application-specific damage tolerance and order-cycle compression rates determine packaging specification intensity, with electronics fulfillment demanding engineered solutions while retail consolidation enables upstream working capital shifts.
- E-Commerce:Parcelization compresses order cycles and forces finished-goods inventory positioning closer to Midwest fulfillment clusters. Digital print direct-to-corrugate adoption enables seasonal graphic refreshes below 5,000-unit run lengths.
- Logistics:Third-party providers now specify corrugated and void fill separately from transportation rates, forcing converters to bid direct against specialized distributors. Consolidated buying desks have shifted substantial packaging spend to direct mill relationships.
- Retail:Consolidation pushes buyers toward vendor-managed inventory programs that shift working capital upstream to converter balance sheets.
- Manufacturing:Automotive parts fulfillment centers in the Great Lakes corridor drive 40% packaging spend migration to direct mill relationships.
Deepest specification complexity: E-Commerce. Fastest procurement model evolution: Logistics.
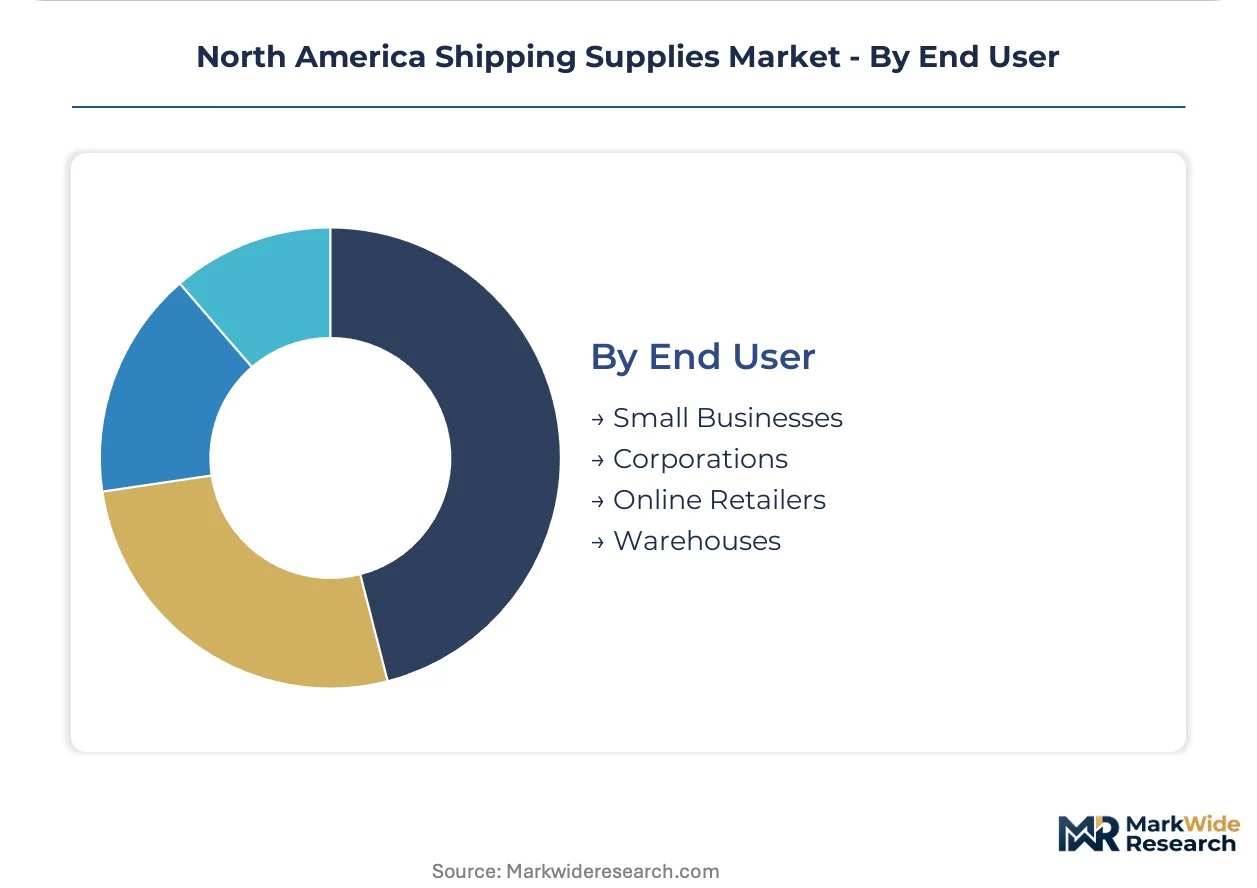
End User:
Customer-type scale determines ERP integration requirements and die-cutting tooling lead time tolerance, with large warehouses accepting 6-8 week custom box cycles while online retailers demand same-day fulfillment for standard units.
- Corporations:Enterprise procurement desks leverage volume concentration to negotiate vendor-managed inventory arrangements. Legacy warehouse management systems require middleware development to accept real-time packaging specification feeds from converter portals.
- Warehouses:Mid-size facilities specify modular kit configurations bundling corrugated boxes with void fill and tape into single-SKU procurement packages. Uline dominates same-day fulfillment through Midwest distribution footprint density.
- Online Retailers:Pure-play brands adopt AI-driven dimensional optimization to reduce parcel carrier dimensional weight charges.
- Small Businesses:Price-sensitive buyers rely on distributor stock programs with limited customization capability.
Strongest vendor leverage: Corporations. Fastest kit-configuration adoption: Warehouses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Containerboard production concentrates in the US Great Lakes corridor while Canadian mills supply specialty grades and Mexican converters serve cross-border assembly operations. Consumption patterns diverge sharply across the three economies, driven by distinct regulatory frameworks and industrial clustering.
United States
E-commerce fulfillment centers in Michigan, Ohio, and Illinois drive procurement of Edge Crush Test 44+ boxes with inflatable void fill. EPA sustainable materials management mandates require federal contractors to document post-consumer fiber percentages through chain-of-custody certification. The Ohio River Valley automotive corridor has shifted 40% of packaging spend to direct mill relationships as 3PLs unbundle procurement.
Canada
Health Canada enforces phytosanitary requirements on wood packaging materials crossing the US border, directing pallet demand toward heat-treated or plastic alternatives. Ontario and Quebec containerboard mills supply food-contact corrugated with FDA-compliant barrier coatings for cross-border food shipments. Vancouver and Toronto distribution hubs position finished inventory within 48-hour ground coverage of Midwest US markets.
Mexico
Cross-border manufacturing under USMCA drives demand for specification-grade corrugated serving automotive and electronics assembly operations in Nuevo León and Baja California. Mexican converters face pressure from US EPA recycled-content guidelines when supplying federal contractors through nearshoring arrangements. Tijuana and Monterrey industrial parks concentrate packaging procurement for just-in-time delivery to Texas and California fulfillment networks.
North America Shipping Supplies Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Four integrated producers control 70% of North American kraft linerboard capacity, creating consolidated supply-side concentration. Strategic archetypes include captive containerboard-integrated box manufacturers, automated packaging design service providers, and distributor-led same-day fulfillment operators. Competitive moves center on vendor-managed inventory programs and CAD-based dimensional optimization services.
Within the integrated manufacturing tier, International Paper and WestRock exemplify scale-driven positions anchored to captive pulp supply. Uline occupies the distributor archetype with Midwest distribution density enabling same-day standard SKU fulfillment. Packaging Corporation of America represents the regional mill-network model with integrated box plant operations. These three anchors illustrate how competitive positioning splits between upstream manufacturing control and downstream logistics proximity.
| Leading Market Players |
|---|
| Uline |
| Packaging Corporation of America |
| International Paper |
| Sealed Air Corporation |
| WestRock |
| Staples, Inc. |
| Veritiv Corporation |
| Berry Global Group, Inc. |
| Graphic Packaging Holding Company |
| Others |
Value Network & Pricing Analysis
Captive containerboard integration anchors pricing power for four dominant North American producers, converting in-house kraft linerboard into finished corrugated at margins insulated from spot-market volatility. This backward control over primary feedstock enables contract pricing discipline against fragmented box buyers while OCC export demand swings compress independent converter margins.
Pricing Analysis
Margin tightening in commodity-grade corrugated traces to Chinese OCC import policy volatility, which spikes feedstock costs during export demand surges. Three-tier pricing structure across specification-grade certified, standard industrial, and spot-market economy levels separates federal contractors facing EPA recycled-content mandates from price-sensitive small businesses purchasing distributor stock programs. Cost-down pressure on custom die-cut programs accelerates because 6-8 week steel-rule tooling lead times conflict with e-commerce SKU proliferation demands. Third-party logistics buying desks exhibit lowest price sensitivity due to unbundled procurement authority, while small online retailers face acute cost pressure from dimensional weight charges.
Supply Chain Analysis
Freight-in costs for inbound linerboard concentrate procurement decisions in the Michigan-Ohio-Illinois corridor, where 48-hour ground coverage reaches 60% of US manufacturing. Containerboard production draws from recycled pulp lines integrated with chain-of-custody certification documentation, while finished box distribution rests on captive box plant networks and independent converter operations. Single-source vulnerability concentrates in four integrated producers controlling 70% of North American kraft linerboard capacity. Distribution runs through direct mill relationships, specialized distributors like Uline, and vendor-managed inventory programs at retail consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America shipping supplies market reads as a cost-of-compliance story where EPA sustainable materials management mandates and state-level extended producer responsibility legislation erect barrier-to-entry moats favoring certified converters with documented post-consumer fiber chain-of-custody.
For Market Incumbents: Anticipate plastic pallet substitution pressure from USDA-APHIS phytosanitary requirements by deepening captive containerboard integration and pre-positioning heat-treated wood certification documentation. Defend against 3PL unbundling threats by expanding vendor-managed inventory programs that shift working capital upstream and lock in floor-stock commitments at Ohio River Valley automotive fulfillment centers. Prioritize CAD-based dimensional optimization services to capture subscription-based engineering revenue from parcel shippers facing carrier dimensional weight algorithms. For New Entrants and Emerging Players: Third-party logistics buying desks represent the most penetrable channel, particularly in the Ohio River Valley where 40% of packaging spend has migrated to direct mill relationships and specialized distributors retain service gaps. Target California extended producer responsibility compliance services as a white-space entry point, offering closed-loop takeback programs that incumbent converters have delayed implementing. Penetrate through automated packaging design partnerships with mid-size warehouses seeking modular kit configurations bundling boxes, void fill, and tape into single-SKU procurement packages. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated containerboard producers seeking downstream box plant consolidation and by private equity platforms rolling up regional converter networks. Long-term viability favors converters with FDA-compliant food-contact barrier coating capabilities and digital print direct-to-corrugate installations serving e-commerce pure-plays below 5,000-unit run lengths. Monitor California and New York state extended producer responsibility implementation timelines as the critical inflection signal for corrugated recovery accountability reshaping competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Containerboard | Captive kraft linerboard supply insulates International Paper and WestRock from OCC price volatility. |
| Vendor-Managed Inventory Expansion | Converters owning floor-stock at distribution centers lock in working capital shifts from retail consolidation. |
| Automated Packaging Design Services | AI-driven dimensional optimization reduces parcel carrier charges for e-commerce shippers. |
| Digital Print Direct-to-Corrugate | Short-run capabilities below 5,000 units capture seasonal graphic refresh demand from pure-play brands. |
| Closed-Loop Takeback Programs | California EPR legislation creates first-mover advantage for certified corrugated recovery offerings. |
Research Methodology
Multi-period observation of OCC price volatility, EPA procurement guideline implementation, and 3PL unbundling patterns anchored the trend analysis, supplemented by interviews with containerboard mill procurement directors, corrugated box plant operations managers, third-party logistics buying desk executives, and federal contracting officers. Secondary validation drew from US EPA sustainable materials management documentation, USDA-APHIS phytosanitary requirement filings, FTC Green Guides enforcement records, and SEC 10-K disclosures from publicly traded packaging producers. Bottom-up shipment data triangulated against top-down capacity estimates from linerboard production databases.
Input-output matrices modeled demand across product type, material grade, industry vertical, and end-user scale dimensions over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by price realization trends. Forecast inputs incorporated e-commerce parcelization rates, federal recycled-content procurement thresholds, and state-level extended producer responsibility legislative progress.
Several conditions sit outside the modeled scope, including sudden Chinese OCC import policy reversals, accelerated plastic pallet substitution beyond USDA-APHIS baseline assumptions, and unanticipated federal procurement guideline tightening. Forecasts reflect documented assumptions subject to revision from these industry-specific risk factors. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Egypt Freight and Logistics Market
Logistics and Shipping
Intra-Asia Freight Forwarding Market
Logistics and Shipping
Global Automated Container Terminal Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
Iraq Freight and Logistics Market
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
India Cold Chain Logistics Market
Logistics and Shipping
Chile Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Russia Third-Party Logistics (3PL) Market
Logistics and Shipping
Europe Logistics Automation Market
Logistics and Shipping
Italy Cold Chain Logistics Market
Logistics and Shipping
Poland Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
United States Chemical Logistics Market
Logistics and Shipping
Retail Logistics Market