
 Global Ophthalmic Sutures Market | 2026-2036
Global Ophthalmic Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ophthalmic Sutures Market Foresight
The capability gap between integrated suture manufacturers and assembly-only suppliers is collapsing as automated braiding technology commoditizes precision production. Alcon Inc. leverages captive polymer extrusion facilities to anchor North American supply security. Medtronic Plc sustains European hospital contracts through dedicated ophthalmic sales forces. B Braun Melsungen AG differentiates via vertical control from raw filament to sterile packaging.
Ophthalmic sutures are sterile, ultra-fine threads—typically 8-0 to 11-0 in diameter—engineered from materials such as polypropylene, nylon, or polyglycolic acid to approximate ocular tissues without inducing astigmatism or inflammatory response. Their primary purpose is to maintain wound integrity during corneal, scleral, or conjunctival healing while minimizing patient discomfort and scarring. Absorbable polyglycolic acid sutures dominate pediatric and anterior segment procedures where follow-up removal proves impractical, while non-absorbable polypropylene variants command premium positioning in corneal transplant applications requiring extended tensile strength. Barbed configurations represent the fastest-expanding product category as knotless designs reduce operative time in minimally invasive glaucoma surgeries.
FDA Class II device controls, EU MDR technical documentation requirements, and ISO 13485 quality management standards collectively elevate barriers for entrants lacking validated sterilization infrastructure. REACH compliance on chemical constituents further constrains material sourcing flexibility for European manufacturers. Stakeholders must monitor evolving biocompatibility testing protocols and pre-approval inspection frequencies as regulators tighten post-market surveillance frameworks.
Market Dynamics
Automated braiding systems are collapsing the historical capability gap between integrated manufacturers and assembly-only suppliers, eroding the premium once commanded by captive polymer extrusion and forcing incumbents to defend positioning through sterile packaging infrastructure and regulatory dossier depth.
Growth Catalysts
- EU MDR technical documentation mandates:Stricter post-market surveillance requirements in Europe are filtering out undercapitalized competitors and consolidating procurement toward manufacturers with validated sterilization infrastructure.
- Barbed suture configurations:Knotless designs reduce operative time in minimally invasive glaucoma surgeries, accelerating replacement of conventional interrupted suturing in anterior segment procedures.
- Ambulatory surgery center expansion in India:Cataract surgery volumes are climbing in metropolitan surgical hubs serving aging populations across Delhi, Mumbai, and Chennai.
Market Restraints
- Monofilament polypropylene feedstock concentration:Specialty polymer supply chains cluster among a limited set of European and North American chemical producers, exposing suture manufacturers to input volatility.
- FDA Class II device inspection frequency:Pre-approval facility inspections and sterility validation protocols extend time-to-market for new entrants lacking established quality management systems.
- Tissue adhesive substitution in pediatric cases:Cyanoacrylate formulations for small-incision closure threaten absorbable polyglycolic acid suture volumes in select anterior segment applications.
Strategic Opportunities
- Indonesia's underpenetrated ophthalmic surgical base:Jakarta and Surabaya surgical hubs lack consistent access to 10-0 and 11-0 caliber sutures for corneal transplant procedures.
- Japan's PMDA fast-track pathway for knotless devices:Regulatory tailwinds for reduced operative-time technologies favor barbed configuration submissions.
- Direct-to-hospital digital procurement platforms:Specialized distributors in South Korea are bypassing traditional multi-tier medical supply intermediaries for high-volume cataract centers.
Industry Challenges
- Micro-braiding technician scarcity:Precision textile engineering talent capable of maintaining 8-0 to 11-0 diameter tolerances concentrates in legacy European and Japanese manufacturing clusters.
- ISO 13485 certification timeline compression:Accelerated audit schedules strain quality documentation systems as notified bodies clear backlogs from MDR transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ophthalmic Sutures Market |
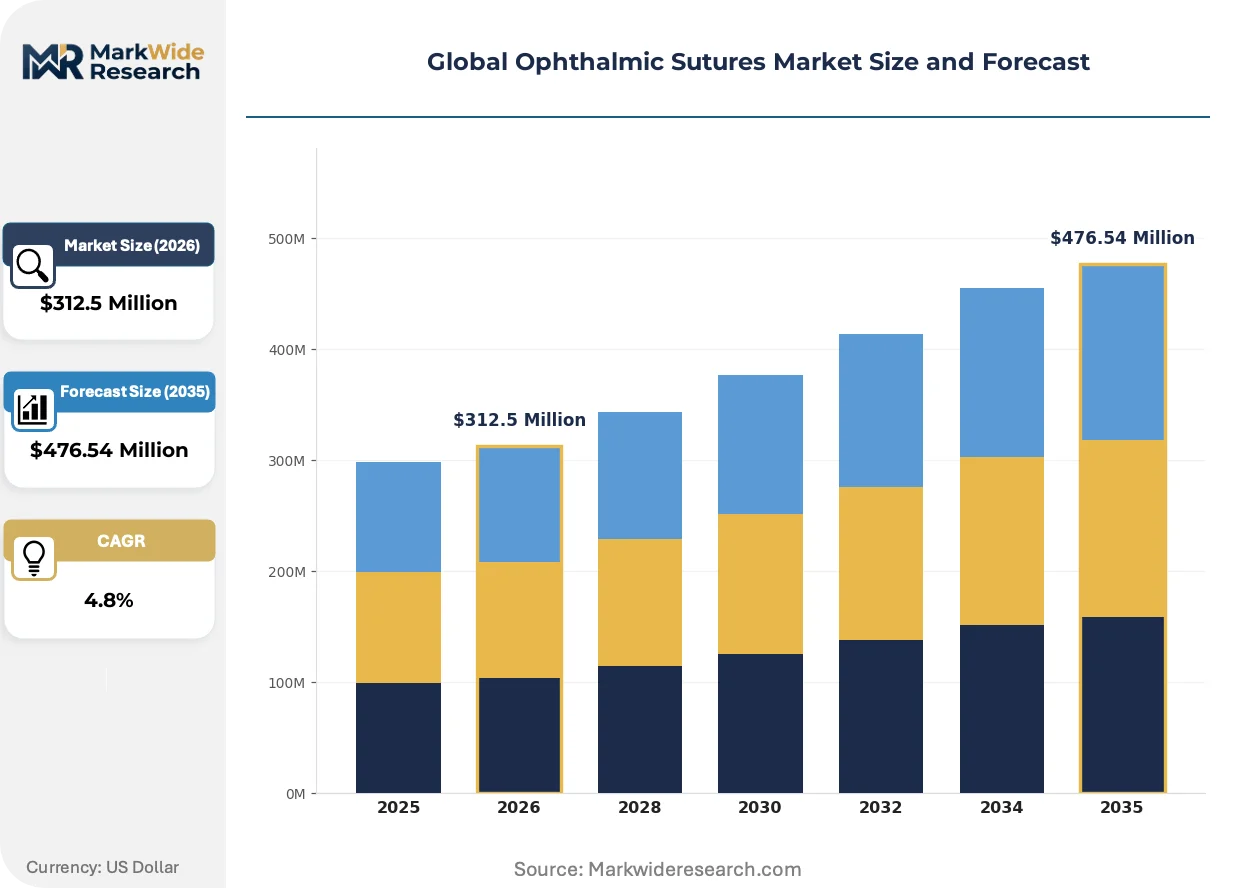
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Absorbable, Absorbable, Synthetic, Natural, Barbed Application: Cataract Surgery, Glaucoma Treatment, Corneal Transplant, Retinal Detachment, Lid Reconstruction End User: Ophthalmic Clinics, Ambulatory Surgery Centers, Specialty Hospitals, Eye Care Centers, Diagnostic Laboratories Material Composition: Silk, Polypropylene, Nylon, Polyglycolic Acid, Polyester |
| Companies Covered | Alcon Inc., Medtronic Plc, B Braun Melsungen AG, Ethicon (J&J), Corza Medical, Aurolab, DemeTech Corporation, Accutome Inc., Mani, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ophthalmic Sutures Market Shifts & Advancements
Three convergent forces are restructuring ophthalmic suture value creation: materials science advancement, regulatory documentation intensification, and procurement channel rationalization toward outcome-verified supply relationships.
Antibacterial-coated monofilament designs are decomposing the traditional trade-off between tensile strength and infection risk in corneal transplant applications. Tertiary eye hospitals in Germany and Switzerland are piloting these formulations for penetrating keratoplasty cases. The technology is decomposing premium pricing power for standard polypropylene variants by collapsing the clinical justification for prophylactic antibiotic irrigation.
REACH compliance on chemical constituents is constraining material sourcing flexibility for European manufacturers. ECHA substance of very high concern listings now cover several legacy polymer stabilizers used in suture coatings. Absorbable polyglycolic acid producers are reformulating additive packages to maintain biocompatibility certification under tightened hazard assessment protocols.
Hospital procurement departments are consolidating suture purchasing into multi-year framework agreements with sterilization-verified suppliers. French and Italian public health systems are displacing spot-buying relationships with tiered vendor qualification systems. This concentration is most visible in corneal transplant centers where graft failure traceability requirements mandate lot-level supply chain documentation.
Global Ophthalmic Sutures Market Segmentation
Ophthalmic suture purchasing decisions split across clinical application demands, material performance specifications, and sterilization infrastructure requirements. Procurement committees weight knot security against inflammatory response profiles differently across pediatric, geriatric, and transplant patient cohorts.
Product Type:
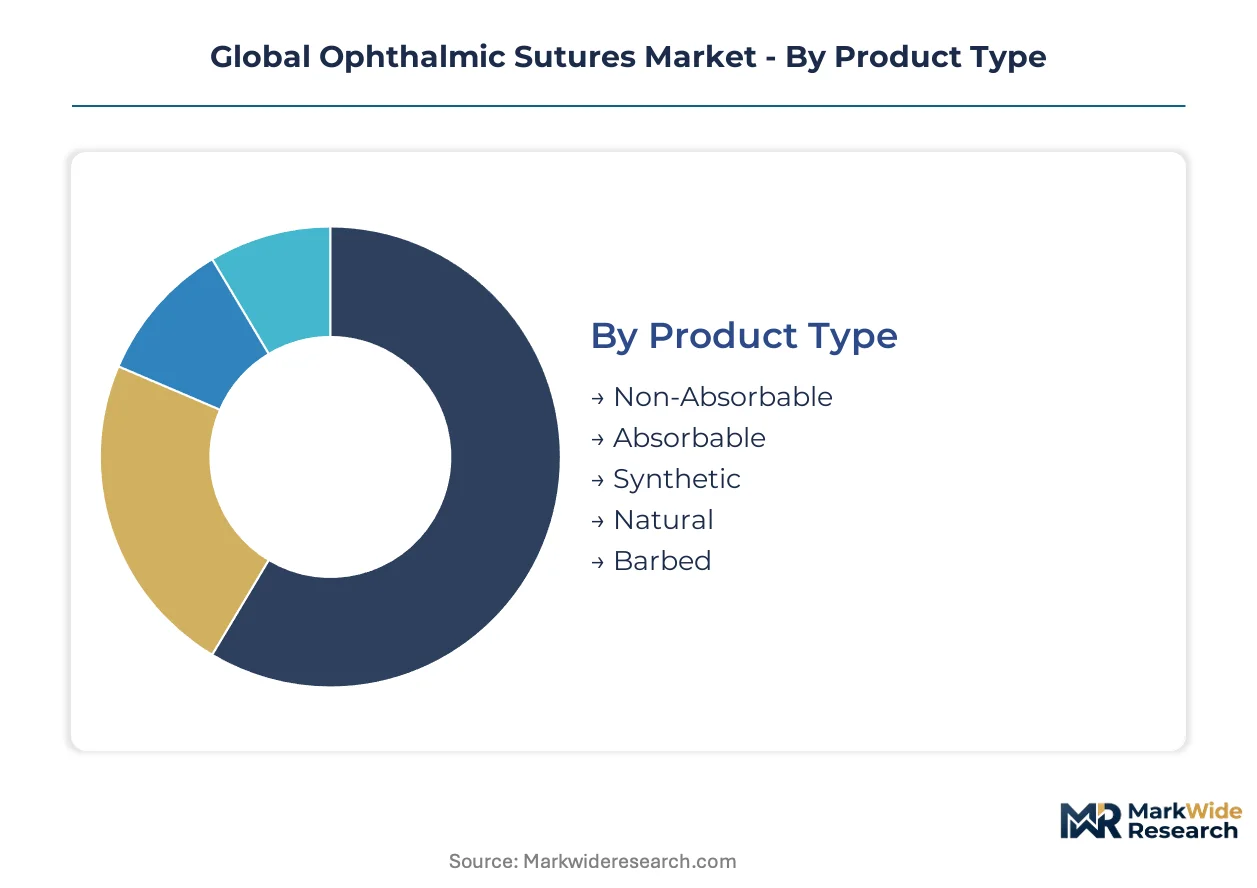
Margin pools concentrate in synthetic non-absorbable configurations where extended tensile strength justifies premium positioning in corneal transplant workflows.
- Non-Absorbable:Polypropylene and nylon monofilaments maintain wound integrity across 6-12 month healing cycles. Corneal transplant centers in Germany and Switzerland specify these for penetrating keratoplasty where suture removal would risk graft dehiscence.
- Absorbable:Polyglycolic acid and polylactic acid formulations hydrolyze within 30-90 days, eliminating follow-up removal in pediatric cataract cases. Demand clusters in Delhi and Mumbai ambulatory surgery centers where postoperative access constraints favor resorbable designs.
- Synthetic:Engineered polymers offer batch-to-batch consistency absent in biological materials. FDA sterility validation protocols favor synthetic substrates for Class II device submissions.
- Natural:Silk and catgut variants retain niche positioning in lid reconstruction where handling characteristics outweigh synthetic alternatives. Japanese surgical hubs maintain limited procurement for traditional technique preservation.
- Barbed:Knotless configurations reduce operative time in minimally invasive glaucoma surgeries. PMDA fast-track pathways in Japan accelerate regulatory clearance for reduced-procedure-time devices.
The dominant share belongs to Non-Absorbable, while Barbed is closing the gap fastest.
Application:
Volume concentration tracks cataract surgery throughput, though corneal transplant applications command superior unit economics per procedure.
- Cataract Surgery:Phacoemulsification wound closure drives the highest absolute suture consumption. Metropolitan surgical hubs across Chennai and Seoul process thousands of monthly procedures requiring 10-0 caliber precision.
- Glaucoma Treatment:Trabeculectomy and tube shunt fixation demand specialized needle curvature for scleral passage. Barbed configurations are displacing interrupted suturing in minimally invasive glaucoma surgery workflows.
- Corneal Transplant:Penetrating keratoplasty requires 10-0 to 11-0 diameter sutures with extended tensile maintenance. EU MDR lot-level traceability mandates concentrate procurement toward sterilization-verified suppliers.
- Retinal Detachment:Scleral buckling and vitrectomy wound closure utilize heavier 8-0 to 9-0 calibers. Retina specialists in Swiss tertiary centers specify braided polyester for knot security in buckling elements.
- Lid Reconstruction:Tarsal plate and canthal tendon repair favor 5-0 to 6-0 silk or nylon for handling precision. Oculoplastic subspecialists in French public hospitals source through multi-year framework agreements.
Cataract Surgery anchors absolute volume, though Corneal Transplant generates superior per-procedure margins.
End User:
Procurement authority concentrates in specialty hospital materials management departments, though ambulatory surgery centers are consolidating purchasing into regional buying cooperatives.
- Ophthalmic Clinics:Office-based procedures utilize limited suture volumes for chalazion excision and biopsy closure. Regulatory constraints on sterile field maintenance restrict in-clinic suturing scope.
- Ambulatory Surgery Centers:High-throughput cataract workflows in Indian metropolitan hubs drive bulk procurement of 10-0 polypropylene. Direct-to-hospital digital platforms in South Korea bypass traditional distributor tiers.
- Specialty Hospitals:Corneal transplant centers in Germany and Italy mandate lot-level documentation for graft failure traceability. Framework agreements displace spot-buying relationships.
- Eye Care Centers:Comprehensive facilities combine diagnostic and surgical functions under single procurement umbrellas. REACH compliance documentation requirements filter supplier qualification.
- Diagnostic Laboratories:Minimal direct suture consumption; occasional procurement for ocular tissue sampling procedures. ISO 13485 certification timelines constrain vendor onboarding.
Specialty Hospitals control premium segment procurement, while Ambulatory Surgery Centers are expanding volume share fastest.
Material Composition:
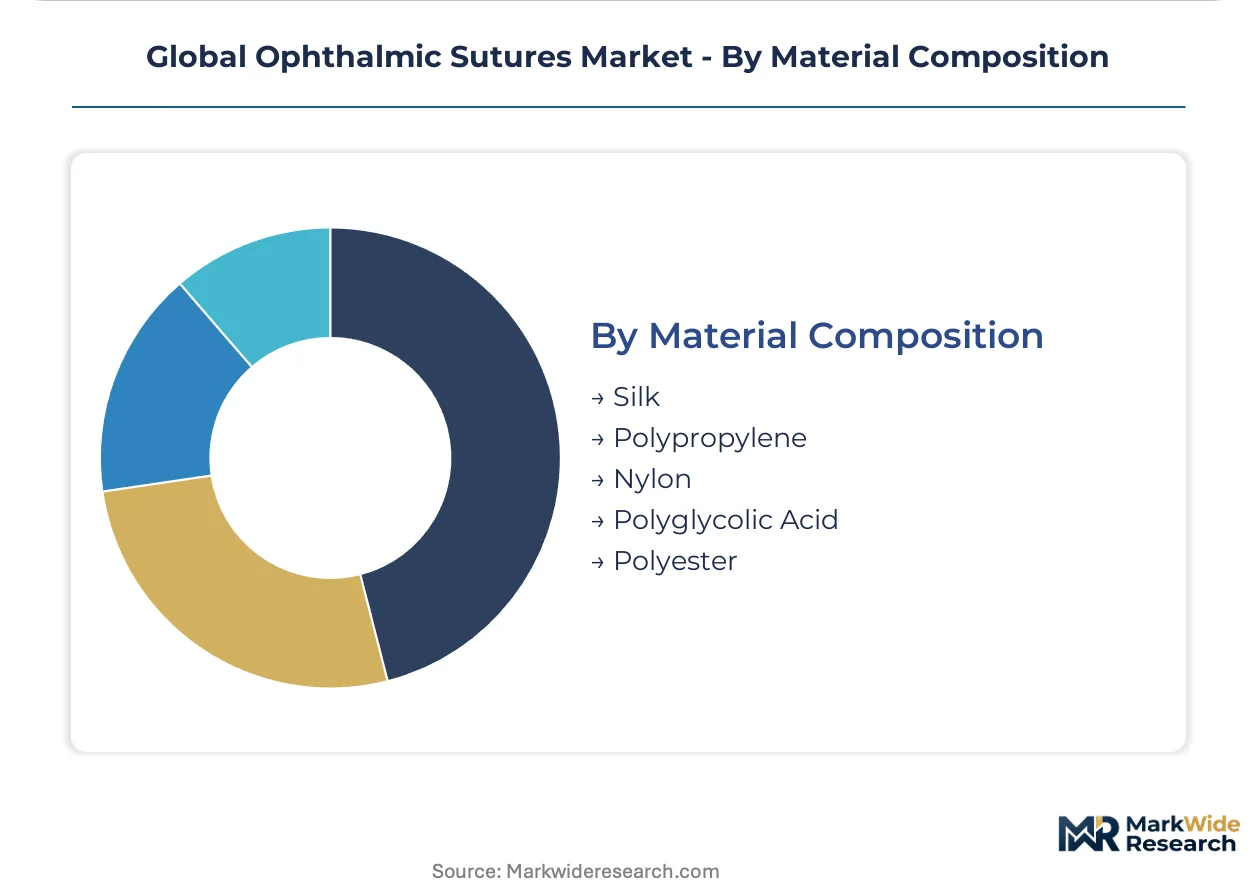
Polypropylene commands the strongest pricing power due to specialty polymer supply concentration among limited European and North American chemical producers.
- Silk:Braided natural protein fiber retains handling preference in lid reconstruction. ECHA substance of very high concern listings constrain coating additive formulations.
- Polypropylene:Monofilament synthetic dominates corneal transplant applications for extended tensile strength. Feedstock concentration exposes manufacturers to input volatility from specialty polymer producers.
- Nylon:Polyamide monofilament offers intermediate absorption profiles for anterior segment procedures. Antibacterial-coated variants are decomposing premium pricing for standard configurations.
- Polyglycolic Acid:Synthetic absorbable hydrolyzes rapidly in pediatric and anterior segment applications where follow-up removal is impractical. Tissue adhesive substitution threatens volumes in small-incision closure.
- Polyester:Braided synthetic maintains knot security in scleral buckling and extraocular muscle procedures. Swiss and German retina specialists specify these for buckling element fixation.
Polypropylene retains the dominant revenue position, though Polyglycolic Acid faces substitution pressure from tissue adhesives in select applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies. German corneal transplant centers demand extended tensile strength polypropylene for penetrating keratoplasty, while Indian ambulatory surgery centers prioritize absorbable polyglycolic acid for cataract workflows where follow-up removal proves impractical.
United States
FDA Class II device sterility mandates filter procurement toward manufacturers with validated quality management systems. Pre-approval facility inspections extend time-to-market for new entrants lacking established ISO 13485 documentation. Boston and Baltimore surgical hubs concentrate corneal transplant volume, driving premium polypropylene consumption for graft fixation procedures.
Germany
EU MDR technical documentation requirements and REACH compliance on chemical constituents constrain material sourcing flexibility for domestic manufacturers. Tertiary eye hospitals in Berlin and Munich pilot antibacterial-coated monofilament designs for penetrating keratoplasty cases. Lot-level traceability mandates concentrate procurement toward sterilization-verified suppliers with framework agreements.
India
Ambulatory surgery center expansion across Delhi, Mumbai, and Chennai drives bulk consumption of 10-0 caliber sutures for phacoemulsification wound closure. CDSCO medical device regulations align with international standards for sterile field maintenance. Metropolitan surgical hubs serving aging populations absorb resorbable designs where postoperative access constraints limit removal visits.
Japan
PMDA fast-track pathways for reduced operative-time technologies accelerate regulatory clearance for barbed knotless configurations. Chubu and Kansai manufacturing clusters retain precision textile engineering talent capable of maintaining 8-0 to 11-0 diameter tolerances. Osaka surgical centers specify braided polyester for scleral buckling procedures requiring knot security.
China
NMPA medical device classification controls elevate barriers for entrants lacking validated sterilization infrastructure. Cataract surgery volumes climb in Shanghai and Guangzhou metropolitan hubs serving aging urban populations. Domestic manufacturers face feedstock concentration exposure as specialty polymer supply chains cluster among limited European and North American chemical producers.
Global Ophthalmic Sutures Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding premium positioning through captive polymer extrusion and sterile packaging infrastructure. The capability gap between these tiers narrows as automated braiding technology commoditizes precision production. Two strategic archetypes dominate: vertically integrated manufacturers with backward control from raw filament to sterile packaging, and assembly-focused specialists dependent on third-party polymer supply. Competitive moves center on M&A consolidation of sterilization-verified assets and geographic expansion into underpenetrated surgical hubs.
Within the integrated tier, Alcon Inc. and Medtronic Plc exemplify manufacturers with established regulatory dossier depth and North American supply security. B Braun Melsungen AG occupies a position representing European-based fabricators with vertical control spanning material sourcing through sterile packaging. These three entities anchor the premium segment where corneal transplant centers mandate lot-level traceability and extended tensile strength specifications.
| Leading Market Players |
|---|
| Alcon Inc. |
| Medtronic Plc |
| B Braun Melsungen AG |
| Ethicon (J&J) |
| Corza Medical |
| Aurolab |
| DemeTech Corporation |
| Accutome Inc. |
| Mani |
| Others |
Supply & Pricing Matrix
FDA Class II device sterility validation gates both supply qualification and price differentiation in ophthalmic sutures, concentrating procurement toward manufacturers with certified quality management systems while collapsing premiums for assembly-only suppliers lacking captive sterilization infrastructure. This regulatory filter stratifies pricing across sterilization-verified integrated manufacturers, regional specialists with third-party sterilization contracts, and price-competitive assembly-focused entrants.
Pricing Analysis
Long-term framework agreements dominate procurement in German and French corneal transplant centers, displacing spot-buying relationships as EU MDR lot-level traceability mandates harden. Three-tier pricing structure across premium, standard, and economy levels separates sterilization-verified polypropylene for penetrating keratoplasty from absorbable polyglycolic acid for high-volume cataract workflows and unbranded alternatives for cost-constrained ambulatory centers. Pricing pressure stems from automated braiding technology commoditizing precision production and eroding historical capability premiums. Ambulatory surgery centers in India exhibit highest price sensitivity, while specialty hospitals in Switzerland and Germany prioritize tensile performance over unit cost.
Supply Chain Analysis
Specialty polymer feedstock concentration among limited European and North American chemical producers creates a chokepoint exposing suture manufacturers to input volatility and qualification delays. Monofilament polypropylene and polyglycolic acid resin production clusters in Germany, the United States, and Japan, with braided polyester filament drawing from Swiss and Japanese textile engineering clusters. Single-source vulnerability runs through certified polymer suppliers serving multiple suture manufacturers under exclusive supply agreements. Distribution runs through specialized medical device distributors in South Korea and direct-to-hospital digital platforms displacing traditional multi-tier intermediaries in high-volume cataract centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating in ophthalmic sutures as hospital procurement committees consolidate purchasing into multi-year framework agreements, displacing fragmented spot-buying relationships and filtering supplier qualification toward sterilization-verified manufacturers with regulatory dossier depth.
For Market Incumbents: Consolidate sterile packaging infrastructure and regulatory certification assets to defend positioning against automated braiding technology commoditizing precision production. Acquire precision textile engineering capabilities in Japanese or European manufacturing clusters to secure 8-0 to 11-0 diameter tolerance expertise. Deepen backward integration into polymer extrusion to reduce feedstock concentration exposure from specialty chemical producers. For New Entrants and Emerging Players: Lead with barbed knotless configurations targeting Japan's PMDA fast-track pathway for reduced operative-time technologies, bypassing entrenched polypropylene positioning in corneal transplant centers. Target Indonesia's underpenetrated surgical hubs in Jakarta and Surabaya where 10-0 and 11-0 caliber sutures for corneal transplant procedures lack consistent supply. Deploy direct-to-hospital digital procurement platforms to bypass traditional distributor tiers and capture ambulatory surgery center volume in South Korean metropolitan markets. For Investors and Strategic Acquirers: EU MDR technical documentation mandates and accelerated ISO 13485 audit schedules reshape the acquisition landscape toward sterilization-verified manufacturers with validated quality management systems and cleared regulatory backlogs. Long-term viability over the projection horizon favors integrated manufacturers with captive polymer extrusion and sterile packaging infrastructure over assembly-focused specialists dependent on third-party supply. Target acquisition archetypes include regional specialists with framework agreements in French or Italian public health systems. Monitor PMDA submission volumes for barbed configurations as signal of knotless device adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sterilization Infrastructure Acquisition | Consolidates EU MDR-compliant capacity as audit backlogs strain notified body capacity. |
| Antibacterial Coating R&D Investment | Decomposes premium pricing for standard polypropylene in German keratoplasty centers. |
| Indonesia Distribution Partnership | Addresses 10-0 and 11-0 caliber supply gaps in Jakarta corneal transplant hubs. |
| Japan PMDA Fast-Track Submission | Accelerates barbed configuration clearance for minimally invasive glaucoma surgery workflows. |
| Direct-to-Hospital Platform Launch | Bypasses traditional intermediaries for high-volume cataract centers in South Korea. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract registries preceded structured interviews with ophthalmic surgeons, hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and precision textile manufacturing specialists. Primary fieldwork validated secondary data on suture consumption patterns across cataract, glaucoma, and corneal transplant workflows. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Variance decomposition across product type, application, end user, material composition, and regional regulatory cluster informed the analytical framework. CAGRs were derived from segment-level growth trajectories weighted by base-year revenue contributions. Forecast inputs incorporated ambulatory surgery center expansion rates in Indian metropolitan hubs, PMDA submission volumes for knotless devices, and REACH compliance timelines for polymer additive reformulation.
Forecasts assume regulatory continuity in FDA Class II device controls, EU MDR post-market surveillance frameworks, and Japan PMDA fast-track pathways; material policy shifts in sterility validation protocols or biocompatibility testing standards would require re-modeling. Practitioners should keep alternative scenarios live as tissue adhesive substitution rates in pediatric applications and automated braiding technology diffusion curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Retina Health Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Global Retinal Detachment Treatment Market
Ophthalmology
India Ophthalmology Devices Market
Ophthalmology
Retinal Detachment Diagnostic Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Japan Dry Eye Syndrome Market
Ophthalmology
US Ophthalmic Sutures Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Ocular Pain Market