
 Heart Health Products Market | 2026-2036
Heart Health Products Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Health Products Market Intelligence
FDA guidance on New Dietary Ingredient notifications is expanding the cost-of-entry calculus for heart health supplement entrants. Nordic Naturals leverages its omega-3 supply chain control to sustain premium positioning across retail and clinical channels. NOW Foods anchors its competitive stance through manufacturing scale and transparent sourcing protocols that resonate with ingredient-conscious buyers.
Heart health products encompass formulations, diagnostic tools, and therapeutic interventions designed to support cardiovascular function, reduce risk factors, or manage existing conditions. Supplements containing EPA and DHA fatty acids, plant sterols, or coenzyme Q10 target lipid profiles and endothelial health through mechanisms validated in peer-reviewed literature. The preventive care application leads volume as consumers shift spending from reactive treatment to risk mitigation, while telehealth delivery is expanding fastest as virtual cardiology consultations normalize prescription and monitoring workflows.
FDA oversees dietary supplement safety and labeling claims under DSHEA, while FTC polices advertising substantiation, creating a dual-compliance environment that elevates legal spend for market participants. EMA and national EU regulators enforce novel food and health claim assessments that delay European launches relative to US timelines. Stakeholders must monitor evolving substantiation standards for structure-function claims and anticipate how FDA enforcement priorities will reshape competitive viability for emerging ingredient platforms.
Market Dynamics
FDA's New Dietary Ingredient notification requirements are forcing smaller supplement manufacturers to consolidate or exit, while telehealth platforms absorb prescription-grade heart health monitoring into virtual care workflows. This regulatory-cost squeeze concentrates formulation expertise among scaled producers.
Growth Catalysts
- Employer Wellness Mandates:Large US corporations now subsidize biometric screening and preventive supplement regimens, channeling steady volume toward omega-3 and plant sterol categories.
- Telehealth Normalization:Virtual cardiology platforms integrate remote patient monitoring devices with supplement adherence tracking, creating closed-loop preventive care ecosystems.
- DSHEA Structure-Function Clarity:FDA's evolving guidance on qualified health claims permits more specific cardiovascular benefit language, reducing marketing friction for substantiated ingredients.
Market Restraints
- Wild-Caught Fish Oil Volatility:Peruvian anchovy harvest fluctuations and El Niño patterns create raw material cost instability for EPA/DHA concentrate producers.
- European Novel Food Assessments:EFSA's prolonged safety evaluations delay ingredient launches by 18-36 months relative to US market entry timelines.
- Synthetic Statin Substitution:Generic atorvastatin and rosuvastatin pricing compression pulls moderate-risk patients toward pharmaceutical lipid management over supplement regimens.
Strategic Opportunities
- Direct-to-Consumer Genetic Testing:Polygenic risk score platforms identify high-risk cohorts for targeted CoQ10 and omega-3 interventions before clinical symptoms emerge.
- Japan's Functional Foods Framework:Foods with Function Claims system permits heart health positioning for fortified beverages with streamlined substantiation versus pharmaceutical pathways.
- Continuous Glucose Monitoring Integration:CGM-derived metabolic data streams enable personalized supplement dosing algorithms that adjust antioxidant and fatty acid intake to real-time inflammatory markers.
Industry Challenges
- Clinical Trialist Shortage:Cardiovascular outcomes studies require specialized biostatisticians and principal investigators with nutraceutical trial experience, creating recruitment bottlenecks for substantiation programs.
- Cross-Border E-Commerce Compliance:Divergent health claim regulations between US, EU, and Asian markets force platform operators to maintain jurisdiction-specific storefront configurations and inventory segregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Health Products Market |
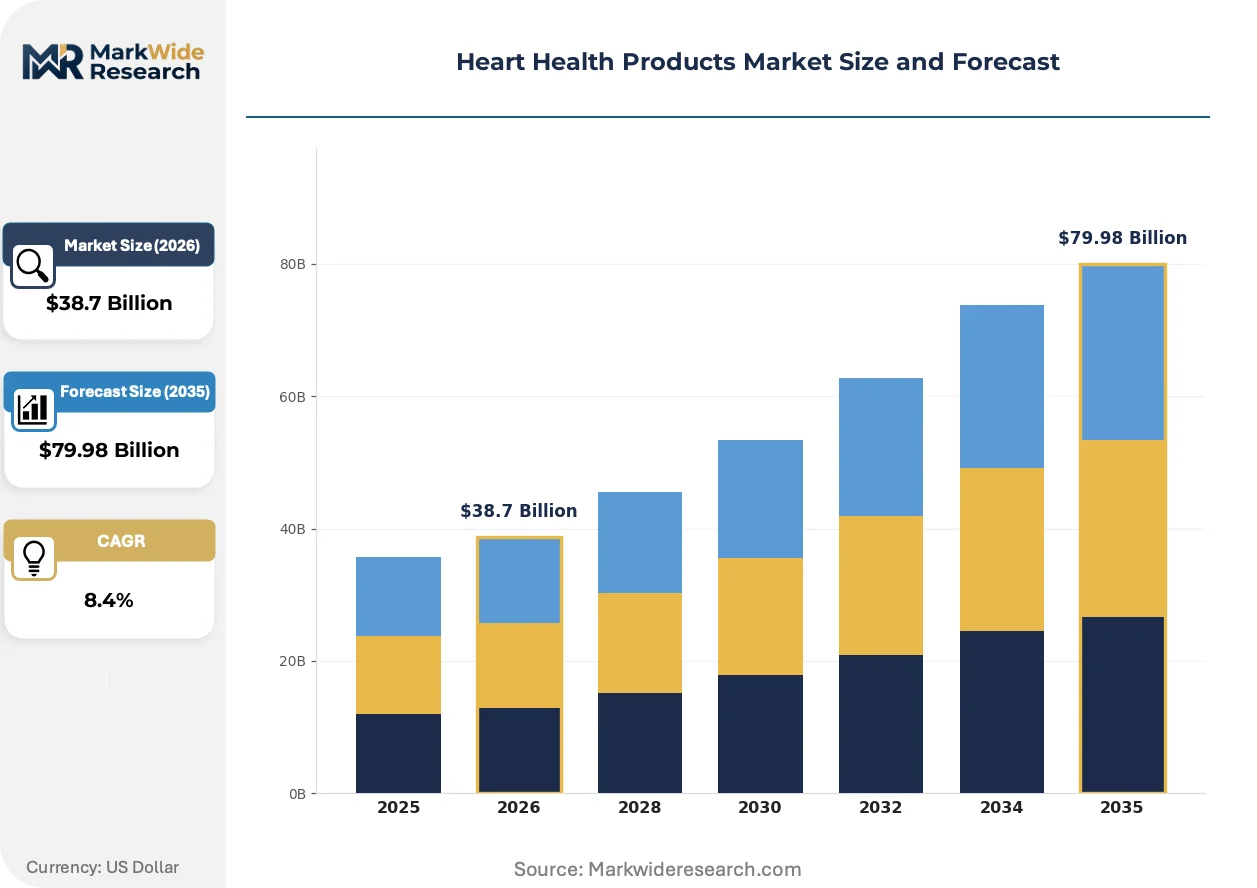
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Supplements, Monitors, Medications, Devices Application: Preventive Care, Heart Disease Management, Rehabilitation, Lifestyle Modification End User: Patients, Healthcare Providers, Fitness Enthusiasts, Caregivers Delivery Mode: Prescription, Over-the-Counter, Home Care, Telehealth |
| Companies Covered | Amway, Herbalife Nutrition, Nature's Bounty, NOW Foods, Nordic Naturals, GNC Holdings, LLC, Thorne HealthTech, Inc., Pure Encapsulations, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Health Products Market Strategic Shifts & Innovations
Biomarker-driven personalization is displacing one-size-fits-all supplement regimens, while algae-derived omega-3 alternatives decouple supply chains from marine ecosystem volatility. These shifts compress formulation cycles and reward rapid clinical validation capabilities.
Algal oil EPA/DHA production is absorbing capital from fermentation infrastructure originally built for biofuels, yielding pharmaceutical-grade fatty acids without oceanic sourcing constraints. Biotechnology firms with synthetic biology platforms are scaling photobioreactor capacity to serve vegan and kosher supplement markets. This technology is absorbing demand previously served by anchovy and krill oil concentrates.
EMA's tightened Novel Food safety assessments are extending European launch timelines for emerging ingredients like hemp-derived CBD heart health formulations and postbiotic cardiovascular compounds. Manufacturers now front-load toxicology packages and commission parallel EFSA scientific opinions before filing. Smaller entrants lacking regulatory affairs depth are ceding continental market access to multinational pharmaceutical conglomerates with established EU liaison offices.
Subscription-based replenishment models are capturing recurring revenue from diagnosed cardiac patients and fitness enthusiasts pursuing preventive lipid optimization. Amazon's Subscribe & Save and specialized platforms like Persona Nutrition displace pharmacy shelf purchases through algorithmic dosing reminders and home delivery convenience. This channel shift concentrates most visibly in US metropolitan markets where same-day delivery infrastructure supports just-in-time supplement resupply.
Heart Health Products Market Segmentation
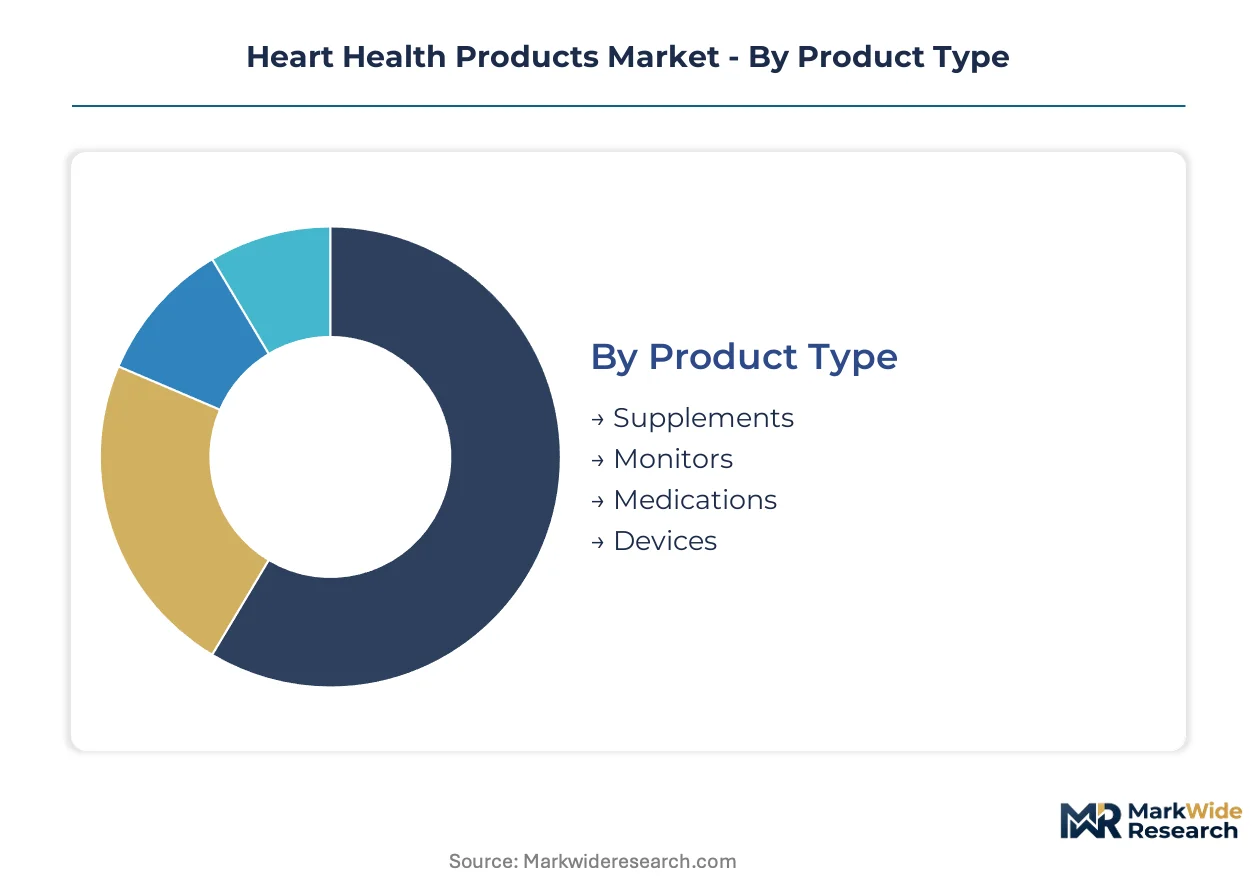
Heart health products span formulations, diagnostics, and therapeutics with divergent regulatory pathways. Segmentation reveals where FDA device approvals, DSHEA compliance, and prescription mandates create divergent margin structures and competitive barriers.
Product Type:
FDA's New Dietary Ingredient notifications apply to supplements, while 510(k) or PMA pathways govern monitors and devices. Medications face the steepest entry barriers through IND and NDA requirements.
- Supplements:EPA/DHA concentrates, plant sterols, and CoQ10 formulations dominate shelf space. DSHEA structure-function claims permit cardiovascular benefit language for substantiated ingredients, though FTC advertising scrutiny elevates legal spend for marketing teams.
- Monitors:Wearable ECG devices and blood pressure cuffs integrate with telehealth platforms. Bluetooth-enabled units with FDA 510(k) clearance command premium positioning against unregulated imports in US retail channels.
- Medications:Prescription anticoagulants and lipid-lowering agents face generic substitution pressure from atorvastatin and rosuvastatin commoditization.
- Devices:Implantable cardiac monitors and external defibrillators require PMA approval, concentrating manufacturing among medtech conglomerates with clinical trial infrastructure.
Leading the category by volume: Supplements. Growing fastest: Monitors.
Application:
Cost tier stratification separates reimbursed clinical interventions from out-of-pocket wellness spending.
- Preventive Care:Omega-3 and antioxidant regimens target asymptomatic consumers with polygenic risk scores. Employer wellness subsidies channel steady volume through biometric screening programs at Fortune 500 headquarters.
- Heart Disease Management:Post-MI patients require coordinated medication adherence and remote monitoring. Medicare reimbursement codes for cardiac rehabilitation sustain hospital-affiliated program enrollment.
- Rehabilitation:Structured exercise protocols with wearable feedback loops reduce readmission penalties for US health systems under CMS quality metrics.
- Lifestyle Modification:Smoking cessation and dietary coaching apps integrate supplement recommendations through AI-driven personalization engines.
Expanding most quickly: Preventive Care. Revenue concentration: Heart Disease Management.
End User:
Customer type determines channel strategy and pricing power across the value chain.
- Patients:Direct-to-consumer genetic testing identifies high-risk cohorts before symptom onset. Subscription replenishment models capture recurring revenue through algorithmic dosing reminders.
- Healthcare Providers:Cardiologists and primary care physicians prescribe remote patient monitoring bundles with supplement adherence tracking. Telehealth platforms normalize virtual consultation workflows for lipid optimization.
- Fitness Enthusiasts:Amateur athletes pursue endothelial function optimization through biomarker-driven personalization. CrossFit and endurance sports communities drive word-of-mouth adoption of nitric oxide boosters.
- Caregivers:Adult children managing elderly parents' medication schedules favor pre-sorted pill packaging with digital adherence confirmation.
Driving volume: Patients. Steepest expansion trajectory: Fitness Enthusiasts.
Delivery Mode:
Supply concentration favors scaled distributors with multi-channel logistics infrastructure.
- Prescription:Pharmacy benefit managers negotiate rebate structures for branded cardiovascular medications. Mail-order 90-day supplies displace retail pickup for chronic condition maintenance.
- Over-the-Counter:Mass merchandisers and club stores dominate omega-3 volume through private label and national brand co-location. Amazon's Subscribe & Save captures metropolitan same-day delivery demand.
- Home Care:Skilled nursing visits for post-acute cardiac recovery face Medicare reimbursement compression. Family-directed care shifts spending toward consumer-grade monitoring devices.
- Telehealth:Virtual cardiology platforms integrate prescription fulfillment with remote device data streams. State licensing requirements create operational complexity for multi-jurisdiction operators.
Capturing share fastest: Telehealth. Maintaining volume leadership: Over-the-Counter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones across the United Arab Emirates and Singapore concentrate heart health product distribution and regulatory testing infrastructure for regional re-export markets. These zones attract manufacturers seeking streamlined customs clearance and consolidated multi-market compliance services.
United States
Employer wellness mandates at Fortune 500 headquarters drive preventive supplement procurement through biometric screening programs. FDA's DSHEA framework permits structure-function cardiovascular claims with substantiation requirements that elevate legal spend for marketing teams. Minneapolis-St. Paul anchors omega-3 manufacturing with Nordic Naturals' supply chain control operations serving retail and clinical channels.
Germany
Aging demographics and statutory health insurance reimbursement for preventive cardiac diagnostics sustain device demand in Bavaria and North Rhine-Westphalia. EMA's Novel Food assessments extend launch timelines for emerging ingredients like postbiotic cardiovascular compounds. Frankfurt's logistics corridor concentrates EU distribution centers for supplement re-export to Eastern European markets.
Japan
METI's Foods with Function Claims system permits heart health positioning for fortified beverages with streamlined substantiation versus pharmaceutical pathways. Polygenic risk score adoption among consumers drives targeted CoQ10 and omega-3 interventions before clinical symptoms emerge. Tokyo-Osaka corridor hosts fermentation infrastructure originally built for biofuels now repurposed for algal oil EPA/DHA production.
China
SAMR's evolving health claim regulations create compliance complexity for imported supplement brands while domestic manufacturers exploit local registration pathways. NMPA oversight of diagnostic devices concentrates wearable ECG production in Shenzhen's electronics manufacturing cluster. Yangtze River Delta absorbs capital for photobioreactor capacity serving vegan and kosher supplement export markets.
India
FSSAI's functional food regulations and Ayush Ministry integration of traditional cardiovascular remedies create dual-pathway market access for domestic and international formulations. CDSCO's medical device classification rules govern remote patient monitoring device imports for telehealth platforms. Maharashtra's pharmaceutical manufacturing belt in Pune and Mumbai anchors contract manufacturing for global supplement brands.
Heart Health Products Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three concentration levels: multinational consumer health divisions with pharmacy retail reach, mid-scale supplement specialists with manufacturing scale advantages, and niche clinical-grade formulators serving practitioner channels. Dominant competitive moves include strategic partnerships with telehealth platforms for closed-loop preventive care ecosystems and portfolio diversification into algae-derived omega-3 alternatives decoupled from marine supply volatility.
Within the clinical-grade specialist tier, Nordic Naturals and NOW Foods exemplify divergent scale-positioning strategies. Thorne HealthTech, Inc. occupies a position bridging practitioner-channel distribution with direct-to-consumer genetic testing integration. Amway's multi-level marketing infrastructure represents an alternative channel archetype bypassing traditional retail pharmacy concentration.
| Leading Market Players |
|---|
| Amway |
| Herbalife Nutrition |
| Nature's Bounty |
| NOW Foods |
| Nordic Naturals |
| GNC Holdings, LLC |
| Thorne HealthTech, Inc. |
| Pure Encapsulations |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Biostatistician and cardiovascular trialist concentration in the Boston-Cambridge corridor and Basel pharmaceutical cluster feeds labor-cost differentials into three-tier pricing spreads across clinical-grade, premium retail, and mass-market supplement tiers.
Pricing Analysis
Lead-time premiums for EPA/DHA concentrates with documented chain-of-custody certification command pricing advantages over spot-market fish oil inventory with uncertain provenance. Three-tier pricing structure across pharmaceutical-grade, practitioner-channel, and club-store economy levels separates Nordic Naturals' clinical positioning from NOW Foods' transparent sourcing value play from private-label mass merchandisers. Cost compression in the economy tier intensifies because Peruvian anchovy harvest volatility and El Niño disruption force spot buyers into premium contract positions. Employer wellness program procurement managers demonstrate lowest price sensitivity due to subsidy structures, while direct-to-consumer fitness enthusiasts exhibit highest elasticity.
Supply Chain Analysis
Wild-caught fish oil supply rests on Peruvian anchovy fisheries, Antarctic krill harvesting, and North Atlantic cod liver processing infrastructure. Algal oil fermentation capacity draws from repurposed biofuel photobioreactors in Japan's Osaka corridor, California's biotech belt, and Singapore's Tuas industrial zone. Single-source vulnerability concentrates in Peruvian anchovy meal reduction facilities that serve both aquaculture feed and human-grade EPA/DHA concentrate markets. Distribution runs through Minneapolis-St. Paul omega-3 manufacturing hubs, Frankfurt's EU logistics corridor, and Singapore's free trade zone re-export infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized cardiovascular trialist scarcity props pricing for substantiated structure-function claims, constraining rapid formulation expansion among mid-scale entrants lacking clinical affairs depth.
For Market Incumbents: Hedge wild-caught marine oil exposure through backward integration into algal fermentation capacity or long-term offtake agreements with photobioreactor operators in Japan and California. Fortify regulatory affairs teams against FDA New Dietary Ingredient notification expansion and EMA Novel Food assessment prolongation that threatens European launch timelines for emerging ingredients. For New Entrants and Emerging Players: Begin with Japan's Foods with Function Claims system for fortified beverage positioning, where streamlined substantiation pathways bypass pharmaceutical-grade clinical trial requirements that dominate US and EU entry. Target telehealth platform integration partnerships for closed-loop preventive care ecosystems combining genetic risk scoring with supplement adherence tracking. For Investors and Strategic Acquirers: Re-rating potential sits with clinical-grade formulators possessing EFSA scientific opinion precedents and FDA structure-function claim substantiation packages given regulatory barrier expansion. Monitor EMA Novel Food assessment queue length as inflection indicator for European market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Algal Oil Capacity Expansion | Decouples EPA/DHA supply from Peruvian anchovy harvest volatility and El Niño disruption. |
| Telehealth Platform Integration | Creates closed-loop preventive care ecosystems combining remote monitoring with supplement adherence. |
| Direct-to-Consumer Genetic Testing Partnership | Identifies high-risk cohorts for targeted CoQ10 and omega-3 interventions before symptom onset. |
| EMA Novel Food Assessment Front-Loading | Accelerates European launch timelines through parallel EFSA scientific opinion commissioning. |
| Subscription Replenishment Model Deployment | Captures recurring revenue through algorithmic dosing reminders and same-day delivery infrastructure. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cardiovascular trial principal investigators, FDA regulatory affairs consultants, supplement formulation chemists, and telehealth platform operations directors. FDA 510(k) clearance databases, EMA Novel Food assessment registers, EPA/DHA import manifests, and employer wellness program procurement disclosures provided triangulation points. Bottom-up volume modeling across product type, application, end user, and delivery mode segments converged with top-down market sizing from trade association revenue aggregates.
Segment-level CAGRs were derived through driver elasticity modeling across the projection horizon, with preventive care application expansion, telehealth delivery normalization, and employer wellness mandate penetration treated as independent variables. Product type segmentation modeled supplements, monitors, medications, and devices at distinct regulatory pathway and margin structure levels. Application segmentation distinguished preventive care, heart disease management, rehabilitation, and lifestyle modification by reimbursement code availability and out-of-pocket spending propensity.
Underlying measurement precision varies by segment; telehealth delivery mode and preventive care application carry tighter precision than rehabilitation and lifestyle modification given nascent reimbursement code standardization. Forecasts reflect assumptions around FDA enforcement priority stability, EMA assessment timeline normalization, and employer wellness subsidy continuity. Regulatory guidance revision, marine ecosystem disruption, and synthetic statin pricing compression warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Cardiovascular Pledgets Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Myocardial Ischemia Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Antihypertensive Market
Cardiovascular
Cardiovascular Enterprise Viewer Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Pulmonary Valve Replacement Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
High-Sensitivity Cardiac Biomarker Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Ischemia Market
Cardiovascular
Fractional Flow Reserve Market
Cardiovascular
Venous Thromboembolism Treatment Market
Cardiovascular
Endocarditis Therapeutics Market