
 Screw Press Dewatering Machine Market | 2026-2036
Screw Press Dewatering Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Screw Press Dewatering Machine Market Insights
Aftermarket service contracts for screw press maintenance and remote condition monitoring is realigning how vendors capture lifetime value from municipal buyers. ANDRITZ leverages its global service network to lock in multi-year operator agreements across European wastewater utilities. HUBER SE anchors its competitive position through specialized sludge handling expertise and localized technical support in German-speaking markets. Mitsubishi Kakoki Kaisha dominates Asian municipal procurement through integrated dewatering and drying system packages.
A screw press dewatering machine mechanically compresses slurry through a tapered cylindrical screen using a rotating helical screw, typically achieving cake solids content of 18-25% depending on feed characteristics and screen aperture design. The equipment serves primarily to reduce sludge volume prior to disposal or thermal processing, cutting transport and incineration costs for wastewater treatment plants and industrial processors. Dual shaft configurations lead municipal installations where throughput reliability matters most, while hydraulic press technology captures the deepest margin pools in mining and metallurgy applications demanding extreme pressure tolerance. Food processing represents the fastest-growing application segment as processors face rising costs for liquid waste hauling and seek in-house solids recovery.
EPA biosolids regulations under 40 CFR Part 503 and EU urban wastewater treatment directives enforced by national environmental agencies mandate pathogen reduction and vector attraction control, directly shaping screw press specification for pathogen-grade cake production. ISO 9001 quality certification and CE marking requirements filter market access for non-European suppliers serving European municipal tenders. Buyers must weigh total cost of ownership against upfront capital outlay as energy efficiency standards tighten and remote monitoring capabilities become baseline procurement criteria rather than differentiators.
Market Dynamics
Municipal wastewater utilities across Germany, Japan, and the United States face simultaneous pressure from tightening effluent standards and landfill capacity constraints, forcing accelerated replacement of legacy belt press systems with higher-solids screw press technology.
Growth Catalysts
- EPA 40 CFR Part 503 biosolids rules:Pathogen reduction mandates in the United States require utilities to achieve cake solids content that legacy equipment cannot reliably deliver, driving specification upgrades.
- East Asian coastal megacities:Land scarcity for sludge disposal in dense urban corridors makes volume reduction equipment critical infrastructure rather than optional capacity.
- Helical screw wear-resistant alloys:Advanced metallurgy extending component lifecycles is reducing total cost of ownership calculations for budget-constrained municipal buyers.
Market Restraints
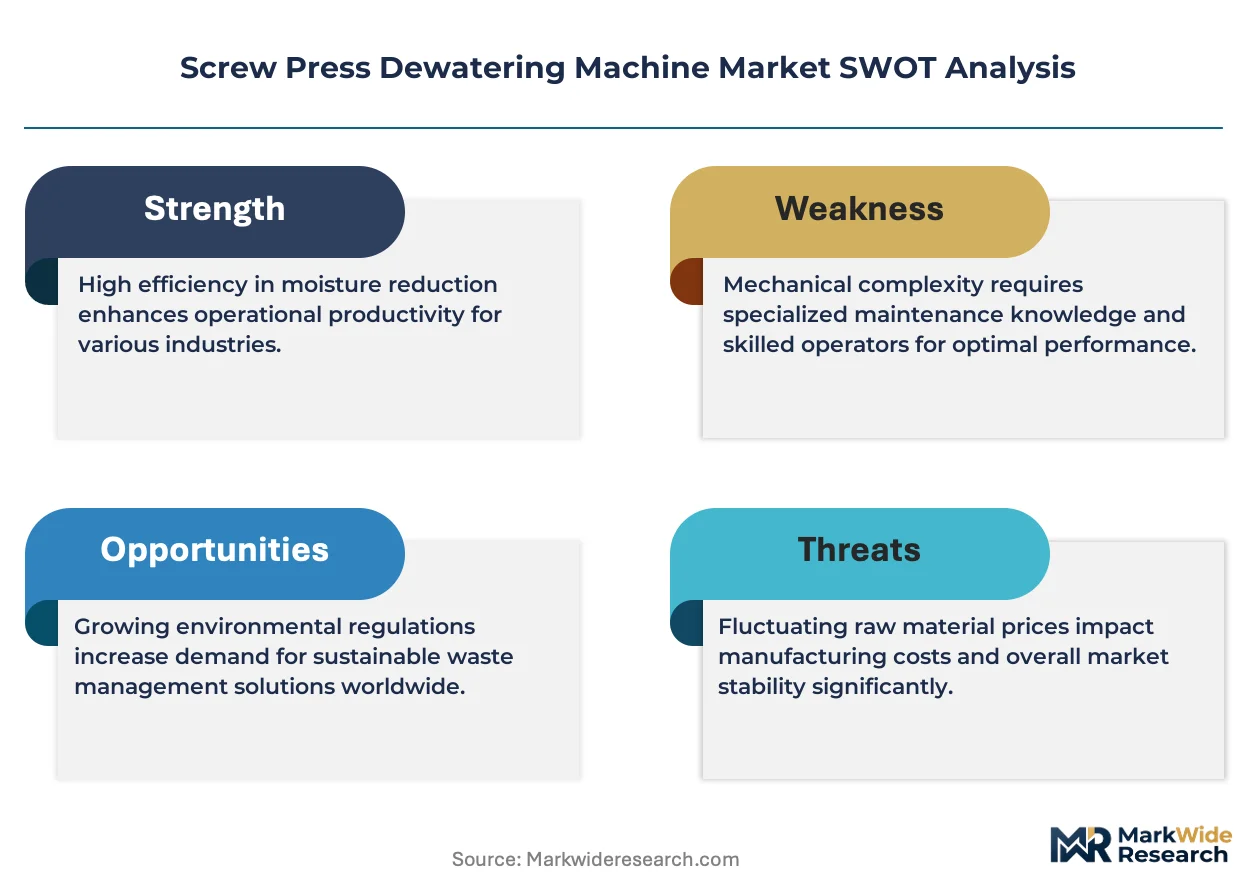
- Stainless steel input volatility:Screw press construction relies heavily on austenitic grades whose price swings compress fabricator margins and destabilize project quoting.
- Specialized technical labor scarcity:Commissioning and maintenance of precision-tapered screen systems requires skills concentrated in German and Japanese supplier workforces.
- Centrifuge substitution in high-throughput settings:Continuous decanter technology retains advantages in mining and large-scale industrial applications where cake dryness is secondary to volume velocity.
Strategic Opportunities
- Food processing liquid waste recovery:Dairy and protein processors facing rising hauling costs seek in-house solids recovery systems sized below traditional municipal scales.
- EU urban wastewater treatment directive revisions:Anticipated tightening of sludge management requirements creates preemptive upgrade cycles among European utilities.
- Remote condition monitoring convergence:Integration of vibration sensors with cloud-based analytics platforms enables predictive maintenance contracts that reshape vendor revenue models.
Industry Challenges
- ISO 9001 and CE marking compliance timelines:Non-European suppliers face extended certification periods that disqualify them from time-sensitive municipal tenders.
- Legacy SCADA integration complexity:Brownfield installations require custom protocol bridges between modern screw press controls and decades-old plant automation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screw Press Dewatering Machine Market |
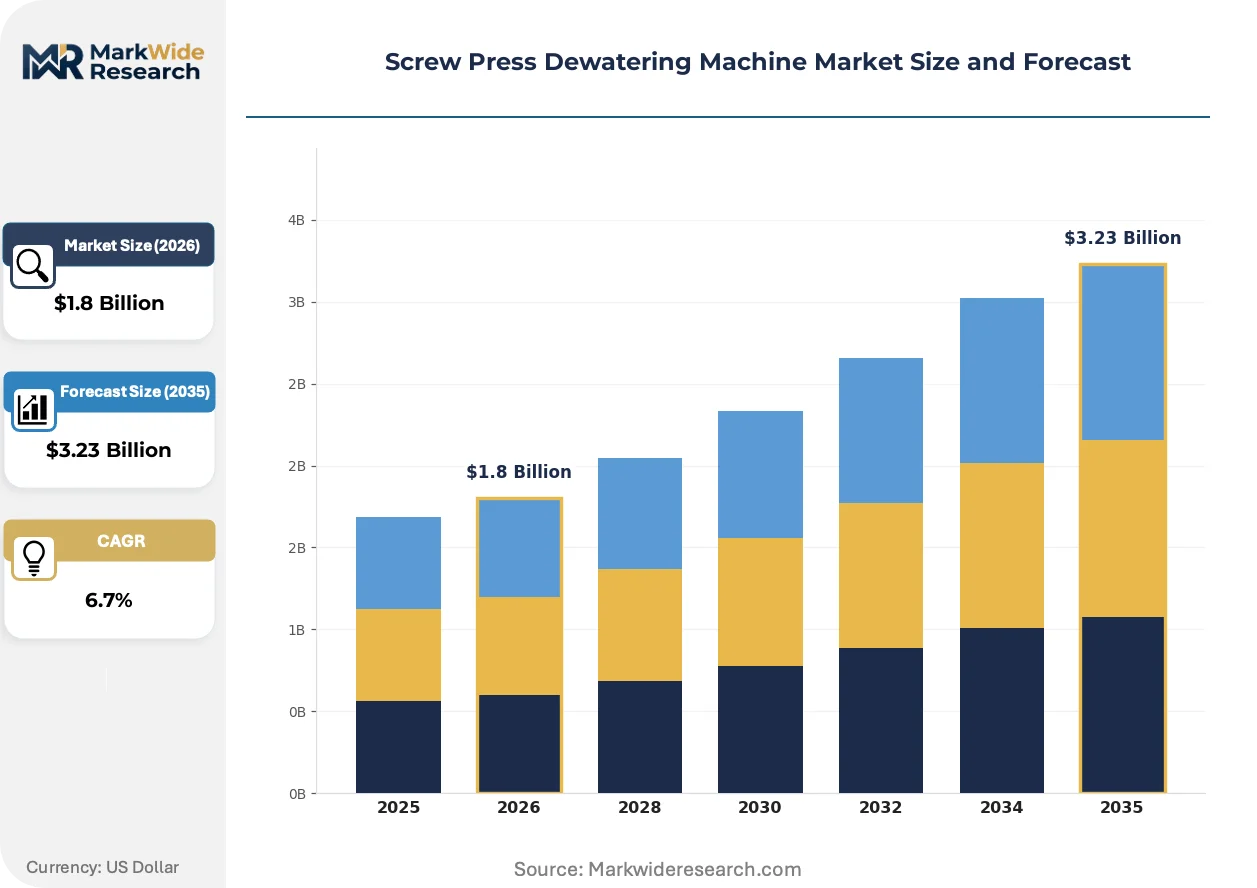
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Shaft, Dual Shaft, Triple Shaft, Multi Shaft Technology: Hydraulic Press, Mechanical Press, Pneumatic Press, Electric Press Application: Wastewater Treatment, Pulp & Paper, Mining & Metallurgy, Food Processing End User Industry: Industrial Plants, Municipal Facilities, Mining Companies, Food Manufacturers |
| Companies Covered | ANDRITZ, HUBER SE, Mitsubishi Kakoki Kaisha, Voith, Veolia Water Technologies, SUEZ, Aqseptence Group, Fournier Industries, IHI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screw Press Dewatering Machine Market Trends and Innovations
Automation and materials science are converging to transform screw press architecture from static mechanical equipment into adaptive, sensor-driven systems that optimize dewatering performance in real time.
Self-cleaning screen designs using electropolished wedge wire with automated backwash cycles are rewriting maintenance economics for high-fiber sludge applications. Municipal operators in Japan and Germany are specifying these configurations to reduce manual intervention frequency. The technology is compressing lifecycle cost gaps between screw presses and higher-maintenance centrifuge alternatives.
REACH chemical compliance and F-Gas Regulation restrictions on industrial refrigerants are reshaping thermal drying integration decisions. Combined dewatering-drying system packages must now demonstrate refrigerant-free or low-GWP thermal pathways to qualify for European public procurement. Asian system integrators are responding with heat-pump dryer configurations that bypass conventional refrigerant loops entirely.
Aftermarket service unbundling is fragmenting traditional equipment-plus-maintenance bundles. Municipal buyers in the United States increasingly separate capital procurement from multi-year service contracts, creating openings for specialized regional maintenance providers. This pattern is most visible in mid-sized utilities with sufficient in-house mechanical expertise to self-perform routine operations.
Screw Press Dewatering Machine Market Segmentation
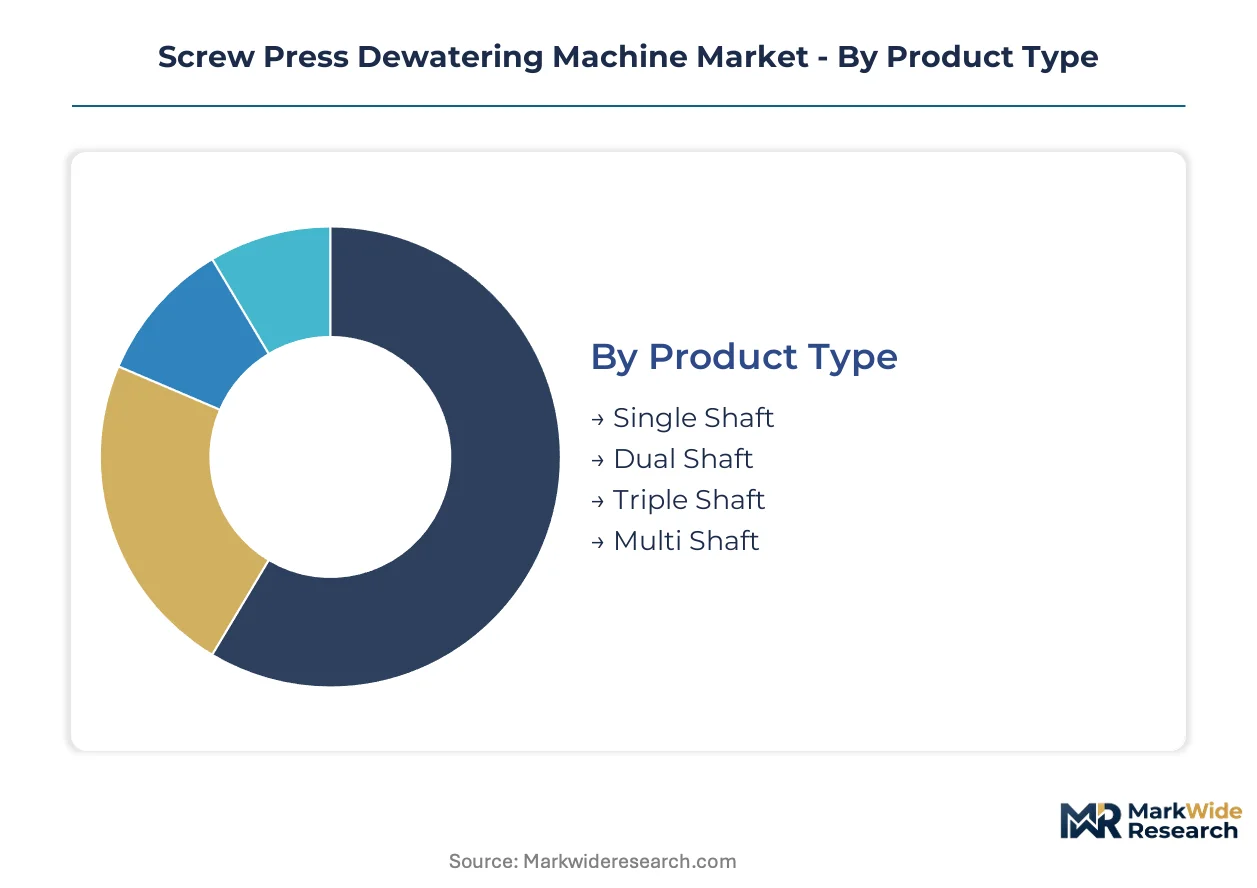
Screw press dewatering equipment exhibits distinct performance profiles across shaft configurations, press technologies, and end-use environments. Procurement patterns diverge sharply between municipal utilities prioritizing operational reliability and industrial processors optimizing for cake solids content or throughput velocity.
Product Type:
Supply concentration for precision-machined helical screws and tapered screen assemblies favors fabricators with captive metallurgy capabilities and multi-axis CNC capacity.
- Dual Shaft:Parallel screw configurations distribute mechanical load across two intermeshing helical elements, enabling higher throughput at equivalent footprint. Municipal wastewater facilities in Germany and Japan specify dual shaft systems for their redundancy advantage and reduced unplanned downtime exposure. The configuration dominates urban treatment plant retrofits where continuous operation is non-negotiable.
- Single Shaft:A solitary helical screw compresses slurry against a cylindrical screen in the simplest mechanical arrangement. Food processing plants in the United States favor compact single shaft units for batch operations where space constraints and capital budgets limit equipment scale. The design sacrifices throughput for footprint efficiency and lower maintenance complexity.
- Triple Shaft:Three synchronized screws handle high-fiber sludge streams that bind or channel in single or dual configurations. Pulp and paper mills deploy triple shaft presses for fibrous waste streams with elevated solids loading.
- Multi Shaft:Modular arrays of four or more screws address extreme volume requirements in centralized sludge processing hubs. Regional wastewater authorities in East Asian coastal megacities evaluate multi shaft configurations for consolidated dewatering facilities serving multiple treatment plants.
Today's leader: Dual Shaft. Tomorrow's challenger: Multi Shaft.
Technology:
Cost tier differentiation separates capital-intensive hydraulic systems from electrically actuated alternatives with lower installed cost but pressure limitations.
- Hydraulic Press:Fluid-powered actuation generates extreme compressive forces exceeding 300 bar for applications demanding maximum cake dryness. Mining and metallurgy operations in mineral processing circuits specify hydraulic screw presses for tailings dewatering where transport cost reduction justifies premium equipment spend. The technology captures the deepest margin pools in the segment.
- Mechanical Press:Direct gear or belt drives translate motor torque into screw rotation without intermediate power conversion. Municipal facilities across the United States default to mechanical presses for their operational simplicity and familiar maintenance protocols. The technology offers the lowest total cost of ownership over extended depreciation schedules.
- Pneumatic Press:Compressed air systems provide adjustable pressure profiles for shear-sensitive sludge streams. Specialty chemical processors evaluate pneumatic actuation where batch variability requires rapid pressure modulation.
- Electric Press:Servo-controlled electric actuators enable precise torque and speed programming with energy recovery capabilities. Food manufacturers seeking sustainability credentials specify electric presses for their efficiency advantages and elimination of hydraulic fluid contamination risk.
Mechanical Press commands current procurement volume. Electric Press is climbing the fastest as efficiency regulations tighten.
Application:
Volume concentration in wastewater treatment creates procurement scale effects that reshape supplier economics and service network deployment.
- Wastewater Treatment:Municipal and industrial sewage sludge dewatering constitutes the foundational application for screw press technology. Facilities across Germany, Japan, and the United States deploy screw presses to achieve 18-25% cake solids prior to disposal or thermal processing. EPA 40 CFR Part 503 biosolids rules and EU urban wastewater treatment directives mandate pathogen reduction performance that legacy belt presses cannot reliably deliver.
- Food Processing:Dairy, protein, and beverage processors recover solids from liquid waste streams to reduce hauling costs and generate secondary revenue from animal feed or fertilizer products. The segment is gaining share fastest as environmental compliance costs escalate and in-house waste processing becomes economically rational.
- Pulp & Paper:Fiber recovery from white water and sludge dewatering for boiler fuel preparation drive specification in integrated mills. Scandinavian and North American pulp producers evaluate screw presses against vacuum filtration alternatives.
- Mining & Metallurgy:Tailings dewatering and concentrate filtration in mineral processing circuits demand extreme pressure tolerance and abrasion resistance. Hydraulic screw press configurations dominate this segment where cake dryness directly reduces downstream transport and disposal expenditures.
Wastewater Treatment anchors installed base. Food Processing represents the steepest expansion trajectory.
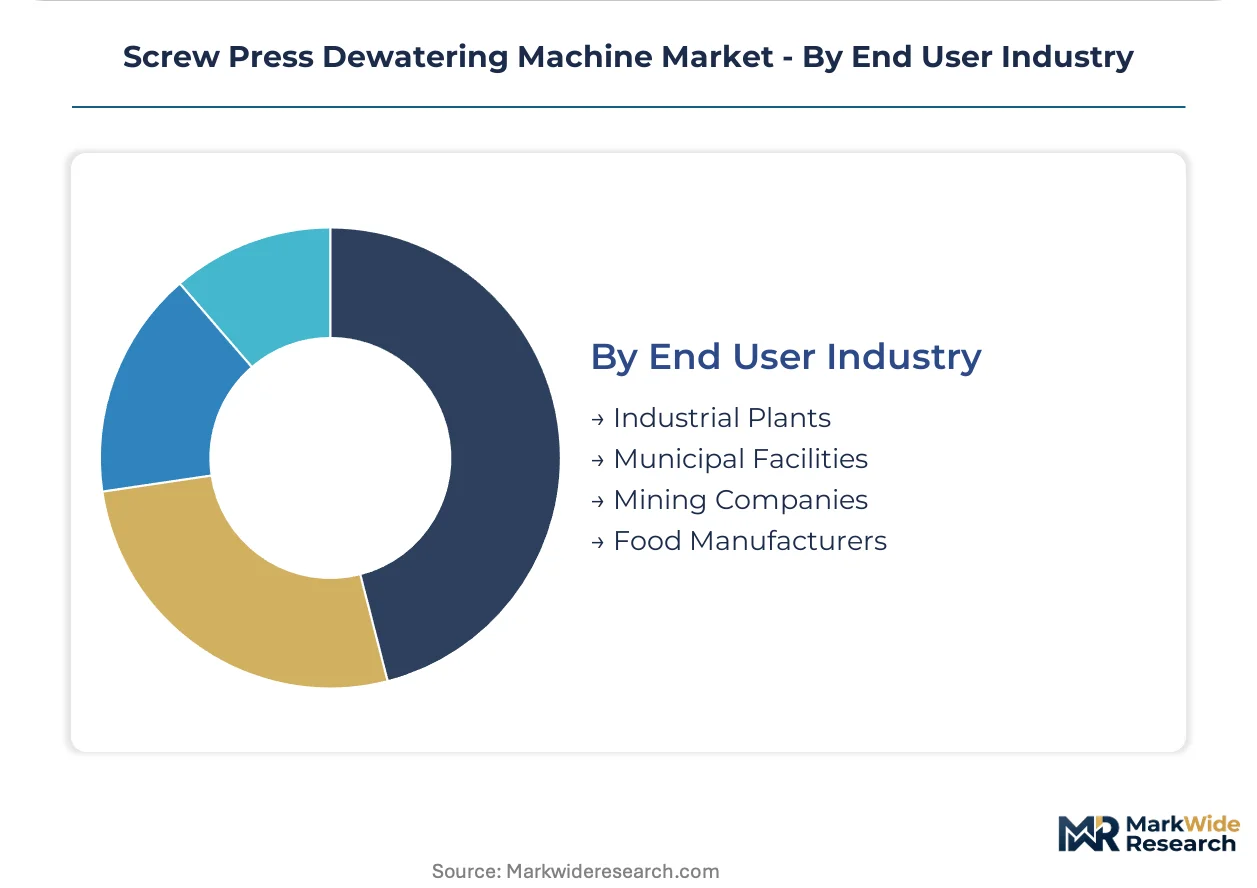
End User Industry:
Customer type segmentation reveals divergent procurement behaviors between public-sector utilities with extended capital cycles and private industrial operators with shorter payback horizons.
- Municipal Facilities:Publicly owned wastewater treatment plants operate under regulatory compliance mandates with 20-30 year asset lifecycles. Procurement emphasizes reliability, spare parts availability, and multi-year service contracts. German and Japanese municipal utilities leverage integrated dewatering-drying system packages to minimize vendor interface complexity.
- Industrial Plants:Private-sector processors in chemicals, pharmaceuticals, and textiles deploy screw presses for process water recovery and waste minimization. Capital approval cycles compress specification timelines compared to municipal procurement.
- Food Manufacturers:Dairy cooperatives and protein processors face rising liquid waste hauling costs that accelerate in-house dewatering investments. The customer type is expanding most quickly as environmental surcharges and landfill restrictions tighten.
- Mining Companies:Extractive operations prioritize tailings management technologies that reduce water consumption and surface impoundment requirements. Procurement decisions hinge on total cost of ownership across transport, disposal, and regulatory compliance dimensions.
Municipal Facilities dominate current procurement volume. Food Manufacturers are gaining share fastest as waste cost pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan demonstrate contrasting procurement maturity for screw press dewatering systems, with German utilities favoring integrated system packages while Japanese operators prioritize predictive maintenance convergence.
United States
Municipal wastewater utilities in the Great Lakes and Gulf Coast corridors face EPA 40 CFR Part 503 biosolids compliance deadlines that legacy belt presses cannot meet. The agency's pathogen reduction mandates force cake solids specifications above 20% across Class A and Class B sludge categories. Chicago and Houston metropolitan treatment authorities are consolidating regional dewatering capacity through multi-shaft installations serving multiple plant sites.
Germany
Rhineland and Bavarian utilities operate under EU urban wastewater treatment directive enforcement that exceeds baseline European requirements. The country's environmental agencies mandate nutrient recovery and phosphorus recycling from sewage sludge, tightening dewatering performance thresholds. Munich and Stuttgart treatment clusters specify combined dewatering-drying packages to minimize vendor interface complexity and thermal integration risk.
Japan
East Asian coastal megacities confront acute land scarcity for sludge landfill disposal that makes volume reduction equipment critical infrastructure. METI efficiency standards and local prefectural regulations accelerate replacement of aging centrifuge systems with higher-solids screw press technology. Tokyo Bay and Osaka metropolitan wastewater authorities deploy remote condition monitoring to compress maintenance intervals and extend component lifecycles.
China
Yangtze River Delta and Pearl River Delta municipalities expand sludge treatment capacity under MEE discharge standard tightening and dual carbon goals for wastewater sector emissions reduction. Provincial environmental protection bureaus enforce Class A sludge standards that demand 20% cake solids minimum. Shanghai and Shenzhen treatment plants evaluate multi-shaft configurations for consolidated regional dewatering hubs serving satellite facilities.
India
Gujarat and Maharashtra industrial corridors face Central Pollution Control Board effluent standards that mandate zero liquid discharge for textile and chemical processors. State pollution control boards in these regions enforce compulsory sludge management plans for large water users. Ahmedabad and Mumbai industrial clusters drive demand for compact single-shaft units suited to space-constrained plant retrofits and batch operational patterns.
Screw Press Dewatering Machine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with municipal procurement favoring established service networks while food processing opens doors for regional fabricators. The vendor base concentrates among European and Japanese groups with captive metallurgy capabilities and multi-axis CNC capacity for precision-tapered screen production. Three archetypes dominate: integrated system integrators bundling dewatering with thermal drying, component specialists supplying precision-machined screws and screens to third-party assemblers, and regional maintenance providers unbundling aftermarket service from capital sales. Geographic expansion through localized technical support and predictive maintenance contract capture represent the dominant competitive vectors.
Among European-based integrated suppliers, ANDRITZ and HUBER SE occupy positions anchored by global service networks and German-speaking market penetration. ANDRITZ exemplifies the system integrator archetype through multi-year operator agreements across European wastewater utilities. HUBER SE represents specialized sludge handling expertise with localized technical support concentration. Mitsubishi Kakoki Kaisha sits within the Asian system integrator tier, dominating municipal procurement through integrated dewatering and drying packages in Japanese and East Asian coastal markets. These three anchors demonstrate how regional regulatory alignment and service infrastructure investment determine competitive positioning.
| Leading Market Players |
|---|
| ANDRITZ |
| HUBER SE |
| Mitsubishi Kakoki Kaisha |
| Voith |
| Veolia Water Technologies |
| SUEZ |
| Aqseptence Group |
| Fournier Industries |
| IHI Corporation |
| Others |
Pricing and Supply Chain Analysis
Precision-machining expertise concentrated in German and Japanese supplier workforces creates labor-cost differentials that widen pricing-tier spreads between premium system integrators and regional fabricators. Municipal buyers in Europe and East Asia absorb these premiums for predictive maintenance convergence and localized technical support, while budget-constrained processors in emerging markets gravitate toward standardized mechanical configurations with thinner service margins.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for mid-tier mechanical press configurations. Three-tier pricing structure across premium, standard, and economy levels separates integrated dewatering-drying packages from standalone screw press units and compact food-processing models. Price differentiation hinges on ISO 9001 certification tier and after-sales service bundling depth. Pricing pressure stems from stainless steel input volatility compressing fabricator margins. Food manufacturers exhibit highest price sensitivity due to compressed capital approval cycles, while municipal utilities prioritize total cost of ownership over upfront outlay.
Supply Chain Analysis
Freight cost escalation for precision-machined helical screws and tapered screen assemblies is amplifying geographic supply concentration effects. Manufacturing gravity centers on Germany, Japan, and China for captive metallurgy capabilities and multi-axis CNC capacity. Component sourcing draws from austenitic stainless steel mills, electropolished wedge wire foundries, and servo-controlled actuator suppliers. Single-source vulnerability concentrates in specialized wear-resistant alloy formulations for helical screw production. Distribution runs through direct OEM channels for municipal utilities and specialized industrial distributors for food processing and mining segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Screw Press Dewatering Machine Market functions as a stable compounder, with regulatory tightening across EPA, EU, and East Asian jurisdictions ensuring replacement-driven demand continuity regardless of macroeconomic cyclicality.
For Market Incumbents: Hedge centrifuge substitution risk in high-throughput mining applications by deepening captive metallurgy capabilities for extreme-pressure hydraulic configurations. Lock in municipal renewal cycles through multi-year predictive maintenance contracts that embed remote condition monitoring. Prioritize CE marking and ISO 9001 certification maintenance to preserve European tender eligibility against Asian challengers.
For New Entrants and Emerging Players: Launch via regional maintenance provider partnerships to capture aftermarket service unbundling opportunities in mid-sized US utilities with in-house mechanical expertise. Target food processing liquid waste recovery as the most penetrable segment, where batch operational patterns and space constraints favor compact single-shaft configurations underserved by municipal-focused incumbents. Lead with energy-efficient electric press technology to differentiate on sustainability credentials.
For Investors and Strategic Acquirers: Water infrastructure specialists are the most active acquirer in this space, seeking dewatering technology tuck-ins to complement membrane and biological treatment portfolios. The five-to-ten year viability thesis rests on sludge volume reduction becoming non-discretionary infrastructure under tightening landfill restrictions. Acquisition target archetype: regional fabricators with captive CNC capacity and established aftermarket service relationships. Watch for EU urban wastewater treatment directive revision timing as the signal for preemptive European upgrade cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contract Capture | ANDRITZ and HUBER SE lock in multi-year operator agreements across German wastewater utilities. |
| Integrated Dewatering-Drying System Launch | Mitsubishi Kakoki Kaisha bundles thermal processing to minimize vendor interface complexity in Tokyo Bay. |
| Electropolished Wedge Wire Screen Technology | Self-cleaning designs reduce manual intervention frequency for high-fiber sludge in Japanese municipal plants. |
| Heat-Pump Dryer Configuration Development | Asian system integrators bypass F-Gas Regulation restrictions with refrigerant-free thermal pathways. |
| Regional Maintenance Provider Partnership | Specialized service unbundling creates openings for mid-sized US utilities with self-perform capability. |
Research Methodology
Bottom-up municipal and industrial procurement modeling reconciled against top-down OEM shipment tracking forms the analytical core of this study. Primary interviews with maintenance directors at wastewater treatment plants, plant engineers at food processing facilities, OEM procurement teams, and aftermarket service heads informed demand-side assumptions. Secondary validation drew from EPA 40 CFR Part 503 enforcement data, EU urban wastewater treatment directive implementation reports, METI efficiency standard filings, and customs records for precision-machined screw press components. Triangulation across these sources anchored volume and value estimates.
Input-output matrices mapped screw press deployment across shaft configurations, press technologies, and end-use environments. Segmentation dimensions modeled include product type, technology tier, application vertical, and end-user industry classification. CAGRs were derived from regression analysis of historical replacement cycles against regulatory compliance deadline clustering. Industry-specific forecast inputs incorporated stainless steel price indices and municipal capital budget approval timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt stainless steel price spikes or accelerated EU directive revision schedules. Model assumptions reflect documented regulatory enforcement patterns and OEM capacity expansion announcements. A model refresh is warranted upon material change in EPA biosolids rule interpretation or East Asian landfill restriction tightening.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Asia-Pacific Agricultural Shredder Machine Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
Feed Screw Barrel Market
Agricultural Processing Equipment
Global Dry Milling Market
Agricultural Processing Equipment
Shelling Machine Market
Agricultural Processing Equipment
Dal Mill Machine Market
Agricultural Processing Equipment
Combine Harvesters Market
Agricultural Processing Equipment
Tobacco Drying Machines Market
Agricultural Processing Equipment
Sugarcane Harvesters Market
Agricultural Processing Equipment
Global Rice Milling Market
Agricultural Processing Equipment
Global Egg Processing Market
Agricultural Processing Equipment
Meat Processing Equipment Market
Agricultural Processing Equipment
Solar Herbs Dryer Market
Agricultural Processing Equipment
Animal Feed Processing Equipment Market
Agricultural Processing Equipment
Rice Milling Machines Market