
 Iridium Spark Plug Market | 2026-2036
Iridium Spark Plug Market Size, Share, and Industry Trends Forecast 2026-2036
Iridium Spark Plug Market Foresight
Performance enthusiast demand is broadening the end-use vertical mix beyond traditional automotive OEM channels. NGK Spark Plugs Co. Ltd. dominates fine-wire manufacturing scale across Asia-Pacific production bases. Robert Bosch GmbH leverages its integrated ignition systems portfolio to control OEM supply relationships in Europe. Denso Corporation anchors hybrid-gasoline platform specifications through direct collaboration with Japanese automakers.
An iridium spark plug is a spark-ignition device featuring a center electrode composed primarily of iridium, a platinum-group metal with a melting point exceeding 2,400°C, typically alloyed with platinum or rhodium and manufactured via powder metallurgy and laser welding to deliver extended service life beyond 100,000 miles in gasoline engines. Its primary commercial purpose is to provide consistent, high-energy ignition in high-compression or lean-burn engine architectures where conventional nickel-alloy electrodes degrade prematurely. Double iridium configurations command premium positioning in long-life OEM specifications, while racing iridium variants occupy niche margin pools among motorsport and high-performance aftermarket segments. Aftermarket providers represent the volume foundation, though fleet services installation channels are gaining structural importance as commercial vehicle operators prioritize total cost of ownership over upfront component pricing.
EPA tailpipe standards, Euro 7 emission frameworks, and China's GB 18352.6 regulations collectively mandate tighter combustion control, directly elevating iridium spark plug specifications as lower-emission engine calibrations require precise, durable ignition timing. NHTSA fuel economy requirements in the US and the EU Green Deal's transport decarbonization targets further reinforce OEM demand for extended-life ignition components that maintain efficiency across longer replacement cycles. Stakeholders must monitor evolving alloy sourcing constraints for iridium and platinum-group metals, as geopolitical concentration in South African and Russian supply corridors introduces procurement risk that could reshape component economics and regional manufacturing strategies.
Market Dynamics
Turbocharged direct-injection gasoline engines are forcing iridium spark plug specifications upward as combustion pressures and temperatures exceed nickel-alloy electrode durability limits, compressing replacement intervals and elevating OEM procurement standards.
Growth Catalysts
- EPA Tier 3 tailpipe standards:Tighter combustion control mandates in the United States require precise ignition timing that only fine-wire iridium electrodes can sustain across extended service cycles.
- Turbocharged direct-injection architectures:Gasoline engine downsizing for fuel economy generates higher cylinder pressures that degrade conventional spark plugs prematurely, accelerating iridium adoption.
- China's domestic engine production scaling:Expansion of local automotive manufacturing and aftermarket service networks concentrates volume demand in the world's largest vehicle market.
Market Restraints
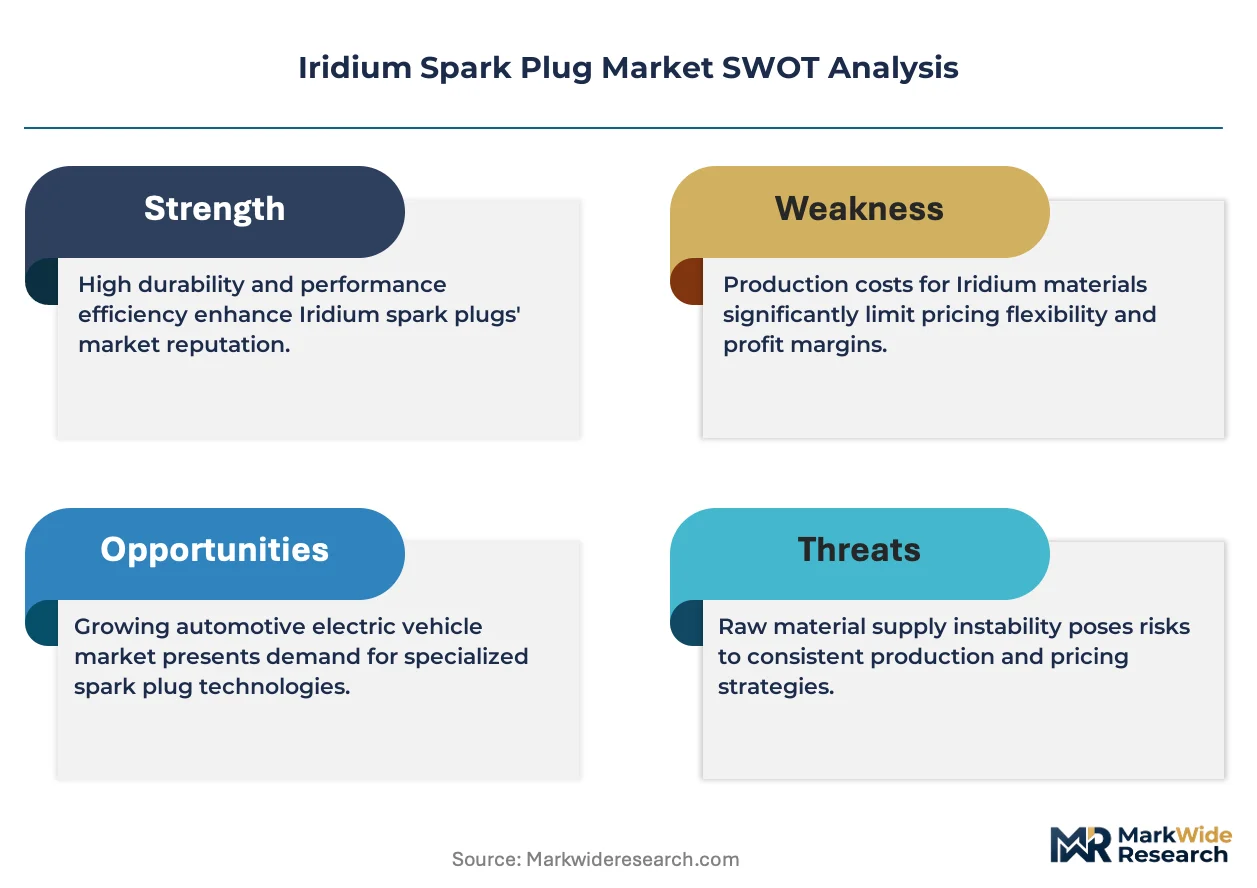
- Platinum-group metal supply concentration:Iridium extraction concentrates in South African and Russian mining corridors, exposing procurement to geopolitical disruption and price volatility.
- Double iridium cost premiums:OEM long-life specifications requiring dual iridium electrodes carry manufacturing cost multiples that compress margin pools in price-sensitive aftermarket channels.
- Electric vehicle powertrain substitution:Battery-electric platforms eliminate spark-ignition systems entirely, capping addressable market expansion in passenger vehicle segments.
Strategic Opportunities
- Euro 7 emission framework compliance:Upcoming European standards mandate lean-burn engine calibrations that demand iridium durability, creating specification upgrade cycles across existing vehicle fleets.
- Commercial vehicle fleet services:Total cost of ownership calculations by logistics operators favor extended-life ignition components, opening volume channels beyond traditional retail aftermarket.
- Racing and motorsport aftermarket:Performance enthusiast segments accept premium pricing for specialized iridium variants with optimized heat ranges and electrode geometries.
Industry Challenges
- Powder metallurgy and laser welding skill scarcity:Fine-wire electrode manufacturing requires specialized metallurgical expertise that concentrates at established Asian production bases.
- Extended replacement interval compression:100,000-mile service life claims reduce absolute unit demand velocity, forcing manufacturers to capture value through specification upgrades rather than volume.
- Alloy sourcing certification complexity:Conflict mineral traceability requirements and responsible mining standards add procurement documentation burdens across platinum-group metal supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iridium Spark Plug Market |
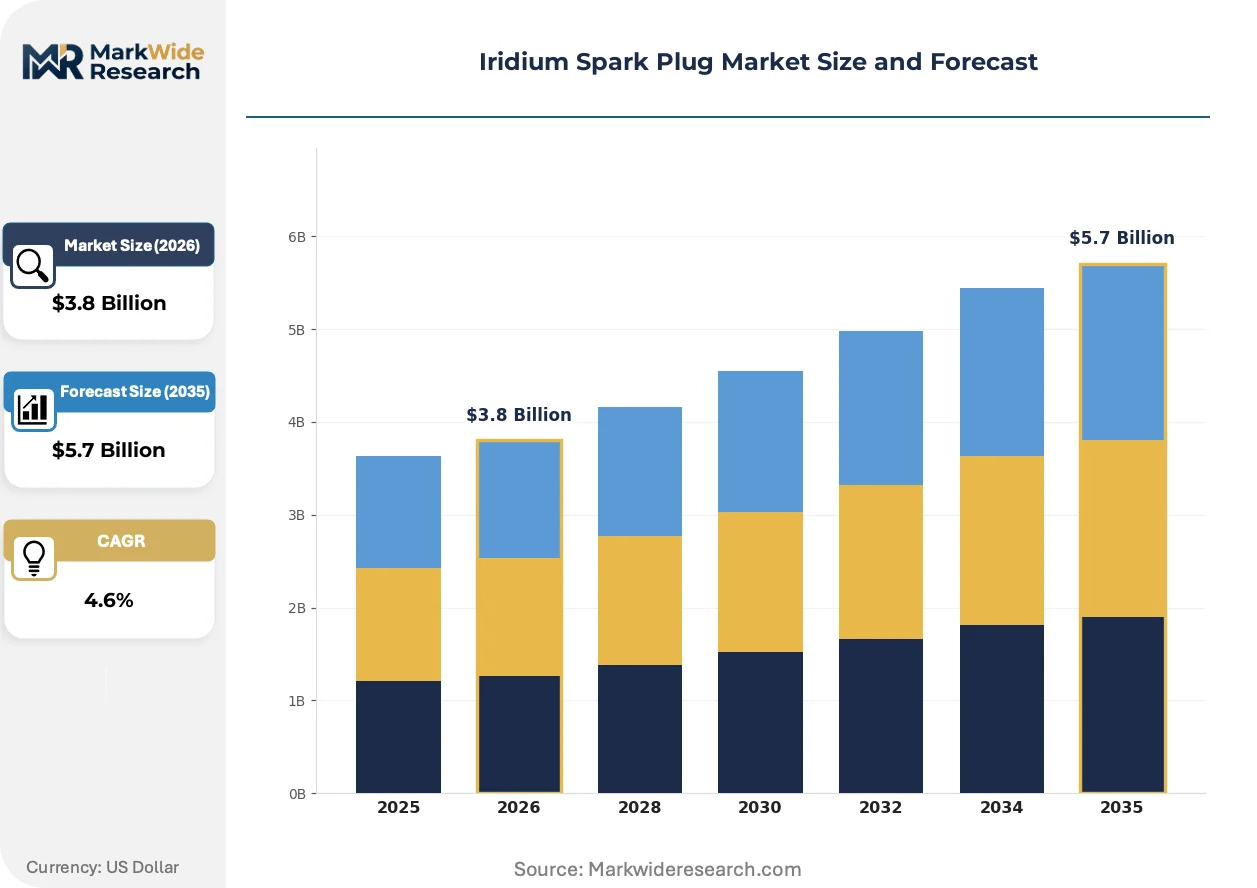
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Iridium, Iridium Fine Wire, Double Iridium, Racing Iridium End User: Automotive OEMs, Aftermarket Providers, Performance Enthusiasts, Service Centers Installation Type: DIY, Professional, Fleet Services, Specialized Installations Application: Gasoline Engines, Diesel Engines, Motorsports, Auxiliary Applications |
| Companies Covered | Federal-Mogul Corporation, ACDelco, NGK Spark Plugs Co. Ltd., Holley Performance Products, Magneti Marelli S.p.A, Denso Corporation, Hella KGaA Hueck & Co., Weichai Power Co. Ltd., Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iridium Spark Plug Market Shifts & Advancements
Ignition system architecture is converging with engine management electronics as combustion precision demands tighten, reshaping how spark plug specifications are validated and procured across OEM and aftermarket channels.
Laser-welded iridium-rhodium alloys are integrating into center electrode designs to withstand peak firing pressures exceeding 150 bar in downsized turbocharged engines. Tier 1 suppliers are adopting these configurations for 2026 model year powertrains. This metallurgical advancement is integrating ignition component specifications directly into engine calibration software, eliminating aftermarket interchangeability.
China's GB 18352.6 emission regulations are mandating onboard diagnostic systems that monitor misfire detection with greater sensitivity. Engine control modules now flag ignition degradation before perceptible drivability loss. This diagnostic precision is compressing replacement trigger points and elevating iridium specifications in domestic Chinese production.
Commercial fleet operators are consolidating ignition maintenance through authorized service networks rather than independent repair channels. Long-haul trucking and delivery van segments in the United States are bundling spark plug replacement into powertrain service contracts. This channel concentration is visible most acutely in California and Texas logistics corridors where EPA compliance enforcement is strictest.
Iridium Spark Plug Market Segmentation
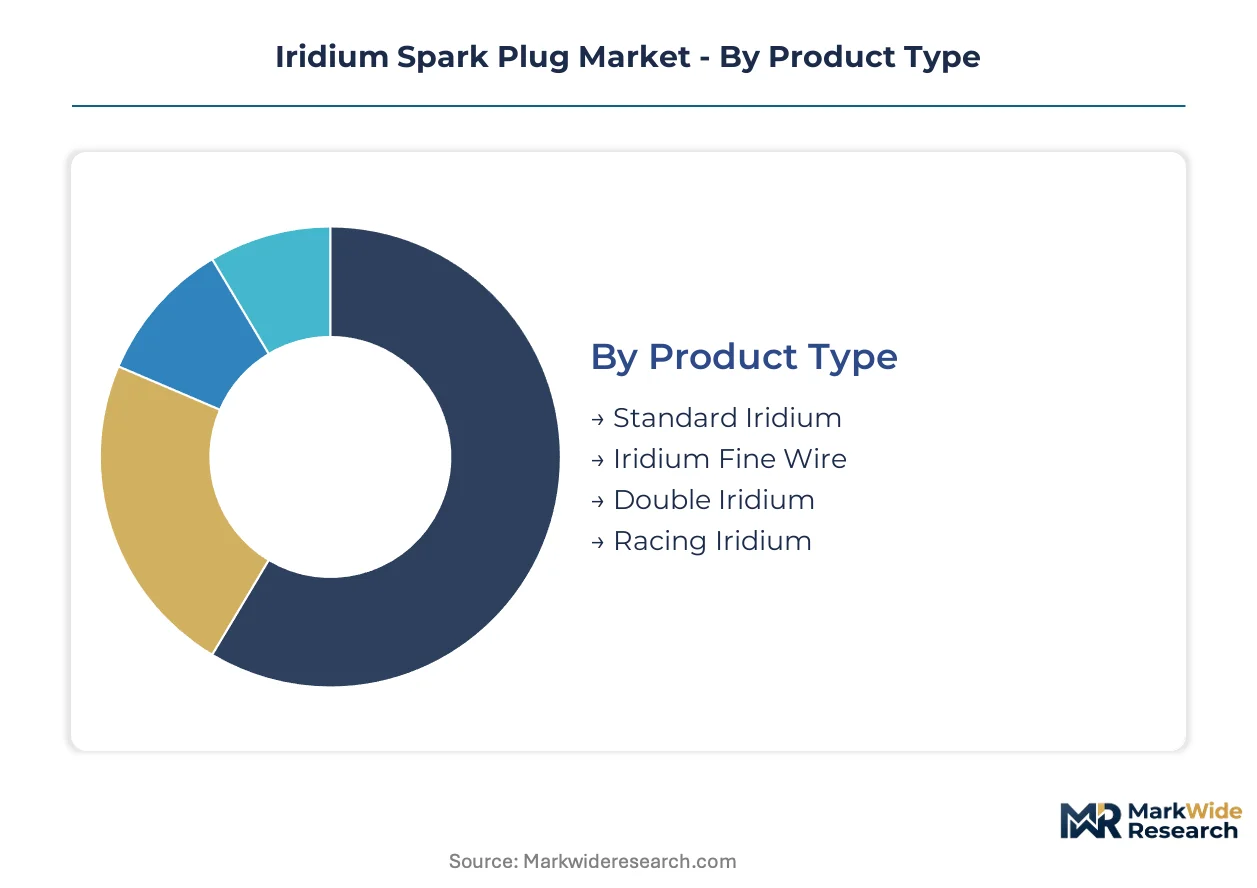
Iridium spark plug procurement decisions hinge on service interval expectations, combustion environment severity, and total cost of ownership calculations across divergent end-use contexts. Segmentation reveals how specification tiers align with buyer willingness to pay for electrode durability versus replacement frequency trade-offs.
Product Type:
Purchase volume concentrates where replacement cycle compression justifies electrode material premiums against labor cost economics.
- Iridium Fine Wire:Center electrodes measure 0.4-0.6mm diameter, manufactured via powder metallurgy and laser welding to reduce voltage requirements and improve ignitability in lean-burn calibrations. Turbocharged direct-injection gasoline engines in Germany, Japan, and the United States specify this configuration for OEM factory fill as EPA Tier 3 and Euro 7 thresholds tighten combustion precision demands.
- Double Iridium:Both center and ground electrodes carry iridium or iridium-rhodium alloys, extending service intervals beyond 100,000 miles. Premium passenger vehicle platforms and commercial fleet operators in California and Texas logistics corridors favor this specification where downtime minimization outweighs upfront cost multiples.
- Standard Iridium:Single iridium center electrode with conventional nickel-alloy ground, balancing durability and cost for mainstream replacement cycles.
- Racing Iridium:Specialized heat range configurations with optimized electrode geometries for sustained high-RPM operation.
Iridium Fine Wire leads on scale; Double Iridium leads on momentum.
End User:
Channel concentration shapes margin capture as procurement authority shifts from retail consumers to consolidated fleet operators and integrated OEM supply chains.
- Automotive OEMs:Factory-fill specifications lock in multi-year supply agreements with ignition system integrators, with turbocharged gasoline engine programs in China, Germany, and Japan driving volume concentration.
- Aftermarket Providers:Retail and wholesale distribution channels serve replacement demand across vehicle age cohorts, with pricing sensitivity highest in price-tier competition against nickel-alloy alternatives.
- Performance Enthusiasts:Motorsport and tuning segments accept 3-5x pricing premiums for specialized heat ranges and electrode geometries, with demand clustering in Southern California, Osaka, and Stuttgart aftermarket hubs.
- Service Centers:Authorized dealer networks and independent repair facilities control installation labor revenue, increasingly bundling spark plug replacement into scheduled maintenance packages.
Aftermarket Providers anchor volume throughput; Service Centers are expanding most quickly.
Installation Type:
Labor skill requirements and diagnostic equipment access determine channel viability for fine-wire electrode handling and engine calibration integration.
- Professional:Certified technicians with torque-controlled installation tools and onboard diagnostic interfaces dominate warranty-compliant replacement, particularly for direct-injection engines requiring coil-on-plug extraction expertise.
- Fleet Services:Consolidated maintenance contracts for commercial vehicle operators prioritize extended-life specifications and predictive replacement scheduling based on telematics data.
- DIY:Consumer self-installation persists in older vehicle segments with accessible engine bays and conventional ignition architectures.
- Specialized Installations:Racing teams and performance shops demand custom gapping and heat range selection for modified engine calibrations.
Professional installation commands margin; Fleet Services show steepest expansion trajectory.
Application:
Combustion chemistry and thermal loading profiles dictate electrode material selection and replacement interval engineering.
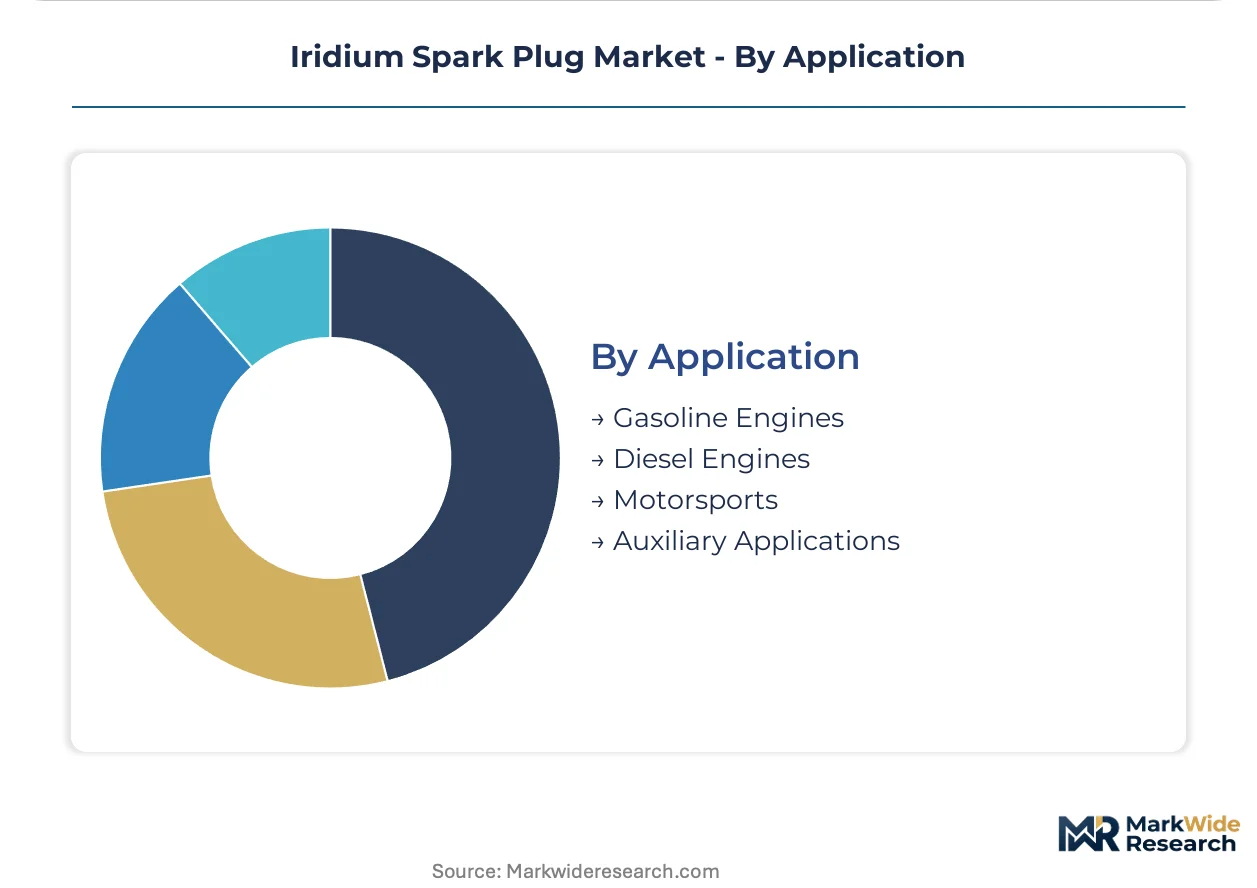
- Gasoline Engines:Spark-ignition architectures across port-injection and direct-injection configurations constitute the core addressable market, with downsized turbocharged variants generating highest iridium specification rates.
- Motorsports:Sustained high-load operation with aggressive ignition timing advances accelerates electrode erosion, driving demand for premium iridium-rhodium alloys in Formula, NASCAR, and endurance racing series.
- Diesel Engines:Compression-ignition architectures eliminate spark plugs entirely; this segment captures glow plug applications where iridium specifications remain marginal.
- Auxiliary Applications:Stationary generators, marine outboards, and small-engine equipment represent fragmented demand with extended replacement cycles.
Gasoline Engines dominate absolute volume; Motorsports deliver premium margin extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers exploit cost-of-compliance gaps between emission enforcement regimes, migrating fine-wire electrode production toward jurisdictions with streamlined environmental permitting and concentrated PGM refining infrastructure.
China
Domestic engine production scaling and aftermarket network densification concentrate demand in Yangtze River Delta manufacturing clusters. GB 18352.6 regulations mandate onboard diagnostic sensitivity that elevates iridium specifications for misfire detection compliance. Shanghai and Jiangsu Province host the fastest-expanding spark plug finishing capacity serving both local OEM factory-fill and export aftermarket channels.
United States
California and Texas logistics corridors drive fleet services consolidation as commercial operators prioritize total cost of ownership calculations. EPA Tier 3 tailpipe standards enforce precise ignition timing requirements that only fine-wire iridium electrodes sustain across extended service cycles. Detroit's powertrain engineering centers specify double iridium configurations for turbocharged direct-injection gasoline platforms.
Germany
Euro 7 emission framework preparation accelerates lean-burn engine calibration development requiring iridium durability thresholds. Stuttgart's automotive OEM headquarters anchor ignition system integration partnerships with tier-1 suppliers. Bavaria's precision manufacturing corridor hosts powder metallurgy expertise for laser-welded electrode production serving premium passenger vehicle specifications.
Japan
Hybrid-gasoline platform proliferation sustains OEM demand for extended-life ignition components through collaborative specification development. METI industrial policy supports domestic PGM alloy processing capabilities. Osaka's aftermarket hub clusters performance enthusiast demand for specialized heat range configurations.
South Korea
Domestic automaker powertrain downsizing strategies elevate iridium adoption rates in turbocharged gasoline architectures. Seoul Capital Area engineering centers integrate ignition specifications directly into engine management software. Busan-Ulsan manufacturing complexes supply finished spark plug assemblies for regional export markets.
Iridium Spark Plug Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with OEM factory-fill relationships concentrating around integrated ignition system providers while aftermarket channels fragment across price-tier competition. The structure tiers into three archetypes: vertically integrated automotive suppliers controlling multi-year supply agreements, independent component specialists capturing retail replacement volume, and regional fabricators serving price-sensitive emerging markets. Dominant competitive moves include strategic partnerships for PGM alloy sourcing security and geographic expansion into Chinese domestic production bases.
Among Japanese specialists, NGK Spark Plugs Co. Ltd. and Denso Corporation exemplify the integrated tier-one archetype through their positioning within Asia-Pacific OEM supply chains. Robert Bosch GmbH represents the European diversified industrial model, leveraging cross-product ignition portfolio breadth. Federal-Mogul Corporation occupies the independent aftermarket specialist position, with geographic naming suggesting North American operational roots.
| Leading Market Players |
|---|
| Federal-Mogul Corporation |
| ACDelco |
| NGK Spark Plugs Co. Ltd. |
| Holley Performance Products |
| Magneti Marelli S.p.A |
| Denso Corporation |
| Hella KGaA Hueck & Co. |
| Weichai Power Co. Ltd. |
| Robert Bosch GmbH |
| Others |
Supply & Pricing Matrix
Powder metallurgy specialists concentrated in Aichi Prefecture and Bavaria command wage premiums that translate directly into manufacturing cost spreads between premium double-iridium configurations and standard single-electrode alternatives. Labor-cost differentials between Japanese precision manufacturing corridors and emerging Asian finishing bases create pricing-tier spreads that OEM procurement teams exploit across factory-fill and aftermarket channels. EPA Tier 3 compliance costs and Euro 7 calibration requirements further stratify what buyers pay for equivalent electrode durability.
Pricing Analysis
Distributor margin layers absorb the steepest compression as double-iridium specifications carry manufacturing cost multiples that challenge price-sensitive aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels separates OEM factory-fill agreements from retail replacement and budget private-label alternatives. Price differentiation hinges on certification grade for emission-system compatibility and volume scale in multi-year procurement contracts. Pricing pressure stems from nickel-alloy alternatives in aging vehicle fleets where total cost of ownership calculations favor frequent replacement over premium electrode investment. Fleet operators show least price sensitivity; independent repair channels show most.
Supply Chain Analysis
Freight cost escalation on platinum-group metal concentrates from Johannesburg and Norilsk to Asian refining centers elevates landed input costs for electrode manufacturers. Iridium extraction concentrates in South Africa and Russia; laser welding equipment and powder metallurgy feedstock draw from Germany and Japan. Raw material dependencies include iridium sponge, rhodium alloy additives, and high-purity nickel substrates. Single-source vulnerability in South African mining corridors exposes procurement to geopolitical disruption. Distribution runs through tier-1 ignition system integrators serving OEM assembly plants, with aftermarket volume flowing through authorized dealer networks and independent parts distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The iridium spark plug market functions as a stable compounder anchored by regulatory emission standards that mandate precise ignition timing across increasingly durable service intervals. Turbocharged direct-injection proliferation sustains specification upgrades even as electric vehicle substitution caps absolute volume expansion.
For Market Incumbents: Deepen backward integration into PGM alloy processing to insulate margin pools from South African and Russian supply corridor volatility. Secure multi-year offtake agreements with mining concentrators before geopolitical disruption reshapes spot market availability. Expand finishing capacity in Yangtze River Delta clusters to capture Chinese domestic OEM factory-fill growth. Prioritize laser welding skill retention in Aichi and Bavaria production bases where capability scarcity threatens quality consistency. For New Entrants and Emerging Players: The price-point gap between double-iridium OEM specifications and standard iridium aftermarket alternatives creates entry space for mid-tier positioning. Target commercial fleet service networks in California and Texas logistics corridors where predictive maintenance contracts favor extended-life specifications. Pursue white-label manufacturing partnerships with established Asian powder metallurgy specialists to bypass capital-intensive electrode fabrication. Emphasize GB 18352.6 diagnostic compatibility as a go-to-market wedge against incumbent interchangeability limitations. For Investors and Strategic Acquirers: Automotive Tier 1 suppliers with integrated ignition portfolios are the most active acquirer in this space, seeking electrode manufacturing capabilities to complete system-level offerings. The five-to-ten year viability window favors targets with established OEM qualification records and captive PGM sourcing relationships. Acquisition focus should center on mid-scale specialists with laser welding expertise concentrated in Japan or Germany. Watch battery-electric vehicle penetration rates in premium passenger segments as the critical inflection signal for gasoline ignition component demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| PGM Alloy Sourcing Security Partnership | Long-term offtake agreements with South African concentrators reduce exposure to Russian supply disruption. |
| Laser Welding Capacity Expansion | Additional powder metallurgy finishing lines in Jiangsu Province capture Chinese OEM factory-fill growth. |
| Fleet Services Channel Integration | Direct maintenance contracts with California logistics operators bypass fragmented retail aftermarket competition. |
| Euro 7 Calibration Pre-Qualification | Early validation with Stuttgart OEM engineering centers locks in specification upgrade cycles. |
| Hybrid Platform Specification Collaboration | Joint development with Japanese automakers secures extended-life ignition content in gasoline-electric architectures. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build convergent validity across market sizing and demand driver assessment. Primary fieldwork engaged Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel managers, and commercial fleet maintenance operators across Asia-Pacific, European, and North American production corridors. Secondary validation drew from vehicle production databases, EPA certification filings, Euro 7 regulatory drafts, customs trade records for platinum-group metal concentrates, and SEC disclosures from listed automotive component manufacturers. Bottom-up segment aggregation and top-down macroeconomic anchoring were cross-checked for consistency.
Segment-weighting approaches distributed total market value across product type tiers, end-user channel categories, installation method classifications, and regional production clusters. The analytical framework modeled demand evolution across the projection horizon without assuming discrete technology discontinuities. CAGRs were derived from fitted growth curves applied to baseline volume data, adjusted for regulatory phase-in schedules and powertrain mix shifts. Key forecast inputs included turbocharged gasoline engine production forecasts, PGM price volatility scenarios, and electric vehicle substitution elasticity estimates by vehicle class.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for gasoline engine longevity and associated ignition component replacement cycles. Forecasts reflect documented assumptions regarding emission regulation enforcement timing and hybrid platform proliferation rates. A model refresh is warranted upon material change in Chinese domestic OEM sourcing preferences or South African mining labor stability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
CNG Powertrain Market
Powertrain
Automotive Fuel Pressure Regulator Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Industrial Diesel Turbocharger Market
Powertrain
Automotive Fluid Reservoir Market
Powertrain
United States Electro Hydraulic Power Steering Market
Powertrain
Global Automotive GD Injector Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Mexico Electrically Powered Hydraulic Steering Market
Powertrain
Power Liftgate for Automotive Market
Powertrain
Asia-Pacific Torque Vectoring Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market
Powertrain
India Automotive Engine Oils Market