
 Power Liftgate for Automotive Market | 2026-2036
Power Liftgate for Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Power Liftgate for Automotive Market Insights
Fleet buyers and premium SUV consumers are redrawing power liftgate procurement priorities toward hands-free and programmable height systems. Brose Fahrzeugteile GmbH & Co. KG leverages its vertical integration in motor and electronics manufacturing to dominate European OEM supply chains. Magna International Inc. anchors North American production through dedicated stamping and assembly facilities in Michigan and Ontario. Aisin Corporation specializes in compact actuator designs that navigate the packaging constraints of Japanese kei-car and compact crossover platforms.
A power liftgate is an electromechanical rear cargo access system comprising DC motors, spindle drives, torque sensors, and control modules that automate hatch opening and closing via touchless gesture or remote activation. The assembly typically operates at 12V with anti-pinch force thresholds calibrated to 100N maximum under FMVSS 118 standards, serving both convenience and occupant protection functions. Electric liftgate configurations lead volume shipments while touch sensor technology captures the fastest expansion as OEMs eliminate physical contact points. Aftermarket suppliers occupy a mature margin pool concentrated in replacement strut and controller retrofit kits for vehicles three to eight years post-sale.
NHTSA mandates FMVSS 118 power-operated window and door systems compliance, while Euro NCAP protocols reward active pedestrian protection where powered liftgates integrate automatic reversal. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces type approval for electromagnetic compatibility of motor-driven closure systems. Stakeholders must monitor how software-defined vehicle architectures reshape controller hardware requirements and supplier qualification timelines.
Market Dynamics
Hands-free gesture recognition is compressing controller hardware architectures while forcing actuator suppliers to consolidate sensor fusion capabilities into single-module designs.
Growth Catalysts
- FMVSS 118 Anti-Pinch Mandates:US NHTSA calibration requirements for 100N maximum closure force are standardizing torque sensor integration across all powered rear closure systems, expanding addressable component volumes.
- Crossover Platform Proliferation:C-segment utility vehicle architectures in Germany, Japan, and the United States are specifying power liftgates as standard equipment rather than trim-tier options.
- Capacitive Proximity Sensing:Foot-activated entry systems eliminate physical contact points and differentiate premium SUV offerings in crowded segments.
Market Restraints
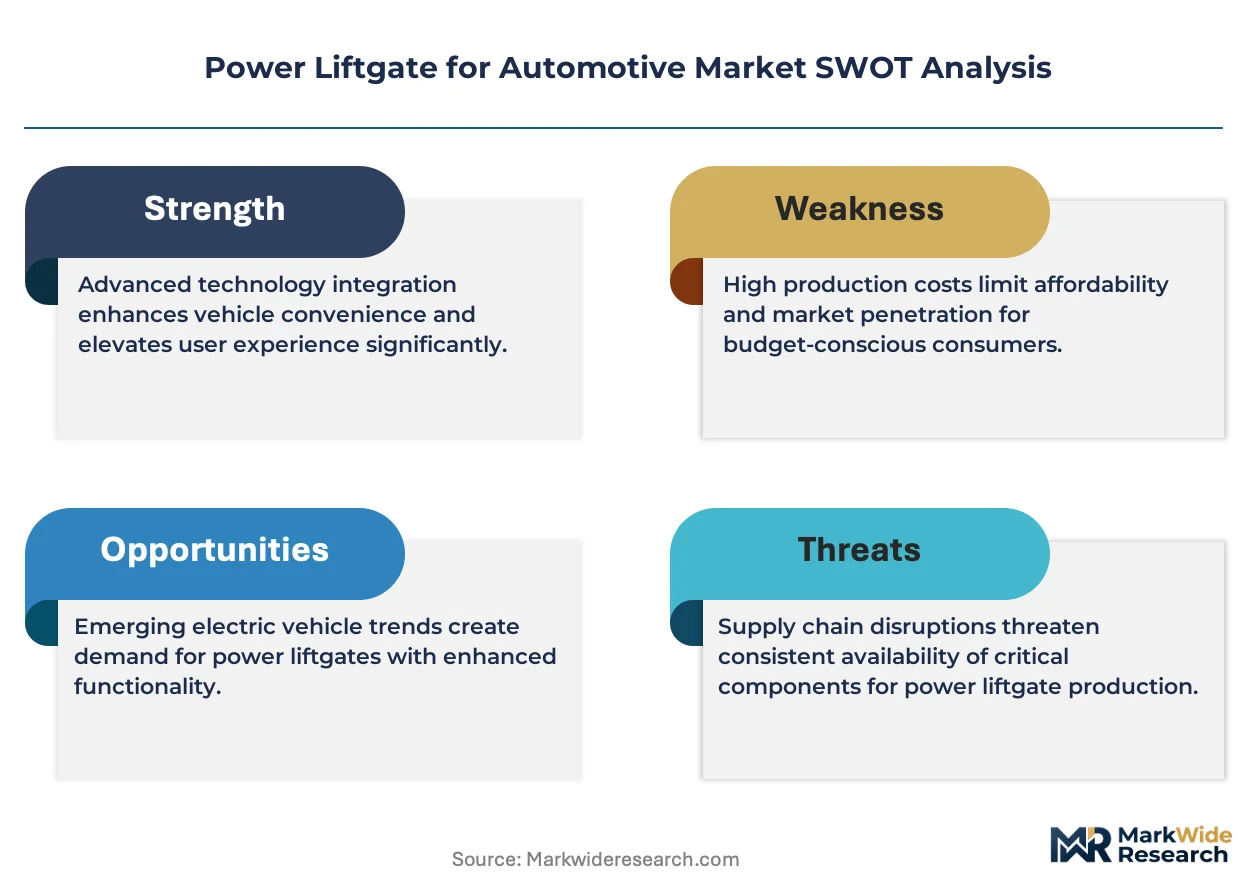
- DC Motor Magnet Cost Volatility:Neodymium and dysprosium price swings from Chinese processing concentration compress actuator margin structures unpredictably.
- Stamping Die Capital Intensity:Rear closure panel tooling requires 18-24 month payback periods that deter supplier entry into low-volume specialty vehicle programs.
- Mechanical Strut Substitution:Pneumatic and gas-charged manual liftgate systems retain cost advantage in economy compact segments where electrification penetration stalls.
Strategic Opportunities
- Software-Defined Vehicle Convergence:Controller firmware-over-the-air update capability creates recurring revenue attachment for hardware suppliers previously limited to one-time module sales.
- India Premium SUV Local Assembly:PLI scheme incentives for automotive component manufacturing attract power liftgate module production to serve domestic luxury utility vehicle demand.
- Euro NCAP Pedestrian Protection Credits:Automatic reversal algorithms triggered by capacitive edge sensors qualify for active safety scoring bonuses that OEMs prioritize in European product planning.
Industry Challenges
- Functional Safety Certification Timelines:ISO 26262 ASIL-B compliance documentation for spindle drive controllers extends qualification cycles by 8-12 months versus legacy mechanical systems.
- Legacy 12V Electrical Architecture Integration:Current draw management for multi-motor liftgate systems conflicts with start-stop and mild-hybrid voltage fluctuation constraints in aging vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Liftgate for Automotive Market |
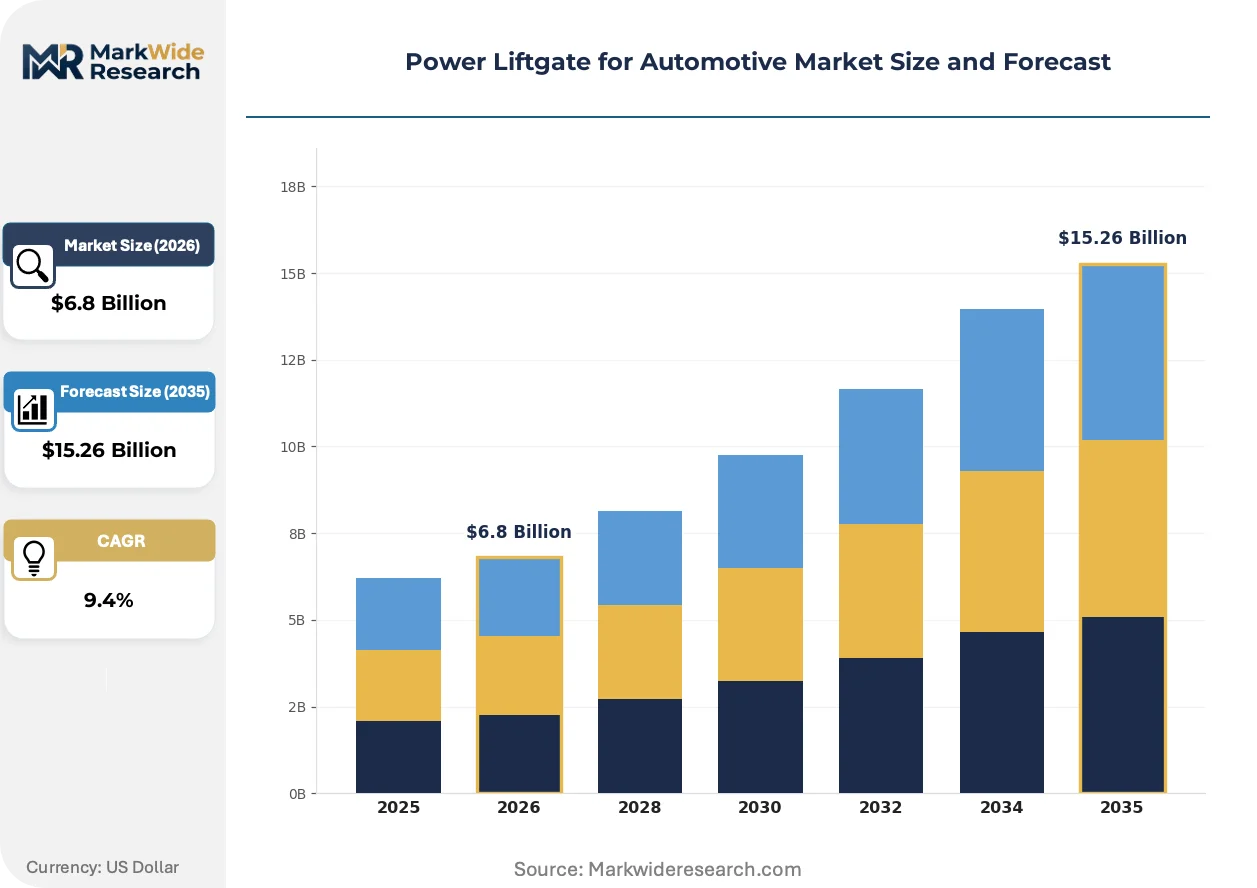
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Liftgate, Manual Liftgate, Pneumatic Liftgate, Hybrid Liftgate Technology: Touch Sensor, Remote Control, Push Button, Automatic Open/Close End User: OEMs, Aftermarket Suppliers, Automotive Tier-1s, Vehicle Assemblers Distribution Channel: Retail, Online, Direct Sales, Distributors |
| Companies Covered | Brose Fahrzeugteile GmbH & Co. KG, Magna International Inc., Aisin Corporation, Johnson Electric, Continental AG, Huf Hulsbeck & Furst GmbH & Co. KG, Hi-Lex Corporation, Faurecia SE, Grupo Antolin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Liftgate for Automotive Market Trends and Innovations
Gesture recognition algorithms and solid-state motor controls are collapsing the traditional separation between convenience features and active safety systems in rear cargo access.
Capacitive foot sensors are decomposing the discrete switch module supply chain by integrating proximity detection directly into bumper fascia wiring harnesses. Tier-1 suppliers in Germany and Japan are accelerating adoption to reduce part count and assembly labor. This consolidation is decomposing standalone controller supplier margins while rewarding integrated mechatronics capabilities.
REACH substance restrictions on hexavalent chromium plating are forcing spindle drive manufacturers to migrate toward zinc-nickel coating chemistries for corrosion resistance. The industrial consequence is qualification delays for European OEM supply chains and accelerated testing protocols for salt-spray durability. Japanese kei-car and compact crossover platforms are most affected, with suppliers redesigning compact actuator housings to accommodate thicker alternative coatings.
Fleet procurement for rental and commercial utility vehicles is unbundling after-sales service contracts from initial hardware supply, creating direct channel relationships between actuator suppliers and national fleet maintenance networks. This disintermediation of OEM parts distribution is most visible in the United States, where enterprise buyers negotiate multi-year replacement strut and controller sourcing agreements independent of vehicle purchase terms.
Power Liftgate for Automotive Market Segmentation
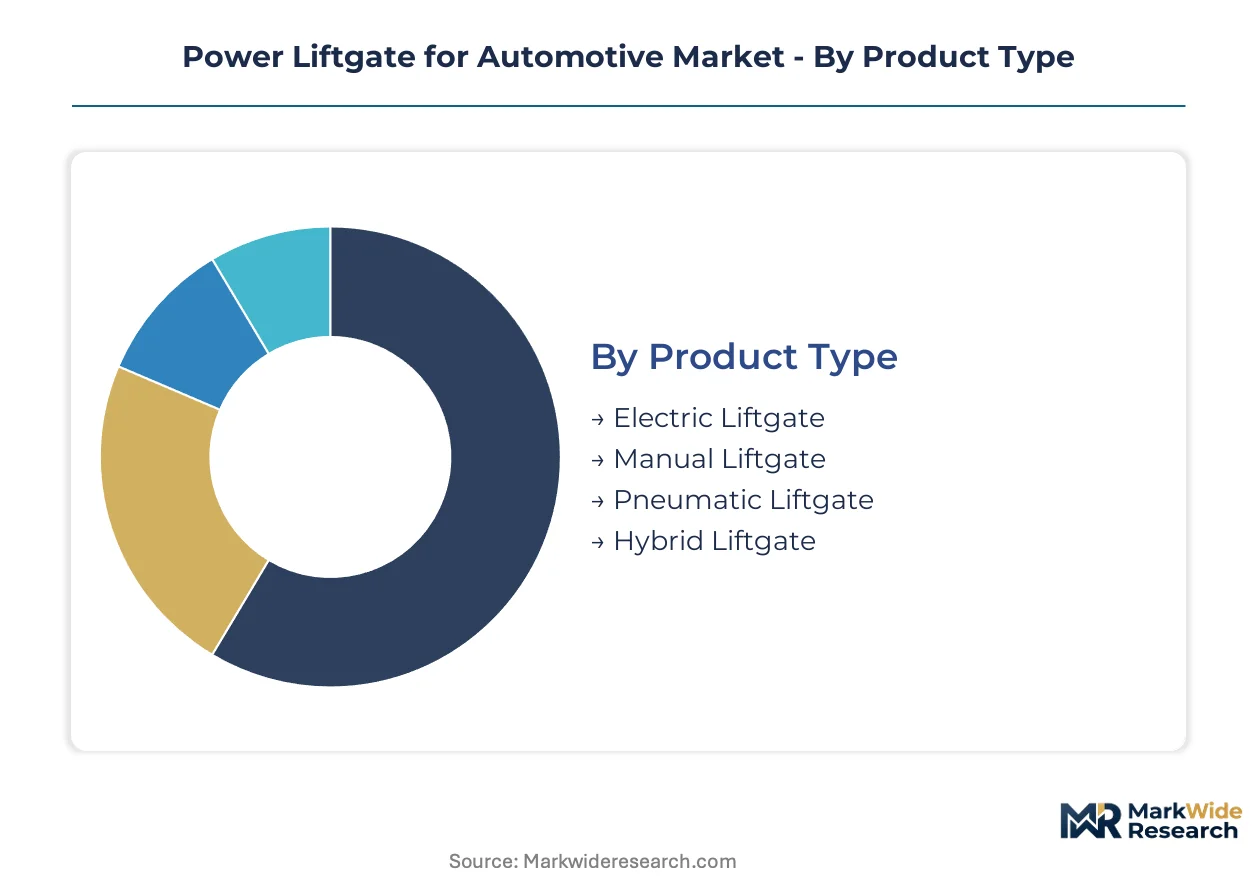
Power liftgate procurement patterns fragment sharply across product architectures and channel structures. Segment boundaries determine where suppliers capture margin versus where price competition erodes returns.
Product Type:
Margin pools concentrate in electrified configurations where motor and controller integration creates switching costs for OEMs.
- Electric Liftgate:DC motor-driven systems with spindle drives and torque sensors operate at 12V, calibrated to FMVSS 118 anti-pinch thresholds. Demand clusters in German and Japanese premium SUV platforms where hands-free entry is standard equipment.
- Manual Liftgate:Gas-charged and torsion spring mechanisms retain cost advantage in economy compact segments across India and Southeast Asia. Pneumatic and gas-charged alternatives stall electrification penetration where price sensitivity dominates procurement.
- Pneumatic Liftgate:Compressed air actuation serves commercial fleet applications requiring rapid cycle durability.
- Hybrid Liftgate:Dual-mode systems combine manual override with electric assist for emerging market versatility.
Electric liftgate holds installed capacity. Hybrid liftgate is rotating up the share rankings.
Technology:
Controller firmware and sensor fusion capabilities determine tiered pricing power across convenience versus safety-integrated systems.
- Touch Sensor:Capacitive proximity detection eliminates physical contact points, differentiating premium SUV offerings in crowded segments. Broader adoption in North American and European markets accelerates as Euro NCAP pedestrian protection credits reward automatic reversal algorithms.
- Remote Control:RF and Bluetooth-enabled activation from key fobs or smartphones serves fleet and rental vehicle operators seeking centralized access management.
- Push Button:Discrete switch modules face margin compression as bumper-integrated harnesses decompose standalone controller supply chains.
- Automatic Open/Close:Fully autonomous cargo access with programmable height memory captures luxury utility vehicle specifications.
Touch sensor commands technology premiums. Automatic open/close is climbing the fastest in specification rates.
End User:
Channel power concentrates with vehicle assemblers who bundle liftgate modules into platform supply agreements.
- OEMs:Original equipment manufacturers in Germany, Japan, and the United States specify power liftgates as standard equipment on C-segment utility architectures.
- Aftermarket Suppliers:Replacement strut and controller retrofit kits target vehicles three to eight years post-sale, occupying mature margin pools.
- Automotive Tier-1s:Dedicated stamping and assembly facilities in Michigan and Ontario anchor North American production integration.
- Vehicle Assemblers:Final assembly plants negotiate multi-year sourcing agreements that disintermediate traditional parts distribution.
OEMs hold specification authority. Aftermarket suppliers are gaining direct channel relationships with fleet maintenance networks.
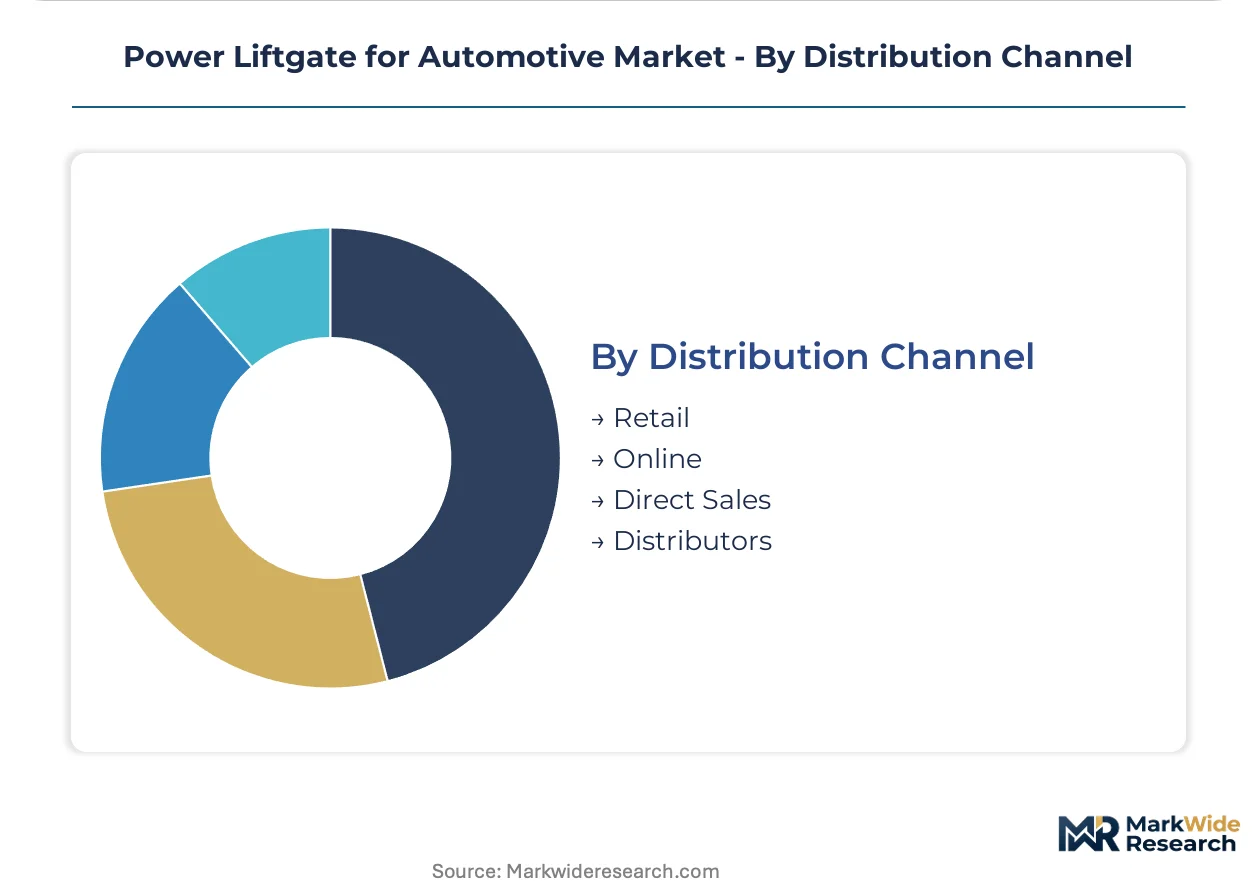
Distribution Channel:
Enterprise procurement is unbundling after-sales service from initial hardware supply, reshaping channel economics.
- Retail:Dealer parts counters serve warranty replacement and consumer upgrade demand.
- Online:E-commerce platforms capture DIY retrofit kit sales for aging vehicle parc.
- Direct Sales:National fleet maintenance networks negotiate multi-year replacement agreements independent of vehicle purchase terms.
- Distributors:Regional warehousing networks serve independent repair facilities with consolidated logistics.
Direct sales holds fleet volume concentration. Online is expanding most quickly in consumer retrofit penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German power liftgate module exports supply premium SUV assembly lines across the United States and Japan, establishing a transatlantic-Pacific trade corridor that channels European mechatronics expertise into high-volume crossover production.
Germany
Premium SUV demand from BMW and Mercedes-Benz platforms drives specification of hands-free entry systems as standard equipment. KBA vehicle type approval requirements enforce electromagnetic compatibility testing for motor-driven closure systems. Suppliers cluster in Bavaria and Baden-Württemberg, where Brose Fahrzeugteile anchors European OEM supply chains through captive motor and electronics manufacturing.
United States
Fleet procurement for rental and commercial utility vehicles accelerates direct channel relationships between actuator suppliers and national maintenance networks. NHTSA FMVSS 118 mandates 100N maximum anti-pinch closure force across all powered rear closure systems. Michigan and Ontario host dedicated stamping and assembly facilities that anchor North American production integration for Detroit Three automakers.
Japan
Compact crossover and kei-car platforms create packaging constraints that favor specialized compact actuator designs. METI enforces type approval for electromagnetic compatibility of motor-driven closure systems under transport ministry protocols. Aisin Corporation concentrates production in Aichi Prefecture, navigating space limitations through miniaturized spindle drive architectures.
China
Domestic premium SUV assembly expansion drives localization of power liftgate module production. MIIT GB standards govern vehicle electrical system safety including powered closure mechanisms. Yangtze River Delta and Pearl River Delta clusters attract component manufacturing investments serving local luxury utility vehicle demand from SAIC and Gecko platforms.
India
Premium SUV local assembly incentives under the PLI scheme attract power liftgate module production for domestic luxury utility vehicle demand. BIS certification requirements apply to automotive electrical components including motorized closure systems. Maharashtra and Gujarat host emerging supplier footprints serving Mahindra and Tata Motors premium crossover programs.
Power Liftgate for Automotive Market Competitive Landscape
Player mix skews toward integrated mechatronics specialists with captive motor and controller manufacturing capabilities. The supplier base concentrates around three strategic archetypes: vertically integrated European system houses, North American stamping-assembly integrators, and Japanese compact actuator specialists. Consolidation pressure operates through M&A targeting sensor fusion capabilities and strategic partnerships securing rare earth magnet supply chains.
Among European integrated system houses, Brose Fahrzeugteile GmbH & Co. KG exemplifies the vertically integrated archetype through its German GmbH & Co. KG structure. Magna International Inc. represents the North American stamping-assembly model with its Ontario and Michigan operational footprint. Aisin Corporation occupies the Japanese compact specialist position, reflecting the kei-car packaging constraints that shaped its actuator architecture focus.
| Leading Market Players |
|---|
| Brose Fahrzeugteile GmbH & Co. KG |
| Magna International Inc. |
| Aisin Corporation |
| Johnson Electric |
| Continental AG |
| Huf Hulsbeck & Furst GmbH & Co. KG |
| Hi-Lex Corporation |
| Faurecia SE |
| Grupo Antolin |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month stamping die payback periods compress pricing power for low-volume specialty programs while concentrating supplier margins in high-run German and Japanese premium SUV platforms. Controller firmware-over-the-air capabilities are bifurcating pricing models between one-time module sales and recurring revenue attachments, reshaping how Tier-1 suppliers capture value across the vehicle lifecycle.
Pricing Analysis
Next-generation touch sensor systems command 15-25% premiums over push-button legacy configurations, while electric liftgate assemblies price above pneumatic alternatives by a comparable spread. Three-tier pricing structure across premium hands-free, standard electric assist, and economy manual levels stratifies procurement, with OEM volume commitments and ISO 26262 ASIL-B certification tiers as primary differentiation drivers. Cost compression in economy segments stems from gas-charged strut substitution where electrification penetration stalls. Fleet buyers exhibit highest price sensitivity due to unbundled after-sales service negotiations, while luxury SUV OEMs prioritize feature differentiation over unit cost.
Supply Chain Analysis
Inventory cycles for neodymium and dysprosium magnet feedstock run 90-120 days, exposing actuator manufacturers to Chinese processing concentration and volatile rare earth pricing. Manufacturing gravity centers on Germany, Japan, and the United States, with spindle drive controllers and DC motors drawing from Taiwan semiconductor foundries and South Korean magnet suppliers. Single-source vulnerability in Chinese rare earth processing creates tariff and supply disruption exposure. Distribution runs through captive OEM platform supply agreements rather than open market channels, with aftermarket retrofit kits penetrating through direct fleet maintenance networks and e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation and OEM platform standardization are shifting bargaining power toward volume buyers, compressing supplier margins and demanding new value-capture mechanisms.
For Market Incumbents: Compound firmware-over-the-air update capabilities into recurring revenue streams to offset one-time hardware margin erosion. Deepen backward integration into rare earth magnet supply chains to mitigate Chinese processing concentration risk. Secure ASIL-B certification ahead of competitors to lock in European OEM platform specifications before qualification timelines extend further. For New Entrants and Emerging Players: Differentiate on compact actuator architectures purpose-built for Indian and Southeast Asian compact crossover platforms where electrification penetration remains nascent. Target the hybrid liftgate segment as the most penetrable white space, bridging manual cost structures with electric convenience. Pursue direct fleet maintenance network relationships to bypass established OEM parts distribution chokepoints. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized automotive closure divisions lacking sensor fusion capabilities. Frame long-term viability around software-defined vehicle convergence and controller hardware consolidation trends. Monitor NHTSA and Euro NCAP regulatory calibration changes as inflection signals for torque sensor and automatic reversal algorithm demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Module Integration | Consolidates proximity detection and motor control into single-mechatronics designs, reducing OEM assembly labor. |
| Firmware-Over-the-Air Infrastructure | Enables recurring revenue attachment for controller suppliers previously limited to one-time module sales. |
| Rare Earth Magnet Supply Partnership | Secures dysprosium and neodymium feedstock outside Chinese processing concentration to stabilize actuator margins. |
| India PLI Manufacturing Footprint | Captures domestic premium SUV assembly growth under production-linked incentive schemes for component manufacturing. |
| Euro NCAP Pedestrian Protection Certification | Qualifies automatic reversal algorithms for active safety scoring bonuses prioritized in European product planning. |
Research Methodology
The analysis maps electric liftgate, manual liftgate, pneumatic liftgate, and hybrid liftgate sub-sectors, each validated through Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and fleet maintenance network managers. Primary interview findings triangulate against vehicle production databases, IHS Markit registration data, NHTSA FMVSS 118 regulatory filings, and Euro NCAP technical protocols. Bottom-up component demand modeling and top-down OEM platform specification analysis cross-validate volume and value estimates.
Consistency checks against external benchmarks validate output plausibility across the projection horizon. The analytical framework segments by product type, technology generation, end-user channel, and regional production cluster, with CAGRs derived from fitted growth curves anchored to observed specification rates and platform proliferation timelines. Content-per-vehicle trajectories and electrification penetration curves serve as industry-specific forecast inputs.
Material uncertainties — rare earth price volatility, regulatory calibration changes, and software-defined vehicle architecture shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions about OEM platform standardization and fleet procurement consolidation trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
North America Precision Gearbox Market
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Automotive Oil Sump Market
Powertrain
South America Automotive Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Global Automotive Drive Shaft Market
Powertrain
Natural Gas Engines Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
New Energy Vehicle Scroll Compressor Market
Powertrain
Japan Automotive Engine Oils Market
Powertrain
Turbocharger Market
Powertrain
Engine Starter Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Brazil Automotive Market