
 South America Data Center Rack Market | 2026-2036
South America Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
South America Data Center Rack Market Insights
Aftermarket service revenue for rack-level thermal management and cable infrastructure is tilting from hardware vendors toward specialized integrators and facility operators. Schneider Electric SE leverages its regional service network to capture recurring maintenance contracts across Brazilian and Chilean installations. Rittal GmbH & Co. KG anchors its position through localized manufacturing and rapid cabinet configuration capabilities. Vertiv Group Corp. differentiates by controlling the cooling-to-rack integration workflow, bundling precision air handlers with enclosure sales.
Data center racks are standardized metal enclosures designed to house servers, networking equipment, and power distribution units, typically conforming to 19-inch mounting widths and load ratings exceeding 1,500 kg for dense compute configurations. Their primary purpose is to organize physical infrastructure, enable vertical space efficiency, and support airflow management for thermal dissipation in controlled environments. Enclosed racks command premium positioning in the product mix due to dust filtration and security requirements across Brazilian and Colombian facilities. Among end users, cloud service providers represent the fastest-expanding category as AWS, Azure, and Google Cloud expand local zones. Liquid cooling attachments within rack accessories are gaining traction where power densities exceed 20 kW per cabinet.
Brazil's ANATEL telecommunications regulator and the LGPD data protection authority shape deployment patterns by mandating local data residency and physical security standards for critical infrastructure. Chile's SUBTEL and Argentina's ENACOM impose analogous facility certification requirements that influence rack specification and vendor qualification processes. Stakeholders must monitor evolving national cybersecurity decrees that could mandate tamper-evident enclosure designs or biometric access integration at the rack level.
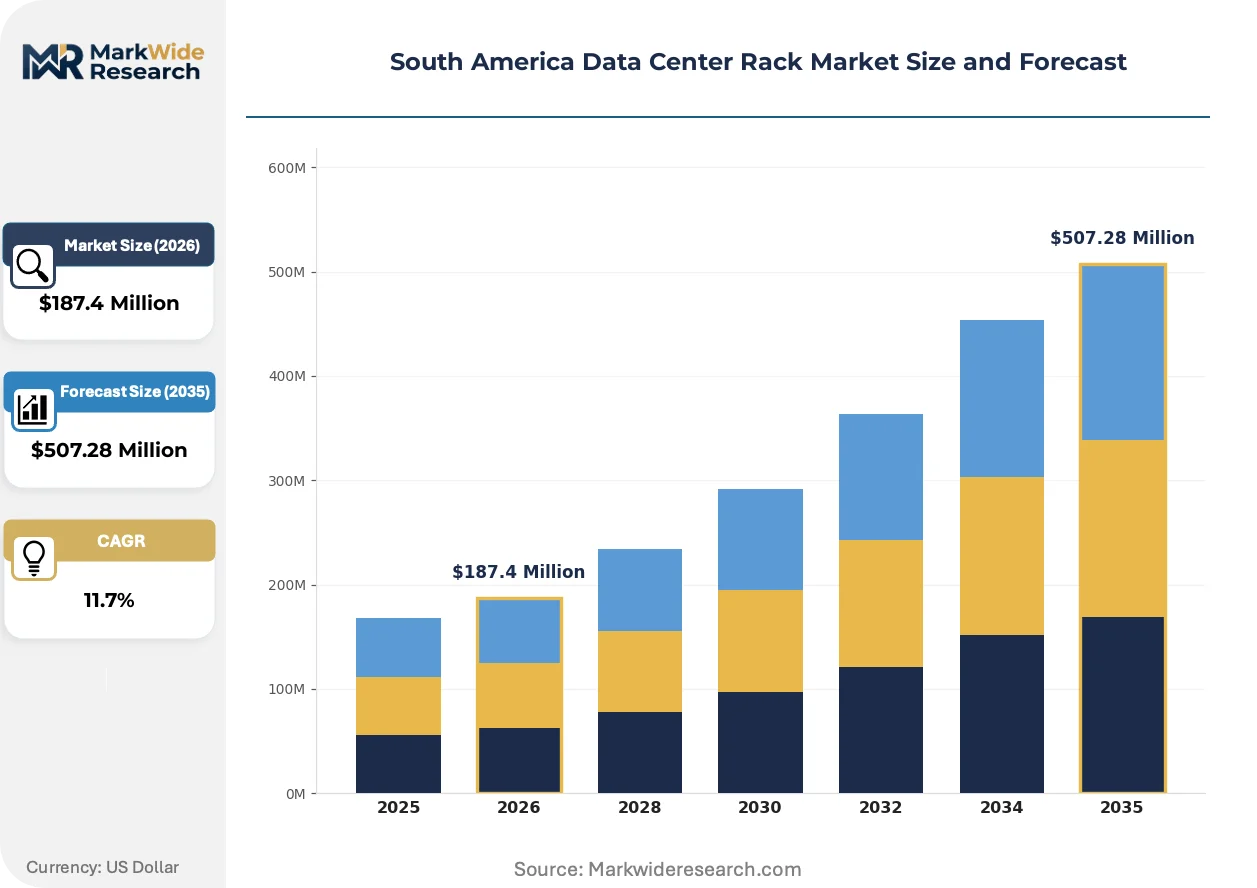
Market Dynamics
Hyperscale cloud providers are compressing procurement cycles for data center racks across South America, forcing enclosure vendors to accelerate configuration-to-delivery timelines while integrating liquid cooling compatibility into standard cabinet designs.
Growth Catalysts
- LGPD Data Residency Mandates:Brazil's data protection framework compels foreign cloud operators to establish local physical infrastructure, generating sustained rack procurement from AWS, Azure, and Google Cloud regional zone expansions.
- Edge Computing Deployments:Telecommunications operators in Chile and Argentina are installing micro data centers requiring compact, thermally optimized enclosures to support low-latency content delivery networks.
- High-Density GPU Clusters:Artificial intelligence training workloads exceeding 30 kW per rack are driving demand for reinforced structural frames and integrated liquid cooling manifolds in São Paulo's metropolitan fiber corridor.
Market Restraints
- Steel Price Volatility:Cold-rolled steel input costs fluctuate with Brazilian exchange rate instability, compressing margin predictability for cabinet manufacturers serving price-sensitive mid-market colocation operators.
- Import Dependency for Precision Components:Rack-level power distribution units and intelligent cooling sensors concentrate sourcing from East Asian suppliers, exposing lead time risks to Argentine and Colombian project timelines.
- Limited Local Fabrication Capacity:Domestic metalworking infrastructure in Peru and Ecuador lacks precision laser cutting capabilities for complex cable management integration, constraining rapid customization.
Strategic Opportunities
- Colombia's Untapped Secondary Markets:Bogotá and Medellín exhibit colocation vacancy rates above regional averages, creating whitespace for rack vendors to establish distribution partnerships ahead of hyperscale entry.
- Chilean Renewable Energy Corridors:SUBTEL certification requirements for data centers powered by solar and wind installations favor rack designs with enhanced thermal tolerance for fluctuating ambient conditions.
- Modular Prefabricated Integration:Convergence of containerized data center architecture with standardized rack form factors enables factory-integrated power and cooling modules that compress on-site deployment schedules.
Industry Challenges
- Thermal Engineering Talent Scarcity:Computational fluid dynamics expertise for optimizing rack airflow in tropical humidity conditions remains concentrated among São Paulo-based specialists, limiting vendor expansion.
- Multi-Standard Certification Complexity:ANATEL electromagnetic compatibility testing, LGPD physical security audits, and ISO 27001 facility accreditation create overlapping compliance timelines that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Data Center Rack Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame Rack, Enclosed Rack, Wall-Mounted Rack, Rack Accessories End User: Telecommunications, Cloud Service Providers, Enterprises, Colocation Providers Size: 42U, 27U, 15U, Custom Size Cooling Technology: Air Cooling, Liquid Cooling, Hybrid Cooling, Free Cooling |
| Companies Covered | Schneider Electric SE, Rittal GmbH & Co. KG, Legrand SA, Dell Inc., Hewlett Packard Enterprise, Eaton Corporation, Vertiv Group Corp., Fujitsu Limited, Cisco Systems, Inc., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Data Center Rack Market Trends and Innovations
Rack-level infrastructure is converging with thermal and power management systems as a single procurement category, compressing vendor boundaries and elevating integration capabilities above standalone enclosure specifications.
Direct-to-chip liquid cooling is hybridizing traditional air-cooled rack architectures, enabling heat removal at the server level through cold plates integrated into cabinet rear doors. Cloud service providers in Brazil are specifying hybrid configurations for new builds, blending liquid-cooled high-density zones with conventional air-cooled infrastructure. This technology is hybridizing vendor competitive positioning, rewarding suppliers who control both precision cooling equipment and enclosure fabrication workflows.
Brazil's ANATEL telecommunications regulator is tightening electromagnetic interference standards for data center equipment, mandating shielded rack enclosures in facilities handling financial and government data traffic. The industrial consequence is elevated testing costs and extended product certification timelines for imported cabinet lines. Colocation operators in São Paulo and Rio de Janeiro are responding by prioritizing domestically manufactured racks with pre-validated compliance documentation.
Consolidated infrastructure procurement is displacing fragmented buying patterns as hyperscale tenants negotiate rack-power-cooling bundles directly with integrated suppliers. Traditional electrical and mechanical contractors in Chile and Argentina face margin compression as facility operators bypass channel intermediaries for factory-direct relationships. This behavioral shift is most visible among Brazilian cloud service providers establishing dedicated procurement teams with technical specification authority previously held by general contractors.
South America Data Center Rack Market Segmentation
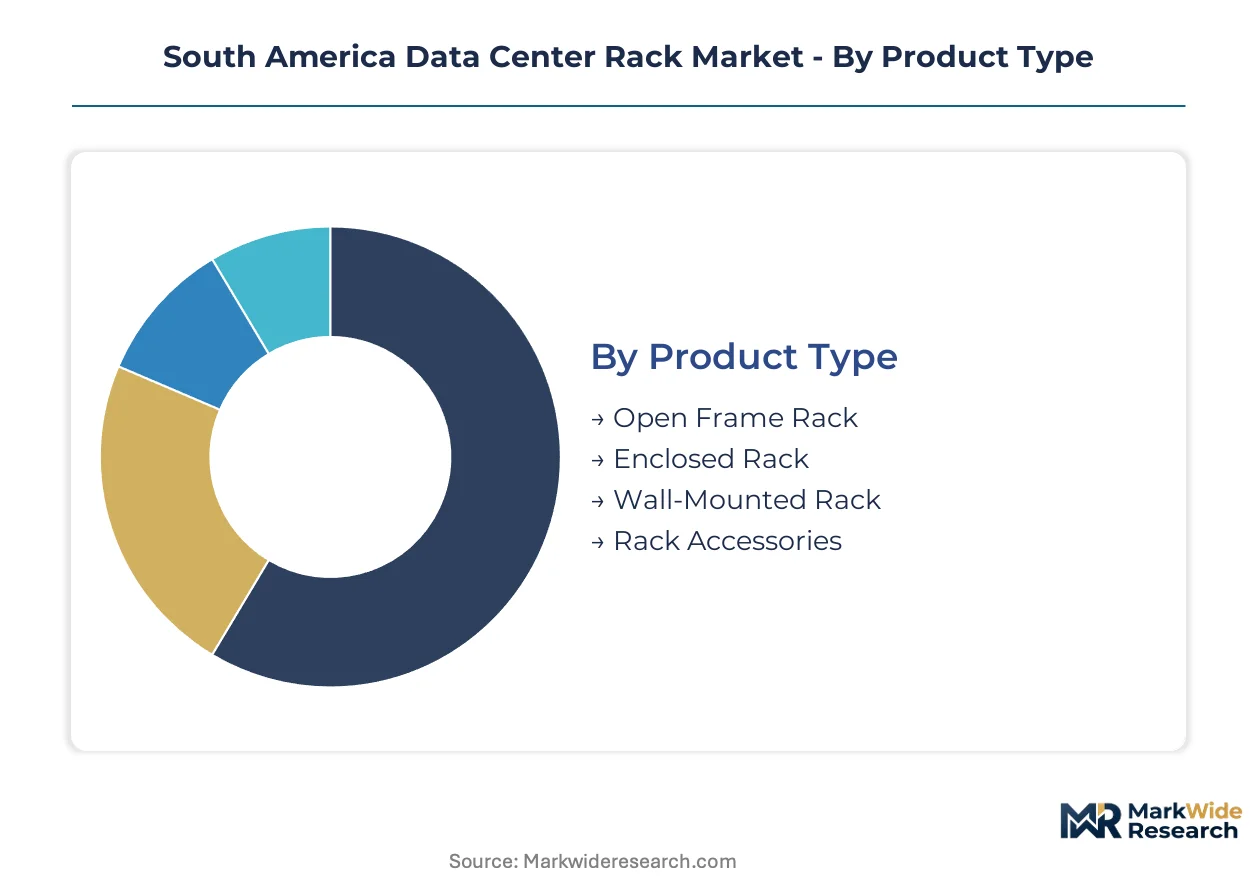
Data center rack segmentation in South America reflects divergent service intensity requirements across enclosure types and cooling architectures. Procurement patterns vary sharply between hyperscale cloud operators seeking standardized configurations and telecommunications carriers demanding localized customization support.
Product Type:
After-sales service intensity varies dramatically by enclosure architecture, with sealed cabinets requiring ongoing maintenance contracts that open-frame alternatives rarely trigger.
- Enclosed Rack:Sealed metal cabinets with integrated cable management, dust filtration, and security locking systems dominate São Paulo's financial district deployments. LGPD-mandated physical security standards for sensitive data processing drive specification of biometric-ready enclosures with tamper-evident seals across Brazilian government and banking facilities.
- Open Frame Rack:Four-post skeletal structures without side panels maximize airflow for high-density compute but sacrifice environmental protection. Chilean renewable-powered edge facilities in Atacama Desert zones specify open-frame designs for natural ventilation cooling, accepting dust exposure trade-offs against energy consumption.
- Wall-Mounted Rack:Compact enclosures for network closets and branch office server consolidation, typically 6U to 15U capacity. Argentine retail banking networks deploy wall-mounted units for provincial branch digitization under SUBTEL connectivity mandates.
- Rack Accessories:Cable management arms, blanking panels, and mounting hardware sold separately from primary enclosures. Colombian colocation operators bulk-purchase accessories to standardize tenant fit-outs across multi-site portfolios.
Enclosed Rack holds the largest share; momentum sits with Rack Accessories as operators unbundle procurement for granular cost control.
End User:
Customer type dictates configuration complexity, with cloud hyperscales driving volume standardization while enterprise buyers fragment demand across customized specifications.
- Cloud Service Providers:AWS, Azure, and Google Cloud regional zone expansions in Brazil generate concentrated demand for 42U liquid-cooling-ready cabinets with standardized power distribution. These operators negotiate factory-direct rack-cooling bundles that compress channel margins and accelerate deployment schedules.
- Telecommunications:Carriers in Chile and Argentina deploy edge micro data centers requiring compact, thermally optimized enclosures for low-latency content delivery networks. SUBTEL certification requirements shape vendor qualification timelines for these deployments.
- Enterprises:Corporate data center refreshes in Peru and Ecuador favor air-cooled enclosed racks with domestic assembly to bypass import lead time exposure. Manufacturing and logistics verticals dominate this segment.
- Colocation Providers:Multi-tenant facility operators in Bogotá and Medellín balance premium cabinet configurations against economy-tier options to capture price-diverse tenant demand. Vacancy rates above regional averages create whitespace for specification experimentation.
Cloud Service Providers command the volume base; Telecommunications exhibits the steepest expansion trajectory as 5G edge infrastructure scales.
Size:
Physical dimensions correlate directly with power density tolerance and structural reinforcement requirements, driving divergent sourcing strategies across height categories.
- 42U:Full-height standard for hyperscale compute floors, supporting 1,500+ kg loads and liquid cooling manifold integration. São Paulo's metropolitan fiber corridor concentrates demand for reinforced 42U frames handling GPU clusters exceeding 30 kW per cabinet.
- 27U:Mid-size configuration for enterprise server rooms and regional colocation footprints. Brazilian mid-market operators specify 27U units to optimize floor space efficiency without full hyperscale infrastructure investment.
- 15U:Compact form factor for network equipment aggregation and edge compute nodes. Wall-mount and floor-standing variants serve Argentine telecommunications central office modernization under ENACOM infrastructure mandates.
- Custom Size:Non-standard heights for specialized industrial or military applications with unique spatial constraints. Limited local fabrication capacity in Peru and Ecuador constrains rapid customization turnaround.
42U generates the revenue concentration; Custom Size captures expanding interest as non-standard edge form factors proliferate.
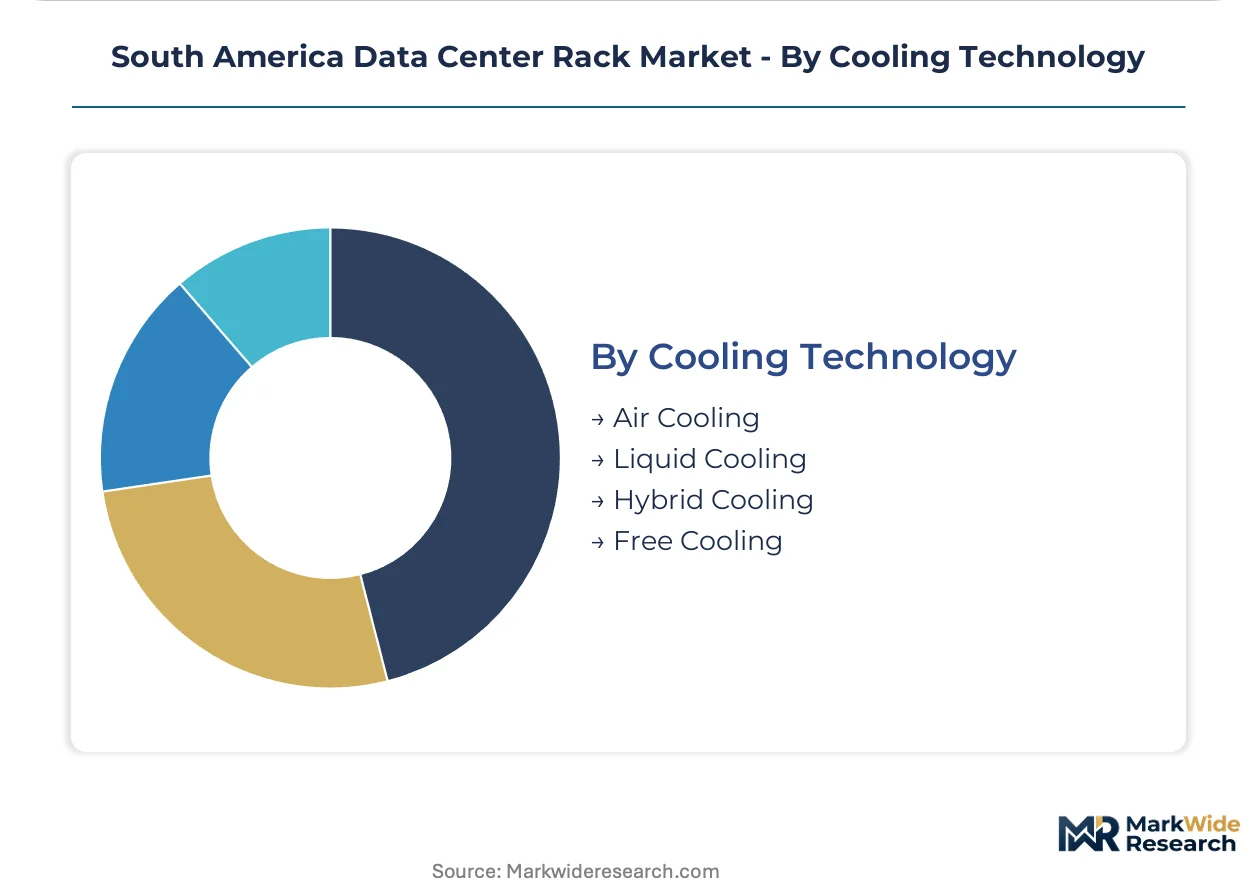
Cooling Technology:
Thermal management architecture determines rack structural specifications, with liquid-cooling compatibility commanding premium positioning and specialized integration capabilities.
- Air Cooling:Conventional raised-floor precision air handler configurations remain dominant for loads below 15 kW per cabinet. Brazilian colocation facilities standardize on air-cooled racks for multi-tenant flexibility where tenant density varies unpredictably.
- Hybrid Cooling:Blended architectures combining liquid-cooled high-density zones with conventional air-cooled infrastructure within single facilities. Cloud service providers in Brazil specify hybrid configurations to future-proof against AI workload growth without full infrastructure replacement.
- Liquid Cooling:Direct-to-chip and rear-door heat exchanger systems for power densities exceeding 30 kW. ANATEL electromagnetic compatibility testing requirements for shielded liquid-cooling manifolds extend certification timelines for imported systems.
- Free Cooling:Ambient air and evaporative cooling leveraging Chile's Atacama Desert temperature differentials. SUBTEL certification for renewable-powered facilities favors rack designs with enhanced thermal tolerance for fluctuating ambient conditions.
Air Cooling maintains installed base dominance; Hybrid Cooling is climbing the fastest as operators hedge thermal infrastructure bets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates hyperscale rack deployments for cloud sovereignty compliance, while Chile and Argentina prioritize edge-optimized thermal architectures for renewable-powered facilities. Colombia and Peru exhibit divergent sourcing patterns shaped by local fabrication capacity and import dependency exposure.
Brazil
AWS, Azure, and Google Cloud regional zone expansions drive concentrated 42U liquid-cooling-ready cabinet procurement in São Paulo's metropolitan fiber corridor. ANATEL electromagnetic compatibility standards and LGPD physical security mandates compel shielded enclosure specifications with tamper-evident seals. GPU clusters exceeding 30 kW per rack dominate new builds in the Barueri and Tamboré data center clusters.
Chile
Telecommunications carriers deploy compact thermally optimized enclosures for low-latency content delivery networks across Santiago and Valparaíso. SUBTEL certification requirements for renewable-powered facilities favor rack designs with enhanced thermal tolerance for solar and wind fluctuation. Atacama Desert edge installations exploit free cooling architectures with open-frame designs accepting dust exposure trade-offs.
Argentina
ENACOM infrastructure mandates accelerate central office modernization with 15U compact form factors for provincial branch digitization. SUBTEL-analogous facility certification requirements influence vendor qualification timelines for rack-level power distribution integration. Buenos Aires concentrates enterprise server room refreshes favoring air-cooled enclosed racks with domestic assembly.
Colombia
Bogotá and Medellín colocation operators balance premium cabinet configurations against economy-tier options amid vacancy rates above regional averages. The national data protection authority shapes physical security specifications for sensitive data processing workloads. Distribution partnerships establish ahead of hyperscale entry into secondary markets.
Peru
Domestic metalworking infrastructure lacks precision laser cutting capabilities for complex cable management integration, constraining rapid customization turnaround. Manufacturing and logistics verticals dominate enterprise demand for air-cooled enclosed racks. Lima concentrates procurement activity with import-dependent sourcing for intelligent cooling sensors and rack-level power distribution units.
South America Data Center Rack Market Competitive Landscape
Capability concentration sits with integrated cooling-to-enclosure specialists; scale advantage sits with diversified electrical infrastructure conglomerates. The vendor base organizes around three strategic archetypes: European-headquartered integrated infrastructure providers, German precision fabrication specialists, and North American thermal management technology developers. Competitive dynamics center on factory-direct procurement relationships and localized manufacturing investments that compress configuration-to-delivery timelines.
Among European-headquartered integrated providers, Schneider Electric SE and Legrand SA exemplify the capability-intensive tier controlling recurring maintenance contract flows across Brazilian and Chilean installations. Rittal GmbH & Co. KG anchors the German precision fabrication archetype through localized cabinet configuration capabilities. Vertiv Group Corp. occupies a distinct position bundling precision air handlers with enclosure sales to control the cooling-to-rack integration workflow. These three represent divergent strategic postures on the integration spectrum.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Rittal GmbH & Co. KG |
| Legrand SA |
| Dell Inc. |
| Hewlett Packard Enterprise |
| Eaton Corporation |
| Vertiv Group Corp. |
| Fujitsu Limited |
| Cisco Systems, Inc. |
| Others |
Pricing and Supply Chain Analysis
Underutilized fabrication capacity in Brazilian metalworking clusters tilts supplier behavior toward aggressive contract bidding, compressing rack pricing for standard 42U configurations while elevating premium positioning for liquid-cooling-ready enclosures with ANATEL pre-certification.
Pricing Analysis
Long-term offtake agreements dominate hyperscale procurement, with AWS, Azure, and Google Cloud negotiating multi-year rack-cooling bundles that lock in volume pricing against steel input volatility. Three-tier pricing structure across premium certified, standard domestic, and economy import tiers differentiates on LGPD compliance documentation and thermal engineering support. Cost compression in mid-market colocation stems from vacancy-driven tenant competition in Bogotá and Medellín. Cloud service providers exhibit lowest price sensitivity due to sovereign data mandates, while Peruvian manufacturing verticals prioritize landed cost minimization over specification flexibility.
Supply Chain Analysis
Extended payment terms from Brazilian facility operators strain working capital for Chilean and Argentine distributors, accelerating supply-chain finance facility adoption among regional integrators. Cold-rolled steel draws from Brazilian and Chinese mills, while precision power distribution units and intelligent cooling sensors rest on East Asian component ecosystems. Single-source vulnerability concentrates in liquid-cooling manifold imports subject to ANATEL electromagnetic compatibility testing delays. Distribution runs through factory-direct relationships with hyperscale tenants, displacing traditional electrical contractor intermediaries in São Paulo's metropolitan fiber corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment—ANATEL certification timelines and LGPD physical security mandates—creates structural barriers that reward early compliance investment and localized manufacturing presence.
For Market Incumbents: Harden recurring maintenance contract capture through Schneider Electric-style regional service network density, defending against specialized integrator encroachment in thermal management. Expand precision laser cutting capabilities in Brazilian fabrication clusters to compress customization turnaround for edge micro data center configurations. Deepen ANATEL pre-certification investments to extend lead times for imported cabinet lines. For New Entrants and Emerging Players: Colombian secondary markets—Bogotá and Medellín colocation facilities with above-average vacancy rates—represent the most penetrable entry point for rack vendors establishing distribution partnerships ahead of hyperscale entry. Chilean renewable-powered edge installations in Atacama Desert zones offer whitespace for thermally tolerant open-frame designs. Lead with SUBTEL certification support as a differentiated go-to-market wedge against established Brazilian-centric competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated cooling-to-enclosure specialists controlling factory-direct hyperscale relationships. Long-term viability hinges on thermal engineering talent scarcity in tropical humidity optimization, favoring acquisition targets with captive São Paulo-based computational fluid dynamics capabilities. Monitor LGPD enforcement intensity and ANATEL electromagnetic interference standard tightening as inflection indicators for compliance-driven specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Manufacturing Investment | Brazilian precision laser cutting capacity compresses configuration-to-delivery timelines for ANATEL-certified cabinets. |
| Liquid Cooling Integration Partnership | Vertiv-style cooling-to-rack workflow control captures hyperscale bundle procurement displacing channel intermediaries. |
| Recurring Maintenance Contract Expansion | Schneider Electric's regional service network model secures aftermarket revenue tilting from hardware vendors. |
| SUBTEL Certification Pre-Investment | Early compliance positioning in Chilean renewable-powered facilities ahead of telecommunications edge buildouts. |
| Distribution Partnership in Secondary Markets | Bogotá and Medellín colocation whitespace capture before AWS, Azure, and Google Cloud zone entry. |
Research Methodology
Desk research of customs trade records, ANATEL certification databases, and hyperscaler capex disclosures preceded structured interviews with data center facility operators, thermal engineering specialists, colocation procurement managers, and rack manufacturing plant managers across Brazil, Chile, and Argentina. Secondary validation drew from LGPD regulatory filings, SUBTEL facility certification registries, and SEC 10-K infrastructure segment disclosures. Bottom-up rack shipment aggregation and top-down facility capacity modeling enabled cross-verification.
Assumptions held fixed include ANATEL electromagnetic compatibility standard stability and LGPD physical security mandate continuity, while steel input cost trajectories and hyperscale entry timing into Colombian markets were varied across sensitivity scenarios. Segmentation dimensions encompassed enclosure architecture, cooling technology integration, end-user category, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and net new hyperscale floor space absorption throughout the projection horizon. GPU cluster density assumptions and liquid-cooling attach rates informed thermal infrastructure demand modeling.
Practitioners should monitor ANATEL standard tightening velocity and Brazilian exchange rate volatility for early signals of certification timeline extension or margin compression. Macroeconomic deviation, regulatory enforcement intensity shifts, or liquid-cooling technology disruption would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Equipment Market
Data Center Infrastructure
Philippines Data Center Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
South Korea Data Center Market
Data Center Infrastructure
France Data Center Construction Market
Data Center Infrastructure
Multi-Tenant Data Center Market
Data Center Infrastructure
Indonesia Data Center Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
Japan Data Center Construction Market
Data Center Infrastructure
Saudi Arabia Data Center Power Market
Data Center Infrastructure
Data Center Life Cycle Services Market
Data Center Infrastructure
Nigeria Data Center Power Market
Data Center Infrastructure
Netherlands Data Center Market
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Physical Security Market