
 Smart Data Center Market | 2026-2036
Smart Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Data Center Market Outlook
Liquid cooling is expanding its footprint in high-density compute environments as thermal loads from AI training clusters exceed air-cooling thresholds. Nvidia sustains leadership in GPU-accelerated infrastructure for generative AI workloads. Microsoft anchors one of the largest capital deployment programs for hyperscale facilities across multiple continents. Schneider Electric dominates electrical infrastructure and precision cooling systems for mission-critical deployments.
A smart data center integrates virtualization, artificial intelligence, robotics, and integrated infrastructure to autonomously manage power distribution, thermal regulation, security, and workload orchestration with minimal human intervention. These facilities typically operate at Power Usage Effectiveness ratios below 1.2 through real-time sensor feedback and predictive analytics. AI-powered solutions within the technology segment command the fastest expansion as machine learning models optimize energy consumption and fault prediction. Edge data centers under the deployment category represent a concentrated growth vector as latency-sensitive applications require distributed processing nodes closer to end users.
EPA energy efficiency guidelines and FERC interconnection standards shape facility design and grid integration requirements in the United States, while China's MIIT enforces GB standards for data center power usage and carbon intensity. The EU Green Deal and CSRD disclosure mandates in Europe compel operators to report embodied carbon and renewable energy procurement. Stakeholders must weigh sovereign data residency rules against the capital efficiency of centralized hyperscale architectures.
Market Dynamics
AI training clusters are forcing thermal design thresholds past air-cooling limits, triggering wholesale infrastructure replacement cycles across hyperscale and colocation facilities.
Growth Catalysts
- MIIT GB Standards:China's carbon intensity mandates for data centers are accelerating liquid cooling retrofits in facilities exceeding 30MW capacity.
- Generative AI Workloads:Training clusters from hyperscale cloud operators are saturating existing power densities and demanding specialized thermal architectures.
- Edge Latency Requirements:Autonomous vehicle and industrial IoT applications are mandating sub-10ms response times, driving distributed node deployment.
Market Restraints
- Copper and Nickel Price Volatility:Liquid cooling manifolds and busbar assemblies face input cost swings that compress equipment margins.
- Skilled Technician Scarcity:Dielectric fluid handling and precision cooling maintenance require certifications that remain concentrated in Germany, the United States, and Japan.
- FERC Interconnection Queues:Grid connection timelines in the United States now stretch 36-48 months for large-scale facilities, freezing capital deployment.
Strategic Opportunities
- India's Data Center Policy:State-level incentives in Maharashtra and Tamil Nadu offer power tariff concessions for facilities achieving PUE below 1.25.
- AI-Driven Predictive Maintenance:Convergence of digital twin modeling with thermal sensor arrays enables fault prediction 72 hours ahead of failure.
- Direct-to-Chip Cooling:Emerging two-phase immersion systems address GPU TDP thresholds above 700W that traditional cold plates cannot manage.
Industry Challenges
- Dielectric Fluid Certification Delays:UL and IEC safety approvals for new synthetic coolants extend product launch timelines by 14-18 months.
- Legacy Facility Retrofit Complexity:Raised floor and perimeter CRAC architectures in facilities built 2010-2018 resist cost-effective liquid cooling integration.
- Cross-Domain Talent Shortage:Facilities engineering now demands simultaneous expertise in electrical infrastructure, thermal physics, and machine learning operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Data Center Market |
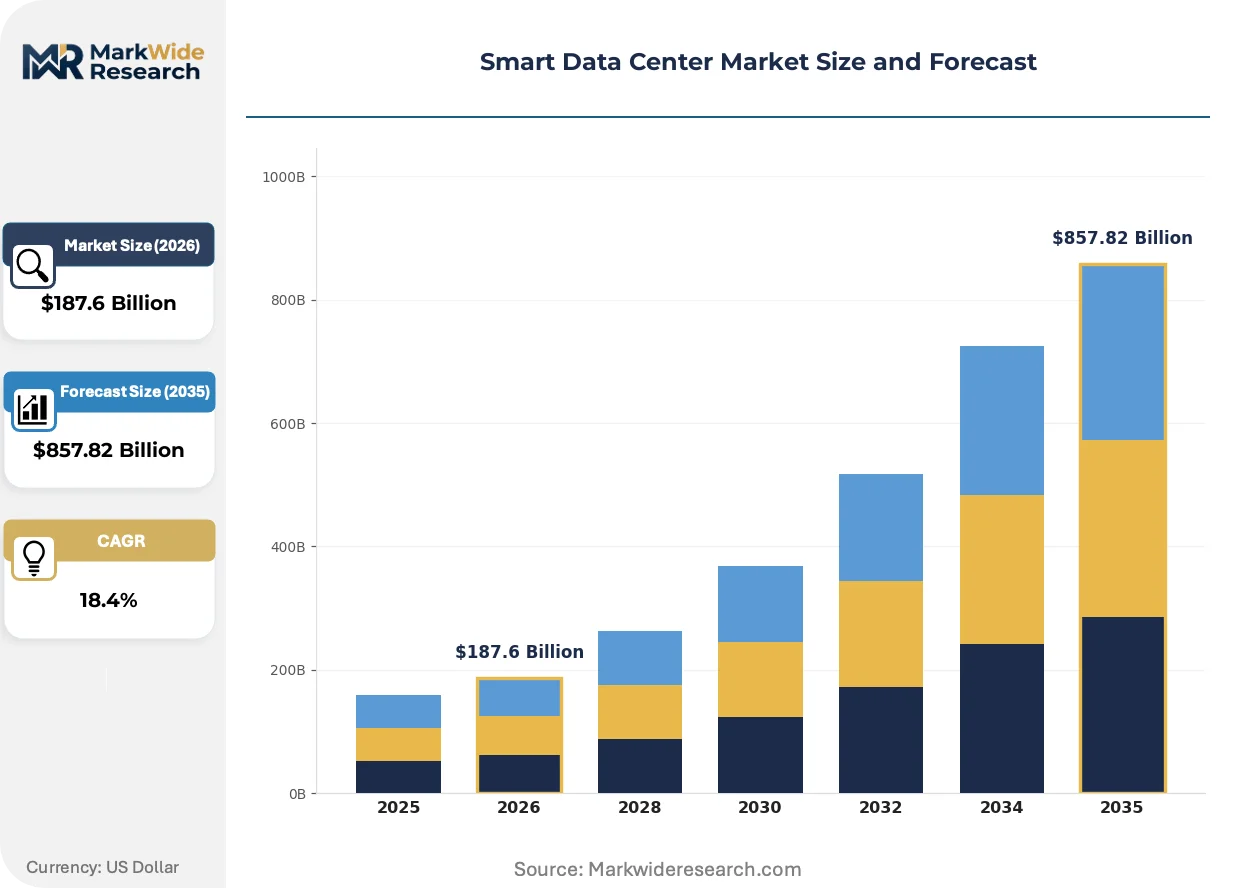
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $857.82 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Virtualization, AI, Robotics, Integrated Infrastructure Solution: Cooling Management, Power Management, Security Solutions, Management Software End User: Telecommunications, IT Service Providers, Government, Enterprises Deployment: On-Premises, Colocation, Edge Data Centers, Hybrid Model |
| Companies Covered | Amazon Web Services (AWS), Microsoft, Google Cloud, Meta, Equinix, Digital Realty, Dell Technologies, Nvidia, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Data Center Market Strategic Shifts
Liquid cooling architectures are fragmenting deployment patterns as thermal loads from AI accelerators exceed legacy mechanical limits. Three distinct vectors are reshaping facility design and operator procurement behavior.
Two-phase immersion cooling is decentralizing compute placement by eliminating dependence on raised-floor air distribution and perimeter mechanical rooms. Hyperscale operators in the United States and China are piloting tank-based systems for 100kW-plus racks. This technology is decentralizing facility layout constraints that previously dictated building geometry and location selection.
The EU CSRD disclosure mandates are forcing operators to report Scope 3 embodied carbon from construction materials and equipment manufacturing. Colocation providers in Germany and the Netherlands now face procurement rules favoring suppliers with verified Environmental Product Declarations. Server OEMs are responding with modular chassis designs that reduce aluminum content and enable component-level recycling.
Workload orchestration software is compressing switching cycles between on-premise, colocation, and cloud capacity as AI training jobs migrate toward lowest-cost power markets. Financial services and pharmaceutical buyers in Singapore and Switzerland are unbundling long-term contracts in favor of hourly spot pricing for burst compute. This behavioral shift is fragmenting revenue predictability for facility operators and accelerating demand for software-defined power distribution.
Smart Data Center Market Segmentation
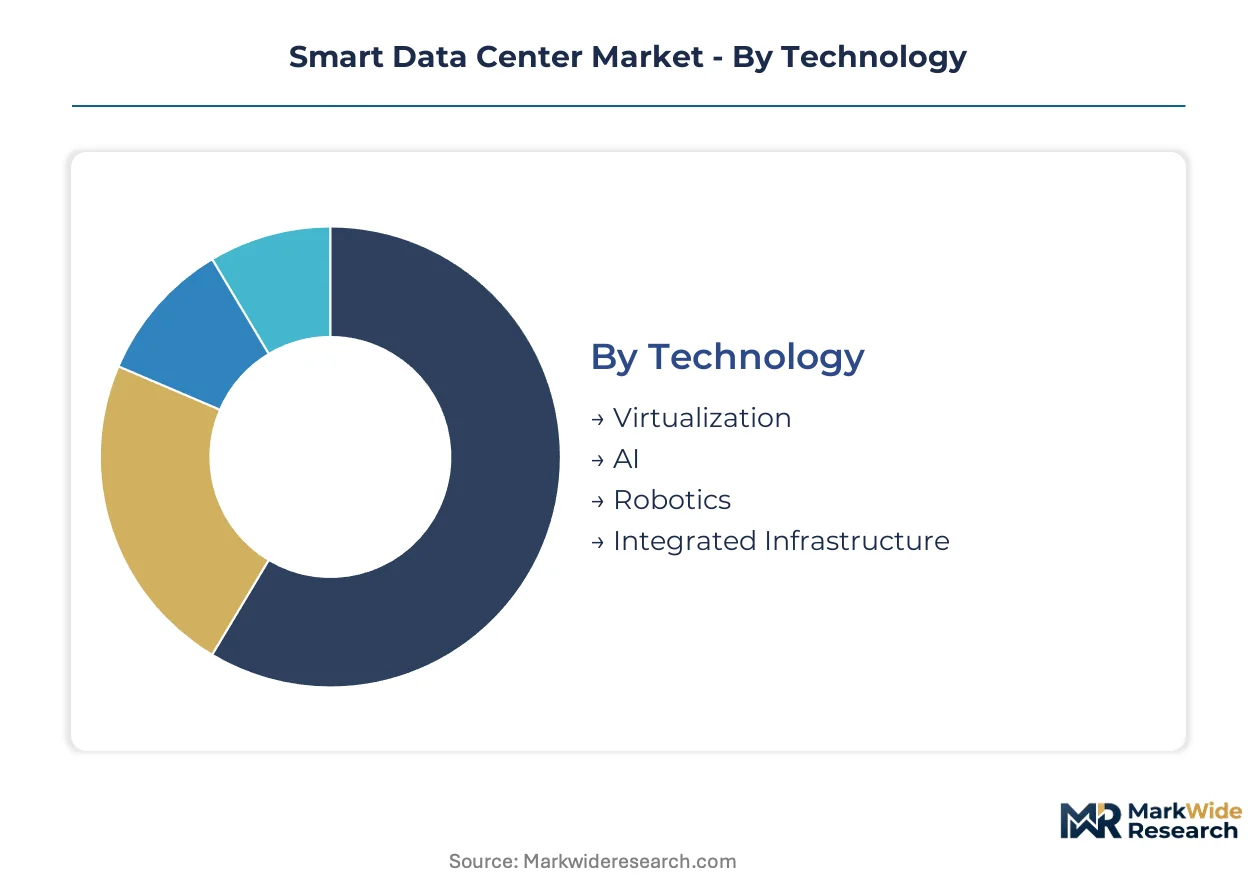
Smart data center procurement follows distinct technology and deployment pathways that separate hyperscale capital deployment from enterprise retrofit cycles. Segmentation reveals where liquid cooling investments concentrate versus where legacy air-cooled infrastructure persists. Buyers in telecommunications and IT service providers operate on fundamentally different procurement timelines than government and enterprise accounts.
Technology:
Volume deployments cluster around mature virtualization stacks, while premium pricing attaches to AI-driven autonomous management layers.
- AI:Machine learning models optimize energy consumption and fault prediction through real-time sensor feedback. Demand concentrates in hyperscale facilities across the United States and China as training clusters exceed 700W GPU thermal densities. China's MIIT GB standards accelerate retrofit timelines for facilities above 30MW capacity.
- Integrated Infrastructure:Converged hardware-software stacks unify power distribution, cooling, and workload orchestration under single management planes. Procurement concentrates among colocation operators in Germany and the Netherlands seeking PUE ratios below 1.2. EU CSRD disclosure mandates favor suppliers with verified Environmental Product Declarations.
- Virtualization:Software-defined compute and storage abstraction remains the baseline deployment architecture across enterprise data centers.
- Robotics:Autonomous physical security patrols and hardware maintenance drones augment human technician capacity in unmanned edge facilities.
Today's leader: Integrated Infrastructure. Tomorrow's challenger: AI.
Solution:
Cooling systems command capital allocation priority as thermal loads from AI accelerators force infrastructure replacement cycles.
- Cooling Management:Liquid cooling manifolds and two-phase immersion systems address GPU TDP thresholds above 700W. Demand concentrates in hyperscale cloud operator facilities across multiple continents. Dielectric fluid certification delays at UL and IEC extend product launch timelines by 14-18 months.
- Power Management:Software-defined power distribution enables dynamic capacity allocation across hybrid deployment models. Procurement accelerates among financial services buyers in Singapore and Switzerland adopting hourly spot pricing. FERC interconnection queues stretching 36-48 months freeze capital deployment for large-scale facilities.
- Security Solutions:Biometric access control and AI-driven threat detection protect mission-critical infrastructure.
- Management Software:Digital twin modeling converges with thermal sensor arrays for predictive maintenance.
Cooling Management captures current capital flows. Power Management offers the steepest expansion trajectory as grid-interactive facilities proliferate.
End User:
IT service providers deploy at hyperscale velocity while government accounts impose sovereign data residency constraints.
- IT Service Providers:Hyperscale cloud operators anchor the largest capital deployment programs across multiple continents. Liquid cooling retrofits accelerate as training clusters saturate existing power densities. Skilled technician scarcity for dielectric fluid handling concentrates certifications in Germany, the United States, and Japan.
- Telecommunications:5G network densification drives edge node deployment for sub-10ms latency requirements. Demand concentrates in autonomous vehicle and industrial IoT application corridors. Copper and nickel price volatility compress equipment margins for liquid cooling manifolds.
- Government:Sovereign data localization requirements tighten procurement around domestic facility construction.
- Enterprises:Legacy raised-floor facilities built 2010-2018 resist cost-effective liquid cooling integration.
IT Service Providers dominate volume. Telecommunications offers the fastest climb as edge latency requirements harden.
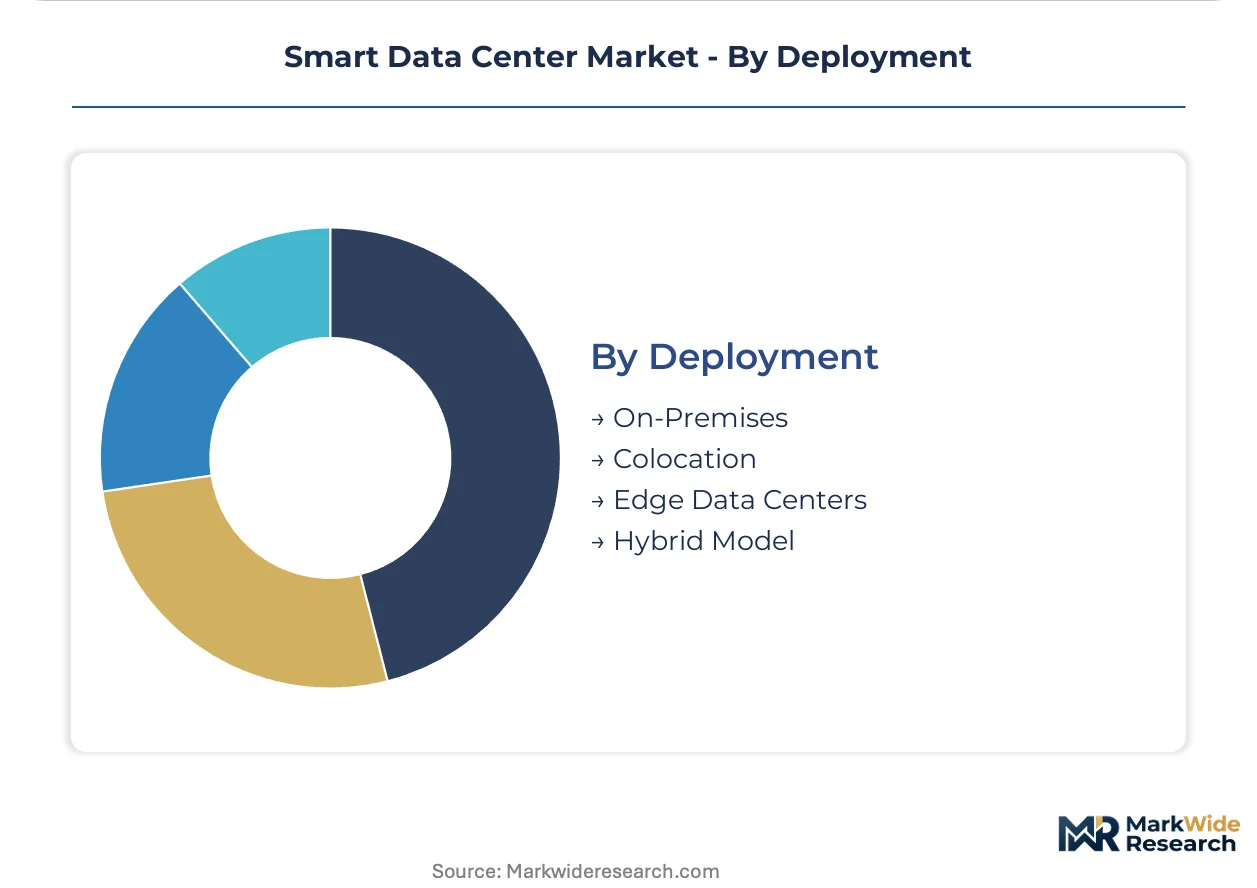
Deployment:
On-premises enterprise retention battles against colocation flexibility and edge distribution for latency-sensitive workloads.
- Edge Data Centers:Distributed processing nodes position compute closer to end users for autonomous vehicle and industrial IoT applications. Deployment concentrates in latency-sensitive corridors across the United States, China, and Germany. Two-phase immersion cooling eliminates dependence on raised-floor air distribution and perimeter mechanical rooms.
- Hybrid Model:Workload orchestration software compresses switching cycles between on-premise, colocation, and cloud capacity. Adoption accelerates among pharmaceutical and financial services buyers unbundling long-term contracts. Revenue predictability fragments for facility operators as hourly spot pricing displaces fixed commitments.
- Colocation:Third-party facility operators face procurement rules favoring embodied carbon disclosure.
- On-Premises:Enterprise retention of owned facilities persists in regulated industries with strict data sovereignty requirements.
Hybrid Model leads current architectural transitions. Edge Data Centers represent the sharpest growth vector as latency thresholds tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Virginia's Data Center Alley anchors global hyperscale deployment velocity, hosting the densest concentration of cloud compute infrastructure worldwide. Sovereign data localization mandates and divergent regulatory frameworks are fragmenting facility investment patterns across national boundaries.
United States
Hyperscale cloud operators deploy training clusters exceeding 100MW in single facilities across Northern Virginia and Phoenix. EPA energy efficiency guidelines and FERC interconnection standards shape facility design and grid integration timelines stretching 36-48 months. Loudoun County, Virginia maintains the world's highest data center capacity density per square mile.
China
Domestic cloud providers accelerate facility buildouts in Guizhou and Inner Mongolia to exploit renewable energy abundance and cooler ambient temperatures. MIIT enforces GB standards for data center power usage and carbon intensity, mandating PUE below 1.3 for new facilities above 30MW. The Yangtze River Delta cluster around Shanghai concentrates financial services and AI training workloads.
Germany
Colocation operators face EU CSRD disclosure mandates compelling embodied carbon reporting from construction materials and equipment manufacturing. The EU Green Deal drives procurement rules favoring suppliers with verified Environmental Product Declarations. Frankfurt's Rhine-Main region anchors continental interconnection density for latency-sensitive financial services workloads.
India
State-level incentives in Maharashtra and Tamil Nadu offer power tariff concessions for facilities achieving PUE below 1.25. The country's national telecommunications regulator enforces data localization requirements for sensitive government and financial data. Mumbai and Chennai emerge as primary hubs for cloud operator expansion targeting domestic enterprise demand.
Singapore
Financial services and pharmaceutical buyers unbundle long-term contracts in favor of hourly spot pricing for burst compute capacity. The country's central bank and financial services authority impose strict operational resilience requirements on critical digital infrastructure providers. The Jurong and Tuas industrial zones concentrate new facility construction despite land and power constraints.
Smart Data Center Market Competitive Environment
Global majors compete with regional champions across electrical infrastructure, precision cooling, and cloud services segments. The vendor base separates into three tiers: hyperscale cloud operators deploying at continental scale, electrical and thermal infrastructure specialists, and colocation providers offering neutral interconnection platforms. Dominant competitive moves include vertical integration into renewable energy procurement and strategic partnerships for liquid cooling technology access.
Within the hyperscale operator tier, Amazon Web Services, Microsoft, and Google Cloud anchor the largest capital deployment programs across multiple continents. These entities exemplify scale-driven facility construction velocity, with each representing distinct approaches to energy procurement and thermal architecture selection. Microsoft occupies a position emphasizing integrated software-hardware stack control, while Nvidia sits within the semiconductor layer supplying GPU-accelerated infrastructure for generative AI workloads. Schneider Electric exemplifies the electrical infrastructure and precision cooling specialist archetype serving mission-critical deployments.
| Leading Market Players |
|---|
| Amazon Web Services (AWS) |
| Microsoft |
| Google Cloud |
| Meta |
| Equinix |
| Digital Realty |
| Dell Technologies |
| Nvidia |
| Schneider Electric |
| Others |
Value Chain & Pricing Dynamics
Hyperscale cloud operators with sovereign wealth backing anchor capital deployment velocity across liquid cooling infrastructure, compressing equipment margins through volume procurement while concentrating pricing power with dielectric fluid specialists holding UL and IEC certifications. This ownership pattern tightens supplier payment terms and accelerates cost pass-through from copper and nickel volatility to colocation operators lacking comparable scale leverage.
Pricing Analysis
Input-cost pass-through from copper and nickel volatility runs through liquid cooling manifold and busbar assembly tiers, compressing equipment margins for mid-scale colocation providers. Three-tier pricing structure across certified-premium, standard-UL, and economy-uncertified levels separates hyperscale direct procurement from enterprise retrofit channels. Pricing pressure stems from FERC interconnection queues stretching 36-48 months, freezing capital deployment and forcing spot-market premiums for available grid capacity. IT service providers exhibit lowest price sensitivity due to training cluster revenue density, while legacy enterprise facilities face acute cost compression from retrofit complexity.
Supply Chain Analysis
Single-source vulnerability sits with synthetic dielectric fluid production concentrated in Germany, the United States, and Japan, where skilled technician certifications for precision cooling maintenance remain geographically locked. Manufacturing draws from copper processing in Chile, nickel refining in Indonesia, and semiconductor-grade cold plate fabrication in Taiwan. Regulatory restriction risk intensifies as UL and IEC safety approvals for new synthetic coolants extend product launch timelines by 14-18 months. Distribution runs through direct hyperscale procurement channels and integrator-mediated enterprise retrofit pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart data center deployment functions as a geographic-arbitrage play between India's Maharashtra power tariff concessions for PUE sub-1.25 facilities and Germany's EU CSRD embodied carbon disclosure mandates that elevate compliance costs.
For Market Incumbents: Extend liquid cooling technology access through strategic partnerships with dielectric fluid specialists, defending against emerging two-phase immersion entrants. Prioritize backward integration into renewable energy procurement to offset FERC interconnection queue delays. Strengthen certification investment in UL and IEC pathways to maintain premium pricing tiers against uncertified competitors. For New Entrants and Emerging Players: AI-driven predictive maintenance platforms offer the most penetrable wedge, targeting legacy enterprise facilities built 2010-2018 that resist cost-effective liquid cooling integration. Focus white-space capture on India's state-level incentive corridors in Tamil Nadu and Maharashtra. Deploy digital twin modeling with thermal sensor arrays as the primary go-to-market angle for fault prediction capabilities. For Investors and Strategic Acquirers: Hyperscale cloud operators are the most active acquirer in this space, consolidating electrical infrastructure specialists to secure captive supply of precision cooling systems. Long-term viability centers on facilities achieving grid-interactive flexibility and sub-1.2 PUE ratios through AI optimization. Target acquisition archetype: mid-scale colocation operators with existing renewable energy offtake agreements. Watch for dielectric fluid certification acceleration as the inflection signal indicating supply constraint easing.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Technology Partnership | Secures access to UL-certified dielectric fluids amid 14-18 month approval delays. |
| Renewable Energy Procurement Integration | Aligns with EU CSRD disclosure mandates and India's PUE incentive thresholds. |
| Edge Node Distributed Deployment | Addresses sub-10ms latency requirements from autonomous vehicle and industrial IoT corridors. |
| Digital Twin Predictive Maintenance Platform | Enables 72-hour fault prediction through thermal sensor array convergence. |
| Backward Integration into Power Distribution | Mitigates FERC interconnection queue risk through captive grid infrastructure development. |
Study Parameters
Multiple input streams — hyperscaler capex disclosures, facility operator procurement records, and regulatory filing databases — were reconciled across primary interviews with data center engineering directors, colocation procurement leads, thermal infrastructure specialists, and grid interconnection planners. Secondary validation drew from EPA energy efficiency guidelines, FERC interconnection standards, China's MIIT GB standards filings, and EU CSRD disclosure frameworks. Bottom-up facility capacity tallies and top-down cloud operator investment trajectories were triangulated to anchor market sizing.
Data-stream reconciliation across technology segmentation, deployment model, and end-user vertical dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from facility buildout velocity weighted against retrofit cycle constraints and interconnection queue timelines. Modeled inputs incorporated GPU thermal density trajectories, liquid cooling adoption curves by facility age cohort, and sovereign data localization policy enforcement intensity.
The model holds under stable FERC interconnection processing timelines and continued MIIT GB standard enforcement; deviation in dielectric fluid certification acceleration or copper-nickel price volatility spikes would shift capital deployment patterns. Forecasts reflect assumptions regarding AI training cluster expansion rates and edge latency requirement tightening. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Germany Data Center Rack Market
Data Center Infrastructure
Shanghai Data Center Market
Data Center Infrastructure
India Data Center Server Market
Data Center Infrastructure
Indonesia Data Center Rack Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
Australia Data Center Construction Market
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
Global Data Colocation Market
Data Center Infrastructure
Denmark Data Center Power Market
Data Center Infrastructure
Switzerland Data Center Market
Data Center Infrastructure
Asia-Pacific Virtual Desktop Infrastructure Market
Data Center Infrastructure
Composable-Disaggregated Infrastructure Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Sweden Data Center Market
Data Center Infrastructure
Poland Data Center Market