
 ASEAN Commercial Vehicles Market | 2026-2036
ASEAN Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Commercial Vehicles Market Outlook
Thailand's Eastern Economic Corridor is narrowing the production capacity gap with traditional Northeast Asian manufacturing hubs for medium and heavy commercial vehicles. Isuzu Motors Limited leverages its decades-long dominance in diesel powertrain engineering across Thai assembly lines. Toyota Motor Corporation anchors regional hybrid commercial vehicle supply through its Bangkok-area production network. Volvo Group competes in premium long-haul segments with advanced driver-assistance architectures tailored to ASEAN road conditions.
ASEAN commercial vehicles encompass motorized transport equipment designed for goods carriage, passenger movement, and specialized industrial tasks, with gross vehicle weights typically spanning 3.5 to 44 tonnes and powertrains configured for tropical climates and variable road infrastructure. Trucks configured for freight transport command the largest installed base across archipelagic logistics networks where inter-island shipping connects with last-mile road distribution. Electric powertrains represent the fastest-expanding fuel category as battery-electric buses gain traction in Jakarta, Singapore, and Manila urban transit procurement cycles. Light commercial vehicles serving delivery services sustain durable margin pools due to fragmented buyer structures and recurring replacement demand from SME fleet operators.
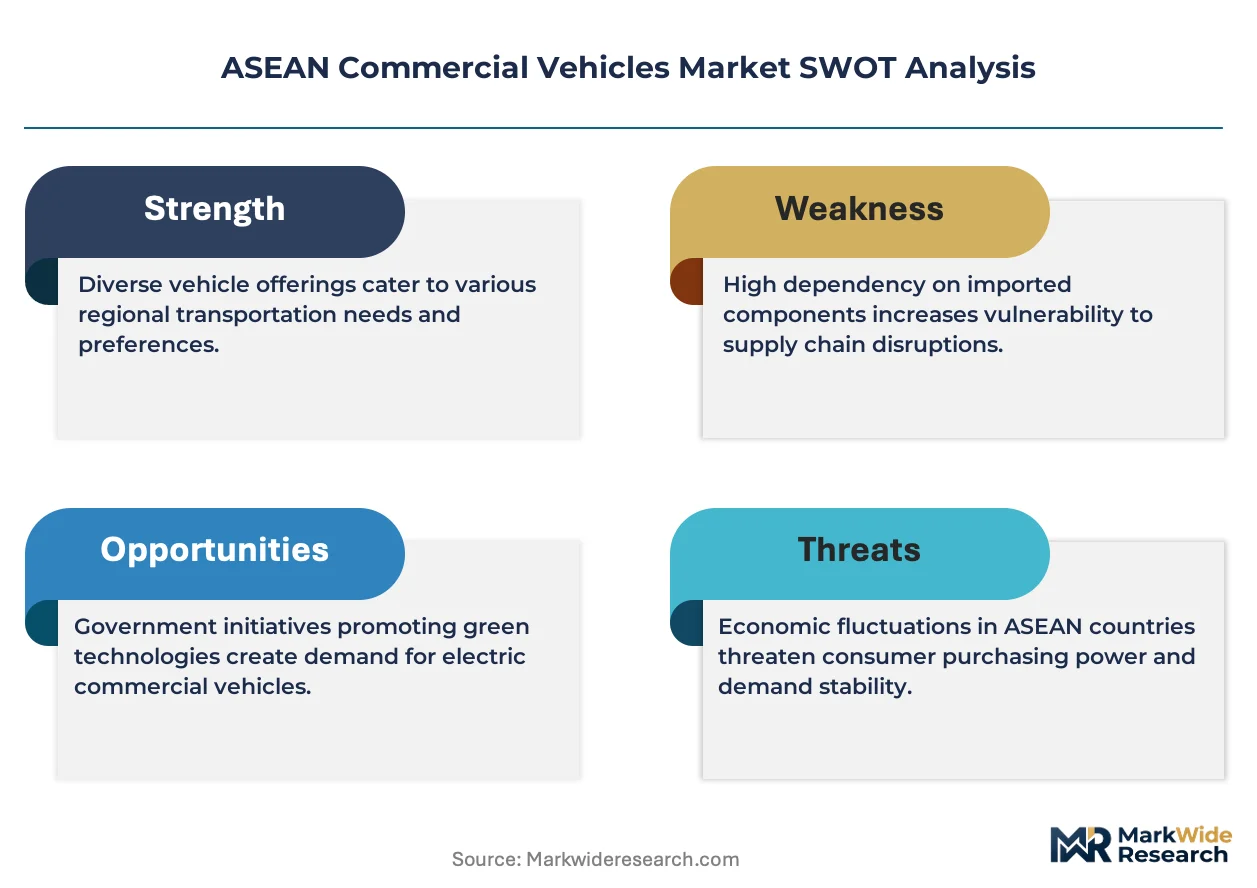
Thailand's Department of Land Transport enforces Euro 5 emission standards that compel engine recalibration and after-treatment investments from manufacturers serving Bangkok and Chiang Mai freight corridors. Indonesia's Ministry of Energy and Mineral Resources mandates B35 biodiesel blending that reshapes fuel type demand and engine compatibility requirements for domestic commercial vehicle buyers. Singapore's Land Transport Authority imposes vehicle quota and carbon-based registration frameworks that accelerate electric bus and truck trials. Stakeholders must monitor how divergent national incentive structures for electrification reshape cross-border fleet standardization and parts commonality across the ASEAN production network.
Market Dynamics
Thailand's Euro 5 emission mandates and Indonesia's B35 biodiesel blending rules are forcing simultaneous powertrain recalibration across ASEAN assembly networks. Fleet operators face compressed replacement cycles as tropical climate specifications diverge from legacy Northeast Asian designs.
Growth Catalysts
- E-commerce logistics scaling:Medium-duty truck procurement is accelerating across Java-based freight corridors and Thailand's Eastern Economic Corridor manufacturing zones as last-mile delivery networks expand.
- Thailand's Euro 5 standards:Bangkok and Chiang Mai freight corridor regulations compel engine after-treatment investments that upgrade fleet efficiency benchmarks regionally.
- Battery-electric bus traction:Urban transit procurement cycles in Jakarta, Singapore, and Manila are displacing diesel chassis with electric powertrains in municipal fleet tenders.
Market Restraints
- High-voltage battery supply concentration:Cell production for electric commercial vehicles clusters in Northeast Asian supply bases, creating import dependency for ASEAN assemblers.
- Biodiesel compatibility friction:Indonesia's B35 blending mandate forces engine recalibration investments that strain smaller domestic fleet operators with limited technical capacity.
- Inter-island logistics fragmentation:Archipelagic freight networks in Indonesia and the Philippines require multi-modal coordination that elevates operating complexity above continental ASEAN markets.
Strategic Opportunities
- Vietnam's underpenetrated freight corridors:Manufacturing relocation from China is generating demand for medium-duty distribution vehicles serving Hanoi-Ho Chi Minh City logistics lanes.
- Singapore's carbon-based registration frameworks:The Land Transport Authority's vehicle quota system creates premium positioning for electric truck and bus trials in controlled urban environments.
- Hybrid powertrain convergence:Diesel-electric architectures tailored to tropical climates offer bridging technology for fleets awaiting charging infrastructure maturity.
Industry Challenges
- Powertrain engineering talent scarcity:ASEAN technical institutes produce insufficient technicians trained in high-voltage systems and advanced after-treatment calibration.
- Cross-border parts commonality erosion:Divergent national electrification incentives fragment fleet standardization, complicating multi-country operator maintenance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Commercial Vehicles Market |
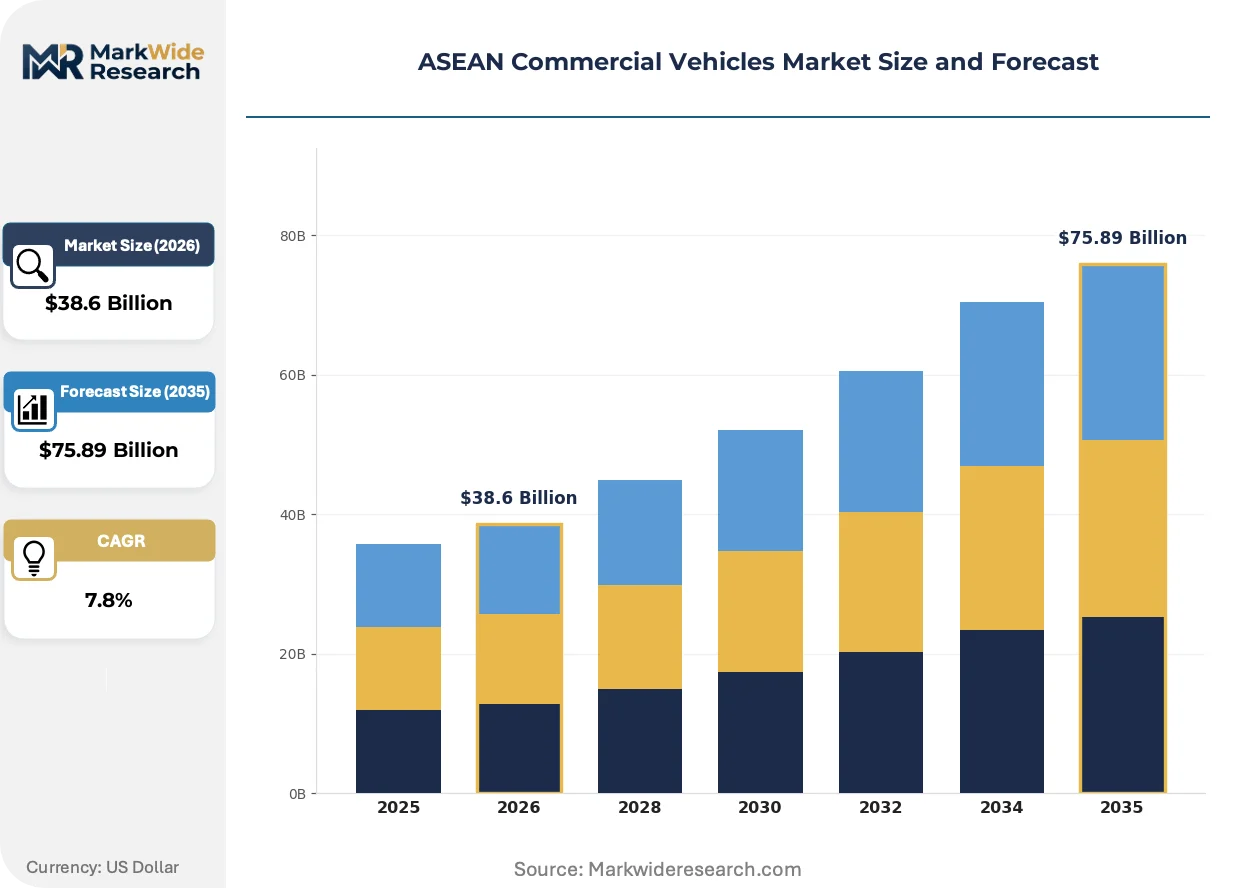
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $75.89 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Trucks, Buses, Vans, Light Commercial Vehicles Fuel Type: Diesel, Gasoline, Electric, Hybrid End User: Logistics Companies, Construction Firms, Public Transport, Retailers Application: Freight Transport, Passenger Transport, Construction Activities, Delivery Services |
| Companies Covered | Mitsubishi Fuso Truck and Bus Corporation, Volvo Group, Isuzu Motors Limited, Scania AB, UD Trucks Corporation, Toyota Motor Corporation, Daimler Truck AG, BYD Company Limited, Hino Motors Ltd, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Commercial Vehicles Market Strategic Shifts
Powertrain electrification is intersecting with emission compliance deadlines to reshape commercial vehicle specifications across tropical logistics networks. Technology roadmaps now prioritize climate-adapted architectures over direct technology transfers from temperate markets.
Diesel-electric hybrid architectures are hybridizing conventional freight vehicle designs for ASEAN operating conditions. Medium-duty truck fleets serving Thailand's Eastern Economic Corridor are piloting these systems to maintain payload capacity while meeting Bangkok emission zone restrictions. The technology is hybridizing procurement criteria as fleet managers weigh total cost of ownership against upfront capital requirements.
Thailand's Department of Land Transport Euro 5 enforcement is compressing engine certification timelines for manufacturers serving Bangkok freight corridors. After-treatment system investments now dominate powertrain engineering budgets for diesel platforms. Medium and heavy commercial vehicle segments face the steepest compliance cost escalation as legacy engine architectures require fundamental redesign.
Fleet operators are consolidating procurement decisions under centralized technical specifications that span multiple national operating licenses. Large logistics providers serving cross-border ASEAN routes now specify unified chassis configurations to simplify spare parts inventory and driver training. This concentration is most visible among e-commerce fulfillment networks coordinating Indonesia- Malaysia-Singapore distribution lanes.
ASEAN Commercial Vehicles Market Segmentation
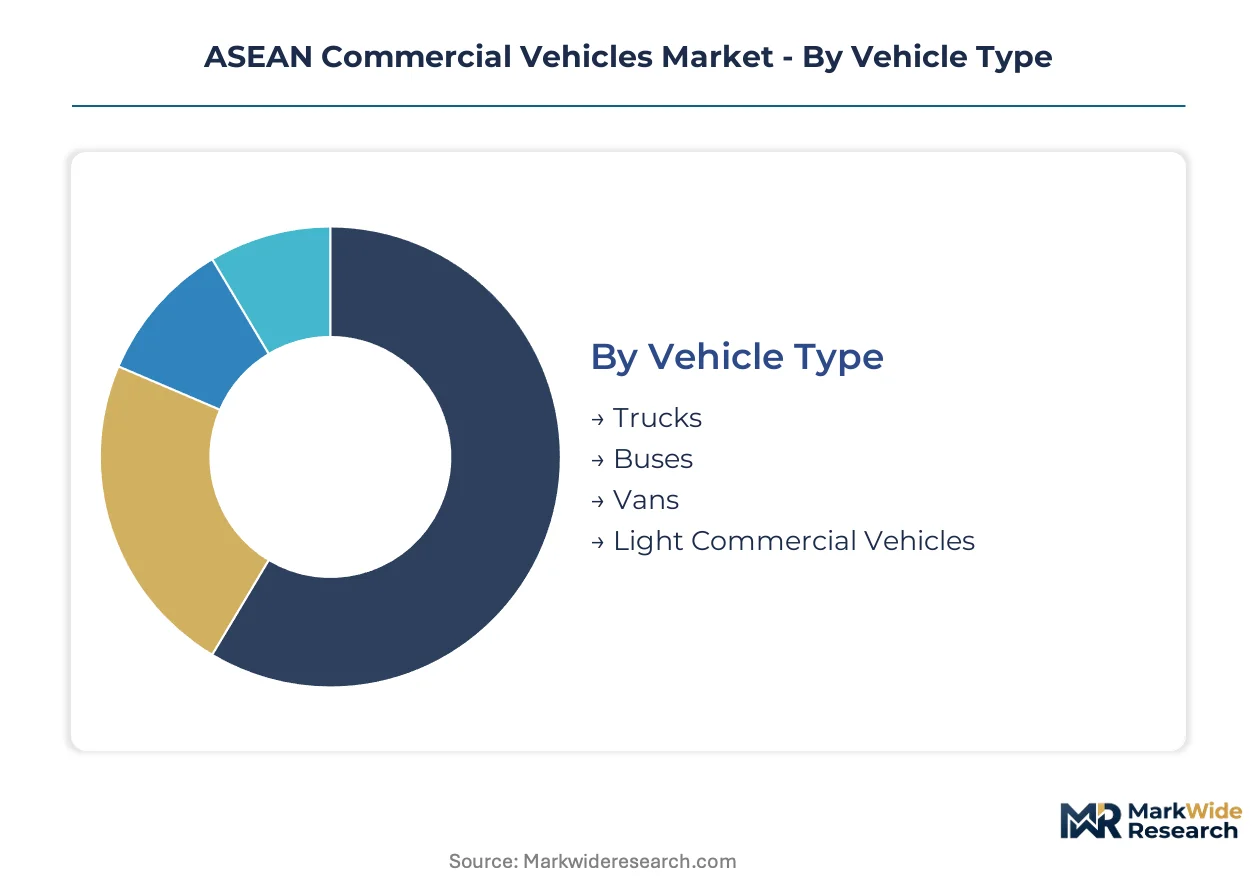
Commercial vehicle procurement across ASEAN clusters around four structural dimensions that determine replacement cadence and specification requirements. Fleet operators weight vehicle type and fuel category most heavily when aligning assets with corridor-specific regulations and payload demands.
Vehicle Type:
Replacement cycles stretch from five years for light distribution assets to twelve years for heavy long-haul platforms, compressing margin recovery windows for higher-investment categories.
- Trucks:Gross vehicle weights from 3.5 to 44 tonnes configured for tropical climate endurance and variable road infrastructure. Demand concentrates in Indonesia's Java-based freight corridors and Thailand's Eastern Economic Corridor manufacturing zones where e-commerce logistics fleets scale medium-duty procurement.
- Light Commercial Vehicles:Delivery-configured chassis serving last-mile distribution networks with fragmented SME fleet ownership structures. These units sustain durable margin pools due to recurring replacement demand from small operators across Bangkok and Ho Chi Minh City urban zones.
- Buses:Urban transit and intercity passenger configurations subject to municipal procurement cycles. Battery-electric variants gain traction in Jakarta, Singapore, and Manila fleet tenders as emission zones tighten.
- Vans:Compact cargo configurations bridging light commercial and passenger transport applications. These assets serve retail distribution and service technician mobility requirements across archipelagic logistics networks.
Trucks anchor the volume base while electric buses gain share at the steepest rate.
Fuel Type:
Cost tier stratification separates legacy diesel platforms from emerging electrification pathways, with hybrid architectures occupying a bridging position for infrastructure-constrained operators.
- Diesel:Compression-ignition powertrains dominating heavy freight applications with established service networks across ASEAN. Thailand's Euro 5 mandates and Indonesia's B35 biodiesel rules force simultaneous recalibration of injection and after-treatment systems.
- Electric:Battery-electric powertrains expanding fastest in municipal bus procurement and controlled urban delivery zones. Singapore's Land Transport Authority carbon-based registration frameworks accelerate truck and bus trials in premium positioning segments.
- Hybrid:Diesel-electric architectures tailored to tropical climates for fleets awaiting charging infrastructure maturity. Medium-duty pilots across Thailand's Eastern Economic Corridor maintain payload capacity while meeting Bangkok emission restrictions.
- Gasoline:Spark-ignition configurations limited to light commercial and van segments where capital constraints prioritize lower upfront acquisition costs.
Diesel retains the dominant revenue share while electric powertrains climb the fastest among new procurements.
End User:
Customer type determines specification complexity, with consolidated logistics providers driving standardization against fragmented construction and retail buyer structures.
- Logistics Companies:E-commerce fulfillment networks and third-party distributors operating cross-border Indonesia-Malaysia-Singapore lanes. These operators consolidate procurement under centralized technical specifications to simplify spare parts inventory and driver training protocols.
- Construction Firms:Project-based fleet operators requiring specialized chassis configurations for material handling and equipment transport. Demand fluctuates with infrastructure investment cycles across Vietnam's manufacturing relocation corridors.
- Public Transport:Municipal and state-owned operators subject to government procurement regulations and emission compliance deadlines. Jakarta, Singapore, and Manila transit authorities displace diesel chassis with electric alternatives in fleet renewal programs.
- Retailers:Fragmented SME operators with limited technical capacity for powertrain recalibration investments. These buyers prioritize acquisition cost over total cost of ownership, sustaining gasoline and older diesel platform demand.
Logistics companies anchor the volume base while public transport operators gain share at the steepest rate.
Application:
Geographic concentration patterns separate archipelagic multi-modal requirements from continental corridor operations, reshaping payload and range specifications.
- Freight Transport:Goods carriage across inter-island shipping connections and last-mile road distribution networks. Archipelagic logistics in Indonesia and the Philippines elevate operating complexity above continental ASEAN markets through multi-modal coordination requirements.
- Delivery Services:Last-mile urban distribution serving e-commerce expansion with high-frequency, short-range duty cycles. These applications favor light commercial vehicles and emerging electric van configurations in Bangkok and Ho Chi Minh City zones.
- Passenger Transport:Urban transit and intercity mobility services subject to municipal tender regulations. Battery-electric buses displace diesel chassis in Jakarta, Singapore, and Manila procurement cycles.
- Construction Activities:Material and equipment movement tied to infrastructure and manufacturing facility development. Vietnam's underpenetrated Hanoi-Ho Chi Minh City logistics lanes generate demand for medium-duty distribution vehicles as manufacturing relocates from China.
Freight transport anchors the volume base while delivery services gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand deploys commercial vehicles as manufacturing supply chain anchors while Indonesia configures them for archipelagic freight consolidation, creating divergent specification requirements across ASEAN procurement networks.
Thailand
The Eastern Economic Corridor drives medium and heavy truck demand as manufacturing relocates from Northeast Asia. The Department of Land Transport enforces Euro 5 emission standards that compel engine after-treatment investments for Bangkok freight corridors. Isuzu Motors Limited and Toyota Motor Corporation anchor production networks around Bangkok-area assembly plants serving regional export markets.
Indonesia
Java-based freight corridors concentrate procurement of medium-duty trucks for e-commerce logistics scaling across Jakarta, Surabaya, and Bandung distribution hubs. The Ministry of Energy and Mineral Resources mandates B35 biodiesel blending that forces engine recalibration investments for domestic fleet operators. Manufacturing clusters in Bekasi and Karawang generate concentrated demand for construction-configured heavy vehicles.
Vietnam
The Hanoi-Ho Chi Minh City logistics corridor attracts medium-duty distribution vehicle demand as manufacturing relocates from China. National technical standards for commercial vehicle emissions are tightening ahead of planned Euro 5 adoption timelines. Industrial zones in Binh Duong and Dong Nai provinces sustain replacement cycles for light commercial vehicles serving last-mile delivery networks.
Singapore
The Land Transport Authority imposes carbon-based registration frameworks and vehicle quota systems that accelerate electric bus and truck trials. Urban density constraints favor compact electric commercial configurations for controlled municipal environments. Jurong Island industrial logistics and port connectivity sustain premium positioning for advanced driver-assistance architectures in heavy freight applications.
Philippines
Manila metropolitan transit procurement cycles displace diesel chassis with battery-electric alternatives under municipal fleet renewal programs. Archipelagic logistics fragmentation elevates operating complexity through multi-modal coordination requirements connecting Luzon, Visayas, and Mindanao. Cebu and Davao secondary urban centers sustain regional distribution vehicle demand outside the capital corridor.
ASEAN Commercial Vehicles Market Competitive Environment
Capability concentration sits with established diesel powertrain engineers; scale advantage sits with diversified automotive conglomerates with regional assembly footprints. The market structures around three tiers: legacy Japanese commercial vehicle specialists, European premium long-haul architects, and emerging Chinese electric powertrain entrants. Competitive positioning hardens through strategic partnerships for battery supply security and technology licensing for emission compliance architectures.
Within the established diesel-engineering tier, Isuzu Motors Limited and Mitsubishi Fuso Truck and Bus Corporation exemplify powertrain specialization adapted to tropical operating conditions. Toyota Motor Corporation occupies a position bridging conventional and hybrid commercial configurations through Bangkok-area production networks. Volvo Group and Scania AB anchor the premium segment with advanced driver-assistance systems calibrated for ASEAN road infrastructure. BYD Company Limited represents the electric powertrain challenger archetype, leveraging battery supply integration to compete in municipal bus procurement cycles across Jakarta, Singapore, and Manila.
| Leading Market Players |
|---|
| Mitsubishi Fuso Truck and Bus Corporation |
| Volvo Group |
| Isuzu Motors Limited |
| Scania AB |
| UD Trucks Corporation |
| Toyota Motor Corporation |
| Daimler Truck AG |
| BYD Company Limited |
| Hino Motors Ltd |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Thailand's battery-electric chassis assembly plants is compressing supplier margins while amplifying pricing power for Japanese and European OEMs serving Bangkok freight corridors. This utilization asymmetry forces fleet operators toward longer contract tenors to secure allocation, reshaping procurement economics across the ASEAN production network.
Pricing Analysis
Long-term offtake contracts dominate procurement for medium and heavy commercial vehicles serving Indonesia's Java-based freight corridors and Thailand's Eastern Economic Corridor manufacturing zones. Three-tier pricing structure across premium, standard, and economy levels separates Volvo Group and Scania AB configurations from Isuzu Motors Limited workhorses and emerging Chinese electric entrants. Price differentiation rests on Euro 5 certification grade and after-sales service bundling. Cost compression in economy-tier diesel platforms is intensifying because Indonesia's B35 biodiesel mandate forces engine recalibration investments that smaller fleet operators cannot absorb. Retail SME buyers exhibit highest price sensitivity, prioritizing acquisition cost over total cost of ownership.
Supply Chain Analysis
Tariff exposure between China and ASEAN member states dominates supply chain risk planning for high-voltage battery procurement. Cell production draws from China, South Korea, and Japan, with lithium carbonate and nickel sulfate feedstocks anchored in Australian and Indonesian mining operations. Single-source vulnerability concentrates in semiconductor components for advanced driver-assistance systems, where Taiwan and South Korea fabrication capacity feeds ASEAN assembly lines. Distribution runs through Bangkok-area parts hubs serving cross-border Indonesia-Malaysia-Singapore logistics networks, with secondary nodes in Jakarta and Ho Chi Minh City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-electric powertrains represent the substitution threat that diesel-engineering incumbents must navigate through hybrid bridging architectures and charging infrastructure partnerships.
For Market Incumbents: Build regulatory compliance moats by accelerating Euro 5 after-treatment investments and B35 biodiesel compatibility certification ahead of enforcement deadlines. Deepen backward integration into battery pack assembly through joint ventures with Chinese or Korean cell suppliers to deflect BYD Company Limited's vertical cost advantage. Anchor capacity addition in Thailand's Eastern Economic Corridor to capture manufacturing relocation demand. For New Entrants and Emerging Players: Build out Vietnam's underpenetrated Hanoi-Ho Chi Minh City logistics corridor with medium-duty electric distribution vehicles tailored to tropical climate specifications. Target Singapore's carbon-based registration frameworks for premium positioning in controlled urban trials. Pursue municipal bus procurement in Jakarta and Manila as the most penetrable segment, leveraging battery supply integration against legacy OEM cost structures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric commercial vehicle sub-segments as charging infrastructure and battery supply security demands escalate. Five-to-ten-year viability favors diversified automotive conglomerates with regional assembly footprints over pure-play diesel specialists. Target acquisition archetypes: hybrid powertrain engineering boutiques with tropical climate calibration expertise. Monitor Indonesia's B35 enforcement timeline and Thailand's Euro 5 compliance deadlines as inflection indicators for fleet replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cell allocation from Chinese or Korean suppliers for ASEAN assembly network resilience. |
| Platform Standardization | Reduces parts complexity across Thailand, Indonesia, and Vietnam production footprints. |
| Charging Infrastructure Partnership | Accelerates fleet electrification pilots in Singapore's carbon-based registration zones. |
| Geographic Manufacturing Footprint | Expands Eastern Economic Corridor capacity to capture manufacturing relocation from China. |
| Software-Defined Vehicle Investment | Enables advanced driver-assistance architectures calibrated to ASEAN road conditions. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers at Indonesian logistics companies, Thai manufacturing zone operators, Vietnamese industrial zone developers, and Singapore Land Transport Authority planning officers. Secondary validation drew from ASEAN automotive production databases, Thailand Department of Land Transport emission compliance filings, Indonesia Ministry of Energy and Mineral Resources biodiesel policy circulars, and customs records for commercial vehicle trade flows. Bottom-up fleet size modeling and top-down macroeconomic triangulation converged on volume estimates.
Calibration against historical replacement cycles and regulatory enforcement timelines anchored the projection framework across the analysis window. Segmentation dimensions modeled include vehicle class, propulsion architecture, end-user category, and application type. CAGRs were derived from elasticity-adjusted demand curves incorporating e-commerce logistics scaling parameters and emission compliance cost pass-through assumptions. Powertrain mix trajectories incorporated Indonesia's B35 mandate penetration and Thailand's Euro 5 adoption curves.
Stress conditions across battery cell price volatility, biodiesel blend ratio escalations, and cross-border tariff regime shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding infrastructure buildout pacing and fleet operator capital availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Refrigerated Truck Market
Commercial Vehicles
Industrial Vehicles Market
Commercial Vehicles
France Light Commercial Vehicles Market
Commercial Vehicles
Semi-Tractor Trailer Market
Commercial Vehicles
Europe Light Commercial Vehicle (LCV) Market
Commercial Vehicles
Japan Commercial Vehicles Market
Commercial Vehicles
Cryogenic Liquid Transport Vehicle Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Canada Commercial Vehicles Market
Commercial Vehicles
North America Van Market
Commercial Vehicles
Global Fuel Cell Commercial Vehicle Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Commercial Air Brake Market