
 FPSO Market | 2026-2036
FPSO Market Size, Share, and Industry Trends Forecast 2026-2036
FPSO Market Analysis
IMO 2023 carbon intensity regulations are recalibrating the cost-of-entry calculus for FPSO contractors by mandating lower-emission hull designs and power systems. SBM Offshore leverages its Fast4Ward hull program to sustain delivery timelines across multiple basins. MODEC Inc. anchors its competitive position through integrated topside engineering capabilities. Yinson Holdings Berhad differentiates via aggressive fleet expansion across African and Latin American waters.
A floating production storage and offloading vessel is a ship-shaped unit that receives hydrocarbons from subsea wells, processes crude oil and gas onboard, stores stabilized oil in hull tanks typically exceeding one million barrels, and offloads to shuttle tankers via dynamic positioning or spreader mooring systems. Converted FPSO units retain cost advantages for marginal fields, while new-build FPSO orders command premium pricing where field life exceeds twenty years. Turret moored systems dominate harsh-environment deployments, with spreader moored configurations gaining share in benign West African waters where cost minimization drives contractor selection.
Classification societies including DNV, ABS, and Lloyd's Register enforce structural and safety standards that govern hull design, mooring integrity, and process equipment certification for offshore operations. Brazil's ANP and Norway's PSA impose local content requirements that reshape supply chain sourcing and fabrication yard selection for major awards. Stakeholders must monitor regulatory divergence between prescriptive North Sea standards and performance-based regimes emerging in Asia-Pacific licensing rounds.
Market Dynamics
Subsea tieback maturation is compressing field development timelines and expanding economically recoverable reserves in ultra-deepwater basins, forcing contractors to reconfigure hull delivery models around standardized, repeatable designs.
Growth Catalysts
- Pre-salt reserve commercialization:Brazil's ANP licensing rounds continue awarding blocks in the Santos Basin, sustaining long-cycle demand for high-capacity processing vessels with twenty-plus year field lives.
- Carbon intensity regulations:IMO 2023 metrics mandate lower-emission power systems and hull designs, accelerating replacement of legacy fleet units unable to meet operational carbon thresholds.
- Electrification infrastructure:Subsea power distribution networks are enabling all-electric production trees, reducing topside footprint and expanding deployable water depths.
Market Restraints
- Steel and alloy input volatility:Specialized marine-grade plate and cryogenic alloy pricing fluctuations compress fabrication yard margins on fixed-price contracts.
- Asian yard concentration:Heavy hull construction concentrates in Singaporean, South Korean, and Chinese facilities, creating bottleneck risk during concurrent award cycles.
- Local content mandates:Brazil's ANP and Norway's PSA domestic sourcing requirements fragment supply chains and inflate non-recurring engineering costs for international contractors.
Strategic Opportunities
- West African marginal fields:Ghanaian and Ivorian shallow-water discoveries suit converted FPSO economics where capital discipline overrides processing sophistication.
- Renewable power integration:Hybrid turbine-battery systems paired with gas turbine generators offer compliance pathways under tightening North Sea emissions frameworks.
- Digital twin deployment:Real-time hull and process simulation is reducing unplanned downtime and extending dry-dock intervals for operating units.
Industry Challenges
- Marine systems engineering talent scarcity:Specialized mooring and turret design expertise concentrates among retiring cohorts in European maritime clusters.
- Classification timeline compression:DNV and ABS certification queues for novel power system configurations are extending final delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FPSO Market |
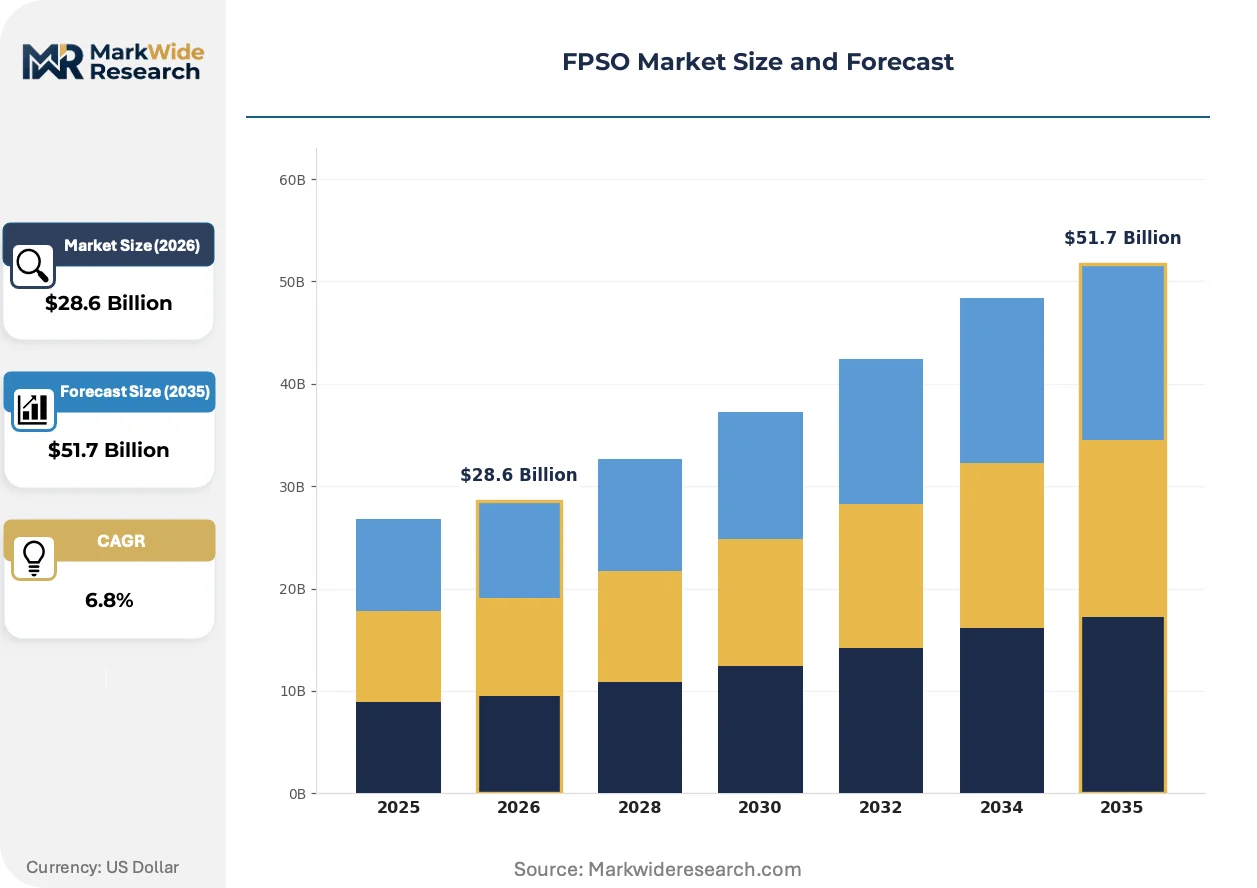
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Converted FPSO, New-build FPSO, Leasing FPSO, Redeployed FPSO Technology: Single Point Mooring, Turret Moored, Spreader Moored, Submerged Buoy End User: Oil & Gas Producers, Independent Operators, NOCs, IOCs Deployment: Shallow Water, Deep Water, Ultra Deep Water, Arctic Operations |
| Companies Covered | TotalEnergies SE, BW Offshore Limited, Petrobras, ExxonMobil Corporation, Yinson Holdings Berhad, SBM Offshore, MODEC Inc., Altera Infrastructure, CNOOC Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FPSO Market Emerging Trajectories
Standardization pressures are colliding with field-specific engineering requirements, producing modular architecture innovations that preserve customization flexibility while capturing manufacturing scale.
Integrated process modules are unifying separation, compression, and power generation into skid-mounted, factory-tested units. Deepwater operators in Brazil and West Africa are specifying these packages to compress onshore integration schedules. This unifying approach is compressing yard occupancy durations and enabling concurrent hull and topside construction paths.
EU Green Deal methane emissions monitoring mandates are requiring continuous flare and vent detection systems on all new-build units. Process safety instrument vendors are retrofitting sensor networks capable of real-time leak localization. FPSO contractors serving North Sea licensing rounds are absorbing these compliance costs into front-end engineering packages to preempt regulatory delay.
Lifecycle service contracting is displacing traditional EPC handoff models. National oil companies in Brazil and Angola are negotiating twenty-year operations and maintenance commitments bundled with construction awards. This restructuring concentrates contractor balance sheet exposure while transferring operational risk from field operators to vessel providers.
FPSO Market Segmentation
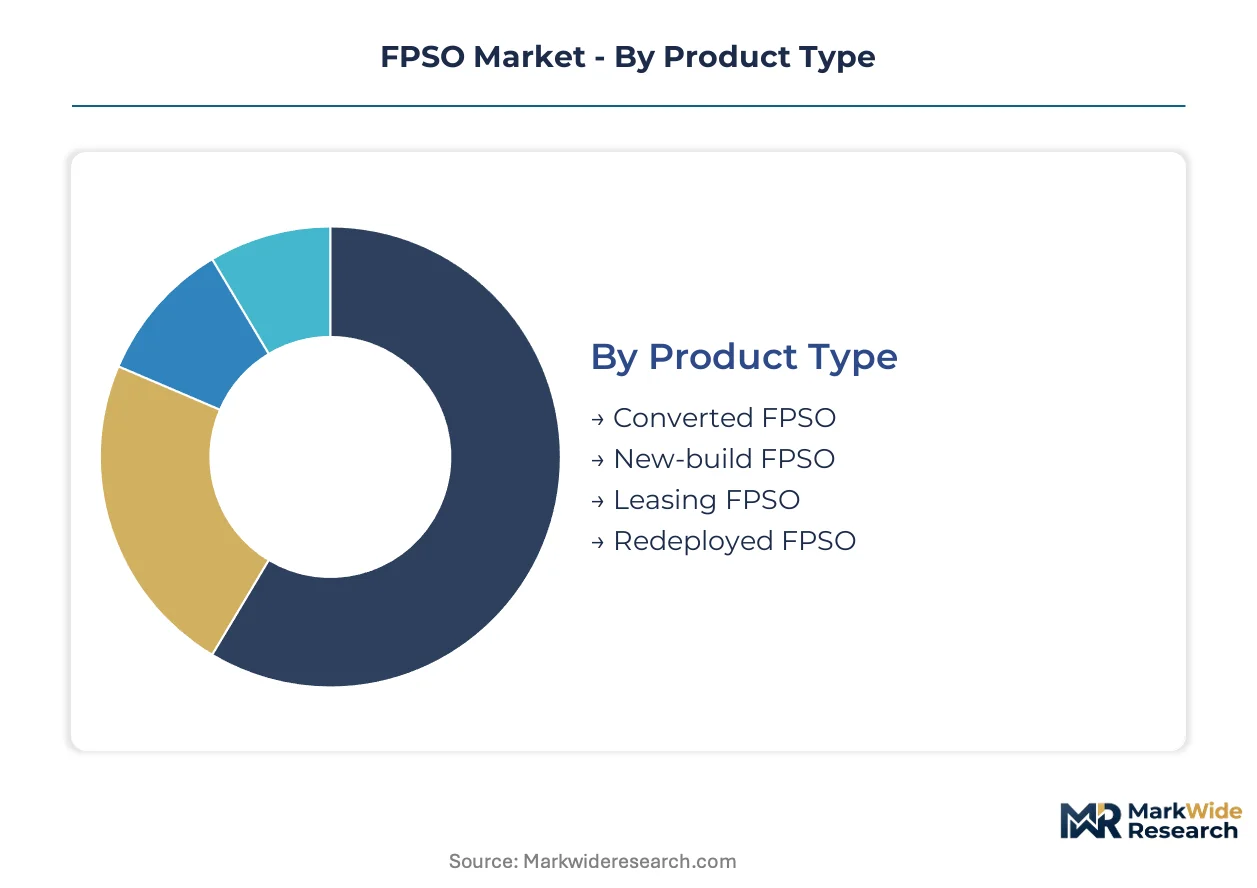
FPSO procurement patterns diverge sharply across vessel origin, mooring technology, and water depth, with each axis imposing distinct engineering constraints and capital requirements on field developers. Contractors must align hull specifications with reservoir characteristics, regulatory regimes, and operator balance sheet capacity to capture awards across Brazil's pre-salt basins and West African marginal fields.
Product Type:
Customization intensity spans from standardized lease structures to fully bespoke new-build hulls engineered for twenty-year field lives.
- New-build FPSO:Purpose-constructed hulls integrate process equipment during fabrication, enabling higher topside capacity and lower maintenance intensity over extended production horizons. Brazilian pre-salt operators specify these units where reservoir confidence justifies front-loaded capital deployment and ANP local content mandates favor domestic yard involvement.
- Converted FPSO:Retrofitted tanker hulls retain cost advantages for marginal fields with shorter reserve profiles, compressing delivery schedules by twelve to eighteen months versus greenfield construction. Ghanaian and Ivorian shallow-water developments favor this route where capital discipline outweighs processing sophistication requirements.
- Leasing FPSO:Contractors retain ownership while operators pay throughput-based tariffs, transferring residual value risk and obsolescence exposure.
- Redeployed FPSO:Existing units relocate between basins after dry-dock refurbishment, capturing demand in frontier provinces lacking indigenous fabrication capacity.
Leading the category by volume: Converted FPSO. Growing fastest: New-build FPSO.
Technology:
Cost tier stratification separates harsh-environment turret systems from spreader configurations optimized for benign West African conditions.
- Turret Moored:Internal or external turrets accommodate vessel weathervaning around a fixed geostatic point, essential for North Sea and Brazilian Buzios-class deployments where directional wave spectra exceed fifteen-meter significant heights. SBM Offshore and MODEC dominate this segment through proprietary swivel stack technology.
- Spreader Moored:Multi-point catenary systems anchor vessels in fixed orientation, reducing capital outlay by thirty to forty percent versus turret alternatives. Nigerian and Angolan shallow-water fields specify this architecture where monsoon severity permits fixed heading operations.
- Single Point Mooring:Simplified buoy connections support offloading operations without full weathervaning capability.
- Submerged Buoy:Deep-draft buoyancy cans decouple vessel motion from riser dynamics, enabling steel lazy-wave riser configurations in ultra-deepwater.
Highest capital intensity: Turret Moored. Expanding most quickly: Spreader Moored.
End User:
Customer type determines contracting structure, with NOCs favoring bundled lifecycle commitments and independents prioritizing capital flexibility.
- NOCs:National oil companies in Brazil and Angola negotiate twenty-year operations and maintenance packages alongside construction awards, concentrating contractor balance sheet exposure while transferring operational risk from field operators to vessel providers.
- IOCs:International oil companies deploy portfolio-level procurement strategies across multiple basins, favoring Fast4Ward-style standardized hulls that preserve supplier competition.
- Oil & Gas Producers:Integrated majors balance proprietary engineering standards against contractor design repetition.
- Independent Operators:Mid-cap explorers prioritize lease structures and redeployed assets to preserve exploration budget capacity.
Dominant procurement volume: NOCs. Steepest contract value expansion: IOCs.
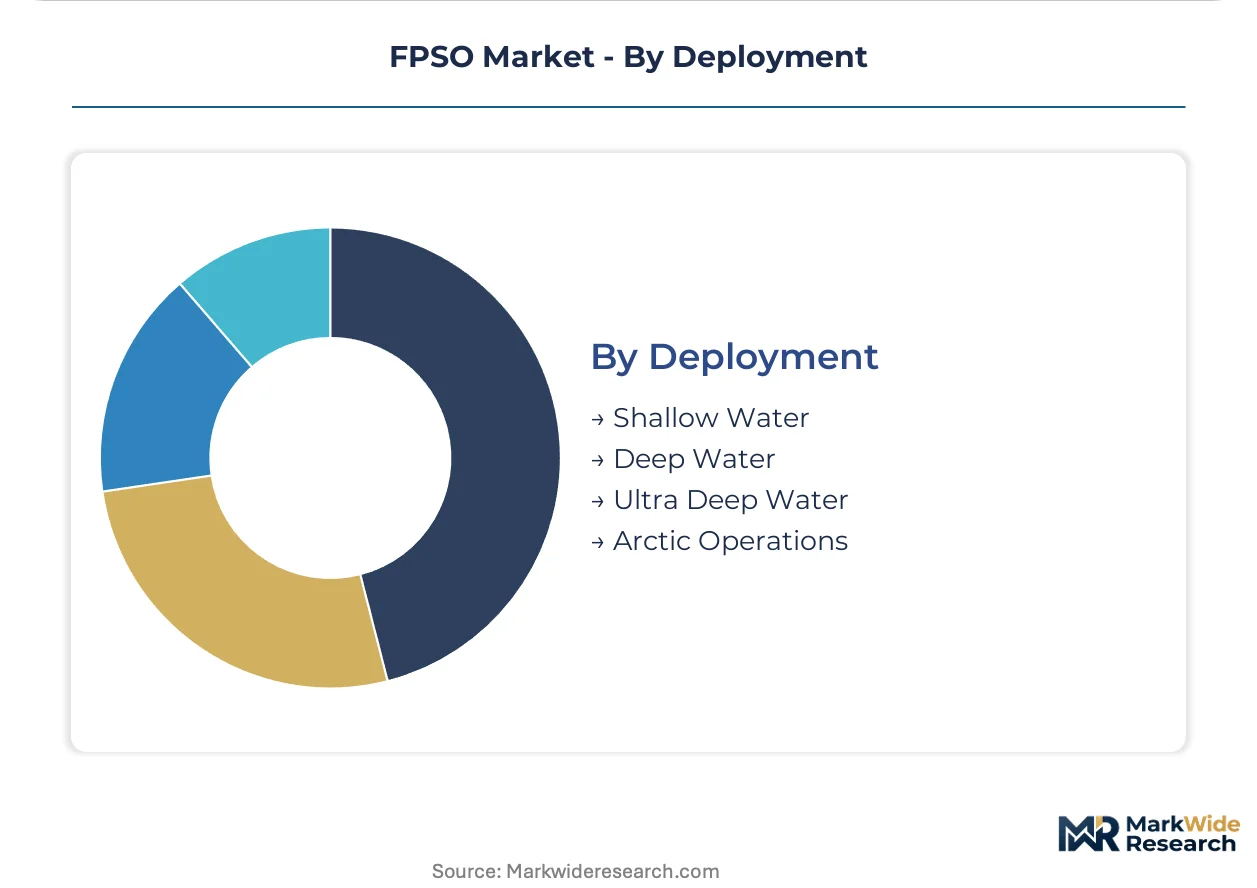
Deployment:
Water depth thresholds dictate riser technology selection and hull station-keeping requirements across the maturity spectrum.
- Ultra Deep Water:Operations below fifteen hundred meters require dynamic positioning or taut-leg mooring systems paired with steel catenary risers, commanding premium dayrates reflecting limited contractor capability and extended classification timelines at DNV and ABS.
- Deep Water:Five hundred to fifteen hundred meter developments represent the commercial core, with standardized spreader mooring and lazy-wave riser configurations capturing Brazilian Santos Basin and West African pre-salt analogues.
- Shallow Water:Jackup-competitive depths below one hundred meters favor converted FPSO economics where fixed platform capex proves prohibitive.
- Arctic Operations:Ice-class hull strengthening and disconnectable turret systems address seasonal ice loadings in Barents Sea and Canadian Beaufort licensing rounds.
Maximum award value concentration: Deep Water. Gaining share fastest: Ultra Deep Water.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates pre-salt field development demand, while West African basins and Southeast Asian yards shape supply-side execution. Field operators in Norway and the Gulf of Mexico add regulatory complexity through divergent certification regimes. Asian fabrication clusters absorb the majority of hull construction contracts.
Brazil
Petrobras anchors Santos Basin pre-salt commercialization through long-cycle FPSO awards requiring twenty-plus year operational horizons. ANP local content mandates reshape supply chain sourcing toward domestic fabrication yards. The Rio de Janeiro metropolitan cluster hosts engineering centers coordinating subsea tieback integration with hull delivery schedules.
Norway
Equinor and Aker BP drive North Sea electrification requirements through hybrid power system specifications on new-build units. The PSA enforces performance-based safety standards distinct from prescriptive regimes elsewhere. Stavanger and Bergen harbor maritime engineering expertise concentrated among turret mooring and dynamic positioning specialists.
Singapore
Keppel and Sembcorp Marine yards execute hull construction and topside integration for Brazilian and West African export markets. The Maritime and Port Authority coordinates classification society interfaces with DNV and ABS certification queues. Jurong Island process module fabricators supply skid-mounted separation and compression packages.
United States
Chevron and ExxonMobil deploy portfolio procurement strategies across Gulf of Mexico deepwater developments. The Bureau of Safety and Environmental Enforcement imposes distinct well control and containment requirements. Houston hosts contractor engineering offices coordinating Fast4Ward-style standardized hull specifications.
Angola
Sonangol negotiates bundled operations and maintenance commitments alongside construction awards for Block 15 and 17 developments. Local content requirements fragment supply chains toward Luanda-based fabrication partners. The Lobito corridor concentrates logistics coordination for West African marginal field redeployments.
FPSO Market Vendor Landscape
Dutch and Malaysian contractors anchor one tier; Japanese and Norwegian specialists hold differentiated positions in integrated topside engineering and harsh-environment mooring systems. Market structure consolidates around four to six integrated contractors capable of executing full lifecycle contracts from hull construction through twenty-year operations. Two strategic archetypes predominate: standardization-driven hull programs preserving delivery timelines, and customization-focused engineering houses capturing premium pricing on complex turret deployments. Competitive moves concentrate on M&A to secure fabrication yard capacity and strategic partnerships to satisfy ANP and PSA local content mandates.
Within the integrated contractor tier, SBM Offshore and MODEC Inc. exemplify divergent strategic positioning—SBM through its Fast4Ward hull standardization program, MODEC through captive topside engineering capabilities. Yinson Holdings Berhad occupies a position representing aggressive fleet expansion across African and Latin American waters. These three anchors illustrate how geographic footprint specialization and hull delivery model selection determine contract capture in Brazil's pre-salt basins versus West African marginal fields.
| Leading Market Players |
|---|
| TotalEnergies SE |
| BW Offshore Limited |
| Petrobras |
| ExxonMobil Corporation |
| Yinson Holdings Berhad |
| SBM Offshore |
| MODEC Inc. |
| Altera Infrastructure |
| CNOOC Ltd. |
| Others |
Supply Flow & Price Mechanics
Subsea tieback maturation is compressing field development timelines while simultaneously concentrating hull construction in Asian fabrication clusters, creating a pricing dynamic where standardized Fast4Ward-style designs capture volume awards while bespoke turret-moored units command premium positioning for Brazilian pre-salt operators.
Pricing Analysis
Volume capture concentrates in converted FPSO lease structures where Yinson Holdings Berhad and BW Offshore compete on throughput-based tariffs, while margin extraction favors new-build units with integrated topside engineering where MODEC Inc. and SBM Offshore differentiate via twenty-year operational commitments. Price differentiation hinges on local content compliance costs for ANP-mandated Brazilian projects versus stripped-down spreader-moored configurations for West African shallow-water fields. Pricing pressure intensifies in the converted segment as steel and alloy input volatility compresses fabrication yard margins on fixed-price contracts. Independent operators in Ghana and Ivory Coast exhibit highest price sensitivity, prioritizing capital discipline over processing sophistication, while Petrobras and Equinor absorb premium pricing for harsh-environment turret systems with disconnectable capabilities.
Supply Chain Analysis
Regional distribution centers in Singapore, South Korea, and China coordinate hull module fabrication and topside integration through hub-and-spoke patterns radiating toward Brazilian and West African installation sites. Marine-grade steel plate and cryogenic alloy sourcing draws from Chinese and South Korean mills, while subsea power distribution equipment and turret swivel stacks rest on European specialist suppliers in Norway and the Netherlands. Supply chain risk centers on Asian yard concentration during concurrent award cycles, creating bottleneck exposure when multiple Santos Basin developments compete for simultaneous delivery slots. Distribution runs through contractor-controlled logistics corridors linking Jurong Island process module fabricators to deepwater deployment sites, with ANP and PSA local content mandates fragmenting procurement toward domestic partners in Brazil and Norway.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification infrastructure is displacing gas turbine-heavy legacy power systems, with hybrid turbine-battery configurations and subsea power distribution networks becoming baseline specifications for new-build awards across North Sea and Brazilian licensing rounds.
For Market Incumbents: To counter IMO 2023 carbon intensity compliance costs eroding legacy fleet competitiveness, SBM Offshore and MODEC Inc. should deepen Fast4Ward program standardization to preserve delivery timelines while retrofitting sensor networks for EU Green Deal methane monitoring mandates. Backward integration into captive topside engineering capabilities protects margin extraction on complex turret deployments where swivel stack technology creates supplier stickiness. For New Entrants and Emerging Players: Digital twin deployment platforms offer a white-space entry route into lifecycle service contracting, where real-time hull simulation reduces unplanned downtime and extends dry-dock intervals for operating units. Target West African marginal field operators in Ghana and Ivory Coast seeking converted FPSO economics with lease-structured tariffs, positioning against capital-constrained independents prioritizing throughput flexibility over ownership. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated contractors with captive fabrication yard access and ANP-compliant local content networks, as national oil companies bundle twenty-year operations commitments with construction awards. Long-term viability hinges on electrification-ready hull specifications and hybrid power system integration capabilities. Watch DNV and ABS certification queue compression for novel power configurations as the signal indicating delivery schedule inflection and contractor selection advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Fast4Ward Hull Standardization | SBM Offshore's repeatable design compresses delivery timelines across multiple basins simultaneously. |
| Hybrid Power System Integration | Equinor's North Sea electrification requirements drive gas turbine-battery pairing adoption. |
| Local Content Compliance Buildout | ANP-mandated Brazilian sourcing reshapes supply chain selection toward Rio de Janeiro fabrication partners. |
| Digital Twin Platform Deployment | Real-time hull simulation extends dry-dock intervals and reduces unplanned downtime for operating units. |
| Lifecycle Service Contracting | Sonangol and Petrobras bundle twenty-year operations commitments transferring risk to vessel providers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with FPSO project directors, subsea engineering leads, ANP licensing officials, and fabrication yard procurement managers with validation against IMO carbon intensity submissions and ANP production disclosure databases. Bottom-up vessel deployment tallies triangulated against top-down operator capex guidance across Brazilian pre-salt and West African deepwater basins.
Data-stream reconciliation across hull order backlogs, subsea tree installation schedules, and turret mooring contract awards shaped the analytical framework, modeling segmentation across vessel origin, mooring technology, water depth threshold, and end-user contracting structure throughout the projection horizon. CAGRs derived from regression against historical award cycles, with forward adjustments for electrification infrastructure penetration and local content mandate evolution.
Inputs from DNV and ABS classification societies were available through the study window; gaps in proprietary turret swivel stack cost structures and contractor margin disclosure introduce uncertainty bands around new-build versus converted FPSO pricing trajectories. Forecasts reflect documented assumptions regarding ANP licensing round continuity and IMO regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Midstream Market
Offshore Oil and Gas
Indonesia Oil and Gas Upstream Market
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
Norway Oil and Gas Downstream Market
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
Subsea Production and Processing System Market
Offshore Oil and Gas
Marine Seismic Equipment and Acquisition Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Nigeria Oil and Gas Downstream Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market
Offshore Oil and Gas
Norway Oil and Gas EPC Market
Offshore Oil and Gas
Thailand Oil and Gas Downstream Market
Offshore Oil and Gas
India Oil and Gas Downstream Market