
 Iran Oil and Gas Exploration and Production Market | 2026-2036
Iran Oil and Gas Exploration and Production Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Oil and Gas Exploration and Production Market Foresight
Market Context
The capability gap between state-backed operators and private consortium partners is collapsing as NIOC tightens capital allocation rules. National Iranian Oil Company dominates onshore conventional reserves through direct field control. Petropars Ltd leverages its partnership model to sustain development at South Pars phases. MAPNA Group anchors domestic engineering procurement through localized rig fabrication.
Technical Definition and Segments
Iran oil and gas exploration and production encompasses the geological survey, drilling, completion, and hydrocarbon extraction from onshore and offshore reservoirs, typically involving well depths from 2,500 to 5,000 meters and reservoir pressures requiring artificial lift or gas injection. This activity supplies feedstock to refineries, power generation assets, and petrochemical complexes for domestic consumption and limited export. Crude oil extraction from mature fields increasingly depends on enhanced oil recovery techniques to offset natural decline rates. Natural gas processing capacity expansion at South Pars is outpacing condensate handling infrastructure. Drilling services face margin compression as NIOC pushes fixed-cost contracts over day-rate structures.
Regulatory Framework
Iran's Ministry of Petroleum sets production quotas through the Iran Petroleum Contract framework, while the Central Bank of Iran governs repatriation rules that constrain foreign partner capital flows. NIOC's buy-back contract terms limit equity ownership and reshape risk allocation for field developers. Stakeholders must monitor sanctions enforcement shifts and domestic contract model revisions to calibrate capital deployment timelines.
Market Dynamics
Sanctions relief uncertainty is fragmenting capital deployment timelines as international partners reassess field development commitments against repatriation risk.
Growth Catalysts
- South Pars Condensate Output:Petrochemical complexes at Asaluyeh and Bandar Imam are absorbing heavier crude slates, pulling upstream investment toward gas-condensate field expansion.
- Iran Petroleum Contract Revisions:Modified buy-back terms are extending contract duration limits, allowing foreign operators to recover capital over longer production windows.
- Enhanced Recovery Mandates:NIOC is requiring artificial lift and gas injection deployment at mature onshore fields to offset natural decline rates.
Market Restraints
- Central Bank Repatriation Rules:Hard currency conversion restrictions trap foreign partner earnings inside Iran, elevating counterparty risk premiums.
- Drilling Rig Import Dependence:Domestic fabrication capacity at MAPNA Group cannot fully replace Chinese and European rig supply channels under sanctions pressure.
- Condensate Infrastructure Bottleneck:Gas processing expansion at South Pars phases is outpacing condensate stabilization and export terminal capacity.
Strategic Opportunities
- Azadegan Heavy Oil Block:Underdeveloped reserves in the West Karun basin offer scale potential for thermal recovery pilots if secondary sanctions clarity emerges.
- Special Economic Zone Permits:Kish Island and Qeshm free trade zones are streamlining customs procedures for subsea equipment imports.
- Digital Twin Integration:Reservoir simulation convergence with real-time well monitoring is opening efficiency gains at fields with legacy data gaps.
Industry Challenges
- Reservoir Engineering Talent Pool:Emigration of petroleum geoscientists to UAE and Qatar operators is thinning NIOC's technical depth.
- Buy-Back Contract Renegotiation Cycles:Fixed-cost contract structures compress service company margins when drilling complexity exceeds baseline assumptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Oil and Gas Exploration and Production Market |
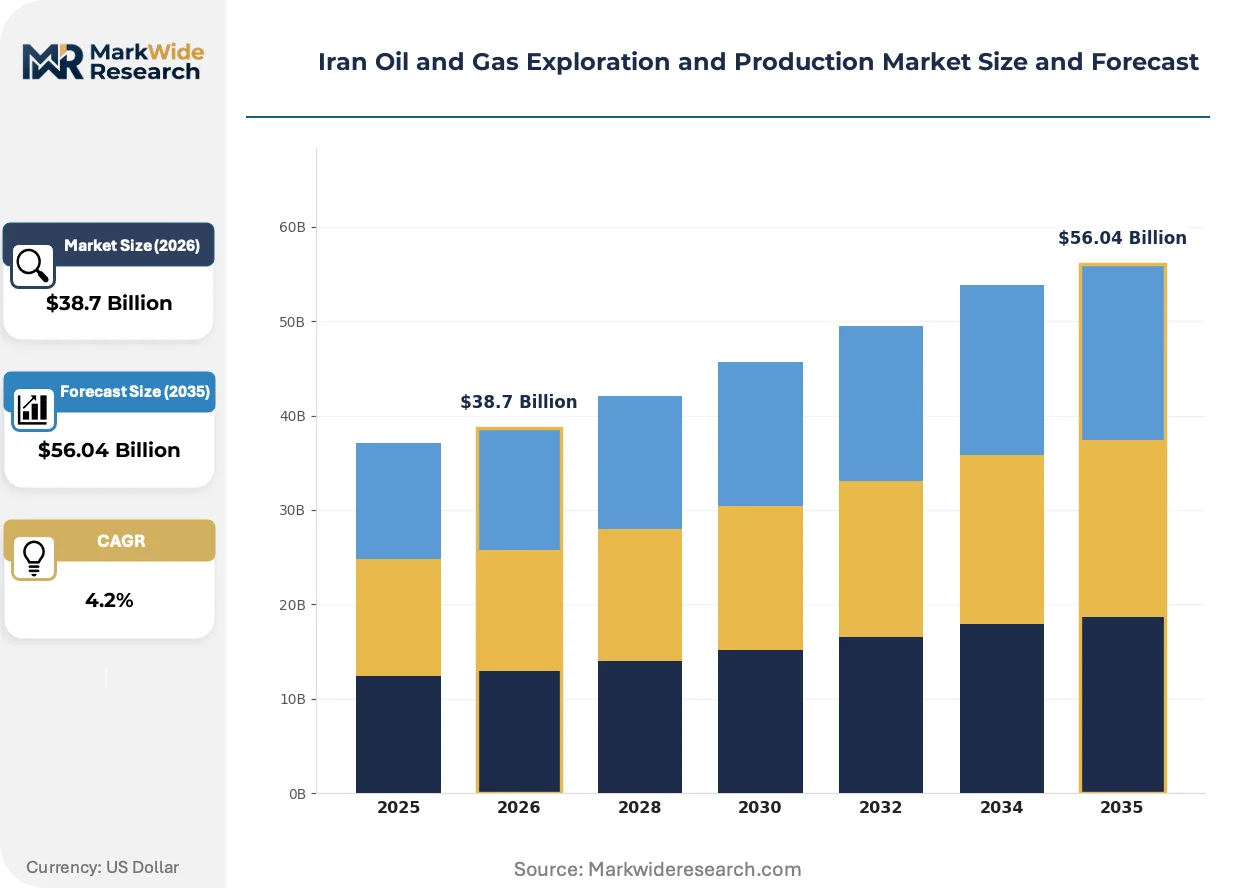
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Liquefied Natural Gas, Condensate Technology: Drilling, Seismic Survey, Enhanced Oil Recovery, Gas Processing End User: Refineries, Power Plants, Petrochemical Companies, Industrial Users Service Type: Exploration Services, Production Services, Engineering Services, Maintenance Services |
| Companies Covered | National Iranian Oil Company, Petropars Ltd, MAPNA Group, Khazar Exploration and Production Company, Pasargad Energy Development Company, National Iranian South Oil Company, Iranian Offshore Oil Company, Pars Oil and Gas Company, Iranian Central Oil Fields Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Oil and Gas Exploration and Production Market Shifts & Advancements
Upstream digitization and contract structure evolution are compressing field development cycles while sanctions compliance technology reshapes partner selection criteria.
Managed pressure drilling systems are displacing conventional overbalanced techniques at high-pressure South Pars formations. NIOC drilling units are adopting these systems to reduce non-productive time in narrow-margin zones. The technology is displacing legacy jackup rig deployment models and enabling faster phase completion timelines.
The Iran Petroleum Contract framework is tightening local content mandates for engineering procurement. Foreign consortiums must now source fabrication and construction services through domestic subcontractors. Offshore platform projects are absorbing the highest compliance burden as NIOC enforces steel structure localization rules.
Fixed-cost service contracts are replacing day-rate drilling agreements across NIOC tender rounds. Service providers absorb downhole risk while operators gain budget predictability. This procurement compression is most visible at onshore mature fields where well intervention frequency is highest.
Iran Oil and Gas Exploration and Production Market Segmentation
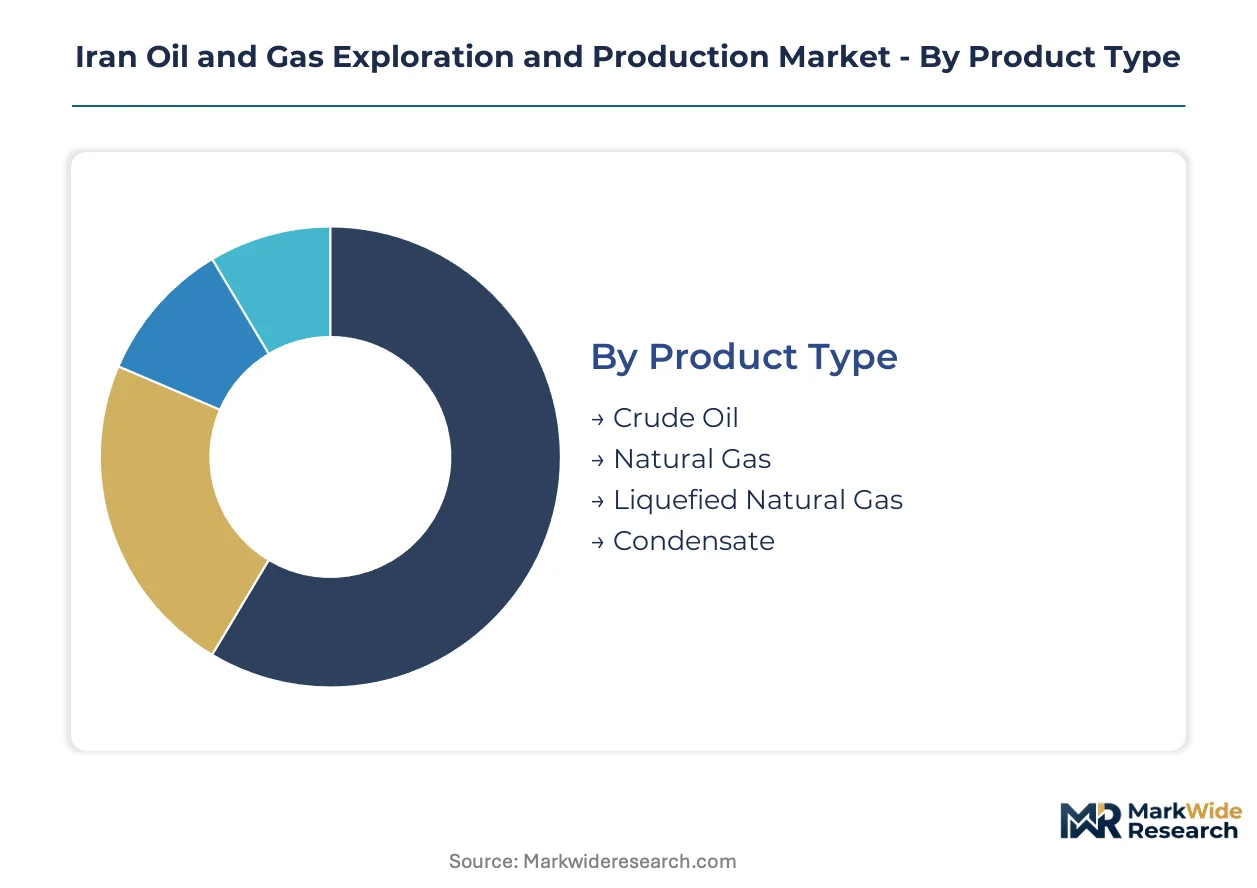
Segmentation in Iran's upstream sector reveals how sanctions architecture and domestic policy reshape investment allocation across hydrocarbon types and service categories. NIOC's contract frameworks and Central Bank repatriation rules create divergent risk-return profiles that segment capital deployment.
Product Type:
NIOC production quotas and Ministry of Petroleum export licensing differentiate commercial viability across hydrocarbon categories, with gas-condensate streams receiving preferential treatment under current policy.
- Crude Oil:Heavy and extra-heavy grades dominate West Karun basin output, requiring thermal recovery methods. Refinery demand from Bandar Imam and Tehran complexes absorbs domestic barrels, though export limitations constrain field development economics.
- Natural Gas:Non-associated gas from South Pars phases supplies power generation and residential heating loads. Pipeline infrastructure expansion to Pakistan and Turkey borders remains stalled by financing restrictions.
- Liquefied Natural Gas:Iran holds no operational LNG export capacity despite holding the world's second-largest gas reserves. Sanctions block liquefaction technology transfer from Western engineering firms.
- Condensate:Light liquid output from South Pars gas processing feeds Asaluyeh petrochemical crackers. Stabilization capacity constraints create periodic bottlenecks at export terminals.
Crude oil handles the majority of throughput; condensate is climbing the fastest on share as South Pars phases commission.
Technology:
Cost tier differentiation separates proven conventional techniques from advanced recovery systems requiring foreign technology partnerships.
- Drilling:Managed pressure systems are displacing conventional overbalanced methods at high-pressure South Pars formations. MAPNA Group fabricates jackup rigs domestically, though directional drilling software remains import-dependent.
- Seismic Survey:Onshore 3D seismic acquisition targets mature field redevelopment in the Ahwaz and Marun clusters. Offshore surveys face vessel availability constraints under sanctions.
- Enhanced Oil Recovery:Thermal and gas injection mandates at mature onshore fields absorb capital but extend plateau production. CO2 flooding pilots at Gachsaran field test carbon capture integration.
- Gas Processing:Sweetening and dehydration capacity at South Pars phases outruns condensate stabilization infrastructure. Sulfur recovery units supply domestic fertilizer manufacturers.
Drilling commands the largest equipment spend; enhanced oil recovery shows steepest expansion trajectory as NIOC mandates decline mitigation.
End User:
Customer type concentration creates divergent offtake reliability, with state-backed petrochemical complexes offering the most stable demand profiles.
- Refineries:Domestic processing capacity at Abadan, Isfahan, and Bandar Abbas facilities absorbs medium and heavy crude slates. Upgrade investments to handle extra-heavy West Karun grades proceed slowly.
- Power Plants:Gas-fired generation assets in Tehran and Shiraz load centers depend on South Pars supply commitments. Electricity subsidies distort true demand signaling.
- Petrochemical Companies:Asaluyeh and Bandar Imam complexes consume condensate and ethane feedstocks for olefin production. Methanol and ammonia export volumes compete for limited gas allocation.
- Industrial Users:Steel, cement, and fertilizer plants receive priority gas supply during winter peak demand periods. CNG vehicle fueling networks expand in urban corridors.
Petrochemical companies secure the largest contracted volumes; power plants are gaining share fastest on absolute demand growth.
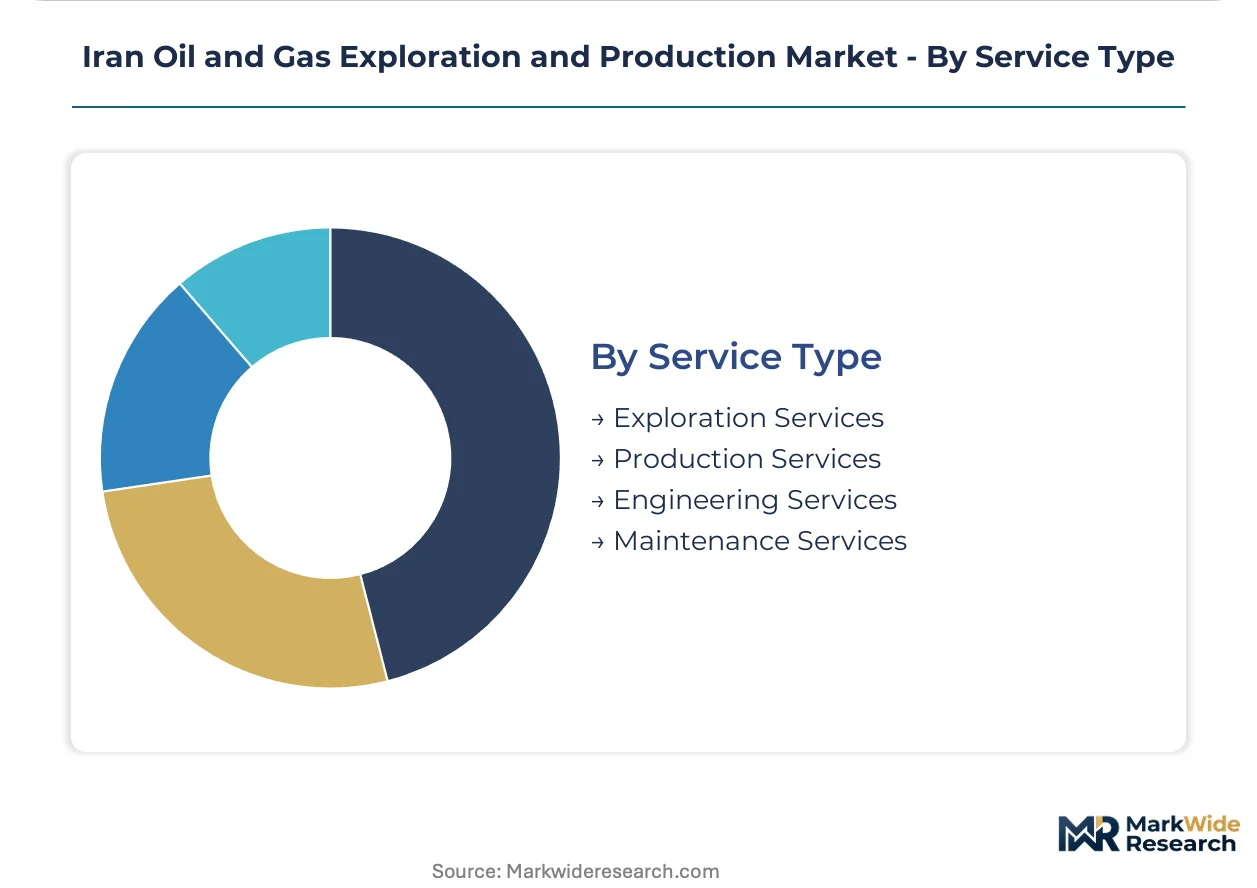
Service Type:
Margin structure varies by contract duration and risk allocation, with fixed-cost production services compressing returns relative to exploration risk-sharing arrangements.
- Exploration Services:Seismic acquisition and wildcat drilling face capital rationing as NIOC prioritizes development over greenfield appraisal. Buy-back contract terms limit foreign partner equity exposure.
- Production Services:Artificial lift installation and workover rigs operate under fixed-cost tenders at mature onshore fields. Service providers absorb downhole complexity risk.
- Engineering Services:Front-end design and project management concentrate at MAPNA Group and domestic EPC contractors. Local content mandates enforce fabrication sourcing through Iranian subcontractors.
- Maintenance Services:Well intervention and facility integrity programs sustain output at declining fields. Import restrictions on spare parts elevate downtime risk.
Production services generate the largest revenue pool; engineering services are expanding most quickly on South Pars phase construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iran's hydrocarbon trade balance tilts toward import substitution for refined products despite holding vast crude reserves, with sanctions constraining export revenue realization and foreign exchange access. Domestic consumption patterns and regional pipeline politics reshape production allocation across the country's major basins. Sub-regional development priorities diverge based on reservoir maturity and infrastructure proximity.
South Pars Gas Field
The world's largest non-associated gas reservoir drives condensate output for Asaluyeh petrochemical feedstock. Ministry of Petroleum production quotas prioritize phases 11 through 14 for domestic supply security. Kish Island special economic zone facilities process surplus volumes for limited export.
West Karun Basin
Azadegan and Yadavaran heavy oil blocks contain underdeveloped reserves requiring thermal recovery investment. Iran Petroleum Contract revisions target extended buy-back terms to attract foreign capital for these technically challenging fields. Ahvaz industrial corridor refineries absorb medium-gravity domestic crude.
Zagros Fold Belt
Mature onshore clusters at Gachsaran, Marun, and Ahwaz fields mandate enhanced oil recovery to offset natural decline. NIOC artificial lift deployment concentrates here under fixed-cost service tenders. Shiraz power generation load centers receive priority gas allocation from associated production.
Caspian Sea Offshore
Deepwater exploration in Iran's northern waters faces vessel availability constraints under sanctions. Khazar Exploration and Production Company holds block concessions with limited development progress. Anzali free trade zone offers streamlined customs for subsea equipment imports.
Persian Gulf Offshore
Sirri Island and Soroosh fields operate under Iranian Offshore Oil Company jurisdiction with shallow-water platform infrastructure. Condensate stabilization bottlenecks periodically constrain export terminal throughput. Qeshm free zone permits facilitate rig maintenance and spare parts access.
Iran Oil and Gas Exploration and Production Market Competitive Landscape
Concentration sits with state-backed operators controlling reserve access through direct NIOC field assignments. The capability gap between national companies and private partners is compressing as capital allocation rules tighten. Two strategic archetypes dominate: integrated state operators with direct reserve control, and specialized service consortiums executing fixed-cost development contracts. Competitive positioning hinges on buy-back contract tenure extension and local content compliance rather than technology differentiation.
Among state-anchored operators, National Iranian Oil Company occupies the central position as reserve gatekeeper and production quota setter. Petropars Ltd exemplifies the partnership-model archetype, sustaining development execution through consortium structures. MAPNA Group anchors domestic engineering procurement capacity, representing the localization-mandated fabrication tier that foreign contractors must engage for platform and rig construction compliance.
| Leading Market Players |
|---|
| National Iranian Oil Company |
| Petropars Ltd |
| MAPNA Group |
| Khazar Exploration and Production Company |
| Pasargad Energy Development Company |
| National Iranian South Oil Company |
| Iranian Offshore Oil Company |
| Pars Oil and Gas Company |
| Iranian Central Oil Fields Company |
| Others |
Supply & Pricing Matrix
Scale economies at South Pars gas processing facilities concentrate supply-side leverage among NIOC-affiliated operators and compress price floors for drilling and engineering services. Capacity utilization rates above 85% at Asaluyeh condensate stabilization plants reinforce buyer power for petrochemical feedstock offtake, while underutilized West Karun heavy oil infrastructure elevates cost recovery thresholds for thermal recovery contractors.
Pricing Analysis
Industrial OEM buyers anchor fixed-cost contract structures across NIOC tender rounds. Three-tier pricing structure across premium, standard, and economy levels separates international consortium partners from domestic EPC contractors and local subcontractors. Cost compression in drilling services intensifies because MAPNA Group's rig fabrication capacity cannot fully substitute sanctioned import channels. State-backed petrochemical complexes at Bandar Imam demonstrate lowest price sensitivity; independent industrial gas users face highest procurement cost volatility.
Supply Chain Analysis
China and South Korea anchor drilling equipment and subsea component fabrication for Iranian upstream projects. MAPNA Group sources steel structures and jackup rig hulls from domestic mills, though directional drilling software and managed pressure control systems draw from European and American suppliers now restricted by sanctions. Single-source vulnerability concentrates in high-pressure wellhead assemblies and subsea Christmas trees. Distribution runs through Kish Island and Qeshm free trade zones for customs-cleared equipment staging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed-cost production services and well intervention contracts expand faster than exploration hardware sales, creating attach opportunities for service providers with operational data platforms. Recurring revenue from artificial lift monitoring and predictive maintenance contracts outpaces newbuild rig deployment economics.
For Market Incumbents: Shield reserve access through accelerated South Pars phase completion before contract tenure windows compress. Prioritize vertical integration into condensate stabilization capacity at Asaluyeh to capture margin leakage from infrastructure bottlenecks. Counter emerging digital twin specialists by embedding real-time monitoring into legacy service contracts. For New Entrants and Emerging Players: Anchor in Azadegan heavy oil block thermal recovery pilots where NIOC's extended buy-back terms reduce capital recovery risk. Target underpenetrated Caspian Sea offshore seismic survey demand where vessel availability constraints have thinned incumbent presence. Lead with reservoir engineering talent recruitment from UAE and Qatar expatriate networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors service providers with Iranian domestic content certification and NIOC pre-qualification status. Long-term viability rests on sanctions relief optionality rather than current cash flow generation. Monitor Central Bank repatriation rule amendments as the primary inflection signal for foreign partner capital redeployment.| Strategic Initiative | Industry Significance |
|---|---|
| Buy-Back Contract Tenure Extension | Longer capital recovery windows attract foreign consortium partners to West Karun heavy oil blocks. |
| Domestic Content Certification Investment | NIOC local content mandates enforce fabrication sourcing through MAPNA Group and Iranian subcontractors. |
| Digital Twin Platform Deployment | Real-time reservoir simulation convergence opens efficiency gains at mature fields with legacy data gaps. |
| Condensate Stabilization Capacity Buildout | Asaluyeh infrastructure expansion absorbs South Pars phase output and reduces export terminal bottlenecks. |
| Special Economic Zone Permit Utilization | Kish Island and Qeshm free trade zones streamline customs procedures for sanctioned subsea equipment imports. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with NIOC planning officers, Petropars project managers, MAPNA Group procurement leads, and Bandar Imam petrochemical complex feedstock directors. Secondary validation drew from Ministry of Petroleum production quota disclosures, Central Bank of Iran repatriation circulars, South Pars phase commissioning reports, and Iran Petroleum Contract framework amendments. Bottom-up field-level production estimates and top-down sector value aggregation were triangulated against contract award databases.
Across the analysis window, the forecast framework modeled hydrocarbon type segmentation, technology tier differentiation, end-user concentration patterns, and service contract structure evolution. CAGRs were derived from production trajectory modeling against infrastructure commissioning schedules and NIOC capital allocation priorities. Key inputs included South Pars phase completion timelines, West Karun thermal recovery pilot results, and sanctions enforcement intensity indices.
Material uncertainties — sanctions relief timing, Central Bank repatriation rule revisions, and drilling rig import channel viability — sit outside the modeled envelope. Forecasts reflect assumptions about contract framework stability and foreign partner risk appetite. Recalibration cycles align with material shifts in sanctions enforcement posture and Iran Petroleum Contract amendment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Well Completion Market
Oil & Gas
Deepwater Hydrocarbons Exploration Market
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
Latin America Coiled Tubing Market
Oil & Gas
Well Logging Tools Market
Oil & Gas
Oilfield Drill Bits Sales Market
Oil & Gas
Global Oilfield Communications Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
Logging While Drilling (LWD) Market
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Smart Oilfield Market