
 Packaged Burgers Market | 2026-2036
Packaged Burgers Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Burgers Market Intelligence
New front-of-pack labeling requirements from the US FDA and Europe's Nutri-Score system are consolidating the market around transparently sourced ingredients. Nestlé S.A. leverages its extensive global distribution network to introduce both meat and plant-based options across diverse retail formats. Impossible Foods Inc. specializes in developing proprietary heme-containing formulations to mimic the taste and texture of conventional beef. BUBBA foods LLC sustains its market position through a focus on classic, high-quality frozen beef patties for the US retail segment.
Packaged burgers are pre-formed patties, either cooked or raw, sealed for retail or foodservice distribution to extend shelf life and ensure food safety. These products typically have a specific fat-to-lean meat ratio, such as 80/20, and are formulated with binders and seasonings. Their primary purpose is to provide a convenient meal solution for consumers and standardized ingredients for commercial kitchens. Frozen products dominate sales volume due to longer shelf life, while the plant-based meat source category represents the fastest-growing segment.
Product safety and labeling are governed by agencies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). In China, the State Administration for Market Regulation (SAMR) enforces GB standards for food additives and contaminants. These regulations directly influence formulation, packaging claims, and market access. Future competitive advantage will depend on navigating evolving international food safety protocols and managing supply chain volatility for key protein inputs.
Market Dynamics
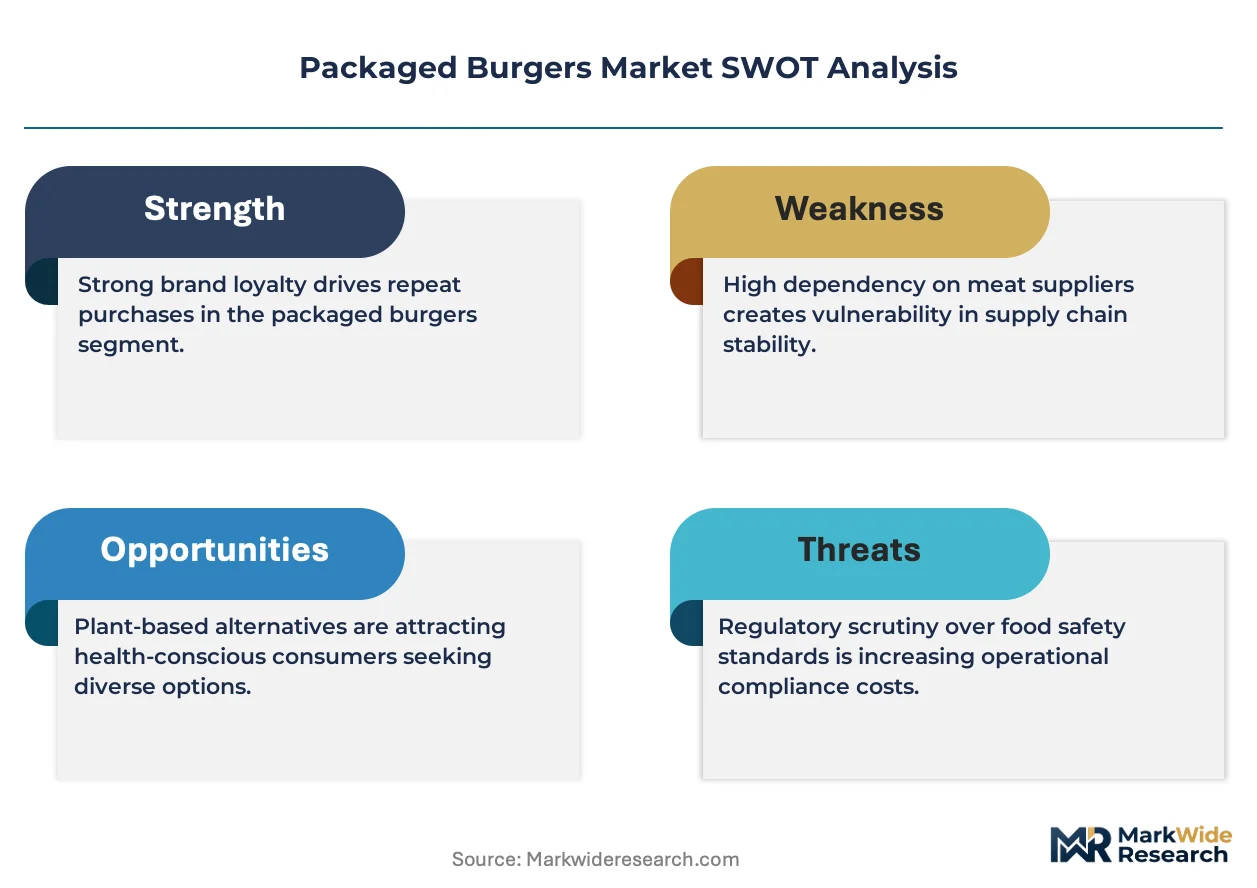
The central dynamic shaping the packaged burgers market is the tension between the mass-market demand for convenience and the growing consumer insistence on ingredient transparency and alternative proteins. This bifurcation forces producers to manage dual supply chains: one optimized for volume and cost for traditional beef patties, and another built for value-added attributes like plant-based formulations and clean-label credentials.
Growth Catalysts
- Foodservice Expansion:The continued global expansion of quick-service restaurants, particularly in Asia-Pacific and Latin American markets, creates sustained demand for standardized, pre-packaged patties that ensure consistency and operational efficiency.
- Advanced Processing Technology:Innovations like high-moisture extrusion for plant-based proteins are creating products with more realistic meat-like textures, successfully attracting flexitarian consumers who were previously deterred by the sensory profile of legacy vegetarian burgers.
- Convenience Culture in Europe:Strong demand for convenient meal solutions in developed markets, especially Germany, combined with a high degree of consumer trust in frozen food formats, provides a powerful catalyst for both traditional and alternative protein burgers.
Market Restraints
- Input Price Volatility:Fluctuations in the global commodity prices for key inputs, such as beef trimmings and soy protein isolate, create significant margin pressure and make long-term cost planning difficult for manufacturers.
- Cold Chain Infrastructure Gaps:In certain emerging markets, underdeveloped cold chain logistics present a structural barrier, limiting the distribution of frozen products and increasing the risk of spoilage and food safety incidents.
- Regulatory Formulation Hurdles:Strict regulations on food additives and binders, such as those enforced by the European Food Safety Authority (EFSA), can constrain formulation options, slowing innovation for products that must balance texture, taste, and shelf stability.
Strategic Opportunities
- Hybrid Product Development:There is a significant opportunity in creating hybrid burgers that blend conventional meat with plant-based ingredients or mushrooms, appealing to health-conscious consumers seeking reduced meat consumption without abandoning traditional flavors.
- Direct-to-Consumer Channels:Establishing direct-to-consumer (DTC) e-commerce platforms allows brands to capture higher margins and build direct relationships with consumers, particularly for niche products like organic, grass-fed, or specialized plant-based options.
- Clean Label and Fortification:Developing patties with simplified, "clean label" ingredient lists and fortifying them with vitamins and minerals can command a premium by appealing to health and wellness-focused consumer segments.
Industry Challenges
- Packaging Compliance Costs:The operational challenge of redesigning entire product lines to comply with new front-of-pack labeling mandates, such as the US FDA's updated nutrition facts or Europe's Nutri-Score, requires significant investment and logistical coordination.
- Managing Allergen Cross-Contamination:For facilities producing both traditional meat and plant-based products, which often contain common allergens like soy or wheat, preventing cross-contamination requires stringent and costly production scheduling and sanitation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Burgers Market |
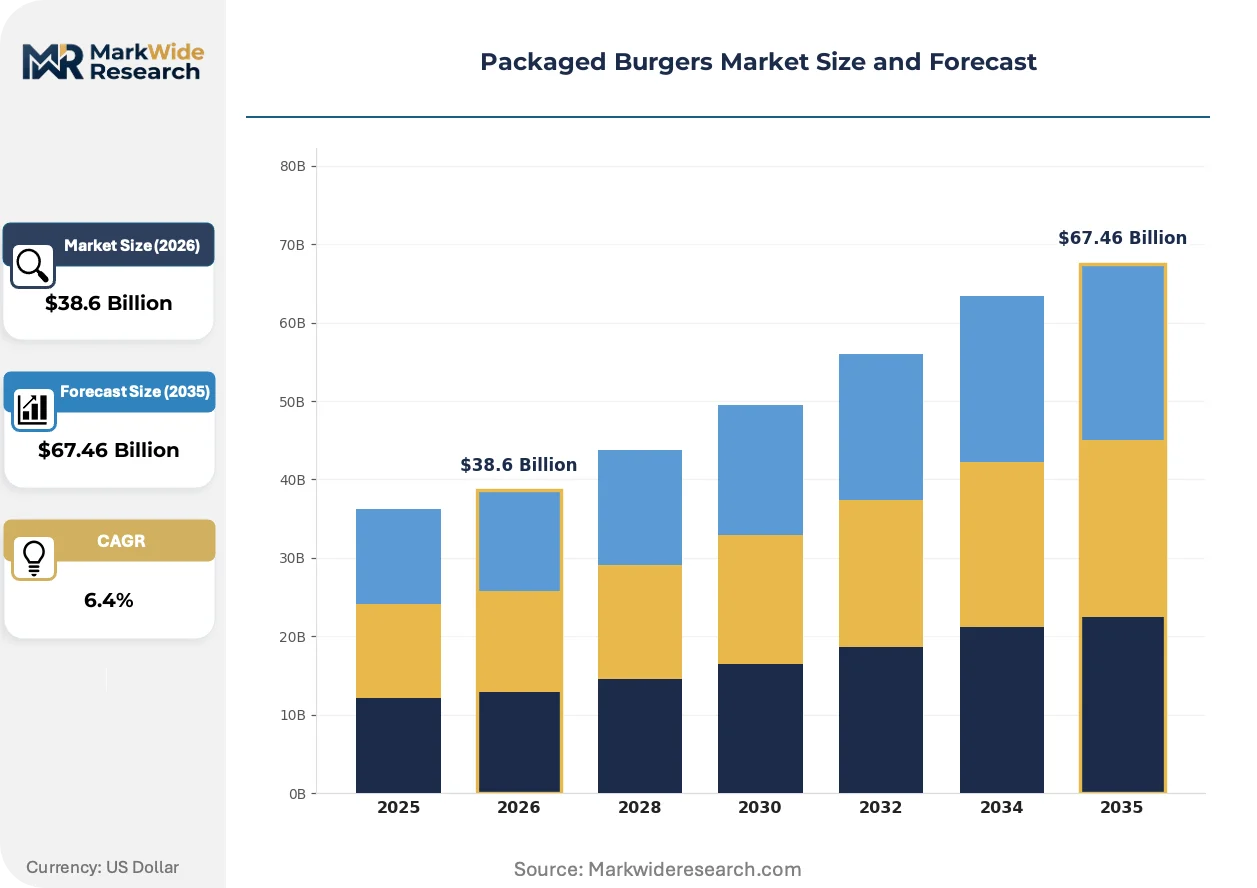
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Refrigerated, Canned, Shelf-stable Meat Source: Beef, Chicken, Turkey, Plant-based Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Foodservice Package Type: Tray, Vacuum-Sealed, Boxed, Pouch |
| Companies Covered | Beyond Meat Inc., BUBBA foods LLC, Impossible Foods Inc., The Kraft Heinz Company, Nestlé S.A., Dr. Praeger's Sensible Foods, Paragon Quality Foods, WK Kellogg Co, Amy's Kitchen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Burgers Market Strategic Shifts & Innovations
Product development is pivoting from a singular focus on cost and preservation toward a multi-faceted strategy emphasizing sensory experience, nutritional transparency, and protein source diversification. This shift reflects a market where consumer choice is increasingly influenced by factors beyond simple convenience. The result is a more complex and competitive innovation landscape.
High-moisture extrusion is a key processing technology that applies heat and pressure to plant proteins, creating fibrous structures that mimic the texture of muscle meat. Foodservice operators and premium retail brands are rapidly adopting this method to elevate their plant-based offerings. The resulting textural realism is overtaking older, crumbly veggie patty formulations, establishing a new quality benchmark that expands consumer acceptance.
Europe's comprehensive "Farm to Fork" strategy, along with the voluntary but influential Nutri-Score front-of-pack labeling system, is compelling manufacturers to improve the nutritional profile of their products. This regulatory pressure forces reformulation, particularly around reducing sodium and saturated fat content. The conventional frozen beef burger segment is most impacted, responding by launching leaner options and highlighting transparent sourcing on packaging.
Consumer purchasing behavior is fragmenting away from a single, large weekly grocery trip toward multiple, smaller purchases across different channels. This trend disrupts the market dominance of large, family-sized frozen multipacks typically sold in hypermarkets, creating demand for smaller pack sizes and single-serve options. The shift is most pronounced in dense urban centers in North America and Europe, where online grocery, convenience stores, and meal-kit services are prevalent.
Packaged Burgers Market Segmentation
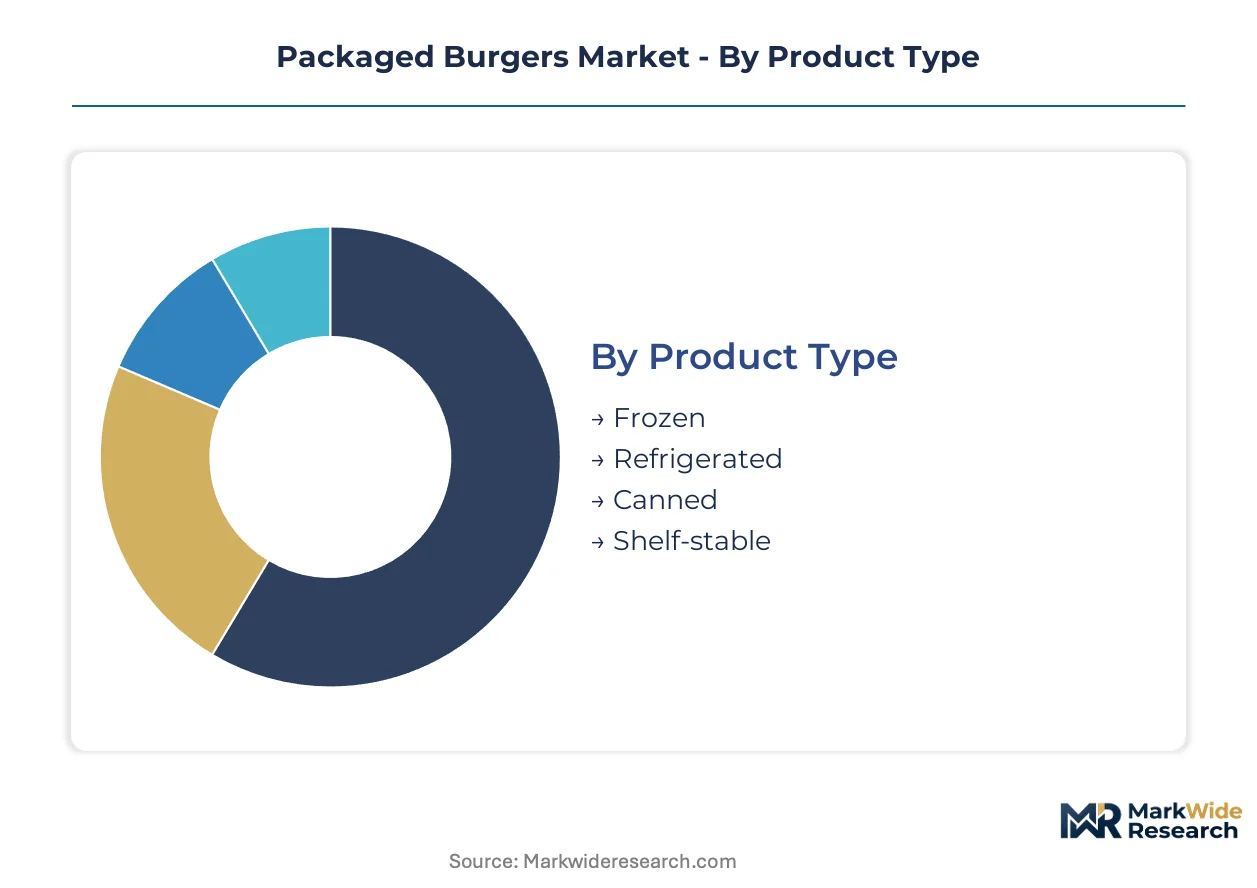
The packaged burgers market exhibits diverse segmentation, reflecting varied consumer preferences, technological advancements, and distribution complexities. Understanding these distinct segments provides clarity on market dynamics and strategic positioning for manufacturers. This granular analysis illuminates where value is created and captured across the supply chain.
Product Type:
Consumer decisions regarding packaged burgers often hinge on desired preparation time and perceived freshness, influencing product type selection.
- Frozen:These patties are preserved at sub-zero temperatures, offering extended shelf life and significant convenience for both retail consumers and foodservice operations. Frozen products dominate sales volume due to longer preservation and ease of storage.
- Refrigerated:Maintained at chilled temperatures, refrigerated burgers appeal to consumers seeking fresher options with a shorter shelf life, often found in the fresh meat sections of supermarkets. Demand for refrigerated products is increasing in urban centers due to perceived quality.
- Canned:Canned burger products are shelf-stable, undergoing retort processing to ensure long-term preservation without refrigeration. This format offers extreme convenience in specific niche markets.
- Shelf-stable:These products utilize various preservation methods, including advanced packaging or specific formulations, to remain stable at ambient temperatures. Shelf-stable options cater to emergency preparedness or limited cold chain regions.
Frozen products lead on sales volume; refrigerated options lead on convenience momentum.
Meat Source:
The choice of meat source directly reflects evolving dietary preferences and health considerations among consumers globally.
- Beef:Conventional beef patties, often formulated with specific fat-to-lean ratios like 80/20, remain a staple in the packaged burger market, valued for their traditional taste and texture. This segment holds the largest volume share, particularly in North American and European markets.
- Plant-based:Utilizing ingredients like soy, pea, or mushroom proteins, these patties mimic the sensory experience of meat, attracting flexitarian and vegetarian consumers. Plant-based options are the fastest-growing segment, propelled by innovations in high-moisture extrusion.
- Chicken:Chicken burgers offer a leaner alternative to beef, appealing to health-conscious consumers and those seeking different flavor profiles. This segment sees consistent demand in various global markets.
- Turkey:Turkey patties provide another lean protein option, often marketed for their lower fat content and distinct taste. Turkey burgers are popular in specific dietary niches across the United States.
Beef patties command the largest market share, while plant-based formulations represent the fastest-growing segment.
Distribution Channel:
Market accessibility and consumer purchasing habits dictate the prominence of various distribution channels for packaged burgers.
- Foodservice:This channel includes quick-service restaurants, casual dining establishments, and institutional kitchens that rely on standardized, pre-packaged patties for operational efficiency and consistency. The global expansion of quick-service restaurants, particularly in Asia-Pacific, drives significant volume through this channel.
- Supermarkets:Large retail chains offer a broad selection of packaged burgers, catering to household consumers seeking convenient meal solutions for at-home consumption. Supermarkets remain a primary purchasing point for traditional beef and frozen varieties.
- Convenience Stores:These smaller format stores provide quick access to single-serve or smaller multi-packs of packaged burgers, addressing immediate consumer needs. Convenience stores are important for impulse purchases in urban areas.
- Online Retailers:E-commerce platforms and grocery delivery services facilitate the purchase of packaged burgers, offering convenience and a wider selection of niche or specialty products. Online sales are gaining share in North America and Western Europe.
Foodservice channels prioritize operational efficiency; online retailers offer direct consumer access and niche product availability.
Package Type:
Packaging innovation for packaged burgers balances product preservation with consumer convenience and visual appeal on retail shelves.
- Tray:Often made of plastic or foam, tray packaging is common for refrigerated and fresh packaged burgers, providing visibility and protection. This type is prevalent in supermarket fresh meat sections.
- Vacuum-Sealed:This method removes air from the package, extending shelf life and preventing freezer burn, particularly for frozen and some refrigerated products. Vacuum-sealed packaging enhances food safety and product integrity.
- Boxed:Boxed packaging typically encloses multiple frozen patties, offering structural protection and space for branding and nutritional information. This format is common for larger family-sized packs.
- Pouch:Flexible pouch packaging is used for some shelf-stable or specialty burger products, offering lightweight and compact storage solutions. Pouch formats are gaining traction for innovative, ready-to-heat options.
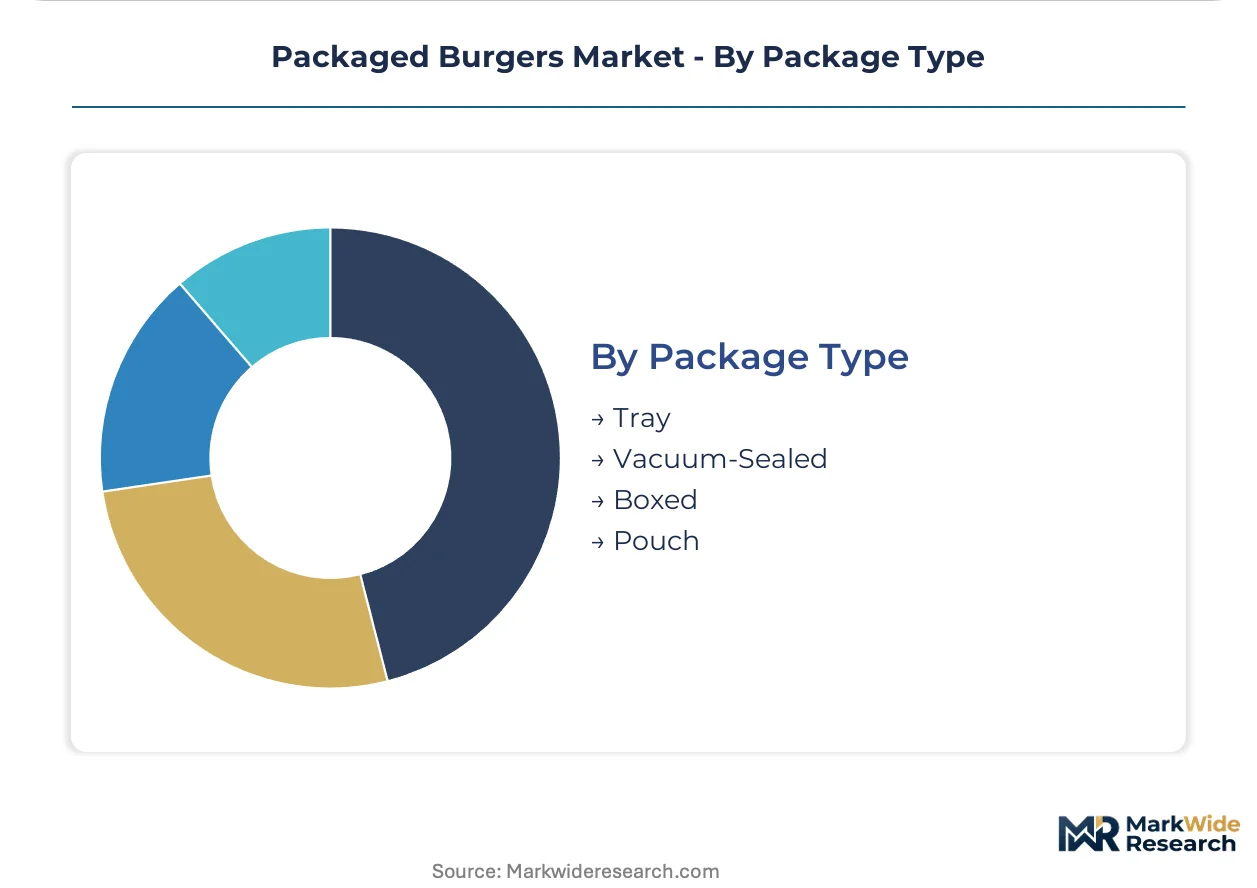
Tray packaging supports visual appeal in retail; vacuum-sealed formats ensure extended shelf life and food safety.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled food science and processing talent concentrations anchor innovation and market growth across several key geographies. These regions combine strong consumer demand with robust regulatory frameworks and advanced manufacturing capabilities, fostering product development and market expansion for packaged burgers.
United States
Consumer demand for convenient meal solutions and diverse protein options drives the United States packaged burger market. The US Food and Drug Administration (FDA) new front-of-pack labeling requirements influence product formulation and transparency. Major food processing hubs in states like Illinois and California see significant investment in both traditional and plant-based patty production.
Germany
Strong consumer preference for convenience and alternative protein options boosts the packaged burger market in Germany. Europe's Nutri-Score system encourages manufacturers to improve the nutritional profiles of their offerings. Food innovation clusters in cities like Berlin and Hamburg are at the forefront of developing advanced plant-based formulations.
China
Urbanization and the expansion of quick-service restaurants fuel demand for standardized packaged burgers in China. The State Administration for Market Regulation (SAMR) enforces stringent GB standards for food additives and contaminants. Major metropolitan areas like Shanghai and Guangzhou are key distribution and consumption centers for these products.
India
A growing middle class and increasing urbanization contribute to the demand for convenient food products, including packaged burgers, in India. The Food Safety and Standards Authority of India (FSSAI) regulates food product safety and labeling. Food processing zones in states such as Maharashtra and Gujarat are expanding their capacity for frozen food production.
Brazil
The expanding foodservice sector and a rising consumer base seeking convenient meal options support the Brazilian packaged burger market. Brazil's National Health Surveillance Agency (ANVISA) oversees food safety and quality standards. Agricultural regions in states like São Paulo and Minas Gerais are important for raw material sourcing and processing.
Packaged Burgers Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the packaged burgers market. The market structure exhibits a tiered approach, with global food giants leveraging extensive distribution networks alongside agile innovators. Strategic archetypes include traditional meat processors, plant-based technology pioneers, and niche premium brands. Portfolio diversification into both meat and plant-based offerings and strategic partnerships are dominant competitive moves.
Within the diversified food giant archetype, Nestlé S.A. leverages its extensive global distribution network to introduce both meat and plant-based options. Impossible Foods Inc. exemplifies the specialized plant-based innovator, developing proprietary heme-containing formulations to mimic conventional beef. Meanwhile, BUBBA foods LLC represents a focused player, sustaining its market position through classic, high-quality frozen beef patties for the US retail segment.
| Leading Market Players |
|---|
| Beyond Meat Inc. |
| BUBBA foods LLC |
| Impossible Foods Inc. |
| The Kraft Heinz Company |
| Nestlé S.A. |
| Dr. Praeger's Sensible Foods |
| Paragon Quality Foods |
| WK Kellogg Co |
| Amy's Kitchen Inc. |
| Others |
Cost & Logistics Intelligence
Foodservice operators' demand for consistent quality often drives contract-based pricing in the packaged burgers market. This structure minimizes immediate price volatility for large buyers while securing volume for manufacturers.
Pricing Analysis
Bundled service offerings, including pre-portioned and pre-seasoned patties, allow for premium pricing in the foodservice segment. The dominant pricing model is per-unit transactional, often supplemented by long-term contracts for large volume buyers. Price differentiation stems from meat source quality and brand premium, particularly for plant-based innovators. Pricing softness reflects intense competition in the conventional frozen beef patty segment due to oversupply. Foodservice buyers are generally less price-sensitive than individual retail consumers.
Supply Chain Analysis
Beef trimmings supply relies heavily on large-scale beef processors concentrated in the United States and Brazil. Key raw material dependencies include beef trimmings, soy protein isolate, and specialized binders. Commodity price volatility for these agricultural inputs creates significant margin pressure for manufacturers. Distribution runs through established foodservice and retail networks, with cold chain infrastructure being critical for frozen product integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The packaged burgers market functions as a stable compounder, with sustained demand for convenience and evolving protein preferences driving consistent expansion. Global quick-service restaurant expansion provides a reliable growth foundation.
For Market Incumbents: Hedge against input price volatility by securing long-term supply agreements for beef trimmings and plant proteins. Diversify product portfolios to include both traditional meat and advanced plant-based options, mitigating risk from shifting consumer preferences. Invest in advanced processing technology like high-moisture extrusion to maintain a competitive edge against emerging plant-based innovators. Enhance cold chain logistics in emerging markets to expand distribution reach.
For New Entrants and Emerging Players: Health-conscious flexitarian consumers represent an underserved buyer archetype for innovative packaged burger products. Target niche segments like organic, grass-fed, or specialized plant-based options with clean label credentials. A direct-to-consumer e-commerce platform offers a compelling go-to-market angle, bypassing established retail channels and building brand loyalty. Focus on regions with strong convenience culture, such as Germany, for initial market penetration.
For Investors and Strategic Acquirers: Diversified food conglomerates are the most active acquirers in this space, seeking to expand their protein portfolios and distribution reach. The market offers long-term viability over a 5-10 year window, driven by sustained consumer demand for convenience and alternative proteins. Acquisition targets should be agile plant-based innovators or niche premium brands with proprietary formulations. Regulatory shifts, particularly new front-of-pack labeling mandates, serve as a critical signal to watch for market consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification (Meat & Plant-based) | Expands market reach by appealing to a broader range of consumer dietary preferences. |
| Investment in High-Moisture Extrusion | Enhances textural realism of plant-based patties, attracting flexitarian consumers. |
| Direct-to-Consumer (DTC) E-commerce Launch | Captures higher margins and builds direct brand relationships with niche consumers. |
| Supply Chain Digitization for Traceability | Ensures compliance with evolving food safety and transparent sourcing regulations. |
| Fortification of Patties with Micronutrients | Commands a premium by addressing health and wellness trends among consumers. |
Research Approach
Bottom-up foodservice modeling reconciled against top-down protein input tracking forms the analytical core of this study. Primary interviews with food scientists, procurement managers at quick-service restaurants, retail category buyers, and plant-based ingredient suppliers provided qualitative insights. Secondary validation drew from US FDA filings, EFSA reports, SAMR GB standards, and Nielsen retail audit data. This approach ensured comprehensive data triangulation.
An input-output matrix integrates market drivers, restraints, and opportunities to project market trajectory across the analysis window. Segmentation dimensions modeled included product type, meat source, distribution channel, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected market shifts. Key forecast inputs included global quick-service restaurant expansion rates and plant-based protein innovation pipelines.
Underlying measurement precision varies by segment; conventional beef patties carry tighter precision than emerging hybrid products. Forecasts reflect assumptions regarding consumer preference evolution and regulatory stability. Input price volatility and unforeseen supply chain disruptions could revise projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Freekeh Market
Packaged Foods
Canned Soup Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
Food and Beverages Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Canned Beans Market
Packaged Foods
UAE Breakfast Cereals Market
Packaged Foods
Bangladesh Instant Noodles Market
Packaged Foods
Packaged Zhug Market
Packaged Foods
Global Packed Food Market
Packaged Foods
Canned Food Market
Packaged Foods
South America Breakfast Cereals Market
Packaged Foods
Prepared Flour Mixes Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Sugar-Free Biscuits and Cookies Market
Packaged Foods
Morning Goods Market