
 Europe Ready-To-Eat Food Market | 2026-2036
Europe Ready-To-Eat Food Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ready-To-Eat Food Market Foresight
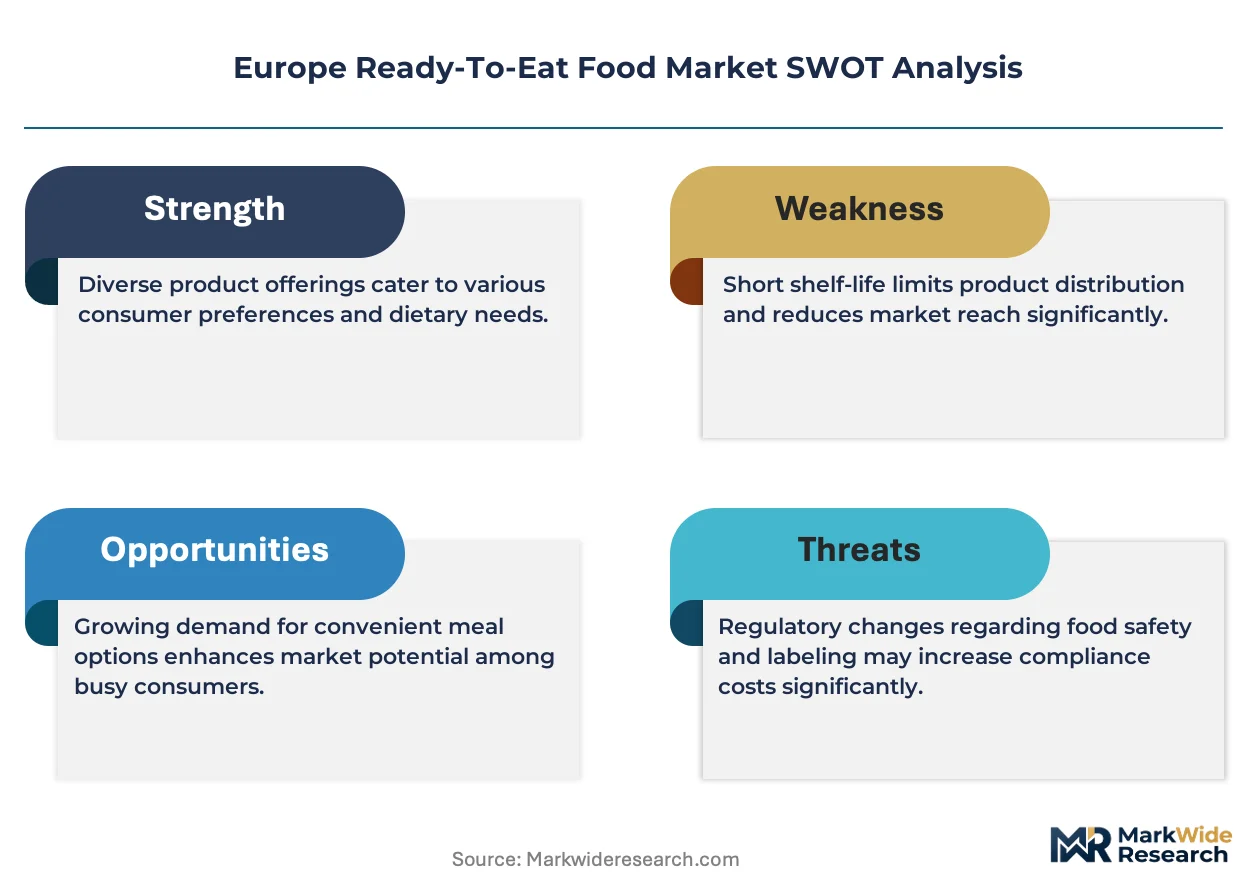
The European ready-to-eat food market is decoupling into two distinct tiers: premium chilled and frozen offerings with clean-label positioning versus commodity canned and dried segments competing on price. Nestlé S.A. leverages its pan-European distribution infrastructure to dominate the frozen dinner category across multiple countries. Greencore Group Plc anchors the chilled prepared meal segment through its manufacturing scale and direct supply relationships with British and Irish retailers. Dr. Oetker KG specializes in premium frozen pizza and bakery products, sustaining brand loyalty through consistent quality and regional recipe adaptation.
Ready-to-eat food encompasses pre-cooked, pre-packaged meals requiring minimal or no preparation beyond heating, typically formulated with specified moisture content, shelf-life parameters, and thermal processing standards to ensure microbiological safety. The category serves industrial purposes by reducing labor costs in food service, institutional catering, and retail environments where speed and portion consistency matter. Frozen dinners lead product type revenue due to extended shelf stability and established cold chain infrastructure, while chilled food represents the fastest-growing segment as consumers prioritize freshness perception and shorter ingredient lists. Online retailers within the distribution channel dimension are capturing disproportionate growth as digital procurement penetrates both household and food service buying patterns.
EFSA governs nutritional and health claims across the European market, while the EU Green Deal and REACH framework mandate progressive reductions in packaging waste and restricted substance use. EMA and national food safety agencies enforce Good Manufacturing Practice standards that determine market access for cross-border suppliers. The F-Gas Regulation further constrains cold chain operations, pushing investment into alternative refrigeration technologies. Stakeholders must monitor evolving CSRD disclosure requirements and national transpositions of EU packaging directives to anticipate compliance costs and redesign timelines.
Market Dynamics
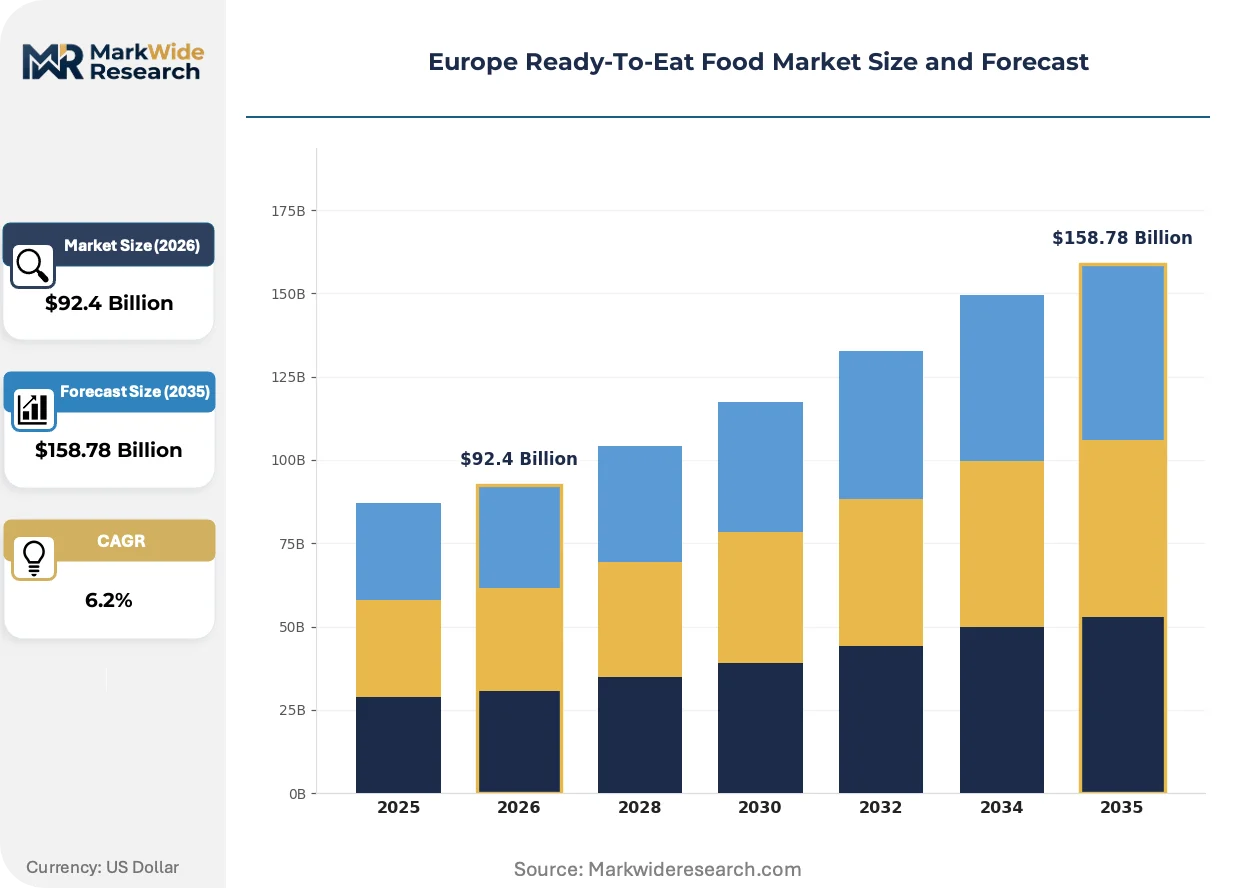
EFSA nutritional labeling mandates and the EU Green Deal packaging rules are forcing simultaneous reformulation and sustainable packaging investments across European ready-to-eat food manufacturers, compressing margins while accelerating product line rationalization.
Growth Catalysts
- EFSA Nutritional Labeling:The European Food Safety Authority's front-of-pack labeling requirements push manufacturers toward cleaner ingredient decks. This regulatory pressure opens premium positioning for brands that reformulate first.
- Cold Chain Modernization:Investments in alternative refrigeration technologies under the F-Gas Regulation are extending shelf-stable distribution reach. Frozen dinner producers now penetrate smaller urban retail formats previously inaccessible.
- Institutional Procurement Scaling:German, French, and British food service operators are consolidating supplier relationships. Direct procurement contracts with prepared meal manufacturers displace fragmented wholesale purchasing.
Market Restraints
- Packaging Input Cost Volatility:Bio-based and recyclable packaging materials face supply constraints under REACH framework compliance timelines. Manufacturers absorb margin compression while scaling sustainable alternatives.
- Cold Chain Concentration Risk:Third-party logistics providers controlling frozen and chilled distribution in Northern Europe extract premium rates. Limited alternative infrastructure locks producers into concentrated supplier relationships.
- Refrigeration Technical Limitation:Alternative refrigeration technologies for F-Gas compliance remain energy-intensive at commercial scale. Frozen food warehouses face operational trade-offs between emissions targets and throughput capacity.
Strategic Opportunities
- Poland and Romania Expansion:Underpenetrated markets in Eastern Europe present volume growth for chilled prepared meals. Modern retail format expansion in Warsaw and Bucharest creates first-mover positioning.
- CSRD Disclosure Tailwind:The Corporate Sustainability Reporting Directive mandates supply chain transparency. Ready-to-eat brands with verified sustainable sourcing gain preferential listing with ESG-focused retailers.
- Direct-to-Foodservice Digital Platforms:Online procurement portals are disintermediating traditional food service distributors. Manufacturers capturing institutional buyers through proprietary digital channels retain margin otherwise lost to intermediaries.
Industry Challenges
- Reformulation Talent Scarcity:Food technologists capable of clean-label reformulation without compromising shelf stability command premium compensation. Manufacturers compete for limited technical expertise across the continent.
- Packaging Certification Timelines:EU Green Deal compliance verification for novel sustainable materials extends 18-24 months. Product launch schedules compress against regulatory approval windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ready-To-Eat Food Market |
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $158.78 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Meals, Frozen Dinners, Dried Snacks, Chilled Food End User: Retail Consumers, Food Service, Institutional Buyers, Online Shoppers Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Food Shops Packaging Type: Plastic Containers, Canned Packaging, Vacuum Packs, Ready-to-Serve Trays |
| Companies Covered | Nomad Foods Ltd, Nestlé S.A., McCain Foods Limited, The Kraft Heinz Company, Dr. Oetker KG, Premier Foods Group Limited, Frosta Aktiengesellschaft, Ebro Foods, S.A., Greencore Group Plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ready-To-Eat Food Market Shifts & Advancements
High-pressure processing and modified atmosphere packaging are converging with digital traceability systems to redefine freshness perception and supply chain transparency across European chilled and frozen prepared meals.
High-pressure processing technology uses extreme hydrostatic pressure to eliminate pathogens without thermal degradation. Chilled prepared meal manufacturers in France and the United Kingdom are adopting this technology at accelerating rates to extend shelf life without preservative additives. The technology is expanding into premium private-label contracts with British and Irish retailers seeking differentiated freshness claims.
The EU Green Deal packaging rules mandate progressive reductions in single-use plastics and establish extended producer responsibility frameworks. Food manufacturers face redesign investments for recyclable or compostable primary packaging by specified compliance windows. Frozen pizza and bakery segments encounter the steepest cost curves given multi-material laminate requirements for moisture barrier performance.
Urban household purchasing patterns favor smaller-format, single-serve chilled meals over traditional family-size frozen offerings. French and German convenience retailers are reallocating refrigerated case space toward fresh-perception prepared meals. This behavioral pivot concentrates volume growth in urban catchments where time-scarcity demographics cluster and delivery aggregator penetration is highest.
Europe Ready-To-Eat Food Market Segmentation
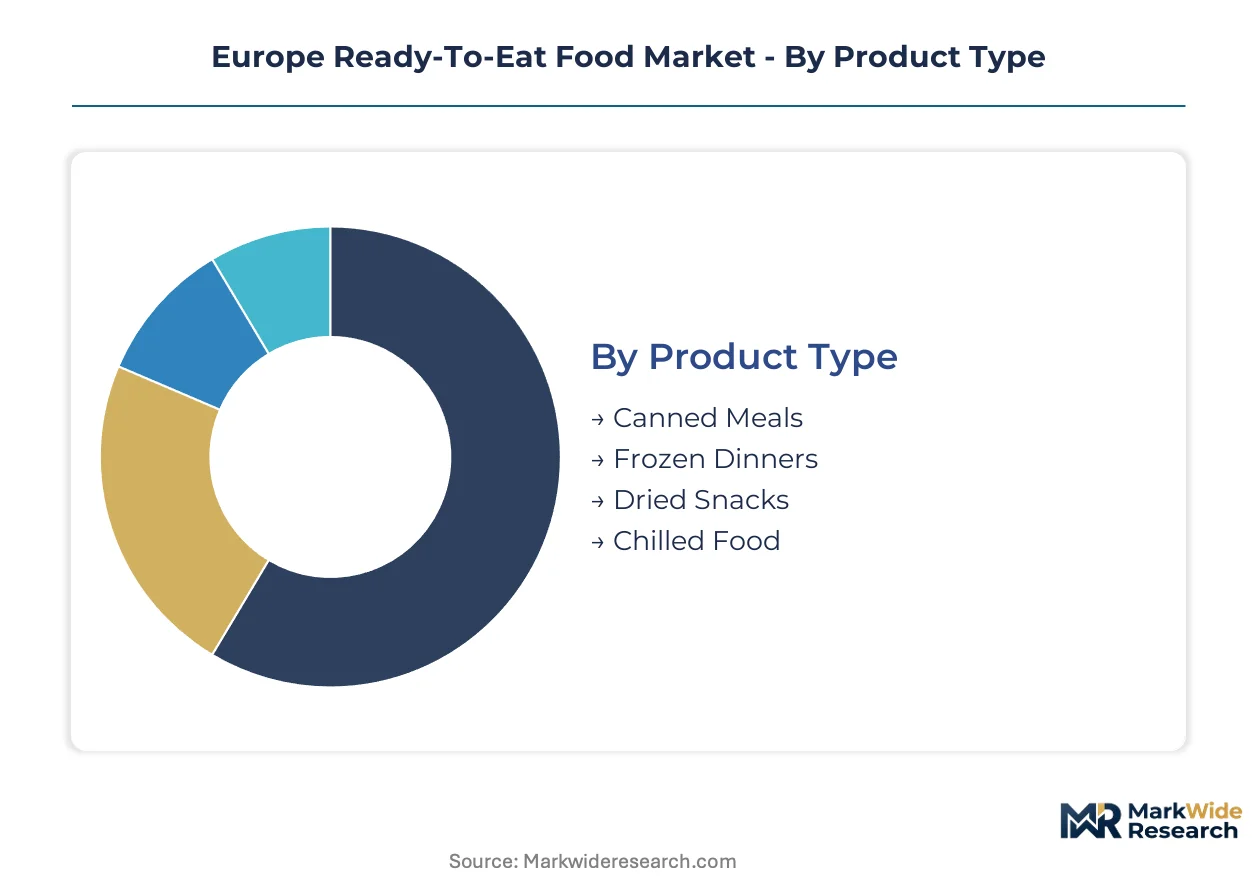
Segmentation reveals how European ready-to-eat food manufacturers allocate capital across divergent demand profiles. Product format, buyer type, and channel access determine margin structure and regulatory exposure for each slice of the market.
Product Type:
Upgrade cycles vary sharply across formats, with thermal processing and cold chain requirements driving replacement timelines for production equipment.
- Frozen Dinners:Multi-component meals undergo blast freezing to preserve texture and nutritional integrity. German and British retail chains anchor volume for premium single-serve and family formats, though energy costs under the F-Gas Regulation compress operating margins for producers.
- Chilled Food:Vacuum-sealed prepared meals with modified atmosphere packaging target freshness-sensitive urban consumers. French convenience retailers and British meal-kit aggregators are expanding refrigerated case space for this segment as high-pressure processing extends shelf life without chemical preservatives.
- Canned Meals:Retort-pouched and metal-canned products serve emergency preparedness and institutional stockpiling needs with multi-year stability.
- Dried Snacks:Dehydrated meal components and instant formulations concentrate in Eastern European markets with less developed cold chain infrastructure.
Frozen Dinners sits at the top of the volume ranking, with Chilled Food climbing the fastest.
End User:
Cost tiers separate household purchasers from commercial buyers, with procurement scale and specification rigor determining supplier qualification requirements.
- Food Service:Hotels, restaurants, and contract caterers specify portion-controlled prepared meals to reduce labor hours and waste. Consolidated procurement by French and German hospitality groups is displacing fragmented wholesale purchasing, favoring manufacturers with HACCP certification and direct delivery capability.
- Institutional Buyers:Hospitals, schools, and military catering operations demand nutritional compliance and batch traceability. EFSA labeling mandates and national dietary guidelines in Germany and Italy drive reformulation toward reduced sodium and clean-label ingredient decks.
- Retail Consumers:Time-scarce urban households purchase single-serve and family formats through physical and digital channels.
- Online Shoppers:Subscription meal services and aggregator platforms capture trial-oriented buyers seeking variety without pantry commitment.
Food Service captures the largest revenue share, while Online Shoppers are gaining share fastest as digital penetration deepens.
Distribution Channel:
Channel concentration in Northern Europe creates margin pressure, with modern retail formats controlling access to household purchasers.
- Supermarkets:Full-service grocers dominate frozen and chilled meal distribution through dedicated aisle and refrigerated case space. British and German multiples are rationalizing supplier rosters, delisting secondary brands to prioritize private-label and tier-one national products.
- Online Retailers:Pure-play digital grocers and platform marketplaces capture disproportionate growth in urban catchments. Direct-to-consumer chilled meal subscriptions in France and the Netherlands bypass traditional retail markup, though cold chain fulfillment costs erode unit economics.
- Convenience Stores:Small-format urban retailers emphasize grab-and-go chilled offerings for commuter and evening meal occasions.
- Specialty Food Shops:Delicatessens and gourmet retailers stock premium imported and artisan prepared meals for occasion-based purchasing.
Supermarkets maintain volume leadership, with Online Retailers showing the steepest expansion trajectory.
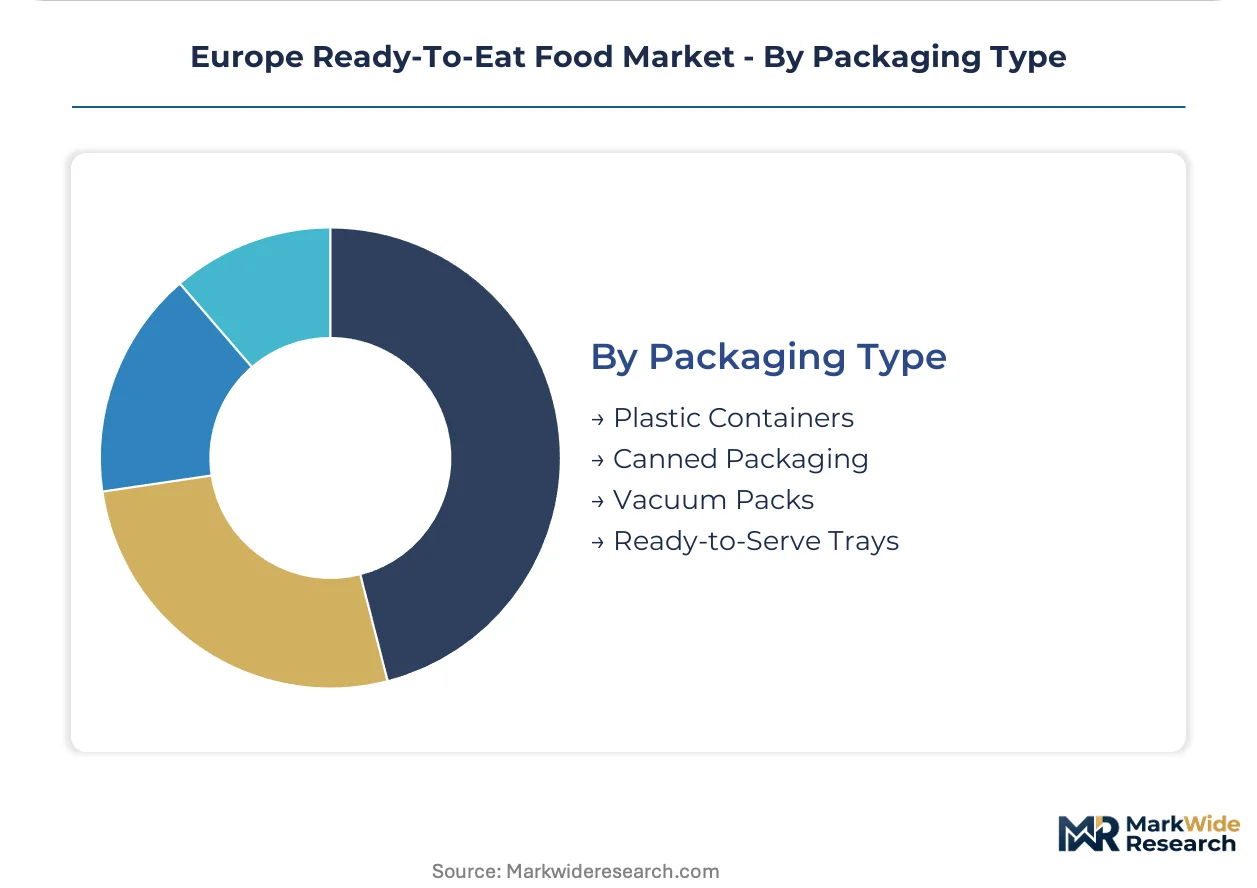
Packaging Type:
Margin pressure concentrates in packaging conversion, with EU Green Deal compliance timelines forcing material redesign investments.
- Vacuum Packs:Multi-layer barrier films exclude oxygen to extend chilled meal shelf life without preservatives. French and British manufacturers face 18-24 month certification timelines for recyclable alternatives under extended producer responsibility frameworks.
- Ready-to-Serve Trays:CPET and aluminum containers withstand oven and microwave thermal profiles for premium positioned frozen meals. German retailers are demanding post-consumer recycled content minimums that strain current supply chains.
- Plastic Containers:Polypropylene and PET formats serve cost-sensitive chilled and frozen segments with established recycling infrastructure.
- Canned Packaging:Metal cans and retort pouches preserve ambient-stable meals for long-duration storage and institutional applications.
Plastic Containers still dominate unit volumes, though Vacuum Packs are expanding most quickly as freshness positioning intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany generates higher per-capita spending on frozen prepared meals than France, yet French consumers demonstrate stronger preference for chilled formats requiring shorter supply chains and rapid turnover.
Germany
Urban households in Berlin, Munich, and Hamburg drive volume for premium frozen dinners and vacuum-packed chilled offerings through discounter and full-service channels. The F-Gas Regulation accelerates warehouse refrigeration upgrades across Bavaria and North Rhine-Westphalia. The Frankfurt-Rhine-Main corridor hosts centralized distribution hubs where third-party logistics providers consolidate cross-border shipments to Benelux markets.
France
Parisian convenience retailers and meal-kit aggregators expand refrigerated case space for high-pressure processed chilled meals targeting time-scarce professionals. ANSM enforces strict microbiological standards for ready-to-eat products distributed through urban retail formats. The Île-de-France region concentrates manufacturing capacity for modified atmosphere packaging innovations serving premium private-label contracts.
United Kingdom
British food service operators consolidate procurement relationships with prepared meal manufacturers holding HACCP certification and direct delivery capability. EFSA front-of-pack labeling mandates push reformulation toward reduced sodium and cleaner ingredient decks. The Midlands industrial corridor anchors chilled meal production facilities supplying major retail multiples and institutional catering contracts.
Italy
Milan and Rome institutional buyers demand nutritional compliance with national dietary guidelines for school and hospital catering operations. The EU Green Deal packaging rules force redesign investments for recyclable primary packaging across Emilia-Romagna manufacturing clusters. Northern Italian cold chain infrastructure extends distribution reach for fresh-perception prepared meals into Alpine catchments.
Poland
Warsaw modern retail format expansion creates first-mover positioning for chilled prepared meals previously underpenetrated in Eastern European markets. REACH framework compliance timelines strain bio-based packaging material supply chains serving Polish manufacturers. The Łódź manufacturing zone attracts frozen food production investments targeting cost-sensitive segments across Central Europe.
Europe Ready-To-Eat Food Market Competitive Landscape
Top-tier vendors anchor premium frozen and chilled segments, while mid-scale specialists occupy private-label manufacturing niches. The European ready-to-eat food market exhibits tiered consolidation with pan-European distribution networks conferring decisive advantage. Three strategic archetypes dominate: diversified food conglomerates with cross-category scale, chilled meal specialists with retailer-integrated supply relationships, and frozen format innovators with regional recipe adaptation capabilities. Competitive intensity manifests through direct-to-foodservice digital platform development and sustainable packaging certification races.
Within the diversified conglomerate tier, Nestlé S.A. and The Kraft Heinz Company represent archetypes of cross-border brand portfolios leveraging established cold chain infrastructure. Among chilled prepared meal specialists, Greencore Group Plc occupies a position exemplifying direct supply relationships with British and Irish retailers. Dr. Oetker KG anchors the premium frozen pizza and bakery segment through consistent quality positioning and regional recipe adaptation that sustains brand loyalty across German-speaking markets.
| Leading Market Players |
|---|
| Nomad Foods Ltd |
| Nestlé S.A. |
| McCain Foods Limited |
| The Kraft Heinz Company |
| Dr. Oetker KG |
| Premier Foods Group Limited |
| Frosta Aktiengesellschaft |
| Ebro Foods, S.A. |
| Greencore Group Plc |
| Others |
Supply & Pricing Matrix
European wheat futures and rapeseed oil benchmarks cascade through ready-to-eat food manufacturing, compressing margin structures for frozen dinner producers while amplifying pricing power for chilled meal specialists with backward-integrated ingredient sourcing.
Pricing Analysis
Capacity additions in Poland and Romania are reshaping price floors for standard-tier frozen meals. Three-tier pricing structure across premium, standard, and economy levels separates Dr. Oetker-positioned brands from private-label discounter offerings and value-tier Eastern European imports. Price differentiation hinges on clean-label certification status and direct-to-retailer supply relationships. Food service buyers exhibit highest price sensitivity due to consolidated procurement contracts, while urban convenience retail channels absorb premium markups for high-pressure processed chilled formats.
Supply Chain Analysis
Direct-to-foodservice digital channels handle institutional buyer demand growth, bypassing traditional wholesale distributors. Manufacturing concentrates in Germany, France, and the United Kingdom, with emerging capacity in Poland and Romania. Raw material flows draw from Benelux dairy suppliers, Iberian vegetable processors, and Baltic grain exporters. Single-source vulnerability concentrates in modified atmosphere packaging film supply from German and Austrian converters. Distribution runs through third-party cold chain operators controlling frozen and chilled warehousing across Northern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe ready-to-eat food market reads as a late-cycle quality story. Urban household demand is pivoting toward shorter ingredient lists and high-pressure processed freshness claims that command sustained price premiums.
For Market Incumbents: Extend clean-label reformulation pipelines ahead of EFSA disclosure tightening. Acquire chilled meal technology specialists in France and the United Kingdom to consolidate high-pressure processing expertise. Build captive supply relationships with bio-based packaging converters to preempt REACH compliance bottlenecks.
For New Entrants and Emerging Players: Enter via direct-to-foodservice digital platforms serving German and British institutional catering consolidation. Target underpenetrated Polish and Romanian modern retail expansion with vacuum-packed chilled formats. Leverage CSRD transparency verification as a preferential listing wedge with ESG-focused British and Dutch retailers.
For Investors and Strategic Acquirers: Asymmetric upside sits with chilled meal specialists holding retailer-integrated supply relationships and high-pressure processing capabilities. Five-to-ten year viability favors manufacturers with verified sustainable sourcing and F-Gas Regulation-compliant refrigeration infrastructure. Watch EFSA front-of-pack labeling enforcement timelines as a demand inflection signal for premium reformulated products.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Acceleration | EFSA nutritional labeling mandates reward first-mover brands with premium shelf positioning across German and French retail. |
| Bio-Based Packaging Supply Integration | EU Green Deal compliance timelines strain converters; captive supply relationships secure 18-24 month certification windows. |
| Direct-to-Foodservice Platform Launch | Digital procurement portals disintermediate traditional distributors, retaining margin for manufacturers serving British hospitality groups. |
| High-Pressure Processing Capacity Expansion | Extended shelf life without chemical preservatives opens premium private-label contracts with British and Irish retailers. |
| Eastern European Manufacturing Footprint | Polish and Romanian production hubs capture cost-sensitive volume growth across underpenetrated Central European markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged category buyers at British and German retail multiples, procurement directors at French hospitality groups, food technologists at chilled meal manufacturers, and cold chain logistics operators. Secondary validation drew from EFSA guidance documents, EU Green Deal regulatory filings, national food safety agency enforcement records, and customs trade data for prepared meal imports. Bottom-up SKU-level volume estimates triangulated against top-down category expenditure data.
Segment-weighting approaches distributed value and volume across product type, end user, distribution channel, and packaging format dimensions. CAGRs were derived from trend extrapolation adjusted for regulatory enforcement timelines and cold chain infrastructure investment cycles. Forecast inputs incorporated F-Gas Regulation compliance cost curves, EFSA labeling adoption rates, and urban household penetration patterns for digital meal procurement.
Inputs from retail audit databases and food service procurement platforms were available through the study window; gaps in real-time cold chain capacity utilization data introduce uncertainty bands around frozen dinner volume projections. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and bio-based packaging supply scaling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Europe Breakfast Cereals Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
United States Online Grocery Market
Packaged Foods
Dried Soup Market
Packaged Foods
Chewing Gum Market
Packaged Foods
Packaged Zhug Market
Packaged Foods
Global Packed Food Market
Packaged Foods
Australia Food Cans Market
Packaged Foods
Global Breakfast Cereals Market
Packaged Foods
North America Packaged Salad Market
Packaged Foods
Hummus Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
United Kingdom Food Spreads Market
Packaged Foods
Brio Bowls Market
Packaged Foods
Packaged Rice Noodles Market
Packaged Foods
Wet Food Pouch Market