
 Consumer Electronics Chip Market | 2026-2036
Consumer Electronics Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Electronics Chip Market Insights
A chronic shortage of advanced packaging engineers is unwinding capacity expansion timelines across the industry. Taiwan Semiconductor Manufacturing Company leverages its monopoly on 3nm and 2nm fabrication to command premium pricing from fabless designers. Nvidia Corporation anchors its position through AI accelerator dominance in consumer graphics and edge computing. Samsung Electronics competes aggressively in memory and foundry services, sustaining dual-track investments in DRAM and logic scaling.
Consumer electronics chips are integrated circuits fabricated on silicon wafers using photolithography, etching, and deposition processes, typically ranging from 3nm to 28nm nodes depending on performance requirements, designed to process signals, manage power, or execute dedicated computing tasks in mass-market devices. Application-Specific Integrated Circuits concentrate the highest margin pools as smartphone and wearable OEMs commission custom silicon for camera processing and sensor fusion. Power Management ICs are expanding fastest among product types as battery-powered devices proliferate and energy efficiency regulations tighten across jurisdictions. Wi-Fi and 5G technology segments are absorbing disproportionate R&D investment as connectivity bandwidth requirements outpace legacy protocol capabilities.
The US CHIPS Act, EU Chips Act, and China's dual carbon goals are reshaping where fabrication capacity locates and how fabs source renewable power. FDA and FCC frameworks in the United States impose electromagnetic compatibility and safety standards that gate market access for radio-frequency chipsets in wearable and mobile devices. Stakeholders must monitor which regulatory jurisdictions succeed in attracting greenfield fab investment, as subsidy eligibility and local content rules will determine cost structures for the next generation of process nodes.
Market Dynamics
Advanced node monopolization by Taiwanese foundries is compressing margin structures for fabless designers while accelerating geographic diversification mandates from Washington, Brussels, and Beijing.
Growth Catalysts
- US CHIPS Act capital subsidies:$52 billion in fabrication incentives is pulling 3nm and 2nm capacity toward Arizona and Texas, reducing concentration risk in the Taiwan Strait corridor.
- Edge AI inference workloads:On-device neural processing for smartphones and wearables is driving 5nm and below tape-outs at record velocity, expanding addressable silicon content per unit.
- India's PLI scheme for electronics:Production-linked incentives covering semiconductor assembly and testing are attracting packaging investments from Korean and Taiwanese OSATs.
Market Restraints
- EUV lithography equipment scarcity:ASML's annual extreme ultraviolet scanner output caps at roughly fifty units, constraining 3nm ramp schedules regardless of capital availability.
- Fluorinated gas supply concentration:Etching and cleaning chemistries for sub-7nm nodes depend on Japanese and Belgian suppliers exposed to EU F-Gas Regulation phase-down timelines.
- Silicon carbide substrate limitations:Power Management ICs for fast-charging applications face 200mm SiC wafer shortages that outlast 300mm silicon supply corrections.
Strategic Opportunities
- Chiplets and advanced packaging:Heterogeneous integration using 2.5D and 3D stacking is bypassing reticle limits for AI accelerators, opening foundry services to mid-tier fabless designers.
- EU Green Deal power sourcing:Renewable energy mandates for fab operations are creating first-mover advantage for Nordic and Iberian greenfield sites with hydroelectric and wind baseload.
- Automotive-qualified consumer silicon:Infotainment and cockpit convergence is allowing smartphone SoC architectures to penetrate vehicle Tier-1 supply chains with modified validation protocols.
Industry Challenges
- Advanced packaging engineering deficit:CoWoS and InFO talent pools in Hsinchu and San Jose are insufficient for projected 2027-2028 capacity targets, extending customer qualification timelines.
- IP licensing fragmentation:RISC-V ecosystem proliferation is complicating patent clearance for CPU cores in wearables, forcing dual-track ARM and open-standard development.
- Legacy node equipment obsolescence:28nm and 40nm capacity expansion for mature IoT and display driver ICs faces tool refurbishment bottlenecks as original vendors sunset support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Electronics Chip Market |
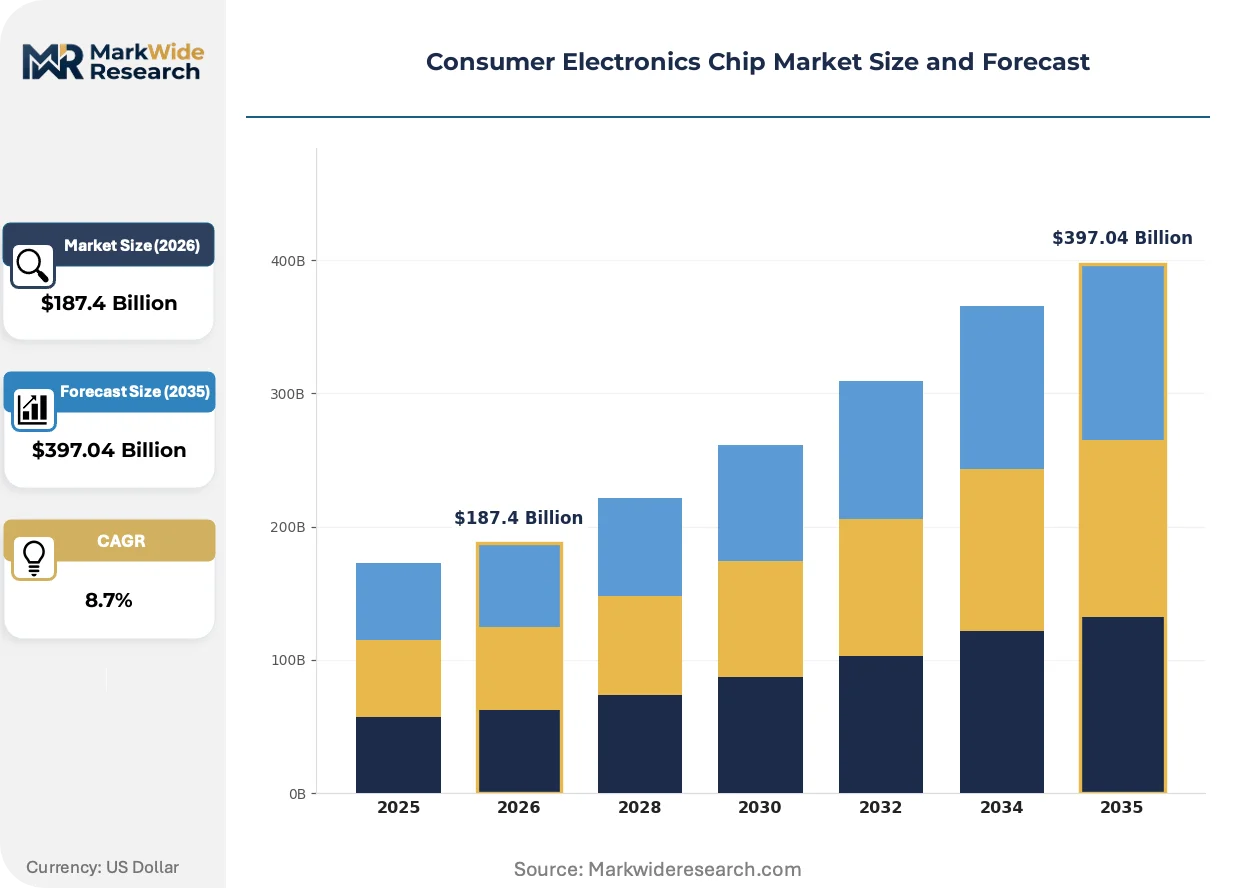
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Digital Signal Processors, Application-Specific Integrated Circuits, Power Management ICs Technology: 5G, Bluetooth, Wi-Fi, NFC End User: Smartphones, Tablets, Smart TVs, Wearable Devices Application: Consumer Electronics, Automotive, Industrial Automation, Healthcare |
| Companies Covered | Nvidia Corporation, Advanced Micro Devices, Intel Corporation, Samsung Electronics, Qualcomm Technologies, SK hynix, Micron Technology, Broadcom, Taiwan Semiconductor Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Electronics Chip Market Trends and Innovations
GAA transistor architectures and backside power delivery are rewriting physical design rules, while regulatory jurisdictions compete to anchor the next wafer fab generation through subsidy design.
Gate-all-around nanosheet transistors are replacing FinFET structures at 3nm and below, delivering superior electrostatic control for leakage reduction. Smartphone SoC designers at Qualcomm and MediaTek are prioritizing GAA tape-outs for 2025 flagship launches. This geometry transition is displacing planar-compatible EDA workflows and compressing competitive timelines for second-source foundry qualification.
The EU AI Act's risk classification framework is imposing documentation and conformity assessment burdens on neural processing units in consumer devices. Chip designers must now embed transparency features and bias audit capabilities into edge AI accelerators. Wearable and smart home segments targeting European distribution are absorbing six-to-nine month certification delays to satisfy notified body requirements.
Direct foundry relationships are supplanting traditional distributor and catalog purchasing for mid-volume IoT and industrial designers. Procurement teams at appliance OEMs are negotiating wafer starts directly with GlobalFoundries and UMC for 22nm mixed-signal products. This channel compression is most visible in Germany and Japan, where automotive heritage suppliers are replicating Tier-1 semiconductor sourcing discipline for white goods and HVAC controllers.
Consumer Electronics Chip Market Segmentation
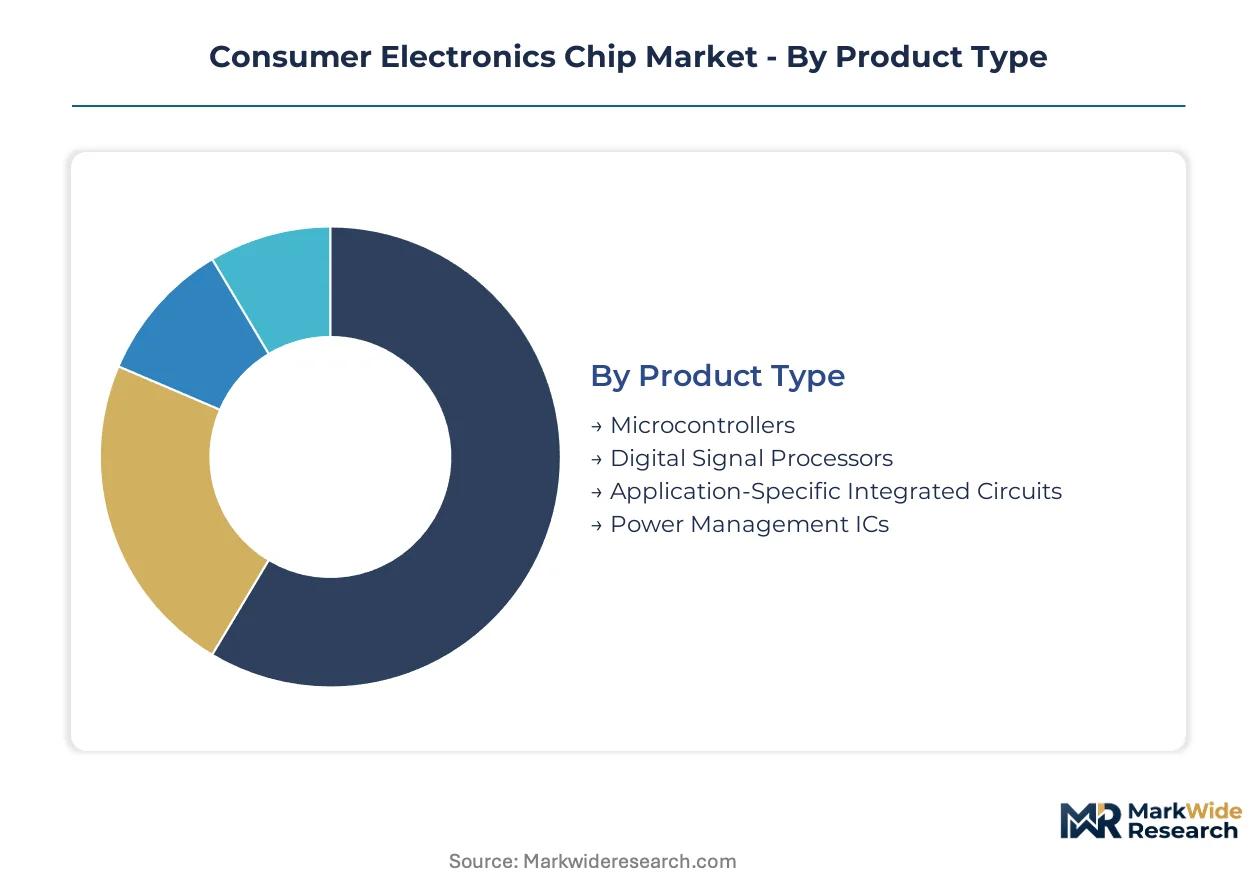
Consumer electronics chip procurement patterns diverge sharply across product architectures, connectivity protocols, device categories, and downstream applications. Understanding these segment boundaries reveals where fabless designers command pricing power versus where foundry capacity constraints dictate availability.
Product Type:
Margin pools concentrate in custom silicon where smartphone OEMs commission exclusive designs, while commodity microcontroller markets compress pricing through Chinese second-source competition.
- Application-Specific Integrated Circuits:Custom-fabricated die integrating camera signal processing, sensor fusion, and display controller functions into single-package solutions. Smartphone OEMs in Taiwan and South Korea commission exclusive tape-outs at 4nm and 5nm nodes, absorbing 18-24 month design cycles to secure performance differentiation against MediaTek reference designs. Qualcomm and Apple internal silicon teams anchor demand for leading-edge ASIC capacity.
- Power Management ICs:Multi-rail voltage regulators, battery fuel gauges, and fast-charging controllers fabricated on 40nm to 130nm BCD processes. Battery-powered device proliferation across Shenzhen and Dongguan manufacturing clusters is absorbing PMIC wafer starts faster than 200mm silicon carbide substrate supply can expand, extending lead times for gallium nitride fast-charging controllers.
- Microcontrollers:Arm Cortex-M and RISC-V cores integrated with flash memory and analog peripherals for IoT edge nodes and appliance controllers.
- Digital Signal Processors:Dedicated arithmetic units for audio processing, noise cancellation, and modem baseband operations in wireless earbuds and smart speakers.
The dominant share belongs to Application-Specific Integrated Circuits, while Power Management ICs is closing the gap fastest.
Technology:
Radio-frequency frontend complexity now exceeds baseband processing cost in flagship smartphone bill-of-materials, shifting R&D allocation toward connectivity integration.
- 5G:Sub-6GHz and mmWave transceiver modules with beamforming antenna arrays and carrier aggregation support. Network infrastructure rollout in India and Brazil is accelerating procurement of 5G-ready modems for mid-tier handsets, though mmWave adoption concentrates in US and Japanese metropolitan markets where Verizon and NTT Docomo have deployed dense small-cell grids.
- Wi-Fi:Wi-Fi 6E and Wi-Fi 7 MAC/PHY implementations operating in 6GHz spectrum with 320MHz channel bonding. Smart home device OEMs in Amsterdam and Seoul are qualifying tri-band solutions for mesh networking products, driven by streaming bandwidth demands and Matter protocol interoperability requirements.
- Bluetooth:Low-energy and LE Audio stacks for wireless earbuds, hearing aids, and location beacons.
- NFC:Contactless payment and device-pairing controllers with secure element integration.
5G commands the largest revenue footprint, though Wi-Fi is expanding most quickly as 6GHz spectrum clears across regulatory domains.
End User:
Silicon content per unit varies by an order of magnitude across device categories, with flagship smartphones absorbing more die area than entire smart TV lineups from second-tier brands.
- Smartphones:Application processors, modem basebands, RF frontends, and power management integrated into tightly constrained thermal envelopes. Annual flagship launches from manufacturers headquartered in Cupertino and Seoul set the cadence for 3nm process node transitions, with each generation demanding 15-20% die shrinks to maintain battery life amid display and camera power growth.
- Wearable Devices:Ultra-low-power SoCs with always-on sensor hubs and compact wireless connectivity. Health-tracking feature expansion in devices shipping from Finnish and California design centers is driving integration of photoplethysmography and bioimpedance sensing circuits previously requiring discrete analog frontends.
- Tablets:Compute-optimized processors derived from smartphone architectures with expanded thermal budgets.
- Smart TVs:Media processors with AI upscaling engines and HDMI 2.1 display controllers.
Smartphones retain the dominant consumption share, while Wearable Devices is gaining share fastest through hearable and health-monitoring category expansion.
Application:
Automotive qualification requirements are opening a secondary revenue stream for consumer-grade silicon architectures with modified validation protocols.
- Consumer Electronics:Mass-market devices with 3-5 year operational lifecycles and standard commercial temperature ratings. White goods manufacturers in Germany and Japan are migrating appliance controllers to 22nm FD-SOI nodes for motor control and touch interface integration, replacing legacy 130nm MCUs.
- Automotive:Infotainment and cockpit electronics repurposing smartphone SoC architectures with AEC-Q100 temperature and reliability screening. Tier-1 suppliers in Stuttgart and Toyota City are qualifying Snapdragon and Exynos derivatives for digital cluster and head-up display applications, bypassing discrete automotive silicon development timelines.
- Industrial Automation:Edge AI accelerators and deterministic networking controllers for factory floor deployment.
- Healthcare:Continuous glucose monitors and pulse oximeters with FDA and CE-MDR regulatory submissions.
Consumer Electronics maintains the dominant application share, while Automotive is closing the gap fastest through cockpit convergence trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Taiwanese foundries commanding premiums for 3nm capacity, while Chinese packaging houses compete on cost for mature node assembly. This asymmetry shapes procurement geography across the industry.
United States
CHIPS Act subsidies are pulling advanced fabrication to Arizona and Texas as Intel and TSMC break ground on greenfield sites. The Department of Commerce administers $52 billion in fabrication incentives with local content requirements. Austin and Phoenix clusters are absorbing EUV scanner allocations as domestic capacity ramps toward 2027-2028 production targets.
China
Dual carbon goals and MIIT localization mandates are accelerating domestic 28nm capacity expansion despite equipment access restrictions. SAMR enforces antitrust scrutiny on semiconductor joint ventures and IP licensing. The Yangtze River Delta around Shanghai anchors mature node foundry construction as Yangtze Memory Technologies scales 3D NAND output.
South Korea
Samsung Electronics and SK hynix are defending memory dominance while pushing logic foundry scale against Taiwanese competition. METI coordinates national semiconductor strategy through K-Chips Act implementation. The Seoul Capital Area and Pyeongtaek corridor concentrate DRAM and NAND flash fabrication with government-backed R&D consortia.
Japan
Rapidus Corporation's 2nm consortium in Hokkaido represents Tokyo's bid to reclaim leading-edge logic production after decades of specialization. METI subsidizes EUV research and advanced packaging equipment development. The Kyushu cluster around Kumamoto is attracting TSMC joint ventures as JASM scales 12-inch capacity for automotive and image sensor demand.
Germany
EU Chips Act funding and Intel's Magdeburg commitment are positioning Saxony-Anhalt as Europe's advanced node anchor. The European Commission approves state aid packages contingent on renewable power sourcing. Dresden's Silicon Saxony cluster sustains automotive-qualified foundry output as Bosch and GlobalFoundries expand 22nm FD-SOI capacity for industrial controllers.
Consumer Electronics Chip Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where advanced node monopolists extract rents while mature node specialists compete on scale. The market consolidates around fabrication capacity ownership rather than design innovation alone. Three archetypes dominate: captive integrated device manufacturers, pure-play foundries with process leadership, and fabless designers with architectural control. Competitive moves center on geographic diversification of fabrication assets and heterogeneous integration capabilities through advanced packaging partnerships.
Among pure-play foundries, Taiwan Semiconductor Manufacturing Company anchors the leading-edge tier through 3nm and 2nm process dominance. Samsung Electronics occupies a dual position spanning memory, foundry services, and captive smartphone silicon. Nvidia Corporation exemplifies the fabless archetype commanding AI accelerator architectures without fabrication ownership. These three represent the structural fault lines of competitive positioning: process technology, vertical integration depth, and architectural control over high-growth workloads.
| Leading Market Players |
|---|
| Nvidia Corporation |
| Advanced Micro Devices |
| Intel Corporation |
| Samsung Electronics |
| Qualcomm Technologies |
| SK hynix |
| Micron Technology |
| Broadcom |
| Taiwan Semiconductor Manufacturing Company |
| Others |
Pricing and Supply Chain Analysis
EUV scanner throughput constraints at ASML's Veldhoven facilities concentrate 3nm and 2nm pricing power in Taiwanese foundries while compressing margin structures for fabless designers across Austin, San Jose, and Shenzhen. This scale asymmetry elevates wafer-start premiums for leading-edge nodes while commoditizing 28nm and 40nm capacity through Chinese second-source competition.
Pricing Analysis
Configured-to-order pricing for custom ASIC tape-outs commands 40-60% premiums over standard catalog microcontroller pricing, with differentiation driven by node complexity and AEC-Q100 automotive certification tiers. Pricing stratifies across premium, standard, and economy tiers based on GAA transistor implementation, foundry node access, and volume commitment scale. Cost compression in mature-node PMICs is intensifying because 200mm silicon carbide substrate shortages extend lead times for gallium nitride fast-charging controllers. Mid-tier smartphone OEMs in India and Brazil exhibit highest price sensitivity, while Cupertino and Seoul flagship designers demonstrate lowest sensitivity to wafer-start premiums.
Supply Chain Analysis
Strait of Malacca transit lanes underpin 90% of advanced packaging equipment shipments from Dutch and Japanese vendors to Hsinchu and Pyeongtaek assembly clusters. Geographic supply concentrates in Taiwan, South Korea, and the United States for leading-edge logic, while China, Malaysia, and Vietnam anchor mature-node assembly and test. Raw material dependencies include fluorinated etching gases from Belgian and Japanese suppliers, 300mm silicon wafers from Shin-Etsu and SUMCO, and EUV photoresists from JSR and Tokyo Ohka Kogyo. Single-source vulnerability around ASML's annual fifty-unit EUV scanner output creates qualification timeline extensions regardless of capital availability. Distribution runs through direct foundry relationships for high-volume smartphone SoC designers, with distributor channels persisting for mid-volume IoT and appliance controller procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among smartphone OEMs into five dominant global players has shifted procurement leverage toward device manufacturers, forcing foundries to absorb qualification timeline risks and customization engineering costs previously borne by buyers.
For Market Incumbents: Shield leading-edge node premiums through exclusive CoWoS capacity reservations at Hsinchu and Taichung facilities, while accelerating geographic diversification into Arizona and Dresden to preempt CHIPS Act and EU Chips Act local content penalties. Threat of RISC-V ecosystem proliferation in wearables demands dual-track ARM and open-standard IP development to maintain architectural control. Vertical integration into advanced packaging engineering pools represents the critical lever for defending margin structures against Samsung's foundry-memory integration. For New Entrants and Emerging Players: Anchor in India's PLI scheme for semiconductor assembly and testing, where Korean and Taiwanese OSATs are expanding capacity faster than local engineering talent can saturate wage premiums. The most penetrable segment lies in 22nm FD-SOI mixed-signal controllers for white goods and HVAC systems, where automotive heritage suppliers in Germany and Japan are replicating Tier-1 sourcing discipline. Go-to-market execution should emphasize direct foundry relationships bypassing traditional distribution markups. For Investors and Strategic Acquirers: Fabless designers with automotive-qualified consumer silicon architectures and established AEC-Q100 validation protocols present the most defensible acquisition profile across the 5-10 year horizon. Tier-1 cockpit convergence trends allow smartphone SoC derivatives to penetrate vehicle infotainment supply chains with modified reliability screening, opening secondary revenue streams beyond consumer replacement cycles. Signal to watch: FDA and FCC electromagnetic compatibility ruling changes that would accelerate or delay wearable and hearable device launches in North American distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Node Capacity Expansion | TSMC's Arizona and Intel's Ohio fabs reduce Taiwan Strait concentration risk for 3nm production. |
| Chiplet and Heterogeneous Integration Partnership | 2.5D and 3D stacking bypasses reticle limits, opening foundry services to mid-tier AI accelerator designers. |
| Automotive Qualification Protocol Adaptation | Snapdragon and Exynos derivatives penetrate Stuttgart and Toyota City cockpit supply chains through AEC-Q100 screening. |
| Renewable Power Sourcing Commitment | EU Green Deal mandates create first-mover advantage for Nordic and Iberian greenfield sites with hydroelectric baseload. |
| Advanced Packaging Engineering Talent Acquisition | CoWoS and InFO specialist shortages in Hsinchu and San Jose extend customer qualification timelines regardless of equipment investment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fabless design executives, foundry capacity planners, OSAT procurement managers, and smartphone OEM silicon sourcing leads. Secondary validation drew from SEC 10-K filings, SEMI equipment shipment databases, customs wafer import records, and EUV lithography utilization disclosures. Bottom-up segment sizing triangulated against top-down semiconductor consumption models across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs through node-specific segmentation, device category silicon content, and geographic production cluster dynamics. CAGRs were derived from wafer-start forecasts, die-size trends, and blended ASP trajectories by process node. Industry-specific inputs included EUV scanner delivery schedules, fluorinated gas regulatory phase-down timelines, and 200mm silicon carbide substrate capacity expansion curves.
Underlying assumptions cover sustained smartphone replacement cycles, wearable health-monitoring feature adoption, and automotive cockpit convergence penetration, with deviation risk concentrated in EU AI Act certification delays, Taiwan Strait logistics disruptions, and ASML equipment output constraints. Practitioners should keep alternative scenarios live as CHIPS Act subsidy disbursement timelines and EU renewable power sourcing requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
Car Chip Market
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Netherlands Data Center Processor Market
Chipset and Processors
Asia Pacific Data Center Processor Market
Chipset and Processors
Automotive Image Signal Processor Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
Airbag Chip Market
Chipset and Processors
Data Processing Neuromorphic Chip Market
Chipset and Processors
8-Bit MCU Market
Chipset and Processors
Global ARM Microcontrollers Market