
 Cellular Internet of Things (IoT) Devices Market | 2026-2036
Cellular Internet of Things (IoT) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular Internet of Things (IoT) Devices Market Insights
South Korea's semiconductor foundry expansion is narrowing the supply gap for cellular IoT modems. Quectel Wireless Solutions leverages its Shanghai manufacturing base to dominate NB-IoT module shipments. Thales Group sustains European defense and aerospace certification standards across its IoT security portfolio. Qualcomm Technologies anchors the premium 5G IoT chipset tier through integrated baseband-to-application processor designs.
Cellular Internet of Things devices comprise embedded radio modules, antennas, and power management circuits that transmit machine-generated data over licensed mobile operator spectrum, typically operating in sub-6 GHz bands with power budgets under one watt for decade-long battery deployments. These systems enable continuous telemetry from distributed assets without proprietary gateway infrastructure. The connectivity technology dimension shows NB-IoT capturing the utility metering segment due to deep indoor penetration and minimal power draw, while 5G RedCap is emerging as the fastest-growing tier for industrial video surveillance and autonomous mobile robots requiring sub-ten-millisecond latency. Within use cases, fleet management commands the highest average revenue per unit through combined hardware, platform, and cellular data service bundles.
The FCC in the United States enforces Part 15 and Part 27 equipment authorization rules that dictate RF emissions limits and modular approval pathways for cellular IoT devices entering the North American market. ETSI and the CE marking framework in Europe mandate cybersecurity resilience ratings under the Radio Equipment Directive, directly influencing product development roadmaps for module vendors seeking cross-border certification. China's MIIT governs network access licenses and spectrum allocation for CAT-M1 and NB-IoT deployments, creating a distinct regulatory perimeter for domestic versus export-bound device configurations. Stakeholders must monitor spectrum refarming decisions by national regulators as 2G and 3G sunsets accelerate migration timelines for legacy installed bases.
Market Dynamics
The Cellular Internet of Things (IoT) Devices Market faces a structural compression between legacy 2G/3G network sunsets and the capital intensity of 5G RedCap migration, forcing module vendors to redesign power architectures while maintaining backward compatibility for installed utility meters and agricultural sensors.
Growth Catalysts
- EU AI Act and RED cybersecurity mandates:Equipment manufacturers in Germany's industrial corridor now require embedded cellular connectivity with certified security stacks, pulling demand for hardened IoT modules into automotive predictive maintenance contracts.
- Smart agriculture sensor deployment:Brazilian farmers are scaling soil moisture and livestock tracking networks across Mato Grosso and Paraná, creating sustained module volume for NB-IoT suppliers with tropicalized hardware specifications.
- 5G RedCap latency thresholds:Autonomous mobile robots and industrial video surveillance systems are adopting sub-ten-millisecond connectivity tiers, expanding addressable use cases beyond legacy LPWAN capabilities.
Market Restraints
- Semiconductor foundry concentration in South Korea and Taiwan:Cellular IoT modem supply remains vulnerable to single-geo disruptions, with limited alternative qualified sources for sub-6 GHz RF front-end integration.
- 2G/3G spectrum refarming timelines:Accelerated network sunsets in North America and Europe strand legacy installed bases, forcing premature hardware replacement cycles on cost-constrained utility operators.
- Proprietary gateway substitution:Private LoRa and Wi-SUN networks in campus and industrial settings capture low-data-rate applications that might otherwise flow to licensed cellular spectrum.
Strategic Opportunities
- Underpenetrated precision agriculture in Southeast Asia:Thailand and Vietnam present white-space demand for livestock tracking and irrigation automation where cellular coverage now exceeds sensor deployment density.
- Convergence of AI inference and 5G RedCap:Edge-integrated cellular modules that combine baseband processors with neural accelerators are opening predictive maintenance contracts in Japanese automotive supply chains.
- FCC Part 27 modular approval streamlining:Simplified equipment authorization pathways for integrated radio modules are compressing time-to-market for North American device entrants, particularly in fleet management hardware.
Industry Challenges
- RF engineering talent scarcity:The specialized skill set for sub-6 GHz antenna design and power-optimized baseband integration concentrates in Shanghai and Seoul, constraining module vendor expansion timelines.
- Multi-jurisdiction certification complexity:Simultaneous FCC, CE marking, and MIIT network access approvals extend product development cycles by twelve to eighteen months for globally distributed device portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular Internet of Things (IoT) Devices Market |
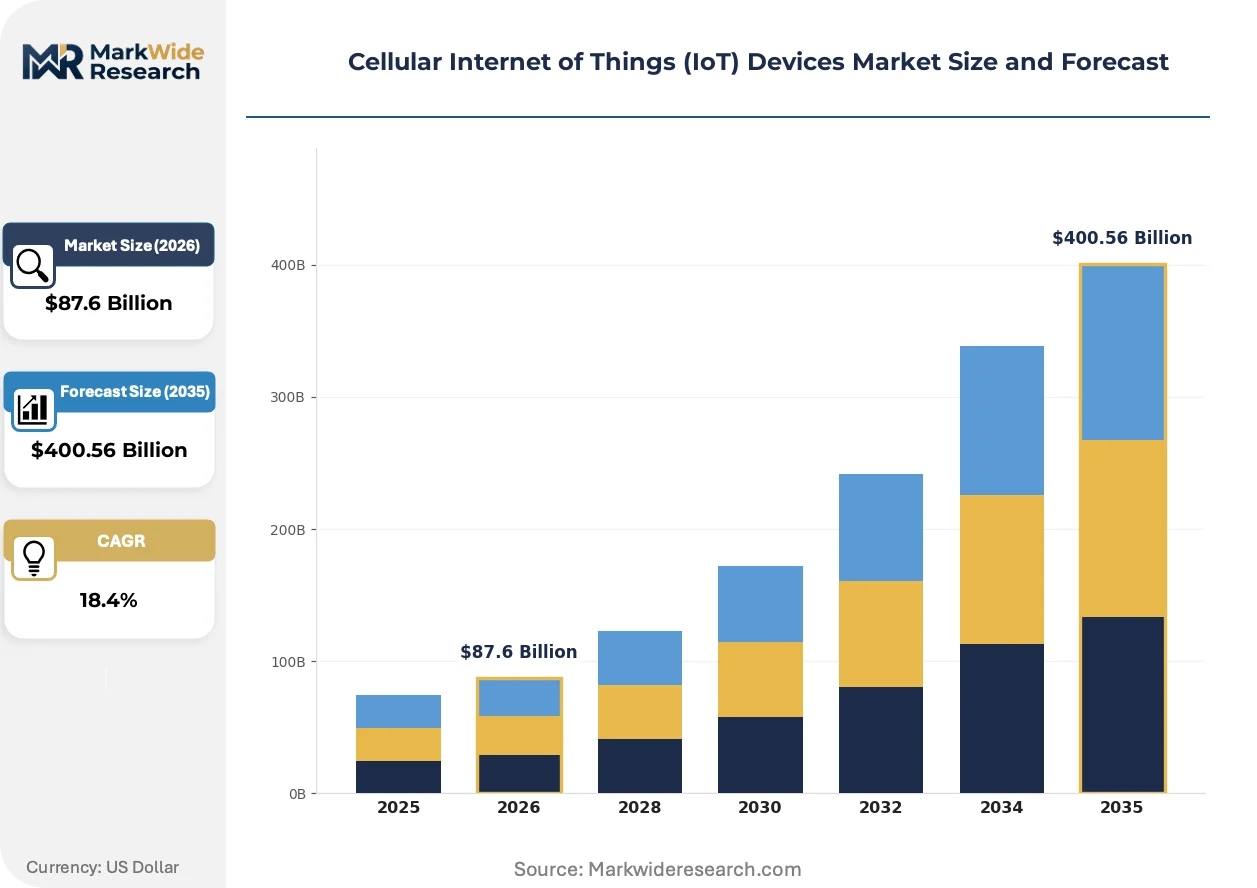
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $400.56 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smart Meters, Wearable Devices, Connected Cars, Industrial Sensors Connectivity Technology: LTE, 5G, NB-IoT, CAT-M1 Use Case: Asset Tracking, Fleet Management, Smart Agriculture, Remote Monitoring End User: Manufacturing, Healthcare, Transportation, Energy |
| Companies Covered | Quectel Wireless Solutions, Thales Group, Fibocom Wireless, Telit Communications, u-blox Holding, Sierra Wireless, Qualcomm Technologies, Huawei Technologies, Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular Internet of Things (IoT) Devices Market Trends and Innovations
Network function virtualization is collapsing the boundary between connectivity hardware and cloud-managed service delivery, enabling cellular IoT deployments to scale without proportional increases in field engineering overhead or proprietary gateway infrastructure.
Embedded SIM (eSIM) and integrated eUICC architectures are virtualizing subscriber identity management for cellular IoT devices, allowing automotive OEMs and industrial machinery manufacturers to provision connectivity post-deployment rather than at manufacturing. Fleet operators in Germany and the United States are adopting remote SIM provisioning at scale, compressing logistics costs for cross-border vehicle deployments. This technology is virtualizing the traditional distributor-carrier relationship, enabling direct device-to-cloud subscription models that bypass regional mobile network operator intermediaries.
ETSI cybersecurity resilience ratings under the Radio Equipment Directive are mandating formalized secure development lifecycles for IoT modules entering European markets, with EN 303 645 baseline requirements now table stakes for CE marking. Module vendors are rearchitecting firmware update mechanisms and secure boot chains to satisfy notified body assessments, extending certification timelines but creating competitive moats for compliant suppliers. Industrial automation and smart metering segments in France, Germany, and the Netherlands are prioritizing certified hardware, shifting procurement criteria from unit cost toward assurance documentation depth.
Buyers in the fleet management vertical are unbundling hardware acquisition from cellular data service contracts, demanding module-only procurement with bring-your-own-connectivity flexibility. This pattern disrupts the traditional bundled average-revenue-per-unit model that combined device, platform, and multi-year data plans. North American logistics operators and European trucking consortiums are driving this disintermediation, compressing margins for integrated solution providers while expanding addressable market for pure-play hardware specialists.
Cellular Internet of Things (IoT) Devices Market Segmentation
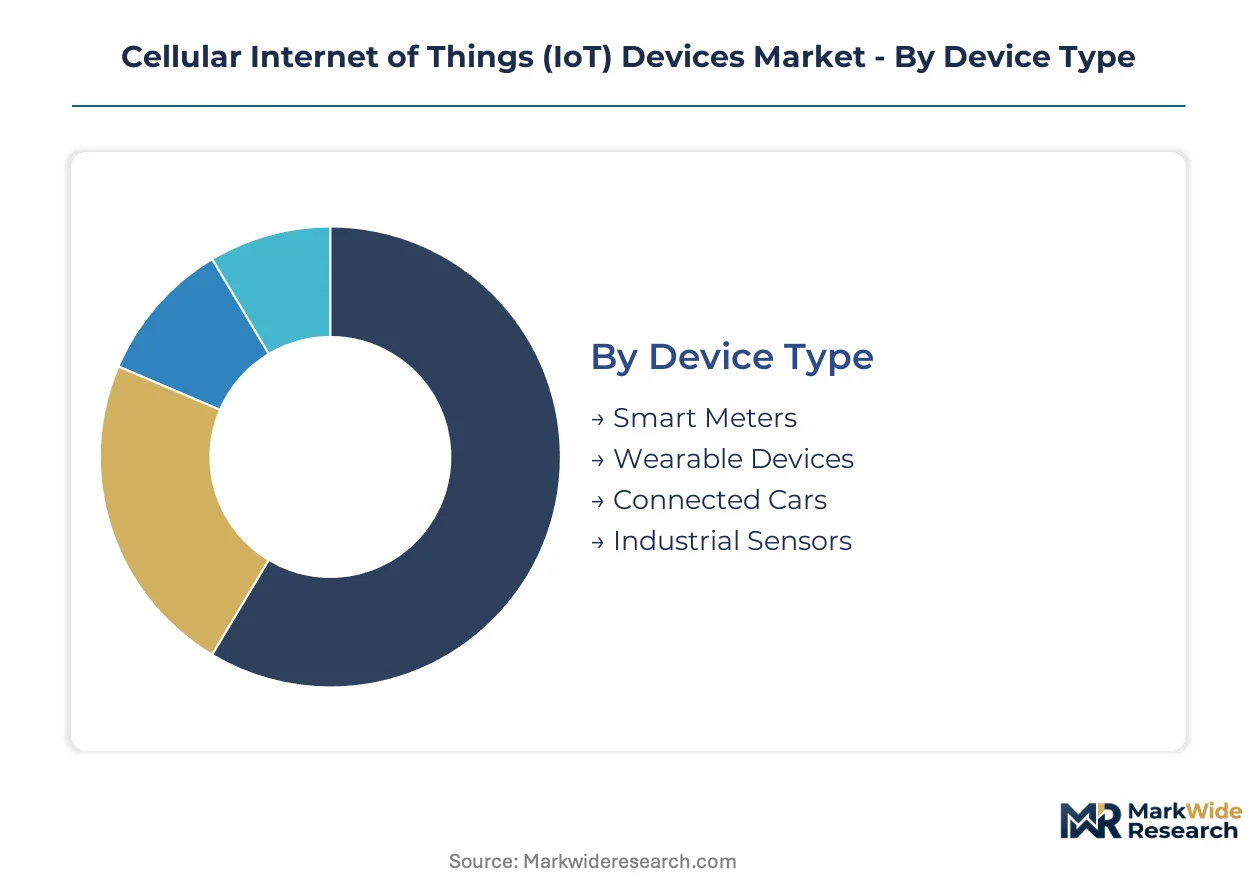
Cellular IoT device procurement varies sharply across deployment contexts, with power budgets, latency tolerances, and certification requirements fragmenting demand into distinct technical tiers. Understanding these segment boundaries clarifies where module vendors must optimize for cost versus performance versus regulatory compliance.
Device Type:
The use-case spectrum spans passive metering endpoints through mobile automotive platforms, each imposing radically different mechanical, thermal, and power constraints on radio module design.
- Smart Meters:Fixed-installation electricity, gas, and water metering endpoints operate on decade-long battery budgets with deep indoor penetration requirements. Brazilian utilities in Mato Grosso are deploying tropicalized NB-IoT variants for irrigation district monitoring, pulling volume from suppliers with IP68 enclosures and extended temperature ratings.
- Connected Cars:Automotive telematics control units integrate cellular modems with GNSS and CAN bus interfaces for over-the-air updates and emergency calling. German automotive OEMs in Baden-Württemberg mandate embedded connectivity with ETSI cybersecurity certification under the Radio Equipment Directive, favoring suppliers with TS 16949 quality systems.
- Wearable Devices:Health and fitness bands require sub-gram radio modules with aggressive power gating for multi-day battery life.
- Industrial Sensors:Vibration, temperature, and pressure transmitters in factory automation use hardened enclosures with isolated power supplies.
Established volume favors Smart Meters; emerging adoption favors Connected Cars.
Connectivity Technology:
Cost tier stratification separates premium low-latency tiers from minimal-cost wide-area alternatives.
- NB-IoT:Narrowband IoT operates in 200 kHz guard bands with peak rates below 250 kbps and power-saving mode intervals up to 2.56 hours. German smart metering deployments and Brazilian agricultural sensor networks dominate current volume, with module ASPs compressed below five dollars at scale.
- 5G:Fifth-generation New Radio including RedCap variants delivers sub-ten-millisecond latency for industrial video and autonomous robotics. Japanese automotive supply chains are piloting edge-integrated 5G modules combining baseband with neural accelerators for predictive maintenance, climbing the fastest among all technology tiers.
- LTE:Legacy Cat-1 and Cat-4 modems retain share in fleet management where bandwidth requirements exceed LPWAN limits.
- CAT-M1:LTE-M provides mobility support and voice capability absent from NB-IoT, capturing wearable and voice-enabled alarm applications.
Volume concentrates in NB-IoT; margin expansion concentrates in 5G.
Use Case:
Application maturity separates proven utility deployments from emerging industrial and agricultural frontiers.
- Fleet Management:Combined hardware-platform-data service bundles command the highest average revenue per unit in cellular IoT. North American logistics operators and European trucking consortiums are unbundling these packages, demanding module-only procurement with bring-your-own-connectivity flexibility.
- Smart Agriculture:Soil moisture, livestock tracking, and irrigation automation sensors are scaling across Brazil's Mato Grosso and Paraná regions. Southeast Asian markets in Thailand and Vietnam present white-space opportunity where cellular coverage now exceeds sensor deployment density.
- Asset Tracking:Container and equipment monitoring relies on battery-optimized modules with accelerometer-triggered wake cycles.
- Remote Monitoring:Industrial equipment telemetry spans pumps, generators, and HVAC systems with varying latency tolerances.
Revenue per unit peaks in Fleet Management; deployment velocity peaks in Smart Agriculture.
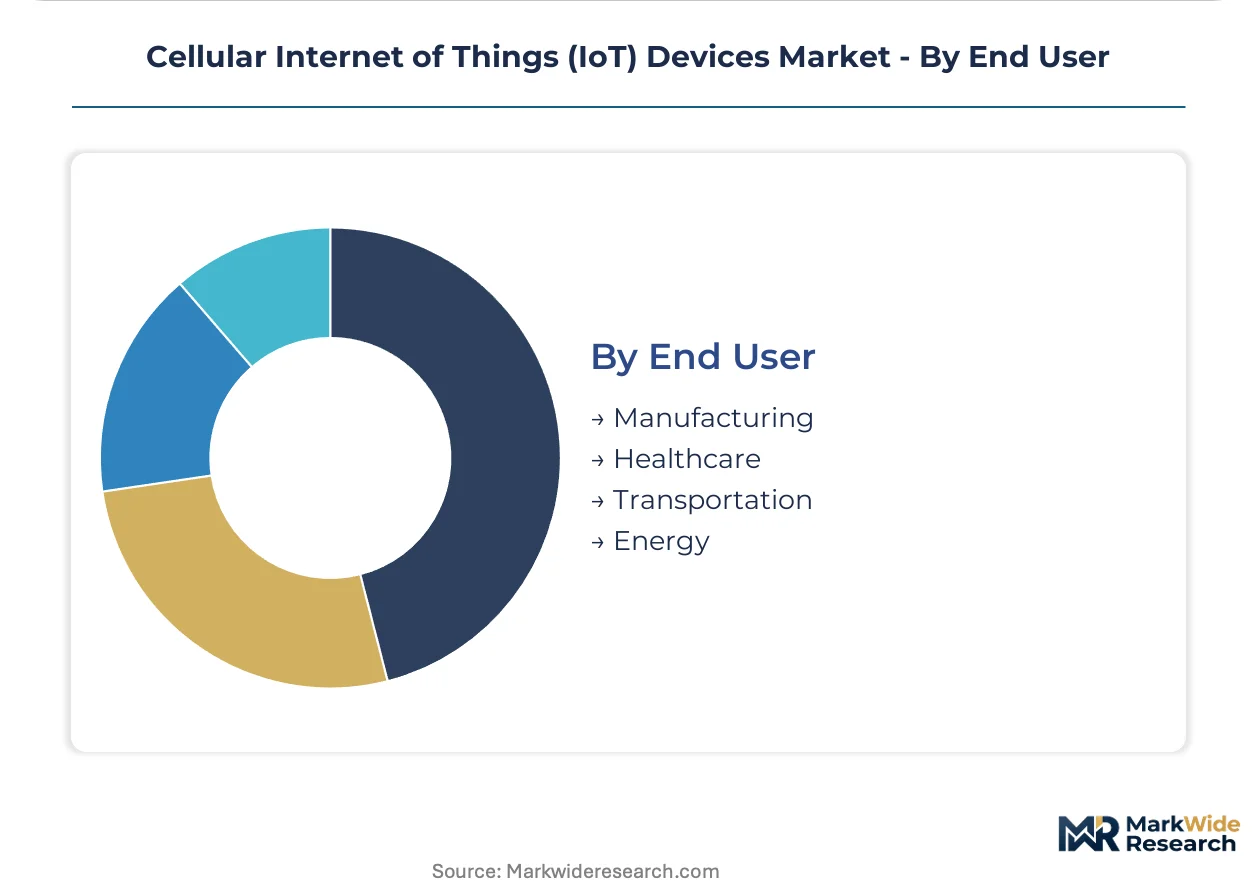
End User:
Customer type dictates certification burden, procurement scale, and integration complexity.
- Manufacturing:Automotive and machinery OEMs in Germany's industrial corridor mandate embedded cellular for predictive maintenance, requiring EN 303 645 cybersecurity compliance and multi-year supply agreements.
- Transportation:Fleet operators prioritize modular approval streamlining under FCC Part 27 for rapid North American market entry, compressing hardware certification timelines.
- Healthcare:Remote patient monitoring devices face FDA and HIPAA constraints in the United States, extending development cycles.
- Energy:Utility operators confront accelerated 2G/3G sunset timelines, forcing premature replacement of legacy metering infrastructure.
Procurement sophistication concentrates in Manufacturing; regulatory complexity concentrates in Healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cellular IoT module fabrication concentrates in East Asian foundry clusters, with South Korean and Taiwanese semiconductor output supplying RF front-end components for global device assembly. This geographic concentration shapes certification patterns and procurement lead times across end markets.
United States
Fleet management operators and industrial automation buyers drive module demand through FCC Part 27 modular approval pathways. The FCC enforces RF emissions limits and equipment authorization rules that compress hardware certification timelines for North American entrants. California-based logistics consortiums are unbundling hardware from data service contracts, shifting procurement toward module-only sourcing with bring-your-own-connectivity flexibility.
Germany
Automotive OEMs and machinery manufacturers in Baden-Württemberg mandate embedded cellular connectivity for predictive maintenance platforms. ETSI cybersecurity resilience ratings under the Radio Equipment Directive now govern CE marking requirements, extending certification timelines but creating compliance moats for hardened module suppliers. The industrial corridor spanning Stuttgart to Mannheim anchors European demand for 5G RedCap-enabled industrial sensors.
China
MIIT network access licenses and spectrum allocation rules create a distinct regulatory perimeter for domestic versus export-bound device configurations. Shanghai-based module vendors dominate NB-IoT shipment volumes through integrated manufacturing and RF engineering capabilities. The Yangtze River Delta cluster supplies tropicalized hardware specifications for Brazilian agricultural sensor deployments.
Brazil
Smart agriculture sensor networks are scaling across Mato Grosso and Paraná as farmers adopt soil moisture and livestock tracking systems. ANVISA and national telecommunications regulator frameworks govern device certification for remote patient monitoring and industrial applications. São Paulo-based system integrators are bridging module supply from Asian manufacturers into Latin American utility metering projects.
Japan
Automotive supply chains are piloting edge-integrated 5G modules that combine baseband processors with neural accelerators for predictive maintenance. METI industrial policy and spectrum allocation decisions shape migration timelines from legacy LTE-M toward RedCap deployments. The Nagoya-Tokyo manufacturing belt represents the fastest-growing addressable market for low-latency industrial connectivity tiers.
Cellular Internet of Things (IoT) Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in module and chipset supply. The vendor base stratifies across three tiers: integrated solution providers bundling hardware, platform, and connectivity; pure-play module specialists focused on RF optimization and certification breadth; and semiconductor foundries supplying baseband silicon and RF front-end components. Competitive dynamics center on geographic certification coverage expansion and firmware security architecture differentiation as ETSI and FCC mandates tighten.
Among module specialists, Quectel Wireless Solutions and Fibocom Wireless exemplify the scale-driven tier serving high-volume utility metering and agricultural sensor deployments. Thales Group occupies a position within the security-hardened segment, with its European defense and aerospace certification heritage translating into IoT portfolio assurance documentation. These three anchors illustrate how competitive positioning fragments across cost-optimized volume supply versus compliance-intensive premium tiers.
| Leading Market Players |
|---|
| Quectel Wireless Solutions |
| Thales Group |
| Fibocom Wireless |
| Telit Communications |
| u-blox Holding |
| Sierra Wireless |
| Qualcomm Technologies |
| Huawei Technologies |
| Ericsson |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in South Korean semiconductor foundries is compressing modem chipset pricing while simultaneously accelerating supplier consolidation toward integrated module vendors with captive RF engineering capabilities.
Pricing Analysis
ETSI cybersecurity resilience ratings under the Radio Equipment Directive dictate the pricing tier structure across European cellular IoT module procurement. Three-tier pricing separates EN 303 645-certified premium modules from standard CE-marked units and uncertified economy alternatives. Cost compression in the NB-IoT tier is intensifying because Brazilian agricultural sensor deployments are driving volume scale above five-dollar module ASPs. Fleet management operators exhibit the lowest price sensitivity due to unbundling hardware from data service contracts, while utility metering buyers in emerging markets remain highly price-sensitive.
Supply Chain Analysis
RF front-end components draw from South Korean and Taiwanese semiconductor foundries, with baseband silicon sourcing from USA-based fabless designers. Critical inputs include sub-6 GHz power amplifiers, ceramic antenna substrates, and low-power MCU cores. Single-source vulnerability concentrates in advanced node RF integration below 22 nanometers. Distribution runs through Shanghai-based module assemblers into São Paulo and Stuttgart system integrator hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward automotive OEMs and fleet operators as procurement consolidation across Germany's industrial corridor enables volume-scale negotiation leverage.
For Market Incumbents: Pre-empt margin erosion in the NB-IoT tier by securing multi-year supply agreements with South Korean foundries before capacity reallocation to AI accelerators. Invest in EN 303 645 certification depth to create compliance moats against emerging Chinese module vendors. Threat substitution from private LoRa networks in campus settings demands hardened cellular value propositions. For New Entrants and Emerging Players: Build out precision agriculture sensor module capabilities for Thailand and Vietnam where cellular coverage exceeds deployment density. Target livestock tracking and irrigation automation as the most penetrable white-space segments. Pursue direct OEM relationships with Brazilian system integrators to bypass established distributor-carrier intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among module vendors with integrated eSIM provisioning platforms and multi-jurisdiction certification breadth. Long-term viability favors suppliers with captive RF engineering in Shanghai or Seoul and established MIIT network access licenses. Watch for FCC Part 27 modular approval streamlining as an inflection signal for North American market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| 5G RedCap Module Development | Japanese automotive supply chains demand sub-ten-millisecond latency for predictive maintenance applications. |
| ETSI Cybersecurity Certification Investment | CE marking under EN 303 645 creates procurement preference in German industrial automation segments. |
| eSIM Platform Integration | Fleet operators in California and Baden-Württemberg compress logistics costs through remote provisioning. |
| Backward Integration into RF Front-End | Shanghai-based vendors reduce dependency on South Korean foundry concentration for sub-6 GHz components. |
| Tropicalized Hardware Specification Expansion | Brazilian agricultural sensor deployments in Mato Grosso require IP68 enclosures and extended temperature ratings. |
Research Methodology
A standing panel of cellular module procurement managers, RF engineering directors, automotive OEM platform engineers, and telecommunications regulatory affairs specialists provided ongoing calibration throughout the study period. Primary interview data combined with secondary validation from FCC equipment authorization databases, ETSI technical specification releases, MIIT network access license filings, and semiconductor trade flow records. Bottom-up shipment volume estimates triangulated against top-down operator connection forecasts.
Scenario-bracketing anchored the analytical framework across the projection horizon, with sensitivity testing for 2G/3G sunset acceleration and 5G RedCap adoption curves. Segmentation dimensions modeled include connectivity technology tier, device type mechanical constraints, end-use certification requirements, and regional regulatory cluster. CAGRs derived from installed base migration timelines and replacement cycle compression in legacy utility metering.
Practitioners should monitor spectrum refarming announcements and cybersecurity directive enforcement intensity for early signals of forecast revision. Cross-checking against operator-reported IoT connection growth and module vendor shipment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
IoT Device Management Platform Market
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
Global Agile IoT Market
Internet of Things (IoT)
IoT in Energy Market
Internet of Things (IoT)
Global IoT Routers Market
Internet of Things (IoT)
Airline IoT Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
Enterprise IoT Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market
Internet of Things (IoT)
Global Internet of Things (IoT) Software Market
Internet of Things (IoT)
Indonesia IoT Market
Internet of Things (IoT)
Global IoT Battery Market
Internet of Things (IoT)
Private Narrowband IoT Market
Internet of Things (IoT)
IoT in Automotive Market