
 Grid Operations Management Software Market | 2026-2036
Grid Operations Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Grid Operations Management Software Market Outlook
Legacy on-premise infrastructure is shifting toward containerized cloud architectures as grid operators seek elastic compute for real-time telemetry processing. Siemens leverages deep domain expertise in transmission control systems to anchor large-scale European deployments. Schneider Electric competes through integrated hardware-software bundles that extend its building-automation footprint into utility operations. GE Vernova specializes in digital twin analytics for asset performance management, differentiating its offering from pure-play software vendors.
Grid Operations Management Software encompasses applications that monitor, control, and optimize electricity generation, transmission, and distribution networks through real-time data acquisition, network topology processing, and dispatch automation with sub-second response thresholds. These systems integrate SCADA feeds, advanced distribution management protocols, and predictive analytics to maintain voltage stability, minimize outage duration, and balance intermittent renewable inflows against base-load supply. Cloud-based Solutions represent the fastest-expanding technology segment as hyperscale infrastructure slashes capital intensity for municipal utilities and cooperatives. Demand Response applications within the Application dimension command premium pricing due to their direct linkage to capacity-market revenues and peak-shaving contracts. The End User base tilts toward Utilities, though Independent System Operators are gaining procurement share as regional transmission organizations consolidate balancing authority functions.
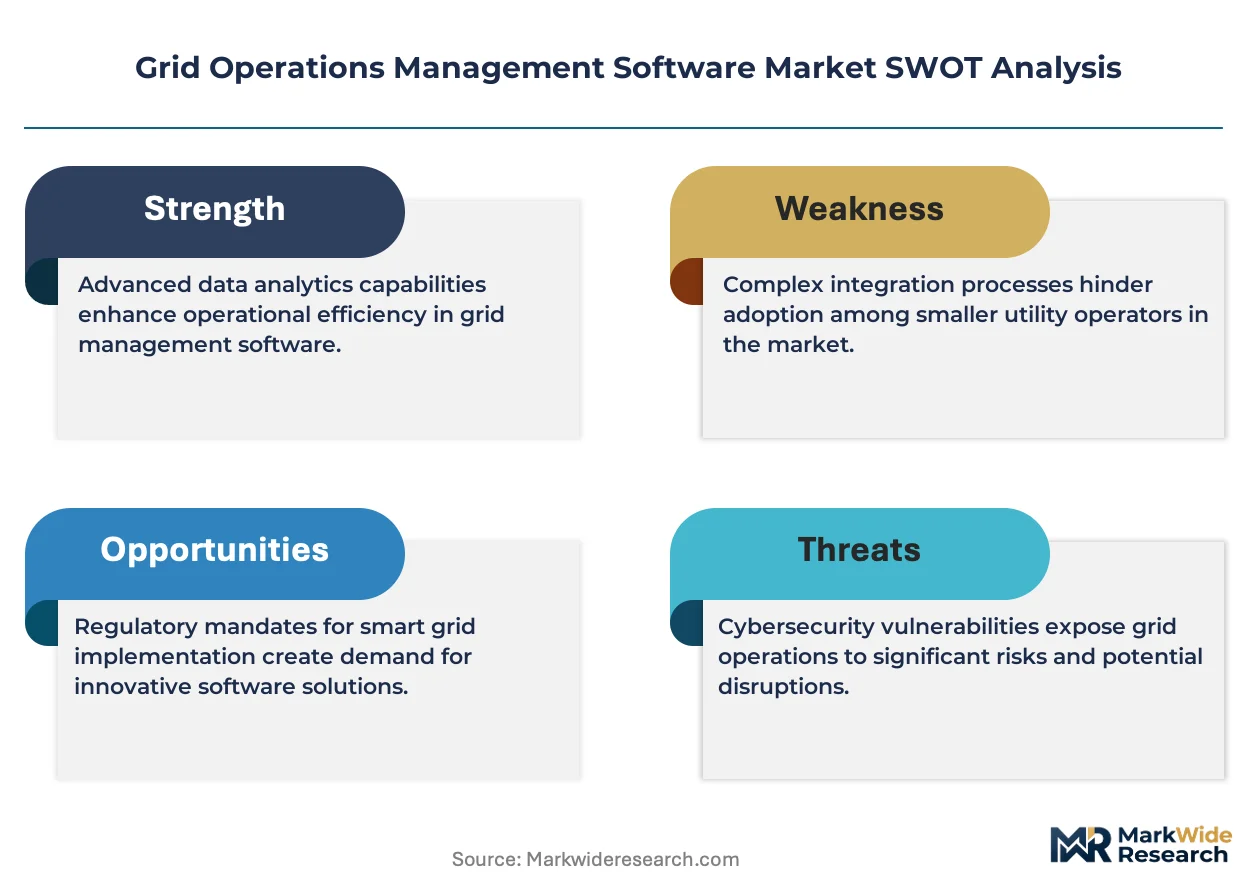
FERC Order 2222 in the United States compels grid operators to accommodate aggregated distributed energy resources, forcing software upgrades that support bidirectional communication with behind-the-meter assets. The EU Green Deal and CSRD disclosure requirements in Europe mandate granular carbon-intensity tracking across transmission networks, embedding emissions-accounting modules into core operations platforms. Grid operators must weigh cloud migration timelines against cybersecurity hardening demands as NERC CIP standards evolve to address API-centric attack surfaces.
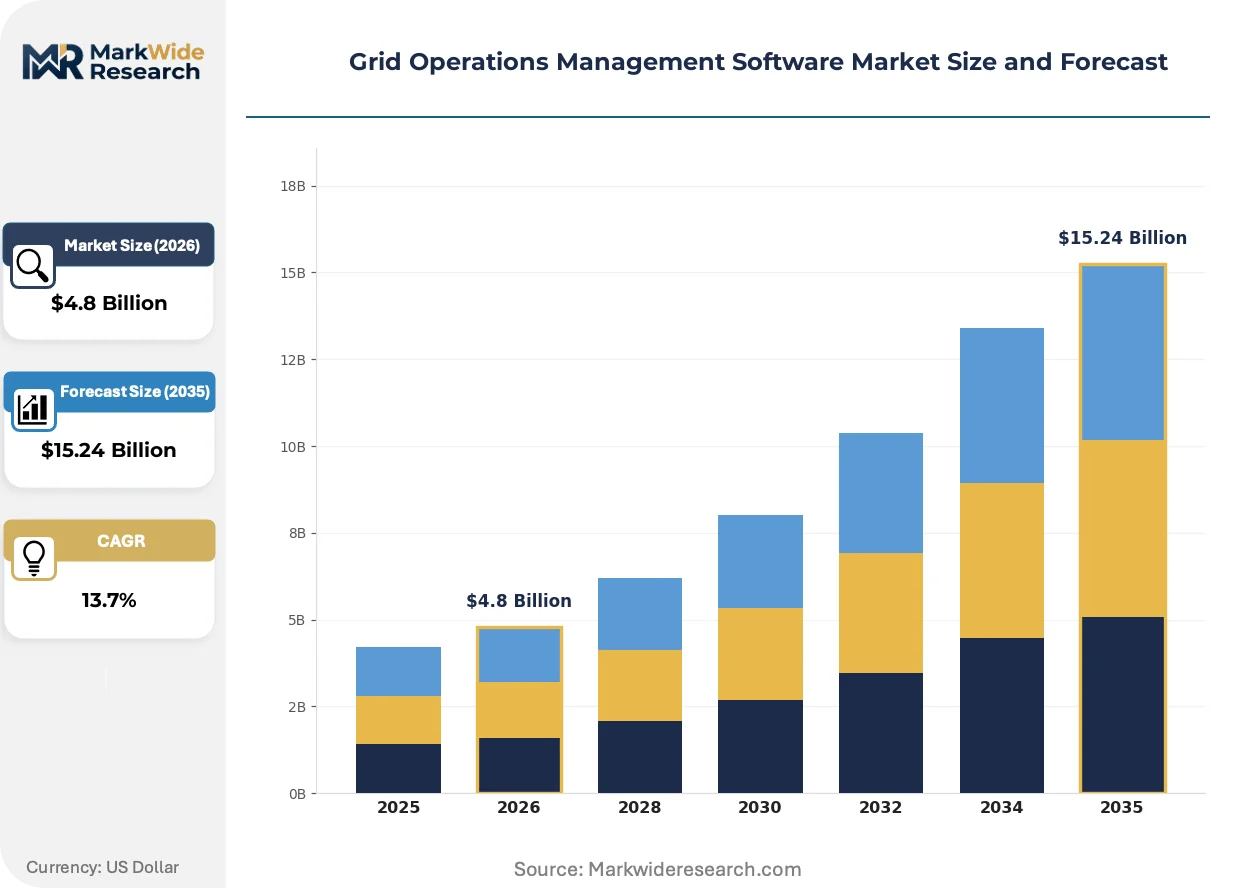
Market Dynamics
Cloud-native architectures are displacing monolithic SCADA deployments as transmission operators confront terabyte-scale telemetry volumes from inverter-based resources. Elastic compute infrastructure now determines competitive viability in real-time grid balancing.
Growth Catalysts
- FERC Order 2222:Aggregated distributed energy resource mandates compel software upgrades supporting bidirectional communication protocols across US balancing authorities.
- EU Green Deal carbon-intensity tracking:CSRD disclosure requirements embed emissions-accounting modules into core European transmission operations platforms.
- Behind-the-meter solar proliferation:Residential and commercial PV installations force distribution utilities to procure visibility tools for voltage regulation at circuit extremities.
Market Restraints
- Specialized OT cybersecurity talent scarcity:NERC CIP evolution toward API-centric attack surfaces outpaces certified workforce availability in North America.
- Legacy protocol fragmentation:DNP3, IEC 61850, and proprietary fieldbus implementations create integration friction delaying cloud migration timelines.
- Hyperscale vendor concentration:Municipal utilities face vendor lock-in risks as AWS, Azure, and GCP dominate cloud infrastructure provisioning.
Strategic Opportunities
- German TSO modernization urgency:Transmission system operators face compressed timelines for control center upgrades under federal network expansion mandates.
- Digital twin convergence:Physics-based modeling merges with machine learning to enable predictive asset degradation forecasting for transformer fleets.
- Capacity-market revenue capture:Demand response software enables utilities to monetize flexible load participation in wholesale electricity markets.
Industry Challenges
- Sub-second latency requirements:Wide-area monitoring systems demand millisecond-grade compute response times that challenge containerized cloud architectures.
- Interoperability certification delays:Multi-vendor integration testing for SCADA-DMS-OMS data exchange extends deployment cycles by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grid Operations Management Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Management Systems, SCADA, Distribution Management Systems, Network Management Systems Application: Load Forecasting, Outage Management, Asset Management, Demand Response End User: Utilities, Independent System Operators, Energy Retailers, Industrial Users Technology: Cloud-based Solutions, On-premise Solutions, Hybrid Solutions, Analytics Tools |
| Companies Covered | ABB, Hitachi Energy, Siemens, OSI (Open Systems International), Cisco, GE Vernova, Oracle, ETAP (Operation Technology), Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grid Operations Management Software Market Strategic Shifts
Software-defined substations and edge-native control logic are compressing traditional hierarchical automation layers. These shifts demand rearchitected data pipelines and revised operator training paradigms.
Edge computing infrastructure is converging with time-synchronized networking to enable localized fault isolation without control center dependency. Distribution utilities in California and Texas deploy micro-PMU clusters at feeder heads for phase-angle monitoring. This topology is converging with centralized analytics to create hybrid architectures that balance autonomy with coordination.
The EU F-Gas Regulation mandates SF6 emissions monitoring across switchgear fleets, forcing GIS asset management modules into operations software stacks. Transmission operators must now track gas inventory leakage rates with the same rigor as outage indices. German and French TSOs lead compliance integration, embedding sensor networks into existing SCADA frameworks.
Subscription-based SaaS procurement displaces perpetual license models for advanced distribution management functions. Municipal cooperatives in the US Midwest favor operational expenditure structures that align software costs with rate-base recovery cycles. This preference accelerates cloud-native vendor penetration among smaller utilities previously excluded from enterprise-tier deployments.
Grid Operations Management Software Market Segmentation
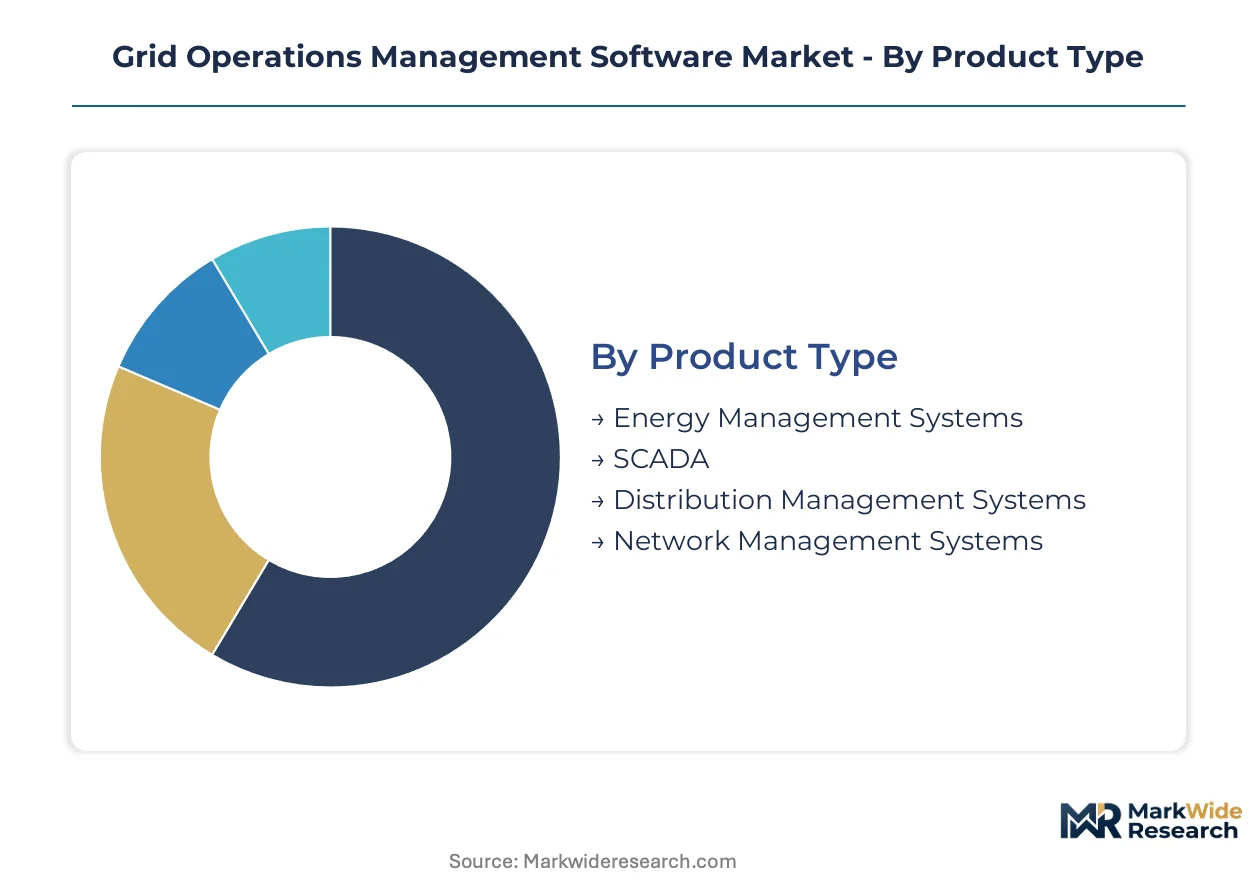
Grid Operations Management Software Market segmentation reflects the architectural tension between legacy operational technology stacks and cloud-native platforms. Each dimension captures distinct procurement rationales, from transmission-scale reliability mandates to distribution-edge flexibility requirements.
Product Type:
Standalone deployments dominate transmission control centers, while embedded modules proliferate at distribution substations where space and latency constraints tighten.
- Energy Management Systems:These platforms coordinate generation dispatch, reserve scheduling, and interchange transactions across balancing authority areas. German transmission system operators anchor procurement volumes as federal network expansion mandates compress modernization timelines.
- SCADA:The foundational telemetry layer acquires analog and digital field data through remote terminal units with sub-second scan cycles. North American municipal utilities concentrate replacement demand where NERC CIP compliance deadlines force cybersecurity hardening of legacy protocol stacks.
- Distribution Management Systems:Outage restoration and voltage optimization modules for radial network topologies.
- Network Management Systems:Topology processing and state estimation for meshed transmission grids.
Volume placements concentrate in SCADA; the faster expansion belongs to Energy Management Systems.
Application:
Revenue capture potential varies sharply across use cases, with wholesale market-linked functions commanding premium pricing over operational efficiency tools.
- Demand Response:Aggregation platforms enable bidirectional communication with behind-the-meter assets for capacity-market participation. US independent system operators drive procurement as FERC Order 2222 compliance deadlines approach.
- Asset Management:Predictive degradation models for transformer fleets and switchgear populations. French transmission operators embed SF6 emissions tracking modules under EU F-Gas Regulation mandates.
- Load Forecasting:Statistical and machine learning models for demand trajectory prediction.
- Outage Management:Fault location, isolation, and service restoration workflow automation.
Margin concentration sits with Demand Response; the steepest expansion trajectory belongs to Asset Management.
End User:
Procurement scale and integration complexity diverge between vertically integrated utilities and specialized balancing authorities.
- Utilities:Vertically integrated generation, transmission, and distribution operators requiring unified control platforms. Cloud-native deployments accelerate among US Midwest cooperatives favoring operational expenditure structures.
- Independent System Operators:Regional transmission organizations managing wholesale markets and grid reliability. Consolidation of balancing authority functions drives software consolidation across US interconnections.
- Energy Retailers:Competitive suppliers seeking customer-facing demand management interfaces.
- Industrial Users:Large commercial and manufacturing facilities with on-site generation and interruptible load contracts.
Contract value concentrates in Utilities; the fastest share gain belongs to Independent System Operators.
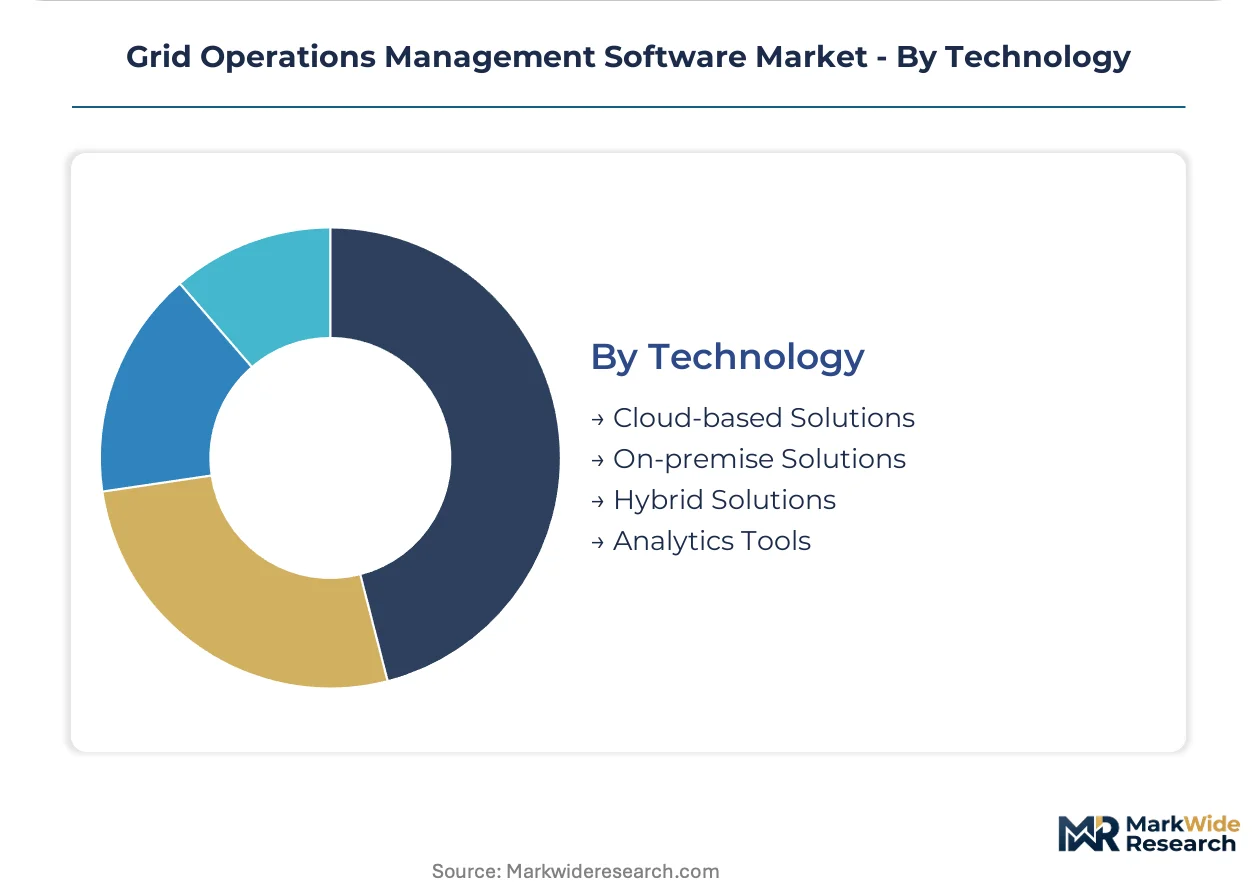
Technology:
Deployment architecture determines capital intensity, cybersecurity exposure, and vendor lock-in risk for grid operators.
- Cloud-based Solutions:Hyperscale infrastructure delivers elastic compute for real-time telemetry processing without on-site hardware procurement. Municipal utilities and cooperatives favor subscription models that align software costs with rate-base recovery cycles.
- Hybrid Solutions:Edge-native control logic with centralized analytics for latency-sensitive and compute-intensive workloads. California and Texas distribution utilities deploy micro-PMU clusters at feeder heads for phase-angle monitoring.
- On-premise Solutions:Air-gapped installations for critical cyber assets under strict NERC CIP boundaries.
- Analytics Tools:Standalone machine learning and optimization modules for predictive maintenance and renewable forecasting.
Deployment share concentrates in On-premise Solutions; the climbing fastest trajectory belongs to Cloud-based Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement concentrates in the United States and Germany, where regulatory mandates and network expansion timelines compress deployment schedules. Cloud-native platform adoption accelerates fastest among municipal cooperatives seeking operational expenditure alignment. European transmission operators face parallel pressures from decarbonization tracking and grid reliability mandates.
United States
FERC Order 2222 drives aggregated distributed energy resource integration across independent system operators. NERC CIP standards evolve toward API-centric cybersecurity frameworks. California and Texas utilities deploy micro-PMU clusters for phase-angle monitoring at distribution feeder heads.
Germany
Transmission system operators confront compressed modernization timelines under federal network expansion mandates. EU Green Deal carbon-intensity tracking requirements embed emissions-accounting modules into core operations platforms. The Rhine-Ruhr industrial corridor anchors SCADA replacement demand for cybersecurity-hardened protocol stacks.
France
EU F-Gas Regulation mandates SF6 emissions monitoring across switchgear fleets, forcing GIS asset management integration. CSRD disclosure requirements tighten granular carbon tracking across transmission networks. The Paris-Saclay cluster concentrates predictive analytics procurement for transformer fleet degradation modeling.
United Kingdom
Ofgem's RIIO price control frameworks incentivize digital infrastructure investment for distribution network operators. National Grid ESO consolidates balancing authority functions, driving software platform unification. London and Southeast England host cloud-native vendor penetration among regional distribution utilities.
Canada
Provincial crown corporations modernize legacy SCADA installations to accommodate behind-the-meter solar proliferation. Environment and Climate Change Canada regulations tighten methane and SF6 emissions tracking for transmission assets. Ontario's Greater Toronto Area concentrates demand response platform procurement for capacity-market participation.
Grid Operations Management Software Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors integrate edge computing with centralized analytics. The market structure consolidates around three tiers: integrated industrial conglomerates with transmission control heritage, pure-play software specialists, and hyperscale cloud providers entering through infrastructure partnerships. Two archetypes anchor competitive positioning: domain-experienced automation vendors leveraging hardware-software bundles, and digital-native analytics platforms emphasizing machine learning differentiation. M&A activity and cloud infrastructure alliances constitute the dominant competitive moves.
Within the integrated industrial tier, Siemens and ABB exemplify archetypes anchored in transmission control system heritage, while Schneider Electric occupies a position emphasizing building-automation extension into utility operations. These three represent the dominant competitive anchors against which pure-play software vendors and cloud infrastructure providers define alternative positioning strategies.
| Leading Market Players |
|---|
| ABB |
| Hitachi Energy |
| Siemens |
| OSI (Open Systems International) |
| Cisco |
| GE Vernova |
| Oracle |
| ETAP (Operation Technology) |
| Schneider Electric |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation compliance gates qualified supply access for SF6 emissions monitoring modules, restricting premium-tier pricing to vendors with certified sensor integration capabilities. German and French transmission operators pay substantial markups for GIS asset management stacks that embed regulatory-grade leakage tracking.
Pricing Analysis
Volume placements concentrate in standardized SCADA replacements, while margins cluster in demand response platforms with wholesale market linkages. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in municipal utility segments is intensifying because cooperatives favor operational expenditure alignment over capital-intensive perpetual licenses. Independent system operators exhibit lowest price sensitivity due to FERC Order 2222 compliance deadlines; Midwest cooperatives drive hardest bargain negotiations.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale transmission operator demand, while systems integrators serve municipal cooperative procurement. Component sourcing draws from Germany, the United States, and India for industrial computing hardware, with specialized sensor manufacturing anchored in Japan and South Korea. Supply chain risk centers on single-source vulnerability for time-synchronized networking chipsets essential to micro-PMU deployments. Distribution runs through OEM-direct relationships for transmission-scale deployments, with value-added resellers penetrating distribution utility segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as cloud-native architectures displace monolithic SCADA deployments. Containerized edge computing is replacing legacy hierarchical automation layers across transmission and distribution control centers.
For Market Incumbents: Deploy hardware-software bundling as the primary defensive lever against pure-play analytics vendors. Siemens and ABB should deepen transmission control system integration with edge-native platforms to counter GE Vernova's digital twin specialization. NERC CIP cybersecurity hardening requirements threaten margin compression unless incumbents certify proprietary protocol stacks ahead of API-centric standard evolution.
For New Entrants and Emerging Players: Launch via SaaS subscription models targeting US Midwest municipal cooperatives excluded from enterprise-tier deployments. White-space concentration sits in demand response aggregation for behind-the-meter solar visibility, with California and Texas distribution utilities showing penetrable procurement appetite. Partner with hyperscale cloud providers to bypass legacy OT cybersecurity talent scarcity blocking direct utility sales cycles.
For Investors and Strategic Acquirers: FERC Order 2222 compliance deadline announcements are the leading indicator that software upgrade procurement cycles are accelerating. Long-term viability favors vendors with domain-experienced engineering talent pools capable of sub-second latency system design. Target acquisition archetype: pure-play analytics platforms with machine learning differentiation and existing utility pilot deployments. Monitor German TSO modernization tender releases for inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Elastic compute infrastructure enables real-time telemetry processing without capital-intensive on-premise hardware procurement. |
| Digital Twin Convergence | Physics-based modeling merged with machine learning transforms transformer fleet maintenance from reactive to predictive regimes. |
| API-Centric Cybersecurity Certification | NERC CIP evolution demands hardened protocol stacks that gate market access for unqualified vendors. |
| Edge Computing Infrastructure Deployment | Micro-PMU clusters at feeder heads enable localized fault isolation without control center dependency. |
| Strategic Hyperscale Partnership | AWS, Azure, and GCP alliances reduce vendor lock-in risks while accelerating municipal cooperative penetration. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with utility planning officers, grid operators, EPC contractors, and software integration specialists combined with FERC Order 2222 implementation tracking, EU Green Deal directive documentation, and NERC CIP standard evolution records. Bottom-up deployment volume estimates triangulated against top-down market sizing from transmission system operator capital expenditure disclosures.
Segment-level granularity modeled deployment architecture across cloud-based, hybrid, and on-premise solutions; application functions spanning demand response, asset management, and outage management; and end-user categories including utilities, independent system operators, and energy retailers. CAGRs derived from regression analysis of historical procurement cycles against regulatory mandate timelines, with inputs from behind-the-meter solar penetration trajectories and SF6 emissions compliance cost curves across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for containerized edge computing would alter the outlook if sub-second latency requirements force reversion to monolithic architectures. Forecasts reflect assumptions about FERC Order 2222 implementation pace, EU Green Deal enforcement stringency, and hyperscale cloud provider pricing trajectories. Practitioners should monitor German TSO tender announcements, NERC CIP standard revision releases, and municipal cooperative SaaS procurement volumes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Shared Power Bank Market
Energy Management Systems
North America Home Energy Management System (HEMS) Market
Energy Management Systems
District Cooling Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
Europe Advanced Distribution Management System Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
Smart HVAC Controls Market
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
Meter Data Management System Market
Energy Management Systems
United Arab Emirates Portable Air Conditioning Market
Energy Management Systems
Smart Cooling Systems Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
AI Water Heater Market