
 Africa Digital Showers Market | 2026-2036
Africa Digital Showers Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Digital Showers Market Analytics
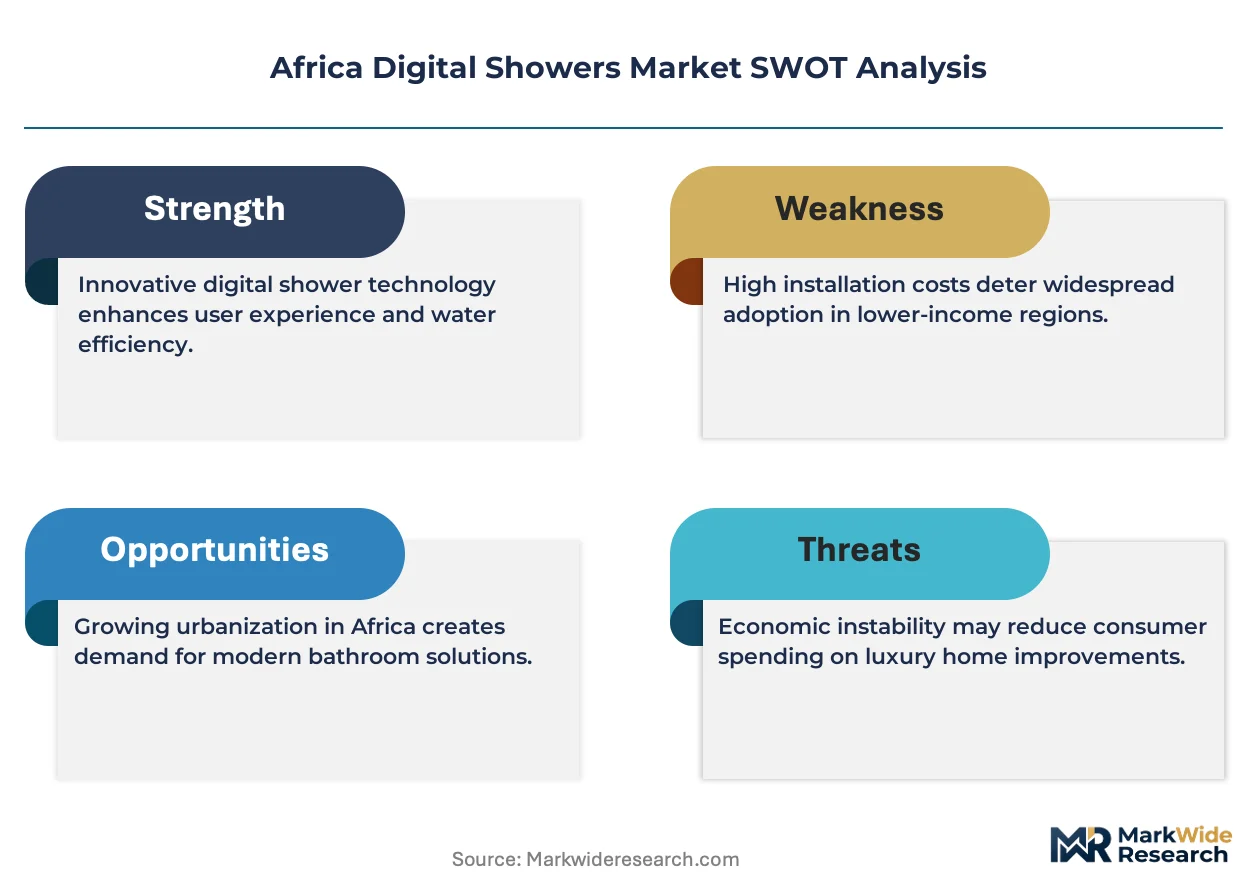
SABS 10400-X plumbing compliance is reorganizing competitive access across Southern Africa. Grohe AG leverages its thermostatic valve expertise to sustain premium positioning in Johannesburg's high-end developments. Jaquar and Company Private Limited anchors its position through backward integration into brass casting, controlling cost structures for price-sensitive East African projects. Kohler Co. differentiates via mobile-app-enabled shower systems that compete on connectivity in Morocco's emerging smart-home channel.
Digital showers integrate electronic thermostatic mixing valves, flow sensors, and programmable user interfaces to deliver temperature-precise water delivery with remote control capability. Smart showers with Wi-Fi and Bluetooth connectivity dominate unit economics, while sensor-based technology captures the fastest growth trajectory in commercial gym and spa deployments. Hotels represent the highest-margin end-user pool, whereas households drive aggregate volume through retrofit demand in Nigeria and Egypt's urban corridors.
South Africa's SABS standards, Kenya's Water Services Regulatory Board efficiency codes, and Nigeria's SON product safety mandates collectively shape import eligibility and local assembly incentives. The EU's REACH chemical compliance for brass alloys further constrains supply chains for European-sourced components. Stakeholders must monitor harmonization between national plumbing codes and smart-device electromagnetic compatibility standards to anticipate certification bottlenecks.
Market Dynamics
South Africa's SABS certification requirements for thermostatic mixing valves are reorganizing competitive access across Southern Africa, forcing import-dependent suppliers to establish local assembly partnerships or exit the premium segment entirely.
Growth Catalysts
- Water efficiency mandates:Kenya's Water Services Regulatory Board efficiency codes and Nigeria's state-level conservation rules are compelling hospitality developers in Lagos and Nairobi to specify sensor-based digital shower units.
- Wi-Fi infrastructure spread:Urban corridors in Morocco and Egypt are seeing broadband penetration sufficient to support mobile-app-enabled shower systems, unlocking smart-home channel development.
- Brass alloy compliance:The EU's REACH chemical standards for brass components are accelerating supplier consolidation, favoring manufacturers with captive foundry operations.
Market Restraints
- Import dependency for electronic components:Thermostatic valve sensors and programmable interfaces rely on Asian-sourced semiconductors, exposing distributors to currency volatility and shipping disruptions.
- High upfront capex versus conventional mixers:Digital shower units command price multiples of three to five times traditional thermostatic valves, compressing retrofit demand in Egypt's mass residential segment.
- Limited certified installer networks:SABS-qualified plumbing technicians concentrate in Johannesburg and Cape Town, leaving secondary South African cities underserved for warranty-validating installation.
Strategic Opportunities
- Underpenetrated East African residential:Ethiopia's Addis Ababa corridor and Tanzania's Dar es Salaam periphery show minimal digital shower penetration despite rising middle-income construction.
- Convergence of water heating and shower control:Integration of solar geyser management with digital shower interfaces offers bundled energy-water efficiency propositions for Kenya's boutique hotel sector.
- Commercial gym and spa deployments:Sensor-based technology captures fastest growth in wellness facility chains seeking touchless operation and usage analytics.
Industry Challenges
- Electromagnetic compatibility certification delays:Harmonization between national plumbing codes and smart-device radio frequency standards remains incomplete, creating bottlenecks for Wi-Fi-enabled product launches.
- Legacy plumbing infrastructure incompatibility:Nigeria's and Egypt's aging copper pipe networks often lack pressure stability required for electronic thermostatic valve performance, necessitating pre-installation assessments that elongate sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Digital Showers Market |
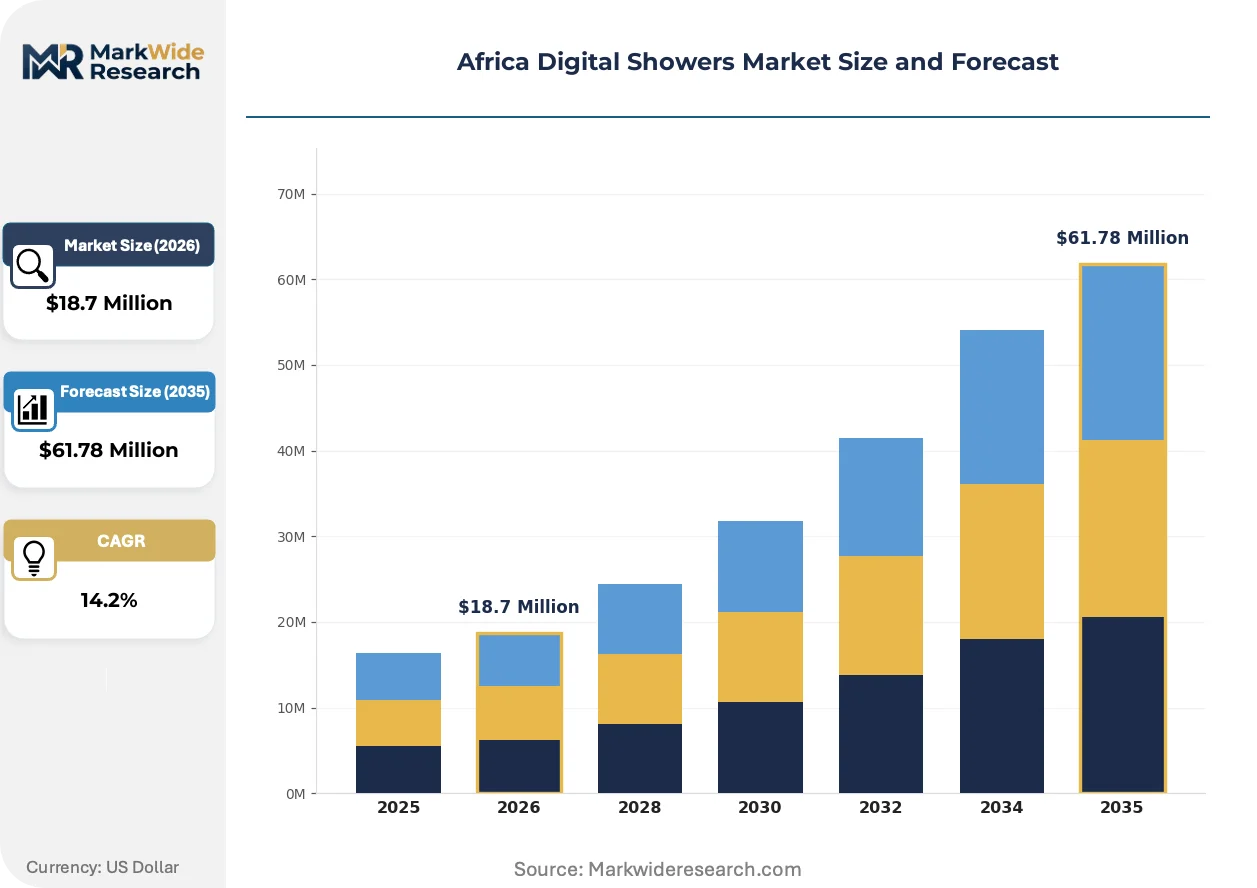
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $61.78 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Showers, Conventional Showers, Digital Controls, Thermostatic Showers End User: Households, Hotels, Gyms, Spas Technology: Wi-Fi Enabled, Bluetooth Connectivity, Mobile App Control, Sensor-Based Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Distributors |
| Companies Covered | Kohler Co., Grohe AG, Hansgrohe AG, Aqualisa Products Limited, Jaquar and Company Private Limited, Moen Incorporated, Roca Sanitario, S.A., TOTO LTD., LIXIL Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Digital Showers Market Evolving Landscape
Product architecture in African digital showers is splitting along connectivity and non-connectivity lines, with thermostatic precision becoming table stakes while remote control capability defines premium positioning.
Thermostatic electronic mixing valves with programmable temperature memory are bifurcating the installed base. High-end residential developers in Johannesburg's Sandton district specify these units for master suites, while hospitality procurement in Nairobi favors simpler sensor-activated models without connectivity. This split is compressing mid-tier mechanical thermostatic mixer demand as buyers polarize toward either basic functionality or full smart-home integration.
South Africa's SABS 10400-X plumbing compliance revisions are tightening thermostatic valve performance thresholds. The standard now mandates specific response times for temperature deviation correction, disqualifying several import brands from specification in government-backed housing projects. Developers in Cape Town's Atlantic Seaboard precinct are responding by pre-qualifying suppliers with existing SABS test reports, narrowing tender participation.
Hotel procurement teams are consolidating vendor relationships around full-bathroom system providers rather than component specialists. Morocco's emerging boutique hotel sector now favors suppliers offering coordinated digital shower, faucet, and water heating controls through single interfaces. This consolidation is most visible in Marrakech's luxury riad renovations, where property owners prioritize unified mobile-app management over best-of-breed component mixing.
Africa Digital Showers Market Segmentation
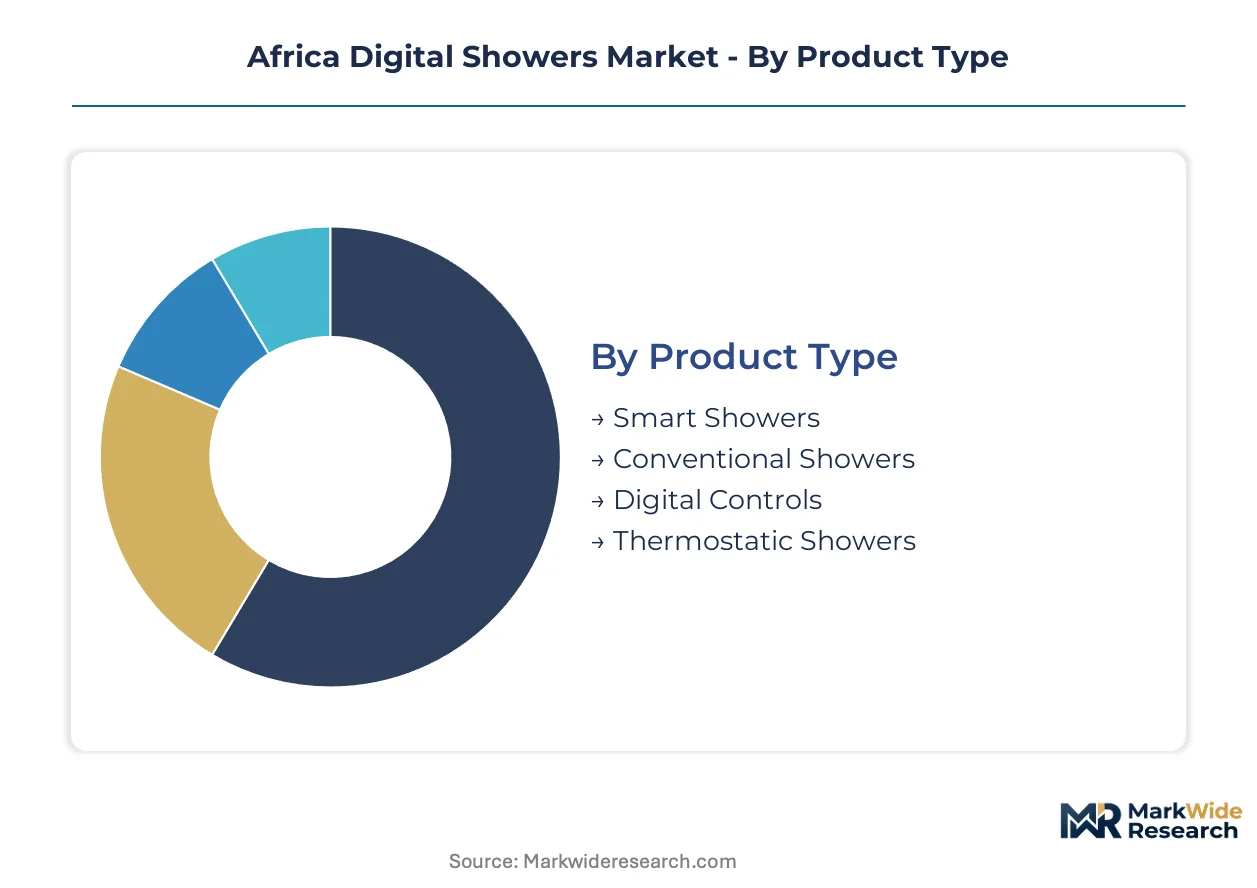
Digital shower procurement in Africa splits sharply between specification-driven commercial projects and price-sensitive residential retrofits. Regulatory compliance tiers and connectivity infrastructure availability create distinct addressable pools across product architectures.
Product Type:
South Africa's SABS 10400-X plumbing code and Kenya's Water Services Regulatory Board efficiency mandates are segmenting product eligibility by thermostatic performance thresholds.
- Smart Showers:Wi-Fi and Bluetooth-enabled units with programmable temperature memory and remote activation. Demand concentrates in Morocco's emerging smart-home channel and Johannesburg's Sandton high-end residential developments, driven by broadband penetration sufficient to support mobile-app ecosystems.
- Conventional Showers:Non-electronic thermostatic mixers with manual temperature control. Volume concentrates in Egypt's mass residential segment and Nigeria's urban corridors where upfront capex multiples of three to five times digital units compress specification.
- Digital Controls:Electronic interfaces for flow and temperature management without full connectivity integration. Kenya's boutique hotel sector specifies these for guest bathroom renovations seeking efficiency compliance without smart-home infrastructure investment.
- Thermostatic Showers:Temperature-stabilizing valves with rapid deviation correction meeting SABS response-time mandates. Cape Town's Atlantic Seaboard developers pre-qualify suppliers with existing test reports for government-backed housing tenders.
Established volume favors Conventional Showers; emerging adoption favors Smart Showers.
End User:
Margin structures diverge between hospitality specification cycles with extended procurement timelines and residential retrofit demand with compressed decision windows.
- Households:Aggregate volume driver through urban corridor retrofit demand in Lagos, Cairo, and Nairobi. Currency volatility and import dependency for electronic components elongate replacement cycles in price-sensitive segments.
- Hotels:Highest-margin end-user pool with consolidated vendor relationships around full-bathroom system providers. Marrakech's luxury riad renovations prioritize unified mobile-app management over component mixing.
- Gyms:Wellness facility chains seeking touchless operation and usage analytics. Sensor-based technology expands most quickly in commercial deployments across South Africa's metropolitan fitness networks.
- Spas:Boutique wellness operations requiring precise temperature control for therapeutic applications. Ethiopia's Addis Ababa corridor shows minimal penetration despite rising middle-income construction.
Procurement consolidation favors Hotels; volume scale favors Households.
Technology:
Infrastructure readiness and electromagnetic compatibility certification completeness determine technology deployment feasibility.
- Wi-Fi Enabled:Full cloud connectivity with remote monitoring and energy-water integration. Morocco's urban corridors leverage sufficient broadband penetration for smart-home channel development.
- Bluetooth Connectivity:Local device pairing without internet dependency. Nigeria's luxury residential segment adopts these where Wi-Fi reliability remains inconsistent.
- Mobile App Control:Smartphone interfaces for scheduling and usage tracking. Kenya's boutique hotel sector bundles these with solar geyser management for energy-water efficiency propositions.
- Sensor-Based:Touchless activation with flow sensors and programmable interfaces. Lagos and Nairobi hospitality developers specify these to meet water efficiency mandates with fastest installation growth in commercial gym deployments.
Regulatory compliance favors Sensor-Based; connectivity premium favors Wi-Fi Enabled.
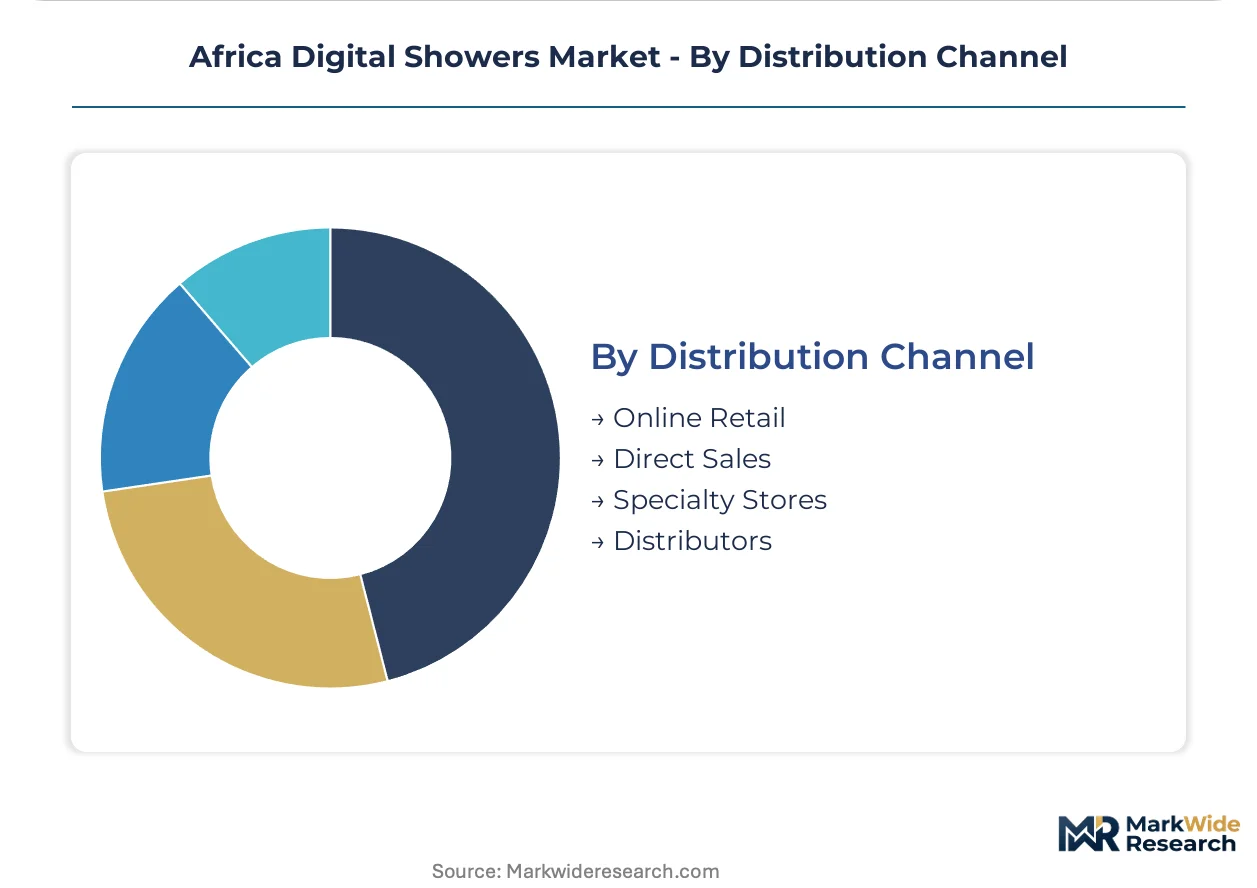
Distribution Channel:
Certified installer network density and warranty validation requirements shape channel economics.
- Online Retail:E-commerce platforms serving price-comparison shoppers in Egypt and Nigeria's urban corridors. Limited penetration for SABS-mandated products requiring qualified installation.
- Direct Sales:Manufacturer relationships with hospitality developers and large-scale residential contractors. Cape Town and Johannesburg concentrate specification activity through this channel.
- Specialty Stores:Showroom-based specification for high-end residential and boutique commercial projects. Sandton district developers rely on these for pre-qualification and SABS documentation access.
- Distributors:Regional inventory and logistics networks covering secondary South African cities underserved by certified technician concentration. Currency hedging and shipping disruption mitigation drive distributor consolidation.
Specification gravity favors Direct Sales; geographic coverage favors Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement teams in Africa's digital showers market cluster around hospitality developers in Lagos and Nairobi, luxury residential contractors in Johannesburg's Sandton district, and boutique hotel operators in Marrakech. These buyer archetypes drive specification patterns across distinct regulatory and infrastructure environments.
South Africa
Sandton high-end residential developments and Cape Town's Atlantic Seaboard precinct anchor demand for SABS-certified thermostatic units. SABS 10400-X plumbing compliance revisions mandate specific temperature deviation response times, disqualifying import brands from government-backed housing tenders. Johannesburg and Cape Town concentrate certified installer networks, leaving secondary cities underserved for warranty-validating installation.
Nigeria
Lagos hospitality developers specify sensor-based digital showers to meet state-level water conservation mandates. The Standards Organisation of Nigeria enforces product safety certification for imported electronic thermostatic components. Luxury residential retrofit demand concentrates in Lagos Island and Ikoyi corridors, though currency volatility elongates replacement cycles for price-sensitive households.
Kenya
Nairobi boutique hotels drive specification for efficiency-compliant digital controls without full smart-home infrastructure investment. The Water Services Regulatory Board codes compel commercial developers to adopt flow-sensor technology. The Karen and Westlands sub-markets show rising procurement of solar geyser-integrated shower systems for bundled energy-water efficiency propositions.
Morocco
Marrakech luxury riad renovations prioritize unified mobile-app management for full-bathroom system integration. Broadband penetration in Casablanca and Rabat urban corridors supports Wi-Fi-enabled smart shower deployment. The country's national standards body aligns electromagnetic compatibility requirements with EU frameworks, smoothing import pathways for connected devices.
Egypt
Cairo's mass residential segment compresses digital shower specification due to upfront capex multiples three to five times conventional thermostatic valves. Aging copper pipe networks in Giza and Alexandria sub-markets lack pressure stability for electronic valve performance, necessitating pre-installation assessments that elongate sales cycles. Hotel procurement in Red Sea resort corridors shows isolated premium adoption.
Africa Digital Showers Market Competitive Landscape
Player mix skews toward European-origin premium specialists and Asia-Pacific scale manufacturers with captive brass foundry operations. Market structure shows moderate concentration at the premium tier, with price-competitive segments fragmenting across regional distributors. Three archetypes dominate: SABS-certified thermostatic valve specialists, backward-integrated brass casting operators, and mobile-app-enabled connectivity providers. Competitive moves center on local assembly partnerships for certification compliance and distributor consolidation to mitigate currency hedging exposure.
Among European-origin specialists, Grohe AG and Hansgrohe AG exemplify thermostatic valve expertise positioning for premium specification in high-end residential developments. Jaquar and Company Private Limited represents the backward-integrated archetype, with its captive brass casting operations controlling cost structures for price-sensitive East African projects. These three companies anchor the competitive landscape across distinct price-performance tiers without overlapping positioning.
| Leading Market Players |
|---|
| Kohler Co. |
| Grohe AG |
| Hansgrohe AG |
| Aqualisa Products Limited |
| Jaquar and Company Private Limited |
| Moen Incorporated |
| Roca Sanitario, S.A. |
| TOTO LTD. |
| LIXIL Corporation |
| Others |
Value Network & Pricing Analysis
Brass alloy substitution for lead-reduced formulations is reorganizing procurement geography and cost structures across African digital shower manufacturing. South Africa's SABS certification requirements and Kenya's Water Services Regulatory Board efficiency codes are simultaneously tightening material specifications while expanding addressable demand pools for compliant suppliers.
Pricing Analysis
Cost-plus contracts with brass ingot indexation dominate procurement between foundries and valve manufacturers. Price differentiation rests on SABS certification tier and captive casting capability, with Johannesburg-based suppliers commanding premiums over import-dependent distributors. Pricing pressure stems from currency volatility affecting Asian-sourced electronic components. Egypt's mass residential segment exhibits highest price sensitivity, while Morocco's boutique hotel developers show lowest sensitivity to upfront capex multiples.
Supply Chain Analysis
Strategic stockpiling of thermostatic valve sensors prevails over just-in-time approaches given semiconductor lead time volatility. Supply concentrates in China for electronic interfaces, India for brass castings, and Germany for precision valve assemblies. Raw material dependencies span copper-zinc alloys, silicon semiconductors, and ceramic disc cartridges. Single-source vulnerability for programmable thermostatic controllers creates exposure to shipping disruption. Distribution runs through Johannesburg and Nairobi-based distributors with SABS-qualified installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Africa's digital showers market represents early-cycle expansion with Wi-Fi infrastructure penetration in Morocco and South Africa unlocking smart-home channel development ahead of regulatory compliance deadlines.
For Market Incumbents: Shield premium positioning in Johannesburg's Sandton district through SABS 10400-X pre-certification investments before revised response-time mandates take full effect. Deepen captive brass casting capacity to offset REACH compliance cost compression. Consolidate distributor relationships in secondary South African cities where certified installer scarcity threatens warranty validation coverage.
For New Entrants and Emerging Players: Differentiate on solar geyser integration for Kenya's boutique hotel sector, where bundled energy-water efficiency propositions lack established suppliers. Target Ethiopia's Addis Ababa corridor and Tanzania's Dar es Salaam periphery for conventional thermostatic shower penetration before specification-driven competition arrives. Pursue direct sales relationships with hospitality developers in Lagos and Nairobi rather than distributor-dependent retail channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with European-origin thermostatic valve specialists facing margin pressure from Asia-Pacific scale manufacturers. Five-to-ten year viability hinges on electromagnetic compatibility certification completeness for Wi-Fi-enabled portfolios. Acquisition targets should show established SABS test report libraries and existing local assembly partnerships. Watch for harmonization between national plumbing codes and smart-device radio frequency standards as inflection indicator for connected product launch feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| SABS Certification Pre-Investment | Early compliance with revised SABS 10400-X response-time mandates secures government-backed housing tender eligibility in Cape Town. |
| Captive Brass Casting Expansion | In-house foundry operations control cost structures against REACH alloy compliance pressures for East African project bids. |
| Solar Geyser Integration Development | Bundled energy-water efficiency propositions capture Kenya's boutique hotel procurement consolidation toward full-bathroom system providers. |
| Certified Installer Network Buildout | SABS-qualified technician density in secondary South African cities enables warranty-validating installation coverage expansion. |
| Electromagnetic Compatibility Pre-Certification | Advance testing against harmonized radio frequency standards accelerates Wi-Fi-enabled product launches in Morocco's smart-home channel. |
Research Methodology
Initial hypotheses were tested against primary input from plumbing contractors, hospitality procurement managers, SABS certification officers, and brass foundry operations directors, then refined through secondary validation. Primary fieldwork combined structured interviews with specification architects in Johannesburg's Sandton district and Nairobi's Westlands sub-market. Secondary sources encompassed SABS technical documentation, Kenya's Water Services Regulatory Board efficiency code filings, EU REACH substance restriction updates, and customs records for thermostatic valve component imports. Bottom-up demand modeling across end-user segments was triangulated against top-down market sizing from regulatory compliance timelines.
Variance decomposition across product type, connectivity technology, end-user segment, and geographic adoption cluster shaped the analytical framework. Modeled dimensions spanned smart versus conventional shower architectures, Wi-Fi versus Bluetooth versus sensor-based activation, hospitality versus residential versus commercial gym deployments, and infrastructure-ready versus infrastructure-constrained urban corridors. CAGRs were derived from penetration rate assumptions calibrated to broadband availability and regulatory mandate enforcement schedules. Forecast inputs incorporated SABS certification completion rates and solar geyser installation growth in Kenya's boutique hotel sector.
Material uncertainties — abrupt currency devaluations, semiconductor shipping disruptions, and electromagnetic compatibility standard harmonization delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding Wi-Fi infrastructure rollout pace and national plumbing code revision timing. Revision becomes warranted when SABS-qualified installer network expansion crosses thresholds that enable warranty coverage in previously underserved secondary cities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Energy Management in Data Centers Market
Energy Management Systems
Airflow Management Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Advanced Server Energy Monitoring Tools Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
Global Data Center Energy Management Solution Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
Asia-Pacific Energy Management System Market
Energy Management Systems
Smart Air Cleaners Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
Global Smart Air Conditioning Market
Energy Management Systems
Smart Programmable Thermostat Market