
 North America Home Energy Management System (HEMS) Market | 2026-2036
North America Home Energy Management System (HEMS) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Home Energy Management System (HEMS) Market Insights
Multifamily residential deployment is expanding across North America as property developers embed HEMS infrastructure into new construction. General Electric Company leverages its utility partnerships to secure bulk deployment contracts across municipal grids. Schneider Electric SE anchors its position through integrated building automation platforms that span residential and light commercial verticals.
Home Energy Management Systems encompass hardware and software platforms that monitor, control, and optimize residential electricity consumption through real-time data analytics and automated load scheduling, typically operating via 2.4 GHz wireless protocols with sub-100 millisecond response times for demand-response events. Smart thermostats dominate product-level revenue due to their direct HVAC control and established consumer familiarity, while IoT-enabled systems capture the fastest expansion as open-protocol interoperability reduces vendor lock-in. Energy Management Software concentrates margin pools through recurring SaaS revenue models that monetize utility tariff optimization.
The Inflation Reduction Act, FERC Order 2222, and IEEE 2030.5 interoperability standards collectively reshape North American HEMS demand by mandating grid-edge device participation in wholesale markets and establishing cybersecurity baselines for networked energy assets. EPA ENERGY STAR certification requirements for connected thermostats further filter market access by excluding uncertified hardware from rebate-eligible procurement channels. Stakeholders must monitor state-level implementation timelines for IRA rebate programs to align channel inventory with localized incentive availability.
Market Dynamics
The Inflation Reduction Act's consumer rebate programs are restructuring North American HEMS deployment economics, compressing payback periods and redirecting channel inventory toward rebate-eligible hardware configurations.
Growth Catalysts
- FERC Order 2222:Aggregated distributed energy resources now participate in wholesale electricity markets across US RTO territories, creating revenue streams for HEMS-enabled demand response.
- Time-of-use rate proliferation:California, Texas, and Northeast utilities deploy dynamic pricing that rewards automated load shifting, directly monetizing HEMS optimization algorithms.
- Smart thermostat familiarity:Residential HVAC replacement cycles pull HEMS adoption as homeowners upgrade legacy controls during equipment end-of-life decisions.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea fabs dominate Wi-Fi and Zigbee chipset production, exposing hardware vendors to allocation volatility.
- Interoperability fragmentation:Competing protocols between Thread, Z-Wave, and proprietary mesh networks force redundant engineering and inflate BOM costs.
- Installer skill scarcity:Licensed electricians with whole-home panel integration expertise command premium labor rates that compress project margins.
Strategic Opportunities
- Multifamily new construction:Property developers in Texas and Florida embed HEMS infrastructure pre-drywall, capturing tenant electricity management as a building amenity.
- Vehicle-to-home integration:Bidirectional EV charging protocols converging with HEMS platforms enable residential battery arbitrage using automotive storage assets.
- State-level IRA implementation:California and New York rebate program rollouts create localized demand surges requiring aligned distribution partnerships.
Industry Challenges
- Cybersecurity certification timelines:IEEE 2030.5 compliance testing bottlenecks delay product launches as third-party labs face accreditation backlogs.
- Legacy HVAC integration complexity:Pneumatic and proprietary control systems in existing commercial-to-residential conversions resist standardized HEMS retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Home Energy Management System (HEMS) Market |
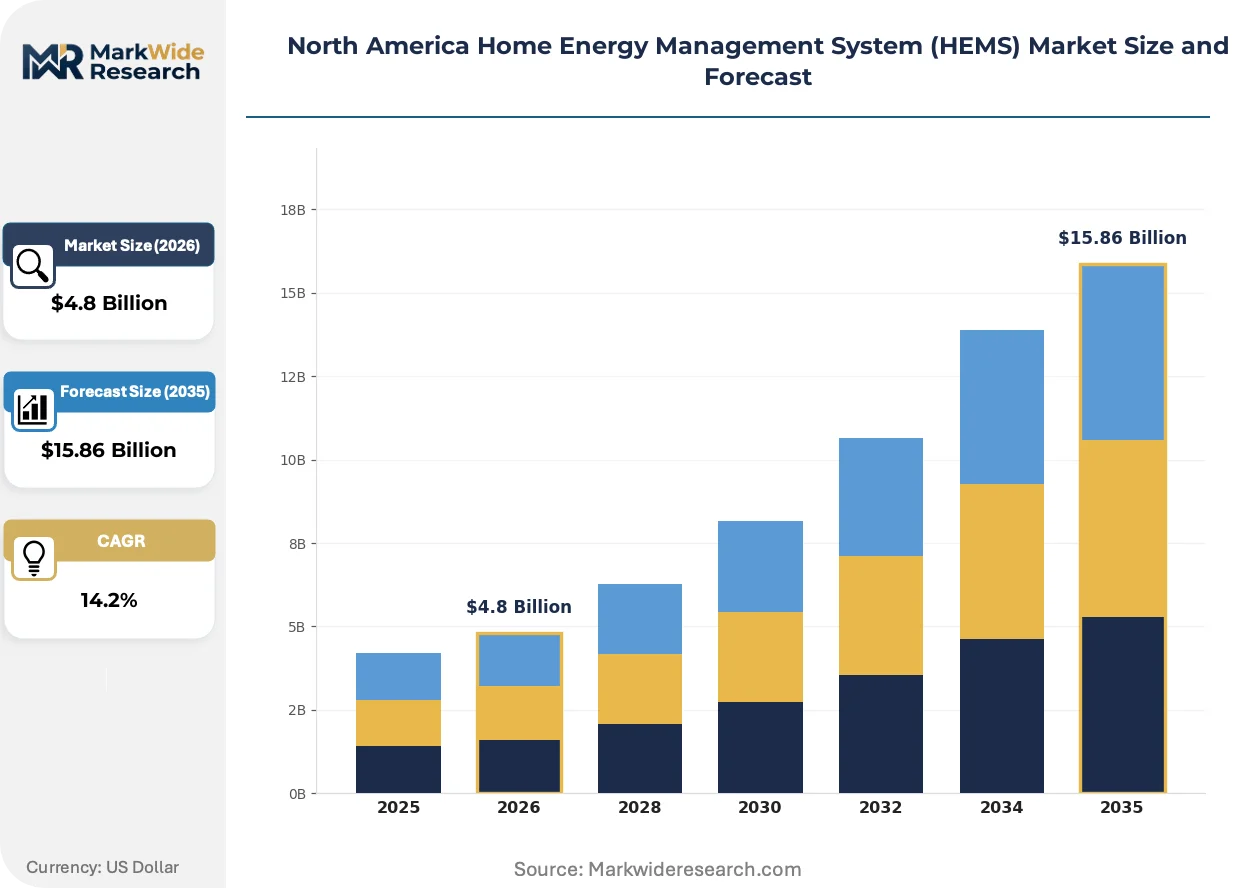
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Thermostats, Energy Monitors, Smart Plugs, Energy Management Software End User: Residential, Retail, Hospitality, Educational Institutions Integration Level: Standalone Systems, Integrated Solutions, IoT-Enabled Systems, Cloud-Based Solutions Technology: Zigbee, Z-Wave, Wi-Fi, Bluetooth |
| Companies Covered | General Electric Company, Siemens AG, Johnson Controls International PLC, Schneider Electric SE, Honeywell International Inc., Panasonic Holdings Corporation, Eaton Corporation PLC, Robert Bosch GMBH, Enel X North America, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Home Energy Management System (HEMS) Market Trends and Innovations
Grid-edge intelligence and open-protocol interoperability are dissolving vendor lock-in while enabling new revenue models that monetize residential flexibility rather than hardware margins alone.
Matter-over-Thread connectivity is expanding into whole-home energy orchestration, replacing siloed device ecosystems with unified commissioning workflows. Single-family homeowners in California and Texas adopt these systems fastest where utility rebate programs subsidize upgrade costs. The technology is expanding into demand-response aggregation, compressing the addressable market for proprietary closed-loop platforms.
The Inflation Reduction Act's Home Energy Rebate Programs restructure procurement incentives by tying federal subsidies to ENERGY STAR certification and contractor training requirements. Hardware manufacturers must redesign product roadmaps around EPA qualification timelines to maintain rebate eligibility. Single-family retrofits in the Northeast corridor face the steepest compliance adjustments as state energy offices administer divergent implementation schedules.
Installer-led channel consolidation concentrates HEMS sales through HVAC contractors and electrical trades rather than retail big-box distribution. Homeowners increasingly purchase systems as bundled upgrade packages during equipment replacement rather than standalone electronics. Texas and Florida markets exhibit this pattern most acutely where heat pump adoption drives simultaneous thermostat and panel upgrade decisions.
North America Home Energy Management System (HEMS) Market Segmentation
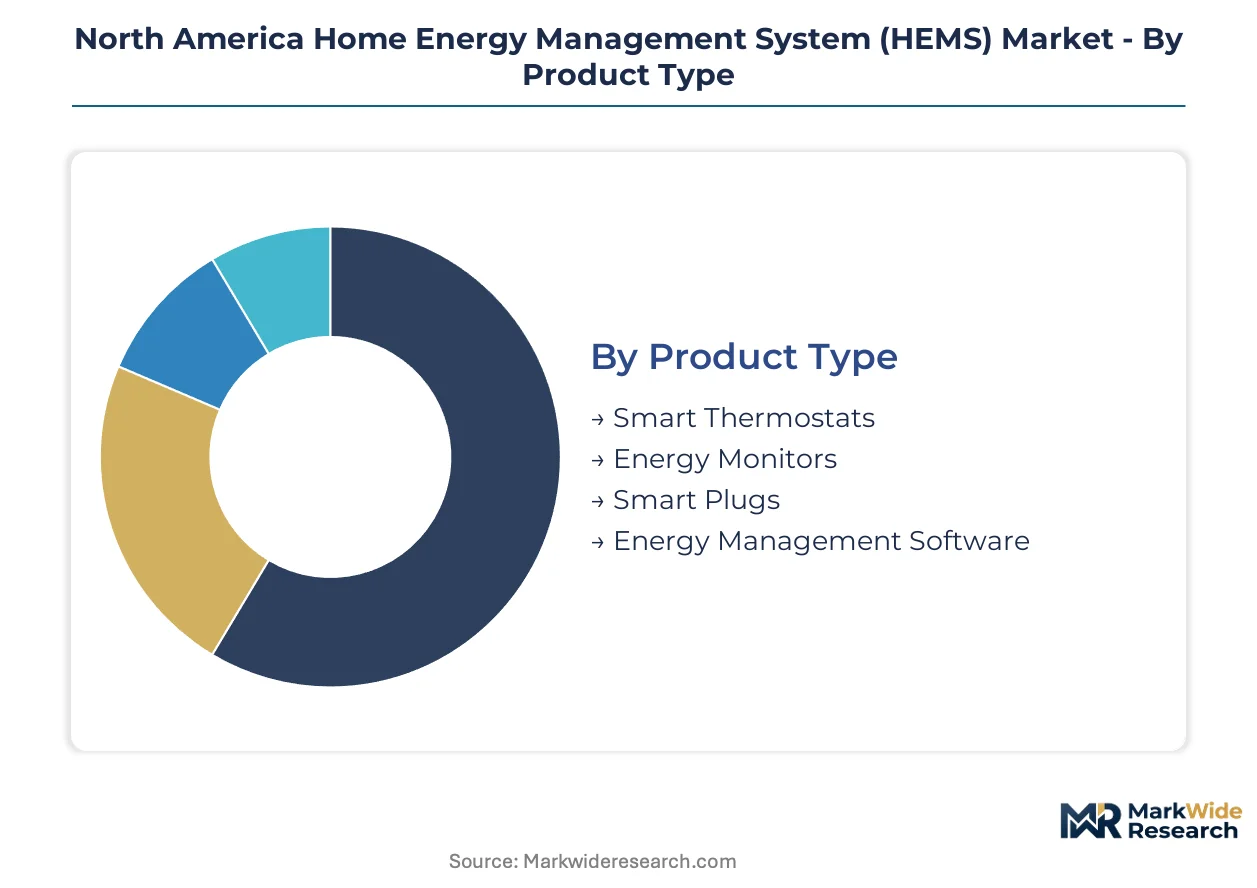
HEMS segmentation reveals divergent margin structures across hardware and software layers. Product type determines upfront revenue capture, while integration level shapes recurring income potential and customer lifetime value.
Product Type:
Smart thermostats command the volume tier through established HVAC replacement channels, while energy management software captures premium recurring margins.
- Smart Thermostats:Wall-mounted controllers with occupancy sensing and weather-responsive algorithms that modulate heating and cooling cycles. California and Texas utilities subsidize ENERGY STAR-certified units through time-of-use rate enrollment programs, pulling adoption during equipment replacement cycles.
- Energy Monitors:Circuit-level sensing hardware that measures real-time consumption at individual breaker panels. Northeast corridor deployments concentrate where aggressive state decarbonization mandates require granular load visibility for electrification planning.
- Smart Plugs:Outlet-level controllers enabling remote switching and standby power elimination for individual appliances. These entry-level devices expand the addressable market to renters and budget-conscious homeowners.
- Energy Management Software:Cloud platforms that aggregate device data, optimize against utility tariffs, and automate demand-response participation. SaaS revenue models concentrate margin pools away from commoditized hardware.
Mature deployment sits with smart thermostats. Newer deployment is concentrated in energy management software.
End User:
Residential applications dominate unit volume, while institutional verticals sustain higher per-site contract values through centralized procurement.
- Residential:Single-family and multifamily dwellings where homeowners or property managers optimize utility spending. IRA rebate eligibility drives retrofit decisions in California and New York.
- Retail:Big-box stores and grocery chains managing lighting and HVAC across distributed footprints. These deployments prioritize centralized dashboard control over residential-grade automation depth.
- Hospitality:Hotels and short-term rental operators using guest room energy management to control unoccupied unit consumption. Texas and Florida markets lead due to extreme cooling loads.
- Educational Institutions:K-12 and university facilities with complex scheduling requirements and public procurement compliance. These buyers require FERC Order 2222 interoperability for utility incentive access.
Residential captures the steepest expansion trajectory as consumer rebates compress payback periods.
Integration Level:
Standalone systems anchor the entry price tier, while cloud-based solutions command premium positioning through continuous algorithmic improvement.
- Standalone Systems:Single-device controllers without network connectivity or centralized orchestration. These units serve budget retrofits and legacy infrastructure constraints.
- Integrated Solutions:Whole-home platforms combining multiple hardware categories under unified software control. Northeast corridor multifamily developers embed these pre-construction as tenant amenities.
- IoT-Enabled Systems:Mesh-networked devices using open protocols for vendor-agnostic expansion. Matter-over-Thread adoption is displacing proprietary ecosystems fastest in California.
- Cloud-Based Solutions:Architectures processing optimization algorithms remotely with over-the-air feature updates. These platforms monetize residential flexibility through utility demand-response contracts.
Standalone systems dominate legacy retrofit. Cloud-based solutions concentrate in new construction and utility partnership deployments.
Technology:
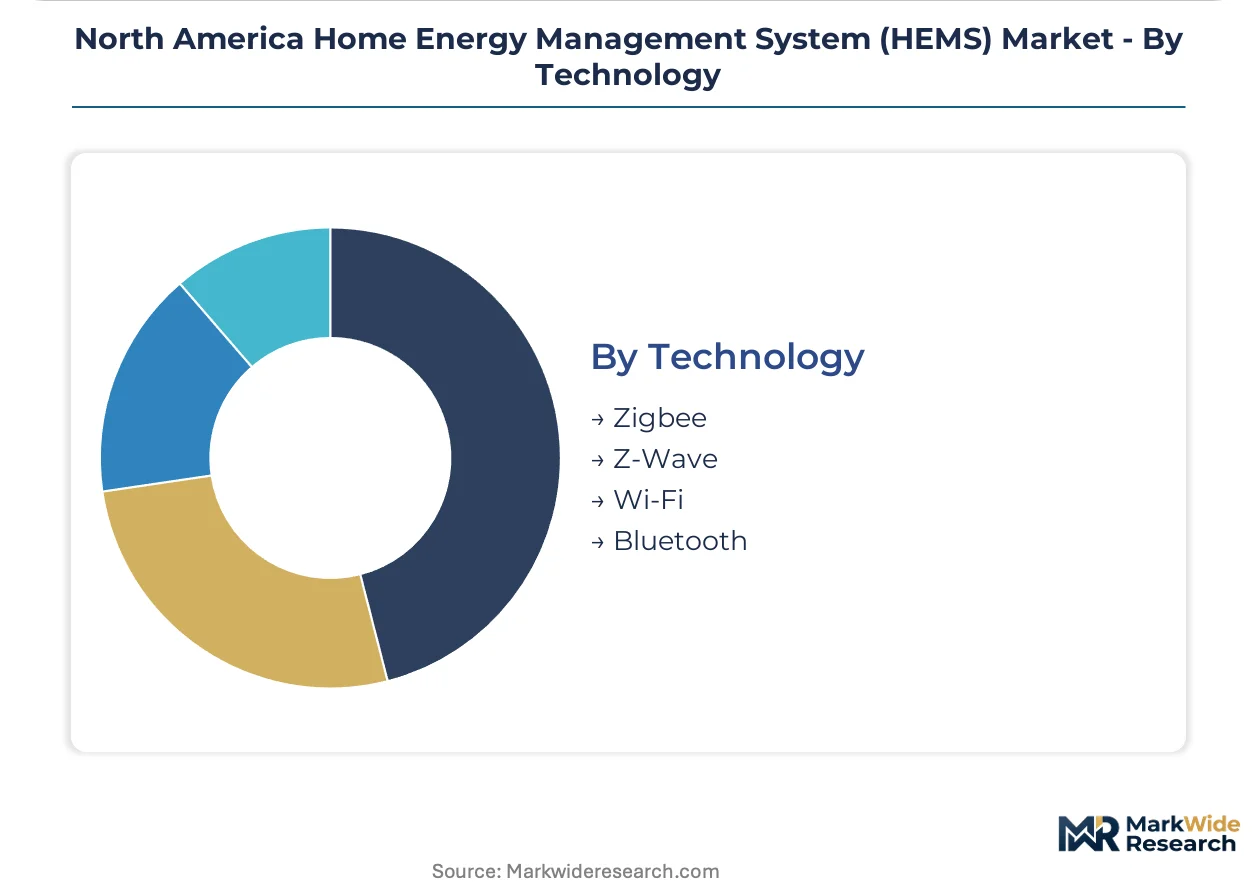
Wi-Fi saturates the mass-market tier through existing home network infrastructure, while mesh protocols command efficiency premiums in whole-home deployments.
- Zigbee:Low-power mesh protocol operating at 2.4 GHz with sub-100 millisecond demand-response latency. Smart meter partnerships in Texas utilities drive Zigbee gateway requirements.
- Z-Wave:Sub-GHz mesh standard with superior wall penetration for larger residential footprints. These deployments concentrate in suburban single-family markets.
- Wi-Fi:IP-native connectivity leveraging existing router infrastructure without dedicated hubs. Thermostat and smart plug categories default to Wi-Fi for consumer simplicity.
- Bluetooth:Point-to-point protocol for commissioning and localized device control. This technology serves as fallback pairing mechanism rather than primary operational transport.
Wi-Fi anchors mainstream consumer adoption. Zigbee and Z-Wave concentrate in utility-integrated and whole-home professional installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and IRA-designated energy communities concentrate HEMS deployment capital in specific metropolitan corridors. State energy offices administer divergent rebate timelines. Utility regulatory frameworks vary sharply across sub-regional jurisdictions.
United States
California's Title 24 building codes mandate solar-ready electrical panels in new construction, embedding HEMS infrastructure by default. The Inflation Reduction Act's Home Energy Rebate Programs channel federal dollars through Sacramento's energy office with contractor certification requirements. Silicon Valley and Los Angeles Basin deployments lead unit volume as Pacific Gas & Electric and Southern California Edison expand time-of-use rate structures.
Canada
Ontario's Independent Electricity System Operator contracts residential demand response through aggregator platforms, creating revenue streams for cloud-based HEMS providers. Natural Resources Canada's Greener Homes Grant subsidizes smart thermostat installations with EnerGuide evaluation requirements. Greater Toronto and Vancouver metropolitan areas concentrate retrofit activity where provincial efficiency programs overlap with municipal building codes.
Mexico
Comisión Federal de Electricidad's tariff reform pilot programs in Baja California and Yucatán introduce dynamic pricing for high-consumption residential segments. The country's national energy regulator permits distributed generation net metering that pairs with home energy monitoring hardware. Mexico City and Monterrey industrial corridors exhibit early HEMS adoption among dual-nationality households with US utility bill exposure.
Texas
ERCOT's wholesale price volatility and retail competition create arbitrage opportunities for automated load-shifting algorithms. The Public Utility Commission of Texas mandates smart meter deployment that enables real-time consumption feedback. Dallas-Fort Worth and Houston metropolitan statistical areas lead multifamily new construction embedding HEMS as tenant amenities.
Northeast Corridor
State decarbonization mandates in New York and Massachusetts require building electrification roadmaps with granular load monitoring. Regional Greenhouse Gas Initiative auction revenues fund efficiency programs with HEMS eligibility. Boston and New York City metropolitan areas concentrate institutional procurement from educational and hospitality verticals.
North America Home Energy Management System (HEMS) Market Competitive Landscape
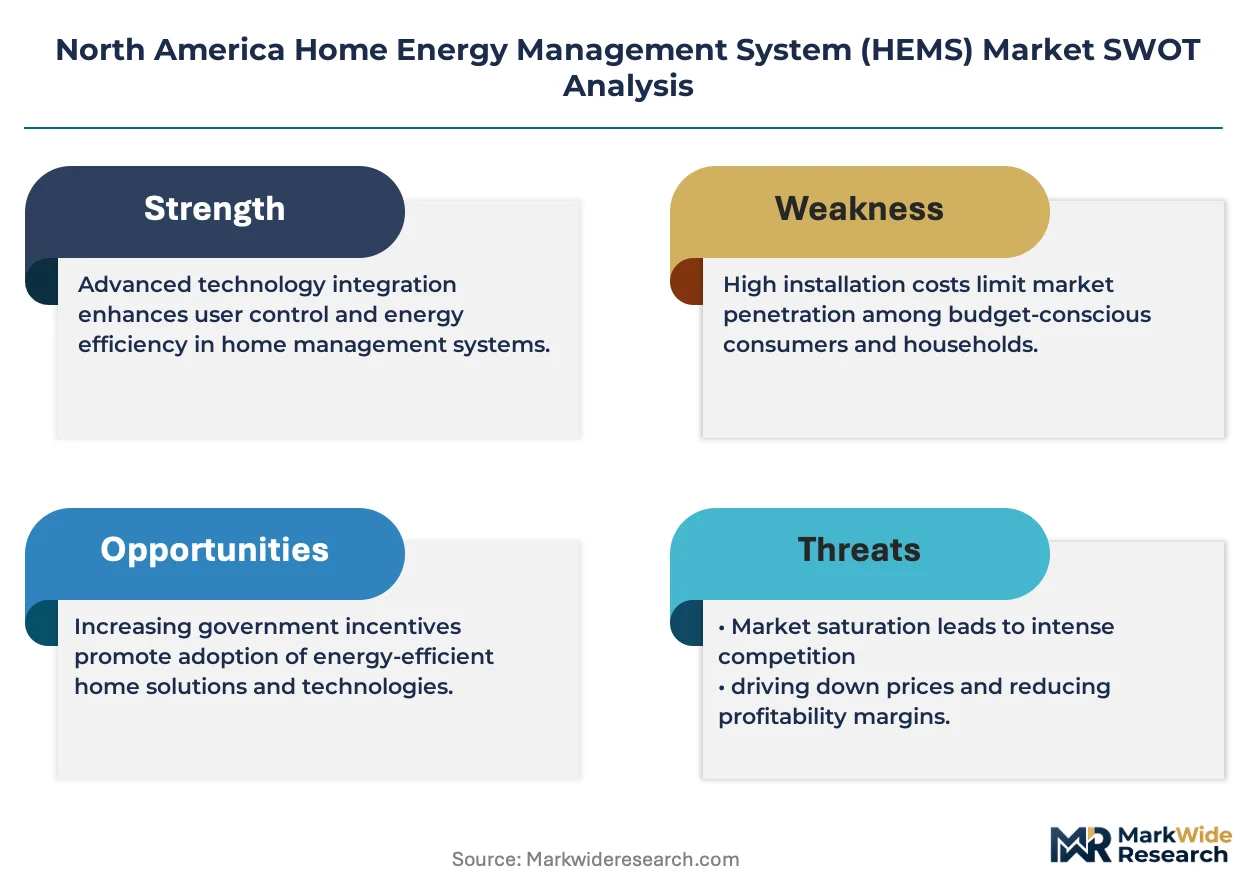
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers commanding premium positioning in utility-direct channels while component OEMs supply private-label retail. Market structure tilts toward consolidation among full-stack energy management platforms, though interoperability standards fragment hardware tiers. Three archetypes dominate: diversified industrial conglomerates with utility partnerships, pure-play building automation specialists, and emerging IoT-native entrants. Competitive moves center on strategic partnerships with regional utilities and portfolio diversification into adjacent grid-edge assets.
Within the industrial conglomerate tier, General Electric Company and Schneider Electric SE exemplify scale-driven positioning through captive utility relationships and integrated building automation spanning residential to light commercial verticals. Siemens AG anchors European-origin technology transfer into North American grid modernization programs. These three entities represent the dominant competitive set as measured by bulk deployment contract capture across municipal and cooperative utility territories.
| Leading Market Players |
|---|
| General Electric Company |
| Siemens AG |
| Johnson Controls International PLC |
| Schneider Electric SE |
| Honeywell International Inc. |
| Panasonic Holdings Corporation |
| Eaton Corporation PLC |
| Robert Bosch GMBH |
| Enel X North America, Inc. |
| Others |
Pricing and Supply Chain Analysis
Matter-over-Thread protocol migration is compressing hardware BOM costs while concentrating procurement leverage among semiconductor vendors with certified radio stacks. This technology shift simultaneously reduces integration engineering overhead and deepens dependency on Taiwan and South Korea fabs for Zigbee and Thread chipsets.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to ENERGY STAR-certified thermostats during IRA rebate program launch windows, while spot inventory of uncertified legacy hardware trades at distressed levels. Pricing stratifies across premium certified, standard compliant, and economy unverified tiers based on EPA qualification status and contractor training bundling. Cost compression in the economy tier is intensifying as private-label retail entrants absorb margin erosion. Single-family retrofit buyers exhibit highest price sensitivity, while utility bulk procurement contracts sustain premium tier stability.
Supply Chain Analysis
Licensed electrician scarcity in Texas and Florida construction corridors extends project timelines and inflates labor cost components faster than hardware inputs. Taiwan, South Korea, and China dominate Wi-Fi and mesh radio chipset fabrication, with Mexico emerging as a nearshore final assembly location for thermostat housings. Raw material dependencies span lithium-ion cells for battery-backed sensors, copper for panel-level current transformers, and rare earth elements for relay actuators. Single-source vulnerability concentrates in Zigbee stack certification labs with IEEE 2030.5 accreditation backlogs. Distribution runs through HVAC contractor channels and electrical wholesale distributors rather than retail big-box.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installer capacity constraints prop pricing power for certified deployment networks, with queue times for whole-home panel integration extending 8-14 weeks in high-growth metropolitan corridors.
For Market Incumbents: Cement utility partnership exclusivity through FERC Order 2222-compliant demand-response aggregation platforms before state IRA implementation timelines accelerate. Defend against IoT-native entrants by acquiring Thread certification expertise and embedding backward integration into cloud software stacks. Prioritize Schneider Electric and General Electric's municipal grid contract capture models as defensive templates. For New Entrants and Emerging Players: Launch via multifamily property developer direct channels in Texas and Florida, bypassing saturated retail thermostat replacement cycles. Target cloud-based SaaS monetization for vehicle-to-home integration as the most penetrable white space, with bidirectional EV charging protocols creating new optimization revenue streams. Pursue state energy office certification pre-approval to align product launches with localized rebate availability. For Investors and Strategic Acquirers: Exit pathways concentrate in utility-facing platform acquisitions by industrial conglomerates seeking grid-edge asset portfolios. Five-to-ten year viability hinges on ENERGY STAR certification moats and IEEE 2030.5 compliance infrastructure. Monitor FERC Order 2222 implementation velocity across RTO territories as the primary inflection signal for demand-response revenue scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Utility Partnership Exclusivity | FERC Order 2222 compliance locks in wholesale market participation revenue for certified platforms. |
| Thread Protocol Certification | Matter interoperability reduces vendor lock-in and accelerates whole-home ecosystem adoption. |
| Installer Network Acquisition | Licensed electrician scarcity makes certified deployment capacity a defendable competitive asset. |
| Vehicle-to-Home Integration | Bidirectional EV charging protocols enable residential battery arbitrage using automotive storage. |
| State Rebate Program Alignment | IRA implementation timelines create localized demand surges requiring pre-positioned inventory. |
Research Methodology
Document review covered FERC filings, EPA ENERGY STAR certification databases, and utility tariff schedules, complemented by interviews with utility demand-response program managers, HVAC contractor operations directors, smart thermostat product managers, and state energy office rebate administrators. Secondary validation drew from EIA electricity consumption data, IEEE standards documentation, and municipal building code filings. Bottom-up unit deployment estimates triangulated against top-down utility incentive budget allocations.
Segment-level outputs across the projection horizon reflect modeled penetration rates by housing stock vintage, integration complexity tier, and regional regulatory framework. The analytical framework incorporated technology adoption curves, equipment replacement cycle timing, and rebate program elasticity. CAGRs derived from compound growth trajectory fitting against historical smart meter deployment patterns and time-of-use rate expansion schedules. Key inputs included semiconductor lead time indices and licensed electrician labor rate surveys.
IRA rebate program rollout delays, IEEE 2030.5 lab accreditation bottlenecks, and Taiwan fab allocation volatility are the dominant revision risks to deployment velocity assumptions. Forecasts reflect documented regulatory timelines and supply chain capacity constraints. Material deviation in named triggers warrants pause and re-evaluation of market penetration trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Global Vibration Control System Market
Energy Management Systems
Energy Management in Data Centers Market
Energy Management Systems
Airflow Management Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
Asia-Pacific Energy Management System Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
India Home Ventilation System Market
Energy Management Systems
Peltier Chillers Market
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
Global Personal Cooling Device Market
Energy Management Systems
Smart Air Cleaners Market
Energy Management Systems
Bed Cooling System Market