
 USA and Canada Portable Air Conditioner Market | 2026-2036
USA and Canada Portable Air Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
USA and Canada Portable Air Conditioner Market Analytics
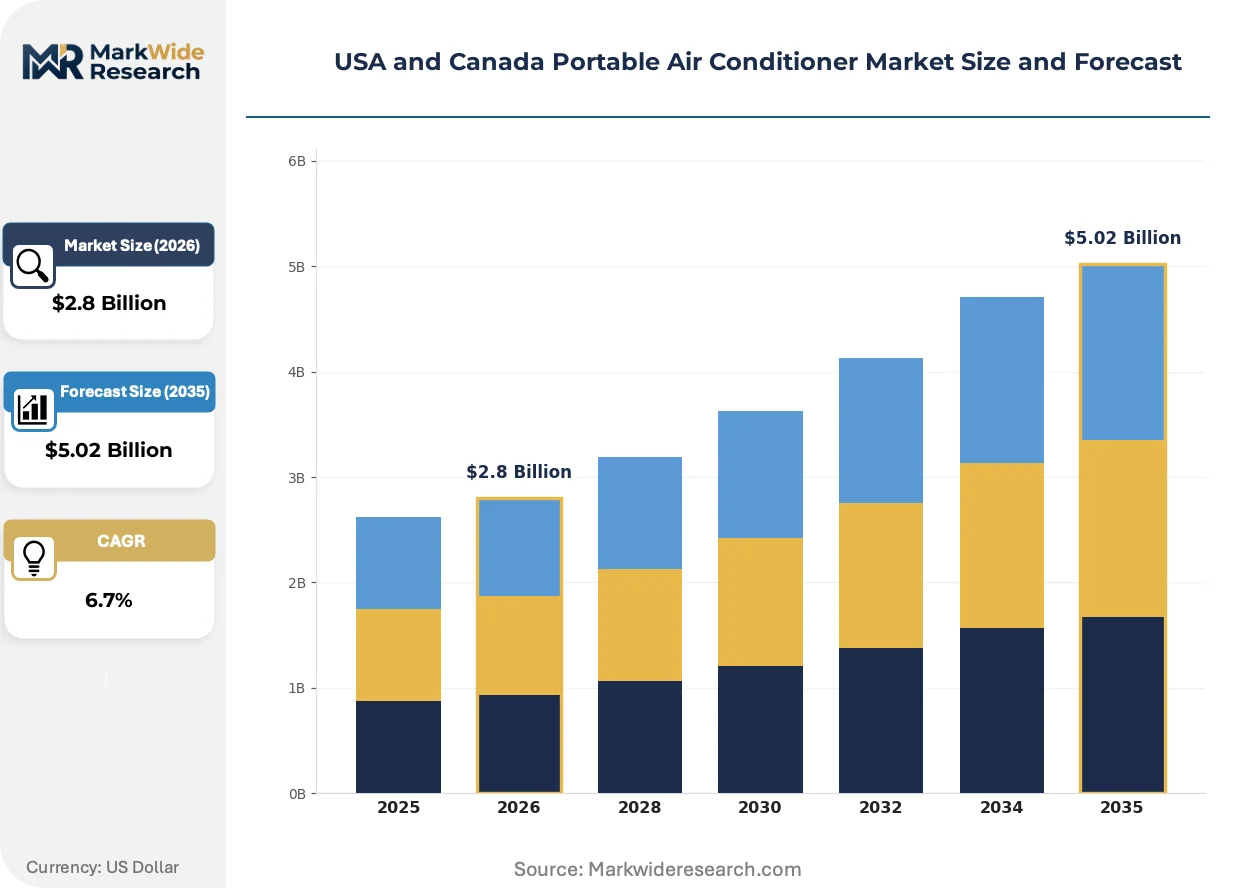
Aftermarket service revenue and filter replacement subscriptions is rewriting margin economics for portable air conditioner vendors. Whirlpool Corporation leverages its established appliance service network to capture recurring revenue from extended warranty programs. Midea Group anchors its North American position through manufacturing scale and cost-competitive dual-hose platforms sold through big-box retail partnerships.
A portable air conditioner is a self-contained, movable cooling appliance utilizing vapor-compression refrigeration with exhaust hose evacuation of condenser heat, typically rated between 8,000 and 14,000 BTU per hour and designed for spaces lacking permanent HVAC infrastructure. The primary commercial purpose is spot cooling in residential, light commercial, and supplemental industrial environments where central system installation proves impractical or cost-prohibitive. Single-hose units still occupy the largest volume tier due to lower retail price points, though dual-hose configurations are gaining structural share as energy efficiency regulations tighten. Smart portable models with Wi-Fi connectivity and voice assistant integration represent the fastest-expanding margin pool, while evaporative cooling technology remains limited to arid climate sub-regions.
The U.S. Department of Energy and Environment and Climate Change Canada jointly shape product efficiency mandates through minimum energy performance standards and seasonal energy efficiency ratio requirements. The EPA's SNAP program restrictions on high-GWP refrigerants are forcing compressor redesigns toward R-32 and R-290 alternatives. Stakeholders must monitor pending federal efficiency tier updates and provincial rebate programs to align product portfolios with compliance thresholds and consumer incentive eligibility.
Market Dynamics
The U.S. Department of Energy's amended appliance efficiency standards are compressing single-hose unit economics while accelerating variable-speed compressor adoption across manufacturer portfolios. This regulatory pressure is restructuring product development roadmaps and channel inventory composition simultaneously.
Growth Catalysts
- Multi-family housing expansion:Residential rental properties across Sun Belt states and Ontario are standardizing portable cooling as amenity infrastructure, creating baseline demand for 8,000-10,000 BTU units.
- Environment and Climate Change Canada efficiency mandates:Provincial rebate programs in British Columbia are pulling dual-hose configurations into mainstream price tiers, expanding addressable market for premium efficiency segments.
- R-32 refrigerant transition:The EPA's SNAP program restrictions on high-GWP alternatives are forcing compressor redesigns that simultaneously improve seasonal energy efficiency ratios and reduce unit weight.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger material costs swing with commodity markets, compressing margin predictability for manufacturers without captive metal supply.
- Single-hose technical ceiling:Thermodynamic limitations prevent these units from achieving DOE efficiency tier thresholds, structurally capping their market lifespan regardless of price competitiveness.
- Central HVAC substitution in new construction:Mini-split system cost declines in Texas and Arizona are narrowing the use-case for portable units in permanent residential builds.
Strategic Opportunities
- Filter replacement subscription models:Aftermarket service revenue streams are rewriting lifetime value calculations for vendors with established appliance service networks.
- Wi-Fi connectivity convergence:Smart home integration is virtualizing portable units into broader HVAC control ecosystems, opening premium pricing tiers.
- Arizona and Nevada sub-regional penetration:Underpenetrated desert metro areas with aging rental stock present white space for dual-hose efficiency messaging.
Industry Challenges
- Variable-speed compressor engineering talent scarcity:Design capabilities for inverter-driven systems concentrate among a limited supplier base, constraining rapid product portfolio pivots.
- DOE certification timeline compression:Accelerated test procedure updates are forcing simultaneous engineering and compliance investments without guaranteed market acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA and Canada Portable Air Conditioner Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Hose, Dual-Hose, Window-Mounted, Smart Portable End User: Residential, Commercial, Industrial, Healthcare Technology: Evaporative Cooling, Refrigerant-Based, Hybrid, Solar-Powered Distribution Channel: Online Retail, Home Improvement Stores, Office Supply Stores, Specialty Retailers |
| Companies Covered | Black+Decker Inc., Frigidaire Company, Whirlpool Corporation, Haier Group Corporation, Samsung Electronics, Midea Group, WHYNTER LLC, Honeywell International Inc., LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA and Canada Portable Air Conditioner Market Evolving Landscape
Refrigerant chemistry transitions and digital control architectures are converging to redefine portable air conditioner performance benchmarks and ownership economics. These shifts are compressing legacy product lifecycles while opening new margin pools for integrated solution providers.
Variable-speed inverter compressors are virtualizing fixed-speed mechanical refrigeration as the baseline technology for mid-tier and premium portable units. Multi-family property managers in Florida and Texas are specifying these systems for reduced peak load management. The technology is virtualizing traditional on-off cycling compressors into obsolescence across efficiency-regulated channels.
The EPA's SNAP program restrictions on R-410A and other high-GWP refrigerants are mandating compressor redesigns toward R-32 and R-290 alternatives. Equipment manufacturers are reconfiguring production lines to accommodate flammable refrigerant handling protocols. California and British Columbia building code jurisdictions are responding with accelerated permit pathways for compliant units.
Voice assistant and smart thermostat integration is shifting buyer preference toward app-controlled portable units with automated scheduling capabilities. Big-box retail partnerships are displacing traditional appliance specialty channels for initial purchase decisions. This behavioral pivot concentrates in Ontario and coastal California metro areas with elevated smart home penetration rates.
USA and Canada Portable Air Conditioner Market Segmentation
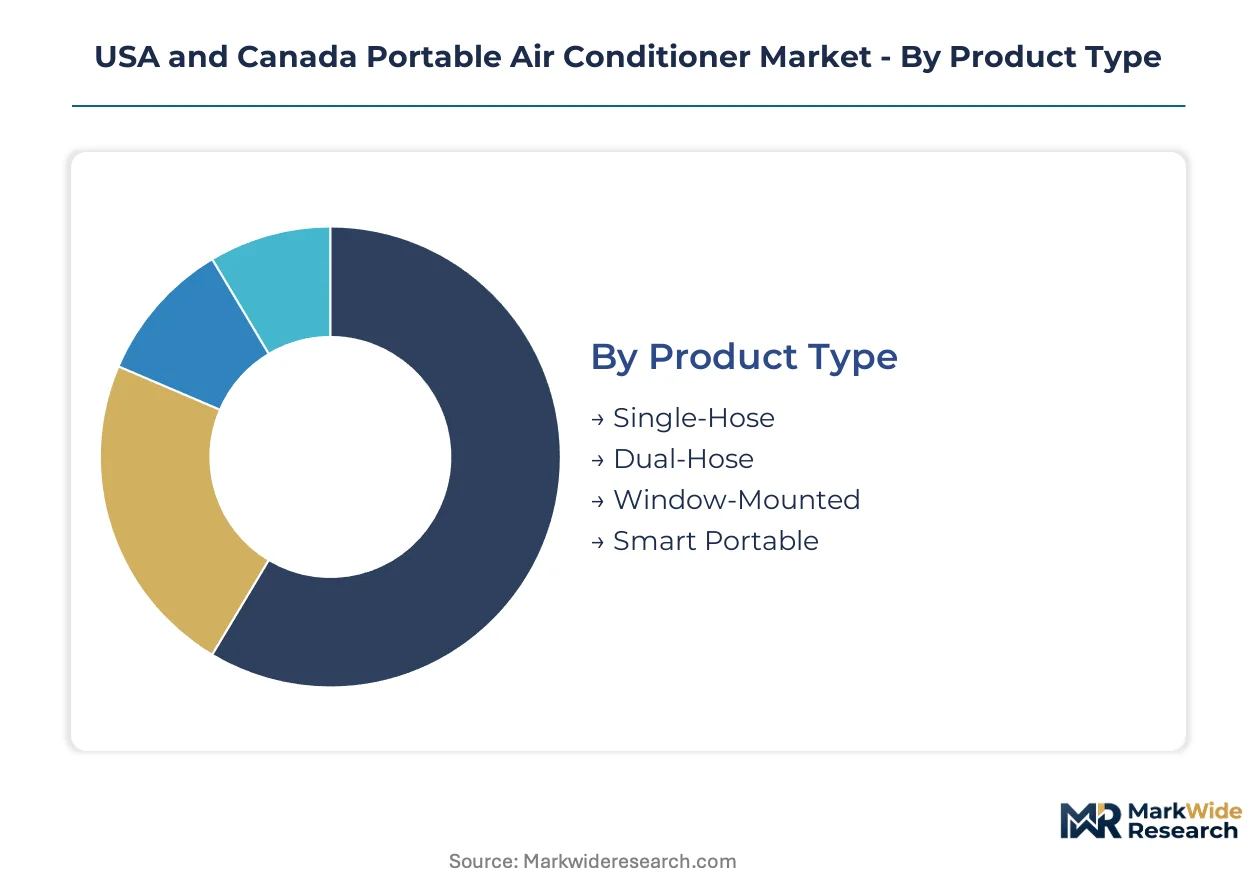
Portable air conditioner segmentation reveals how regulatory pressure, housing stock characteristics, and channel economics partition demand across distinct product configurations. Each dimension carries implications for margin structure, inventory planning, and geographic targeting within the USA and Canada.
Product Type:
Single-hose units dominate volume tiers through price accessibility, while dual-hose configurations respond to efficiency mandates in coastal markets.
- Single-Hose:These units draw indoor air across the condenser and exhaust heat through one hose, creating negative pressure that pulls warm outside air through building leaks. Demand concentrates in Texas and Arizona rental markets where upfront cost sensitivity outweighs efficiency concerns, though DOE tier thresholds now threaten channel viability.
- Dual-Hose:Separate intake and exhaust hoses eliminate negative pressure effects, delivering measurable efficiency gains in humid climates. British Columbia provincial rebates and Florida multi-family specifications are accelerating adoption in premium channels.
- Window-Mounted:Semi-permanent installation with higher BTU capacity serves aging housing stock in Ontario and Nevada where central HVAC retrofits face cost barriers.
- Smart Portable:Wi-Fi-enabled units with voice assistant integration and automated scheduling command pricing premiums in California and Ontario metro areas with elevated smart home penetration.
The dominant share belongs to Single-Hose, while Dual-Hose is closing the gap fastest.
End User:
Customer type determines BTU specification, service expectations, and replacement cycle frequency across the value chain.
- Residential:Individual households purchase 8,000-14,000 BTU units for supplemental cooling in bedrooms and home offices. Sun Belt states from Florida through Arizona generate baseline demand, with Ontario and British Columbia contributing seasonal peaks.
- Commercial:Small retail, restaurant, and office deployments require higher durability ratings and extended warranty terms. Texas and California commercial lease structures favor portable solutions over capital-intensive permanent installations.
- Industrial:Spot cooling for manufacturing floors and server rooms demands specialized filtration and higher capacity ratings, concentrated in Arizona semiconductor corridors and Ontario automotive supplier networks.
- Healthcare:Clinics and eldercare facilities specify medical-grade air filtration and precise temperature control, with demand clustering in Florida retirement communities and British Columbia long-term care expansion zones.
Residential volume leads by a substantial margin, though Commercial applications show the steepest expansion trajectory.
Technology:
Refrigerant chemistry and energy source architecture separate compliance-ready platforms from legacy equipment facing obsolescence pressure.
- Refrigerant-Based:Vapor-compression systems using R-32 or R-290 refrigerants dominate the addressable market following EPA SNAP program restrictions on high-GWP alternatives. California and British Columbia building codes now mandate these configurations for permit approval.
- Evaporative Cooling:Water-based cooling without refrigerant suits arid climates with low ambient humidity. Arizona and Nevada desert metros represent the viable addressable market, with limited applicability elsewhere.
- Hybrid:Combined refrigerant and evaporative stages optimize efficiency across variable humidity conditions, gaining traction in Texas and Ontario where seasonal humidity swings are pronounced.
- Solar-Powered:Photovoltaic-integrated units target off-grid applications and peak demand reduction in California and Arizona markets with high electricity rates and solar penetration.
Refrigerant-Based technology commands the installed base, while Hybrid configurations are gaining share fastest in mixed-humidity corridors.
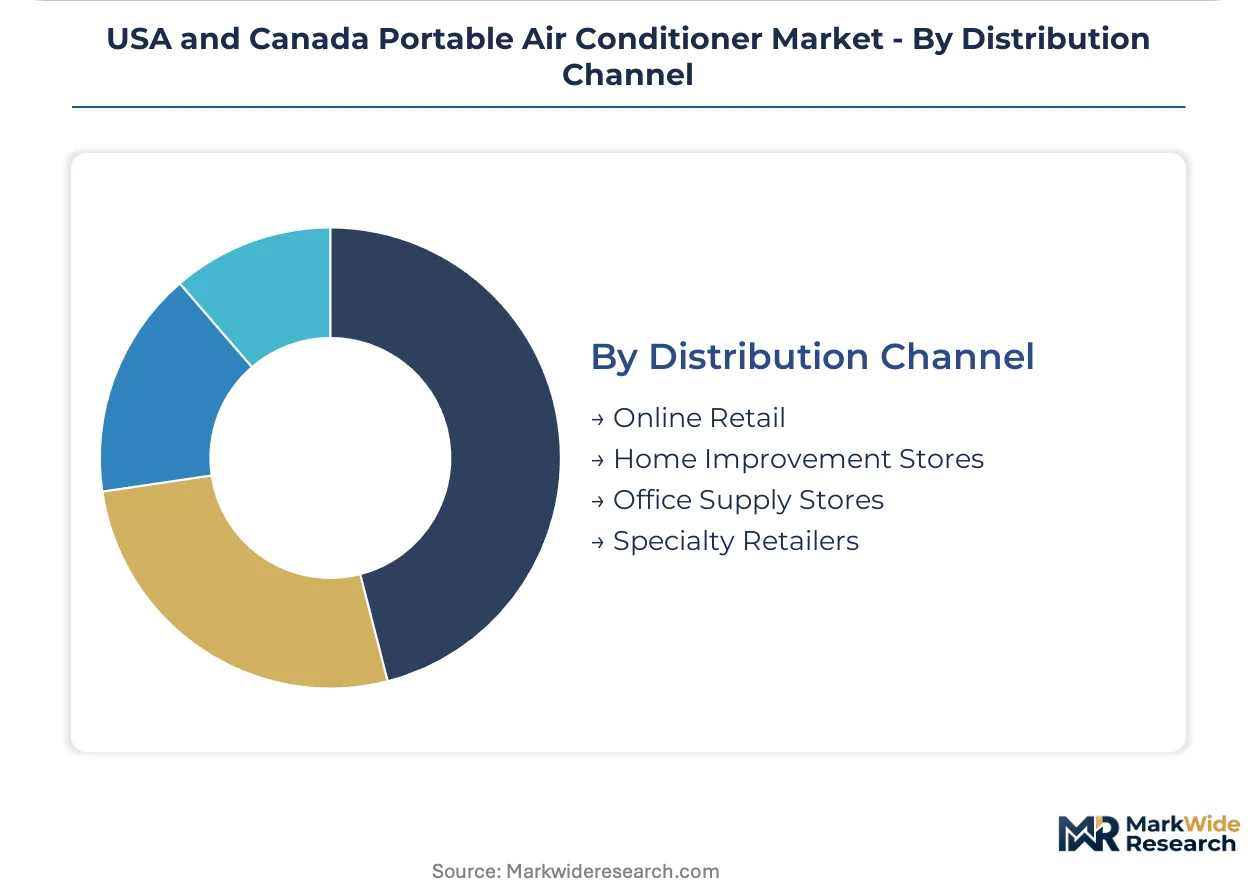
Distribution Channel:
Channel selection shapes price realization, brand positioning, and aftermarket service attachment rates.
- Online Retail:E-commerce platforms capture comparison-shopping behavior and subscription filter attachment, concentrated in Ontario and coastal California markets with high digital commerce penetration.
- Home Improvement Stores:Big-box retail partnerships drive volume for standard BTU ratings through seasonal merchandising and immediate fulfillment, dominant in Texas and Florida.
- Office Supply Stores:Commercial-grade units and bulk procurement contracts serve small business customers in Arizona and Nevada metro areas.
- Specialty Retailers:Appliance-focused channels deliver higher-touch consultation and extended warranty attachment for premium dual-hose and smart configurations, resilient in British Columbia and California.
Home Improvement Stores hold the dominant position, while Online Retail is climbing the fastest as filter subscription models rewrite customer lifetime value economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the USA and Canada Portable Air Conditioner Market. Texas and Arizona rental markets prioritize upfront affordability, while British Columbia and coastal California buyers absorb premiums for efficiency-certified units.
Texas
Multi-family housing construction in Dallas-Fort Worth and Houston generates steady demand for 8,000-12,000 BTU units as amenity infrastructure. The U.S. Department of Energy's amended efficiency standards are compressing single-hose economics and accelerating variable-speed compressor adoption among regional distributors. Austin's tech corridor exhibits elevated smart home integration rates, pulling Wi-Fi-enabled configurations into mainstream price tiers.
Florida
Humidity-driven performance requirements favor dual-hose configurations in Miami-Dade and Broward County rental markets. The EPA's SNAP program restrictions on high-GWP refrigerants are forcing compressor redesigns toward R-32 alternatives across Florida-based inventory channels. Orlando's retirement community expansion is standardizing portable cooling as healthcare facility infrastructure, creating demand for medical-grade filtration specifications.
Arizona
Desert metro areas with aging rental stock present white space for dual-hose efficiency messaging in Phoenix and Tucson. The U.S. Department of Energy's seasonal energy efficiency ratio requirements are disqualifying legacy single-hose units from rebate-eligible procurement programs. Flagstaff and Prescott sub-markets with elevated solar penetration are testing photovoltaic-integrated portable units for off-grid applications.
British Columbia
Provincial rebate programs in Vancouver and Victoria are pulling dual-hose configurations into mainstream price tiers, expanding addressable market for premium efficiency segments. Environment and Climate Change Canada efficiency mandates are accelerating R-32 refrigerant transition timelines for units sold through provincial channels. Kelowna's wine country hospitality sector is adopting portable cooling for seasonal event infrastructure, creating commercial-grade demand clusters.
Ontario
Toronto's condominium market standardizes portable cooling as supplementary infrastructure where central HVAC retrofit faces structural barriers. The country's national energy regulator maintains parallel efficiency certification pathways with U.S. DOE standards, enabling cross-border inventory fluidity. Ottawa-Gatineau's government lease structures favor portable solutions over capital-intensive permanent installations, concentrating commercial demand in the National Capital Region.
USA and Canada Portable Air Conditioner Market Competitive Landscape
Capability concentration sits with inverter engineering specialists; scale advantage sits with diversified appliance conglomerates. The vendor base organizes around three strategic tiers: full-line appliance manufacturers with established service networks, electronics specialists with smart home integration expertise, and private-label assemblers serving price-sensitive retail channels. Consolidation pressure is mounting as efficiency certification costs rise and commodity volatility squeezes margin predictability. Dominant competitive moves include backward integration into compressor supply and strategic partnerships with big-box retail for seasonal merchandising.
Among North American-headquartered manufacturers, Whirlpool Corporation and Frigidaire Company exemplify the full-line appliance archetype with established service infrastructure. Midea Group anchors the scale-driven tier through manufacturing volume and cost-competitive platform strategies. These three occupy distinct competitive positions without direct segment overlap, reducing price warfare intensity across mainstream distribution channels.
| Leading Market Players |
|---|
| Black+Decker Inc. |
| Frigidaire Company |
| Whirlpool Corporation |
| Haier Group Corporation |
| Samsung Electronics |
| Midea Group |
| WHYNTER LLC |
| Honeywell International Inc. |
| LG Electronics |
| Others |
Value Network & Pricing Analysis
Guangdong Province's compressor manufacturing clusters anchor global supply for inverter-driven systems, concentrating engineering talent and component sourcing in a tight geographic radius that shapes downstream pricing power for North American distributors. This supply concentration creates asymmetric leverage where variable-speed compressor availability directly constrains premium product rollout timelines and margin capture across the USA and Canada.
Pricing Analysis
Long-term offtake agreements dominate procurement between major retailers and Asian OEMs, insulating volume tiers from spot commodity volatility while compressing flexibility for rapid specification changes. Pricing stratifies across premium dual-hose smart configurations, standard efficiency-compliant units, and economy single-hose tiers with widening gaps driven by DOE certification tier and Wi-Fi integration bundling. Cost compression in single-hose segments is intensifying because efficiency disqualification is collapsing channel viability regardless of retail price points. Residential rental property managers in Texas and Arizona exhibit highest price sensitivity, while British Columbia rebate-eligible buyers absorb premiums for certified efficiency performance.
Supply Chain Analysis
Export-control scrutiny on advanced inverter control algorithms and semiconductor content limits technology transfer flows from certain jurisdictions, forcing North American vendors to qualify alternative controller suppliers. Manufacturing concentrates in China, Thailand, and Mexico, with heat exchanger copper and aluminum sourcing drawing from Chilean mining output and domestic U.S. smelting. Single-source vulnerability concentrates in rare-earth magnet supply for high-efficiency compressor motors. Distribution runs through big-box retail consolidation in Texas and Florida, with direct-to-consumer e-commerce gaining share in Ontario and coastal California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering capabilities for variable-speed inverter systems are scarce and geographically concentrated, creating a structural bottleneck that determines which vendors can execute efficiency-mandated product transitions. This capability gap separates consolidation winners from obsolescence casualties across the forecast window.
For Market Incumbents: Harden inverter engineering capabilities through captive recruitment or targeted acquisition of specialist design houses before talent scarcity worsens pricing power. Defend channel position by locking multi-year seasonal merchandising commitments with Home Depot and Lowe's before private-label competitors secure shelf space. Variable-speed compressor certification investment represents the critical defensive lever against DOE disqualification of legacy portfolios. For New Entrants and Emerging Players: Build out service network partnerships in Arizona and Nevada desert metros where aging rental stock and underpenetrated dual-hose messaging create white space. Target commercial lease structures in Ottawa-Gatineau and Austin tech corridors where portable cooling substitutes for capital-intensive permanent HVAC. Lead with filter subscription attachment and Wi-Fi integration as differentiated go-to-market positioning against price-driven incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because efficiency mandate acceleration is structurally capping single-hose economics while rewarding inverter engineering depth. Acquisition target archetype: mid-tier OEMs with DOE certification pipeline progress but constrained working capital for production scale-up. Watch Environment and Climate Change Canada tier advancement announcements as the signal for accelerated R-32 transition capital deployment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Variable-Speed Compressor Platform Development | DOE efficiency tier compliance locks in channel eligibility for Texas and Florida volume. |
| Filter Replacement Subscription Launch | Recurring revenue attachment rewrites customer lifetime value for Ontario digital buyers. |
| Big-Box Retail Seasonal Merchandising Partnership | Shelf space concentration in Home Depot and Lowe's secures Sun Belt state visibility. |
| R-32 Refrigerant Production Line Reconfiguration | EPA SNAP program alignment qualifies California and British Columbia permit pathways. |
| Smart Home Integration Certification | Voice assistant compatibility commands pricing premiums in Austin and Toronto tech corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with multi-family property managers, big-box retail category buyers, HVAC distribution channel heads, and compressor engineering specialists at OEMs. Secondary validation drew from U.S. Department of Energy certification databases, Environment and Climate Change Canada efficiency registry filings, EPA SNAP program refrigerant approval notices, and provincial rebate program administrative records. Bottom-up unit shipment estimates by state and province were triangulated against top-down market value reconstructions.
Calibration against historical efficiency standard implementation patterns in adjacent appliance categories anchored the projection framework across the analysis window. Segmentation dimensions modeled include product configuration, end-use application, refrigerant technology, and smart connectivity tier. CAGRs were derived from elasticity-adjusted demand curves responding to regulatory threshold timing. Forecast inputs incorporated copper and aluminum price scenario bands and multi-family housing permit velocity by metro.
Stress conditions across commodity input volatility, DOE certification timeline compression, and provincial rebate program funding levels were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding efficiency tier adoption curves and channel inventory turnover rates. Material shifts in EPA refrigerant approval timelines or Environment and Climate Change Canada mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Global Digital Thermostats Market
Energy Management Systems
United Arab Emirates Portable Air Conditioning Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
Global Data Center Energy Management Solution Market
Energy Management Systems
Building Energy Management Systems (BEMS) Market
Energy Management Systems
Asia-Pacific Home Energy Management System Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
Energy Management Systems (EMS) Market
Energy Management Systems
Meter Data Management System Market
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
Data Center Power Management Market
Energy Management Systems
Shared Power Bank Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Energy Management in Data Centers Market
Energy Management Systems
District Cooling Market
Energy Management Systems
Global Vibration Control System Market