
 India Home Ventilation System Market | 2026-2036
India Home Ventilation System Market Size, Share, and Industry Trends Forecast 2026-2036
India Home Ventilation System Market Foresight
Buyer concentration in India's home ventilation sector is shifting from individual homeowners toward large-scale apartment developers and housing societies procuring centralized systems. Daikin India Private Limited leverages its inverter-driven heat recovery technology to anchor premium project contracts in NCR and Pune. Blue Star Limited competes aggressively on retrofitting solutions for aging residential stock across tier-2 cities.
India home ventilation systems encompass mechanical and hybrid technologies that exchange stale indoor air with filtered outdoor supply, typically operating at 30-150 CFM depending on room volume and occupancy load, with heat recovery efficiency ratings between 60-85% for energy-compliant units. Exhaust fans and air purifiers dominate current volume sales, though smart ventilation systems represent the fastest-expanding margin pool as IoT-enabled humidity and CO2 sensors gain traction among eco-friendly home builders. Heat recovery ventilators remain niche due to upfront cost barriers but attract growing interest from green-certified apartment complexes seeking BEE compliance.
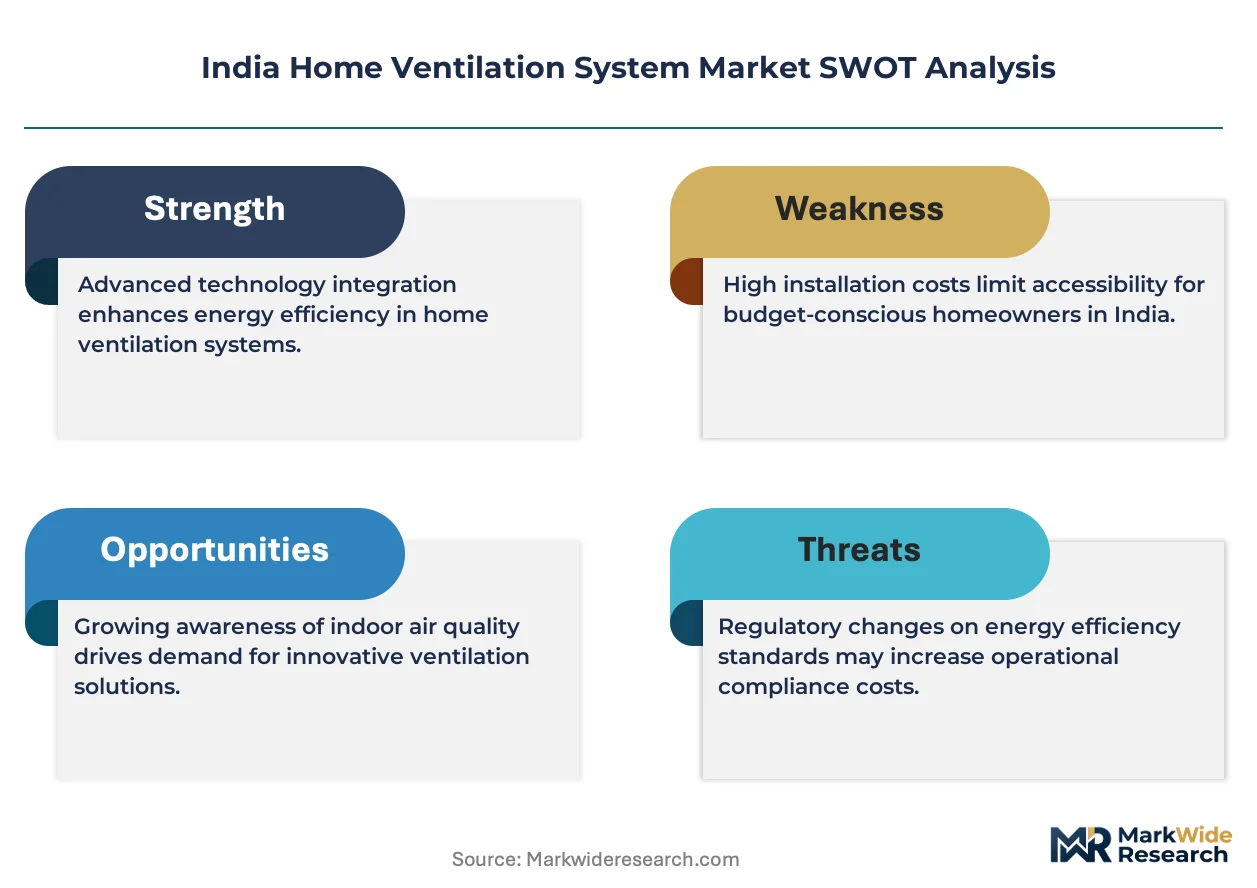
BIS certification requirements and the Bureau of Energy Efficiency's mandatory labeling standards shape product design and market access for domestic and imported ventilation equipment. State-level RERA enforcement in Maharashtra and Karnataka compels developers to specify certified ventilation in project disclosures, tightening compliance timelines. Stakeholders must monitor evolving BIS test protocols for PM2.5 filtration efficiency and acoustic performance thresholds that will determine which product portfolios remain viable.
Market Dynamics
Urban residential density in Maharashtra and Karnataka is compressing natural airflow through building envelopes, forcing mechanical ventilation from optional amenity to code-mandated infrastructure in high-rise construction.
Growth Catalysts
- BIS Energy-Efficiency Mandates:The Bureau of Indian Standards is tightening minimum performance thresholds for household appliances, compelling developers to specify certified heat recovery units in new apartment disclosures.
- RERA Enforcement:State-level real estate regulators in Maharashtra and Karnataka now require ventilation specifications in project filings, accelerating specification timelines for housing societies.
- PM2.5 Filtration Integration:Hybrid mechanical systems combining ventilation with particulate filtration are capturing specification share in Delhi-NCR and Bengaluru as ambient air quality concerns mount.
Market Restraints
- Heat Recovery Ventilator Cost Barrier:Upfront capital requirements for energy-recovery units remain prohibitive for individual homeowners outside premium apartment segments.
- Copper and Electronics Input Volatility:Heat exchanger coils and IoT sensor components expose manufacturers to commodity price swings that compress margin on mid-tier product lines.
- Exhaust Fan Substitution:Low-cost point-source extraction devices continue to dominate retrofit decisions in aging residential stock across tier-2 and tier-3 urban centers.
Strategic Opportunities
- Tamil Nadu Construction Pipeline:Chennai and Coimbatore residential permits are outpacing national averages, creating specification white space for centralized ventilation in gated community developments.
- IoT-Enabled Predictive Maintenance:Smart systems with humidity and CO2 sensors are converging with building management platforms to create recurring revenue streams for equipment suppliers.
- BEE Star Rating Differentiation:Bureau of Energy Efficiency labeling is creating tiered product positioning that rewards early certification investment with preferential developer procurement.
Industry Challenges
- Acoustic Performance Certification:Evolving BIS test protocols for noise thresholds are forcing redesign cycles that delay product launches and strain R&D timelines.
- Legacy Ductwork Integration:Retrofit installations in 1990s-era apartment stock require custom fabrication to interface with existing concrete shafts, inflating project execution complexity.
- Skilled Installation Shortage:Heat recovery ventilator commissioning demands certified technicians that remain concentrated in Mumbai, Bengaluru, and Delhi-NCR, limiting geographic expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Home Ventilation System Market |
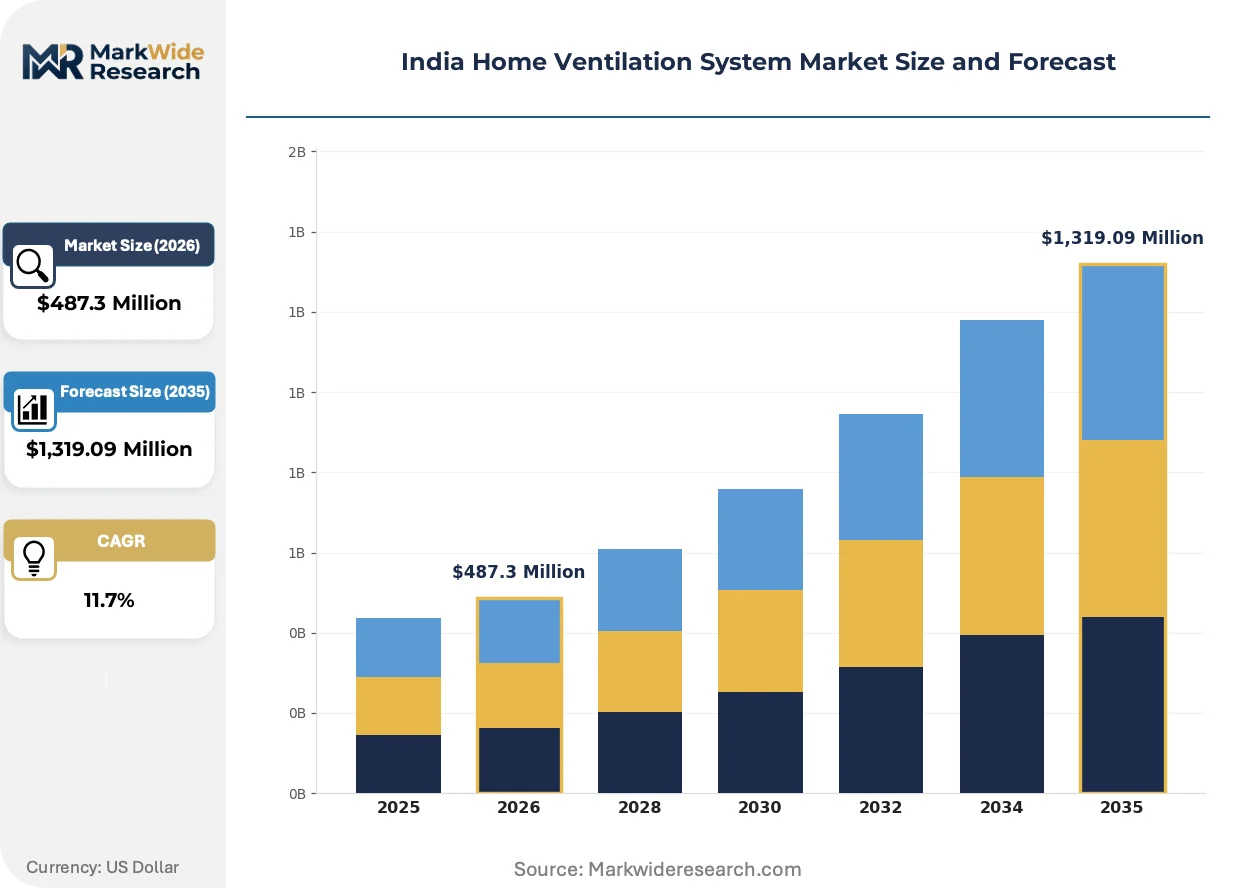
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exhaust Fans, Ceiling Vents, Air Purifiers, Heat Recovery Ventilators Technology: Natural Ventilation, Mechanical Ventilation, Hybrid Systems, Smart Ventilation End User: Residential Buildings, Apartment Complexes, Individual Homes, Eco-Friendly Homes Installation Type: New Construction, Retrofitting, DIY Installations, Professional Installations |
| Companies Covered | Haier India, Carrier Airconditioning & Refrigeration Limited, Daikin India Private Limited, Mitsubishi Electric India Private Limited, LG Electronics India Private Limited, Blue Star Limited, Samsung India Electronics Ltd., Panasonic India Private Limited, Voltas Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Home Ventilation System Market Shifts & Advancements
Mechanical ventilation is shedding its passive infrastructure status as sensor networks and energy-recovery hardware merge into intelligent climate systems that actively modulate indoor environmental quality.
Heat recovery ventilator technology is converging with building-integrated photovoltaic systems in green-certified apartment complexes. Developers in Pune and Hyderabad are specifying solar-assisted ventilation preheating to meet net-zero energy targets. This convergence is compressing payback calculations and displacing conventional exhaust-only configurations in premium project tenders.
Bureau of Energy Efficiency mandatory labeling standards are reshaping product portfolio architecture for domestic manufacturers. Compliance timelines are accelerating test laboratory bottlenecks as BIS certification queues extend. Heat recovery units bearing four-star and five-star ratings are capturing disproportionate specification share in Maharashtra and Karnataka RERA-registered projects.
Large housing societies are consolidating procurement decisions that previously fragmented across individual unit owners. Centralized maintenance contracts and bulk replacement schedules are displacing ad-hoc vendor selection in Mumbai and Bengaluru high-rises. This concentration is most visible in cooperative housing societies with 100-plus units, where annual maintenance contracts now bundle ventilation servicing with HVAC and elevator agreements.
India Home Ventilation System Market Segmentation
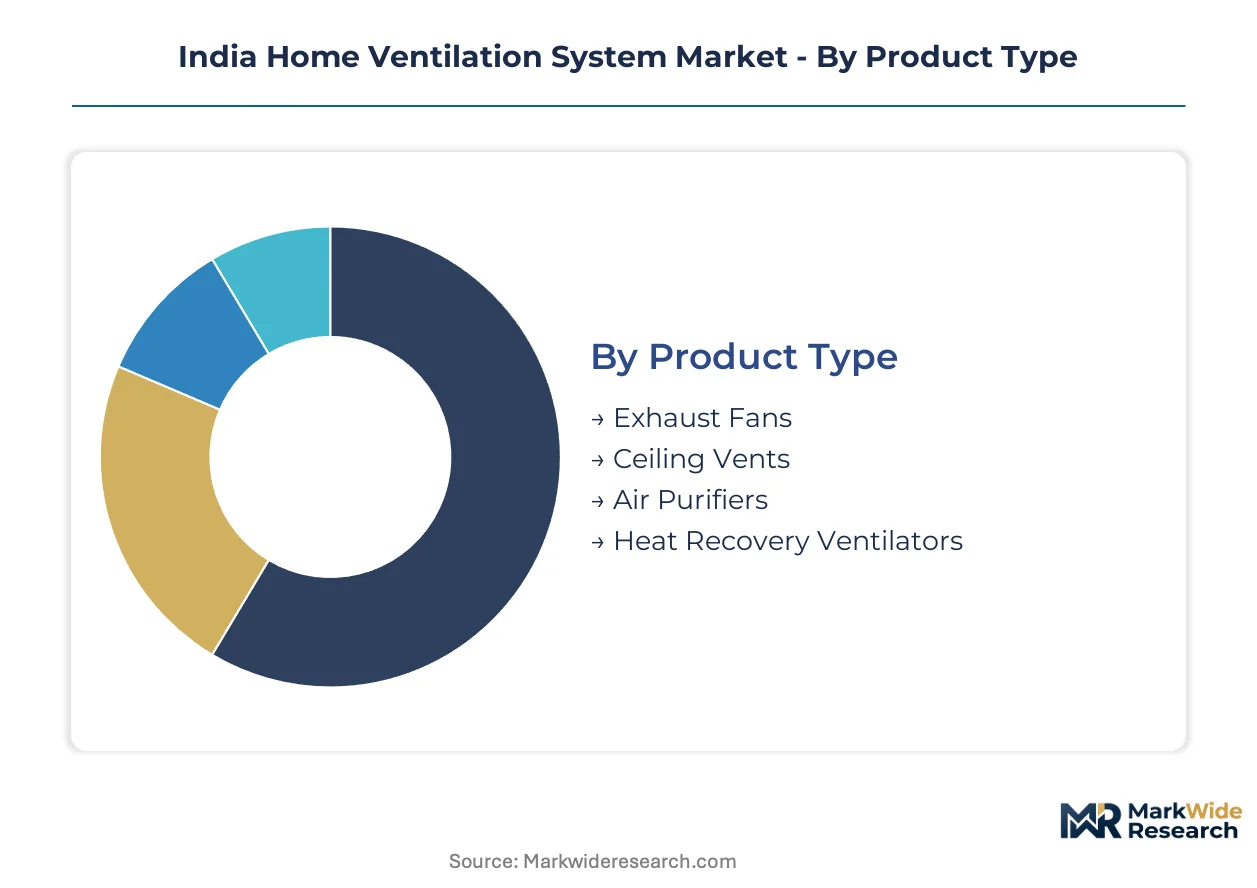
Segmentation in India's home ventilation market reveals how procurement power concentrates among large developers while technology choices fragment across price tiers and building vintages. Understanding these divides exposes where specification influence resides and which product architectures align with enforceable regulatory timelines.
Product Type:
Supply concentration in ventilation hardware tilts toward mass-market point-source devices, though project-scale procurement is pulling specification share toward integrated systems with certified performance metrics.
- Exhaust Fans:Axial and centrifugal designs dominate volume production from Gujarat and Tamil Nadu manufacturing clusters, serving tier-2 and tier-3 retrofit demand where RERA compliance pressure remains weakest. Maharashtra apartment developers now exclude these from green-certified project specifications.
- Heat Recovery Ventilators:Cross-flow and counter-flow heat exchanger configurations recover 60-85% of thermal energy from exhaust air streams, commanding specification in Karnataka and Maharashtra RERA-registered projects where BEE star ratings are mandatory disclosure items. BIS certification queues currently bottleneck import-dependent supply chains.
- Ceiling Vents:Passive grille systems with adjustable damper mechanisms serve as low-cost fresh air inlets in natural ventilation schemes across aging Mumbai housing stock.
- Air Purifiers:Standalone filtration units with HEPA and activated carbon stages address Delhi-NCR particulate concerns without addressing CO2 buildup or moisture control.
Exhaust fans absorb the bulk of installed capacity; heat recovery ventilators are expanding most quickly.
Technology:
Cost tier stratification separates commodity extraction devices from sensor-networked climate systems, with hybrid architectures capturing specification share in mid-market developments seeking BEE compliance without premium smart system price points.
- Mechanical Ventilation:Continuous supply and exhaust systems with filtered outdoor air delivery operate at 30-150 CFM depending on room volume, specified in high-rise construction across Bengaluru and Pune where natural airflow through building envelopes is structurally compromised.
- Smart Ventilation:IoT-enabled platforms with humidity, CO2, and VOC sensors modulate airflow based on real-time indoor environmental quality readings, converging with building management systems in Mumbai and Hyderabad premium apartment tenders. Recurring software subscription revenue is displacing pure hardware margin models.
- Natural Ventilation:Stack-effect and wind-driven airflow through operable windows and vents persists in low-rise construction outside RERA enforcement zones.
- Hybrid Systems:Mechanical backup integrated with natural airflow pathways offers cost-optimized compliance for mid-tier developers in Chennai and Coimbatore.
Mechanical ventilation commands current specification volume; smart ventilation is gaining share fastest among new project tenders.
End User:
Customer type concentration has shifted from fragmented individual purchases toward consolidated housing society procurement with multi-year maintenance contracts.
- Apartment Complexes:Centralized ventilation plants with ducted distribution to individual units are specified by developers in Maharashtra and Karnataka RERA filings, with 100-plus unit societies bundling maintenance with HVAC and elevator service agreements.
- Eco-Friendly Homes:Green-certified developments targeting IGBC or GRIHA ratings specify heat recovery ventilators with PM2.5 filtration as mandatory infrastructure, concentrated in Pune and Hyderabad net-zero energy pilots.
- Residential Buildings:Broad category encompassing mixed-use developments where ventilation specification varies by unit price tier within the same project.
- Individual Homes:Standalone villa and bungalow owners in Delhi-NCR and Bengaluru periphery drive demand for retrofit-compatible compact heat recovery units.
Apartment complexes absorb the bulk of installed capacity; eco-friendly homes are expanding most quickly.
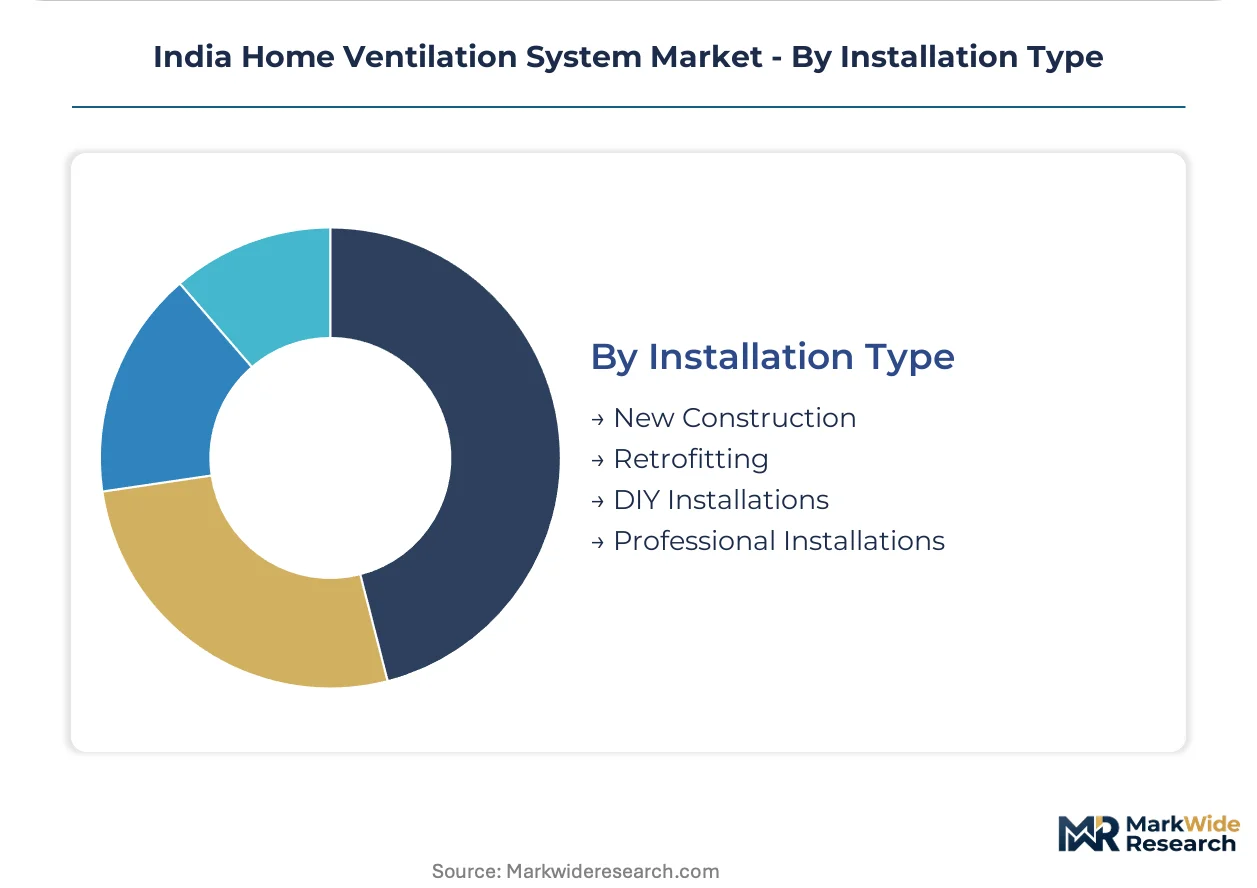
Installation Type:
Maturity divides separate new construction specification workflows from retrofit execution complexity, with skilled technician scarcity constraining geographic expansion of heat recovery ventilator deployment.
- New Construction:Integrated ductwork and equipment specification during structural build enables optimized airflow path design, capturing specification share in Tamil Nadu and Karnataka residential permits outpacing national averages.
- Retrofitting:Custom fabrication to interface with 1990s-era concrete shafts inflates project complexity in Mumbai and Delhi-NCR aging stock, limiting heat recovery ventilator penetration to premium segments.
- Professional Installations:Certified technician commissioning required for BIS-compliant heat recovery ventilator performance validation, with labor pools concentrated in Mumbai, Bengaluru, and Delhi-NCR.
- DIY Installations:Consumer-assembled exhaust fans and standalone air purifiers dominate tier-2 and tier-3 markets outside RERA enforcement corridors.
New construction absorbs the bulk of installed capacity; retrofitting is expanding most quickly among green-certified renovation projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper coil fabrication clusters in Gujarat and Tamil Nadu anchor component supply chains for heat exchanger manufacturing. These feedstock localities determine where final assembly plants locate and which states capture BEE certification investment.
Maharashtra
Mumbai's high-rise density compresses natural airflow through building envelopes, forcing mechanical ventilation into code-mandated infrastructure. RERA enforcement requires ventilation specifications in project filings, accelerating developer procurement timelines. Pune's green-certified apartment complexes specify solar-assisted heat recovery systems to meet net-zero energy targets.
Karnataka
Bengaluru's apartment construction pipeline outpaces national averages, creating concentrated demand for centralized ventilation plants. BIS energy-efficiency mandates tighten minimum performance thresholds for household appliances specified in new disclosures. Whitefield and Electronic City housing societies bundle ventilation maintenance with HVAC service agreements.
Tamil Nadu
Chennai and Coimbatore residential permits exceed national growth rates, opening specification white space for gated community developments. State-level building codes incorporate BEE star rating requirements for mechanical ventilation in high-rise construction. Sriperumbudur manufacturing corridors host exhaust fan production clusters serving tier-2 retrofit demand.
Delhi-NCR
Particulate pollution concerns drive hybrid system adoption combining ventilation with PM2.5 filtration. RERA-registered projects in Gurugram and Noida mandate certified heat recovery unit disclosure. Skilled technician concentration here enables complex retrofit commissioning that tier-3 markets cannot replicate.
Telangana
Hyderabad's premium apartment tenders specify smart ventilation with IoT-enabled CO2 and humidity sensors. BIS test protocol evolution for acoustic performance creates compliance bottlenecks delaying product launches. HITEC City and Gachibowli developments anchor specification demand for building-integrated photovoltaic ventilation systems.
India Home Ventilation System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart ventilation and IoT-enabled climate control. The market structures around three maturity tiers: diversified HVAC conglomerates with inverter technology portfolios, mid-scale specialists in retrofit-compatible compact units, and regional fabricators serving exhaust fan volume demand. Consolidation pressure concentrates specification influence among BEE-certified portfolios, while price competition fragments retrofit segments. Dominant competitive moves include backward integration into heat exchanger coil production and strategic partnerships with housing society maintenance aggregators.
Within the diversified HVAC tier, Daikin India Private Limited and Blue Star Limited exemplify contrasting positioning archetypes. Daikin anchors premium project contracts through inverter-driven technology representation, while Blue Star occupies retrofit solution positioning across aging residential stock. LG Electronics India Private Limited sits within the electronics conglomerate archetype, leveraging consumer brand recognition to penetrate individual homeowner segments outside RERA-mandated procurement channels.
| Leading Market Players |
|---|
| Haier India |
| Carrier Airconditioning & Refrigeration Limited |
| Daikin India Private Limited |
| Mitsubishi Electric India Private Limited |
| LG Electronics India Private Limited |
| Blue Star Limited |
| Samsung India Electronics Ltd. |
| Panasonic India Private Limited |
| Voltas Limited |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fabricators in Gujarat and Tamil Nadu anchor exhaust fan volume production, compressing margin pools for standardized equipment while BEE-certified specialists capture premium pricing power in RERA-mandated procurement channels across Maharashtra and Karnataka.
Pricing Analysis
Volume sales concentrate in mass-market exhaust fans where price differentiation hinges on motor efficiency grades and acoustic performance certifications, while margin pools migrate toward smart ventilation systems with IoT-enabled sensor networks. Three-tier pricing structure across premium heat recovery ventilators, standard mechanical systems, and economy exhaust devices reflects BIS compliance tiers and installation complexity. Pricing pressure stems from copper coil and electronics input volatility that squeezes mid-tier product lines. Individual homeowners in tier-2 cities exhibit highest price sensitivity, whereas housing societies with bundled maintenance contracts demonstrate lowest sensitivity to upfront capital costs.
Supply Chain Analysis
Direct-to-developer specification channels handle large-project demand for certified heat recovery ventilators, while distributor networks serve retrofit exhaust fan replacement cycles across aging residential stock. Component sourcing draws from Gujarat copper fabrication clusters, Tamil Nadu electronics assembly corridors, and imported heat exchanger cores subject to BIS certification queues. Raw material dependencies center on copper coils, IoT sensor modules, and aluminum heat exchanger fins. Single-source vulnerability in certified heat exchanger supply creates bottleneck risk for premium product lines. Distribution runs through regional HVAC wholesalers with project-specification relationships and housing society maintenance aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS energy-efficiency mandates and RERA disclosure requirements have erected a cost-of-compliance barrier that rewards early certification investment while disqualifying uncertified portfolios from specification consideration in Maharashtra and Karnataka.
For Market Incumbents: Deepen backward integration into heat exchanger coil production to insulate margin from copper price volatility and compress lead times for BIS certification queues. Expand certified technician training programs beyond Mumbai and Bengaluru to capture Tamil Nadu construction pipeline growth before skilled labor scarcity constrains geographic expansion. Priority lever: housing society maintenance contract bundling to lock in recurring revenue streams and displace ad-hoc vendor selection. For New Entrants and Emerging Players: IoT-enabled predictive maintenance platforms offer a technology-first wedge into premium apartment tenders where software subscription revenue displaces pure hardware margin models. Target Tamil Nadu gated community developments where specification white space exceeds incumbent coverage density. Go-to-market angle: solar-assisted ventilation preheating integration for Pune and Hyderabad net-zero energy pilots seeking compressed payback calculations. For Investors and Strategic Acquirers: BEE four-star and five-star rating attainment acceleration is the leading indicator that margin structure is shifting toward certified portfolios with durable specification influence. Long-term viability favors acquisition targets with established BIS test laboratory relationships and RERA-registered project track records in Maharashtra, Karnataka, and Tamil Nadu. Signal to monitor: state-level building code amendments extending BEE star rating requirements to tier-2 city construction permits.| Strategic Initiative | Industry Significance |
|---|---|
| BEE Star Rating Certification | Four-star and five-star ratings unlock preferential procurement in RERA-registered Maharashtra and Karnataka projects. |
| Backward Integration into Heat Exchanger Production | In-house coil fabrication insulates margin from copper volatility and accelerates BIS compliance timelines. |
| IoT Platform Development | Sensor-networked climate systems generate recurring software revenue in Mumbai and Hyderabad premium tenders. |
| Certified Technician Network Expansion | Labor pool extension beyond Delhi-NCR and Bengaluru enables Tamil Nadu and Telangana geographic penetration. |
| Housing Society Maintenance Bundling | Annual service contracts with 100-plus unit societies displace fragmented ad-hoc vendor relationships. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with HVAC equipment procurement managers, housing society maintenance coordinators, BIS certification laboratory directors, and real estate developer project engineers. Secondary sources encompassed BEE star rating registries, RERA project disclosure databases, Maharashtra and Karnataka state building code amendments, and copper trade flow customs documentation. Bottom-up unit shipment estimates triangulated against top-down construction permit valuations across the analysis window.
Data-stream reconciliation between equipment manufacturer shipment reports, distributor inventory positions, and developer specification disclosures informed the analytical framework. Segmentation dimensions modeled encompassed product type, technology architecture, end-user category, and installation context alongside state-level regulatory enforcement intensity. CAGRs derived from regression analysis of historical permit trajectories and BEE compliance adoption curves. Industry-specific forecast inputs included RERA registration velocity and BIS test protocol evolution timelines for PM2.5 filtration and acoustic performance thresholds.
Several conditions sit outside the modeled scope, including potential BIS protocol amendments not yet published in draft form, state-level RERA enforcement variance outside Maharashtra and Karnataka, and commodity price shock scenarios exceeding historical volatility bands. Forecasts reflect documented assumptions regarding regulatory timeline adherence and construction permit issuance continuity. Practitioners should monitor draft BIS test protocol releases and state building code amendment notices for early signals of specification requirement shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Smart Air Cleaners Market
Energy Management Systems
Global Vibration Control System Market
Energy Management Systems
United Arab Emirates Portable Air Conditioning Market
Energy Management Systems
USA and Canada Portable Air Conditioner Market
Energy Management Systems
Energy Management Systems (EMS) Market
Energy Management Systems
Global Digital Thermostats Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
Advanced Server Energy Monitoring Tools Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
Mobile Metering System Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
Bed Cooling System Market
Energy Management Systems
Smart Thermostat Market
Energy Management Systems
Building Energy Management Systems (BEMS) Market