
 Global Open IoT Platform Market | 2026-2036
Global Open IoT Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Open IoT Platform Market Foresight
The EU Green Deal is broadening procurement criteria for open IoT platforms across European industrial buyers. Microsoft Corporation leverages its Azure IoT stack to anchor enterprise deployments across manufacturing verticals. Amazon Web Services competes through edge-to-cloud integration, while Siemens AG specializes in operational technology convergence for factory floors.
An open IoT platform constitutes a standards-based middleware architecture that enables interoperability across heterogeneous devices, protocols, and cloud services through open APIs and containerized microservices. These platforms process telemetry streams, execute device provisioning, and expose data pipelines to third-party applications at latencies under 100 milliseconds for time-critical workloads. Cloud-based deployment captures the dominant margin pool as hyperscalers bundle compute with platform services, though edge computing represents the fastest-expanding segment for latency-sensitive use cases in connected transportation and industrial automation.
The European Telecommunications Standards Institute, the US National Institute of Standards and Technology, and China's Ministry of Industry and Information Technology each enforce divergent cybersecurity certification regimes that fragment platform compliance costs. The EU AI Act imposes risk-classification obligations on autonomous IoT decision systems, while NIST's IoT device cybersecurity guidance shapes federal procurement specifications. Stakeholders must monitor regulatory divergence between Brussels and Beijing as a decisive factor in platform architecture roadmaps and market entry sequencing.
Market Dynamics
The convergence of EU AI Act risk-classification mandates with GDPR privacy-by-design requirements is forcing platform vendors to rearchitect middleware stacks, creating a structural divergence between compliance-ready and legacy architectures.
Growth Catalysts
- Smart city mandates:Municipal governments in Germany, China, and the United States are embedding open IoT platforms into traffic management and energy distribution systems.
- EU Green Deal procurement criteria:European industrial buyers now require carbon-footprint transparency in platform selection, favoring open architectures with auditable data lineage.
- Edge-to-cloud latency compression:Containerized microservices processing telemetry under 100 milliseconds are unlocking time-critical workloads in connected transportation.
Market Restraints
- Fragmented cybersecurity certification:ETSI, NIST, and MIIT regimes impose divergent compliance costs that inflate platform development overhead.
- Input concentration in semiconductor supply:Taiwan-dominant advanced chip fabrication creates vulnerability for edge-computing hardware stacks.
- Legacy OT system lock-in:Proprietary industrial protocols in factory floors resist middleware abstraction, slowing platform penetration.
Strategic Opportunities
- Underpenetrated Indian manufacturing:PLI scheme incentives for industrial automation are creating first-mover openings for open platform vendors.
- 5G-TSN convergence:Time-sensitive networking over private 5G slices is enabling new deterministic control applications in automotive assembly.
- CSRD reporting mandates:EU corporate sustainability disclosure rules are driving demand for IoT platforms with embedded emissions-tracking modules.
Industry Challenges
- Embedded systems security expertise scarcity:Shortage of engineers proficient in secure boot, hardware roots of trust, and side-channel mitigation is throttling platform hardening timelines.
- Multi-jurisdiction compliance orchestration:Simultaneous GDPR, EU AI Act, and sector-specific NIS2 obligations are stretching legal-engineering bandwidth at mid-size vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Open IoT Platform Market |
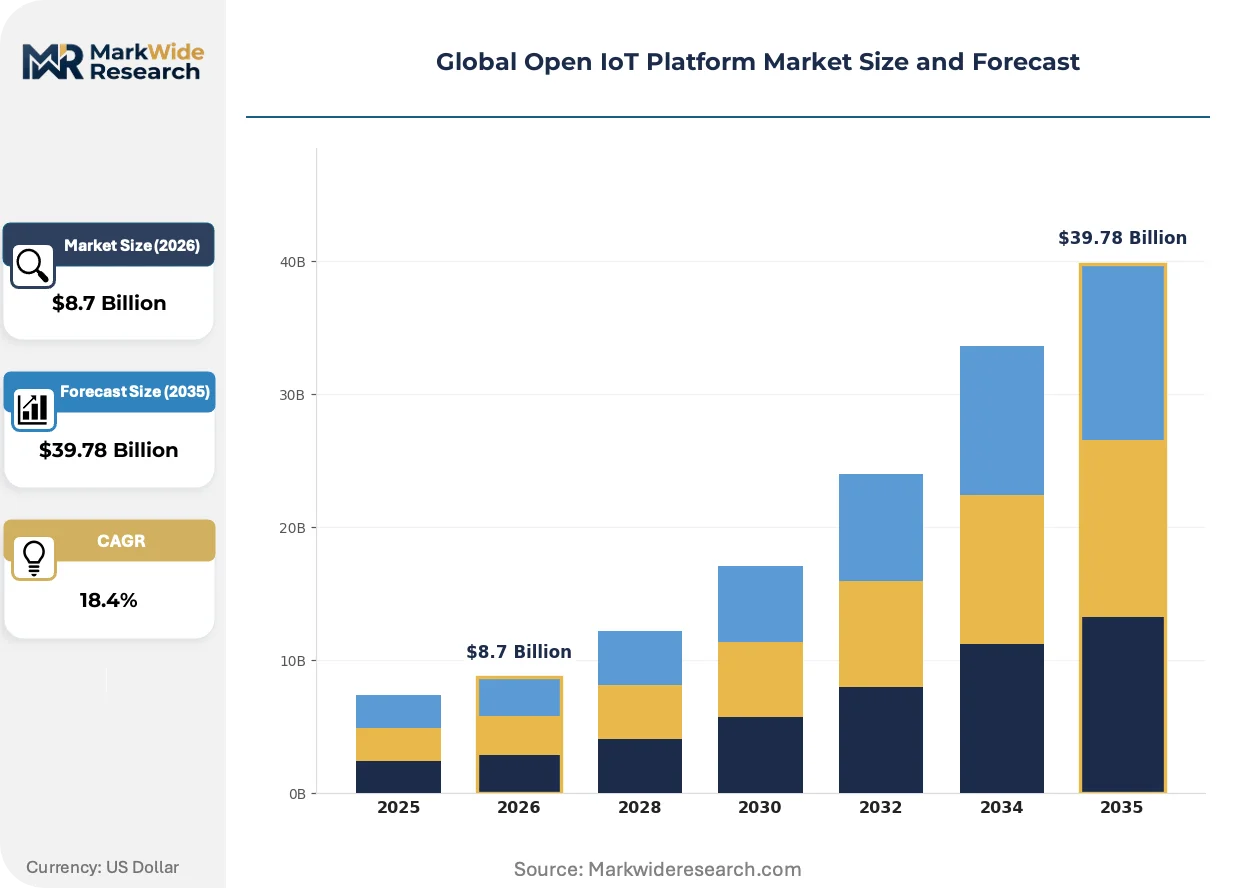
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Type: Device Management, Data Analytics, Security Management, Application Enablement Use Case: Smart Cities, Connected Transportation, Precision Agriculture, Industrial Automation End User Industry: Manufacturing, Energy Management, Retail Chains, Agriculture Enterprises |
| Companies Covered | Microsoft Corporation, Amazon Web Services, Huawei Technologies, Alibaba Group, Oracle Corporation, Cisco Systems, Siemens AG, IBM Corporation, Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Open IoT Platform Market Shifts & Advancements
Three forces are actively restructuring competitive positioning: sovereign data architectures, deterministic networking overlays, and outcome-based platform commercialization models.
Digital twin integration is electrifying platform value propositions. These virtual replicas synchronize physical asset states through real-time telemetry ingestion. Automotive OEMs and chemical processors are deploying twins for predictive maintenance and process optimization. The technology is electrifying R&D cycle compression, compressing prototype-to-production timelines from months to weeks.
REACH substance restrictions and RoHS hazardous material limits are reshaping hardware component sourcing for IoT edge devices. Platform vendors must now certify entire supply chains for restricted substance compliance. Industrial automation deployments in Germany and France are experiencing the steepest compliance cost escalation.
Subscription-based platform licensing is displacing perpetual software sales across enterprise accounts. Chief information officers prefer operational expenditure treatment for middleware budgets. German automotive suppliers and Japanese electronics manufacturers are leading this transition, with annual contract values now dominating vendor revenue mixes.
Global Open IoT Platform Market Segmentation
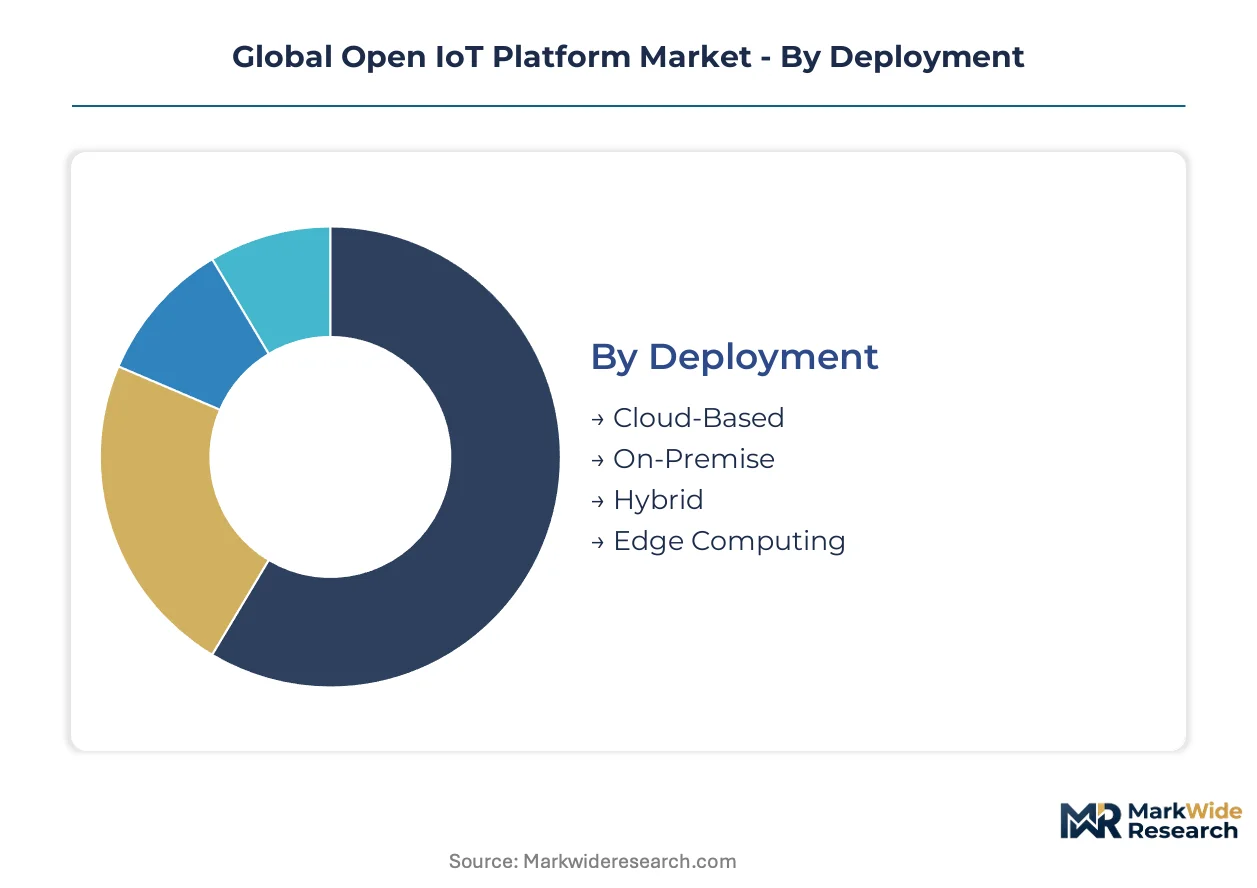
Open IoT platform segmentation reveals divergent architectural requirements across latency tolerance, data sovereignty, and operational technology maturity. Each axis shapes procurement criteria, vendor selection, and integration complexity for enterprise buyers.
Deployment:
Architectural placement determines latency profiles, compliance boundaries, and total cost of ownership for platform operators.
- Cloud-Based:Hyperscaler-hosted middleware stacks aggregate telemetry from distributed device fleets. German automotive suppliers and Japanese electronics manufacturers favor this model for centralized analytics, though GDPR data-residency clauses require EU-zone server provisioning.
- Edge Computing:Containerized microservices deploy on factory-floor gateways or vehicle-embedded hardware to process sub-100-millisecond control loops. Connected transportation systems in the United States and industrial automation clusters in China are driving capacity expansion here.
- Hybrid:Orchestration layers split workloads between edge preprocessing and cloud deep analytics. Energy management utilities leverage this architecture for real-time grid balancing combined with long-term demand forecasting.
- On-Premise:Air-gapped deployments serve defense contractors and critical infrastructure operators with strict data-sovereignty mandates. Compliance with NIST cybersecurity frameworks dominates procurement specifications.
Mature deployment sits with Cloud-Based configurations. Newer deployment is concentrated in Edge Computing.
Solution Type:
Functional module selection correlates with buyer digital maturity and legacy system complexity.
- Device Management:Lifecycle orchestration for heterogeneous sensor fleets—provisioning, firmware updates, and certificate rotation—constitutes the foundational platform layer. Manufacturing verticals in Germany and the United States treat this as table stakes for any procurement.
- Data Analytics:Stream processing and predictive model execution transform raw telemetry into operational intelligence. Precision agriculture operations in the United States and energy management utilities deploy these modules for yield optimization and demand-response algorithms.
- Security Management:Embedded encryption, anomaly detection, and zero-trust access policies address escalating ransomware exposure. EU AI Act risk-classification mandates are accelerating procurement of these modules for autonomous decision systems.
- Application Enablement:Low-code development environments and open APIs accelerate third-party solution integration. Retail chains building customer-facing IoT experiences represent the primary demand concentration.
Procurement volume clusters on Device Management. Fastest capability expansion is occurring in Data Analytics.
Use Case:
Application context dictates protocol requirements, scalability thresholds, and regulatory exposure.
- Industrial Automation:OT-IT convergence platforms bridge proprietary factory protocols with modern cloud architectures. Siemens AG and similar vendors specialize here, though legacy system lock-in slows middleware abstraction in German and Chinese manufacturing clusters.
- Smart Cities:Municipal traffic management, waste collection, and energy distribution systems require multi-tenant platforms with citizen-data privacy safeguards. GDPR and local variants shape architecture decisions across European deployments.
- Connected Transportation:Vehicle-to-infrastructure and fleet-management systems demand deterministic latency for safety-critical functions. Private 5G-TSN convergence is unlocking new control applications in automotive assembly and logistics.
- Precision Agriculture:Soil-moisture monitoring, automated irrigation, and crop-health sensing drive rural connectivity investments. The segment climbs fastest as subsidy programs in India and Brazil accelerate farm-digitization timelines.
Commercial maturity concentrates in Industrial Automation. Steepest expansion trajectory belongs to Precision Agriculture.
End User Industry:
Sector-specific compliance regimes and operational workflows fragment platform customization requirements.
- Manufacturing:Discrete and process industries deploy platforms for predictive maintenance, quality control, and supply-chain visibility. REACH substance restrictions and RoHS limits are escalating hardware certification costs for German and French automation deployments.
- Energy Management:Grid operators and renewable asset managers leverage platforms for distributed generation coordination and carbon-footprint tracking. CSRD reporting mandates are embedding emissions-tracking modules into procurement specifications.
- Retail Chains:Inventory optimization, cold-chain monitoring, and customer-analytics applications drive adoption. Subscription-based licensing models are displacing perpetual sales across this buyer segment.
- Agriculture Enterprises:Large-scale farming operations integrate satellite imagery, drone telemetry, and ground-sensor networks. India's PLI scheme incentives are creating first-mover openings for platform vendors.
Established penetration sits with Manufacturing. Emerging demand concentrates in Agriculture Enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors platform demand through its dense concentration of smart hardware OEMs and systems integrators. German industrial automation clusters and US hyperscaler headquarters complete the triangular demand structure.
United States
Connected transportation deployments and federal smart city grants drive procurement across municipal governments. NIST cybersecurity frameworks shape federal procurement specifications for critical infrastructure operators. The San Francisco Bay Area and Seattle metropolitan region concentrate hyperscaler R&D investment and enterprise platform development.
Germany
Factory-floor OT-IT convergence and predictive maintenance applications dominate industrial demand. EU AI Act risk-classification mandates and GDPR privacy-by-design requirements compel middleware rearchitecture. The Ruhr industrial belt and Baden-Württemberg manufacturing clusters lead platform integration in automotive and machinery verticals.
China
Industrial automation digitization and smart city infrastructure scale create massive deployment pipelines. MIIT cybersecurity certification regimes and dual carbon goals influence platform procurement criteria. The Yangtze River Delta and Pearl River Delta manufacturing zones drive edge-computing hardware demand for latency-sensitive control systems.
India
PLI scheme incentives for industrial automation and precision agriculture digitization open first-mover opportunities. BIS standards and TRAI connectivity regulations shape platform interoperability requirements. Maharashtra and Gujarat industrial corridors concentrate manufacturing automation deployments, while Karnataka anchors technology services integration.
Global Open IoT Platform Market Competitive Landscape
The competitive structure tilts toward hyperscaler-dominated cloud services with specialized industrial technology vendors occupying vertical niches. Cloud infrastructure providers bundle compute with platform middleware, while operational technology specialists focus on factory-floor protocol translation. Three archetypes define positioning: hyperscaler-anchored stacks, industrial OT convergence specialists, and telecommunications-integrated platform vendors. Strategic moves concentrate on edge-to-cloud orchestration partnerships and compliance-ready architecture certification.
Among US-based technology conglomerates, Microsoft Corporation and Amazon Web Services exemplify the hyperscaler archetype through cloud-native middleware aggregation. Siemens AG occupies a distinct position as an operational technology convergence specialist with deep manufacturing vertical integration. These three entities represent the structural poles around which mid-size platform vendors and regional telecommunications providers coordinate partnership strategies.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| Huawei Technologies |
| Alibaba Group |
| Oracle Corporation |
| Cisco Systems |
| Siemens AG |
| IBM Corporation |
| Google LLC |
| Others |
Supply & Pricing Matrix
EU AI Act risk-classification mandates and GDPR privacy-by-design requirements are compelling industrial buyers to demand certified middleware stacks, forcing vendors to absorb compliance engineering costs that compress margins on legacy architectures while creating premium pricing power for compliant platforms.
Pricing Analysis
Outcome-based commercialization anchored to manufacturing uptime guarantees and predictive maintenance yield improvements now dominates enterprise procurement. Three-tier pricing structure across premium, standard, and economy levels separates GDPR-EU AI Act certified stacks from legacy middleware and open-source alternatives. Price differentiation hinges on certification tier and embedded security module depth, with German automotive suppliers least sensitive to subscription escalations and Indian manufacturing clusters most responsive to per-device economics. Pricing pressure stems from hyperscaler bundling of compute with platform services, eroding standalone middleware margins.
Supply Chain Analysis
Embedded systems security engineering talent scarcity in Shenzhen and Bangalore is throttling edge-computing hardware stack expansion. Taiwan-dominant advanced semiconductor fabrication, Chinese rare-earth magnet processing, and German precision sensor manufacturing form the geographic supply concentration. Raw material dependencies span silicon wafers, gallium nitride substrates, and lithium-ion battery cells for gateway power backup. Single-source vulnerability in Taiwan semiconductor foundries poses the dominant structural risk. Distribution runs through hyperscaler marketplaces, systems integrator channels, and direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Open IoT Platform Market operates as a cost-of-compliance story where EU AI Act risk-classification obligations erect substantial barrier-to-entry moats favoring vendors with pre-certified architectures and legal-engineering bandwidth.
For Market Incumbents: Cement compliance-ready architecture differentiation by accelerating NIST cybersecurity framework certification for federal procurement eligibility and embedding hardware roots of trust through backward integration into secure element supply. Threat substitution from hyperscaler bundled offerings demands channel control reinforcement through exclusive systems integrator partnerships in German and Chinese industrial clusters. For New Entrants and Emerging Players: The price-point gap between premium certified stacks and economy-tier open-source alternatives creates viable white-space entry through containerized microservices targeting precision agriculture digitization in India and Brazil. Focus deployment model innovation on hybrid edge-cloud orchestration for energy management utilities, leveraging PLI scheme incentives as the go-to-market anchor. For Investors and Strategic Acquirers: The window for entry favors mid-size platform vendors with embedded OT protocol translation expertise and existing ETSI certification trajectories. Long-term viability centers on acquisition targets demonstrating deterministic networking integration capabilities and sovereign data architecture deployment track records. Watch 5G-TSN convergence adoption rates in automotive assembly as the inflection signal for platform value capture acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Edge-to-cloud orchestration partnerships with Siemens AG and AWS unlock manufacturing vertical penetration. |
| Regulatory Certification | EU AI Act risk-classification pre-certification creates procurement preference moat in European industrial accounts. |
| Geographic Expansion | Indian PLI scheme-aligned entry captures first-mover positioning in underpenetrated manufacturing automation. |
| Acquisition of Specialist Firm | OT protocol translation expertise addresses legacy system lock-in barriers in German factory floors. |
| Strategic Partnership | Private 5G-TSN convergence alliances with telecommunications vendors enable deterministic control applications. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and ETSI certification registries formed the secondary backbone, cross-referenced with primary interviews with platform engineering leads, industrial IT procurement officers, and systems integrator technical directors. Bottom-up device shipment aggregation and top-down enterprise middleware spend analysis enabled triangulation across deployment models and vertical segments.
Historical trendline analysis of cloud infrastructure spend and edge-computing hardware shipments informed baseline calibration across the projection horizon. Segmentation dimensions modeled encompass deployment architecture, solution type, use case maturity, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating EU AI Act compliance cost pass-through assumptions and 5G-TSN convergence penetration timelines.
Inputs from ETSI, NIST, and MIIT certification databases were available through the study window; gaps in real-time edge-computing hardware pricing introduce uncertainty bands around total cost of ownership projections. Forecasts reflect documented assumptions regarding hyperscaler bundling intensity and semiconductor supply normalization trajectories. Material deviation in Taiwan foundry utilization rates or EU AI Act enforcement timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Cellular Internet of Things (IoT) Devices Market
Internet of Things (IoT)
Consumer Internet of Things (IoT) Market
Internet of Things (IoT)
Global Satellite Enabled IoT Software Market
Internet of Things (IoT)
IoT in Energy Market
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
Asia-Pacific IoT Device Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
IoT Device Management Platform Market
Internet of Things (IoT)
Europe IoT Services Market
Internet of Things (IoT)
Internet of Things (IoT) Connected Cars Market
Internet of Things (IoT)
Mobile-Connecting Smart Objects Market
Internet of Things (IoT)
Internet of Everything Market
Internet of Things (IoT)
GCC Indoor LBS Market
Internet of Things (IoT)
Wifi IoT Market
Internet of Things (IoT)
Global IoT Managed Services Market
Internet of Things (IoT)
Internet of Things in Energy Market