
 IoT Software Market | 2026-2036
IoT Software Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Software Market Intelligence
Platform licensing revenue is tilting from perpetual on-premises contracts toward recurring cloud-based subscriptions. Microsoft Corporation leverages its Azure IoT suite to anchor enterprise accounts across manufacturing and energy verticals. Amazon Web Services competes through edge-to-cloud integration, while Siemens AG sustains dominance in industrial automation through its MindSphere platform and deep OT-IT convergence.
IoT software encompasses middleware, device management platforms, analytics engines, and security protocols that enable bidirectional data exchange between connected hardware and enterprise systems. These platforms typically process telemetry at sub-second latency thresholds while enforcing encryption standards such as TLS 1.3 across heterogeneous device fleets. Cloud-based deployment captures the dominant share of new bookings as enterprises abandon capital-intensive infrastructure builds. Industrial Automation applications generate the highest per-account value, whereas Asset Tracking segments expand fastest in logistics and cold-chain monitoring.
The EU AI Act imposes risk-classification requirements on autonomous IoT decision systems, while FDA cybersecurity guidance mandates premarket submission controls for connected medical devices. Germany's BSI and the US NIST IoT cybersecurity framework collectively shape procurement criteria for critical infrastructure operators. Stakeholders must monitor divergence between regional certification regimes when architecting multi-national deployment roadmaps.
Market Dynamics
Platform consolidation is compressing vendor margins as enterprises demand unified OT-IT stacks over fragmented point solutions. The shift from perpetual licensing to consumption-based billing is redistributing cash flow risk from buyers to software providers.
Growth Catalysts
- EU AI Act risk classification:Mandatory conformity assessments for autonomous IoT systems are creating certified software tiers that command pricing premiums from medical device and automotive manufacturers.
- Edge-to-cloud orchestration:Latency-sensitive manufacturing workloads in Germany's automotive corridor are pulling real-time analytics platforms into brownfield deployments.
- NIST IoT cybersecurity framework:US critical infrastructure operators now mandate TLS 1.3 and device attestation protocols, accelerating security module attach rates.
Market Restraints
- Semiconductor supply concentration:Edge AI chip fabrication bottlenecks in Taiwan constrain hardware-software bundle rollouts for predictive maintenance applications.
- Interoperability protocol fragmentation:Competing standards from OPC Foundation, Eclipse Foundation, and proprietary industrial consortia force vendors into redundant certification cycles.
- OT-IT skill scarcity:Manufacturing enterprises face 18-month average hiring timelines for engineers fluent in both SCADA systems and cloud-native architectures.
Strategic Opportunities
- India's PLI scheme for electronics:Contract electronics manufacturers setting up in Tamil Nadu and Karnataka require localized device management platforms with rupee-denominated pricing.
- FDA premarket cybersecurity guidance:Connected medical device submissions now require software bill of materials, opening compliance tooling revenue streams.
- Digital twin convergence with physics engines:Automotive wind tunnel simulation vendors are licensing real-time sensor feed integration for virtual validation workflows.
Industry Challenges
- Brownfield integration complexity:1970s-era programmable logic controllers in process industries lack API exposure, forcing costly protocol gateway middleware.
- Multi-jurisdiction certification timelines:Simultaneous EU AI Act, FDA, and BSI approvals extend product launch windows by 14-22 months for safety-critical applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Software Market |
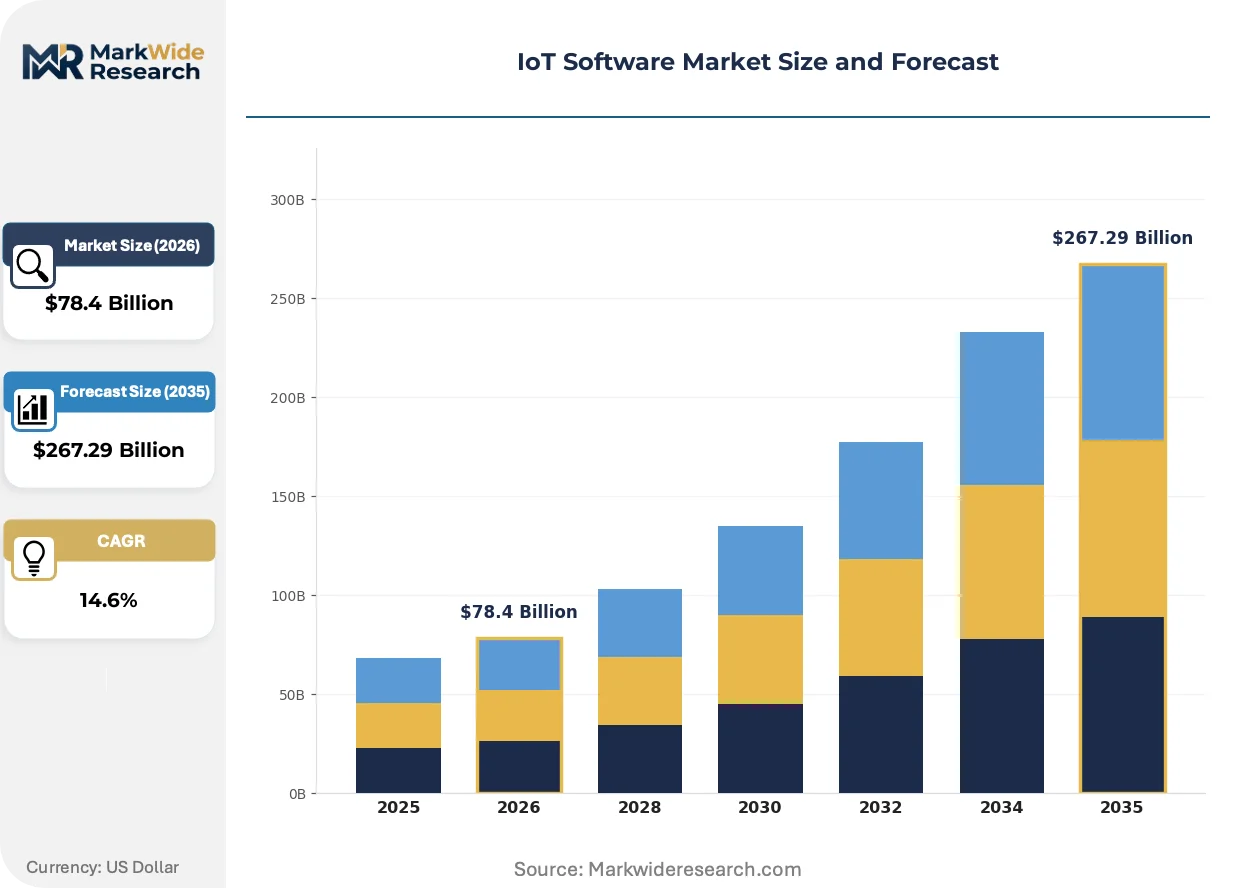
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $267.29 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Application: Smart Home, Industrial Automation, Wearable Technology, Asset Tracking End User: Healthcare Providers, Transportation Services, Retail Outlets, Manufacturing Firms Technology: Machine Learning, Blockchain, Data Analytics, Cloud Computing |
| Companies Covered | Microsoft Corporation, Amazon Web Services, IBM Corporation, Cisco Systems, PTC Inc., SAP SE, Siemens AG, Oracle Corporation, Software AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Software Market Strategic Shifts & Innovations
Software architectures are bifurcating between lightweight edge runtimes and heavyweight cloud analytics, with middleware layers absorbing most innovation investment. This structural split is forcing vendors to choose specialization depth over horizontal breadth.
Digital twin platforms are hybridizing physics-based simulation with live telemetry streams, collapsing the gap between virtual commissioning and production deployment. Siemens and Dassault Systèmes customers in automotive powertrain development are deploying these merged environments at 40% faster cycle times than siloed approaches. The compression of design-to-production feedback loops is redefining competitive moats around data latency rather than feature count.
REACH substance restrictions on persistent organic pollutants are forcing PCB and sensor manufacturers to reformulate hardware stacks, which cascades into firmware certification recertification obligations. Medical device exporters to the European Economic Area face 12-18 month material compliance validation cycles. German industrial automation vendors are responding by pre-certifying component libraries to accelerate customer system integration.
Buyer contracting preferences are fragmenting between capital-expense-averse mid-market manufacturers and long-term total-cost-of-ownership focused energy utilities. Subscription pricing with usage-based overage clauses is displacing perpetual licenses in logistics and cold-chain monitoring. This bifurcation is most visible in the US Midwest, where agricultural equipment OEMs now bundle sensor analytics into harvest-season rental agreements rather than hardware sales.
IoT Software Market Segmentation
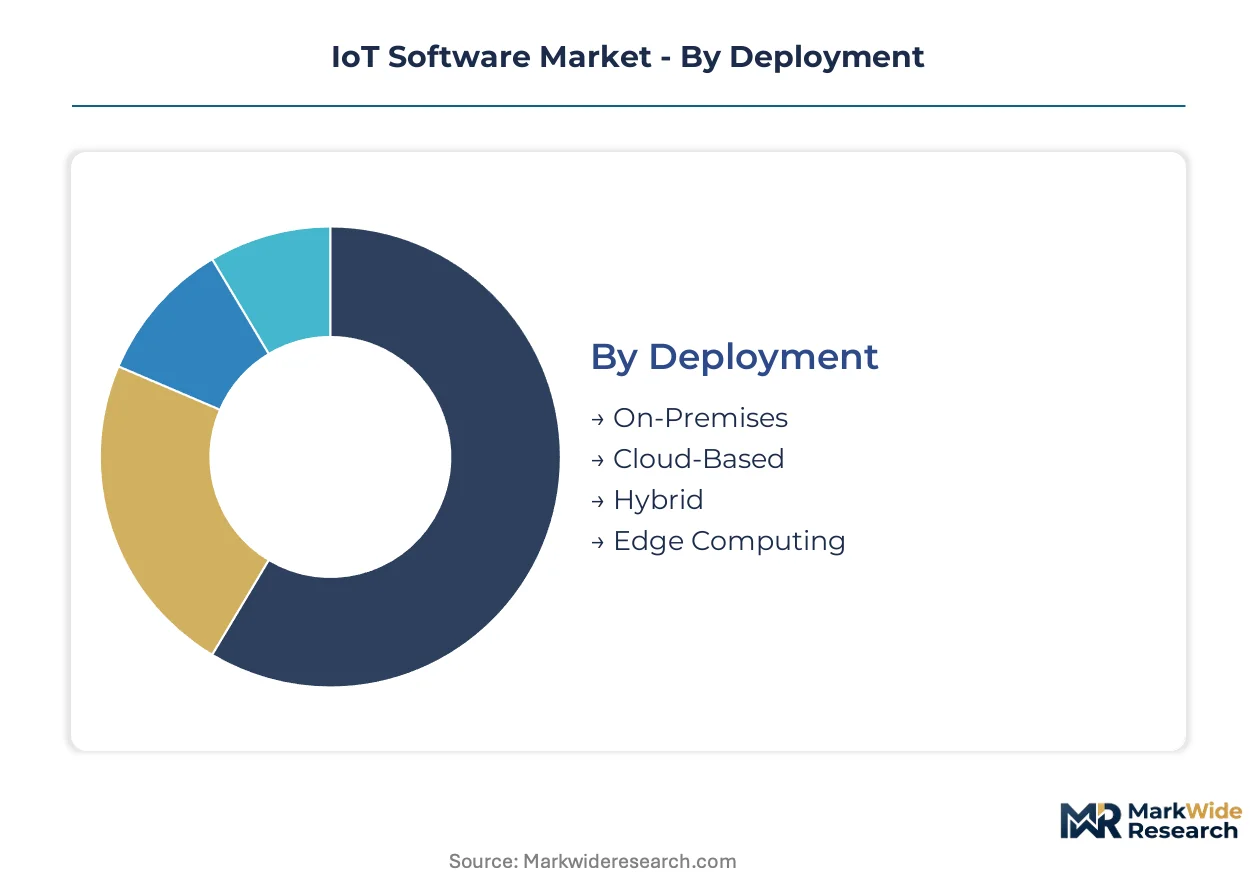
IoT software segmentation reveals how deployment architectures, application domains, and underlying technologies create distinct commercial territories with divergent margin profiles and competitive dynamics. Understanding these boundaries helps vendors calibrate R&D investment and pricing strategy against actual buyer willingness to pay.
Deployment:
Deployment mode dictates latency tolerance, data sovereignty requirements, and capital expenditure patterns across buyer organizations.
- On-Premises:Self-managed infrastructure running within buyer-controlled data centers or server rooms. Defense contractors and regulated utilities in Germany's Ruhr industrial belt favor this mode for air-gapped operational technology environments where cloud connectivity violates security protocols.
- Cloud-Based:Fully managed SaaS platforms delivering elastic compute and storage without hardware ownership. Logistics operators across India's National Capital Region are migrating fleet management workloads here to avoid monsoon-season infrastructure failures.
- Hybrid:Orchestrated workloads split between private infrastructure and public cloud tiers. Automotive manufacturers in Stuttgart deploy this architecture to keep proprietary CAD data on-premises while pushing anonymized telemetry to cloud analytics engines.
- Edge Computing:Distributed processing nodes positioned within meters of sensor arrays to minimize round-trip latency. Semiconductor fabs in Dresden use these runtimes for sub-10-millisecond defect detection on wafer inspection lines.
The dominant share belongs to Cloud-Based deployments, while Edge Computing is closing the gap fastest.
Application:
Application focus determines integration complexity, regulatory exposure, and customer lifetime value metrics.
- Smart Home:Consumer-facing platforms coordinating lighting, climate, security, and entertainment systems through unified mobile interfaces. Property developers in Spain's Costa del Sol are pre-installing these systems in vacation rental portfolios to capture recurring service fees.
- Industrial Automation:SCADA-adjacent software orchestrating programmable logic controllers, robotics, and quality inspection systems. German automotive suppliers anchor demand here, with per-account values exceeding other segments by substantial multiples due to 24/7 uptime requirements.
- Wearable Technology:Firmware and companion applications for biometric monitoring devices. Hospital networks in Paris are prescribing connected glucose monitors to diabetic patients, creating institutional procurement channels distinct from consumer retail.
- Asset Tracking:Real-time location systems for fleet vehicles, shipping containers, and high-value equipment. Cold-chain pharmaceutical distributors across the Benelux region are expanding fastest here to comply with EMA temperature excursion reporting mandates.
Industrial Automation commands the largest revenue pool, though Asset Tracking is expanding most quickly as logistics compliance tightens.
End User:
End-user verticals impose sector-specific certification requirements and procurement cycle lengths.
- Healthcare Providers:Hospitals, clinics, and home health services deploying connected diagnostic and therapeutic devices. FDA premarket cybersecurity guidance and EMA MDR compliance create dual-jurisdiction validation burdens for software vendors.
- Transportation Services:Fleet operators, railways, and aviation maintenance organizations. Germany's KBA type-approval processes for connected vehicle components add regulatory layers absent in logistics software.
- Retail Outlets:Brick-and-mortar and omnichannel merchants using inventory sensors and customer analytics. Franchise networks in Italy's Lombardy region are consolidating point-of-sale and supply chain visibility onto single platforms.
- Manufacturing Firms:Discrete and process manufacturers unifying operational and information technology stacks. Machine builders in Bavaria represent the densest concentration of demand within this category.
Manufacturing Firms generate the highest platform subscription volumes, while Healthcare Providers are deepening fastest as remote patient monitoring scales.
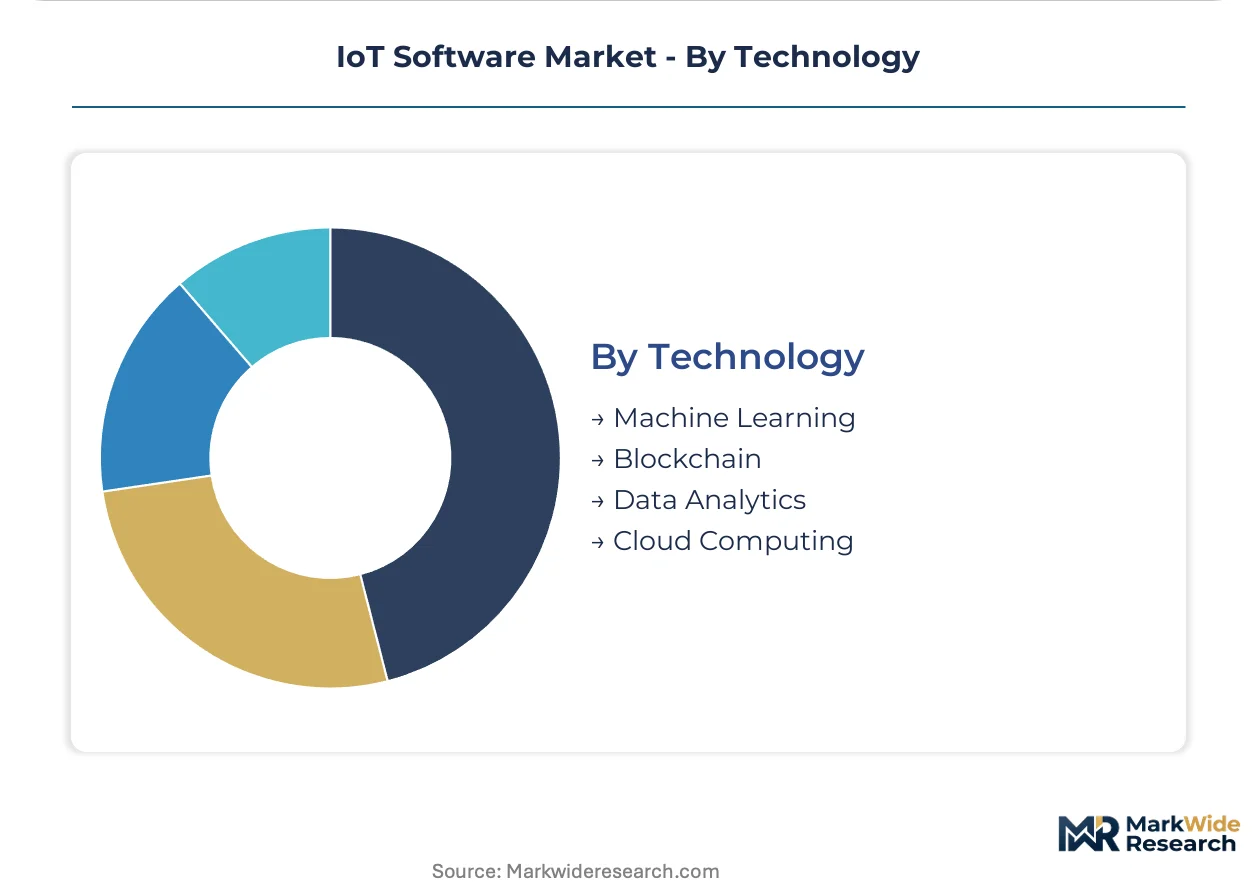
Technology:
Underlying technology stacks differentiate vendor capabilities in processing throughput and inference accuracy.
- Machine Learning:Predictive models trained on historical telemetry to forecast equipment failures or demand patterns. Wind farm operators in Denmark's Jutland Peninsula deploy these for turbine blade ice detection.
- Blockchain:Distributed ledger architectures ensuring data provenance and tamper-evident audit trails. Pharmaceutical serialization mandates in the EU are pulling this technology into supply chain verification stacks.
- Data Analytics:Batch and stream processing engines converting raw sensor feeds into operational dashboards. Municipal water utilities across the Netherlands use these for leakage detection in aging pipe networks.
- Cloud Computing:Foundational infrastructure-as-code and platform services enabling elastic resource allocation. This layer underpins all other technology deployments but is increasingly commoditized.
Data Analytics retains the broadest installed base, while Machine Learning is climbing fastest as edge AI chip availability improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud hyperscalers concentrate their IoT platform engineering in the United States and Germany, while semiconductor-dependent edge software development clusters in Taiwan and South Korea. This geographic split shapes divergent regulatory compliance burdens and procurement timelines across buyer organizations.
United States
NIST IoT cybersecurity framework mandates now govern procurement for critical infrastructure operators, pulling TLS 1.3 and device attestation into standard RFP requirements. FDA premarket cybersecurity guidance imposes software bill of materials obligations on connected medical device vendors. Seattle and Redmond anchor Azure IoT engineering density, while AWS edge-to-cloud integration teams concentrate in Northern Virginia data center corridors.
Germany
BSI technical guidelines and EU AI Act risk classifications create dual-layer compliance for autonomous industrial systems, extending certification timelines for safety-critical deployments. Stuttgart's automotive corridor drives demand for sub-10-millisecond edge analytics in powertrain manufacturing. Munich hosts Siemens AG's MindSphere development operations alongside BMW and Bosch pilot programs for brownfield OT-IT convergence.
China
MIIT industrial internet platform standards and GB/T cybersecurity certification requirements shape domestic procurement for smart manufacturing software. Dual carbon policy targets accelerate energy monitoring platform adoption in steel and cement sectors. Shanghai's Yangtze River Delta corridor concentrates demand from semiconductor fabs and battery gigafactories deploying predictive maintenance workloads.
India
PLI scheme incentives for electronics manufacturing in Tamil Nadu and Karnataka generate localized demand for rupee-denominated device management platforms. BIS IoT device security guidelines impose encryption and firmware update requirements on imported and domestic hardware. Bengaluru's technology corridor hosts engineering centers serving both domestic contract manufacturers and export-oriented automotive suppliers.
Japan
METI Society 5.0 roadmap and JIS standards for industrial IoT interoperability guide platform selection in precision manufacturing and robotics integration. Aging workforce demographics drive remote monitoring adoption in SME machine shops. Nagoya's Chubu industrial region anchors Toyota supplier network deployments of edge analytics for quality inspection and predictive maintenance.
IoT Software Market Key Industry Players
Hyperscale cloud providers and industrial automation incumbents split the market into distinct competitive spheres with minimal direct overlap. Consolidation pressure favors vendors offering unified OT-IT stacks over fragmented point solutions. Platform licensing shifts from perpetual contracts toward consumption-based subscriptions, redistributing cash flow risk. Geographic expansion and strategic partnerships constitute the dominant competitive moves as vendors chase multi-jurisdiction certification coverage.
Within the cloud-native tier, Microsoft Corporation and Amazon Web Services exemplify hyperscale platform strategies, while Siemens AG anchors the industrial automation archetype with deep OT-IT convergence capabilities. These three entities occupy positions that reflect divergent heritage advantages—enterprise software ecosystems, cloud infrastructure scale, and manufacturing domain expertise respectively.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| IBM Corporation |
| Cisco Systems |
| PTC Inc. |
| SAP SE |
| Siemens AG |
| Oracle Corporation |
| Software AG |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Taiwan's edge AI chip fabrication determines both pricing tier spreads and supply chain shape, compressing margins for predictive maintenance software bundles while forcing vendors into extended inventory financing arrangements with semiconductor distributors.
Pricing Analysis
The EU AI Act risk classification dictates the pricing tier structure across the IoT software landscape. Three-tier pricing structure across premium, standard, and economy levels separates certified autonomous systems for medical devices from uncertified monitoring tools. Price differentiation rests on BSI cybersecurity validation and TLS 1.3 protocol compliance as primary drivers. Cost compression in the economy tier is intensifying because logistics operators demand rupee-denominated SaaS subscriptions for India's PLI contract manufacturers. Mid-market manufacturers in cold-chain monitoring exhibit highest price sensitivity, whereas German automotive suppliers in Stuttgart's powertrain corridor demonstrate lowest sensitivity due to 24/7 uptime requirements.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement negotiations between software vendors and Taiwan-based edge AI chip foundries. Geographic supply concentration centers on Taiwan, South Korea, and Germany for semiconductor fabrication, industrial automation hardware, and precision sensor manufacturing respectively. Raw material dependencies draw from silicon wafers, rare earth magnets for actuator motors, and specialized PCB substrates. Single-source vulnerability in TSMC's 7nm and 5nm node capacity creates bottlenecks for hardware-software predictive maintenance bundles. Distribution runs through authorized industrial distributors in Bavaria, direct hyperscaler marketplaces for cloud-native platforms, and systems integrators for brownfield OT-IT convergence projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT software market sits in early-cycle expansion as EU AI Act compliance deadlines force medical device and automotive manufacturers into certified platform procurement before risk-classification mandates take full effect.
For Market Incumbents: Entrench dominance through pre-certifying component libraries under REACH substance restrictions and BSI technical guidelines, accelerating customer integration timelines by 12-18 months. Acquire specialized edge analytics firms in Dresden and Stuttgart to deepen OT-IT convergence capabilities against hyperscaler encroachment. Anchor enterprise accounts through multi-year consumption-based contracts that embed security module attach rates as standard features. For New Entrants and Emerging Players: Mid-market contract electronics manufacturers in Tamil Nadu and Karnataka represent the most penetrable entry point, requiring localized device management platforms with rupee-denominated pricing and BIS IoT security guideline compliance. Target FDA premarket cybersecurity tooling for connected medical devices, where software bill of materials requirements create compliance revenue streams absent incumbent saturation. Pursue strategic partnerships with Indian PLI scheme beneficiaries to embed platforms during facility commissioning rather than retrofit deployment. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors vertical specialists with deep certification expertise over horizontal generalists. Long-term viability across the next decade rests on multi-jurisdiction compliance coverage spanning EU AI Act, FDA, and BSI approval pathways. Acquisition target archetype: edge analytics vendors with existing Stuttgart automotive corridor deployments and physics engine integration capabilities. Monitor divergence between regional certification timelines as the primary inflection signal for vendor margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies OT-IT stacks for German automotive suppliers seeking brownfield convergence without hardware replacement. |
| Geographic Expansion | Establishes rupee-denominated pricing presence in Tamil Nadu and Karnataka PLI manufacturing zones. |
| Regulatory Certification Investment | Accelerates EU AI Act conformity assessment completion for autonomous medical device software tiers. |
| Strategic Partnership | Links edge analytics vendors with Siemens MindSphere ecosystem for Stuttgart powertrain manufacturing workflows. |
| Acquisition of Specialist Firm | Absorbs physics engine developers enabling digital twin convergence with live telemetry streams. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings from hyperscaler platform providers, EU AI Act implementation guidance documents, FDA premarket cybersecurity guidance releases, and BSI technical guideline updates. Interviews with CTOs at German automotive suppliers, IT procurement officers at Indian contract manufacturers, platform engineers at cloud hyperscalers, and integration specialists at industrial automation distributors informed demand-side validation. Bottom-up segmentation modeling across deployment modes, application verticals, and technology stacks triangulated against top-down market sizing from regulatory filing analysis and hyperscaler capex disclosures.
Forecast inputs span elastic compute consumption patterns, edge AI chip availability constraints, and certification timeline divergence across EU AI Act, FDA, and BSI jurisdictions. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity level, and regional adoption pattern. CAGRs derived from regression analysis against historical platform subscription bookings and projected compliance-driven replacement cycles. Physics engine licensing velocity and digital twin deployment rates in automotive powertrain development served as industry-specific demand indicators.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, euro-dollar exchange rate volatility, or India PLI scheme incentive continuity would shift the trajectory. Forecasts reflect assumptions regarding edge AI chip fabrication capacity expansion and regulatory harmonization timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Microcontroller Market
Internet of Things (IoT)
Global IoT in Automobile Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
IoT Platform Market
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
IoT Development Kit Market
Internet of Things (IoT)
IoT Smart Poles Market
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
Industrial IoT Platform Market
Internet of Things (IoT)
Smart Remote Market
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
M2M Communication Market
Internet of Things (IoT)
Narrow Band IoT Tracker Market
Internet of Things (IoT)
IoT Technology Market