
 Global Internet of Things (IoT) Defence Market | 2026-2036
Global Internet of Things (IoT) Defence Market Size, Share, and Industry Trends Forecast 2026-2036
Global Internet of Things (IoT) Defence Market Intelligence
A shift in procurement from standalone hardware to integrated, data-centric platforms by military forces is redrawing the market's competitive landscape. Thales Group leverages its deep expertise in cybersecurity and command & control systems to offer comprehensive solutions. Northrop Grumman Corporation specializes in advanced surveillance and threat detection systems that integrate extensive sensor networks. BAE Systems plc sustains its market position through robust asset tracking and maintenance management offerings for complex naval and air platforms.
Internet of Things (IoT) in defence involves a network of interconnected sensors, devices, and vehicles that collect and exchange data over secure military networks. These systems operate with low-latency protocols to ensure real-time situational awareness and decision support. Its primary function is to enhance operational efficiency, improve soldier safety, and provide a comprehensive intelligence picture. Within the technology segment, AI & Machine Learning combined with Edge Computing represents the fastest-growing area, enabling autonomous threat analysis. Cybersecurity solutions command the highest value share among offerings, reflecting the critical need to protect data integrity across all applications.
Compliance with stringent security protocols, such as the US Department of Defense's cybersecurity standards and NATO's interoperability agreements (STANAGs), is mandatory for market entry. These regulations dictate encryption levels, data handling procedures, and hardware resilience, directly shaping product development cycles. Future success for vendors depends on their ability to navigate evolving data sovereignty laws and deliver solutions that are both technologically superior and certifiably secure.
Market Dynamics
The central force shaping the market is the strategic imperative for multi-domain operations, where real-time, interoperable data from air, land, sea, space, and cyber is fused into a single common operating picture for commanders.
Growth Catalysts
- National Modernization Programs:Defence modernization initiatives in countries like the United States, India, and the United Kingdom are channeling significant investment into C4ISR (Command, Control, Communications, Computers, Intelligence, Surveillance and Reconnaissance) upgrades, directly funding IoT procurement.
- 5G and Edge Computing:The rollout of secure 5G networks and deployment of edge computing hardware enable low-latency data processing directly on military assets, facilitating faster decision-making in contested environments without relying on distant data centers.
- Enhanced Soldier Safety:Demand for improved battlefield survivability drives the adoption of wearable sensors and vehicle-integrated systems that monitor personnel health, detect environmental threats, and provide immediate alerts, enhancing situational awareness for small units.
Market Restraints
- Legacy System Integration:The immense technical difficulty and high cost of integrating modern IoT platforms with decades-old, proprietary military hardware and software systems create significant barriers to widespread adoption and slow down deployment timelines.
- Stringent Security Certification:Gaining market access requires navigating long and complex certification processes, such as adherence to US Department of Defense cybersecurity standards, which adds substantial cost and risk to product development for vendors.
- Spectrum Scarcity:Competition for and congestion of the radio frequency spectrum, essential for wireless data transmission, poses a structural constraint, particularly in dense, multi-force operational theaters where interference and jamming are prevalent threats.
Strategic Opportunities
- Autonomous Logistics:Developing IoT-enabled platforms for autonomous resupply convoys and predictive maintenance on ground vehicles and aircraft presents a significant growth area, addressing critical military needs for efficiency and reduced human risk.
- Biometric Monitoring:The integration of advanced biometric sensors into soldier uniforms and equipment offers a new frontier for monitoring real-time health, fatigue, and stress levels, providing commanders with novel data to manage force readiness.
- Digital Twin Technology:Creating virtual replicas of complex assets like naval vessels or fighter jets, fed by real-time IoT sensor data, allows for advanced simulation, predictive maintenance, and operational planning before missions are executed.
Industry Challenges
- Data Management Overload:The sheer volume of data generated by extensive sensor networks threatens to overwhelm analysts and command structures, creating a challenge to filter actionable intelligence from noise without advanced AI and automation tools.
- Interoperability Across Alliances:Ensuring seamless data sharing and system compatibility between the diverse equipment used by different nations within a coalition, such as NATO, remains a persistent operational and technical hurdle for joint operations.
- Cybersecurity Talent Gap:A critical shortage of personnel possessing deep expertise in both military operational contexts and advanced cybersecurity protocols hinders the ability of defence organizations to effectively secure and manage their expanding IoT networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Internet of Things (IoT) Defence Market |
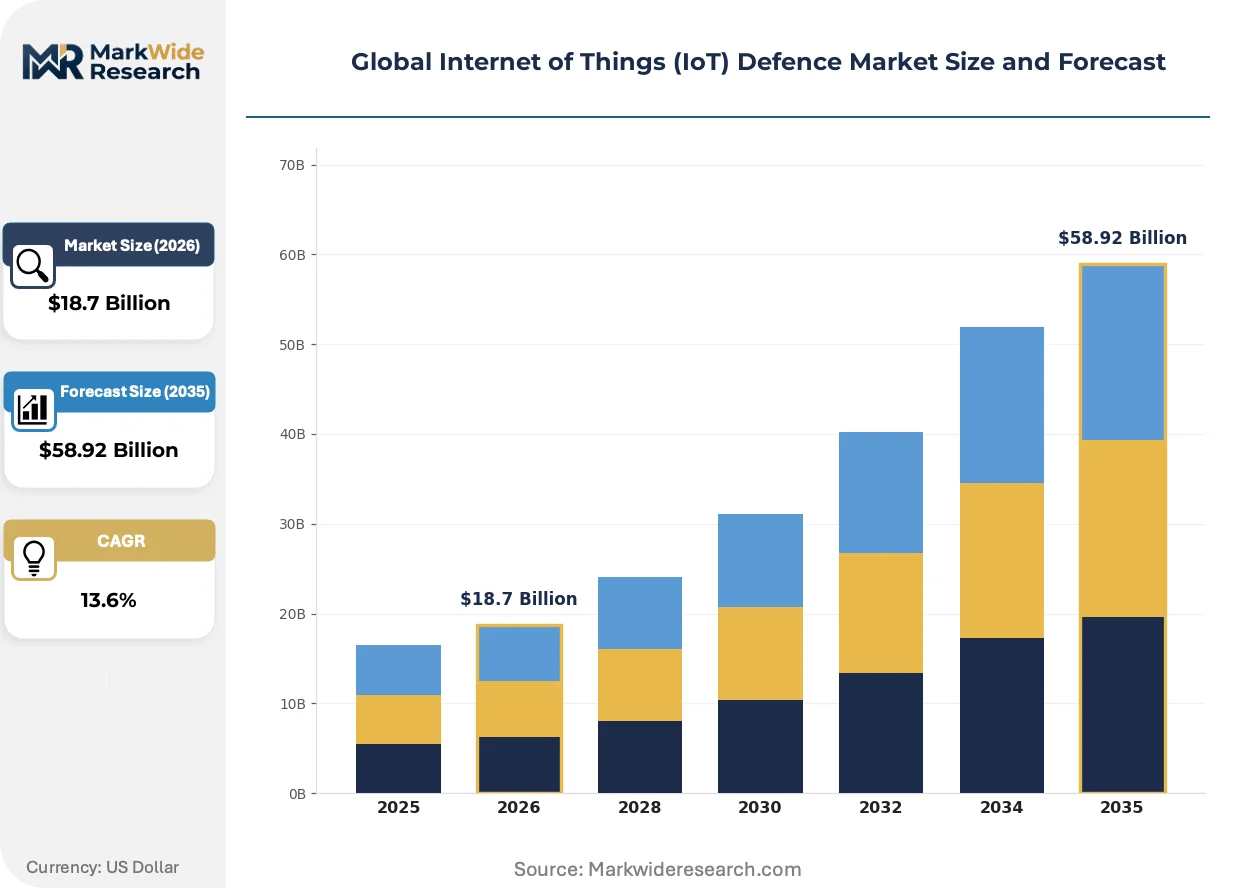
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $58.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Network Security, Data Analytics, Asset Tracking, Maintenance Management, Command & Control, Cybersecurity Technology: Edge Computing, Cloud Computing, LPWAN, Blockchain, AI & Machine Learning, 5G Connectivity Application: Surveillance Systems, Battlefield Communication, Logistics Management, Threat Detection, Equipment Monitoring, Personnel Tracking End User: Military Forces, Defense Contractors, Homeland Security Agencies, Intelligence Units |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems plc, RTX Corporation, Thales Group, Honeywell International Inc., General Dynamics Corporation, L3Harris Technologies Inc., CACI International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Internet of Things (IoT) Defence Market Strategic Shifts & Innovations
The market's evolution is defined by a determined push toward intelligent, autonomous, and resilient battlefield networks that can operate effectively even in degraded or denied communication environments, emphasizing decentralized decision-making capabilities.
Tactical edge sensors provide critical ISR capabilities for forward-deployed military units. Special operations forces and reconnaissance teams are the primary adopters, valuing their small size and low power consumption. This adoption is miniaturizing the physical profile of intelligence-gathering equipment, enabling more pervasive and less detectable sensor placement on the battlefield.
Evolving data sovereignty regulations, particularly those governing data transfers within military alliances like the Five Eyes, are a major influence. These rules mandate that sensitive operational data must be processed and stored within specific geographic or network boundaries. This directly impacts developers of cloud-based command systems, who must now engineer hybrid architectures that support localized data handling to achieve compliance.
A notable behavioral change is the move by defence agencies from procuring single-purpose hardware to acquiring holistic, data-driven capabilities as a managed service. This model replaces large, infrequent capital investments with predictable, long-term operational contracts that guarantee system performance and uptime. The shift is most advanced in logistics and asset management for large naval and air platforms in the United States and across Europe.
Global Internet of Things (IoT) Defence Market Segmentation
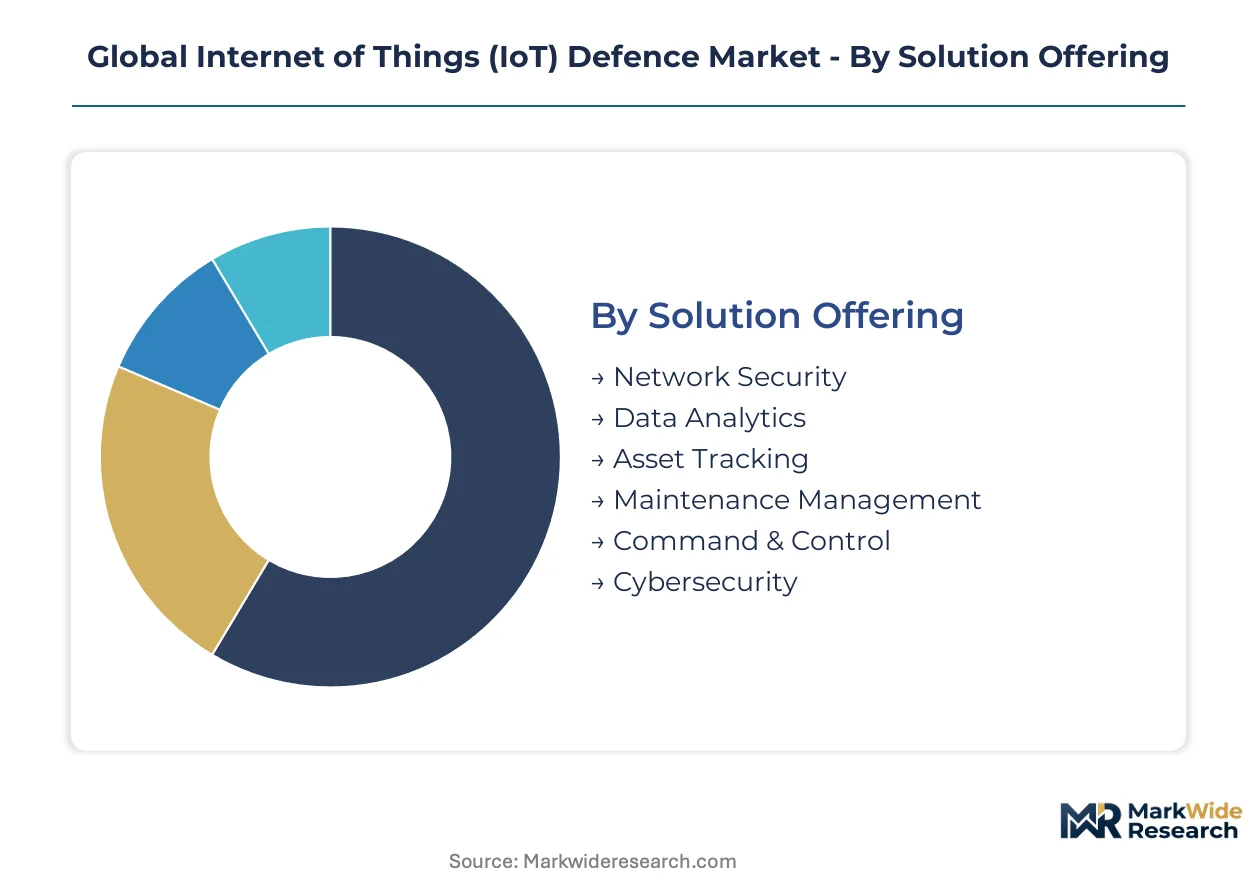
The Global Internet of Things (IoT) Defence market segmentation highlights distinct areas of technological investment and operational deployment across military applications. Understanding these segments is critical for vendors to align their offerings with specific defence modernization programs and evolving battlefield requirements.
Solution Offering:
Regulatory differentiation significantly influences the development and adoption of various IoT defence solution offerings.
- Cybersecurity:These solutions encompass robust encryption, intrusion detection, and data integrity protocols designed to protect sensitive military information and operational networks. Demand for these critical safeguards is particularly concentrated in the United States and NATO member states, driven by stringent compliance with standards like the US Department of Defense's cybersecurity frameworks.
- Command & Control:These platforms integrate data from diverse sensors and systems to provide a unified operational picture for commanders, facilitating real-time decision-making in multi-domain environments. Investment from countries like the United Kingdom and India prioritizes these systems for enhancing strategic oversight and tactical responsiveness.
- Network Security:This segment focuses on securing the underlying communication infrastructure that connects IoT devices within defence networks.
- Data Analytics:These tools process vast amounts of sensor data to extract actionable intelligence and support predictive capabilities for military operations.
- Asset Tracking:Solutions in this area provide real-time location and status monitoring for high-value military equipment and personnel.
- Maintenance Management:This offering uses IoT sensors to monitor asset health and predict maintenance needs, optimizing operational readiness and reducing downtime.
Established volume favors Cybersecurity solutions; emerging adoption favors Data Analytics platforms.
Technology:
Application focus drives the distinct development and integration of various IoT technologies within the defence sector.
- AI & Machine Learning:This technology enables autonomous threat analysis, predictive maintenance, and intelligent decision support systems, particularly for real-time processing at the tactical edge. Demand for these advanced capabilities is expanding most quickly in programs focused on autonomous operations and enhanced intelligence gathering.
- 5G Connectivity:Secure 5G networks provide the high bandwidth and low-latency communication essential for real-time data exchange between interconnected military assets. Deployment in contested environments in countries like the United States and China is accelerating for improved battlefield communication.
- Edge Computing:This technology processes data closer to its source, reducing latency and reliance on centralized cloud infrastructure for front-line operations.
- Cloud Computing:Secure cloud platforms offer scalable storage and processing power for large-scale data analysis and command functions within defence organizations.
- LPWAN:Low-Power Wide-Area Networks support long-range, low-data-rate communication for remote sensors and asset tracking applications.
- Blockchain:This distributed ledger technology provides enhanced data security and integrity for sensitive military transactions and supply chain management.
Performance drivers indicate AI & Machine Learning represents the fastest-growing trajectory, while Edge Computing underpins immediate tactical advantages.
Application:
Customer type dictates the specific implementation and scale of IoT defence applications across military operations.
- Battlefield Communication:These applications ensure secure, low-latency data exchange among deployed units, vehicles, and command centers, forming the backbone of multi-domain operations. National modernization programs in countries such as India and the United Kingdom are channeling significant investment into these systems.
- Logistics Management:IoT-enabled platforms optimize supply chains, track inventory, and facilitate autonomous resupply, reducing human risk and improving operational efficiency. The US Department of Defense prioritizes these solutions for complex global logistics networks.
- Surveillance Systems:This application leverages interconnected sensors to gather intelligence, monitor borders, and track adversary movements across various domains.
- Threat Detection:IoT devices are used to identify and classify potential threats, ranging from environmental hazards to hostile forces, providing early warnings.
- Equipment Monitoring:Sensors on vehicles, aircraft, and other assets continuously collect data on their status and performance, informing predictive maintenance.
- Personnel Tracking:Wearable devices and integrated systems monitor the location, health, and status of soldiers in the field, enhancing safety and situational awareness.
Efficiency gains are paramount for Logistics Management, while Battlefield Communication directly enhances operational effectiveness.
End User:
Volume of procurement and strategic influence shape the engagement patterns of various end-user segments in the IoT defence market.
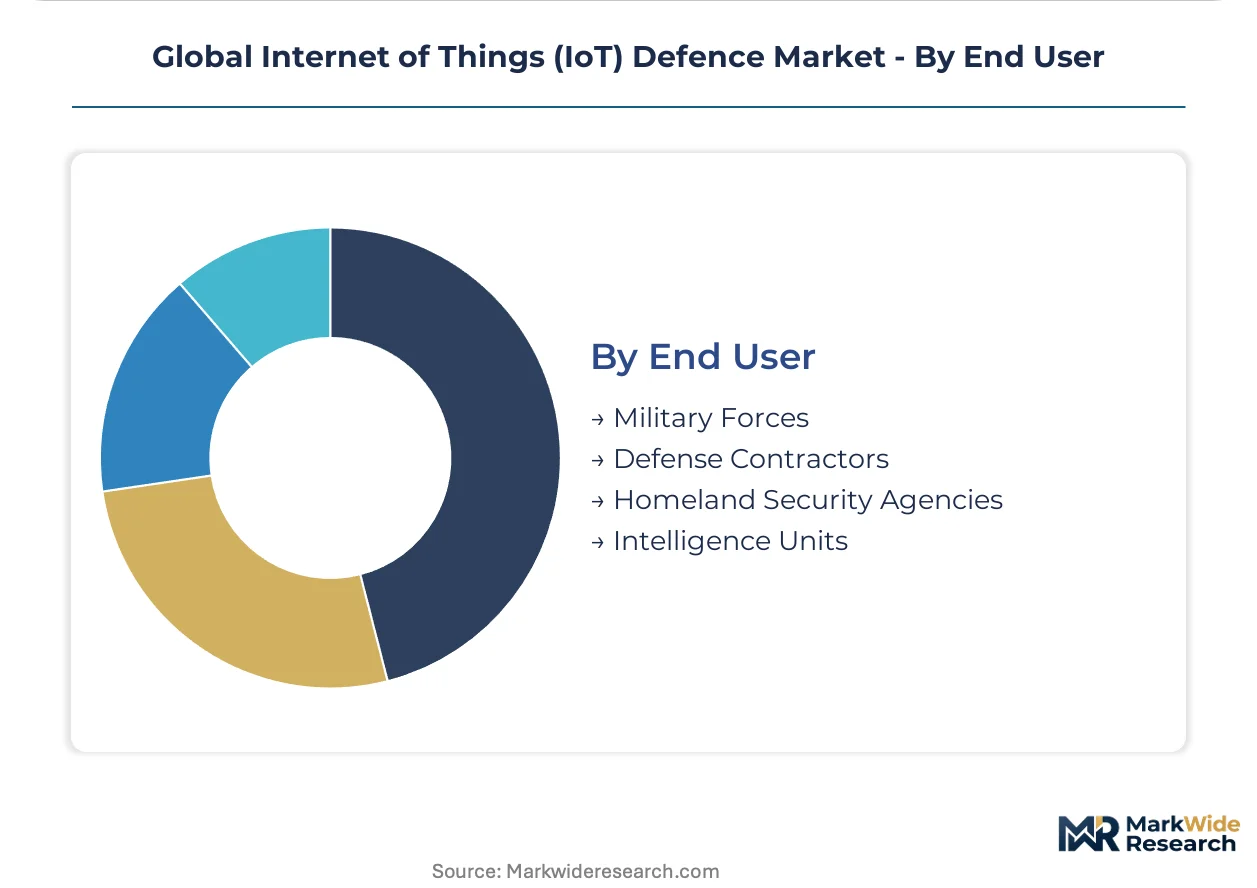
- Military Forces:These entities are the primary consumers of IoT defence solutions, integrating them into C4ISR systems, soldier modernization programs, and strategic asset management. The United States Army, Royal Navy, and Indian Air Force represent significant procurement bodies.
- Defense Contractors:These organizations develop, supply, and integrate IoT solutions for military forces, often acting as prime contractors for large-scale defence projects. Companies like Thales Group and Northrop Grumman Corporation are key players in this segment.
- Homeland Security Agencies:These agencies utilize IoT for border surveillance, critical infrastructure protection, and emergency response coordination.
- Intelligence Units:Specialized intelligence agencies deploy IoT for advanced data collection, analysis, and secure communication in sensitive operations.
Strategic importance is highest for Military Forces, with Defense Contractors serving as critical enablers for technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global secure communication networks underpin the widespread adoption of IoT defence solutions across key regions. These digital backbones enable real-time data exchange for multi-domain operations. Strategic investments in these foundational assets drive market expansion and technological integration worldwide.
United States
The United States market is driven by extensive C4ISR upgrades and soldier modernization programs. Compliance with the US Department of Defense's cybersecurity standards is mandatory for all IoT defence procurements. Defense technology innovation clusters in Northern Virginia and the Washington D.C. area foster new solution development and integration.
United Kingdom
Demand in the United Kingdom prioritizes robust asset tracking for complex naval and air platforms. NATO's interoperability agreements heavily influence product development for secure communication systems. The aerospace and defense industry hub around Farnborough and Bristol sees significant investment in IoT integration.
India
India's market expansion stems from its national modernization programs and enhanced battlefield communication needs. The country's defense procurement policy emphasizes local manufacturing and secure technology transfer for critical systems. Major defense electronics clusters in Bengaluru and Chennai are actively developing indigenous IoT solutions.
France
French defence forces require advanced command and control systems for integrated multi-domain operations. European Union data handling regulations significantly shape the development of secure cloud-based command platforms. The Paris-Saclay innovation cluster and naval base in Toulon are centers for IoT research and deployment.
Japan
Japan's demand focuses on advanced surveillance systems and maritime security applications to protect its territorial waters. The nation's defense guidelines and strict export control laws impact technology partnerships and development. Major electronics and robotics centers in Tokyo and Nagoya contribute to sensor and AI advancements.
Global Internet of Things (IoT) Defence Market Key Industry Players
Concentration sits with established defence prime contractors offering integrated solutions. The market exhibits a tiered structure, with a few large players dominating high-value, complex system integration. These dominant entities often partner with specialized technology providers for niche components. Strategic partnerships and portfolio diversification are common competitive moves to address evolving military requirements.
Within the integrated solutions provider tier, Thales Group exemplifies deep expertise in cybersecurity and command & control systems, reflecting its European origins. Northrop Grumman Corporation, a major US-based defense contractor, anchors the segment for advanced surveillance and threat detection capabilities. BAE Systems plc, a UK-headquartered multinational, maintains its position through robust asset tracking and maintenance management offerings for complex naval and air platforms, serving global defense clients.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| BAE Systems plc |
| RTX Corporation |
| Thales Group |
| Honeywell International Inc. |
| General Dynamics Corporation |
| L3Harris Technologies Inc. |
| CACI International Inc. |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized, certified IoT defence components directly influence pricing power, especially for systems requiring stringent US Department of Defense cybersecurity standards. Supply chain resilience, particularly for microelectronics and secure communication modules, critically underpins market stability and vendor competitiveness.
Pricing Analysis
Volume-discount tiering structures often characterize pricing for large-scale IoT defence procurements, reflecting the significant investment in research and development. Price differentiation stems from the level of security certification, such as NATO STANAGs, and the degree of customization required for specific military platforms. Pricing pressure stems from national defence budget constraints and the imperative for interoperable solutions across allied forces. Military Forces, particularly for mission-critical battlefield communication systems, exhibit the least price sensitivity, prioritizing performance and security over cost.
Supply Chain Analysis
Strategic stockpiling of critical, long-lead-time components for IoT defence systems is common, mitigating risks associated with geopolitical instability and export controls. Geographic supply concentration for advanced microprocessors and secure communication hardware largely resides in the United States, Europe, and specific Asian countries like Japan. The supply chain relies on specialized sensor manufacturers and encrypted data processing units. Single-source vulnerability for highly certified components represents a structural risk. Distribution runs through direct contracts with military forces and prime defence contractors, ensuring secure delivery and integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global IoT Defence market is experiencing a buyer-power shift, driven by military forces increasingly consolidating procurement towards integrated, data-centric platforms. This trend favors vendors offering comprehensive, interoperable solutions over single-purpose hardware providers.
For Market Incumbents:
Consolidate market position by acquiring specialized cybersecurity and AI/ML firms to enhance integrated solution offerings. This move addresses the threat from emerging technology disruptors and strengthens the competitive edge against new entrants. Deepen vertical integration into secure component manufacturing or invest heavily in R&D for next-generation edge computing capabilities. Control over critical certified components becomes a key lever for long-term strategic advantage.
For New Entrants and Emerging Players:
Differentiate on specialized AI & Machine Learning applications for autonomous threat analysis or advanced edge computing hardware optimized for contested environments. White-space targets include niche solutions for smaller allied nations or specific C4ISR components requiring rapid prototyping. A go-to-market angle focusing on agile development and rapid integration with existing legacy systems can penetrate segments where large prime contractors move slower.
For Investors and Strategic Acquirers:
Long-term, this sits as a critical national security infrastructure play because defence spending remains a non-discretionary budget item for major global powers. Acquisition targets should include specialized cybersecurity firms with strong certification portfolios and AI/ML analytics platforms capable of real-time intelligence processing. The signal to watch is a sustained increase in government R&D funding specifically allocated to autonomous battlefield systems or new NATO/DoD interoperability standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies diverse sensor data for multi-domain operations across military forces. |
| Cybersecurity Certification | Ensures compliance with US Department of Defense standards for market entry. |
| Edge AI Development | Enables autonomous threat analysis at the tactical edge for enhanced soldier safety. |
| 5G Network Deployment | Provides low-latency communication essential for battlefield command and control. |
| Digital Twin Investment | Enhances predictive maintenance for complex naval vessels and air platforms. |
Research Approach
The analysis maps various IoT defence sub-sectors, including cybersecurity, command & control, and battlefield communication, each validated through extensive primary interviews with defence procurement officers, systems integrators, and military strategists. Secondary validation draws from government defence budgets, military doctrine publications, technology patent databases, and defence industry reports. This approach ensures robust bottom-up and top-down triangulation of market estimates.
Consistency checks against external benchmarks validated the quantitative outputs across the analysis window. The analytical framework modeled key segmentation dimensions: solution offering, technology, application, end user, and regional defence spending. Compound annual growth rates were derived from historical trends and future investment projections tied to national modernization programs. C4ISR upgrade cycles and 5G infrastructure rollout served as critical industry-specific forecast inputs.
Material uncertainties — including geopolitical shifts or unexpected technological breakthroughs — sit outside the modeled envelope, with forecasts reflecting current assumptions. Practitioners should keep alternative scenarios live as national defence policies and global security landscapes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Integration Market
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
IoT Communication Technologies Market
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
IoT Cloud Platform Market
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
5G Internet of Things Market
Internet of Things (IoT)
Internet of Things in BFSI Market
Internet of Things (IoT)
North America IoT Node and Gateway Market
Internet of Things (IoT)
Consumer Internet of Things (IoT) Market
Internet of Things (IoT)
Global IoT Elevators Market
Internet of Things (IoT)
Global Military IoT Market
Internet of Things (IoT)
Mobile-Connecting Smart Objects Market
Internet of Things (IoT)
IoT Utilities Market
Internet of Things (IoT)
GCC Indoor LBS Market