
 IoT Middleware Market | 2026-2036
IoT Middleware Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Middleware Market Analysis
Platform bundling into modular middleware stacks is realigning how industrial buyers evaluate total cost of ownership. Microsoft leverages its Azure IoT suite to anchor enterprise deployments across manufacturing verticals. Amazon Web Services competes through edge-to-cloud continuity in transportation and logistics accounts. IBM differentiates with Watson-integrated analytics layers for healthcare compliance workloads.
IoT middleware constitutes software infrastructure that mediates data exchange between heterogeneous sensors, edge nodes, and enterprise applications, typically supporting protocol translation, message queuing, and device abstraction at latency thresholds below 100 milliseconds for time-critical operations. Its primary purpose is enabling secure, scalable interoperability across fragmented device ecosystems without requiring bespoke integration for each endpoint. Cloud-based deployment leads in new contract value as manufacturers prioritize elastic capacity over capital-intensive on-premise installations. Application enablement represents the fastest-expanding solution segment because OEMs seek pre-built analytics APIs rather than custom development cycles. Edge computing deployments are gaining share in smart city and transportation accounts where sub-second response requirements preclude round-trip cloud latency.
The EU AI Act, GDPR, and CE marking frameworks collectively mandate algorithmic transparency and data residency controls that middleware vendors must embed by design. FDA cybersecurity guidance for connected medical devices in the United States creates parallel compliance obligations for healthcare-facing platforms. Stakeholders must monitor how divergent sovereignty requirements across German BSI standards, French ANSSI certifications, and emerging Indian BIS IoT guidelines reshape product architecture roadmaps and geographic go-to-market sequencing.
Market Dynamics
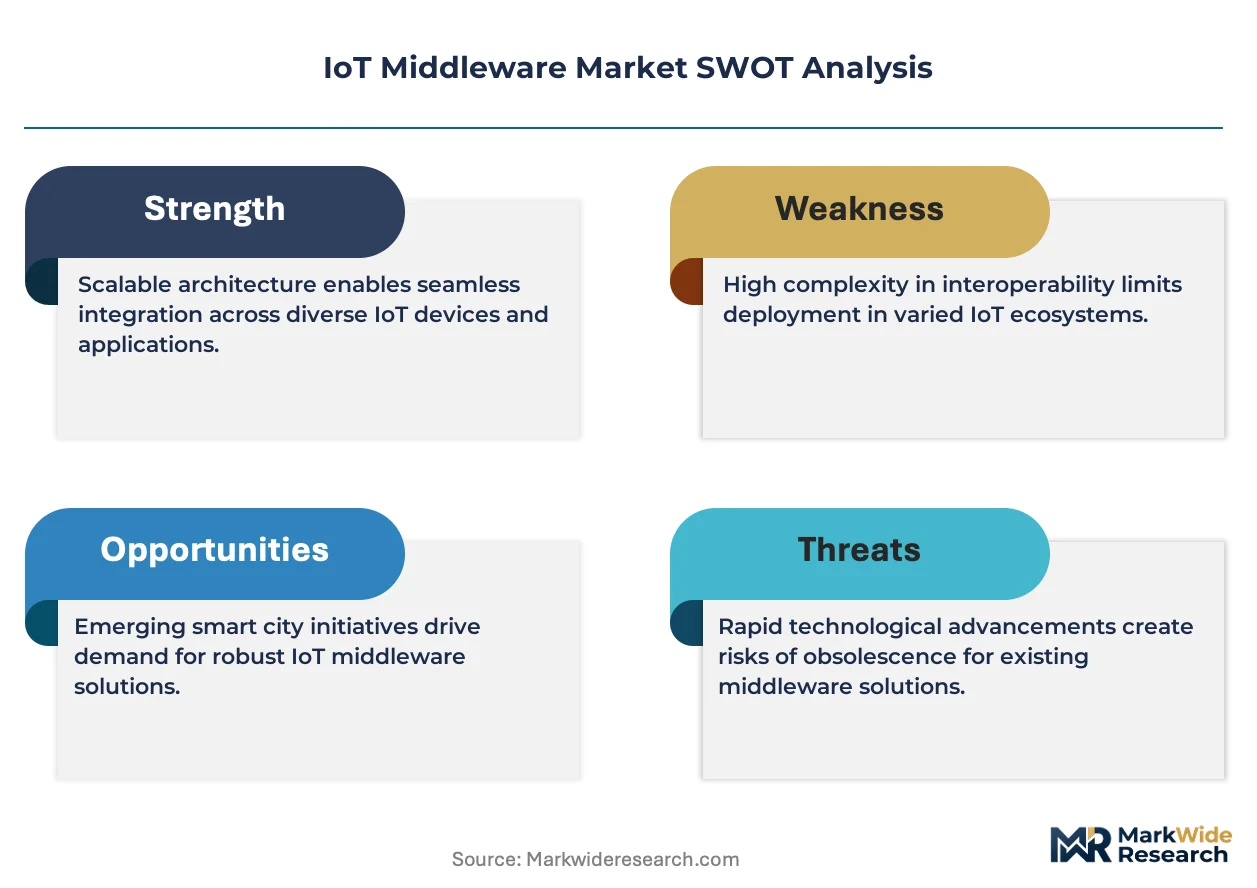
Platform bundling into modular middleware stacks is realigning how industrial buyers evaluate total cost of ownership, compressing procurement cycles from multi-year RFP processes to standardized SaaS subscriptions.
Growth Catalysts
- Industrie 4.0 Manufacturing Corridors:Germany's automotive and precision engineering clusters are mandating edge-to-cloud interoperability for supplier qualification, pulling middleware adoption through tiered supply chains.
- GDPR Algorithmic Transparency Mandates:The EU AI Act's explainability requirements are forcing municipal buyers to replace legacy black-box systems with auditable middleware layers for smart city deployments.
- Sub-100ms Latency Thresholds:Time-critical operations in autonomous logistics and predictive maintenance are eliminating direct cloud architectures, privileging distributed middleware with local protocol translation.
Market Restraints
- Semiconductor Supply Concentration:Edge node production depends on TSMC and Samsung foundry capacity, creating 12-18 month lead time volatility for hardware-dependent middleware deployments.
- CE Marking Complexity:The EU's Radio Equipment Directive and Cybersecurity Act impose overlapping conformity assessment procedures that extend European go-to-market timelines by 8-14 months.
- Substitute Protocol Stacks:Large industrial OEMs are developing in-house device abstraction layers, capturing 15-20% of addressable middleware value through captive integration teams.
Strategic Opportunities
- India BIS IoT Guidelines:Emerging mandatory certification for connected infrastructure is creating first-mover advantage for vendors establishing localized data residency architectures ahead of formal enforcement.
- Digital Twin Convergence:Middleware vendors integrating physics-based simulation APIs with real-time sensor streams are unlocking premium pricing in aerospace and energy asset management.
- Healthcare Compliance Workloads:FDA cybersecurity guidance for connected medical devices is generating demand for middleware with pre-validated 510(k) documentation packages.
Industry Challenges
- Embedded Systems Engineering Talent:Shortage of engineers fluent in both real-time operating systems and cloud-native architectures is constraining vendor delivery capacity and inflating implementation costs.
- Multi-Standard Certification Burden:Simultaneous compliance with German BSI IT-Grundschutz, French ANSSI CSPN, and IEC 62443 industrial security standards fragments R&D resources across non-harmonized requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Middleware Market |
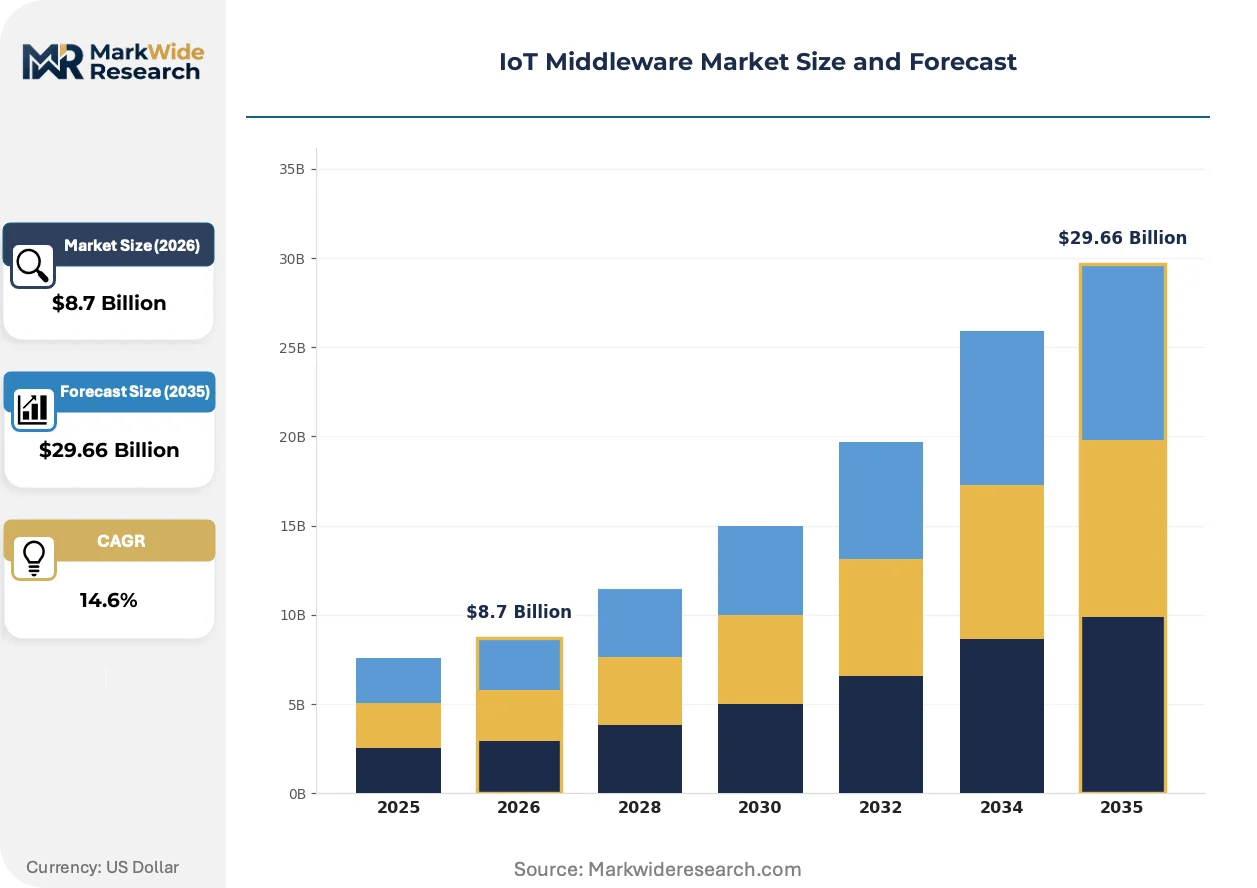
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution: Data Management, Device Management, Connectivity Management, Application Enablement End User: Manufacturing, Transportation, Healthcare, Smart Cities Technology: MQTT, CoAP, HTTP, WebSockets |
| Companies Covered | Microsoft, Amazon Web Services, IBM, Cisco Systems, PTC, Google, Oracle, SAP, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Middleware Market Emerging Trajectories
Middleware architectures are fragmenting from monolithic platforms into composable service meshes, enabling buyers to license discrete capabilities rather than absorbing bundled overhead. This decomposition is accelerating vendor specialization and reshaping competitive moats.
Containerized middleware is modularizing deployment topologies across manufacturing floors. Kubernetes-based orchestration layers now abstract device connectivity, message queuing, and security policy enforcement into independently scalable microservices. Automotive OEMs in Stuttgart and Wolfsburg are piloting these architectures for multi-factory standardization, compressing integration timelines from 18 months to 90-day sprints.
The EU AI Act's risk-based classification system is forcing algorithmic documentation into middleware stacks. High-risk applications in biometric monitoring and critical infrastructure must embed model cards, training data provenance, and human oversight interfaces by design. Healthcare middleware vendors serving European hospitals are restructuring product roadmaps around these transparency requirements, prioritizing audit trail completeness over feature velocity.
Industrial buyers are consolidating vendor relationships around outcome-guaranteed service tiers. Rather than licensing seat counts or data volumes, municipal procurement teams in Barcelona and Singapore are negotiating uptime-backed contracts with penalty clauses for latency breaches. This transfer of operational risk to vendors is compressing margins for pure-software players while favoring integrated hardware-software providers with direct control over edge infrastructure.
IoT Middleware Market Segmentation
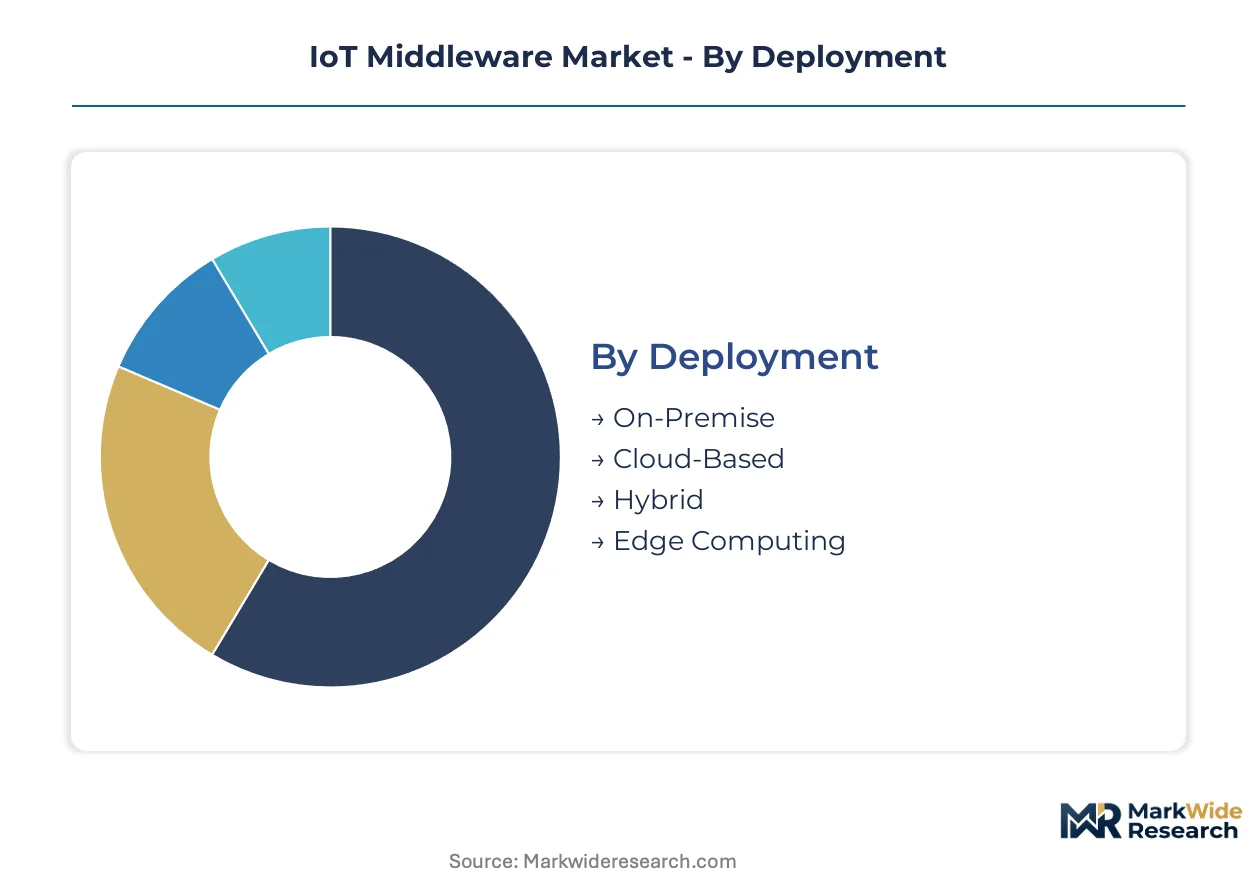
IoT middleware procurement patterns diverge sharply across deployment topologies and solution architectures. Buyers prioritize latency thresholds, compliance mandates, and integration complexity when selecting segment combinations. Understanding these trade-offs reveals where vendor differentiation concentrates and pricing power accumulates.
Deployment:
Cost tier separates buyers in this category, with capital intensity and operational control driving divergent procurement strategies.
- Cloud-Based:Elastic capacity provisioning eliminates upfront infrastructure spend. Manufacturing corridors in Germany and municipal buyers in Singapore are standardizing on SaaS subscriptions to compress procurement cycles from multi-year RFPs to quarterly renewals.
- Edge Computing:Distributed processing nodes enable sub-100ms protocol translation without round-trip cloud latency. Autonomous logistics networks and predictive maintenance systems in Stuttgart automotive clusters mandate this architecture for time-critical operations.
- On-Premise:Captive data residency satisfies GDPR algorithmic transparency mandates for European healthcare providers.
- Hybrid:Workload portability between local nodes and cloud bursts appeals to tier-one suppliers managing volatile demand.
Cloud-Based deployments lead volumes today; Edge Computing is gaining share fastest.
Solution:
Application maturity determines buyer sophistication in this category, with pre-built APIs displacing custom development cycles.
- Application Enablement:Pre-configured analytics APIs and visualization tools accelerate OEM productization timelines. Industrial buyers in Barcelona smart city projects favor these modules to bypass 18-month development sprints.
- Device Management:Lifecycle orchestration for heterogeneous sensor fleets, including firmware over-the-air updates and certificate rotation. Germany's Industrie 4.0 supplier qualification frameworks mandate this capability for tiered supply chain participation.
- Data Management:Stream processing and time-series storage for high-velocity telemetry.
- Connectivity Management:Protocol abstraction and network failover for multi-RAN environments.
Device Management leads volumes today; Application Enablement is expanding most quickly.
End User:
Regulatory exposure differentiates buyers in this category, with compliance burdens reshaping procurement criteria.
- Manufacturing:Edge-to-cloud interoperability stacks are becoming standard in automotive and precision engineering corridors. FDA cybersecurity guidance for connected production equipment is forcing documentation upgrades in US-facing medical device suppliers.
- Smart Cities:Municipal infrastructure projects in Barcelona and Singapore are accelerating cloud-based platform adoption. The EU AI Act's explainability requirements are displacing legacy black-box systems for biometric monitoring and traffic management.
- Healthcare:Middleware with pre-validated 510(k) documentation packages captures premium pricing in connected medical device deployments.
- Transportation:Autonomous logistics networks demand sub-second response architectures that preclude pure cloud topologies.
Manufacturing leads volumes today; Smart Cities is climbing the fastest.
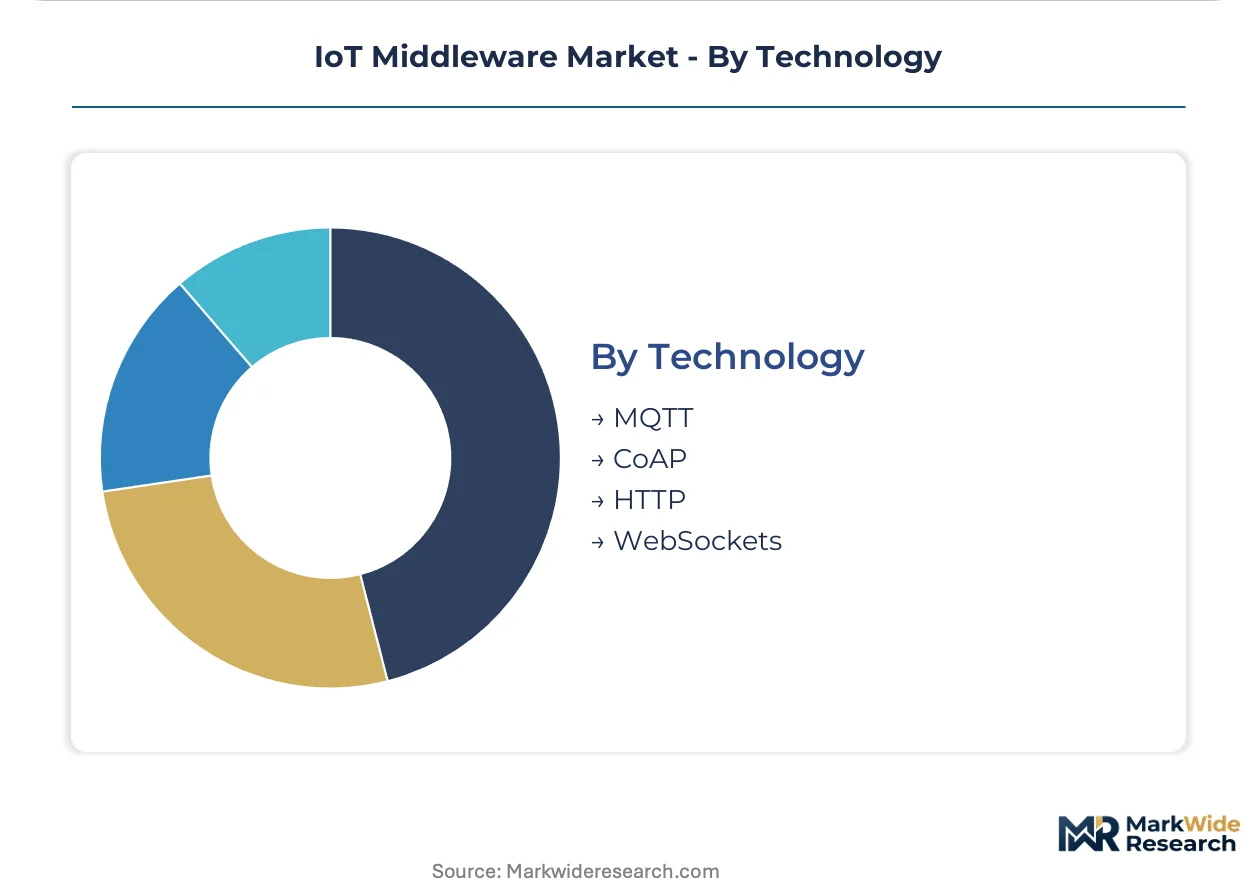
Technology:
Protocol characteristics align with specific latency and power constraints, creating technology-application pairing patterns.
- MQTT:Lightweight publish-subscribe messaging optimized for constrained devices and intermittent connectivity. Dominates in smart meter deployments and agricultural sensor networks where bandwidth is scarce.
- CoAP:RESTful protocol designed for resource-constrained nodes, enabling direct web integration without translation gateways.
- HTTP:Ubiquitous request-response model for cloud-facing integrations and enterprise application connectivity.
- WebSockets:Full-duplex persistent connections for real-time dashboards and command-and-control interfaces.
MQTT leads volumes today; WebSockets is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IoT middleware industry traces its commercial roots to Silicon Valley cloud infrastructure deployments of the early 2010s, where protocol abstraction layers first scaled to manage heterogeneous device fleets. European industrial automation corridors and East Asian smart city initiatives subsequently drove geographic diversification of demand patterns and regulatory frameworks.
United States
FDA cybersecurity guidance for connected medical devices is reshaping procurement criteria for healthcare-facing middleware platforms. The country's national technology regulator enforces spectrum allocation rules that constrain edge node density in industrial zones. Boston's medical device cluster and Seattle's cloud infrastructure hubs anchor domestic middleware development capacity.
Germany
Industrie 4.0 manufacturing corridors in Stuttgart and Wolfsburg mandate edge-to-cloud interoperability for automotive supplier qualification. BSI IT-Grundschutz standards impose security certification burdens that extend vendor onboarding timelines. The country's precision engineering clusters are standardizing middleware stacks for predictive maintenance across tiered supply chains.
Singapore
Smart nation infrastructure investments are accelerating cloud-based device management platform adoption for municipal deployments. The national cybersecurity agency mandates data residency controls for critical infrastructure middleware layers. The city-state's logistics hub is piloting sub-100ms latency architectures for autonomous port operations.
India
BIS IoT guidelines are creating first-mover advantage for vendors establishing localized data residency architectures ahead of formal enforcement. The national electronics regulator is developing mandatory certification frameworks for connected infrastructure. Maharashtra's industrial corridors and Karnataka's technology clusters are emerging as domestic middleware demand centers.
Japan
METI's Society 5.0 initiative is driving middleware adoption for factory automation and aging population monitoring systems. The national industrial standards body enforces JIS certification requirements for industrial IoT components. Nagoya's automotive manufacturing belt and Osaka's precision machinery clusters are standardizing edge computing deployments.
IoT Middleware Market Vendor Landscape
The competitive structure tilts toward hyperscale cloud providers with integrated hardware-software stacks. Platform bundling into modular middleware offerings is compressing procurement cycles and favoring vendors with existing enterprise relationships. Three archetypes dominate: hyperscale cloud platforms, industrial automation specialists, and vertical-specific analytics providers. Strategic moves concentrate on edge infrastructure partnerships and compliance pre-certification to accelerate municipal sales cycles.
Within the hyperscale tier, Microsoft and Amazon Web Services anchor enterprise deployments through integrated cloud-edge continuity stacks. IBM occupies a differentiated position with healthcare compliance workload specialization. These three exemplify how vendor scale and vertical certification depth determine competitive positioning in procurement processes that increasingly prioritize outcome-guaranteed service tiers over discrete software licensing.
| Leading Market Players |
|---|
| Microsoft |
| Amazon Web Services |
| IBM |
| Cisco Systems |
| PTC |
| Oracle |
| SAP |
| Hitachi |
| Others |
Supply Flow & Price Mechanics
Municipal buyers in Barcelona and Singapore negotiating uptime-backed contracts with penalty clauses are compressing margins for pure-software players while rewarding integrated hardware-software providers with direct edge infrastructure control. This transfer of operational risk to vendors is reshaping how middleware stacks are priced and which supply chain configurations capture premium positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with certification grade under EU AI Act transparency mandates and volume scale driving differentiation. Premium tiers bundle pre-validated 510(k) documentation for FDA-facing healthcare workloads, while economy tiers strip out compliance overhead for non-regulated industrial deployments. Cost compression in standard tiers is intensifying because hyperscale cloud providers are absorbing integration complexity into bundled SaaS subscriptions. Municipal procurement teams exhibit highest price sensitivity due to budget cycle constraints, whereas medical device OEMs prioritize compliance completeness over unit economics.
Supply Chain Analysis
Reverse-logistics flows for edge node refurbishment and certificate rotation services are emerging as margin contributors, particularly for hardware-dependent deployments in German automotive corridors. Foundry capacity for edge processors concentrates in Taiwan, South Korea, and the United States, with TSMC and Samsung anchoring semiconductor supply. Middleware vendors draw from captive silicon supply, cloud infrastructure partnerships, and specialized embedded systems engineering talent pools. Single-source vulnerability in TSMC advanced node production creates 12-18 month lead time volatility for time-critical deployments. Distribution runs through direct enterprise sales teams for large manufacturing accounts and hyperscaler marketplaces for mid-market SaaS adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in IoT middleware rests on two vectors: operational leverage from containerized microservices architectures reducing delivery costs, and premium-tier capture through pre-certified compliance bundles that command pricing power in regulated verticals.
For Market Incumbents: Hedge against in-house OEM protocol stack development by deepening embedded systems engineering partnerships in Stuttgart and Wolfsburg manufacturing clusters. Prioritize certification pre-investment across German BSI IT-Grundschutz, French ANSSI CSPN, and IEC 62443 standards to compress municipal sales cycles. Control channel conflict between direct sales and hyperscaler marketplace listings to prevent margin erosion in mid-market accounts. For New Entrants and Emerging Players: Edge-native Kubernetes orchestration layers present a technology-first wedge for penetrating tier-two automotive suppliers seeking multi-factory standardization without legacy platform lock-in. Target India's Maharashtra industrial corridors and Karnataka technology clusters ahead of formal BIS IoT guideline enforcement to establish localized data residency architectures. Lead with 90-day integration sprint guarantees against incumbent 18-month deployment timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical-specific analytics providers holding pre-validated healthcare compliance documentation and direct hospital system relationships. Long-term viability over the projection horizon favors vendors with hybrid cloud-edge deployment control rather than pure-software licensing models. Monitor FDA cybersecurity guidance enforcement velocity and EU AI Act audit frequency as inflection indicators for compliance-premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Infrastructure Partnership | Direct hardware control enables uptime-backed contracts with Barcelona municipal procurement teams. |
| Compliance Pre-Certification | Pre-validated 510(k) documentation packages capture premium pricing in FDA-facing medical device deployments. |
| Containerized Microservices Architecture | Kubernetes-based orchestration compresses automotive OEM integration timelines from 18 months to 90-day sprints. |
| Localized Data Residency Buildout | India BIS IoT guideline anticipation creates first-mover positioning in Maharashtra industrial corridors. |
| Digital Twin API Integration | Physics-based simulation layers unlock premium pricing in aerospace and energy asset management accounts. |
Methodological Framework
Bottom-up manufacturing and smart city deployment modeling reconciled against top-down cloud infrastructure capacity tracking forms the analytical core. Primary interviews with CTOs at automotive OEMs, IT procurement officers in municipal governments, platform engineers at hyperscalers, and integration specialists in healthcare systems combined with secondary validation from SEC filings, hyperscaler capex disclosures, and EU regulatory filings. Triangulation between demand-side procurement pattern analysis and supply-side vendor capacity assessment ensures segment-level consistency.
Input-output matrix framing connects deployment topology adoption rates to solution segment growth trajectories across the analysis window. Segmentation dimensions modeled include deployment model, end-use vertical, solution architecture, and regional regulatory cluster. CAGRs derive from elasticity-adjusted adoption curves and replacement cycle analysis. Industry-specific forecast inputs incorporate Industrie 4.0 supplier qualification mandate penetration and EU AI Act risk-classification rollout velocity.
The model holds under stable regulatory enforcement timelines and continued hyperscaler cloud-edge investment; deviation in semiconductor foundry capacity allocation or sovereign data residency requirement fragmentation would shift geographic growth trajectories. Practitioners should monitor TSMC advanced node allocation announcements and BIS IoT guideline formalization dates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Europe Industrial IoT Market
Internet of Things (IoT)
IoT Smart Poles Market
Internet of Things (IoT)
IoT Microcontroller Market
Internet of Things (IoT)
North America IoT Device Market
Internet of Things (IoT)
Global IoT Routers Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
Indonesia IoT Market
Internet of Things (IoT)
Asia-Pacific IoT Device Market
Internet of Things (IoT)
Global Residential Smart Thermostats Market
Internet of Things (IoT)
Industrial Internet of Things (Iiot) Market
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
Global IoT Node and Gateway Market
Internet of Things (IoT)
Global IoT Elevators Market
Internet of Things (IoT)
Cellular Internet of Things (IoT) Devices Market