
 IoT Communication Technologies Market | 2026-2036
IoT Communication Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Communication Technologies Market Analysis
Buyer concentration in industrial automation is consolidating around a handful of multinational equipment manufacturers that now specify communication modules directly into procurement contracts. Qualcomm Technologies leverages its integrated modem-RF system architecture to anchor premium supply agreements with these consolidated buyers. Texas Instruments competes through specialized low-power microcontroller portfolios that sustain design-win momentum in battery-constrained sensor nodes. Huawei Technologies navigates restricted Western market access by dominating private 5G network deployments across Middle Eastern and Southeast Asian manufacturing zones.
IoT communication technologies encompass the hardware, protocols, and software layers enabling machine-to-machine data exchange across distances from centimeters to kilometers, with LoRaWAN supporting sub-gigahertz unlicensed spectrum operation at link budgets exceeding 150 dB for rural coverage. Their primary commercial purpose is replacing wired infrastructure with standards-based wireless connectivity that permits remote monitoring, predictive maintenance, and automated control in distributed asset environments. NB-IoT occupies the fastest-expanding technology position as cellular operators monetize licensed spectrum for utility metering and fleet tracking with guaranteed quality-of-service terms. Edge computing deployment architectures concentrate margin pools closest to end users, where latency-sensitive industrial automation applications require localized data processing rather than cloud backhaul. Application enablement platforms within the solution layer differentiate through pre-integrated device provisioning and API ecosystems that reduce time-to-market for vertical software developers.
The European Telecommunications Standards Institute coordinates NB-IoT and LTE-M interoperability benchmarks under EU Radio Equipment Directive conformity requirements, while the Federal Communications Commission governs unlicensed spectrum power limits and out-of-band emissions for Zigbee and LoRaWAN devices entering US commerce. China's Ministry of Industry and Information Technology mandates domestic cybersecurity review for IoT platforms processing critical infrastructure data, creating compliance friction for foreign module suppliers. Stakeholders must monitor evolving national spectrum reallocation decisions and certification reciprocity agreements, as fragmented regulatory timelines threaten product rollout synchronization across major demand centers.
Market Dynamics
Cellular operators are aggressively repurposing licensed spectrum assets for narrowband IoT services, compressing deployment timelines for utility-scale metering infrastructure while squeezing unlicensed alternative technologies into niche rural coverage applications.
Growth Catalysts
- EU Green Deal infrastructure mandates:Smart city procurement across Germany, France, and the United Kingdom accelerates LoRaWAN and NB-IoT network rollout for energy-efficient building management and intelligent street lighting systems.
- Precision agriculture sensor density:East Asian manufacturing clusters supply radio-frequency front ends for module integrators serving automated irrigation and soil monitoring deployments across water-stressed farming regions.
- Semiconductor foundry capacity expansion:Dedicated 22nm RF process nodes at leading fabs reduce unit costs for cellular modem integration, enabling sub-dollar module pricing for high-volume industrial automation buyers.
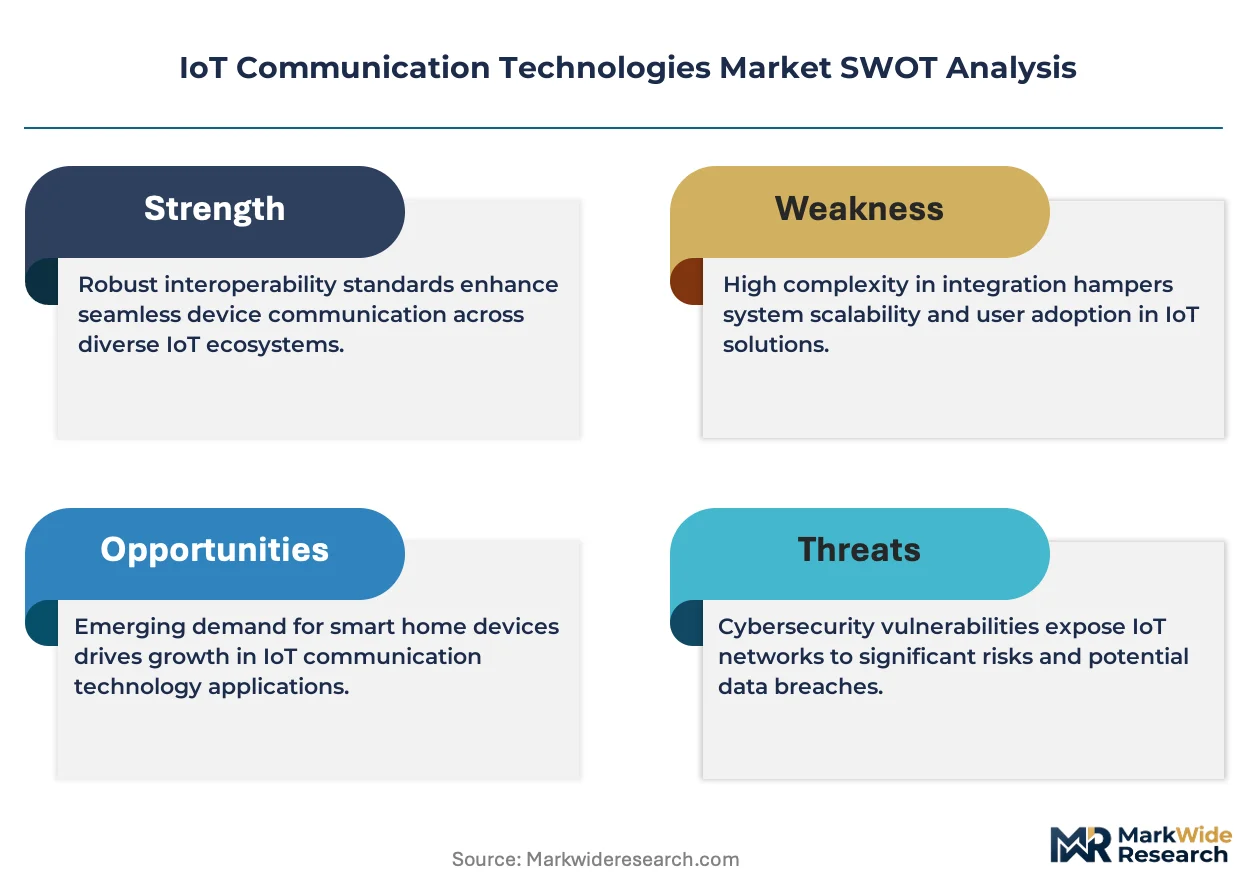
Market Restraints
- Licensed spectrum access fees:Annual carrier subscription costs for NB-IoT connectivity create recurring expense burdens that unlicensed LoRaWAN alternatives avoid, particularly for low-data-rate environmental monitoring applications.
- Radio-frequency front-end concentration:Foundry capacity for gallium arsenide power amplifiers concentrates in Taiwan and South Korea, exposing module suppliers to geopolitical supply disruption risks.
- Interoperability certification fragmentation:Divergent national type-approval requirements for electromagnetic compatibility create duplicated testing costs and extended product launch timelines across major demand centers.
Strategic Opportunities
- Private 5G network deployments:Manufacturing zones in the Middle East and Southeast Asia bypass public carrier infrastructure, creating captive demand for integrated small-cell and core network equipment packages.
- Edge computing convergence:Latency-sensitive industrial automation applications in German automotive plants drive localized data processing architectures that combine radio modules with embedded GPU acceleration.
- REACH-compliant embedded security:EU AI Act and cybersecurity certification requirements push device manufacturers toward hardware-secured elements, differentiating premium module tiers from commodity alternatives.
Industry Challenges
- RF systems engineering talent scarcity:Specialized expertise in antenna design and propagation modeling for sub-gigahertz unlicensed spectrum commands premium compensation, constraining product development velocity at mid-tier suppliers.
- Legacy SCADA integration complexity:Brownfield industrial facilities require protocol translation gateways between proprietary wired fieldbus systems and standards-based wireless overlays, extending deployment timelines and inflating project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Communication Technologies Market |
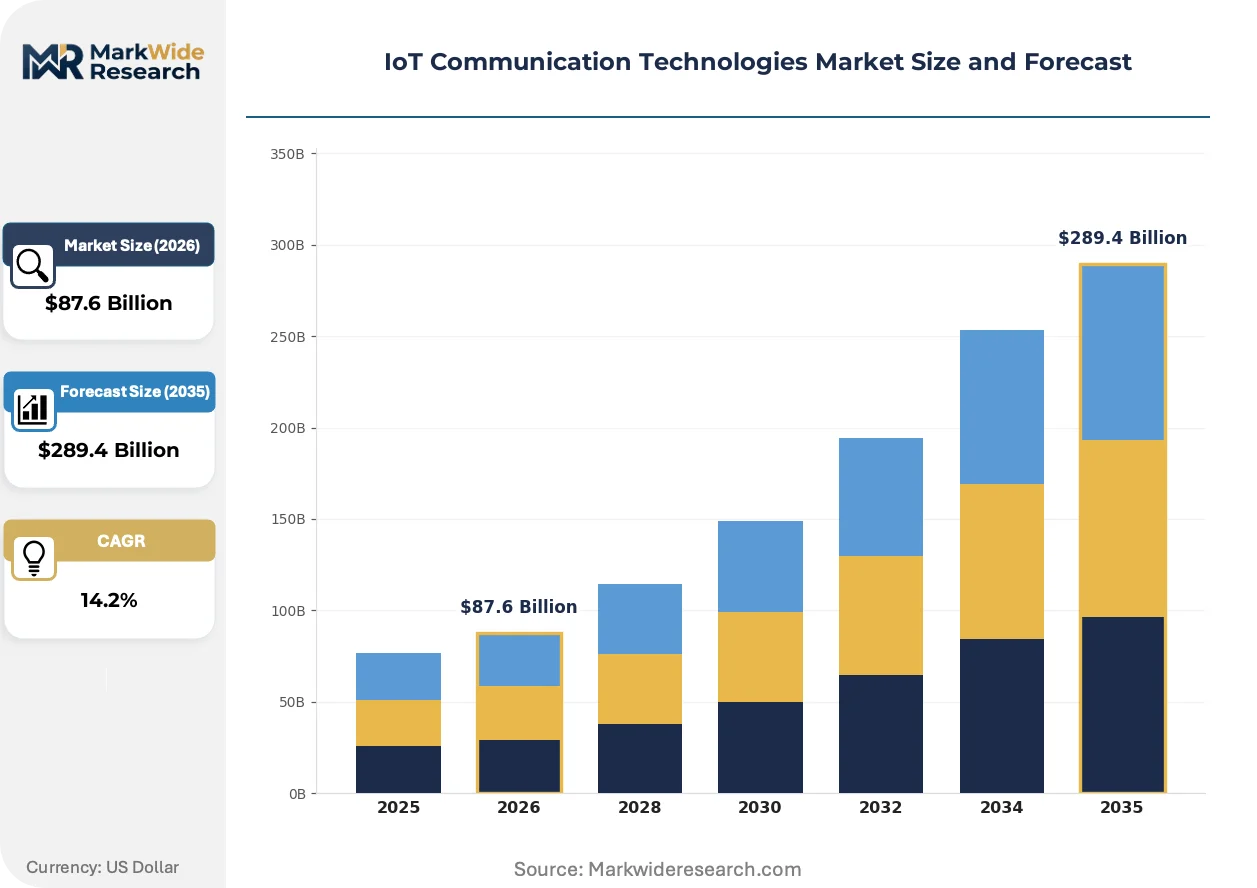
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LoraWAN, Zigbee, NB-IoT, Sigfox Solution: Device Management, Network Management, Application Enablement, Security End User: Smart Cities, Industrial Automation, Healthcare, Agriculture Deployment: Cloud, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Qualcomm Technologies, Inc., Intel Corporation, Microsoft Corporation, Cisco Systems, Inc., Amazon Web Services, Inc., STMicroelectronics N.V., Texas Instruments Incorporated, NXP Semiconductors N.V., Huawei Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Communication Technologies Market Emerging Trajectories
Convergence between radio hardware and edge processing silicon is collapsing traditional supply chain boundaries, while regulatory pressure on embodied carbon and cybersecurity hardens certification requirements faster than design cycles can absorb.
Integrated modem-RF system architectures are consolidating what were previously discrete component supply chains into single-source procurement relationships. Multinational equipment manufacturers now specify complete communication subsystems directly into procurement contracts, bypassing traditional module distributor channels. This compression is eliminating margin pools for second-tier radio frequency component suppliers and concentrating design-win influence with semiconductor vendors capable of delivering certified, carrier-validated reference designs.
The EU AI Act and REACH compliance frameworks are mandating embedded security modules and low-power wide-area certification for devices processing critical infrastructure data. Manufacturers serving European utility and transportation verticals must demonstrate conformity with ETSI interoperability benchmarks under Radio Equipment Directive requirements. German smart city integrators are responding by pre-qualifying suppliers with existing CE marking and cybersecurity certification portfolios, creating compliance moats that delay market entry for uncertified competitors.
Buyer concentration around consolidated industrial automation OEMs is forcing module suppliers to assume extended warranty and firmware update obligations previously borne by system integrators. Direct specification relationships now require radio vendors to maintain decade-long software support lifecycles for deployed sensor populations. This obligation transfer is most visible in Japanese manufacturing supply chains, where keiretsu procurement structures embed communication modules into long-term equipment supply agreements with stringent mean-time-between-failure guarantees.
IoT Communication Technologies Market Segmentation
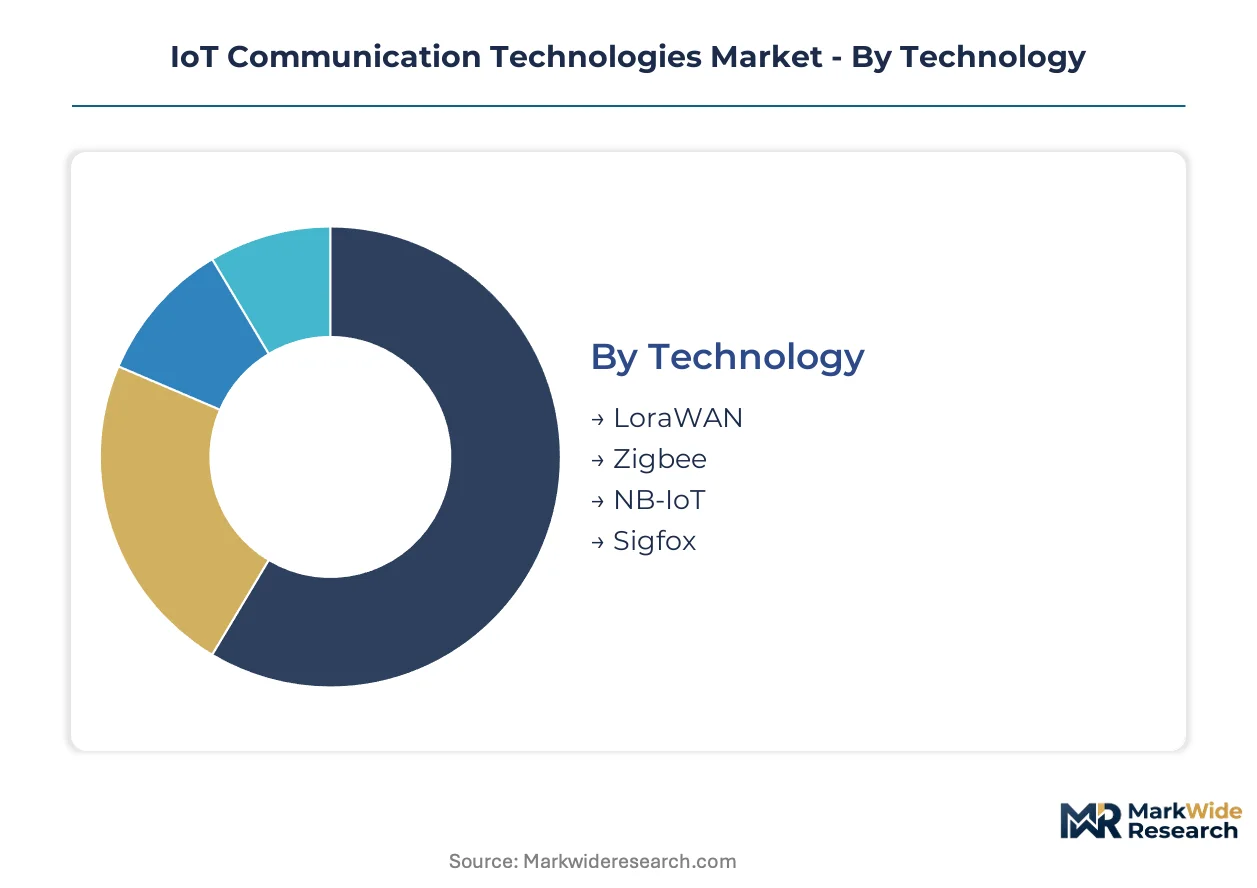
Technology heterogeneity across the IoT communication stack creates divergent margin profiles and certification burdens. Solution providers must align portfolio depth with buyer procurement patterns that favor either integrated platform contracts or best-of-breed component sourcing.
Technology:
Integration depth varies sharply: NB-IoT and LoRaWAN dominate embedded cellular and unlicensed deployments respectively, while Zigbee and Sigfox occupy specialized standalone niches with lighter integration requirements.
- NB-IoT:Licensed-spectrum narrowband protocol operating in sub-gigahertz bands with guaranteed quality-of-service terms. German utility operators specify NB-IoT modules directly into smart metering procurement contracts under EU Green Deal energy-efficiency mandates. The technology's deep carrier integration demands extended firmware support lifecycles that concentrate supply relationships with Qualcomm and Huawei.
- LoRaWAN:Unlicensed sub-gigahertz protocol achieving link budgets exceeding 150 dB for rural coverage without subscription fees. French and United Kingdom smart city integrators deploy LoRaWAN for intelligent street lighting and building management where low-data-rate environmental monitoring avoids cellular recurring costs. Semiconductor foundries in Taiwan and South Korea supply gallium arsenide power amplifiers for module integrators serving this segment.
- Zigbee:Mesh-networking standard for short-range device-to-device communication in building automation and consumer IoT.
- Sigfox:Ultra-narrowband unlicensed technology optimized for minimal power consumption in simple sensor telemetry applications.
Volume placements concentrate in NB-IoT for utility-scale deployments; the steepest expansion trajectory belongs to LoRaWAN as municipal infrastructure budgets prioritize unlicensed alternatives.
Solution:
Cost tier differentiation separates enterprise-grade platform subscriptions from lightweight device-level tooling, with security modules commanding premium positioning under EU AI Act compliance requirements.
- Application Enablement:Middleware platforms providing pre-integrated device provisioning, API ecosystems, and vertical-specific analytics that reduce time-to-market for software developers. German automotive plants and Japanese manufacturing keiretsu structures specify these platforms for predictive maintenance deployments requiring decade-long support guarantees. The segment captures margin pools closest to end-user applications through recurring SaaS structures.
- Security:Embedded hardware-secured elements and cryptographic modules mandated by EU AI Act and REACH frameworks for critical infrastructure data processing. Device manufacturers serving European transportation and utility verticals must demonstrate ETSI interoperability benchmarks under Radio Equipment Directive requirements, creating compliance moats that delay uncertified competitors.
- Device Management:Lifecycle tooling for firmware updates, configuration orchestration, and diagnostic monitoring across distributed sensor populations.
- Network Management:Core infrastructure software for subscriber provisioning, traffic optimization, and carrier-grade reliability in licensed spectrum deployments.
Enterprise procurement concentrates in Application Enablement; Security solutions are climbing fastest as regulatory hardening outpaces design cycle absorption.
End User:
Customer type fragmentation separates consolidated multinational equipment manufacturers from fragmented municipal procurement, with divergent contract structures and warranty obligations.
- Smart Cities:Municipal infrastructure deployments spanning intelligent street lighting, energy-efficient building management, and environmental monitoring across Germany, France, and the United Kingdom. EU Green Deal mandates accelerate LoRaWAN and NB-IoT network procurement with decade-long operational lifecycles that demand extended vendor support commitments.
- Industrial Automation:Manufacturing facility deployments requiring latency-sensitive control loops and predictive maintenance analytics. German automotive plants and East Asian semiconductor foundries drive edge computing convergence that combines radio modules with embedded GPU acceleration for localized data processing.
- Healthcare:Remote patient monitoring and medical device connectivity with stringent data privacy and reliability requirements.
- Agriculture:Precision farming sensor networks for automated irrigation and soil monitoring across water-stressed regions, supplied by East Asian RF front-end manufacturers.
Contract value concentrates in Industrial Automation; Smart Cities are gaining share fastest as EU infrastructure funding unlocks municipal procurement pipelines.
Deployment:
Supply concentration for processing silicon determines architecture selection, with edge and hybrid models capturing manufacturing demand while cloud retains utility-scale metering.
- Edge Computing:Localized data processing architectures eliminating cloud backhaul latency for time-critical industrial control applications. German automotive plants and Middle Eastern manufacturing zones deploy edge computing with private 5G networks to bypass public carrier infrastructure. NVIDIA and Intel embedded GPU acceleration increasingly integrates directly with radio modules.
- Hybrid:Architectures partitioning latency-sensitive processing at the edge with analytics aggregation in cloud environments. Japanese keiretsu manufacturing structures favor hybrid deployments balancing real-time control with centralized operational intelligence.
- Cloud:Centralized data aggregation and analytics for utility metering and fleet tracking with less stringent latency requirements.
- On-Premises:Fully captive infrastructure for critical infrastructure operators with sovereignty or security constraints.
Current installations concentrate in Cloud for utility applications; Edge Computing is expanding most quickly as manufacturing automation demands sub-10 millisecond response times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most visibly in East Asian manufacturing clusters and European smart city procurement corridors, with regulatory divergence fragmenting certification timelines across major deployment zones.
Germany
Industrial automation OEMs in Bavaria and Baden-Württemberg specify NB-IoT modules directly into procurement contracts for predictive maintenance systems. The EU AI Act and REACH compliance frameworks mandate embedded security elements for critical infrastructure data processing. Stuttgart automotive plants drive edge computing convergence that combines radio modules with localized GPU acceleration for sub-10 millisecond control loops.
United States
Federal Communications Commission power limits for unlicensed spectrum shape Zigbee and LoRaWAN device commercialization strategies. Utility operators in Texas and California deploy cellular IoT for smart metering infrastructure with guaranteed quality-of-service terms. Silicon Valley semiconductor designers supply RF front-end architectures to module integrators serving industrial automation buyers.
China
The Ministry of Industry and Information Technology mandates domestic cybersecurity review for IoT platforms processing critical infrastructure data. Yangtze River Delta foundries supply gallium arsenide power amplifiers for module integrators across precision agriculture and manufacturing verticals. Shenzhen hardware ecosystems concentrate design-win influence for low-power microcontroller portfolios in battery-constrained sensor nodes.
Japan
Keiretsu procurement structures embed communication modules into decade-long equipment supply agreements with stringent reliability guarantees. METI standardization efforts coordinate interoperability benchmarks for private 5G network deployments in manufacturing zones. Nagoya automotive clusters demand extended firmware support lifecycles for deployed sensor populations.
United Kingdom
Municipal infrastructure budgets prioritize LoRaWAN for intelligent street lighting and building management systems under energy-efficiency mandates. The Radio Equipment Directive requires ETSI interoperability benchmarks for devices entering European commerce. London smart city integrators pre-qualify suppliers with existing CE marking and cybersecurity certification portfolios.
IoT Communication Technologies Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue private 5G infrastructure and edge-native radio architectures. The vendor base separates into three tiers: integrated modem-RF system architects, specialized low-power microcontroller suppliers, and cloud-native platform operators. Strategic moves concentrate on carrier-validated reference design partnerships and decade-long software support commitments for industrial automation OEMs.
Within the integrated system tier, Qualcomm Technologies, Inc. and Intel Corporation exemplify semiconductor vendors capable of delivering certified architectures that bypass traditional distributor channels. Texas Instruments Incorporated occupies a position among specialized suppliers sustaining design-win momentum in battery-constrained applications. Huawei Technologies Co., Ltd. represents the geographically focused archetype dominating private network deployments in manufacturing zones outside Western markets.
| Leading Market Players |
|---|
| Qualcomm Technologies, Inc. |
| Intel Corporation |
| Microsoft Corporation |
| Cisco Systems, Inc. |
| Amazon Web Services, Inc. |
| STMicroelectronics N.V. |
| Texas Instruments Incorporated |
| NXP Semiconductors N.V. |
| Huawei Technologies Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal mandates for embodied carbon disclosure and REACH-compliant material sourcing gate qualified supply access and premium-tier pricing power for module vendors serving European smart city and industrial automation buyers. Certification moats around ETSI interoperability benchmarks and CE marking create tiered market access where only hardware-secured, pre-qualified suppliers capture utility-scale procurement contracts.
Pricing Analysis
Volume placements in NB-IoT utility metering run on thin margins through carrier-negotiated subscription tiers, while premium positioning concentrates in edge-native radio architectures with embedded GPU acceleration for German automotive plants. Price differentiation hinges on cybersecurity certification grade under EU AI Act requirements and decade-long firmware support obligations demanded by Japanese keiretsu structures. Pricing pressure stems from sub-dollar cellular module targets enabled by 22nm RF process node economics at Taiwanese foundries. Municipal smart city buyers exhibit highest price sensitivity to recurring connectivity fees, whereas industrial automation OEMs prioritize mean-time-between-failure guarantees over unit cost.
Supply Chain Analysis
Reverse-logistics flows for field-deployed sensor populations remain underdeveloped, with most vendors lacking refurbishment capabilities for returned LoRaWAN gateway hardware or end-of-life NB-IoT modules. Taiwan, South Korea, and China anchor gallium arsenide power amplifier supply for radio-frequency front ends, while German and United States-based semiconductor designers provide modem architectures. The chain draws from specialized 22nm RF process nodes, ceramic substrate packaging, and hardware-secured element substrates. Single-source vulnerability concentrates in Taiwan foundry capacity for cellular modem integration. Distribution runs through direct specification relationships with multinational equipment manufacturers, bypassing traditional module distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over RF process node allocation and firmware support infrastructure determines design-win persistence against consolidated industrial automation buyers.
For Market Incumbents: Extend carrier-validated reference design partnerships into decade-long software support commitments that match Japanese keiretsu procurement timelines. Deepen backward integration into gallium arsenide power amplifier supply through dedicated capacity reservations at Taiwanese foundries, insulating against geopolitic disruption while defending margin position against Qualcomm's integrated modem-RF system architecture.
For New Entrants and Emerging Players: Begin with private 5G network deployment packages for Middle Eastern and Southeast Asian manufacturing zones bypassing public carrier infrastructure. Target captive industrial campus environments where latency-sensitive control loops favor edge-native radio architectures over cloud-dependent alternatives. Pursue system integrator partnerships that embed communication modules into predictive maintenance platform subscriptions rather than competing for discrete component procurement.
For Investors and Strategic Acquirers: ETSI cybersecurity certification queue lengths exceeding twelve months are the leading indicator that compliance moats will concentrate supply relationships with pre-qualified vendors. Position for platform-level acquisition targets combining application enablement middleware with embedded security module hardware over pure-play radio component suppliers. Monitor EU spectrum reallocation decisions and CE marking reciprocity negotiations for early signals of certification timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Carrier-Validated Reference Design Partnership | Qualcomm and Intel anchor premium supply agreements with consolidated industrial automation OEMs through certified architectures. |
| Private 5G Network Deployment Package | Huawei dominates captive manufacturing zone infrastructure in Middle Eastern and Southeast Asian markets bypassing Western carriers. |
| Embedded Security Module Integration | EU AI Act compliance mandates hardware-secured elements for critical infrastructure data processing in German utility verticals. |
| Application Enablement Platform Acquisition | Recurring SaaS structures capture margin pools closest to end-user predictive maintenance deployments in Japanese keiretsu. |
| Gallium Arsenide Power Amplifier Capacity Reservation | Taiwanese foundry allocation insulates module suppliers against RF front-end concentration risks in semiconductor supply. |
Methodological Framework
SEC filings from Qualcomm and Texas Instruments, ETSI interoperability benchmark documentation, and FCC unlicensed spectrum rulemakings formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with RF systems engineering directors at module integrators, procurement leads at German automotive OEMs, and smart city integration specialists in France and the United Kingdom validated technology adoption timelines and contract structure evolution. Bottom-up triangulation across cellular operator deployment disclosures and top-down reconciliation against semiconductor foundry capacity announcements anchored volume and value estimates.
Historical trendline analysis of NB-IoT and LoRaWAN network rollout velocities informed adoption curve modeling across the projection horizon. The analytical framework segmented demand by technology protocol, solution layer, end-user vertical, and deployment architecture while incorporating regional regulatory cluster variations. CAGRs derived from fitted growth curves applied to utility metering installation baselines and precision agriculture sensor density trajectories, with cross-checks against carrier capital expenditure guidance for narrowband IoT spectrum repurposing.
Semiconductor foundry allocation disruptions, EU spectrum reallocation delays, and cybersecurity certification queue extensions are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions around carrier subscription pricing stability and keiretsu procurement structure persistence. Practitioners should monitor ETSI certification backlog indicators, Taiwan Strait logistics metrics, and EU AI Act enforcement timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Application Enablement Market
Internet of Things (IoT)
Iiot (Industrial Internet of Things) Technology Market
Internet of Things (IoT)
Global IoT Battery Market
Internet of Things (IoT)
IoT at Workplace Market
Internet of Things (IoT)
Smart Remote Market
Internet of Things (IoT)
LTE IoT Market
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
IoT Solutions Market
Internet of Things (IoT)
Global Internet of Behaviors Market
Internet of Things (IoT)
IoT Development Kit Market
Internet of Things (IoT)
M2M Communication Market