
 Global Agile IoT Market | 2026-2036
Global Agile IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agile IoT Market Foresight
Platform licensing revenue is narrowing as hardware commoditization squeezes margins at the edge layer. Microsoft leverages its Azure IoT stack to sustain recurring software attach rates across enterprise accounts. Cisco Systems anchors its position through silicon-to-cloud security integration in industrial gateways. Huawei Technologies competes on manufacturing scale for 5G-enabled edge nodes in Asia-Pacific infrastructure bids.
Agile IoT denotes adaptive internet-of-things architectures that dynamically reconfigure device fleets, data pipelines, and analytics workloads in response to changing operational conditions through containerized microservices and AI-driven orchestration. These systems typically operate with sub-100ms latency thresholds for closed-loop control in mission-critical environments. Smart Manufacturing applications command the deepest margin pools due to uptime guarantees and predictive maintenance contracts. Edge Computing deployment is expanding fastest as latency-sensitive workloads outgrow centralized cloud economics. Device Management solutions remain mature with incumbents defending renewal bases through protocol standardization.
FCC spectrum allocations in the United States, EU AI Act risk classifications in Europe, and MIIT 5G-Advanced timelines in China collectively shape hardware certification cycles and cross-border data governance requirements. GDPR-derived data residency rules and China's GB standards for industrial internet security force architectural fragmentation that vendors must navigate through regional cloud instances. Stakeholders should monitor which regulator first mandates explainable AI for autonomous IoT decision chains, as this will trigger cascading compliance investments across all major supply bases.
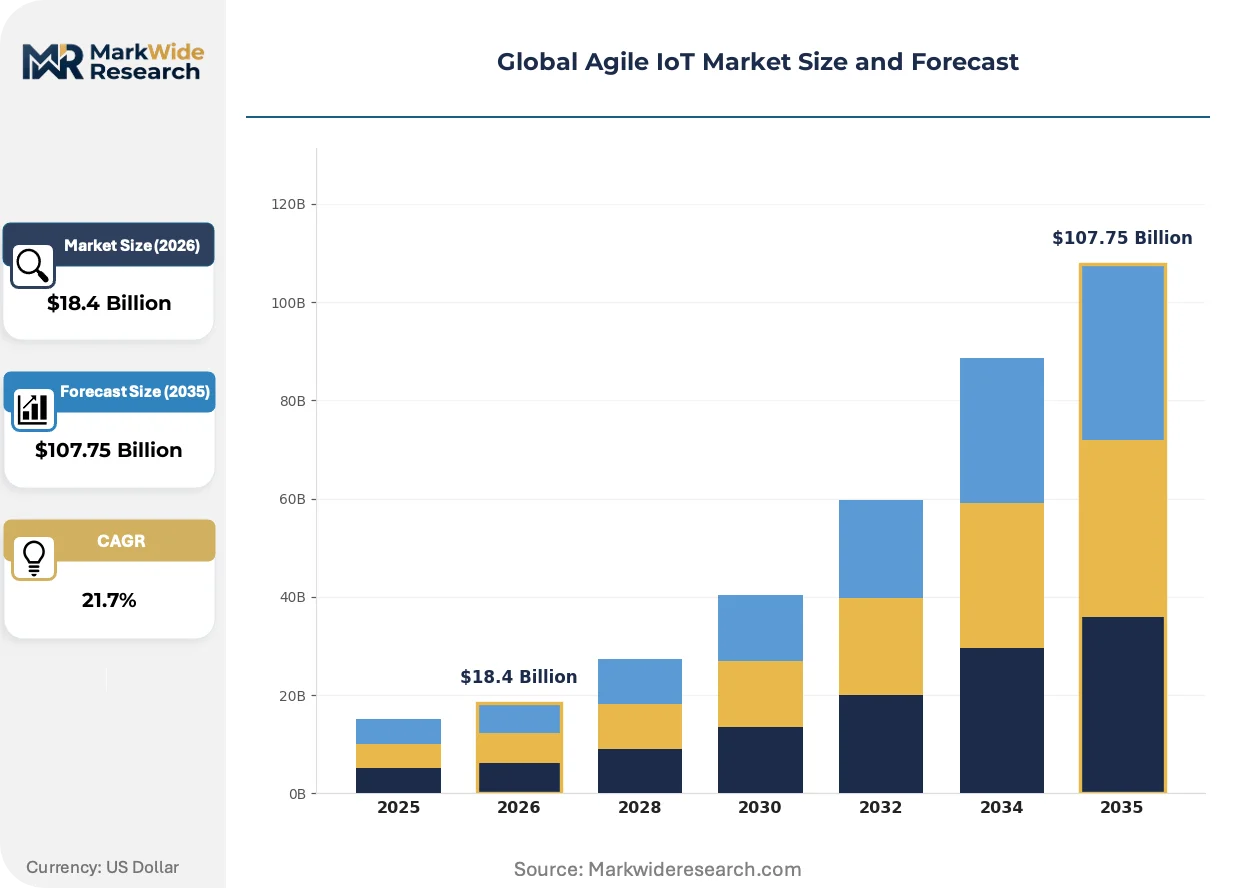
Market Dynamics
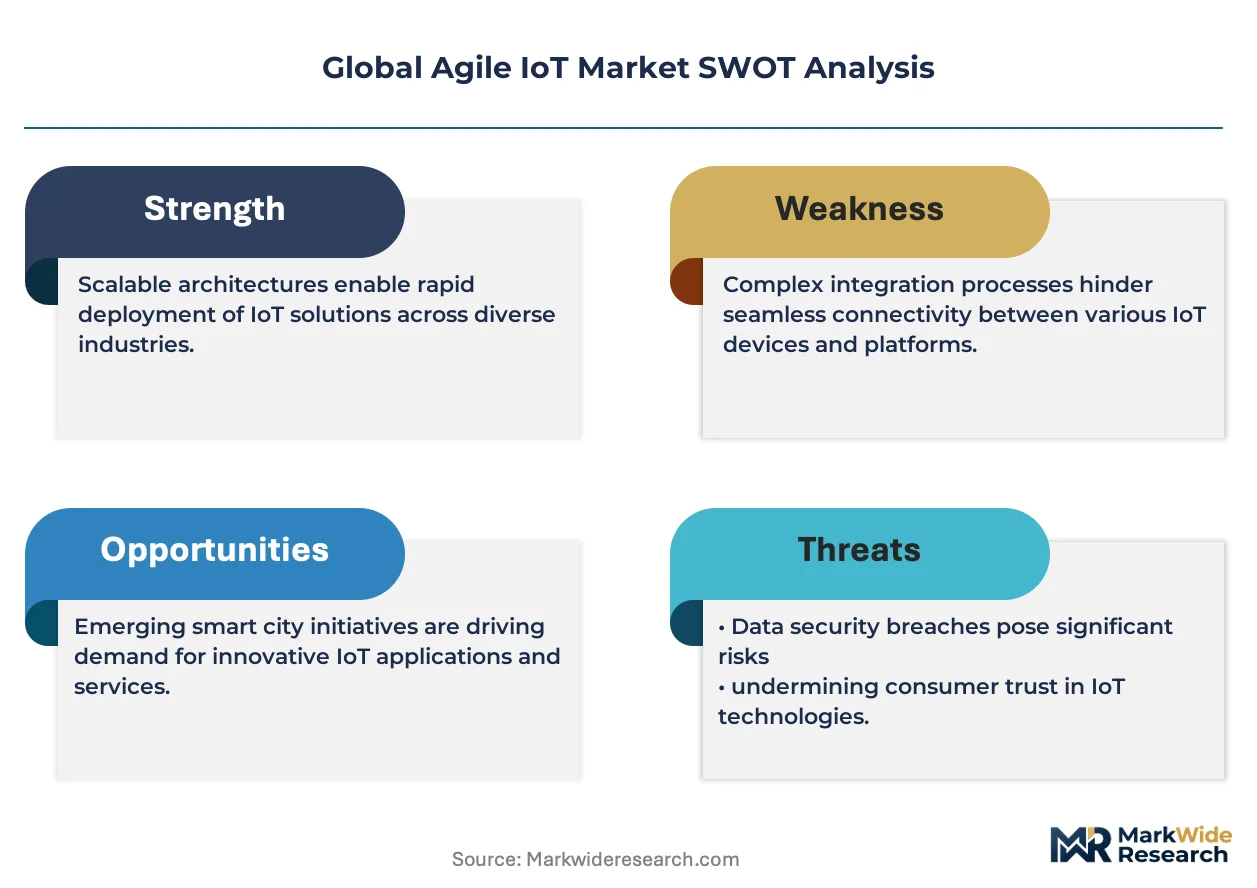
Edge AI inference at the network perimeter is compressing cloud dependency for latency-critical workloads, forcing vendors to re-architect software stacks for containerized microservices deployment.
Growth Catalysts
- EU AI Act risk classifications:Mandatory conformity assessments for autonomous decision systems are accelerating certified hardware procurement cycles among German automotive suppliers seeking compliance-ready edge nodes.
- 5G-Advanced network slicing:MIIT timelines in China are driving infrastructure bids that bundle ultra-reliable low-latency communication modules with industrial gateway contracts.
- Predictive maintenance contracts:Smart manufacturing uptime guarantees in Japan are expanding attach rates for AI-driven condition monitoring services tied to per-device subscription models.
Market Restraints
- Silicon supply concentration:Advanced node semiconductor fabrication clusters in Taiwan create single-point vulnerability for edge AI chip availability during geopolitical disruptions.
- GB standards compliance costs:China's industrial internet security certification mandates force architectural fragmentation requiring separate hardware SKUs for domestic versus export markets.
- Legacy protocol persistence:OPC-UA and Modbus installations in brownfield European factories slow microservices adoption due to translation layer complexity and integration testing overhead.
Strategic Opportunities
- India's PLI scheme for telecom equipment:Domestic manufacturing incentives are attracting edge node assembly investments serving South Asian smart city infrastructure rollouts.
- Digital twin convergence:Physics simulation engines merging with real-time sensor streams are opening new service revenue pools in South Korean semiconductor fabrication facilities.
- FCC CBRS spectrum allocation:Private 5G network licensing for US industrial campuses is creating greenfield deployment opportunities outside carrier-managed subscription models.
Industry Challenges
- Embedded systems talent scarcity:Shortage of firmware engineers capable of optimizing container runtimes for sub-100ms deterministic response in mission-critical control loops.
- Cross-border data governance:GDPR residency requirements conflicting with China's data localization mandates force multi-region cloud instance architectures that inflate operational complexity.
- Interoperability certification delays:Fragmented test lab capacity across national standards bodies slows time-to-market for multi-protocol industrial gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agile IoT Market |
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $107.75 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing Solution Type: Device Management, Data Analytics, Security, Connectivity Management, Application Enablement Application: Smart Cities, Smart Manufacturing, Connected Vehicles, Energy Management, Supply Chain Optimization End User Industry: Telecommunications, Consumer Electronics, Utilities Management, Transportation Services, Agriculture Technology |
| Companies Covered | Microsoft, Amazon Web Services, Cisco Systems, Huawei Technologies, IBM, Intel Corporation, Oracle, Google, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agile IoT Market Shifts & Advancements
Container orchestration at the edge is virtualizing hardware-software binding, enabling workload portability across heterogeneous device fleets without vendor lock-in.
Lightweight Kubernetes distributions are virtualizing the boundary between edge nodes and cloud control planes. Automotive Tier-1 suppliers in Germany are deploying these stacks for over-the-air update pipelines. This architecture is virtualizing traditional gateway vendor margins by decoupling hardware from software licensing.
The EU AI Act's high-risk system designation is mandating explainability modules for autonomous IoT decision chains. Industrial buyers in France and Italy now require algorithmic audit trails as contract prerequisites. European machine builders are responding by embedding interpretable ML frameworks directly into edge inference engines.
Subscription-based device management is displacing perpetual license purchases among Japanese electronics manufacturers. Systems integrators are capturing recurring revenue through uptime-backed service level agreements. This shift is most pronounced in precision equipment sectors where downtime costs exceed hardware depreciation by an order of magnitude.
Global Agile IoT Market Segmentation
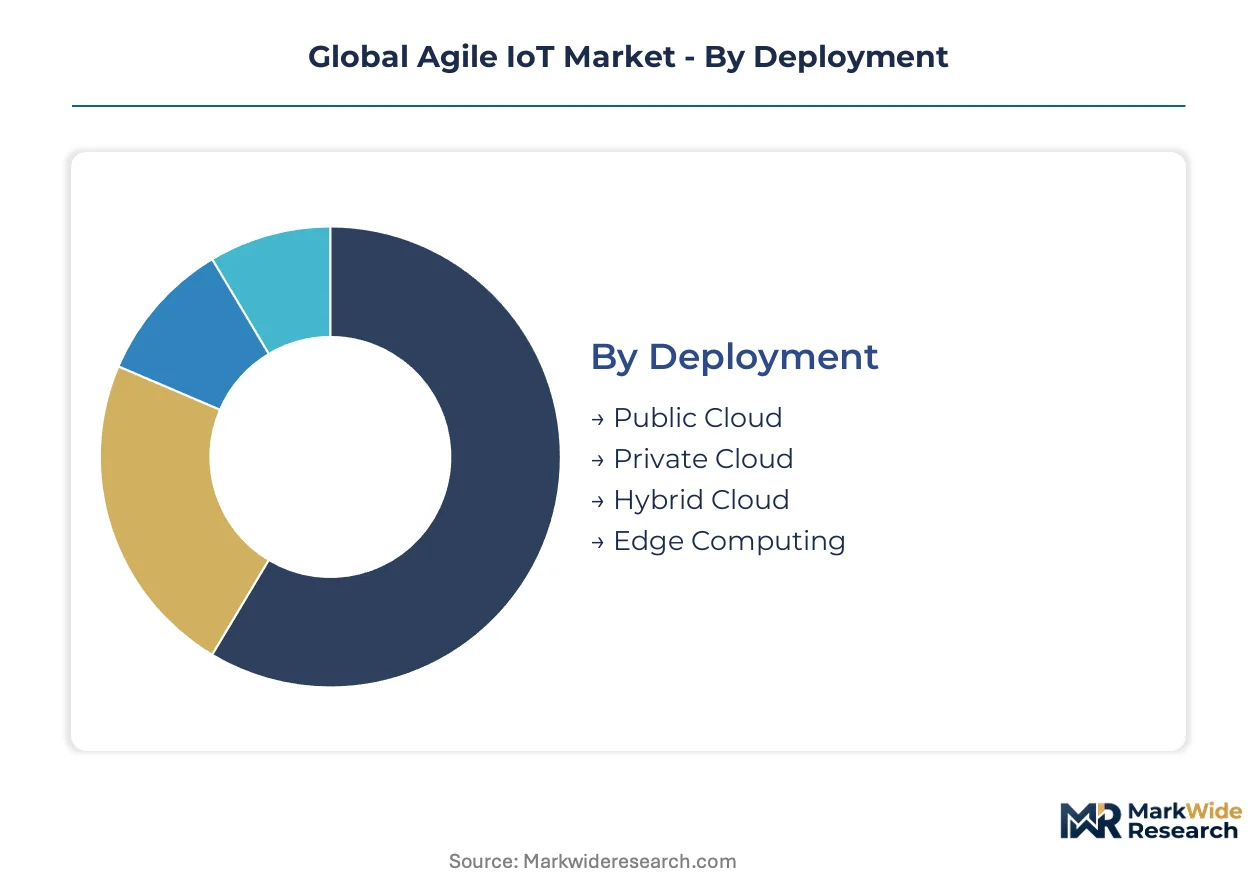
Agile IoT architectures fragment across deployment topologies, solution layers, and vertical applications. Each dimension carries distinct margin profiles and vendor competitive dynamics. Understanding these splits reveals where containerized microservices and AI-driven orchestration concentrate commercially.
Deployment:
Cost tier structures the infrastructure stack from centralized hyperscale to distributed edge nodes.
- Public Cloud:Centralized orchestration platforms host fleet management and analytics workloads on shared infrastructure. German automotive suppliers leverage these for non-deterministic batch processing while maintaining GDPR-compliant EU data residency zones.
- Edge Computing:Sub-100ms latency processing occurs at the network perimeter through containerized microservices on industrial gateways. Japanese precision equipment manufacturers demand these deployments for closed-loop control in mission-critical environments.
- Private Cloud:Dedicated infrastructure instances serve single-tenant requirements with enhanced sovereignty controls.
- Hybrid Cloud:Workload portability spans on-premises edge nodes and burst capacity to public cloud control planes.
Edge Computing holds installed capacity. Hybrid Cloud is rotating up the share rankings.
Solution Type:
Application maturity separates established protocol layers from emerging AI-enabled services.
- Data Analytics:Real-time inference engines process sensor streams for predictive maintenance and anomaly detection. South Korean semiconductor fabrication facilities deploy physics simulation convergence with these modules for digital twin service revenue.
- Security:Silicon-to-cloud integration spans hardware root-of-trust, encrypted transport, and zero-trust access policies. Cisco Systems anchors market position through industrial gateway security stacks.
- Device Management:Protocol standardization defends incumbent renewal bases across heterogeneous fleet footprints.
- Connectivity Management:5G network slicing and private LTE orchestration handles spectrum allocation and quality-of-service enforcement.
- Application Enablement:Low-code platforms accelerate microservices deployment for domain-specific IoT applications.
Device Management holds installed capacity. Data Analytics is rotating up the share rankings.
Application:
Vertical use cases concentrate margin pools where uptime guarantees command premium pricing.
- Smart Manufacturing:Predictive maintenance contracts with uptime-backed service level agreements generate recurring revenue. Japanese electronics manufacturers attach per-device subscriptions where downtime costs exceed hardware depreciation significantly.
- Smart Cities:Municipal infrastructure deployments integrate traffic management, environmental monitoring, and public safety systems. India's PLI scheme for telecom equipment attracts edge node assembly investments serving South Asian urban rollouts.
- Connected Vehicles:Over-the-air update pipelines and autonomous decision chains require explainable AI modules under EU Act compliance.
- Energy Management:Grid-edge optimization and distributed generation control leverage real-time telemetry for demand response.
- Supply Chain Optimization:Asset tracking and condition monitoring span multimodal logistics networks.
Smart Manufacturing holds installed capacity. Smart Cities is rotating up the share rankings.
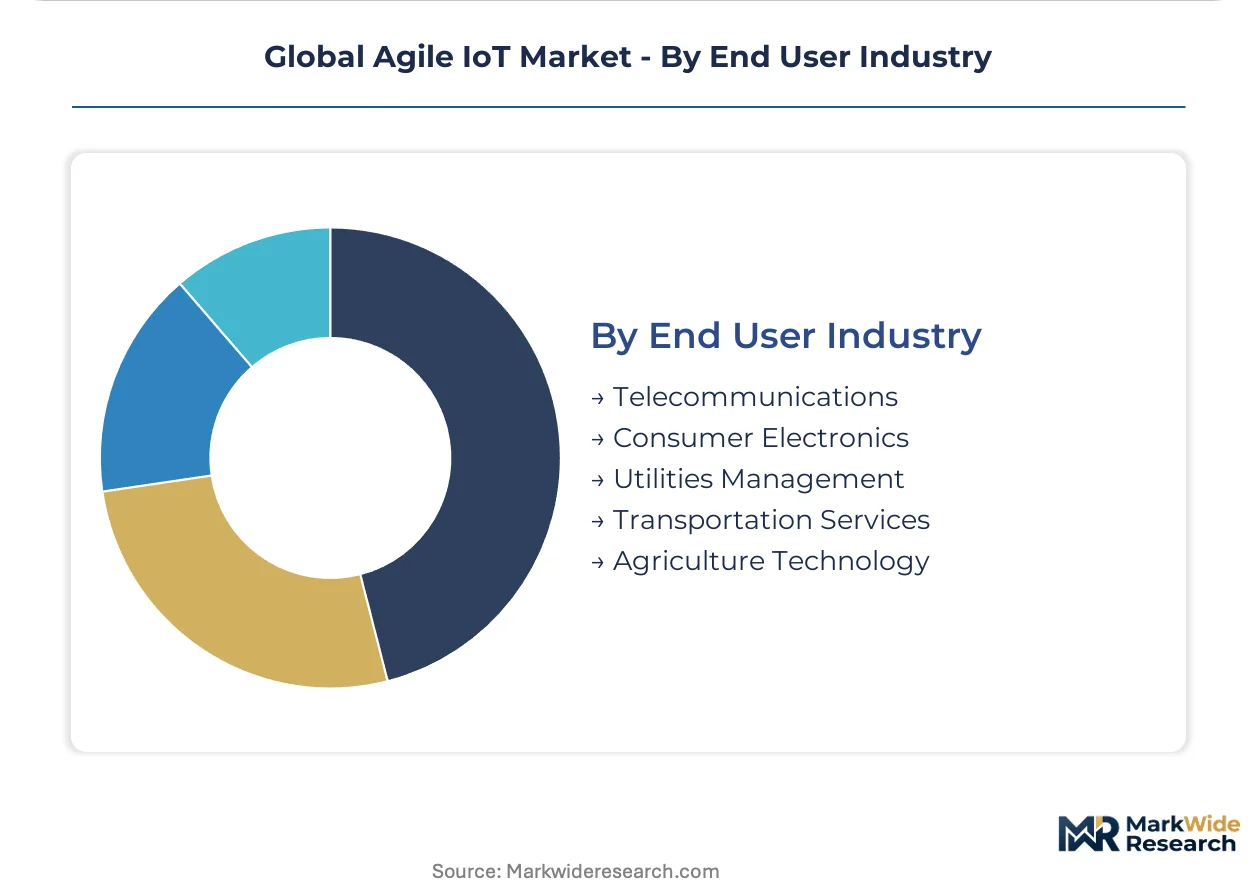
End User Industry:
Customer type differentiation reflects procurement sophistication and contract structure preferences.
- Telecommunications:Carrier-grade infrastructure demands 5G-Advanced network slicing with ultra-reliable low-latency communication modules. MIIT timelines in China drive bundled industrial gateway contract bids.
- Transportation Services:Fleet telematics and autonomous systems require deterministic response guarantees in safety-critical control loops.
- Consumer Electronics:Subscription-based device management displaces perpetual licenses among Japanese manufacturers.
- Utilities Management:Critical infrastructure protection mandates GB standards compliance for industrial internet security certification.
- Agriculture Technology:Precision farming deployments combine soil sensors, drone imagery, and automated irrigation control.
Telecommunications holds installed capacity. Transportation Services is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers deploy Agile IoT for deterministic closed-loop control, while Japanese precision manufacturers prioritize subscription-backed uptime guarantees. Chinese infrastructure bids bundle 5G-Advanced modules with industrial gateways. South Korean semiconductor fabs converge physics simulation with real-time telemetry. Indian smart city rollouts attract domestic edge node assembly through manufacturing incentives.
United States
Industrial campuses deploy private 5G networks through FCC CBRS spectrum allocations, bypassing carrier-managed subscription models. FERC grid-edge mandates accelerate distributed generation control deployments. The Pacific Northwest hosts cloud-native orchestration development for automotive over-the-air update pipelines.
Germany
Automotive Tier-1 suppliers source EU AI Act-certified edge nodes with mandatory explainability modules for autonomous decision chains. KBA conformity assessments drive procurement cycles for high-risk system hardware. The Stuttgart industrial corridor concentrates lightweight Kubernetes stack deployments for microservices virtualization.
Japan
Electronics manufacturers displace perpetual licenses with per-device subscription models tied to uptime-backed service level agreements. METI precision equipment standards mandate sub-100ms deterministic response guarantees. The Nagoya manufacturing belt anchors predictive maintenance contract expansion for mission-critical control loops.
China
MIIT 5G-Advanced timelines drive infrastructure bids bundling ultra-reliable low-latency communication modules with industrial gateway contracts. GB standards for industrial internet security force separate hardware SKUs for domestic versus export markets. The Yangtze River Delta concentrates edge node manufacturing scale for Asia-Pacific deployment.
South Korea
Semiconductor fabrication facilities merge physics simulation engines with real-time sensor streams for digital twin service revenue. MFDS-equivalent industrial safety frameworks shape certified hardware procurement. The Busan-Ulsan corridor hosts containerized microservices deployment for latency-critical process control.
Global Agile IoT Market Competitive Landscape
Capability concentration sits with hyperscale cloud platforms; scale advantage sits with telecom infrastructure vendors. The vendor base organizes around three strategic archetypes: silicon-to-cloud security integrators, manufacturing-scale hardware producers, and subscription-platform orchestrators. Dominant competitive moves include regional cloud instance expansion for data sovereignty compliance and container runtime optimization for deterministic edge inference.
Within the platform-orchestrator tier, Microsoft and Amazon Web Services exemplify recurring software attach rate strategies across enterprise accounts. Cisco Systems anchors the security-integration archetype through industrial gateway positioning. Huawei Technologies occupies the manufacturing-scale vector for 5G-enabled edge node production.
| Leading Market Players |
|---|
| Microsoft |
| Amazon Web Services |
| Cisco Systems |
| Huawei Technologies |
| IBM |
| Intel Corporation |
| Oracle |
| Siemens |
| Others |
Supply & Pricing Matrix
Taiwanese advanced node semiconductor fabrication clusters concentrate upstream supply for edge AI chips, anchoring margin pools in industrial gateway security stacks and subscription-based device management platforms downstream. This concentration amplifies pricing power for silicon vendors while compressing hardware margins at the edge layer.
Pricing Analysis
Long-term offtake agreements dominate procurement for 5G-enabled edge nodes, with Japanese electronics manufacturers locking in multi-year per-device subscriptions tied to uptime-backed service level agreements. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade—EU AI Act high-risk system compliance commands substantial premiums over uncertified alternatives. Cost compression in standard-tier hardware is intensifying because hardware commoditization squeezes gateway vendors without silicon-to-cloud integration. Industrial buyers in smart manufacturing prove least price-sensitive due to downtime costs exceeding hardware depreciation, while municipal smart city deployments exhibit highest sensitivity to upfront capital expenditure.
Supply Chain Analysis
Extended payment terms from German automotive Tier-1 suppliers are reshaping working capital requirements for industrial gateway manufacturers. Supply draws from Taiwan for advanced node semiconductors, China for 5G module assembly, and South Korea for memory components. Raw material dependencies span silicon wafers, rare earth elements for RF components, and specialized substrates for edge AI inference chips. Single-source vulnerability around Taiwanese fabrication facilities creates acute disruption risk during geopolitical tensions. Distribution runs through systems integrators serving vertical-specific deployments rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agile IoT architectures are approaching a platform-economics inflection where container orchestration virtualizes hardware-software binding, enabling workload portability that threatens incumbent vendor lock-in. Interoperability certification across fragmented national standards bodies will determine which ecosystems capture recurring revenue.
For Market Incumbents: Entrench position through silicon-to-cloud security integration in industrial gateways, defending against hyperscale cloud platforms encroaching on edge orchestration. Invest in EU AI Act certification capacity ahead of mandatory conformity assessments for autonomous decision systems. Deepen backward integration into edge AI chip design to escape commodity hardware margin compression.
For New Entrants and Emerging Players: India's PLI scheme-subsidized telecom equipment manufacturing represents the most penetrable entry point for edge node assembly serving South Asian smart city infrastructure rollouts. Mid-market precision equipment manufacturers in Southeast Asia offer underserved demand for subscription-based device management without incumbent renewal base entrenchment. Partner with lightweight Kubernetes distribution providers to bypass proprietary gateway vendor ecosystems.
For Investors and Strategic Acquirers: Capital is best deployed toward container runtime optimization specialists with deterministic sub-100ms response capabilities for mission-critical control loops. Long-term viability across the analysis window favors vendors bridging physics simulation engines with real-time sensor streams for digital twin service revenue. Monitor which regulator first mandates explainable AI for autonomous IoT decision chains as the inflection signal triggering cascading compliance investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure IoT stack sustains recurring software attach rates across enterprise accounts. |
| Acquisition of Specialist Firm | Container runtime optimization targets deterministic edge inference for German automotive suppliers. |
| Strategic Partnership | Cisco Systems anchors silicon-to-cloud security integration in industrial gateway positioning. |
| Geographic Expansion | Huawei Technologies competes on manufacturing scale for 5G-enabled edge nodes in Asia-Pacific. |
| Product Launch | Explainable AI modules embedded in edge inference engines meet EU AI Act contract prerequisites. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, MIIT infrastructure bid documentation, and EU regulatory compliance databases. Interviews with industrial gateway procurement managers, IoT platform engineers, regulatory affairs specialists at automotive Tier-1 suppliers, and systems integrators serving smart manufacturing deployments inform qualitative assessments. Bottom-up triangulation of device shipment volumes and top-down validation against aggregate infrastructure spending produce convergent estimates.
Forecast inputs span deployment topology shifts, solution layer maturity curves, and vertical adoption patterns across smart manufacturing, smart cities, and connected vehicles. Segmentation dimensions include edge computing versus cloud-centralized architectures, data analytics versus device management solution types, and precision equipment versus automotive end-use industries. CAGRs derive from installed base rotation rates and attach rate expansion for subscription services. 5G-Advanced network slicing timelines and FCC spectrum allocations shape infrastructure deployment phasing.
Stress conditions across Taiwanese semiconductor supply disruption, EU AI Act enforcement intensity, and 5G infrastructure subsidy withdrawal were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about protocol standardization velocity and container orchestration adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Connected Machines Market
Internet of Things (IoT)
IoT in BFSI Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
IoT Integration Market
Internet of Things (IoT)
Maritime Internet of Things Market
Internet of Things (IoT)
Enterprise IoT Market
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
IoT Application Enablement Market
Internet of Things (IoT)
Global Open IoT Platform Market
Internet of Things (IoT)
IoT Infrastructure Market
Internet of Things (IoT)
IoT in Warehouse Management Market
Internet of Things (IoT)
Massive Machine Type Communication Market
Internet of Things (IoT)
Europe Massive IoT Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
LTE IoT Market