
 Middle East and Africa IoT Node and Gateway Market | 2026-2036
Middle East and Africa IoT Node and Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa IoT Node and Gateway Market Foresight
Modular gateway configurations that separate radio modules from processing cores is recalibrating procurement patterns across enterprise buyers. Cisco leverages its channel density across Gulf data centers to dominate commercial deployments. Huawei Technologies Co., Ltd anchors large-scale smart city infrastructure with integrated node-to-cloud stacks. NXP Semiconductors specializes in secure element integration for payment and identity gateway applications.
An IoT node and gateway comprises edge computing hardware with embedded microcontrollers, multi-protocol radio front-ends, and power management circuits operating between 0.5W and 15W thermal envelopes, designed to aggregate sensor telemetry and execute local preprocessing before cloud handoff. Gateway devices command the dominant margin pool due to protocol translation complexity and cybersecurity certification requirements. Industrial Automation applications absorb the steepest volume growth as South African mining houses and Saudi petrochemical operators retrofit legacy Programmable Logic Controller networks with IP-enabled edge layers.
SFDA device cybersecurity guidelines in Saudi Arabia, South Africa's ICASA type-approval mandates for radio equipment, and Nigeria's NCC spectrum licensing frameworks collectively determine which gateway radio configurations gain market access across the region. The EU AI Act's extraterritorial reach into data governance is pressuring multinationals to embed explainable edge analytics in gateway firmware sold through Moroccan and Egyptian assembly channels. Stakeholders must weigh sovereign data localization requirements against modular supply chain flexibility when selecting node manufacturing partners.
Market Dynamics
Modular gateway architectures that separate radio modules from processing cores are fragmenting procurement patterns across enterprise buyers, forcing vendors to rebundle hardware and software components around sovereign data localization mandates.
Growth Catalysts
- SFDA Device Cybersecurity Guidelines:Saudi Arabia's mandatory firmware certification for medical and industrial gateways creates a captive certification pipeline that locks in compliant vendors across healthcare and petrochemical deployments.
- NEOM Smart City Infrastructure:The Saudi giga-project's integrated node-to-cloud requirements are pulling multi-protocol edge hardware into municipal networks at scale unmatched elsewhere in the region.
- 5G Spectrum Allocation:South Africa's ICASA and Nigeria's NCC rollout timelines are compressing deployment windows for cellular-enabled gateways across mining and logistics corridors.
Market Restraints
- Radio Chip Supply Concentration:Front-end module fabrication concentrates in East Asian foundries, exposing regional integrators to lead-time volatility and currency hedge costs.
- ICASA Type-Approval Timelines:South Africa's radio equipment certification queue stretches 8-14 months, freezing product launches for modular gateway vendors.
- Legacy PLC Integration Friction:South African mining houses and Saudi petrochemical operators face protocol translation costs that erode edge-layer retrofit economics.
Strategic Opportunities
- Nigerian Agricultural Corridors:Underpenetrated farm telemetry networks present white space for solar-powered LoRa gateways in the Niger Delta and northern irrigation belts.
- EU AI Act Extraterritorial Reach:Explainable edge analytics mandates are creating premium firmware tiers for Moroccan and Egyptian assembly channels serving European multinationals.
- Edge-to-Cloud Convergence:Containerized microservices on gateway hardware are enabling local AI inference without cloud handoff, opening subscription revenue models.
Industry Challenges
- Firmware Security Engineering Talent:Scarce embedded cryptography and secure-boot expertise concentrates in Johannesburg and Dubai, inflating R&D costs for regional vendors.
- Multi-Protocol Certification Stacking:Gateways must sequentially clear Wi-SUN, Thread, and cellular certifications for municipal smart-grid tenders, compressing margin windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa IoT Node and Gateway Market |
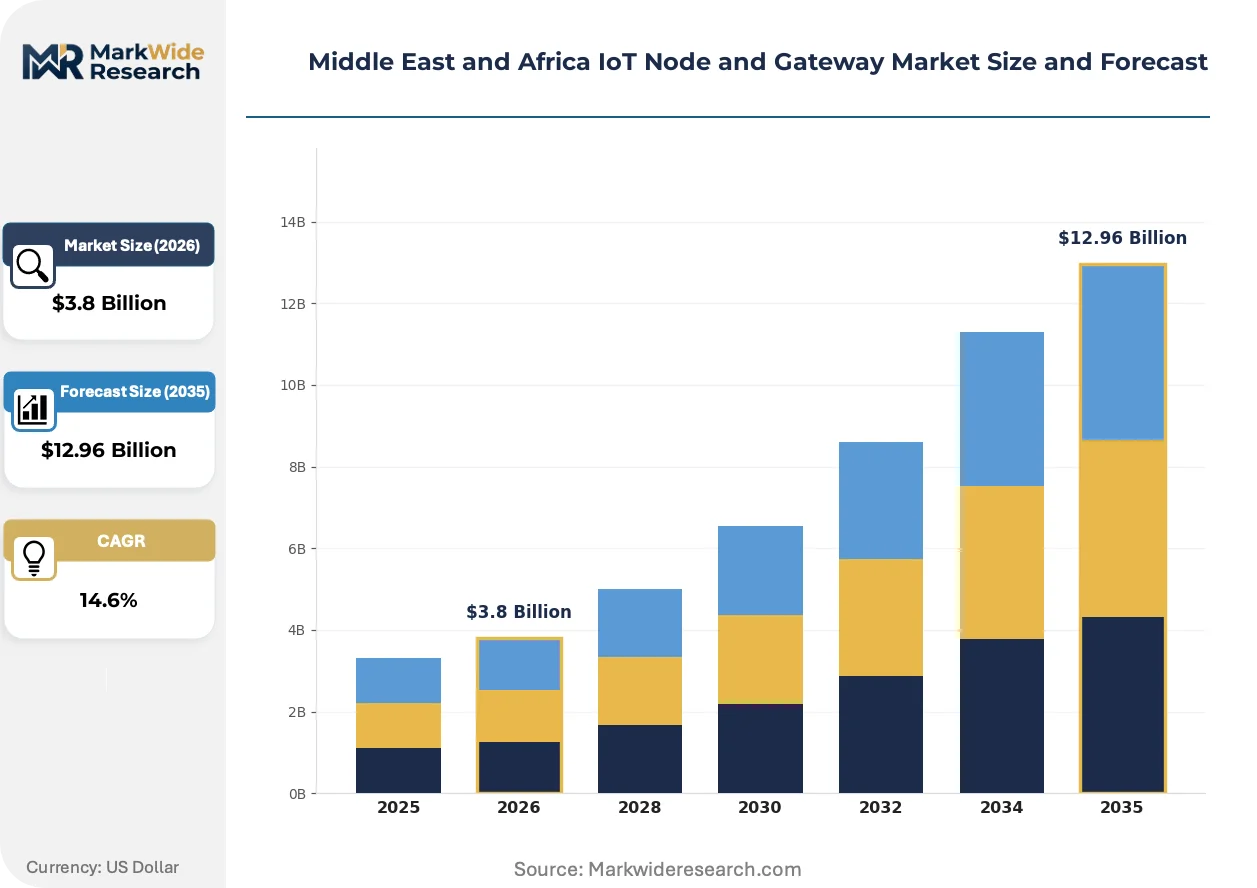
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor Nodes, Gateway Devices, Controllers, Actuators Application: Smart Home, Industrial Automation, Healthcare, Agriculture Technology: LPWAN, Zigbee, Bluetooth, Wi-Fi End User: Enterprise, Government, Retail, Utilities |
| Companies Covered | NXP Semiconductors, Huawei Technologies Co., Ltd, Dell, Texas Instruments Incorporated, Intel Corporation, Cisco, ARM LIMITED, TE Connectivity, Advantech Co., Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa IoT Node and Gateway Market Shifts & Advancements
Edge computing hardware is fragmenting into disaggregated compute-radio-power subsystems, enabling procurement flexibility that conflicts with integrated vendor stacks.
Software-defined radio (SDR) front-ends with field-upgradable modulation profiles are decentralizing gateway deployment models across Gulf municipal networks. Saudi smart-city operators are trialing SDR modules that switch between LoRa and NB-IoT without hardware swaps. This flexibility is compressing vendor lock-in and enabling multi-operator roaming agreements.
South Africa's ICASA type-approval mandates for radio equipment are forcing firmware transparency disclosures that expose proprietary stack architectures. Industrial automation buyers are leveraging this visibility to demand source-code escrow for gateway operating systems. The compliance burden falls heaviest on mid-tier vendors without dedicated regulatory affairs teams.
Enterprise buyers in the region are unbundling hardware procurement from managed connectivity services, reversing the bundled SaaS-gateway contracts that dominated early smart-city pilots. Johannesburg mining houses now source edge hardware directly while contracting connectivity separately through mobile network operators. This bifurcation is visible across Saudi petrochemical and South African logistics verticals.
Middle East and Africa IoT Node and Gateway Market Segmentation
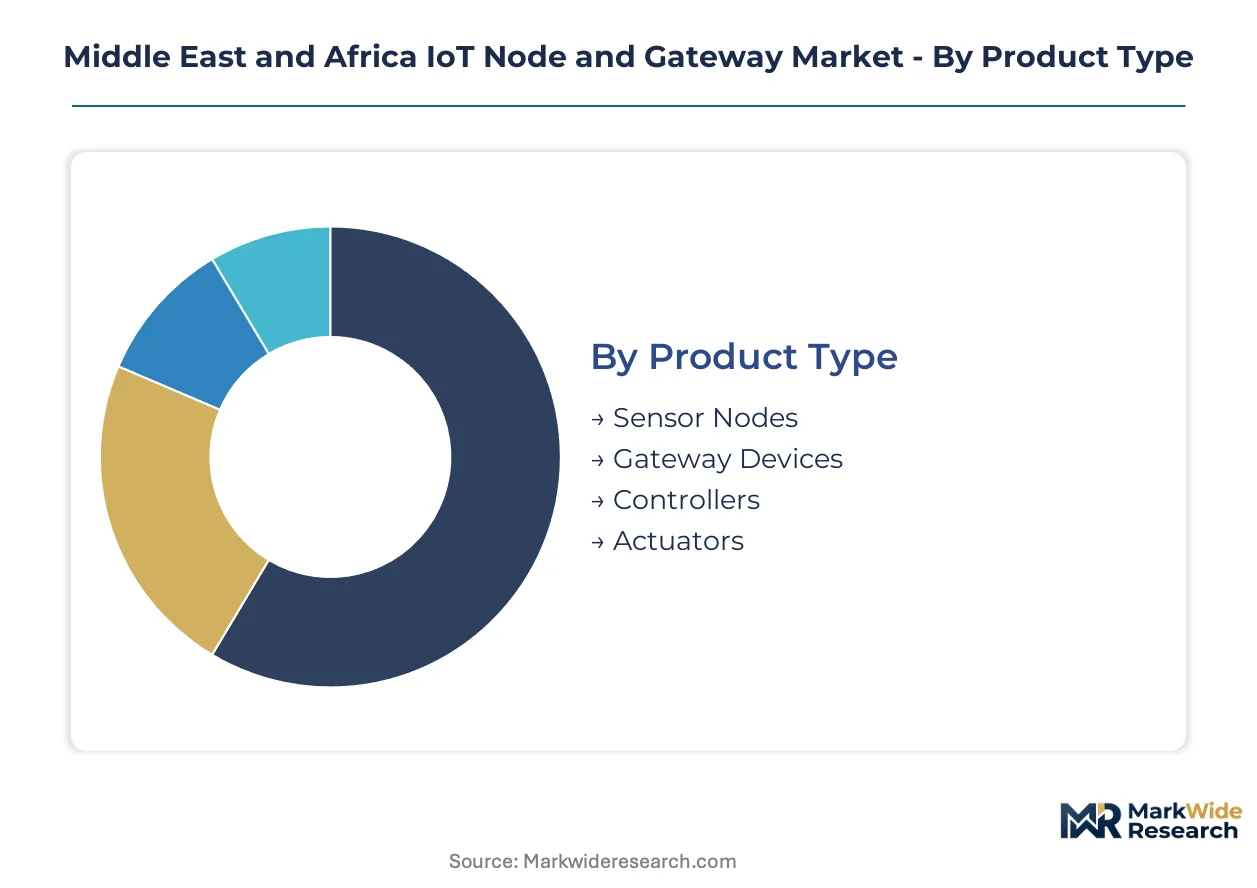
Hardware procurement in Middle East and Africa IoT deployments splits along protocol complexity and certification burden. Buyers weigh modular radio configurations against integrated stacks based on deployment scale and sovereign data mandates.
Product Type:
Enterprise buyers prioritize margin profiles and firmware certification requirements when selecting edge hardware tiers.
- Gateway Devices:Multi-protocol edge hardware with embedded microcontrollers and power management circuits operating between 0.5W and 15W thermal envelopes. NEOM municipal networks and Saudi petrochemical operators absorb the steepest volume as integrated node-to-cloud stacks displace fragmented procurement.
- Sensor Nodes:Compact telemetry endpoints with minimal preprocessing capability and sub-watt power budgets. Johannesburg mining houses deploy these at scale for legacy PLC network retrofits, though protocol translation friction erodes edge-layer economics.
- Controllers:Programmable automation interfaces bridging sensor arrays and actuator networks.
- Actuators:Command-execution hardware with embedded motor drivers or relay circuits.
Gateway Devices lead on scale; Sensor Nodes lead on momentum across industrial retrofit corridors.
Application:
Deployment velocity concentrates where capital expenditure cycles align with national infrastructure timelines.
- Industrial Automation:Edge-layer retrofits of legacy PLC networks in South African mining and Saudi petrochemical operations. ICASA type-approval queues and SFDA cybersecurity guidelines compress vendor selection windows for multi-protocol gateway tenders.
- Smart Home:Residential automation hubs with Zigbee and Wi-Fi front-ends. Gulf Cooperation Council municipal networks absorb volume through integrated smart-city pilots, though consumer adoption lags enterprise deployment.
- Healthcare:Medical-grade gateways with secure element integration for device telemetry.
- Agriculture:Solar-powered LoRa deployments in Nigerian irrigation belts and Niger Delta corridors.
Industrial Automation commands the dominant revenue pool; Agriculture climbs the fastest as underpenetrated farm telemetry networks open white space.
Technology:
Radio configuration decisions hinge on spectrum licensing frameworks and field-upgradability requirements.
- LPWAN:LoRa and NB-IoT front-ends optimized for low-bitrate, long-range telemetry. Nigerian agricultural corridors and Saudi municipal grids drive deployment as software-defined radio modules enable operator roaming without hardware swaps.
- Wi-Fi:High-throughput local area connectivity for dense sensor clusters. Enterprise buyers in Johannesburg and Dubai unbundle Wi-Fi gateway procurement from managed services, reversing bundled SaaS contracts.
- Zigbee:Mesh-networking stacks for residential and light commercial automation.
- Bluetooth:Short-range personal area networks for wearable and mobile device integration.
LPWAN dominates addressable volume; Wi-Fi gains share fastest through procurement bifurcation trends.
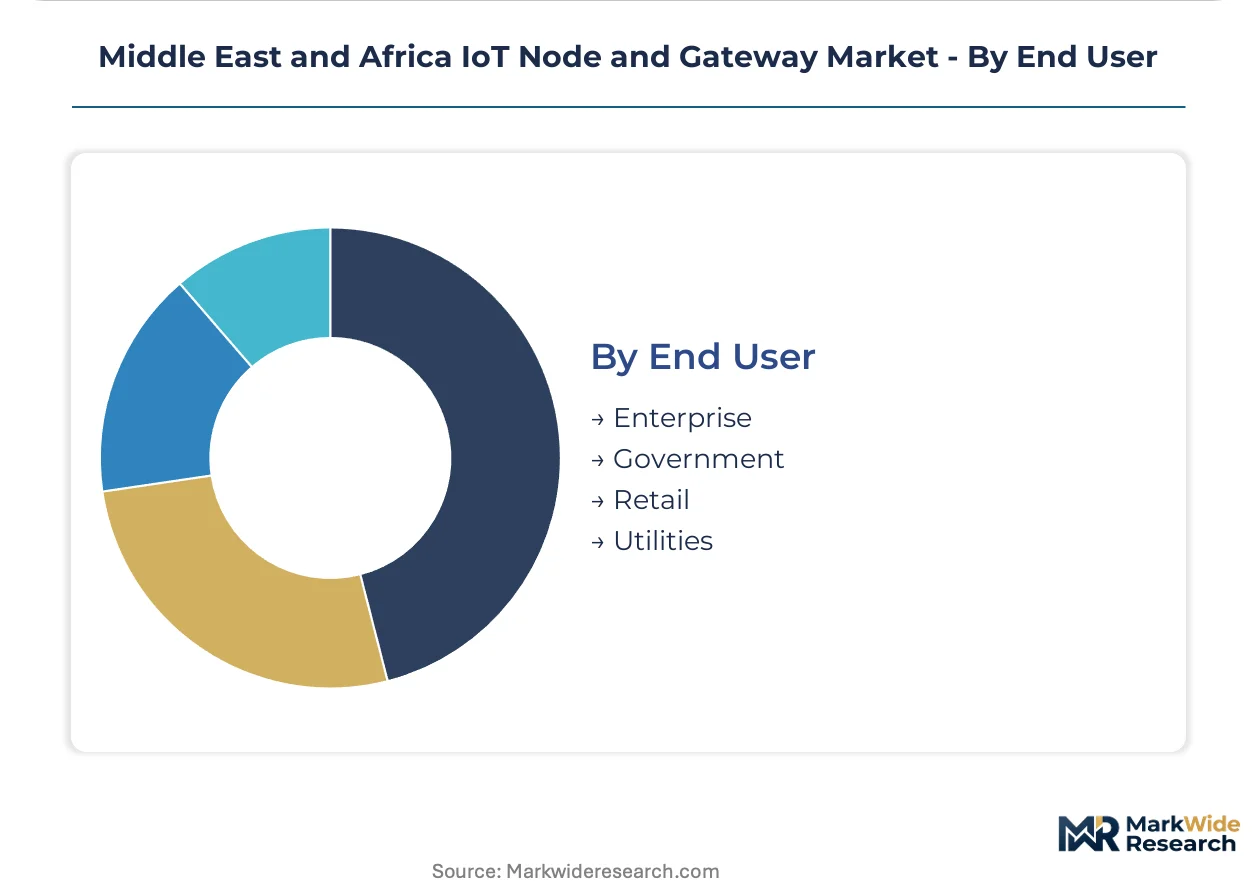
End User:
Budget authority and compliance burden shape vendor engagement models across buyer categories.
- Enterprise:Industrial and logistics operators with dedicated procurement teams and source-code escrow demands. South African mining houses and Saudi petrochemical operators source edge hardware directly while contracting connectivity separately through mobile network operators.
- Government:Municipal and national infrastructure agencies with sovereign data localization mandates. NEOM and Gulf Cooperation Council smart-city projects pull integrated node-to-cloud stacks through captive certification pipelines.
- Utilities:Grid and water operators with mission-critical uptime requirements.
- Retail:Commercial deployment of customer-facing sensor networks and inventory tracking.
Enterprise leads on transaction scale; Government expands most quickly through giga-project infrastructure timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East and Africa IoT node and gateway industry traces its commercial scaling to Gulf Cooperation Council smart-city pilots in the early 2010s, where municipal network upgrades first created sustained demand for multi-protocol edge hardware.
Saudi Arabia
NEOM's integrated node-to-cloud infrastructure and SFDA device cybersecurity guidelines are pulling certified gateway hardware through captive procurement pipelines. The kingdom's national regulator mandates firmware transparency for medical and industrial deployments. Riyadh and the Eastern Province petrochemical corridor absorb the steepest hardware volumes as retrofit timelines compress.
South Africa
ICASA type-approval queues stretching 8-14 months are freezing product launches for modular gateway vendors serving mining and logistics verticals. Johannesburg mining houses now unbundle hardware procurement from managed connectivity contracts. The industrial heartland around Gauteng drives edge-layer retrofit demand for legacy PLC networks.
United Arab Emirates
Dubai's municipal smart-grid tenders require sequential Wi-SUN, Thread, and cellular certifications that compress margin windows for gateway vendors. MOHAP device interoperability standards shape healthcare gateway specifications. Abu Dhabi's data center corridor anchors Gulf commercial deployments for enterprise buyers.
Nigeria
NCC spectrum licensing frameworks for LoRa and NB-IoT are opening white space for solar-powered agricultural gateways in the Niger Delta and northern irrigation belts. Underpenetrated farm telemetry networks present volume opportunities for low-power edge hardware. Lagos anchors commercial pilot programs before national scaling.
Morocco
Assembly channels serving European multinationals face EU AI Act extraterritorial pressure to embed explainable edge analytics in gateway firmware. The country's manufacturing clusters supply modular hardware northward into Mediterranean markets. Casablanca's industrial zones concentrate firmware engineering talent for regional vendors.
Middle East and Africa IoT Node and Gateway Market Competitive Landscape
The competitive structure tilts toward integrated technology conglomerates with captive certification pipelines and channel density across Gulf data centers. Vendor selection windows compress around sovereign data localization mandates, forcing hardware and software rebundling. Three archetypes dominate: Gulf-anchored commercial deployers, integrated node-to-cloud stack providers, and secure element specialists for payment and identity applications. Competitive moves concentrate on strategic partnerships with municipal infrastructure agencies and portfolio diversification into software-defined radio modules.
Among integrated stack providers, Huawei Technologies Co., Ltd and Cisco occupy positions spanning infrastructure deployment and commercial channel access. NXP Semiconductors represents the secure element specialization archetype for gateway applications requiring payment and identity certification. These three anchors exemplify how vendor positioning fragments across procurement bifurcation trends, with enterprise buyers sourcing hardware directly while government tenders pull integrated systems through captive pipelines.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Huawei Technologies Co., Ltd |
| Dell |
| Texas Instruments Incorporated |
| Intel Corporation |
| Cisco |
| ARM LIMITED |
| TE Connectivity |
| Advantech Co., Ltd. |
| Others |
Supply & Pricing Matrix
Embedded firmware engineering talent concentration in Casablanca and Dubai creates labor-cost differentials that widen pricing-tier spreads between premium-certified gateway stacks and economy-grade modular configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification burden and protocol complexity. Premium tiers command spreads based on SFDA cybersecurity compliance and ICASA type-approval status, while economy tiers compete on stripped-down LoRa configurations for Nigerian agricultural corridors. Price differentiation hinges on firmware transparency disclosures and multi-protocol certification stacking. Cost compression in standard tiers intensifies as Johannesburg mining houses unbundle hardware procurement from managed connectivity services. Government tenders through NEOM and Gulf municipal networks exhibit the lowest price sensitivity; mid-tier vendors serving South African logistics verticals face the highest.
Supply Chain Analysis
Single-source vulnerability sits with East Asian foundries for radio front-end module fabrication, exposing regional integrators to lead-time volatility and currency hedge costs. Gateway hardware draws from semiconductor supply chains anchored in Taiwan, South Korea, and China for embedded microcontrollers and multi-protocol radio chipsets. Critical component dependencies include secure elements from NXP-certified fabs, power management circuits, and software-defined radio modules. Tariff exposure through Moroccan assembly channels serving European multinationals compounds supply chain fragility. Distribution runs through Dubai data center corridors for Gulf commercial deployments and Johannesburg industrial zones for South African mining retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where NEOM's integrated node-to-cloud requirements pull premium-specification gateway hardware through captive certification pipelines, displacing fragmented procurement.
For Market Incumbents: Cement certification pipeline control by deepening captive relationships with Saudi SFDA and South African ICASA regulatory affairs teams. Acquire firmware engineering talent clusters in Casablanca and Dubai to defend against modular gateway vendors eroding margin pools through software-defined radio flexibility. Lock in multi-year node-to-cloud stack contracts with Gulf municipal infrastructure agencies before procurement bifurcation accelerates. For New Entrants and Emerging Players: SFDA device cybersecurity guidelines in Saudi Arabia open a window for specialized secure-element gateway vendors to penetrate medical and industrial verticals through compliance-first positioning. Target underpenetrated Nigerian agricultural corridors with solar-powered LoRa gateway configurations optimized for NCC spectrum licensing frameworks. Lead with subscription-based edge-analytics firmware tiers that satisfy EU AI Act extraterritorial requirements for Moroccan assembly channels. For Investors and Strategic Acquirers: Integrated technology conglomerates with Gulf data center channel density are the most active acquirer in this space, consolidating modular gateway vendors to rebundle hardware and software around sovereign data localization mandates. Focus acquisition screens on mid-tier vendors with dedicated regulatory affairs teams and ICASA/SFDA certification pipelines. Watch for inflection when Johannesburg mining houses accelerate legacy PLC retrofit timelines or when Nigerian NCC finalizes national LoRa roaming frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pipeline Investment | SFDA and ICASA compliance locks in vendor selection windows for multi-protocol gateway tenders. |
| Software-Defined Radio Module Launch | Field-upgradable modulation profiles enable Saudi municipal operators to switch between LoRa and NB-IoT without hardware swaps. |
| Firmware Engineering Talent Acquisition | Casablanca and Dubai talent clusters anchor secure-boot and embedded cryptography capabilities for regional vendors. |
| Edge-to-Cloud Stack Integration | Containerized microservices on gateway hardware open subscription revenue models for local AI inference without cloud handoff. |
| Regulatory Affairs Team Buildout | Dedicated teams compress ICASA type-approval timelines from 8-14 months for modular gateway vendors. |
Research Methodology
Multiple input streams — primary interviews with embedded systems engineers, municipal procurement officers, and regulatory affairs specialists; secondary validation through SFDA device filings, ICASA type-approval databases, and NCC spectrum licensing records; plus customs data on radio equipment imports — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned gateway hardware vendors, smart-city infrastructure agencies, and mining house automation directors across Saudi Arabia, South Africa, Nigeria, and the UAE.
Historical shipment data cross-referenced against panel input from industry participants shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application vertical, radio technology protocol, and end-user category. CAGRs were derived from unit economics trajectories in industrial automation retrofits and municipal smart-grid deployments. Key forecast inputs incorporated NEOM infrastructure timelines, 5G spectrum allocation schedules from ICASA and NCC, and EU AI Act compliance cost assumptions for Moroccan assembly channels.
Revisions become necessary when sovereign data localization mandates tighten, East Asian foundry capacity constraints deepen, or modular procurement bifurcation accelerates faster than integrated vendor rebundling efforts. Forecasts reflect assumptions about regulatory queue processing speeds and certification cost pass-through elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global IoT Solutions and Services Market
Internet of Things (IoT)
Location of Things Market
Internet of Things (IoT)
IoT Operating System Market
Internet of Things (IoT)
Global IoT Managed Services Market
Internet of Things (IoT)
US Smart Thermostat Market
Internet of Things (IoT)
Internet of Things (IoT) in Utilities Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
Global 5G Industrial IOT Market
Internet of Things (IoT)
Global Internet of Things (IoT) Defence Market
Internet of Things (IoT)
Global IOT Gateway Market
Internet of Things (IoT)
Wireless Connected Devices Market
Internet of Things (IoT)
Global IoT Routers Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
IoT Gateway Hardware and Software Market
Internet of Things (IoT)
IoT Solutions Market
Internet of Things (IoT)
IoT Software Engineering Market