
 Silicone Tape Market | 2026-2036
Silicone Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Tape Market Analysis
Electrical insulation is realigning the Silicone Tape Market as renewable energy buildouts expand conductor protection needs. 3M leverages its polymer science depth to sustain leadership in high-voltage insulating formulations. H.B. Fuller Company anchors industrial adhesive tape supply chains across North American manufacturing corridors.
Silicone tape comprises a self-fusing, polydimethylsiloxane-based elastomer that bonds to itself without adhesive, typically rated for continuous operating temperatures from -60°C to 260°C and dielectric strengths exceeding 300 V/mil. Medical grade formulations dominate margin pools due to biocompatibility testing burdens and FDA master file requirements, while electrical grade segments lead volume throughput from utility-scale solar and wind installations. Rolls remain the standard form factor for industrial procurement, though pre-cut strips gain traction in automotive assembly lines seeking kit-based workflow efficiency.
REACH and RoHS frameworks in Europe restrict residual platinum catalyst content and halogenated additives, compelling reformulation investments from tape producers seeking CE-marked market access. China's SAMR enforces updated GB standards for electrical insulation materials that now incorporate accelerated aging test protocols. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation threatens to partition supply chains into region-specific product variants with incompatible certification paths.
Market Dynamics
Renewable energy infrastructure buildouts are compressing procurement cycles for electrical-grade silicone tape, forcing producers to recalibrate inventory depth and certification pipelines around utility-scale solar and wind deployment schedules.
Growth Catalysts
- Offshore wind cabling standards:Subsea conductor protection mandates in Germany's North Sea installations are pulling specialized high-voltage tape formulations through certification queues faster than conventional industrial grades.
- REACH Article 33 disclosure thresholds:ECHA's tightened reporting on residual platinum catalyst content is accelerating reformulation investment among tape producers seeking CE-marked market access.
- Solar farm arc-fault mitigation:Utility-scale photovoltaic installations in Texas and Arizona are specifying silicone tape for busbar insulation as NEC compliance deadlines tighten.
Market Restraints
- Platinum catalyst cost volatility:Hydrosilylation chemistry depends on platinum group metal prices that swung 40% between 2022-2024, compressing margin predictability for medical-grade tape producers.
- Fluorosilicone substitution threat:Fuel-resistant fluorosilicone elastomers are capturing aerospace sealing applications previously served by standard polydimethylsiloxane tapes.
- GB standard divergence:SAMR's accelerated aging test protocols for electrical insulation materials are creating incompatible certification paths with IEC baselines, fragmenting export product lines.
Strategic Opportunities
- India's PLI scheme for solar manufacturing:Domestic content requirements under the production-linked incentive program are pulling tape producers toward joint ventures with Gujarat-based module assemblers.
- EV battery pack thermal management:Cell-to-pack architectures are opening specification windows for flame-retardant silicone tape in Chinese and South Korean gigafactory supply chains.
- Digital inventory platforms:Industrial distributors are deploying AI-driven stock positioning for MRO customers, compressing lead times for pre-cut automotive kit components.
Industry Challenges
- Compounding technician scarcity:Two-roll mill operators with polysiloxane formulation expertise are retiring faster than apprentices complete training programs at German and Japanese specialty chemical plants.
- FDA master file synchronization:Biocompatibility testing documentation for medical-grade tapes requires 18-24 month alignment between ISO 10993 updates and 510(k) submission windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Tape Market |
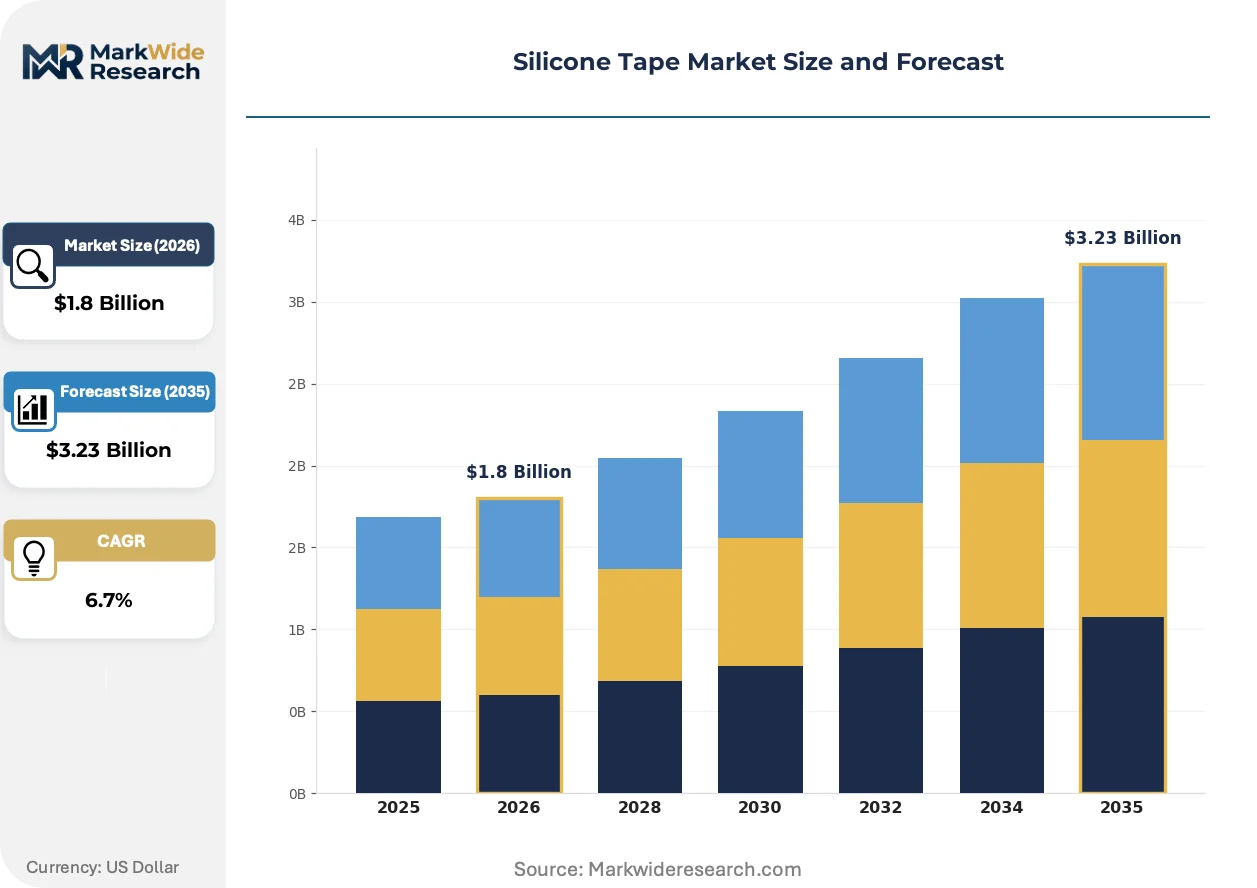
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Grade, Electrical Grade, High-Temperature Grade, Consumer Grade Application: Healthcare, Automotive, Electrical Insulation, Construction End User: Hospitals, Manufacturers, Contractors, DIY Enthusiasts Form: Rolls, Sheets, Pre-Cut Strips, Custom Shapes |
| Companies Covered | 3M, Cheever Specialty Paper and Film, CS Hyde Company, DermaRite Industries, Gergonne, Scapa, Harbor Products, Permatex, H.B. Fuller Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Tape Market Emerging Trajectories
Self-fusing chemistry is migrating beyond traditional electrical insulation into structural bonding applications, while regulatory pressure on residual catalyst content is forcing material science investments that will reshape competitive positioning over the next decade.
Additive manufacturing integration is overtaking conventional tape application methods in wind turbine blade repair workflows. Technicians at Siemens Gamesa service hubs are depositing silicone tape through automated extrusion heads for leading-edge erosion protection. This robotic application is compressing repair cycle times from days to hours while reducing material waste ratios.
REACH Annex XVII restrictions on halogenated flame retardants are compelling tape producers to validate phosphorus-nitrogen synergist systems for electrical-grade formulations. The industrial consequence is a 12-18 month reformulation lag as compounders rebuild UL 94 V-0 certification portfolios. German industrial corridor producers are responding fastest, leveraging existing ECHA pre-registration data to accelerate substitution timelines.
Kit-based procurement is consolidating purchase authority for automotive assembly lines. Tier-1 suppliers at BMW and Volkswagen plants are specifying pre-dimensioned tape strips bundled with torque-sequence documentation, displacing bulk roll purchasing. This specification bundling is most visible in Bavarian and Lower Saxony manufacturing clusters where just-in-sequence delivery contracts now dominate MRO sourcing.
Silicone Tape Market Segmentation
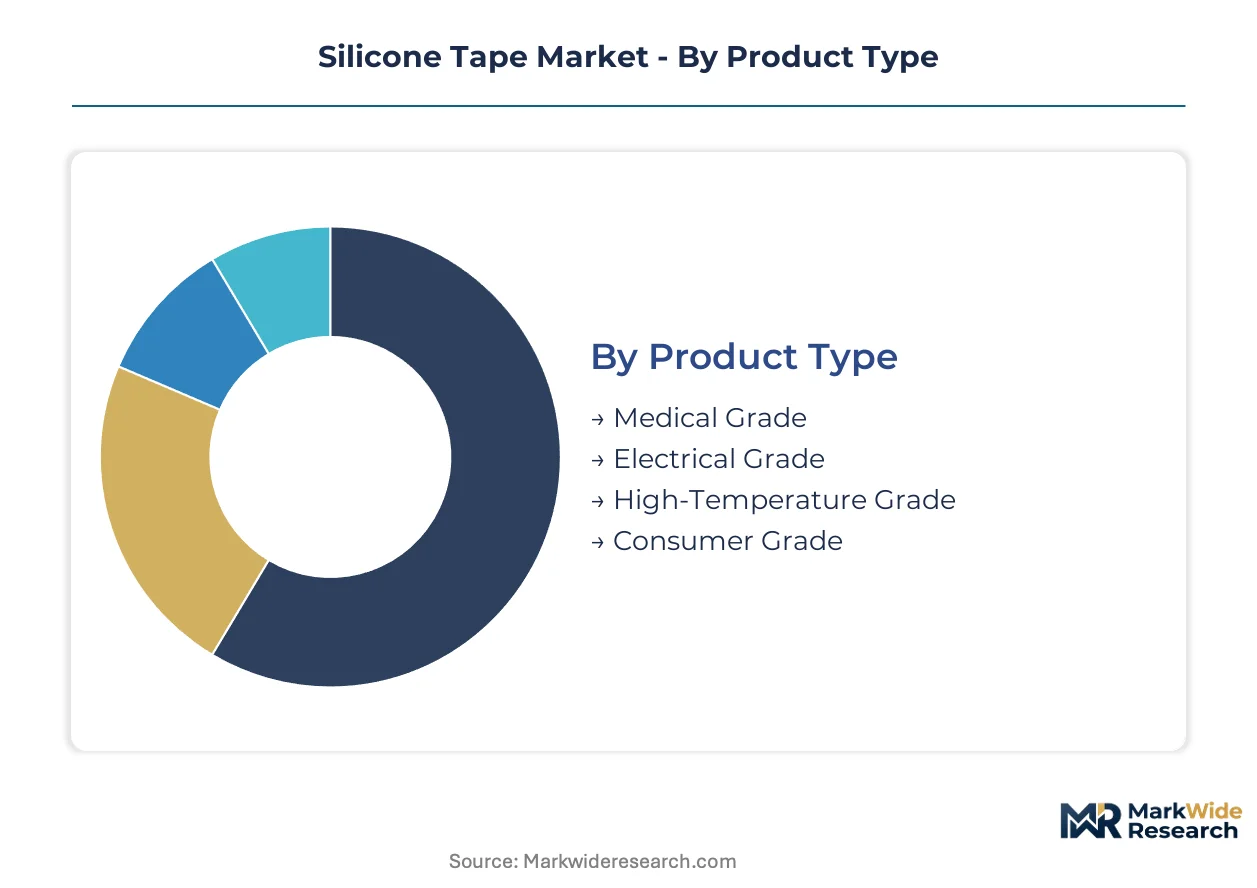
Silicone tape buyers exhibit sharply divergent technical requirements across end-use contexts, from FDA biocompatibility mandates in healthcare to arc-fault specifications in utility-scale solar. Segmentation clarity enables producers to align formulation investments, certification pipelines, and distribution channels with the specific performance thresholds each buyer category demands.
Product Type:
Cost tier separates buyers seeking commodity protection from those requiring certified performance under extreme operating conditions.
- Medical Grade:Biocompatible polydimethylsiloxane formulations undergo ISO 10993 cytotoxicity and sensitization testing, with FDA master file documentation creating 18-24 month qualification cycles. German hospital procurement consortiums and US ambulatory surgical centers drive premium pricing for hypoallergenic adhesive alternatives.
- Electrical Grade:Dielectric strengths exceeding 300 V/mil and continuous thermal ratings to 260°C characterize these formulations. Utility-scale wind installations in Texas and offshore substations in the German North Sea are compressing procurement cycles for arc-fault compliant tapes.
- High-Temperature Grade:Specialized fillers extend operational ceilings for aerospace engine bay applications and industrial furnace maintenance.
- Consumer Grade:General-purpose formulations serve household repair and hobbyist markets through retail hardware channels.
Electrical Grade leads volumes today; Medical Grade is gaining share fastest.
Application:
Volume concentration tracks regulatory enforcement intensity and infrastructure buildout schedules across end-use sectors.
- Healthcare:Wound care, surgical draping, and medical device fixation applications require sterilization-stable adhesion. REACH and FDA dual compliance burdens concentrate procurement authority among contract manufacturers serving Bavarian and Baden-Württemberg medical device clusters.
- Electrical Insulation:Busbar wrapping, motor lead insulation, and cable splicing dominate throughput. China's State Grid Corporation and India's Power Grid Corporation are specifying silicone tape for renewable energy interconnection projects under tightened national electrical codes.
- Automotive:Wire harness bundling and sensor protection in EV battery packs are opening specification windows.
- Construction:Weather sealing and temporary repair applications serve maintenance contractors in Gulf Coast petrochemical corridors.
Electrical Insulation commands the largest volume position; Healthcare demonstrates the steepest margin expansion trajectory.
End User:
Procurement sophistication varies from centralized tender processes to fragmented retail demand across buyer categories.
- Manufacturers:Tier-1 automotive suppliers and medical device OEMs impose lot traceability, statistical process control documentation, and just-in-sequence delivery requirements. BMW's Bavarian assembly network and Volkswagen's Lower Saxony plants specify pre-dimensioned tape kits bundled with torque-sequence protocols.
- Hospitals:Group purchasing organizations consolidate acquisition for wound care and surgical applications, with infection control committees vetting biocompatibility certifications.
- Contractors:Industrial maintenance crews in German chemical corridors and US Gulf Coast refineries prioritize thermal performance over brand specification.
- DIY Enthusiasts:Price-sensitive retail demand flows through home improvement chains and e-commerce marketplaces.
Manufacturers represent the dominant volume segment; Hospitals are expanding procurement most quickly.
Form:
Workflow integration requirements determine whether buyers prioritize material efficiency or labor productivity in format selection.
- Rolls:Standard industrial procurement format enables field-cut customization for cable splicing and irregular surface coverage. Electrical contractors in Arizona solar farms and North Sea offshore technicians maintain inventory depth for unplanned repair scenarios.
- Pre-Cut Strips:Kit-based supply to automotive assembly lines eliminates on-line measurement and cutting operations. Bavarian and Lower Saxony manufacturing clusters have shifted MRO sourcing toward dimension-specified bundles.
- Sheets:Die-cut applications serve gasketing and membrane fabrication in medical device production.
- Custom Shapes:3D-printed tooling and laser cutting accommodate prototype runs and specialized aerospace sealing geometries.
Rolls retain the dominant volume position; Pre-Cut Strips are climbing the fastest as automotive kit procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting silicone tape production toward jurisdictions with streamlined certification pathways, as REACH compliance costs in Europe diverge from GB standard timelines in China and FDA master file burdens in the United States.
Germany
Offshore wind cabling mandates in the North Sea are pulling specialized high-voltage formulations through accelerated certification queues. ECHA's tightened Article 33 disclosure thresholds on residual platinum catalyst content are forcing reformulation investments among producers seeking CE-marked access. Bavarian automotive clusters and Lower Saxony assembly plants are consolidating procurement around pre-dimensioned tape kits bundled with torque-sequence documentation.
United States
Utility-scale solar installations in Texas and Arizona are specifying silicone tape for busbar insulation as NEC compliance deadlines tighten. FDA master file requirements for medical-grade formulations impose 18-24 month qualification cycles that concentrate procurement authority among contract manufacturers. Gulf Coast petrochemical corridors prioritize thermal performance specifications for industrial maintenance applications over brand loyalty.
China
State Grid Corporation procurement for renewable energy interconnection projects is compressing delivery schedules for electrical-grade tape. SAMR's updated GB standards for electrical insulation materials now incorporate accelerated aging test protocols that diverge from IEC baselines. Eastern manufacturing belt compounders are fragmenting export product lines to accommodate incompatible certification paths between domestic and international markets.
India
Domestic content requirements under the PLI scheme for solar manufacturing are pulling tape producers toward joint ventures with Gujarat-based module assemblers. Central Electricity Authority specifications for grid infrastructure are tightening material certification requirements for conductor protection applications. Maharashtra and Karnataka industrial corridors are emerging as procurement concentration points for electrical insulation materials.
Silicone Tape Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with medical-grade procurement concentrating among FDA master file holders while electrical-grade volumes fragment across regional compounders. The vendor base organizes into three strategic archetypes: diversified materials conglomerates with polymer science depth, specialty adhesive tape fabricators serving industrial MRO channels, and medical-grade specialists carrying biocompatibility certification burdens. Competitive moves center on reformulation investments to meet REACH and GB standard divergence, plus geographic expansion through joint ventures in India's PLI-driven solar corridor.
Among diversified materials conglomerates, 3M anchors premium positioning through polymer science capabilities, while H.B. Fuller Company occupies a central role in North American industrial adhesive supply chains. Specialty fabricators including Scapa and Gergonne exemplify the mid-tier segment serving regional MRO procurement patterns. These named entities represent archetype positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| 3M |
| Cheever Specialty Paper and Film |
| CS Hyde Company |
| DermaRite Industries |
| Gergonne |
| Scapa |
| Harbor Products |
| Permatex |
| H.B. Fuller Company |
| Others |
Supply Flow & Price Mechanics
Tier-1 automotive suppliers and medical device OEMs command pricing power through consolidated procurement authority, forcing tape producers to stratify offerings across certification-grade tiers rather than compete on commodity margins.
Pricing Analysis
Distributor margins in industrial MRO channels absorb 15-25 points before product reaches maintenance crews at German chemical corridors or Gulf Coast refineries. Three-tier pricing structure across medical, electrical, and consumer grades reflects ISO 10993 and UL 94 V-0 certification burdens. Cost compression in electrical-grade segments is intensifying because platinum catalyst volatility feeds directly into compounder cost bases. DIY enthusiasts through retail hardware chains exhibit highest price sensitivity; FDA master file holders serving hospital GPOs face least.
Supply Chain Analysis
Single-source vulnerability sits with platinum group metal refiners concentrated in South Africa and Russia, where hydrosilylation chemistry feedstock originates. Silicone tape production draws from polydimethylsiloxane base polymer supply anchored in Germany, China, and Japan. Tariff exposure on medical-grade formulations threatens cross-border shipment economics between European compounders and US contract manufacturers. Distribution runs through industrial distributors deploying AI-driven stock positioning for MRO customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical-grade margin expansion is accelerating as biocompatibility certification barriers filter out commodity competitors, while electrical-grade producers capture cost-down benefits from automated compounding lines.
For Market Incumbents: Acquire compounding technician training programs and apprenticeship pipelines to offset retirement-driven expertise attrition at German and Japanese specialty chemical plants. Secure backward integration into platinum catalyst recovery systems to dampen hydrosilylation input volatility. Defensive priority centers on fluorosilicone substitution threats in aerospace sealing applications previously served by standard polydimethylsiloxane tapes. For New Entrants and Emerging Players: The price-point gap between FDA master file medical-grade premiums and electrical-grade commodity pricing offers entry leverage for hybrid formulations targeting Indian solar manufacturing joint ventures. White-space concentration sits with Gujarat-based module assemblers under PLI domestic content requirements. Go-to-market angle should emphasize accelerated GB standard certification for SAMR-compliant electrical insulation exports. For Investors and Strategic Acquirers: Diversified materials conglomerates with polymer science depth are the most active acquirer in this space, seeking medical-grade certification assets. Long-term viability frames around 5-10 year regulatory divergence windows where REACH and GB standard incompatibility creates regional product line fragmentation. Acquisition target archetype: specialty adhesive tape fabricators with ECHA pre-registration data assets. Signal to monitor: ECHA Article 33 disclosure threshold tightening on residual platinum catalyst content.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Platinum Catalyst Recovery | Secures hydrosilylation input supply against South African and Russian refinery volatility. |
| Medical-Grade FDA Master File Acquisition | Captures 18-24 month qualification cycle barriers that filter commodity competitors. |
| Joint Venture in Gujarat Solar Corridor | Positions for PLI scheme domestic content requirements pulling tape producers toward module assemblers. |
| Automated Compounding Line Deployment | Offsets technician scarcity as two-roll mill operators retire faster than apprentices complete training. |
| Phosphorus-Nitrogen Flame Retardant Reformulation | Anticipates REACH Annex XVII halogenated additive restrictions with 12-18 month certification lead time. |
Methodological Framework
Coverage spans Germany, United States, China, and India, with primary inputs from each. This study combines interviews with silicone compounder plant managers, procurement leads at Tier-1 automotive suppliers, distribution channel partners, and technical R&D directors with secondary validation. Sources include customs and trade data, ECHA pre-registration databases, SEC 10-K filings from diversified materials conglomerates, and SAMR GB standard documentation. Bottom-up segment sizing triangulates against top-down market envelope estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. The analytical framework models grade tier, end-use industry, form factor, and regional production hub dimensions. CAGRs derive from segment-level growth rate aggregation weighted by base-year revenue shares. Industry-specific inputs include utility-scale solar deployment schedules from Texas and Arizona interconnection queues, plus offshore wind cabling procurement timelines from Germany's North Sea installations.
Caveats apply where platinum group metal price volatility, regulatory divergence between REACH and GB standards, or compounding technician training pipeline failures could materially shift the outlook. Forecasts reflect assumptions about certification timeline stability and renewable energy infrastructure buildout continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Gaffers Tape Market
Tapes
Tape Unwinder Market
Tapes
Pressure Sensitive Tapes and Labels Market
Tapes
Automotive Tapes Market
Tapes
PVC Tapes Market
Tapes
Seam Tapes Market
Tapes
Replica Tapes Market
Tapes
Tape Stretching Line Market
Tapes
Paper Gummed Tape Market
Tapes
Flatback Tapes Market
Tapes
Umbilical Tapes Market
Tapes
Carbon Tapes Market
Tapes
Breathable Tape Market
Tapes
Sterilization Indicator Tape Market
Tapes
Application Tapes Market
Tapes
Tape Banding Machine Market