
 Non Woven Water Blocking Tape Market | 2026-2036
Non Woven Water Blocking Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Non Woven Water Blocking Tape Market Insights
Modular cable bundling is pivoting procurement patterns as utilities specify pre-configured water-blocking layers rather than field-applied alternatives. 3M leverages its materials science portfolio to supply integrated tape-and-barrier systems for submarine cable OEMs. Berry Global Group, Inc. anchors North American production capacity with vertically oriented nonwoven lines serving utility infrastructure. Nitto Denko Corporation specializes in thin-gauge precision coatings that differentiate its offerings in electronics-grade applications.
Non woven water blocking tape consists of a fibrous substrate, typically polypropylene or polyester spunbond mat, impregnated with superabsorbent polymers that swell upon moisture contact to seal cable interstices; manufacturers calibrate swelling rate and tensile retention to IEC 60502-2 and IEEE 404 test protocols for medium and high-voltage power cables. Single-Sided configurations dominate volume shipments due to their compatibility with standard cable wrapping lines, while Specialty grades command margin pools in subsea and nuclear-rated installations where certification barriers limit supplier entry. Polypropylene material substrates lead on cost efficiency for terrestrial utility projects, though Polyester variants sustain price premiums in automotive harness applications demanding thermal stability above 125°C.
REACH restrictions on SAP chemistries and RoHS substance thresholds constrain formulation choices for European cable suppliers, while China's GB/T standards and MIIT cable industry directives shape domestic procurement specifications. The US FAA and NHTSA both influence transportation-sector tape requirements through flammability and emissions compliance pathways for mass-transit and electric vehicle cabling. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment supply chain economics and determine which material platforms achieve cross-border scale.
Market Dynamics
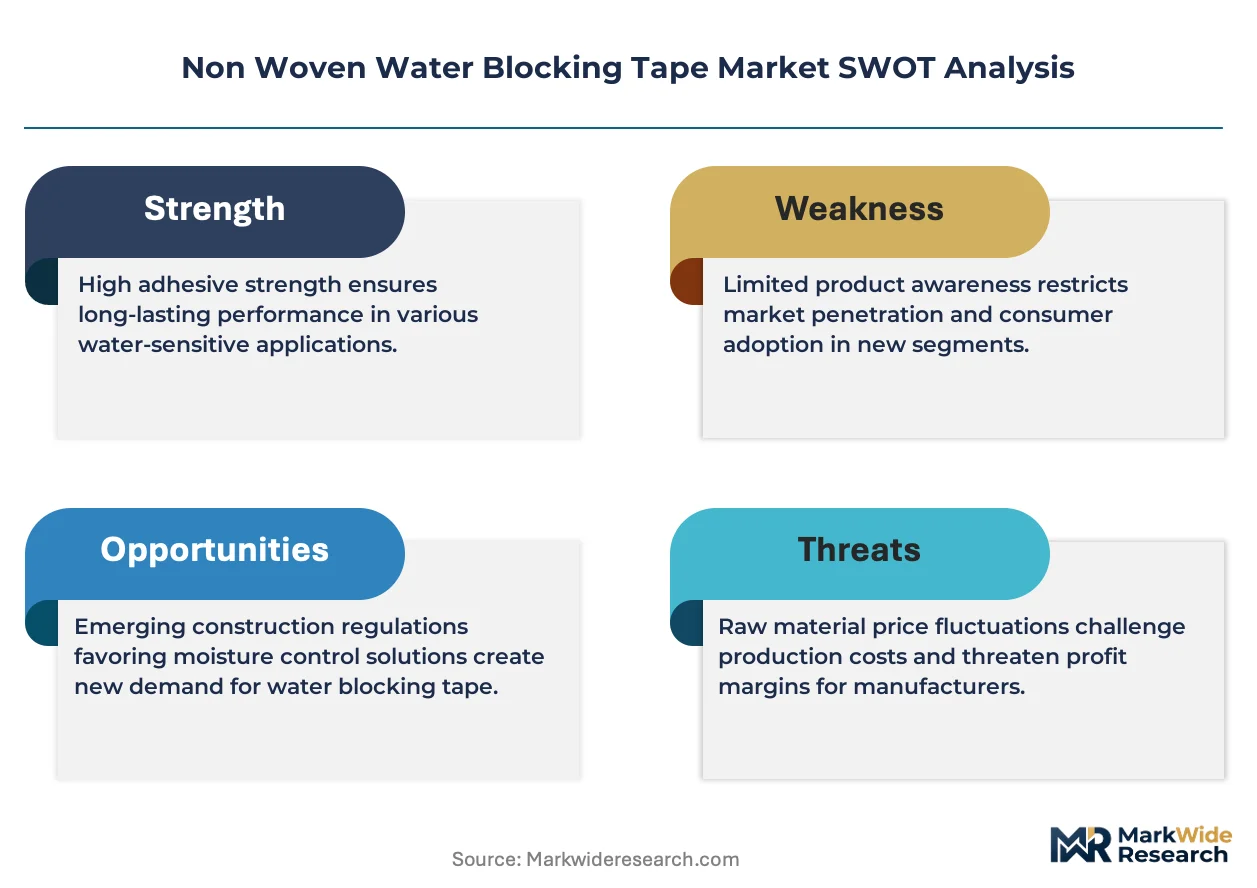
Offshore wind farm developers are consolidating cable specifications around pre-qualified water-blocking tape systems, compressing supplier qualification timelines and favoring manufacturers with existing submarine cable OEM relationships over field-applied product vendors.
Growth Catalysts
- Offshore wind cable installations:Submarine power cable projects in the North Sea and East Asian waters require certified water-blocking layers for 66kV and 220kV inter-array and export cables.
- REACH substance restrictions:ECHA's tightening superabsorbent polymer classifications are accelerating reformulation investments among European compounders, creating first-mover advantages for compliant substrate suppliers.
- China's grid expansion:State Grid Corporation bulk procurement programs for UHV transmission corridors are driving concentrated demand for polypropylene-based water-blocking tapes in 500kV and 1000kV cable systems.
Market Restraints
- Acrylic acid price volatility:Superabsorbent polymer feedstock costs fluctuate with crude oil derivatives, squeezing margin stability for tape manufacturers without backward integration into SAP production.
- Submarine cable OEM concentration:Nexans, Prysmian, and Hengtong Optical-Electric control 70% of qualified supplier slots, limiting market access for tier-two substrate producers.
- Butyl rubber tape substitution:Cold-applied mastic wraps retain cost advantages in low-voltage terrestrial installations below 35kV, capping volume expansion in price-sensitive utility segments.
Strategic Opportunities
- India's renewable corridor buildout:Solar-wind hybrid projects in Rajasthan and Gujarat are creating demand for medium-voltage cable protection materials as state utilities modernize rural distribution networks.
- EV high-voltage harness applications:Automotive OEMs are specifying thermal-stable polyester substrates for 800V battery cabling, opening margin pools outside traditional power transmission.
- EU Green Deal cable recycling mandates:Upcoming ECHA end-of-life regulations for cross-linked polyethylene cables will favor separable water-blocking layers over fused alternatives in new procurement specifications.
Industry Challenges
- IEC 60502-2 certification timelines:Type-testing protocols for high-voltage tape systems require 12-18 month qualification cycles, delaying revenue recognition for new substrate formulations.
- Spunbond line reconfiguration costs:Shifting between polypropylene and polyester fiber production demands capital-intensive die and spinneret changes, constraining manufacturing flexibility for mid-cap producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non Woven Water Blocking Tape Market |
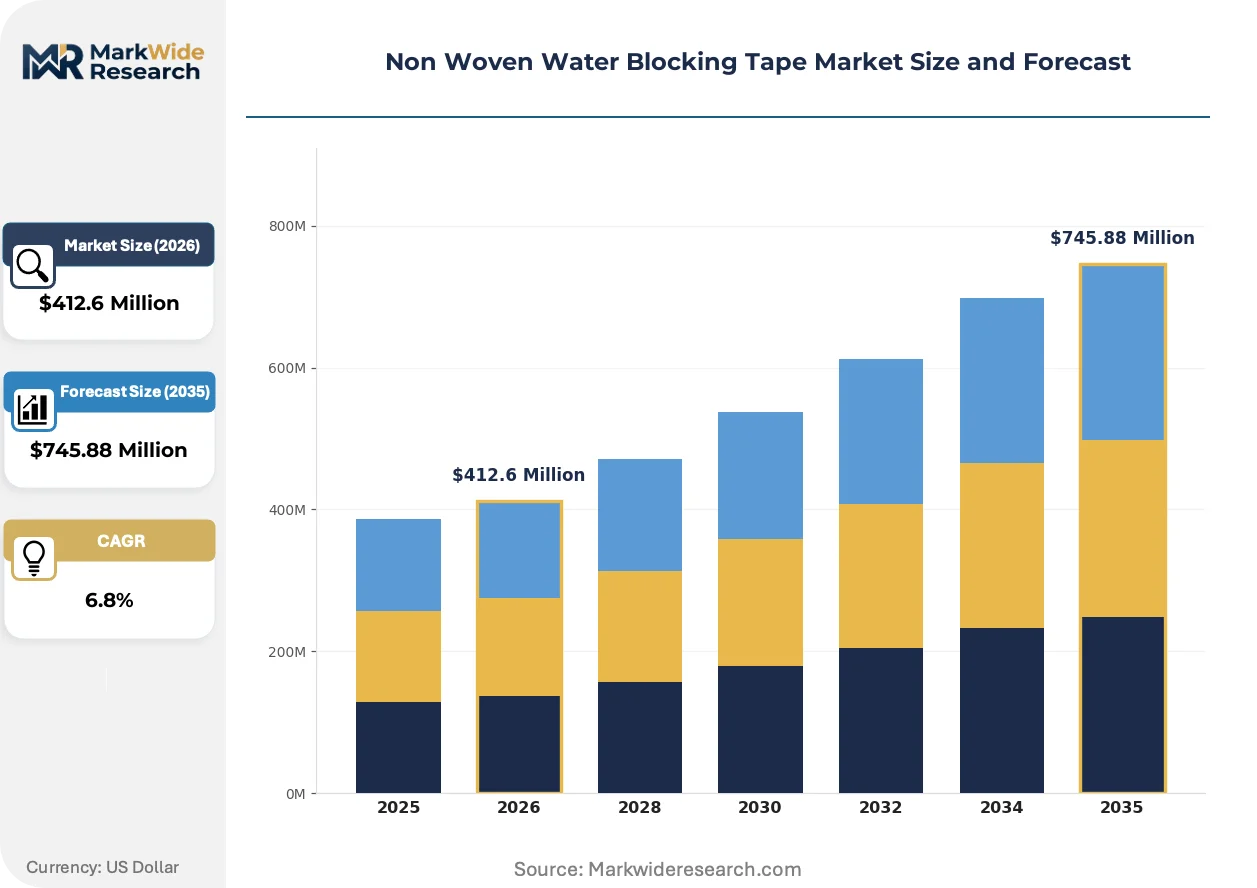
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Specialty, Custom Application: Construction, Automotive, Electronics, Packaging Material: Polypropylene, Polyester, Vinyl, Adhesive End User: Manufacturers, Contractors, Distributors, Retailers |
| Companies Covered | 3M, Berry Global Group, Inc., Nitto Denko Corporation, Tesa SE, Scapa Group Ltd, Intertape Polymer Group, Nichiban Co., Ltd., Fori Group, Chase Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non Woven Water Blocking Tape Market Trends and Innovations
Materials science advances and procurement centralization are restructuring how water-blocking substrates are specified, tested, and integrated into cable manufacturing workflows across voltage classes and end-use verticals.
Hybrid superabsorbent-polymer coatings with controlled particle-size distribution are absorbing moisture at calibrated rates that match specific cable filling compound viscosities. Submarine cable OEMs are specifying these precision-grade tapes for 320kV and 525kV DC export cables where swelling kinetics determine long-term insulation integrity. The technology is absorbing market share from conventional sodium-polyacrylate formulations that exhibit variable performance across temperature gradients.
REACH Annex XIV candidate list expansions for SAP chemistries are forcing European compounders to document substance volumes and safe-use scenarios for tape formulations containing residual monomers. Cable manufacturers serving EU member states are responding by dual-sourcing compliant and non-compliant substrate grades, creating parallel inventory management requirements that favor larger suppliers with dedicated regulatory affairs functions.
Utility procurement departments are consolidating annual water-blocking tape contracts under framework agreements with technical pre-qualification requirements. Tier-one cable producers in Germany and Japan are displacing spot-market purchasing with multi-year supply arrangements that bundle substrate, testing, and logistics services. This consolidation is most visible in offshore wind projects where EPCI contractors demand single-source accountability for cable system performance warranties.
Non Woven Water Blocking Tape Market Segmentation
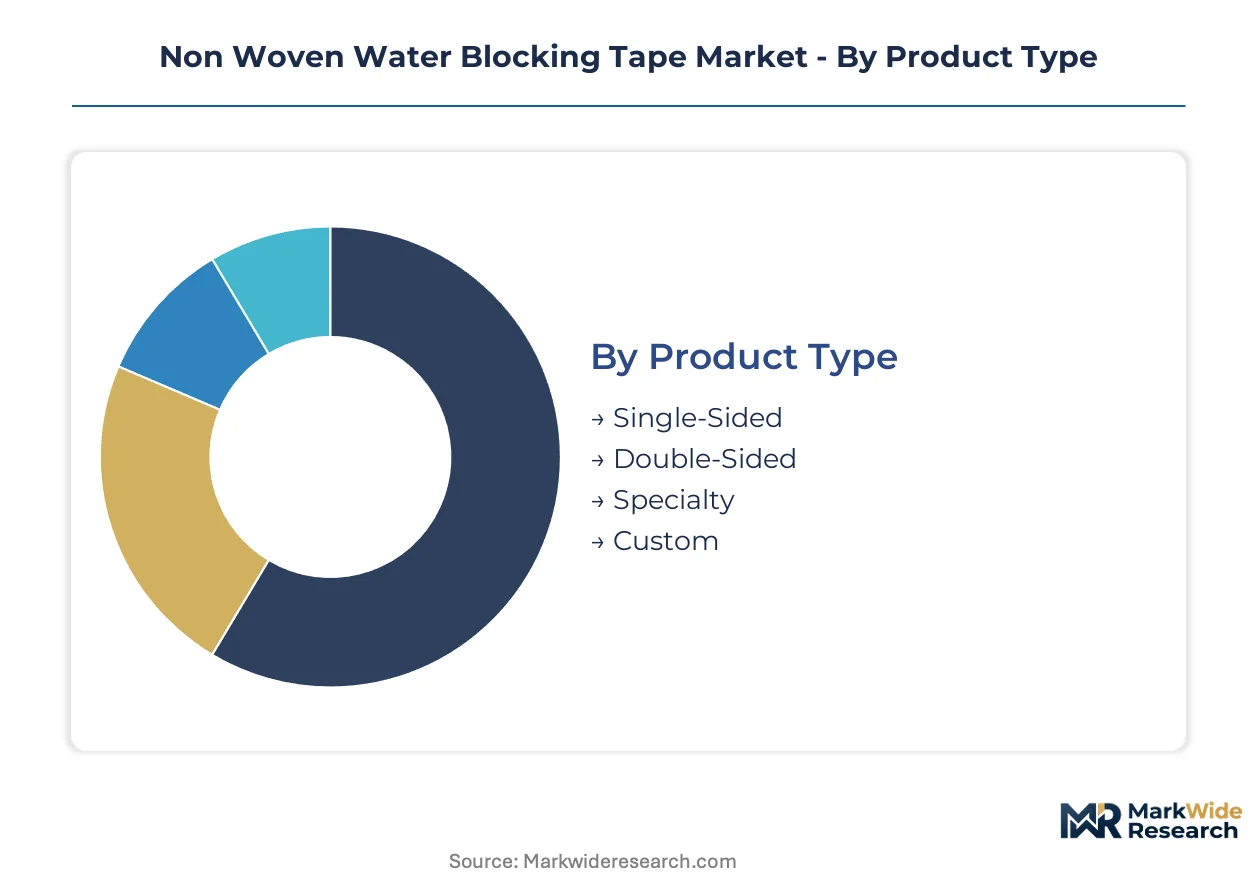
Water-blocking tape procurement hinges on voltage class, installation environment, and regulatory certification requirements. Cable OEMs specify product grades based on swelling kinetics, tensile retention, and compatibility with filling compounds. Segmentation reflects how technical performance tiers align with end-use economics and supply chain qualification barriers.
Product Type:
Buyers select configurations based on wrapping line compatibility and field installation constraints rather than unit cost alone.
- Single-Sided:Standard spunbond polypropylene substrate with one SAP-impregnated face integrates seamlessly with high-speed cable taping equipment. Utility infrastructure projects in China and Germany specify this grade for medium-voltage terrestrial cables where automated wrapping dominates manufacturing workflows.
- Specialty:Precision-calibrated swelling rates and enhanced thermal stability serve 320kV+ submarine DC export cables. North Sea offshore wind developers require EPCI-contractor pre-qualification for these grades, creating supplier lock-in effects.
- Double-Sided:Dual-coated construction for complex cable geometries requiring moisture sealing from multiple orientations.
- Custom:Formulation-to-specification grades for nuclear-rated or aerospace harness applications with non-standard certification protocols.
Single-Sided leads on scale; Specialty leads on momentum.
Application:
End-use concentration follows infrastructure investment cycles and electrification mandates across transportation and grid sectors.
- Construction:Utility-scale power transmission and distribution networks drive bulk consumption of polypropylene-based tapes. State Grid Corporation procurement programs and European TSO grid modernization create sustained demand corridors for standard-grade substrates.
- Electronics:Thin-gauge precision coatings for data center interconnects and telecommunications cables require polyester thermal stability above 125°C. Japanese and South Korean cable producers specify these grades for high-density fiber optic bundles.
- Automotive:800V battery harness applications demand thermal-runaway resistant substrates as EV platforms proliferate.
- Packaging:Moisture-sensitive logistics applications outside electrical cable markets represent peripheral demand.
Construction dominates volume throughput; Electronics climbs the fastest on margin expansion.
Material:
Substrate chemistry determines cost position, thermal ceiling, and regulatory compliance pathways across jurisdictions.
- Polypropylene:Spunbond mat construction delivers lowest unit cost for 500kV and 1000kV UHV transmission corridors. China's GB/T standards and MIIT directives explicitly favor this material platform for domestic grid buildout.
- Polyester:Higher melting point and dimensional stability sustain price premiums in automotive and subsea applications. REACH and RoHS compliance requirements in Europe accelerate reformulation toward cleaner polyester chemistries.
- Vinyl:Alternative substrate for specialty cable jackets requiring chemical resistance profiles.
- Adhesive:Functional coating layer rather than structural substrate, typically combined with primary carrier materials.
Polypropylene anchors volume economics; Polyester gains share fastest on specification upgrades.
End User:
Procurement authority concentrates with entities controlling cable system performance warranties and EPCI contract structures.
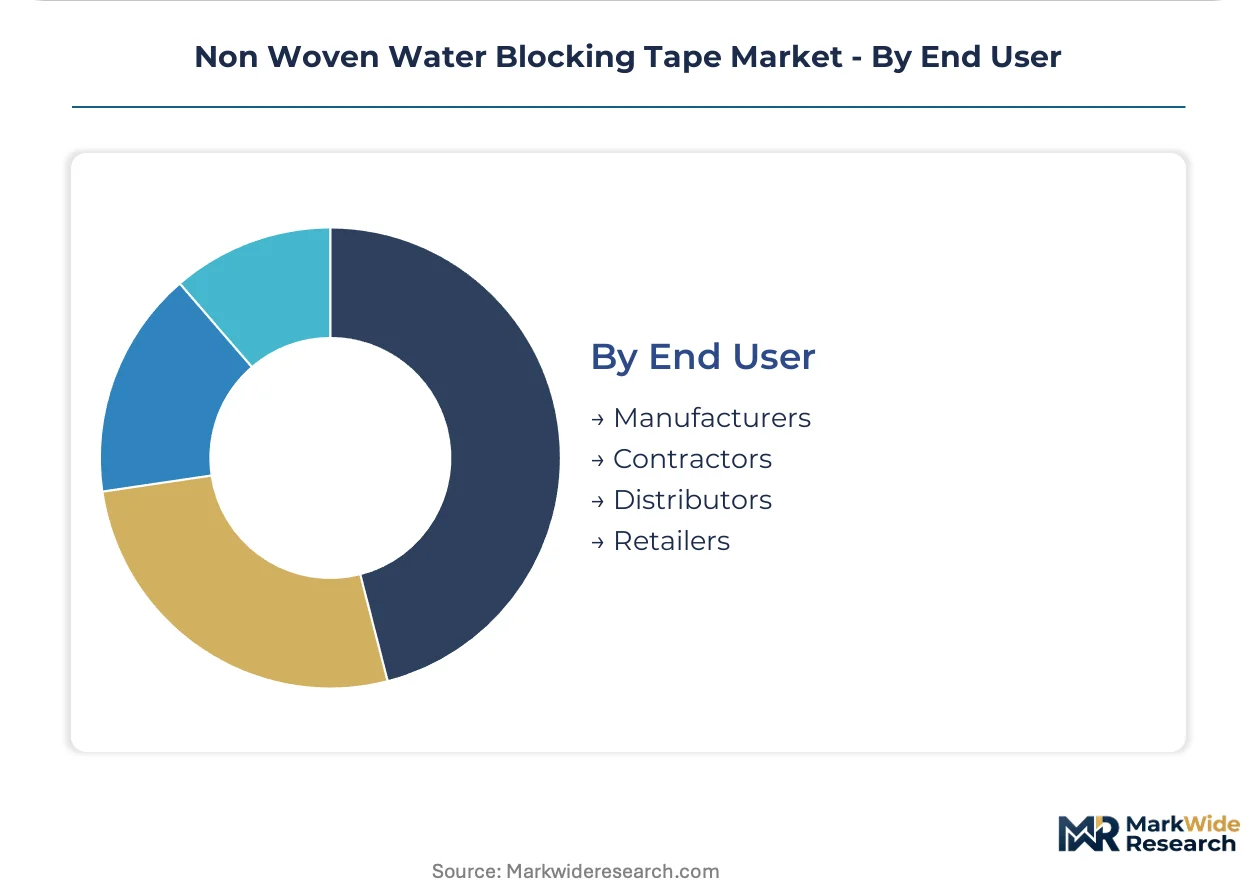
- Manufacturers:Tier-one cable OEMs including Prysmian, Nexans, and Hengtong Optical-Electric consolidate supplier qualification slots. These entities specify tape systems under multi-year framework agreements bundling substrate, testing, and logistics.
- Contractors:EPCI firms in offshore wind demand single-source accountability for submarine cable installations. Pre-qualified water-blocking layers compress field installation risk and warranty exposure.
- Distributors:Intermediary stocking roles for spot-market procurement in lower-voltage terrestrial segments.
- Retailers:Minimal channel presence given technical specification requirements and certification barriers.
Manufacturers command specification authority; Contractors drive fastest adoption through EPCI consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water-blocking tape manufacturing originated in post-war Japan and Germany, where precision nonwoven processing for electrical insulation first achieved industrial scale. Production expertise subsequently dispersed to North America and China as cable infrastructure investment waves shifted across regions.
China
State Grid Corporation bulk procurement for 500kV and 1000kV UHV transmission corridors concentrates demand in Jiangsu and Shandong provinces. MIIT cable industry directives and GB/T standards explicitly favor polypropylene substrates for domestic grid buildout. Suzhou and Nantong host the densest clusters of spunbond line operators serving utility infrastructure.
Germany
North Sea offshore wind developers specify pre-qualified water-blocking layers for 66kV and 220kV submarine cables. ECHA's REACH Annex XIV expansions for superabsorbent polymer chemistries force compounders to document safe-use scenarios. The Ruhr industrial corridor anchors European production capacity for utility-grade substrates.
United States
FAA and NHTSA flammability pathways shape transportation-sector tape requirements for mass-transit and electric vehicle cabling. Midwest utility infrastructure modernization drives procurement of standard-grade polypropylene tapes. Berry Global Group's vertically oriented nonwoven lines in the region serve terrestrial cable OEMs.
Japan
Thin-gauge precision coatings for electronics-grade applications sustain polyester price premiums above 125°C thermal thresholds. METI industrial standards and JIS certification protocols govern data center interconnect specifications. The Kansai region around Osaka hosts specialized coating operations for high-density fiber optic bundles.
India
Solar-wind hybrid projects in Rajasthan and Gujarat create demand for medium-voltage cable protection materials as state utilities modernize rural distribution networks. CEA grid connectivity regulations accelerate procurement of water-blocking substrates for renewable energy evacuation infrastructure. The Gujarat Industrial Development Corporation zone attracts cable accessory suppliers serving western renewable corridors.
Non Woven Water Blocking Tape Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and application complexity. The supplier base organizes into three layers: integrated materials science conglomerates with submarine cable OEM relationships, regional nonwoven specialists with utility infrastructure focus, and precision coating operators serving electronics-grade niches. Consolidation pressures favor manufacturers with captive SAP formulation capabilities and pre-qualified supplier slots. Two dominant competitive moves are multi-year framework agreements bundling substrate, testing, and logistics services, and die/spinneret line reconfiguration investments to shift between polypropylene and polyester fiber production.
Within the integrated materials tier, 3M leverages its broad technology portfolio to anchor submarine cable system supply, while Berry Global Group, Inc. exemplifies regional production concentration through North American vertically oriented nonwoven capacity. Nitto Denko Corporation occupies a position among precision coating specialists, representing the thin-gauge thermal stability segment where Japanese process expertise sustains differentiation. These three entities collectively illustrate how technical pre-qualification barriers and EPCI contractor consolidation favor established substrate suppliers with dedicated regulatory affairs functions and existing OEM relationships.
| Leading Market Players |
|---|
| 3M |
| Berry Global Group, Inc. |
| Nitto Denko Corporation |
| Tesa SE |
| Scapa Group Ltd |
| Intertape Polymer Group |
| Nichiban Co., Ltd. |
| Fori Group |
| Chase Corporation |
| Others |
Pricing and Supply Chain Analysis
Submarine cable OEM concentration among Prysmian, Nexans, and Hengtong Optical-Electric enforces project-based long-term contracting with technical pre-qualification requirements. Tier-one cable producers bundle substrate, testing, and logistics services into multi-year framework agreements that displace spot-market purchasing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IEC 60502-2 certified submarine grades from utility-standard polypropylene tapes and unqualified field-applied alternatives. Price differentiation rests on certification tier and volume scale, with Specialty grades commanding substantial premiums for 320kV+ DC export cable qualifications. Cost compression in standard-grade polypropylene tapes is intensifying because acrylic acid feedstock volatility squeezes compounder margins. State Grid Corporation procurement programs exhibit lowest price sensitivity due to performance warranty requirements, while low-voltage terrestrial installers remain most cost-conscious.
Supply Chain Analysis
Certification gating through 12-18 month IEC type-testing protocols restricts qualified supplier slots and fragments manufacturing scale across substrate tiers. Production gravity centers on China, Germany, and Japan, with spunbond line operators in Jiangsu and Shandong provinces feeding State Grid bulk procurement. Raw material dependencies draw from superabsorbent polymer formulations, polypropylene and polyester fiber feedstocks, and precision coating chemistries. Single-source vulnerability concentrates in SAP compounders lacking backward integration into acrylic acid production. Distribution runs through direct OEM supply contracts for submarine and UHV applications, with distributor stocking limited to spot-market terrestrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as offshore wind developers consolidate procurement around pre-qualified water-blocking layers with certified swelling kinetics.
For Market Incumbents: Anticipate butyl rubber tape substitution pressure in sub-35kV terrestrial installations by accelerating die and spinneret reconfiguration investments that enable flexible polypropylene-to-polyester shifting. Deepen captive SAP formulation capabilities to defend margin stability against acrylic acid price volatility. Secure additional pre-qualified supplier slots with EPCI contractors in North Sea offshore wind to lock out tier-two substrate producers. For New Entrants and Emerging Players: India's solar-wind hybrid developers in Rajasthan and Gujarat represent the most penetrable buyer archetype, as CEA grid connectivity regulations accelerate medium-voltage cable protection procurement without entrenched incumbent relationships. Target state utility modernization programs through technical partnership with established spunbond operators lacking IEC certification capabilities. Lead with EV high-voltage harness applications requiring thermal-stable polyester substrates above 125°C, where automotive OEM specification windows remain less consolidated than submarine cable tiers. For Investors and Strategic Acquirers: Integrated materials science conglomerates with submarine cable OEM relationships are the most active acquirer in this space, seeking captive SAP technology and pre-qualified substrate slots. The long-term viability window favors targets with backward integration into superabsorbent polymer production and existing EPCI contractor framework agreements. Watch for ECHA REACH Annex XIV enforcement actions against residual monomer content as the inflection indicator that will accelerate compliant-grade premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SAP Production | Captive superabsorbent polymer supply insulates margin stability from acrylic acid volatility. |
| Die and Spinneret Line Reconfiguration | Manufacturing flexibility between polypropylene and polyester fiber production captures specification shifts. |
| IEC 60502-2 Certification Investment | Type-testing qualification unlocks 320kV+ submarine cable OEM supply contracts. |
| Multi-Year Framework Agreement | Technical pre-qualification bundling displaces spot-market purchasing among tier-one cable producers. |
| REACH Compliant Reformulation | ECHA safe-use documentation enables continued EU market access as Annex XIV expands. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cable OEM procurement directors, superabsorbent polymer compounders, EPCI contractor materials engineers, and spunbond line operations managers with secondary validation against customs trade data, MIIT cable industry directives, SEC filings from listed suppliers, and IEC certification registry databases. Bottom-up segment sizing and top-down market reconciliation triangulated volume and value estimates.
Segment-weighting approaches applied differential growth assumptions across product type, application, material substrate, and end-user procurement authority dimensions. CAGRs were derived from regression analysis of historical procurement patterns and forward projection of infrastructure investment cycles, incorporating offshore wind capacity buildout timelines, State Grid UHV corridor commitments, and automotive electrification content-per-vehicle trajectories as cable-specific demand drivers.
Underlying measurement precision varies by segment; Specialty and Double-Sided product categories carry tighter precision than standard-grade Single-Sided volumes given concentrated supplier disclosure. Forecasts reflect assumptions around regulatory enforcement timing, SAP feedstock cost trajectories, and OEM qualification slot availability. A model refresh is warranted upon material change in ECHA REACH substance classification or submarine cable OEM consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Dicing Tapes Market
Tapes
Tape Applicator Machines Market
Tapes
Global Electrical Tapes Market
Tapes
Pipe Anti-Corrosion Tape Market
Tapes
Reflective Tape Market
Tapes
Moisture Barrier Tapes Market
Tapes
Thermoplastic Tape Market
Tapes
Foil Tapes Market
Tapes
Aerospace Tapes Market
Tapes
Automotive Tapes Market
Tapes
Asia-Pacific Packaging Tapes Market
Tapes
Tape Stretching Line Market
Tapes
Breathable Tape Market
Tapes
Heat Release Tape Market
Tapes
Global Specialty Tapes Market
Tapes
Carry Handle Tape Market