
 Pucker Free Tapes Market | 2026-2036
Pucker Free Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Pucker Free Tapes Market Analytics
Automotive OEMs are unwinding legacy reliance on mechanical fasteners in favor of adhesive bonding systems for exterior and interior assemblies. 3M Company leverages its polymer science depth to supply specification-grade tapes to tier-1 automotive suppliers across multiple continents. Henkel AG & Co. KGaA anchors its position through integrated adhesive chemistry capabilities that span structural bonding and surface preparation. Tesa SE specializes in precision-coated film tapes calibrated for automated assembly line speeds.
Pucker free tapes are pressure-sensitive adhesive tapes engineered with specialized release coatings and low-tack differential adhesives that eliminate wrinkling or distortion during application, typically specified to thickness tolerances within micrometers for critical bonding operations. Their primary purpose is to deliver uniform adhesion across flexible and rigid substrates in automated manufacturing environments where visual defects trigger rejection protocols. Film-backed variants dominate specification-driven procurement in electronics and automotive sectors due to dimensional stability and clean removability. Foam configurations represent the fastest-expanding category as electric vehicle battery pack assembly demands compressible gasket tapes that maintain seal integrity under thermal cycling. Double-sided products concentrate margin pools where converter-level customization and die-cutting precision create captive supplier relationships.
REACH restrictions on solvent-based adhesive formulations compel European tape manufacturers to migrate toward hot-melt and UV-curable chemistries, altering raw material sourcing and capital equipment requirements. FDA indirect food contact regulations in the United States govern tape selection in packaging applications, particularly for fatty food substrates where migration limits apply. ISO 9001 and IATF 16949 certifications function as baseline qualifiers for automotive supplier qualification programs, effectively filtering market access for non-certified producers. Stakeholders must monitor substrate diversification in electric vehicle architectures and assess whether existing adhesive platforms accommodate novel composite and thermoplastic materials without process requalification.
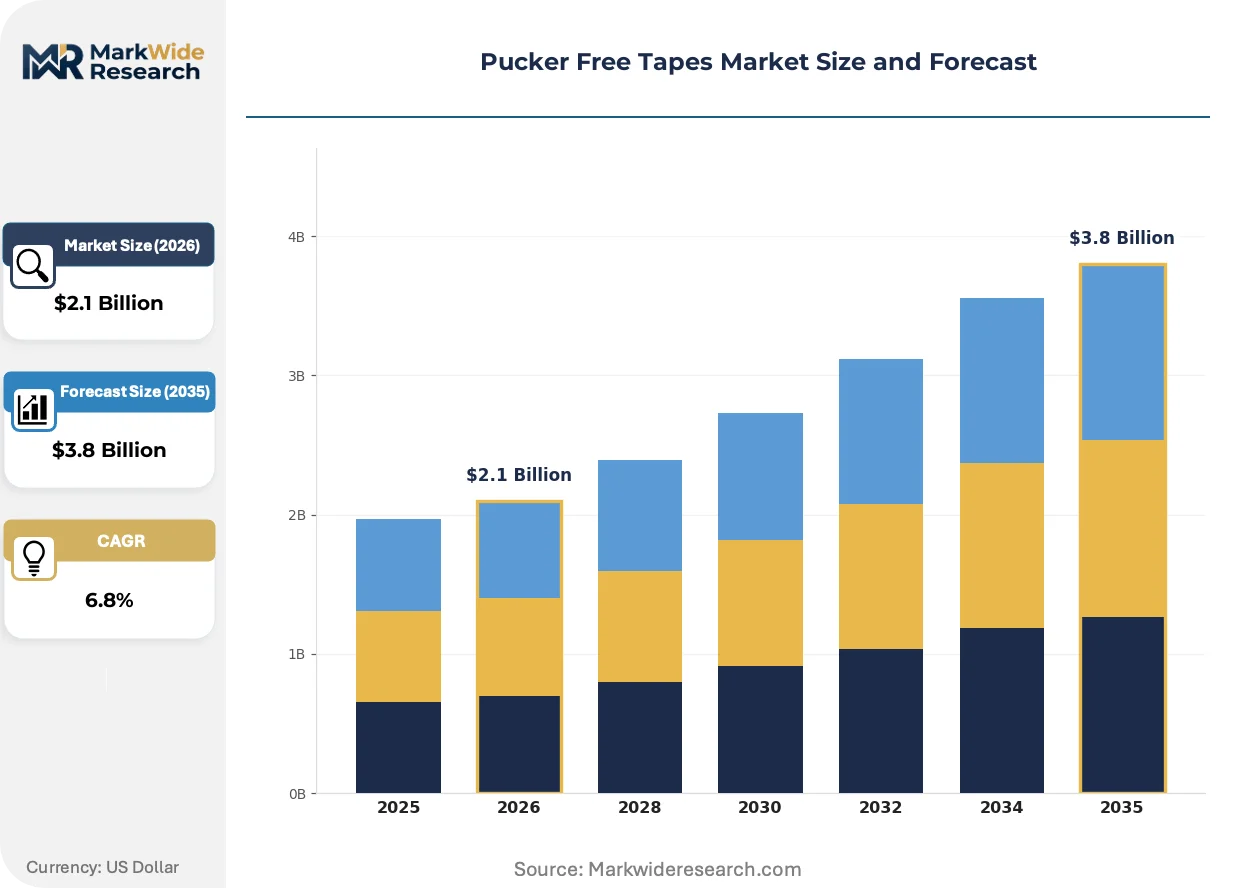
Market Dynamics
Automotive OEMs are compressing mechanical fastener counts across exterior trim assemblies, forcing tape suppliers to requalify adhesive platforms for novel thermoplastic and composite substrates without triggering line-down events.
Growth Catalysts
- EV battery pack sealing:Compressible foam-backed pucker free tapes are displacing liquid gaskets in electric vehicle thermal management systems, with cell-to-pack architectures demanding uniform compression distribution across cycling temperatures.
- REACH solvent restrictions:ECHA's tightening VOC limits on solvent-based adhesives are redirecting European formulation investment toward hot-melt and UV-curable polymer platforms that eliminate wrinkling without flash-off delays.
- German precision manufacturing clusters:Stuttgart and Munich automotive supplier ecosystems are consolidating specification-grade tape procurement around IATF 16949-certified converters capable of micrometer-level thickness control.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and silicone polymer prices fluctuate with propylene and siloxane monomer markets, compressing converter margins on fixed-price automotive supply agreements.
- Release liner supply concentration:Silicone-coated PET liner production clusters in East Asia, exposing European and North American tape manufacturers to ocean freight bottlenecks and currency exposure.
- Plasma surface treatment substitution:Corona and atmospheric plasma bonding systems are eliminating adhesive interfaces entirely in some polymer-to-metal assemblies, capping tape penetration in certain exterior applications.
Strategic Opportunities
- Underpenetrated Indian automotive:Domestic EV production ramp-ups in Tamil Nadu and Gujarat lack qualified local tape converters, creating first-mover advantage for IATF-certified suppliers establishing regional slitting operations.
- Medical device skin contact:ISO 10993 biocompatibility certification opens wearable device markets where pucker-free silicone tapes must conform to irregular anatomical surfaces without edge lift.
- Dual-cure UV/thermal platforms:Convergence of UV-initiated and heat-activated cure chemistries enables in-line processing on mixed-material vehicle assemblies where substrate thermal limits vary.
Industry Challenges
- Adhesive rheology specialization:Formulation chemists capable of tuning viscoelastic response across temperature and shear rate spectra command premium compensation, constraining R&D bandwidth at mid-size converters.
- OEM requalification timelines:Volkswagen, BMW, and Mercedes-Benz supplier approval protocols demand 18-24 month validation cycles for new adhesive platforms, freezing out speculative formulation changes.
- Legacy ERP integration:Automated tape application systems require real-time thickness and tack data feeds that conflict with older manufacturing execution software at tier-2 automotive suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pucker Free Tapes Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided, Foam, Film, Cloth Application: Packaging, Crafts, Automotive, Electronics End User: Manufacturers, DIY Enthusiasts, Retailers, Contractors Thickness: Thin, Medium, Thick, Ultra-Thin |
| Companies Covered | 3M Company, Avery Dennison Corporation, Henkel AG & Co. KGaA, Intertape Polymer Group Inc., Tesa SE, Nitto Denko Corporation, Scapa Group plc, Shurtape Technologies LLC, Berry Global, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pucker Free Tapes Market Evolving Landscape
Adhesive bonding systems are displacing mechanical fixation across transportation and electronics assemblies, with tape manufacturers racing to synchronize polymer science advances with automated line speeds and zero-defect visual standards.
Water-based acrylic emulsion adhesives with controlled particle size distribution are supplanting solvent-borne systems in European automotive exterior applications. BMW and Audi assembly plants in Germany and Hungary have converted windshield bonding lines to aqueous platforms that eliminate VOC capture equipment. This transition is compressing capital requirements for new tape coating lines while extending drying section footprints.
REACH Annex XVII restrictions on organotin catalysts in silicone release coatings are forcing European tape manufacturers to reformulate platinum-cure and tin-free condensation systems. The industrial consequence is elevated scrap rates during coating line changeovers as operators recalibrate release force windows. Automotive specification-grade film tapes are most affected, with converters in Bavaria and Baden-Württemberg accelerating qualification of alternative catalyst platforms.
Specification-driven buyers are consolidating vendor counts and demanding die-cut kit delivery rather than bulk roll supply. Tier-1 automotive suppliers in Stuttgart and Wolfsburg now require tape converters to manage inventory at assembly plant lineside locations, replacing traditional distributor warehousing. This pattern is most visible in Germany, where just-in-sequence production models leave minimal buffer stock for bonding material defects.
Pucker Free Tapes Market Segmentation
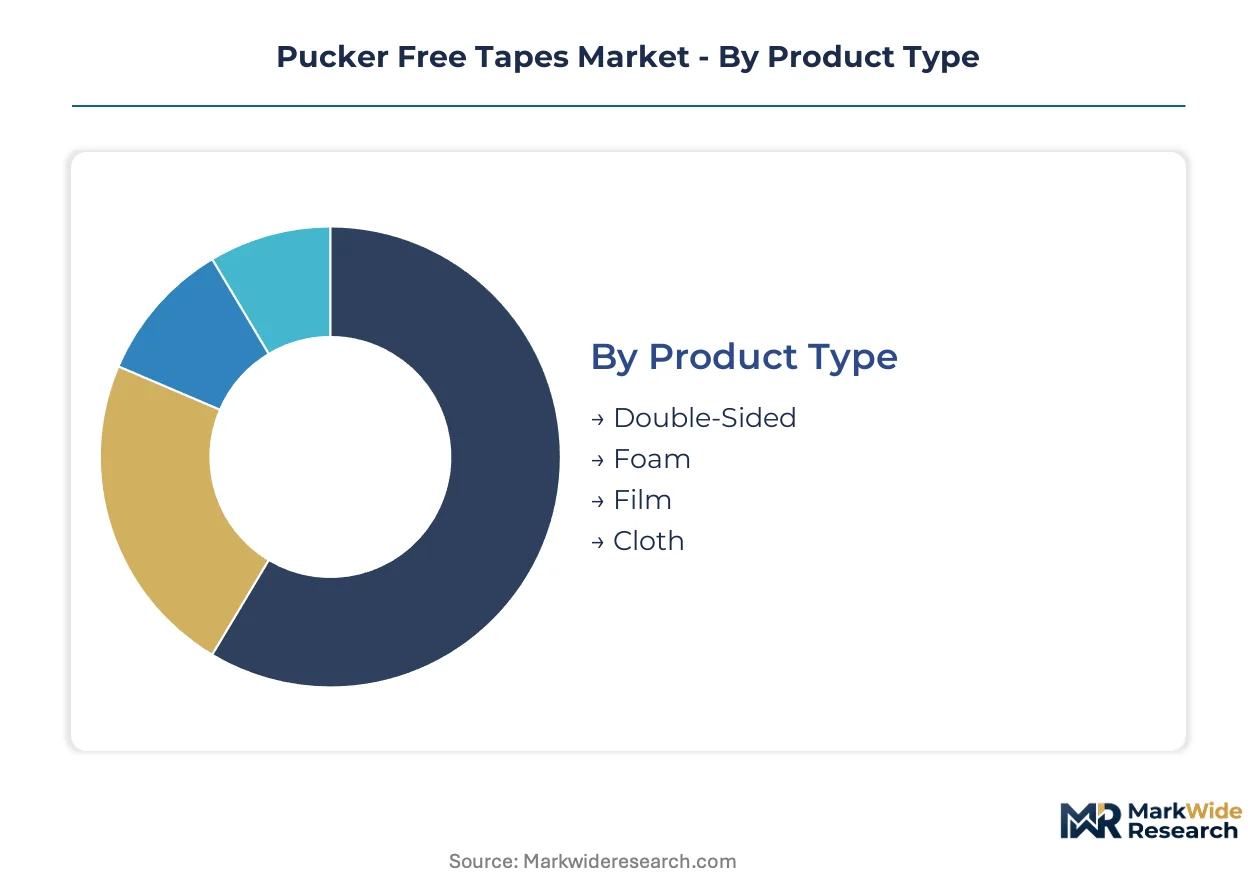
Pucker free tapes serve divergent performance requirements across automotive assembly lines, electronics cleanrooms, and consumer retail shelves. Channel economics and specification intensity vary dramatically by segment, with die-cut kit delivery dominating automotive procurement while bulk roll distribution persists in craft and packaging applications.
Product Type:
Double-sided and foam configurations flow through specification-grade channels to automotive and electronics OEMs, while film and cloth variants split between industrial distributors and retail hardware networks.
- Double-Sided:Pressure-sensitive adhesive layers on both faces of PET or PP carriers enable structural bonding without visible fasteners. Stuttgart and Wolfsburg automotive clusters specify these for exterior trim mounting where removability and clean aesthetics are mandatory.
- Foam:Compressible acrylic or PE foam cores distribute stress across irregular substrates. Electric vehicle battery pack sealing in Germany and Hungary is absorbing volume as cell-to-pack architectures displace liquid gaskets.
- Film:Dimensionally stable polyester or polyimide backings serve electronics lamination and surface protection. REACH-compliant aqueous adhesive platforms are migrating coating lines away from solvent-borne systems.
- Cloth:Woven cotton or synthetic fabric backings provide hand-tearability and conformability. DIY and contractor channels in North America and Europe move volume through hardware retailers and industrial distributors.
Double-sided products dominate specification-grade revenue pools. Foam configurations are where expansion concentrates.
Application:
Application segments separate by qualification burden, with automotive and electronics demanding IATF 16949-certified supply chains that packaging and craft applications do not require.
- Automotive:Exterior trim bonding, interior assembly, and battery sealing require micrometer-level thickness control and zero-defect visual standards. BMW, Audi, and Mercedes-Benz supplier protocols demand 18-24 month adhesive requalification cycles.
- Electronics:Display lamination, flex circuit mounting, and component fixation specify clean removability and outgassing control. German precision manufacturing clusters in Bavaria concentrate procurement around automated die-cutting capabilities.
- Packaging:Carton sealing and temporary closure applications prioritize cost efficiency over specification intensity. FDA indirect food contact regulations govern fatty food substrates where migration limits apply.
- Crafts:Scrapbooking, paper arts, and hobbyist applications drive retail SKU proliferation. Water-based acrylic emulsions dominate this price-sensitive segment.
Automotive commands premium pricing tiers. Electronics is climbing the fastest as display and wearable device assembly expands.
End User:
End user type determines order configuration, with manufacturers demanding just-in-sequence kit delivery while retailers and contractors accept standard roll formats.
- Manufacturers:Tier-1 automotive and electronics producers require lineside inventory management and real-time thickness data integration. IATF 16949 and ISO 9001 certifications function as baseline market access filters.
- Contractors:Construction and installation trades purchase through industrial distributors with volume pricing structures. Application training and on-site technical support differentiate supplier relationships.
- Retailers:Hardware chains and specialty craft stores stock consumer-grade SKUs with branded packaging and merchandising support. Price points and shelf visibility drive procurement decisions.
- DIY Enthusiasts:Individual consumers purchase single rolls or small multipacks through e-commerce and big-box retail. Product reviews and brand recognition influence selection.
Manufacturers anchor specification-grade margin pools. DIY enthusiasts represent the most price-elastic demand segment.
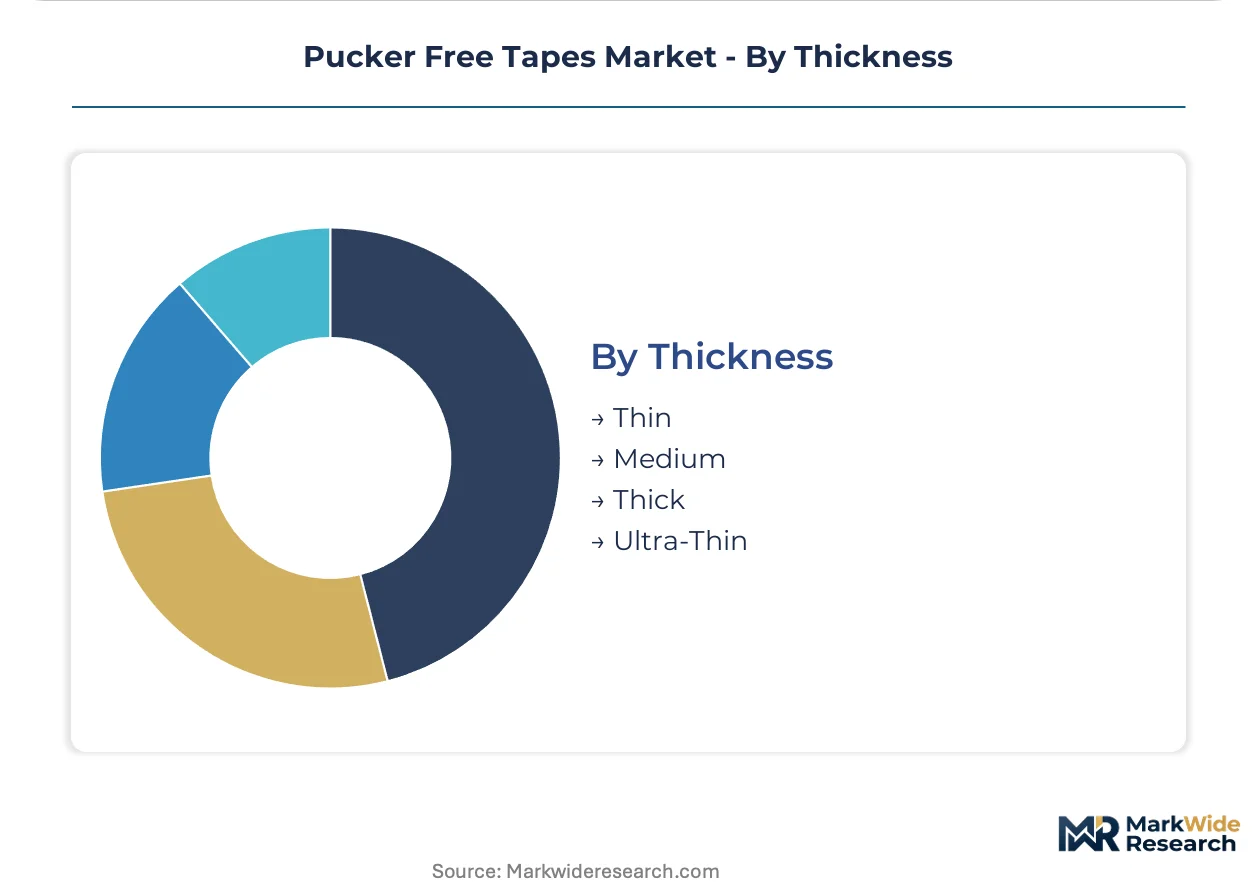
Thickness:
Thickness specifications correlate directly with application precision requirements, with ultra-thin and thin variants serving electronics while thick configurations absorb tolerance stack-up in automotive assemblies.
- Ultra-Thin:Sub-50 micrometer constructions enable miniaturized electronics bonding where z-axis space is constrained. German semiconductor packaging facilities specify these for die attach and wire bonding operations.
- Thin:50-100 micrometer range balances conformability with handling integrity. Automotive interior trim applications in Stuttgart supplier ecosystems standardize on this tier.
- Medium:100-250 micrometer thickness serves general industrial bonding and surface protection. Packaging and craft applications concentrate here.
- Thick:Above 250 micrometer constructions provide gap-filling and cushioning. Battery pack compression pads and exterior automotive gasketing specify these dimensions.
Thin variants dominate current automotive specification volumes. Ultra-thin is gaining share fastest as electronics miniaturization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Adhesive tape manufacturing clusters in Germany, the United States, Japan, China, and South Korea supply specification-grade pucker free products to automotive and electronics OEMs. Raw material proximity and converter density create competitive moats in these production centers.
Germany
Stuttgart and Munich automotive supplier ecosystems drive precision tape procurement for BMW, Mercedes-Benz, and Audi assembly lines. ECHA REACH Annex XVII restrictions on solvent-based adhesives redirect Bavarian coating operations toward aqueous and UV-curable platforms. Baden-Württemberg converter facilities manage IATF 16949-certified slitting operations for just-in-sequence delivery to Wolfsburg powertrain plants.
United States
EV battery pack assembly in Michigan and Ohio absorbs compressible foam-backed tapes for thermal management sealing. FDA indirect food contact regulations govern tape selection in Wisconsin and Illinois packaging corridors serving fatty food substrates. Detroit-area tier-1 suppliers coordinate die-cut kit delivery lineside to Ford and General Motors assembly plants.
Japan
Display lamination and semiconductor packaging in Kansai and Chubu regions specify ultra-thin pucker free constructions with sub-50 micrometer tolerances. METI industrial standards shape adhesive performance benchmarks for electronics cleanroom applications. Osaka-based precision coating facilities supply Tokyo-area consumer electronics assemblers with clean-removal film tapes.
China
Yangtze River Delta EV production clusters in Shanghai and Jiangsu province demand battery compression pads and exterior trim bonding solutions. GB standards and MIIT automotive regulations set adhesive qualification protocols for domestic OEM supply chains. Suzhou and Wuxi converter operations serve BYD and NIO with localized slitting and die-cutting capabilities.
South Korea
Seoul Capital Area display panel manufacturers specify optical-grade pucker free tapes for OLED lamination and flexible circuit mounting. MFDS biocompatibility requirements open wearable device applications for skin-contact silicone adhesive platforms. Gyeonggi-do coating facilities supply Samsung and LG with roll-to-roll processed film constructions.
Pucker Free Tapes Market Competitive Landscape
Concentration sits with diversified adhesive specialists and precision coating converters that span polymer chemistry through automated die-cutting capabilities. Three to five multinational suppliers anchor specification-grade revenue pools in automotive and electronics channels. Market structure rewards integrated players controlling resin formulation, release coating, and slitting operations under unified quality systems. Competitive dynamics favor M&A-driven portfolio expansion and geographic tuck-in acquisitions to secure IATF-certified converter networks.
Within the diversified adhesive specialist tier, 3M Company and Henkel AG & Co. KGaA represent integrated chemistry-to-converter operations spanning structural bonding and pressure-sensitive platforms. Tesa SE exemplifies precision-coated film specialists calibrated for automated automotive assembly line speeds. Among Asia-Pacific fabricators, Nitto Denko Corporation occupies a position bridging electronics lamination and industrial bonding applications. These anchors demonstrate how polymer science depth and certification density create defensive positioning against regional converter competition.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Henkel AG & Co. KGaA |
| Intertape Polymer Group Inc. |
| Tesa SE |
| Nitto Denko Corporation |
| Scapa Group plc |
| Shurtape Technologies LLC |
| Berry Global, Inc. |
| Others |
Value Network & Pricing Analysis
IATF 16949 certification gates both supply qualification and price differentiation simultaneously, filtering out non-certified converters from automotive procurement channels while enabling premium positioning for compliant Bavarian and Baden-Württemberg slitting operations serving Stuttgart OEM clusters.
Pricing Analysis
REACH Annex XVII restrictions on solvent-based adhesives dictate the pricing tier structure across European specification-grade procurement. Three-tier pricing structure across premium, standard, and economy levels separates IATF-certified automotive supply from industrial distributor grades and retail hardware SKUs. Cost compression in standard-tier foam-backed configurations is intensifying because acrylic monomer feedstock volatility transmits directly through fixed-price EV battery supply agreements. DIY enthusiasts exhibit the highest price elasticity, while German automotive OEMs accept substantial premiums for micrometer-level thickness control and zero-defect visual standards.
Supply Chain Analysis
China and South Korea anchor silicone-coated PET release liner production, with East Asian coating facilities supplying European and North American tape manufacturers. Acrylic polymer emulsions and siloxane release coatings draw from propylene and chlorosilane feedstock markets tethered to petrochemical refining cycles. Single-source vulnerability concentrates in ocean freight corridors connecting Shanghai liner plants to Hamburg and Rotterdam converter hubs. Distribution runs through tier-1 automotive supplier lineside inventory management systems that displace traditional distributor warehousing in German just-in-sequence production environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle battery pack architectures are disrupting legacy adhesive bonding specifications, with cell-to-pack thermal management demands rewriting qualification protocols for compressible gasket materials across multiple continents.
For Market Incumbents: Compound polymer science capabilities through captive formulation of UV-curable and hot-melt platforms that eliminate REACH solvent exposure. Acquire IATF-certified converter networks in underpenetrated Indian automotive corridors before domestic EV production ramp-ups consolidate supplier relationships. Atmospheric plasma bonding systems threaten tape penetration in exterior polymer-to-metal assemblies; defend position by deepening technical service relationships with BMW and Mercedes-Benz platform engineering teams. For New Entrants and Emerging Players: Anchor in Tamil Nadu and Gujarat automotive supplier ecosystems where qualified local tape converters remain scarce despite accelerating domestic EV output. Target medical device skin-contact applications where ISO 10993 biocompatibility certification opens wearable device markets for silicone adhesive platforms. Pursue die-cut kit delivery partnerships with tier-1 suppliers rather than bulk roll distribution to bypass entrenched converter relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European converters holding IATF 16949 certification but lacking integrated polymer formulation capabilities. The five-to-ten-year viability window favors platforms accommodating novel thermoplastic and composite substrates without triggering OEM requalification timelines. Monitor substrate diversification announcements from Volkswagen, BMW, and Mercedes-Benz as the signal indicating which adhesive platforms will capture specification-grade procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Formulation | Captive acrylic emulsion production insulates margins from propylene monomer volatility in automotive supply agreements. |
| IATF 16949 Certification Investment | Baseline market access filter for Stuttgart and Wolfsburg supplier ecosystems demands quality system compliance. |
| Regional Slitting Operations in India | Localized die-cutting capabilities capture first-mover advantage in Tamil Nadu and Gujarat EV production corridors. |
| Dual-Cure UV/Thermal Platform Development | Convergent cure chemistries enable in-line processing on mixed-material vehicle assemblies with varying thermal limits. |
| Lineside Inventory Management Partnerships | Just-in-sequence delivery to tier-1 suppliers replaces traditional distributor warehousing in German automotive procurement. |
Research Methodology
Operator-level perspectives from adhesive formulation chemists, tier-1 automotive procurement managers, precision coating line operators, and industrial distribution channel heads anchored the qualitative base. Primary fieldwork combined with secondary validation against ECHA REACH regulatory filings, IATF certification registries, SEC 10-K disclosures from listed adhesive specialists, and German automotive supplier association production data. Bottom-up volume estimates from converter capacity utilization triangulated against top-down OEM procurement spend analysis.
Sensitivity analysis tested forecast robustness across alternative EV adoption trajectories and petrochemical feedstock price scenarios throughout the projection horizon. Segmentation modeling spanned product type, application intensity, end-user configuration, and thickness specification tiers alongside regional production cluster dynamics. CAGRs derived from trend extrapolation of specification-grade procurement volumes normalized against vehicle production and electronics assembly benchmarks. Key inputs included cell-to-pack battery architecture penetration rates and REACH solvent restriction implementation timelines.
Material uncertainties — regulatory acceleration in ECHA VOC limits, plasma bonding substitution rates in exterior assemblies, and release liner supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about OEM requalification cycle durations and converter certification density. Recalibration cycles align with material shifts in EV platform standardization and adhesive chemistry migration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Global Surface Protection Tapes Market
Tapes
Metal Foil Tapes Market
Tapes
Replica Tapes Market
Tapes
India Reflective Tapes Market
Tapes
Tape Applicator Machines Market
Tapes
Splicing Tapes Market
Tapes
Automotive Tapes Market
Tapes
Heat Activated Tear Tape Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Correction Tapes Market
Tapes
PVC Tapes Market
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
Carton Sealing Tape Market
Tapes
Wire Harness Tape Market
Tapes
UV Cured Acrylic Foam Tapes Market