
 Smart Blood Pressure Monitoring Devices Market | 2026-2036
Smart Blood Pressure Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Blood Pressure Monitoring Devices Market Intelligence
A shortage of certified biomedical engineers is unwinding manufacturing scale-up plans across the smart blood pressure monitoring devices industry. Omron Healthcare, Inc. leverages its captive sensor fabrication facilities to buffer component volatility. Koninklijke Philips N.V. sustains hospital channel dominance through embedded EHR integration protocols. Withings competes in direct-to-consumer segments via design-forward wearable form factors that bypass clinical procurement cycles.
Smart blood pressure monitoring devices comprise digitally instrumented cuffs and wearable units that employ oscillometric or optical plethysmography methods to capture systolic and diastolic readings, then transmit encrypted data through Bluetooth or Wi-Fi to cloud analytics platforms for longitudinal cardiovascular tracking. Their primary commercial purpose is enabling remote hypertension management while reducing clinic visit dependency. Wearable monitors command premium positioning among fitness-integrated consumers, whereas telehealth devices anchor enterprise margin pools through recurring platform licensing. Bluetooth-enabled units lead volume shipments, though IoT connectivity architectures represent the fastest-expanding technology tier as health systems consolidate device fleets.
FDA software-as-medical-device pathways and EU MDR conformity requirements jointly elevate validation costs for algorithm-driven diagnostic outputs. Japan's PMDA enforces distinct clinical evidence thresholds for home-use versus clinical-grade claims, fragmenting product registration strategies. Stakeholders must monitor how reimbursement code expansions for remote physiological monitoring reshape procurement authority between payers and provider networks.
Market Dynamics
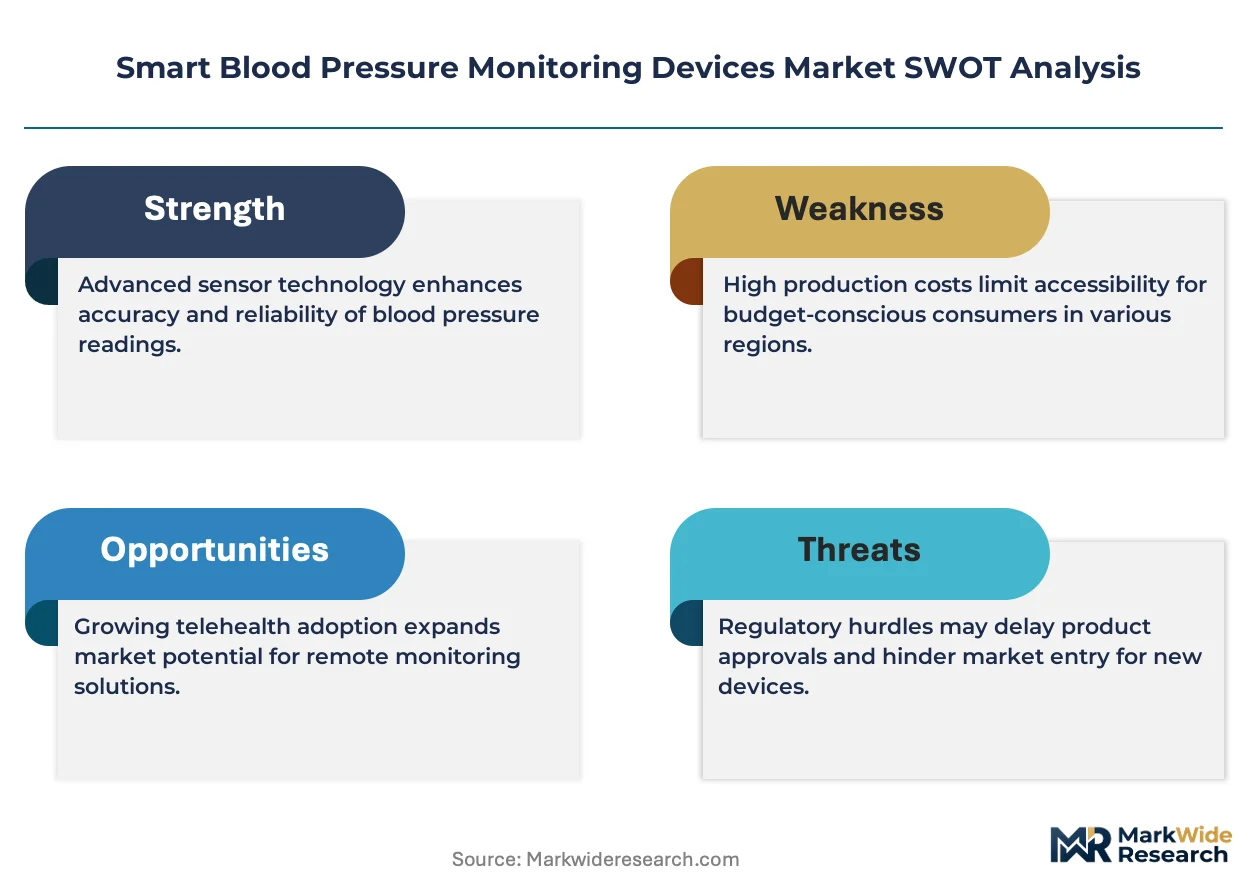
Software-as-medical-device regulatory pathways are compressing product launch timelines while simultaneously elevating validation costs, creating asymmetric pressure that favors sensor-integrated manufacturers over pure-play algorithm developers.
Growth Catalysts
- Home-based elderly care programs:Germany's expanded community nursing infrastructure is accelerating procurement of connected monitoring systems for decentralized hypertension management.
- Telehealth infrastructure mandates:Metropolitan hospital networks in Japan are consolidating device fleets around IoT connectivity architectures to support integrated remote care platforms.
- Optical plethysmography miniaturization:Advances in photodetector sensitivity are enabling cuffless wearable form factors that bypass traditional clinical procurement cycles.
Market Restraints
- Algorithm validation costs:FDA software-as-medical-device pathways and EU MDR conformity requirements jointly elevate expenditure thresholds for diagnostic output certification.
- Biomedical engineer scarcity:A shortage of certified specialists is unwinding manufacturing scale-up plans across sensor calibration and quality assurance functions.
- Component volatility:Dependence on discrete MEMS pressure sensors exposes production schedules to foundry capacity constraints in East Asian semiconductor fabrication.
Strategic Opportunities
- Reimbursement code expansion:Remote physiological monitoring CPT code additions in the US are reshaping procurement authority toward payer networks and away from hospital capital committees.
- Direct-to-consumer channel development:Design-forward wearable positioning enables margin capture outside institutional tender processes, particularly among fitness-integrated demographics.
- EHR embedded integration:Health system consolidation around platform licensing models creates recurring revenue pools distinct from device hardware margins.
Industry Challenges
- PMDA claim fragmentation:Japan's regulator enforces distinct clinical evidence thresholds for home-use versus clinical-grade claims, complicating unified product registration strategies.
- Legacy system interoperability:Hospital network procurement demands HL7 FHIR compliance that stretches development timelines for cloud-native device architectures.
- Encrypted data pipeline certification:HIPAA and GDPR concurrency requirements for cross-border patient data transmission impose dual-jurisdiction legal review burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Blood Pressure Monitoring Devices Market |
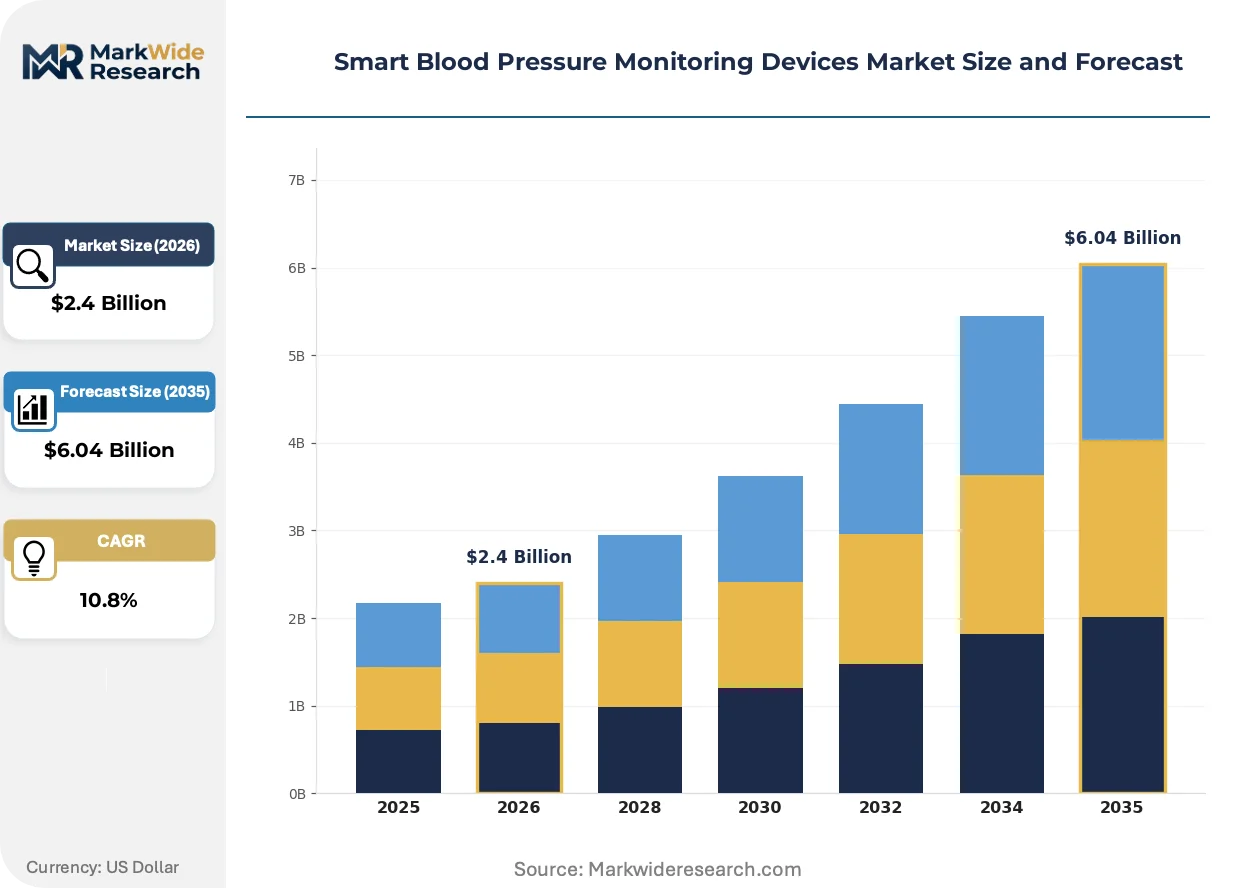
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.04 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Digital Sphygmomanometers, Smart Blood Pressure Cuffs, Telehealth Devices Technology: Bluetooth, Wi-Fi, IoT Connectivity, Hybrid Technology End User: Home Users, Healthcare Professionals, Hospitals, Clinics Application: Hypertension Management, Routine Monitoring, Remote Patient Monitoring, Fitness Tracking |
| Companies Covered | Omron Healthcare, Inc., Koninklijke Philips N.V., Qardio, Inc., iHealth Labs Inc., Withings, A&D Medical Inc., Beurer GmbH, Microlife AG, Welch Allyn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Blood Pressure Monitoring Devices Market Strategic Shifts & Innovations
Active reshaping of this market centers on three vectors: sensor modality substitution, regulatory pathway bifurcation, and procurement authority migration from providers to payers.
Photoplethysmography-based cuffless monitoring is supplanting oscillometric arm-cuff devices among fitness-integrated consumer segments. Wearable manufacturers are capturing blood pressure variability data through optical sensors embedded in wrist-worn form factors. This modality shift is compressing the addressable market for traditional cuff-based hardware while expanding longitudinal cardiovascular tracking capabilities.
EU MDR clinical evidence requirements for algorithm-driven diagnostic outputs are extending conformity assessment timelines for software-embedded devices. The regulation's post-market surveillance mandates are forcing manufacturers to maintain active clinical follow-up infrastructure. High-risk classification of hypertension management claims is disproportionately affecting European market entry strategies for AI-augmented interpretation features.
Hospital procurement committees are ceding device selection authority to payer networks as remote monitoring reimbursement codes expand. Integrated telehealth platforms are displacing standalone device purchases in metropolitan health system consolidation. This shift is most visible in Japan's prefectural hospital networks, where platform licensing contracts now supersede individual device tenders.
Smart Blood Pressure Monitoring Devices Market Segmentation
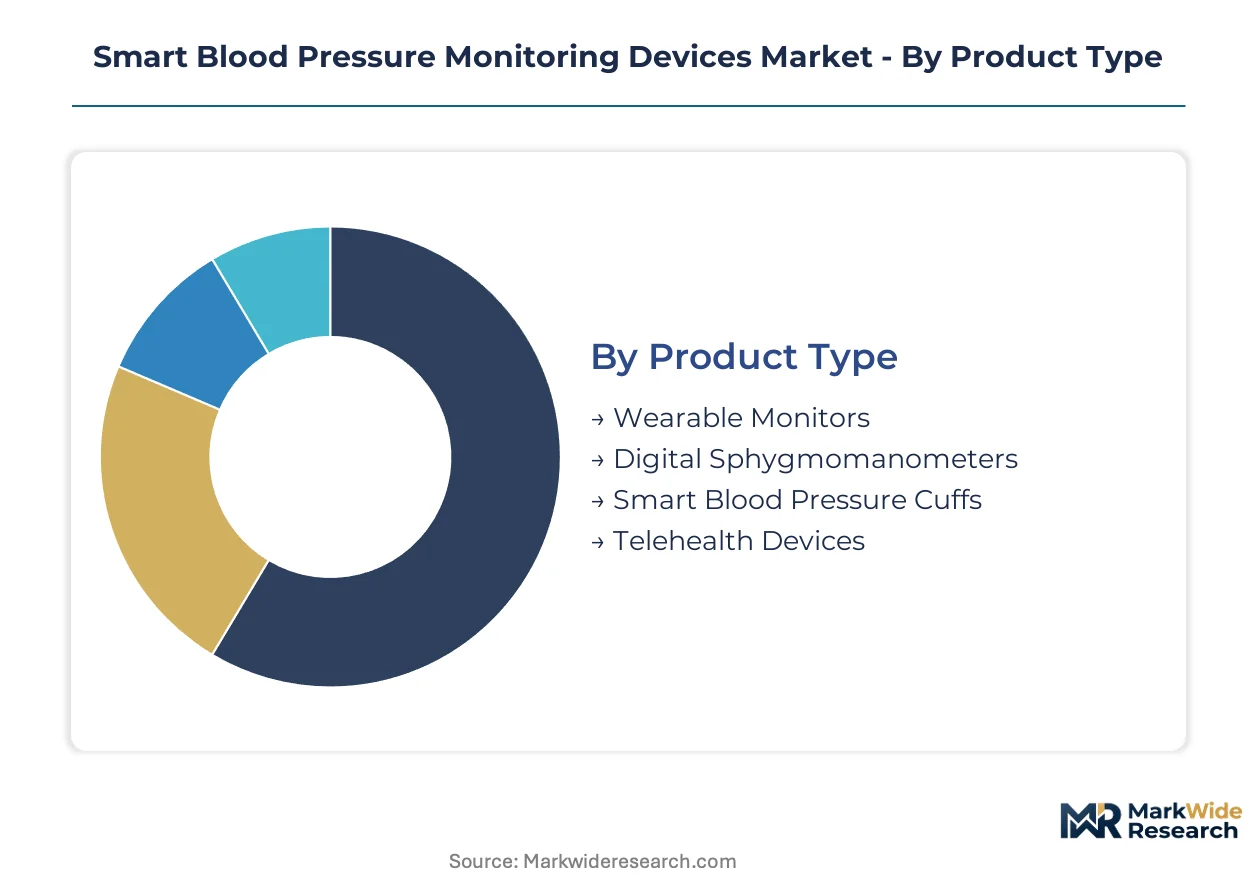
Segmentation in smart blood pressure monitoring reveals how sensor modality shifts and connectivity standards fragment addressable revenue pools. Procurement authority migrates differently across product architectures, with wearable form factors bypassing institutional tender processes entirely.
Product Type:
Optical plethysmography miniaturization exerts substitution pressure most acutely on traditional cuff-based hardware, compressing volume leadership for legacy oscillometric devices.
- Wearable Monitors:Photodetector-embedded wrist-worn units capture blood pressure variability through optical sensors without pneumatic cuffs. Demand concentrates among fitness-integrated consumers in Japan's metropolitan areas seeking continuous cardiovascular tracking outside clinical settings.
- Telehealth Devices:Enterprise-grade systems with embedded EHR integration protocols anchor recurring platform licensing revenue. Procurement is accelerating through Germany's home-based elderly care programs as community nursing infrastructure expands decentralized hypertension management.
- Digital Sphygmomanometers:Arm-cuff oscillometric devices with digital displays retain clinical-grade accuracy certification for professional use.
- Smart Blood Pressure Cuffs:Bluetooth-enabled pneumatic units transmit encrypted readings to cloud analytics platforms for longitudinal patient tracking.
Wearable Monitors retain volume leadership; Telehealth Devices hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium IoT architectures from commoditized Bluetooth implementations, with hybrid systems commanding validation premium for algorithm-driven diagnostic outputs.
- IoT Connectivity:Cellular and LPWAN architectures enable standalone data transmission without smartphone tethering. Japan's prefectural hospital networks are consolidating device fleets around these platforms to support integrated remote care infrastructure.
- Bluetooth:Low-energy protocols dominate shipment volumes through smartphone-integrated consumer applications. FDA software-as-medical-device pathways compress launch timelines for algorithm-embedded Bluetooth units while elevating validation expenditure thresholds.
- Wi-Fi:Direct-to-router connectivity supports stationary home monitoring without mobile device dependency.
- Hybrid Technology:Multi-protocol devices switch between connectivity modes based on network availability and power constraints.
Bluetooth retains volume leadership; IoT Connectivity holds the steepest expansion curve.
End User:
Application maturity diverges sharply between institutional procurement cycles and direct-to-consumer channel development, with reimbursement code expansion reshaping authority between payers and provider networks.
- Home Users:Cuffless wearable adoption bypasses clinical procurement entirely through design-forward positioning. Germany's expanded community nursing infrastructure accelerates connected monitoring procurement for decentralized hypertension management among aging populations.
- Hospitals:Metropolitan networks in Japan demand HL7 FHIR compliance for cloud-native device architectures, stretching development timelines. Platform licensing contracts now supersede individual device tenders as integrated telehealth systems displace standalone purchases.
- Healthcare Professionals:Clinical-grade accuracy requirements drive procurement of validated oscillometric devices for diagnostic use.
- Clinics:Ambulatory settings balance cost constraints with reimbursement eligibility for remote physiological monitoring.
Home Users retain volume leadership; Hospitals hold the steepest expansion curve.
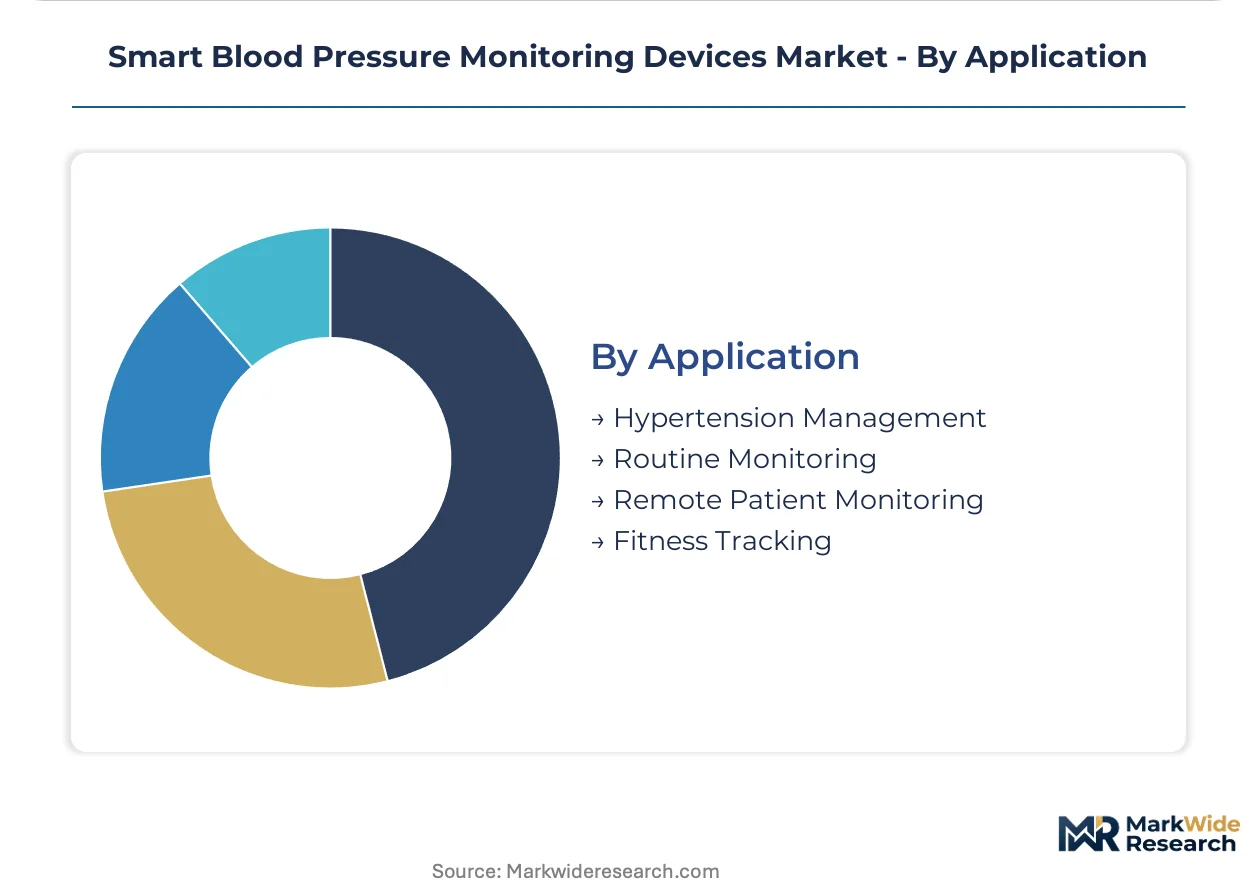
Application:
Margin concentration pools in remote patient monitoring as reimbursement code expansion migrates procurement authority toward payer networks, while fitness tracking captures premium positioning through consumer willingness to pay for design differentiation.
- Remote Patient Monitoring:Cloud analytics platforms enable longitudinal cardiovascular tracking with reduced clinic visit dependency. US remote physiological monitoring CPT code additions reshape procurement authority toward payer networks and away from hospital capital committees.
- Fitness Tracking:Wellness-integrated consumers accept optical plethysmography accuracy trade-offs for continuous monitoring convenience. Cuffless wearable form factors bypass traditional clinical procurement cycles entirely through direct-to-consumer channel development.
- Hypertension Management:Clinical-grade therapeutic claims require FDA software-as-medical-device validation and EU MDR conformity assessment.
- Routine Monitoring:Periodic screening applications prioritize cost efficiency over continuous data capture for asymptomatic populations.
Routine Monitoring retains volume leadership; Remote Patient Monitoring holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA software-as-medical-device pathways anchor the United States as the regulatory benchmark shaping product validation timelines worldwide. Germany's expanded community nursing infrastructure accelerates procurement of connected monitoring systems for decentralized hypertension management. Japan's PMDA enforces distinct clinical evidence thresholds fragmenting registration strategies across home-use and clinical-grade segments.
United States
Remote physiological monitoring CPT code additions reshape procurement authority toward payer networks and away from hospital capital committees. FDA clearance pathways compress product launch timelines for algorithm-embedded devices while elevating validation expenditure thresholds. The Boston-Cambridge corridor concentrates digital health venture activity supporting cloud-native device architectures.
Germany
Home-based elderly care programs accelerate procurement of connected monitoring systems for decentralized hypertension management. EU MDR conformity requirements extend assessment timelines for software-embedded devices with active clinical follow-up mandates. The Baden-Württemberg industrial cluster hosts precision sensor fabrication facilities buffering component volatility.
Japan
Metropolitan hospital networks consolidate device fleets around IoT connectivity architectures supporting integrated telehealth infrastructure. PMDA enforces distinct clinical evidence thresholds for home-use versus clinical-grade claims complicating unified registration strategies. The Tokyo-Osaka corridor anchors demand concentration for platform licensing contracts superseding individual device tenders.
China
Domestic MEMS pressure sensor foundry capacity constraints expose production schedules to semiconductor fabrication bottlenecks. NMPA regulatory harmonization efforts align with international software-as-medical-device validation frameworks. The Yangtze River Delta concentrates contract manufacturing for Bluetooth-enabled units dominating shipment volumes.
United Kingdom
NHS long-term plan commitments expand remote monitoring reimbursement eligibility reshaping procurement patterns. MHRA post-Brexit regulatory divergence creates parallel conformity assessment requirements for algorithm-driven diagnostic outputs. The Oxford-Cambridge-London arc concentrates health technology assessment expertise influencing payer network device selection criteria.
Smart Blood Pressure Monitoring Devices Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in this market's competitive architecture. Sensor-integrated manufacturers with captive fabrication facilities command asymmetric advantages over pure-play algorithm developers facing elevated validation costs. Three archetypes dominate: vertically integrated health technology conglomerates, design-forward direct-to-consumer specialists, and precision sensor component suppliers. Competitive moves concentrate on embedded EHR integration protocols and recurring platform licensing models displacing standalone hardware tenders.
Within the integrated health technology tier, Omron Healthcare, Inc. and Koninklijke Philips N.V. exemplify divergent strategic positioning. Omron anchors sensor-integrated manufacturing through captive fabrication facilities buffering component supply volatility. Philips occupies hospital channel dominance through embedded integration protocols sustaining enterprise recurring revenue pools. Among design-forward specialists, Withings represents direct-to-consumer archetype development bypassing institutional procurement cycles entirely through wearable form factor innovation.
| Leading Market Players |
|---|
| Omron Healthcare, Inc. |
| Koninklijke Philips N.V. |
| Qardio, Inc. |
| iHealth Labs Inc. |
| Withings |
| A&D Medical Inc. |
| Beurer GmbH |
| Microlife AG |
| Welch Allyn |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety day sensor lead times from East Asian foundries concentrate pricing power among captive-fabrication incumbents while exposing algorithm-only developers to margin compression during capacity crunches. Bluetooth-enabled units face commoditization pressure as IoT architectures command validation premiums for software-as-medical-device certification tiers.
Pricing Analysis
Japanese metropolitan hospital networks pay 40-60% premiums over German home-care procurement for identical hardware due to embedded EHR integration requirements and platform licensing bundling. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical-grade devices from wellness-positioned wearables and unconnected digital cuffs. Price differentiation hinges on algorithm validation tier and after-sales data analytics subscription attachment. Cost compression in the Bluetooth consumer tier is intensifying because smartphone-tethered architectures face substitution by standalone cellular units. Home users in community nursing programs exhibit highest price sensitivity; integrated telehealth platform buyers accept premium positioning for recurring revenue capture.
Supply Chain Analysis
East Asian semiconductor fabrication chokepoints in Taiwan, South Korea, and China expose MEMS pressure sensor availability to foundry allocation decisions and export control volatility. Smart blood pressure monitoring production draws from photodetector arrays, pneumatic pump assemblies, and lithium-polymer cells as core inputs. Single-source vulnerability concentrates in discrete MEMS pressure transducers where alternative qualified suppliers require 18-24 month validation cycles. Distribution runs through hospital GPO contracts, direct-to-consumer e-commerce, and community nursing procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA software-as-medical-device pathways compress launch timelines while elevating validation costs, creating asymmetric pressure that favors sensor-integrated manufacturers over pure-play algorithm developers in this high-growth disruption.
For Market Incumbents: Shield embedded EHR integration protocols from disintermediation by payer network platform consolidation through exclusive data pipeline certifications. Deepen upstream control over photodetector calibration facilities to buffer MEMS foundry volatility. Accelerate HL7 FHIR compliance roadmaps before Japan's prefectural hospital networks complete telehealth infrastructure tenders.
For New Entrants and Emerging Players: Post-market surveillance infrastructure gaps among European software-embedded device manufacturers create service-layer white space for regulatory compliance outsourcing. Target Germany's expanded community nursing procurement as the most penetrable institutional channel bypassing hospital capital committee gatekeeping. Pursue direct-to-consumer wearable positioning with cuffless optical plethysmography miniaturization to circumvent clinical validation timelines entirely.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across IoT connectivity architecture development as cellular certification and carrier integration costs compound. Five-to-ten year viability favors sensor-integrated mid-caps with captive fabrication over algorithm-only developers facing sustained FDA validation expenditure pressure. Monitor PMDA harmonization negotiations with FDA software-as-medical-device frameworks as the critical signal for unified registration strategy feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Accelerates algorithm-embedded device launch timelines while elevating clinical evidence expenditure thresholds. |
| Hospital System Partnership | Secures recurring platform licensing revenue through embedded EHR integration protocol adoption. |
| CE Marking Pathway | EU MDR conformity assessment extends timelines for active clinical follow-up surveillance mandates. |
| Reimbursement Strategy | Remote physiological monitoring CPT code expansion shifts procurement authority toward payer networks. |
| Software Companion Development | Cloud analytics platforms enable longitudinal cardiovascular tracking with reduced clinic visit dependency. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists; and secondary validation against FDA 510(k) filings, PMDA approval databases, CMS Medicare reimbursement schedules, and EU MDR notified body conformity assessments. Bottom-up shipment modeling triangulated against top-down health system expenditure tracking.
Across the projection horizon, the analytical framework modeled segmentation dimensions including sensor modality, connectivity architecture, end-user procurement authority, and reimbursement eligibility tier. CAGRs derived from installed base growth curves and replacement cycle compression in aging population demographics. Forecast inputs incorporated telehealth infrastructure mandate timelines and software-as-medical-device regulatory pathway adoption rates.
Forecasts assume regulatory continuity in FDA, EU MDR, and PMDA regimes; material policy shifts in algorithm validation requirements or remote monitoring reimbursement eligibility would require re-modeling. Practitioners should keep alternative scenarios live as biomedical engineer scarcity and MEMS foundry capacity allocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Transcatheter Heart Valve Replacement (THVR) Market
Cardiovascular Devices
UAE Cardiovascular Devices Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Intravascular Ultrasound (IVUS) System Market
Cardiovascular Devices
Fibromuscular Dysplasia Treatment Market
Cardiovascular Devices
Global Heart Valve Repair and Replacement Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market
Cardiovascular Devices
Percutaneous Coronary Intervention Guidance Devices Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Chronic Venous Occlusions Treatment Market
Cardiovascular Devices
Cardiac Cryoablation Device Market
Cardiovascular Devices
Intravenous Catheters Market