
 Europe Medical Gloves Market | 2026-2036
Europe Medical Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Gloves Market Insights
A capital-intensity divergence between integrated manufacturers and contract-dependent distributors is reorganizing competitive tiers in the Europe medical gloves sector. Ansell Ltd leverages its captive nitrile supply chain to sustain margin stability across Northern European hospital networks. Mercator Medical SA anchors its position through Polish manufacturing scale that competes on cost with Asian imports. B. Braun SE differentiates via surgical-grade specialization that dominates German operating theater procurement.
Europe medical gloves are disposable barrier devices manufactured from nitrile, natural rubber latex, vinyl, or polyethylene, with thickness specifications typically ranging from 3 to 8 mils and compliance requirements for tensile strength and pinhole rates under EN 455 and EN ISO 374 standards; they serve primarily to prevent pathogen transmission between healthcare workers and patients during clinical procedures. Nitrile formulations now lead hospital procurement due to latex allergy elimination and superior chemical resistance, while vinyl maintains volume in low-risk examination settings where cost sensitivity structures purchasing decisions. The surgical application segment commands premium positioning through extended cuff designs and sterile packaging requirements that concentrate margin pools with specialized manufacturers.
EMA coordination with national competent authorities and the EU MDR framework shapes product registration pathways, while REACH restrictions on chemical accelerators and plasticizers directly reformulate glove composition across the continent. ECHA substance evaluations are forcing manufacturers to substitute traditional accelerators in nitrile curing processes, creating compliance-driven R&D obligations that favor larger players with analytical chemistry capabilities. Stakeholders must monitor accelerating MDR transition deadlines and accelerator-free formulation shifts to anticipate which production configurations will secure market access.
Market Dynamics
Accelerator-free nitrile formulations are forcing wholesale reformulation of European manufacturing lines as ECHA substance evaluations under REACH tighten restrictions on thiurams and carbamates used in traditional curing processes.
Growth Catalysts
- EU MDR compliance deadlines:Hospital procurement departments are accelerating glove inventory turnover to meet sterility assurance level requirements, creating replacement demand for certified manufacturers.
- Nitrile allergy elimination protocols:German and French hospital networks are mandating latex-free environments, redirecting volume toward synthetic alternatives with EN ISO 374 chemical resistance certification.
- Central and Eastern European hospital expansion:Poland, Romania, and Hungary are constructing new acute care facilities that specify single-use barrier devices in infection control tenders.
Market Restraints
- Butadiene price volatility:Nitrile rubber feedstock costs fluctuate with crude oil derivatives, compressing margins for European converters without backward integration into polymer production.
- Asian import concentration:Malaysian and Thai manufacturers control bulk nitrile supply, exposing European distributors to freight rate spikes and container availability constraints.
- Accelerator substitution technical limits:Alternative curing agents under REACH scrutiny deliver inferior tensile strength, forcing trade-offs between compliance and performance specifications.
Strategic Opportunities
- Romania and Bulgaria hospital underpenetration:Per-capita glove consumption in these markets trails Western European benchmarks by 40%, offering volume expansion for compliant suppliers.
- Surgical robotics integration:Robotic-assisted procedures require specialized extended-cuff sterile gloves with enhanced tactile feedback, creating premium product categories.
- EU Green Deal circular economy incentives:Biodegradable nitrile formulations and recyclable packaging configurations qualify for public procurement preference points in France and the Netherlands.
Industry Challenges
- Analytical chemistry capability gaps:Accelerator-free formulation R&D requires mass spectrometry and chromatography expertise scarce among mid-tier European manufacturers.
- MDR technical documentation timelines:Clinical evaluation reports and biological safety assessments for new glove variants require 18-24 month certification cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Gloves Market |
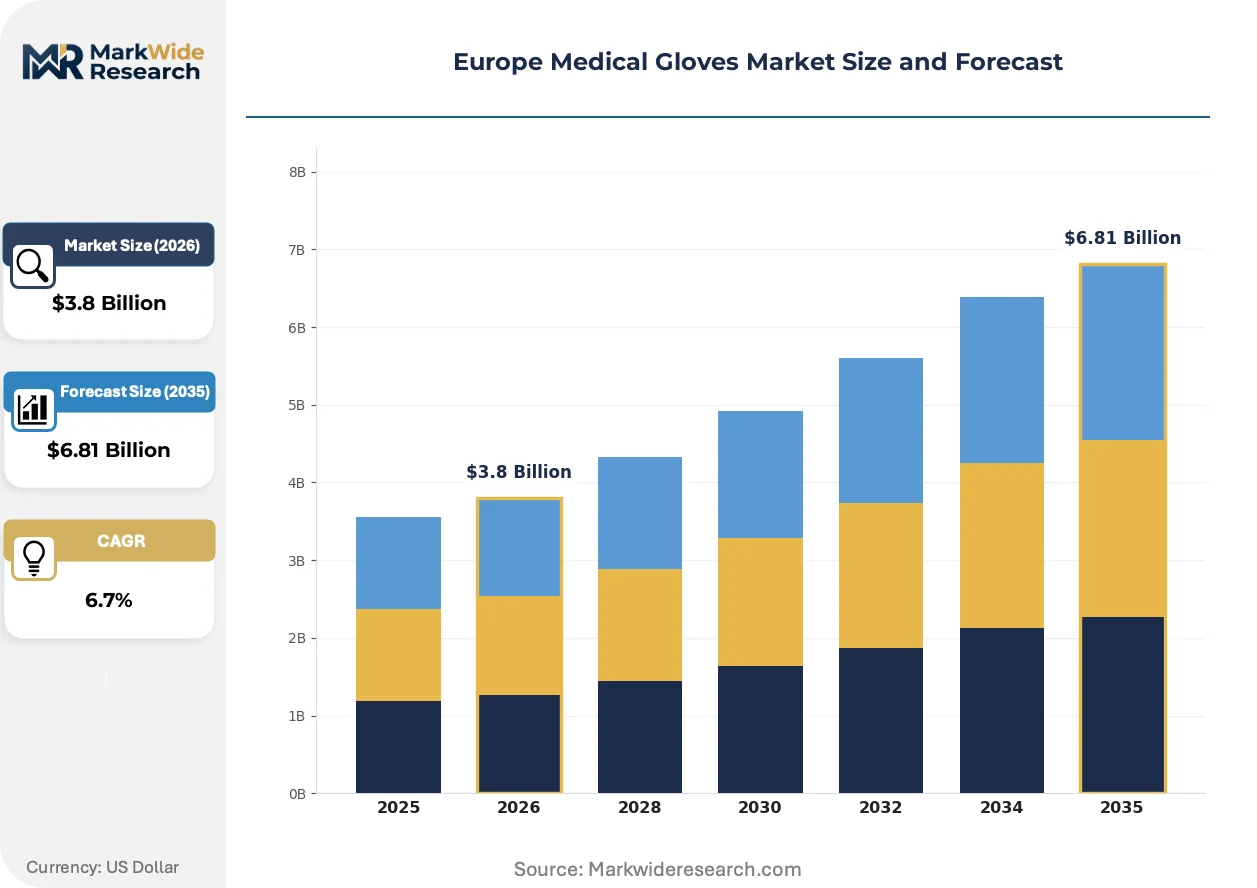
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrile, Latex, Vinyl, Polyethylene End User: Hospitals, Clinics, Laboratories, Homecare Distribution Channel: Online, Retail, Wholesalers, Direct Sales Application: Surgical, Examination, Emergency, Industrial |
| Companies Covered | Cardinal Health, Mercator Medical SA, B. Braun SE, Medline Industries LP, Ansell Ltd, Sempermed, Top Glove Corporation Bhd, HuskMedical, Unigloves (UK) Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Gloves Market Trends and Innovations
Formulation chemistry, regulatory compliance architecture, and procurement digitization are converging to reshape how European healthcare providers source and specify barrier protection devices.
Chlorination-free nitrile surface treatment is displacing traditional post-processing methods that rely on chlorine washing and neutralization. German surgical glove manufacturers are adopting this technology to eliminate residual chloramine compounds and reduce dermatitis incidents among operating theater staff. The shift is compressing demand for legacy chlorination equipment and redirecting capex toward plasma treatment and polymer coating lines.
REACH restrictions on zinc diethyldithiocarbamate and other accelerators are forcing reformulation of nitrile curing systems across European production facilities. ECHA substance evaluations have classified several traditional accelerators as substances of very high concern, compelling manufacturers to validate alternative cross-linking chemistries. Surgical glove segments face the steepest compliance burden due to extended skin contact duration requirements under EN ISO 10993 biocompatibility standards.
Consolidated purchasing alliances among French and Benelux hospital networks are compressing supplier rosters and mandating electronic data interchange for order fulfillment. These buying cooperatives are displacing fragmented distributor relationships with direct manufacturer contracts tied to volume commitments and automated inventory replenishment. The Netherlands and Belgium exhibit the most advanced procurement centralization, with university hospital clusters negotiating multi-year framework agreements that specify sustainability metrics alongside unit pricing.
Europe Medical Gloves Market Segmentation
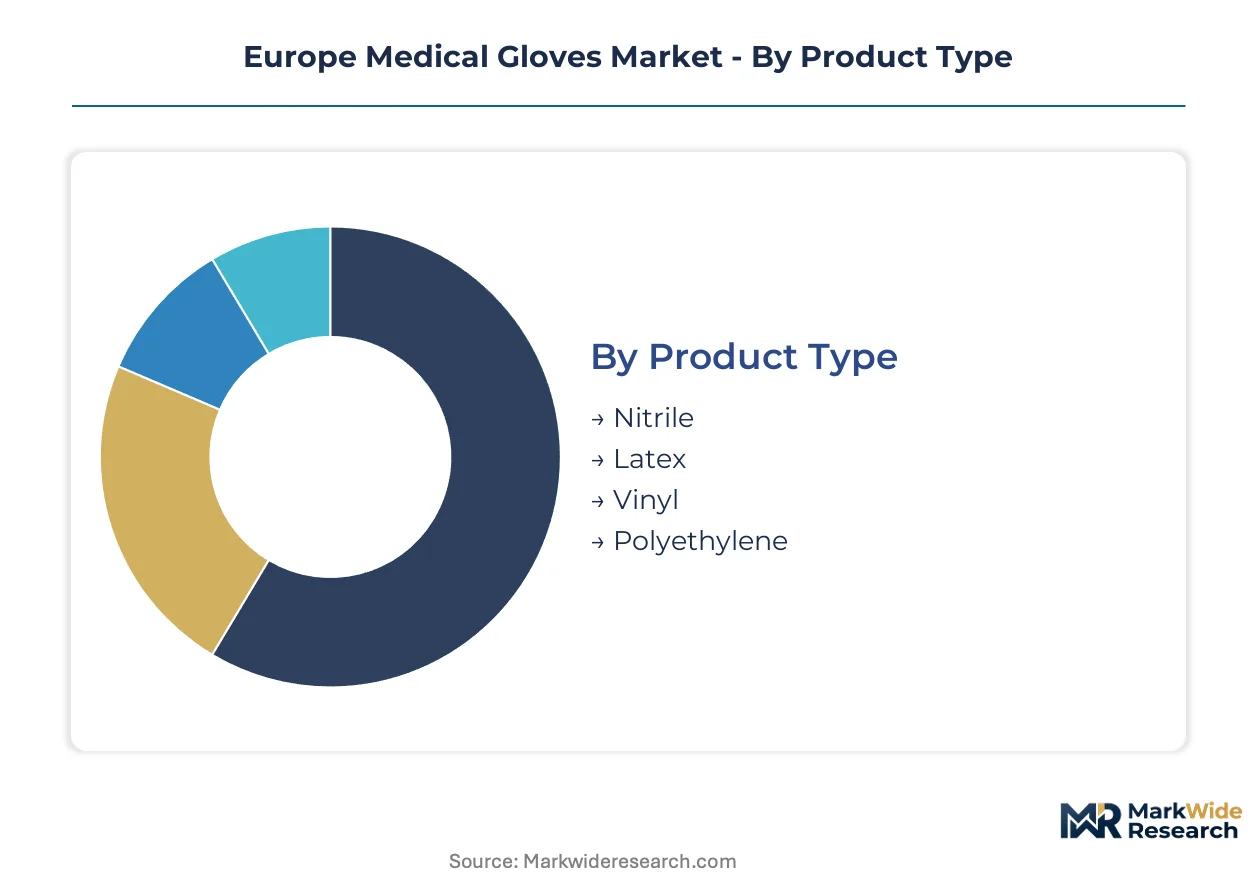
European medical glove procurement routes diverge sharply by product complexity and sterility requirements. Hospital networks negotiate direct contracts for surgical-grade inventory while examination gloves flow through layered distribution.
Product Type:
Channel-mix patterns separate nitrile and latex through hospital procurement departments, while vinyl and polyethylene reach end-users via retail and wholesale intermediaries.
- Nitrile:Synthetic copolymer formulations deliver tensile strength exceeding 14 MPa under EN 455 stress testing. German and French hospital systems specify accelerator-free variants for operating theater procurement, driven by REACH restrictions on thiuram curing agents.
- Latex:Natural rubber formulations maintain dominance in surgical suites requiring maximum tactile sensitivity. Polish and Romanian facilities continue latex adoption where allergy screening protocols remain less stringent, though conversion to synthetics accelerates.
- Vinyl:Polyvinyl chloride compounds serve low-risk examination protocols through retail pharmacy networks and general practitioner supply chains.
- Polyethylene:Cast film constructions handle food-handling adjacent medical applications and veterinary examinations via wholesale distributors.
By volume, vinyl leads through mass examination consumption. By growth pace, nitrile is climbing the fastest as allergy elimination mandates expand.
End User:
Cost-tier stratification separates acute care facilities purchasing premium sterile inventory from outpatient settings optimizing per-procedure economics.
- Hospitals:Tertiary care facilities in the United Kingdom, Germany, and France drive specification-grade procurement through centralized purchasing alliances. EU MDR compliance deadlines accelerate inventory turnover for certified sterile barriers.
- Clinics:Outpatient surgical centers and diagnostic facilities across Benelux and Scandinavia prioritize examination-grade nitrile through distributor consignment arrangements.
- Laboratories:Research and clinical testing facilities require chemical-resistant formulations meeting EN ISO 374 permeation standards.
- Homecare:Post-acute and elderly care settings in Southern Europe source non-sterile inventory through retail pharmacy channels.
By procurement value, hospitals dominate. By expansion trajectory, homecare is gaining share fastest as aging-in-place policies redirect patient volume.
Distribution Channel:
Geographic concentration of healthcare infrastructure determines channel efficiency, with dense hospital networks favoring direct manufacturer relationships.
- Online:E-procurement platforms capture small-clinic and homecare segments where order fragmentation resists traditional sales force economics.
- Retail:Pharmacy chains and medical supply stores serve emergency replenishment and individual practitioner purchases.
- Wholesalers:Regional distributors maintain inventory buffers for mid-tier hospitals across Central and Eastern Europe where direct manufacturer presence remains limited.
- Direct Sales:Integrated manufacturers contract directly with Netherlands and Belgian university hospital clusters under multi-year framework agreements with automated replenishment.
By transaction count, wholesalers process the most orders. By margin capture, direct sales is expanding most quickly as procurement centralization advances.
Application:
Volume-maturity dynamics separate established examination protocols from emerging industrial-medical crossover segments.
- Surgical:Sterile, extended-cuff designs with textured fingertips command premium positioning through specialized manufacturing. German operating theater procurement dominates this segment, with EN ISO 10993 biocompatibility certification mandatory for extended skin contact.
- Examination:Non-sterile nitrile and vinyl formulations handle diagnostic and general patient contact across all European healthcare settings.
- Emergency:Ambulance services and trauma centers require rapid-donning designs with enhanced puncture resistance.
- Industrial:Chemical processing and pharmaceutical manufacturing facilities adopt medical-grade barriers for cleanroom protocols, particularly in Swiss and Irish pharmaceutical clusters.
By unit shipments, examination leads. By value expansion, surgical maintains the steepest trajectory as robotics integration creates specialized glove requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across European procurement zones. German hospital networks prioritize performance specifications over unit cost, while Romanian and Bulgarian acute care facilities remain highly sensitive to per-glove pricing.
Germany
Tertiary care expansion in Bavaria and North Rhine-Westphalia drives specification-grade nitrile procurement. The EU MDR framework mandates sterility assurance documentation that accelerates inventory turnover for certified manufacturers. The Rhine-Ruhr industrial corridor hosts specialized surgical glove fabricators supplying university hospital clusters in Cologne and Düsseldorf.
France
Centralized purchasing alliances among Paris-region hospital networks consolidate supplier rosters toward direct manufacturer contracts. The EU Green Deal circular economy incentives award public procurement preference points for biodegradable formulations. The Lyon-Grenoble medical technology cluster incubates accelerator-free nitrile R&D operations serving operating theater procurement.
United Kingdom
NHS Supply Chain centralization compresses distributor margins while expanding volume commitments for compliant domestic and European manufacturers. REACH restrictions on thiuram accelerators force reformulation of nitrile curing systems used in examination glove tenders. The Midlands manufacturing belt retains polymer processing capacity serving emergency services and primary care networks.
Poland
Hospital construction in Warsaw and Kraków creates demand for single-use barrier devices in infection control tenders. ECHA substance evaluations under REACH prompt domestic manufacturers to validate alternative cross-linking chemistries. The Łódź textile-industrial zone supports glove finishing and packaging operations competing on cost with Asian imports.
Netherlands
University hospital clusters in Amsterdam and Rotterdam negotiate multi-year framework agreements with automated inventory replenishment requirements. The EU MDR transition deadlines compress technical documentation timelines for biological safety assessments. The Rotterdam port logistics hub facilitates just-in-time delivery for Benelux distribution networks serving Belgian and Luxembourg acute care facilities.
Europe Medical Gloves Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European medical gloves sector. Integrated manufacturers with captive nitrile supply chains command premium positioning in surgical-grade segments, while Polish and Southeast Asian scale producers compete on unit economics for examination glove volume. Three archetypes dominate: backward-integrated specialists with polymer production assets, regional scale manufacturers leveraging geographic proximity, and distributor-dependent brands sourcing through contract manufacturing. Consolidation through direct procurement contracts and accelerator-free formulation R&D partnerships represent the dominant competitive moves reshaping tier structure.
Among the integrated manufacturing tier, Ansell Ltd and B. Braun SE exemplify divergent specialization strategies—one anchored in synthetic barrier chemistry, the other in surgical-grade device ecosystems. Mercator Medical SA occupies a position within the regional scale archetype, leveraging Polish production assets to serve Central European hospital networks. These three entities represent the competitive spectrum from premium specialization to cost-optimized regional supply.
| Leading Market Players |
|---|
| Cardinal Health |
| Mercator Medical SA |
| B. Braun SE |
| Medline Industries LP |
| Ansell Ltd |
| Sempermed |
| Top Glove Corporation Bhd |
| HuskMedical |
| Unigloves (UK) Limited |
| Others |
Pricing and Supply Chain Analysis
Asian nitrile production capacity at 85% utilization establishes floor pricing that European converters cannot match without backward integration into polymer production. REACH compliance costs for accelerator-free formulations add 12-18% to manufacturing overhead, compressing margins for distributors dependent on Malaysian and Thai supply.
Pricing Analysis
After-sales service contracts for sterile surgical inventory drive lifetime value capture beyond unit transactions. Three-tier pricing structure across premium, standard, and economy levels separates EN ISO 10993-certified surgical gloves from examination-grade nitrile and bulk vinyl tenders. Pricing pressure stems from NHS Supply Chain centralization and French purchasing alliance consolidation, which compress distributor margins while expanding volume commitments. Homecare segments exhibit highest price sensitivity, while German operating theater procurement prioritizes performance specifications over per-unit cost.
Supply Chain Analysis
Inventory buffers at Rotterdam and Hamburg ports extend lead times to 6-8 weeks for Benelux and German hospital networks sourcing from Southeast Asia. Malaysian and Thai manufacturers control bulk nitrile feedstock, while European converters in Poland and Germany handle finishing and sterilization. Single-source vulnerability concentrates in butadiene-derived acrylonitrile supply from petrochemical complexes. Distribution runs through wholesaler networks in Central and Eastern Europe, with direct manufacturer contracts dominating Netherlands and Belgian procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Accelerator-free formulation mandates under REACH constitute a technological inflection that will eliminate mid-tier competitors lacking analytical chemistry capabilities. The market rewards integrated manufacturers with captive R&D infrastructure.
For Market Incumbents: Consolidate accelerator-free formulation expertise through partnerships with polymer chemistry specialists in the Lyon-Grenoble cluster. Acquire Polish finishing operations to secure cost-competitive supply for Central European expansion. ECHA substance evaluation timelines threaten laggards with 18-24 month certification delays.
For New Entrants and Emerging Players: Anchor in Romanian and Bulgarian hospital construction tenders where per-capita consumption trails Western benchmarks by 40%. Target examination-grade nitrile for outpatient clinics in Benelux through e-procurement platforms. Pursue biodegradable formulation development to capture EU Green Deal procurement preference points in France and the Netherlands.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated specialists with captive nitrile supply chains and mass spectrometry R&D infrastructure. Five-to-ten year viability hinges on MDR certification completion and accelerator-free validation. Monitor ECHA substance evaluation announcements as inflection indicators for competitive tier restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Accelerator-Free Formulation R&D Partnership | REACH compliance secures market access for surgical-grade nitrile manufacturers. |
| Polish Manufacturing Scale-Up | Geographic proximity reduces freight exposure to Asian import volatility. |
| Direct Hospital System Contracting | NHS Supply Chain and French alliance centralization displaces distributor intermediaries. |
| Biodegradable Nitrile Development | EU Green Deal incentives award preference points in Dutch and French tenders. |
| MDR Technical Documentation Investment | Sterility assurance certification accelerates inventory turnover for compliant suppliers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and polymer R&D directors; and secondary validation against ECHA substance evaluation databases, EU MDR technical documentation filings, hospital procurement tender records, and customs trade data. Bottom-up volume estimates triangulated against top-down market sizing across product type, end user, distribution channel, and application dimensions.
Across the analysis window, the forecasting framework modeled nitrile versus latex versus vinyl substitution dynamics, sterile versus non-sterile procurement splits, and direct versus wholesale channel evolution. CAGRs derived from regression analysis of historical consumption patterns against hospital bed expansion, regulatory compliance deadlines, and feedstock cost indices. Industry-specific inputs included EN 455 and EN ISO 374 certification penetration rates and REACH accelerator restriction implementation timelines.
Material uncertainties — ECHA substance evaluation outcomes, butadiene price volatility, and MDR transition deadline extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions about hospital construction trajectories and procurement centralization pace. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Medical Mask Market
Medical Supplies
Sterilization Box Market
Medical Supplies
Smear Mask Market
Medical Supplies
Disposable Medical Gowns Market
Medical Supplies
South Africa Hospital Supplies Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
Cryoboxes Market
Medical Supplies
Hydrogel Dressing Market
Medical Supplies
Surgical and Examination Gloves Market
Medical Supplies
Microcarrier Market
Medical Supplies
Dissolvable Stitches Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Global Swab Market
Medical Supplies
Europe Ultrasound Gels Market
Medical Supplies
Western Europe Sterile Gloves Market