
 Internet of Things (IoT) Security Market | 2026-2036
Internet of Things (IoT) Security Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things (IoT) Security Market Analysis
Healthcare and smart city infrastructure is realigning the Internet of Things (IoT) Security landscape as hospitals and municipal operators prioritize real-time threat detection over legacy perimeter defenses. Palo Alto Networks specializes in network segmentation for clinical environments where medical device interoperability creates attack surface complexity. Forescout dominates device visibility and control, leveraging agentless discovery to secure unmanaged IoT endpoints across heterogeneous enterprise networks. Trend Micro anchors cloud-native security delivery, sustaining competitive pressure through integrated workload protection that spans containerized and serverless IoT backends.
Internet of Things (IoT) Security encompasses cryptographic protocols, behavioral analytics engines, and firmware integrity mechanisms designed to protect connected sensors, actuators, and gateways from unauthorized access, data exfiltration, and operational disruption. The discipline relies on lightweight encryption standards such as AES-128 and certificate-based mutual authentication to function within constrained compute and power budgets characteristic of edge deployments. Endpoint Security solutions currently occupy the largest solution type position as device manufacturers embed hardware trust modules and secure boot capabilities at the silicon layer. Cloud deployment architectures represent the fastest-growing configuration, though hybrid models retain margin strength where regulated industries require on-premise data residency alongside elastic analytics capacity.
The U.S. Food and Drug Administration and the European Union Agency for Cybersecurity shape product standards through pre-market guidance on medical device cybersecurity and the NIS2 Directive's supply-chain security obligations, respectively. China's MIIT enforces GB standards for consumer IoT password complexity and vulnerability disclosure, creating divergent compliance pathways for multinational vendors. Japan's METI coordinates industry-specific security frameworks through its IoT Security Safety Framework consortium, influencing procurement specifications across automotive and industrial sectors. Stakeholders must monitor regulatory fragmentation between these jurisdictions when architecting certification strategies and regional go-to-market sequencing.
Market Dynamics
Edge-native security architectures are displacing centralized cloud processing as smart city infrastructure projects demand millisecond-latency threat response at the network perimeter. This structural shift compresses hardware procurement cycles and forces security vendors to embed cryptographic capabilities directly into gateway silicon.
Growth Catalysts
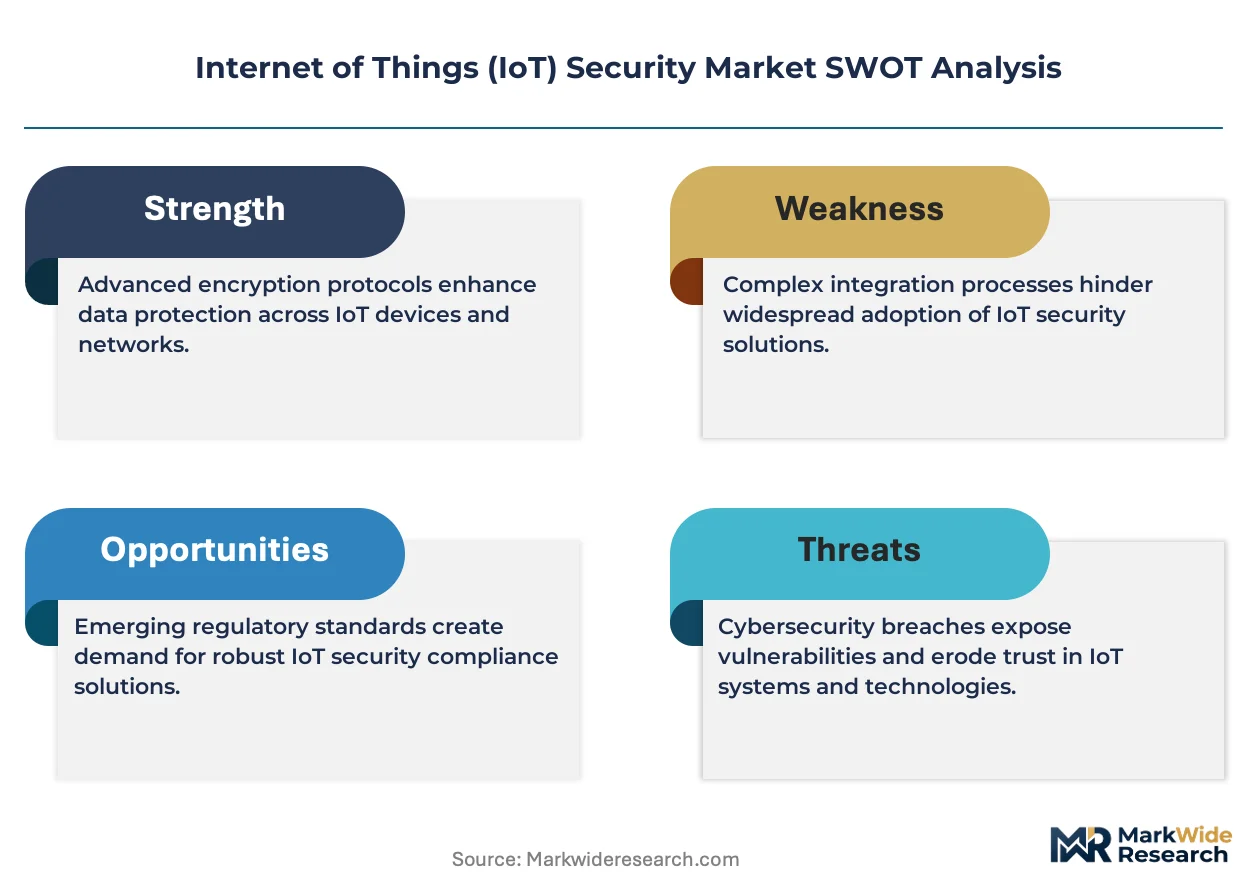
- NIS2 Directive:The EU's supply-chain security obligations mandate vulnerability disclosure and incident reporting for connected device manufacturers, accelerating certification investments across European industrial IoT deployments.
- Medical device interoperability:Hospital networks integrating surgical robots, patient monitors, and imaging systems create attack surface complexity that drives demand for network segmentation and behavioral analytics.
- Japan's automotive sector:METI's IoT Security Safety Framework consortium influences procurement specifications for connected vehicle platforms, embedding security requirements into tier-one supplier contracts.
Market Restraints
- Silicon supply concentration:Hardware trust module production clusters in Taiwan and South Korea, exposing security vendors to geopolitical disruption and foundry allocation constraints.
- Firmware integrity verification costs:Continuous attestation of constrained edge devices demands specialized engineering talent that commands premium compensation in Germany and the United States.
- Legacy protocol persistence:Industrial control systems running Modbus and DNP3 without native encryption force expensive protocol gateway deployments or risky coexistence strategies.
Strategic Opportunities
- India's smart meter rollout:The country's national power grid modernization program creates demand for lightweight cryptographic stacks that function within severe cost and power constraints.
- Post-quantum cryptography convergence:NIST standardization of lattice-based algorithms enables vendors to differentiate through future-proofed certificate infrastructure for long-deployment infrastructure assets.
- Operational technology channel expansion:Industrial automation distributors in Germany and Japan are adding security SKUs, opening access to maintenance-contract relationships that IT channels cannot replicate.
Industry Challenges
- Embedded security engineering scarcity:Firmware hardening, side-channel resistance, and secure boot implementation require specialized skills that universities and vocational programs have not scaled to meet.
- Multi-jurisdiction certification timelines:Concurrent FDA pre-market guidance, EU AI Act conformity assessment, and China's GB standard testing extend product launch windows by 12-18 months for medical and automotive applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things (IoT) Security Market |
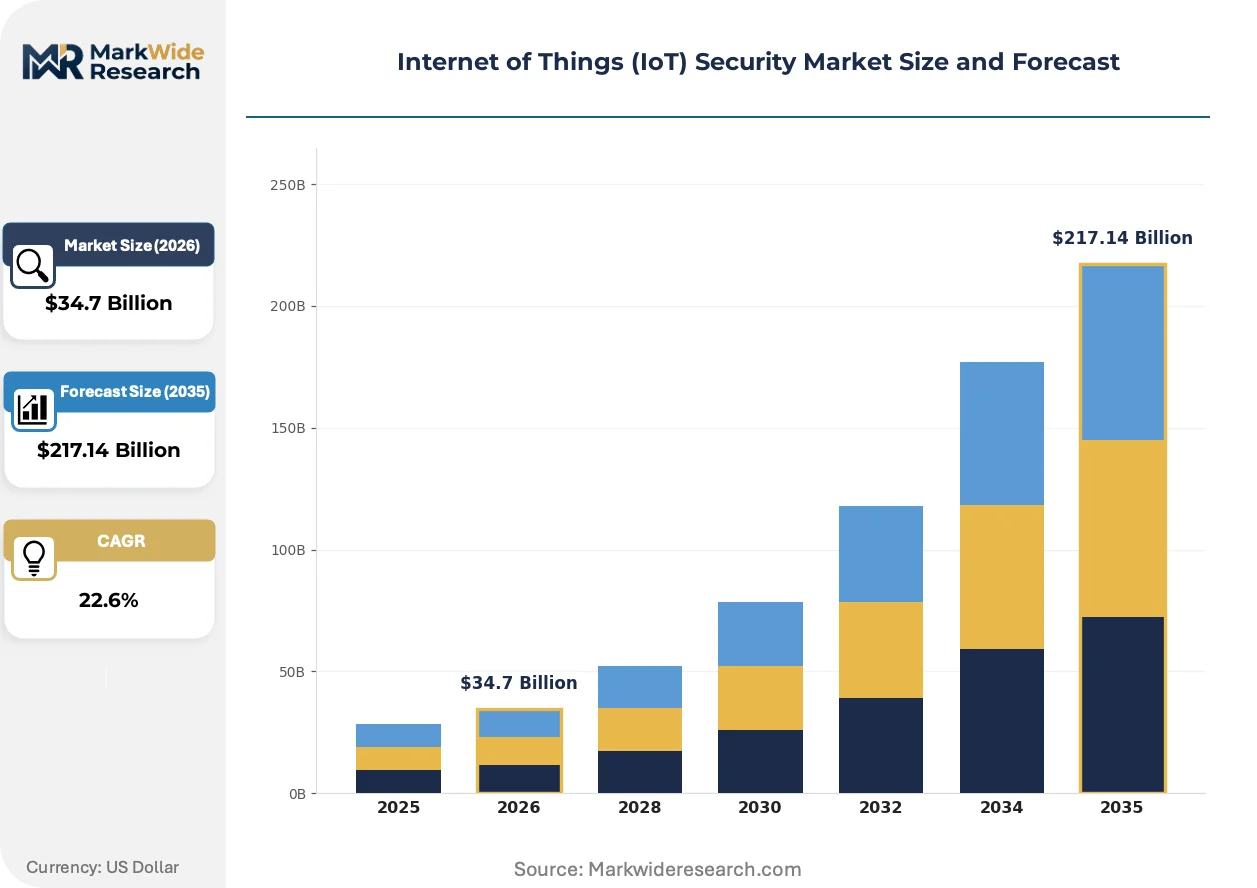
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $217.14 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premise, Cloud, Hybrid, Edge Solution Type: Endpoint Security, Network Security, Application Security, Security Analytics Industry Vertical: Healthcare, Manufacturing, Transportation, Smart Cities End User: Enterprises, Government, SME, Consumers |
| Companies Covered | Check Point Software Technologies, Trend Micro, Palo Alto Networks, Nozomi Networks, Juniper Networks, Armis, Forescout, Symantec, Fortinet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things (IoT) Security Market Emerging Trajectories
Behavioral analytics engines are compressing detection-to-response cycles by identifying anomalous device communication patterns without signature-dependent rules. This capability is reshaping procurement criteria across critical infrastructure operators.
Confidential computing using hardware-based trusted execution environments is automating sensitive data processing at the edge. Municipal water utilities and energy distributors are piloting these capabilities for encrypted analytics on operational data. The technology is automating compliance with data residency requirements that previously forced traffic back to centralized cloud regions.
The EU AI Act's risk classification system for biometric and critical infrastructure applications imposes conformity assessment obligations on IoT vendors deploying machine learning at the edge. Industrial sensor manufacturers must now document training data provenance and model robustness. German automotive suppliers and Dutch port operators face the most immediate compliance deadlines, driving consolidation around notified body relationships.
Hospital procurement departments are unbundling security monitoring from device purchase contracts, creating standalone service relationships with specialized vendors. This shift displaces original equipment manufacturer maintenance bundles that bundled security updates with hardware support. The pattern is most visible in United States health systems responding to FDA post-market surveillance guidance.
Internet of Things (IoT) Security Market Segmentation
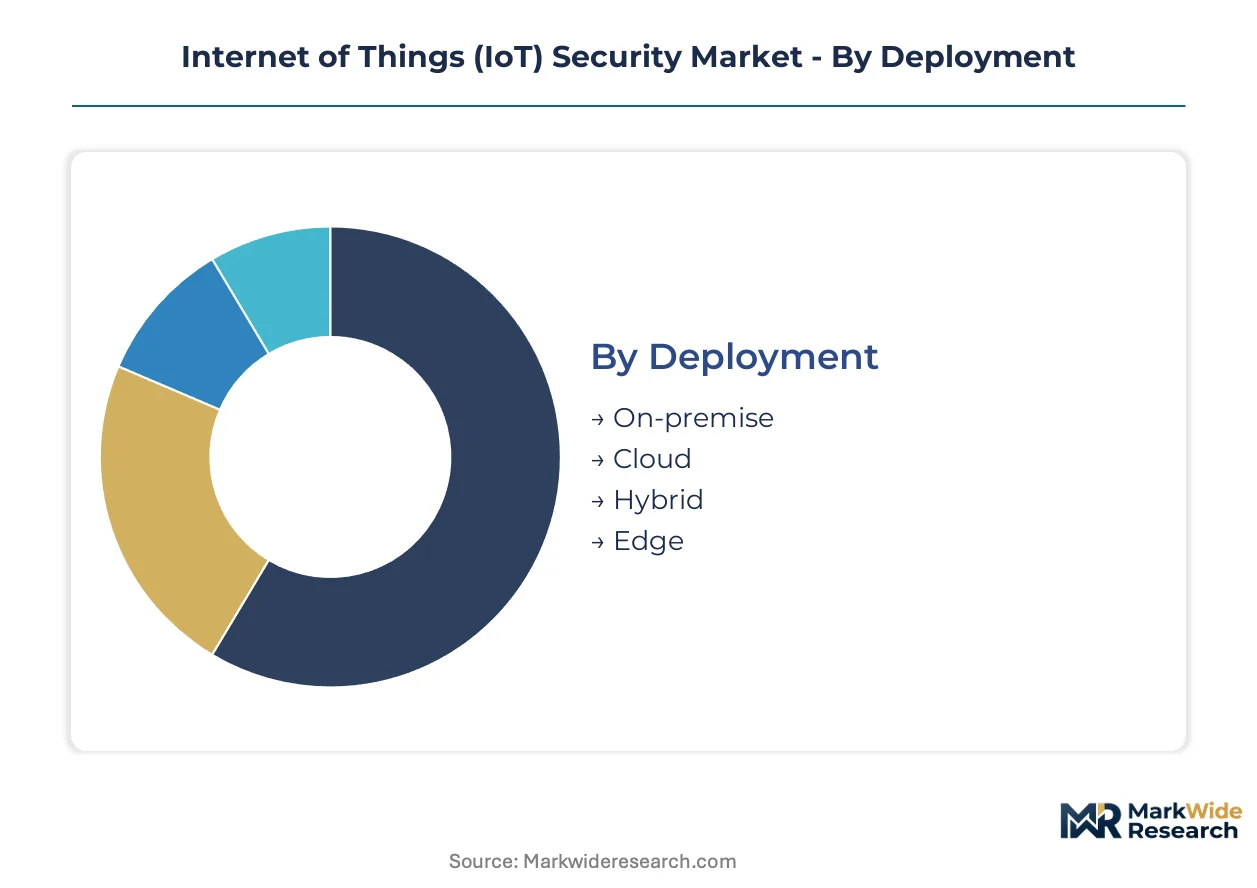
IoT security procurement splits across architectural choices, solution depth, industry risk profiles, and buyer sophistication. Each segmentation axis reveals distinct margin structures and competitive dynamics that vendors must navigate.
Deployment:
Latency requirements and data sovereignty rules drive architectural selection more than cost optimization.
- On-premise:Air-gapped infrastructure serving nuclear facilities and defense installations where external connectivity violates operational security mandates. German automotive suppliers and Japanese semiconductor fabs maintain these deployments for IP protection.
- Cloud:Elastic compute pools enable behavioral analytics at scale for distributed device fleets. Healthcare networks in the United States leverage cloud deployment for centralized threat correlation across multi-hospital systems.
- Hybrid:Sensitive telemetry remains local while threat intelligence feeds centralize. Smart city operators in France and the Netherlands favor this model for GDPR-compliant video analytics.
- Edge:Millisecond-response cryptography embedded in gateway silicon. Manufacturing lines and autonomous vehicle platforms require this architecture where cloud round-trips fail operational deadlines.
Volume sits with Cloud; growth tilts toward Edge.
Solution Type:
Security spend concentrates where device heterogeneity creates visibility gaps.
- Endpoint Security:Hardware trust modules and secure boot capabilities embedded at the silicon layer. Medical device manufacturers in the United States integrate these capabilities to satisfy FDA pre-market cybersecurity guidance.
- Network Security:Micro-segmentation and zero-trust access controls for unmanaged device traffic. Hospital networks deploying surgical robots and patient monitors drive procurement here.
- Application Security:Runtime protection for IoT firmware and API gateways. Smart city platforms integrating third-party sensor networks require this layer.
- Security Analytics:Behavioral engines detecting anomalous device communication without signature dependencies. Critical infrastructure operators in Japan and Germany pilot these capabilities for operational technology environments.
Endpoint Security commands the largest share; Security Analytics is expanding most quickly.
Industry Vertical:
Regulatory enforcement intensity shapes vertical penetration rates.
- Healthcare:FDA post-market surveillance guidance and EU MDR cybersecurity annexes mandate continuous monitoring. United States health systems unbundle security from device purchase contracts.
- Manufacturing:NIS2 Directive supply-chain obligations force European industrial IoT vendors into accelerated certification cycles. German automation distributors add security SKUs to maintenance relationships.
- Transportation:METI's IoT Security Safety Framework embeds requirements into Japanese automotive tier-one supplier contracts. Connected vehicle platforms drive gateway security demand.
- Smart Cities:Municipal procurement prioritizes edge-native architectures for traffic management and utility monitoring. India's national power grid modernization creates demand for lightweight cryptographic stacks.
Manufacturing absorbs the most volume; Smart Cities is gaining share fastest.
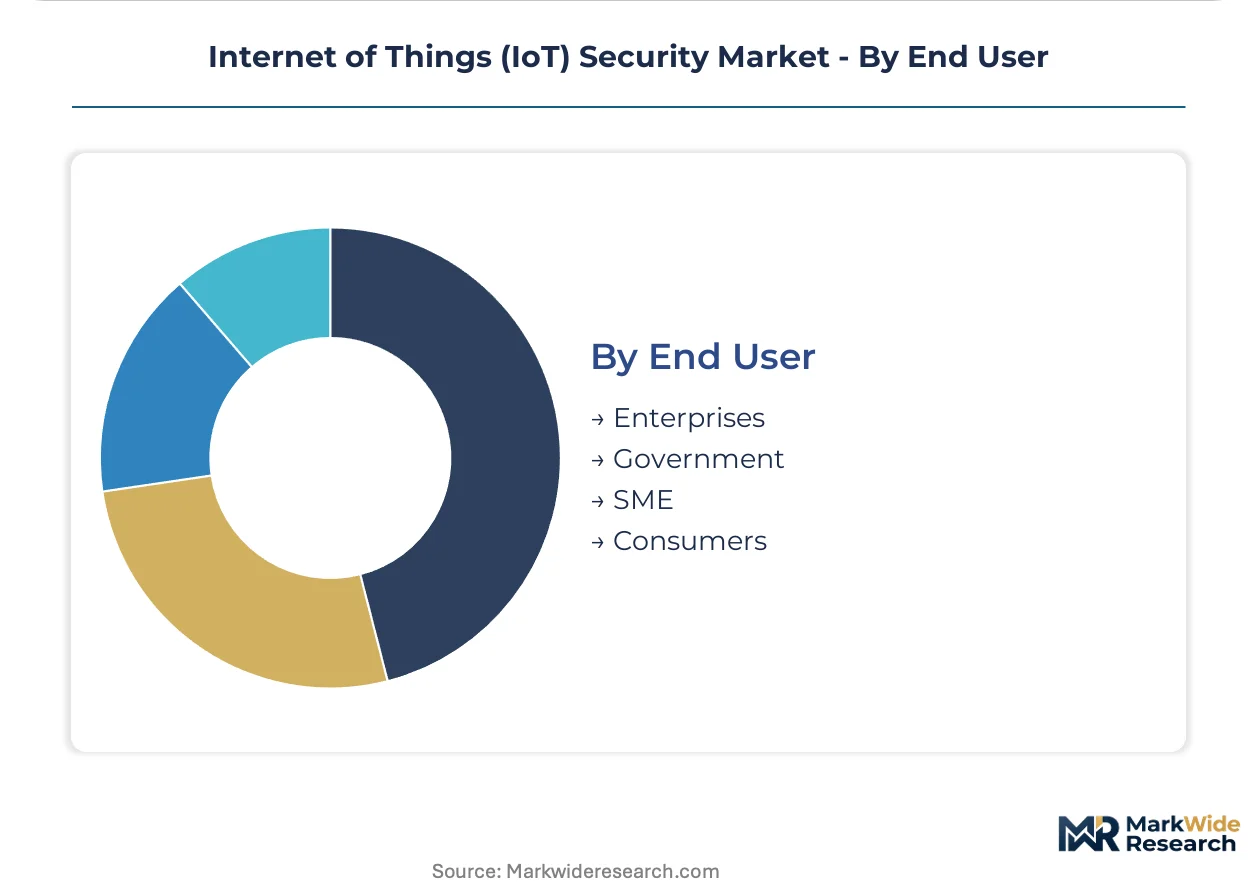
End User:
Budget scale and compliance exposure differentiate buyer segments.
- Enterprises:Fortune 500 industrial conglomerates with dedicated security operations centers. These buyers demand integrated platforms spanning endpoint through cloud.
- Government:Critical infrastructure agencies with classified procurement channels. Defense and intelligence applications require domestic certification and supply-chain provenance.
- SME:Mid-market manufacturers and regional healthcare providers purchasing through managed security service providers. Price sensitivity limits deployment to essential compliance-driven capabilities.
- Consumers:Smart home device owners relying on manufacturer-default security settings. China's MIIT enforces GB standards for password complexity and vulnerability disclosure in this segment.
Enterprises dominate current spend; Government procurement is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Bangalore concentrate IoT security engineering talent through tax incentives and infrastructure subsidies. These zones attract multinational vendors seeking localized certification expertise. Procurement patterns diverge sharply between jurisdictions with mature data protection frameworks and emerging markets prioritizing cost optimization.
United States
FDA post-market surveillance guidance and healthcare network consolidation drive demand for medical device security monitoring. The Cybersecurity and Infrastructure Security Agency coordinates critical infrastructure protection standards. Hospital procurement departments in the Boston-Cambridge corridor unbundle security services from device purchase contracts.
Germany
NIS2 Directive supply-chain obligations accelerate certification investments across industrial IoT deployments. The country's national cybersecurity regulator enforces incident reporting mandates for connected device manufacturers. Automation distributors in Bavaria add security SKUs to long-standing maintenance relationships with Mittelstand manufacturers.
Japan
METI's IoT Security Safety Framework embeds security requirements into automotive tier-one supplier contracts. The framework influences procurement specifications for connected vehicle platforms. Automotive electronics clusters in Aichi Prefecture integrate gateway security capabilities into production lines serving Toyota and Honda supply chains.
India
The national smart meter rollout creates demand for lightweight cryptographic stacks functioning within severe cost constraints. The Central Electricity Authority mandates security standards for power grid modernization. Engineering services firms in Bangalore develop firmware attestation solutions for state electricity distribution companies.
China
MIIT enforces GB standards for consumer IoT password complexity and vulnerability disclosure. The dual carbon goals accelerate smart building deployments requiring edge-native security architectures. Hardware manufacturers in Shenzhen embed trust modules into gateway silicon for domestic and export markets.
Internet of Things (IoT) Security Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pure-play vendors commanding premium positioning in regulated verticals while platform conglomerates absorb volume through bundled offerings. The vendor base organizes into three tiers: network security incumbents extending portfolios, device visibility specialists, and cloud-native workload protection platforms. Consolidation pressures favor acquisition of behavioral analytics capabilities and edge-native cryptographic engineering talent. Strategic partnerships between automation distributors and security vendors reshape channel economics in industrial segments.
Within the network security tier, Check Point Software Technologies and Palo Alto Networks exemplify platform breadth strategies. Forescout occupies a distinct position in device visibility and control through agentless discovery approaches. Trend Micro anchors cloud-native delivery models for containerized IoT backends.
| Leading Market Players |
|---|
| Check Point Software Technologies |
| Trend Micro |
| Palo Alto Networks |
| Nozomi Networks |
| Juniper Networks |
| Armis |
| Forescout |
| Symantec |
| Fortinet |
| Others |
Supply Flow & Price Mechanics
Fortune 500 industrial conglomerates with dedicated security operations centers command pricing leverage through volume commitments and platform consolidation mandates. Their procurement specifications favor subscription-based SaaS tiers bundled with hardware trust modules, compressing margins for point-solution vendors unable to scale across deployment architectures.
Pricing Analysis
Short lead-time delivery commands premium positioning as German automotive suppliers and Japanese semiconductor fabs accelerate certification cycles under NIS2 and METI frameworks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical device stacks from consumer-grade firmware protection. Price differentiation hinges on certification grade and vertical integration depth. Pricing pressure stems from silicon supply concentration in Taiwan and South Korea, forcing cost absorption or foundry allocation premiums. SME manufacturers purchasing through managed security service providers exhibit highest price sensitivity; government critical infrastructure agencies with classified procurement channels show lowest.
Supply Chain Analysis
Embedded security engineering talent scarcity in Germany and the United States constrains firmware hardening and secure boot implementation capacity. Hardware trust module production clusters in Taiwan, South Korea, and China, with Shenzhen special economic zones concentrating gateway silicon manufacturing. Raw material dependencies span semiconductor-grade silicon wafers, cryptographic co-processor IP cores, and secure element substrates. Single-source vulnerability in Taiwan foundry allocation exposes vendors to geopolitical disruption. Distribution runs through industrial automation distributors in Germany and Japan adding security SKUs to maintenance-contract relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as multi-jurisdiction certification timelines extend product launch windows by 12-18 months, forcing capital-constrained specialists toward acquisition or exit.
For Market Incumbents: Anticipate regulatory fragmentation between FDA pre-market guidance, EU AI Act conformity assessment, and China's GB standards by pre-positioning notified body relationships across all three jurisdictions. Acquire behavioral analytics capabilities and edge-native cryptographic engineering talent before talent scarcity worsens in Germany and the United States. Channel control through automation distributor partnerships in Bavaria and Aichi Prefecture defends against IT-channel competitors unable to replicate maintenance-contract access. For New Entrants and Emerging Players: Launch via managed security service provider channels targeting SME manufacturers and regional healthcare providers in India and Southeast Asia, segments where price sensitivity has limited incumbent penetration. India's national smart meter rollout presents the most penetrable geography, with state electricity distribution companies seeking lightweight cryptographic stacks within severe cost constraints. Post-quantum cryptography convergence offers differentiation through future-proofed certificate infrastructure for infrastructure assets with 15-20 year deployment horizons. For Investors and Strategic Acquirers: The window for entry favors behavioral analytics specialists and edge-native firmware engineering boutiques with demonstrated FDA or METI certification pathways. Long-term viability rests on owning capabilities that industrial conglomerates cannot build organically within compressed procurement cycles. The signal to watch is consolidation of notified body relationships as EU AI Act deadlines approach for German automotive suppliers and Dutch port operators.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Edge-Native Cryptographic Engineering Firm | Secures scarce firmware hardening talent ahead of NIS2 certification deadlines in Germany. |
| Notified Body Relationship Consolidation | Accelerates EU AI Act conformity assessment for biometric and critical infrastructure applications. |
| Industrial Automation Channel Partnership | Opens maintenance-contract access in Japan's Aichi Prefecture automotive electronics clusters. |
| Post-Quantum Certificate Infrastructure Launch | Differentiates offerings for India's smart meter rollout and long-deployment infrastructure assets. |
| Behavioral Analytics Engine Integration | Compresses detection-to-response cycles for critical infrastructure operators in Germany and Japan. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with chief information security officers, biomedical engineers at United States health systems, automation distributor procurement leads in Bavaria, and METI framework consortium participants. FDA pre-market guidance documents, EU NIS2 Directive implementation notices, China's MIIT GB standard releases, and Japan's IoT Security Safety Framework technical specifications provided regulatory trajectory validation. Bottom-up device shipment analysis and top-down security spend allocation triangulated market sizing.
Reconciliation of hyperscaler capex disclosures, semiconductor foundry utilization reports, and hospital procurement database trends informed the analytical framework across the projection horizon. Segmentation dimensions modeled encompass deployment architecture, solution type depth, industry vertical risk profile, and end-user sophistication tier, with edge-native versus cloud-native adoption patterns as an IoT-specific dimension. CAGRs derived from regression analysis of historical certification investment cycles and regulatory enforcement intensity trajectories, cross-checked against industrial IoT density metrics in Germany, Japan, and the United States.
Geopolitical disruption in Taiwan foundry operations, delays in NIST post-quantum standardization, and divergence between FDA and EU MDR cybersecurity annex interpretations are the dominant revision risks. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and silicon supply allocation stability. Material deviation in foundry concentration or multi-jurisdiction certification harmonization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Saas-Based IT Security Market
Cybersecurity
Next-Gen Firewall Market
Cybersecurity
Digital Forensics Market
Cybersecurity
Argentina Cybersecurity Market
Cybersecurity
Homomorphic Encryption Market
Cybersecurity
Denmark Cybersecurity Market
Cybersecurity
SD-WAN Security Market
Cybersecurity
AI in Cybersecurity Market
Cybersecurity
Global Digital Forensic Laboratory As a Service Market
Cybersecurity
Multi-Cloud Data Protection Market
Cybersecurity
Anti-Malware Market
Cybersecurity
Europe Web Application Firewall Market
Cybersecurity
Threat Intelligence Security Market
Cybersecurity
Oman Cybersecurity Market
Cybersecurity
Europe Cloud DLP Market
Cybersecurity
Benelux Cybersecurity Market