
 Europe Cloud DLP Market | 2026-2036
Europe Cloud DLP Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cloud DLP Market Analytics
ISO 27001 certification is collapsing the vendor landscape for European cloud DLP procurement, with only a handful of providers meeting the threshold for enterprise and government contracts. Microsoft leverages its Azure ecosystem to anchor cloud-native DLP deployments across the United Kingdom and Nordic public sectors. Palo Alto Networks competes through Prisma Cloud integration, while Forcepoint specializes in human-centric data protection for regulated European industries.
Cloud data loss prevention encompasses policy-driven technologies that monitor, detect, and block unauthorized exfiltration of sensitive information across SaaS, IaaS, and PaaS environments, typically employing deep content inspection, contextual analysis, and automated remediation workflows. The technology serves organizations requiring continuous data visibility without impeding workforce productivity in distributed cloud architectures. Hybrid Cloud deployment configurations generate the deepest margin pools as enterprises balance sovereignty requirements with elasticity needs. Machine Learning technology segments are expanding fastest as behavioral analytics replace static rule-based detection, while Professional Services surrounding implementation and tuning retain premium pricing power.
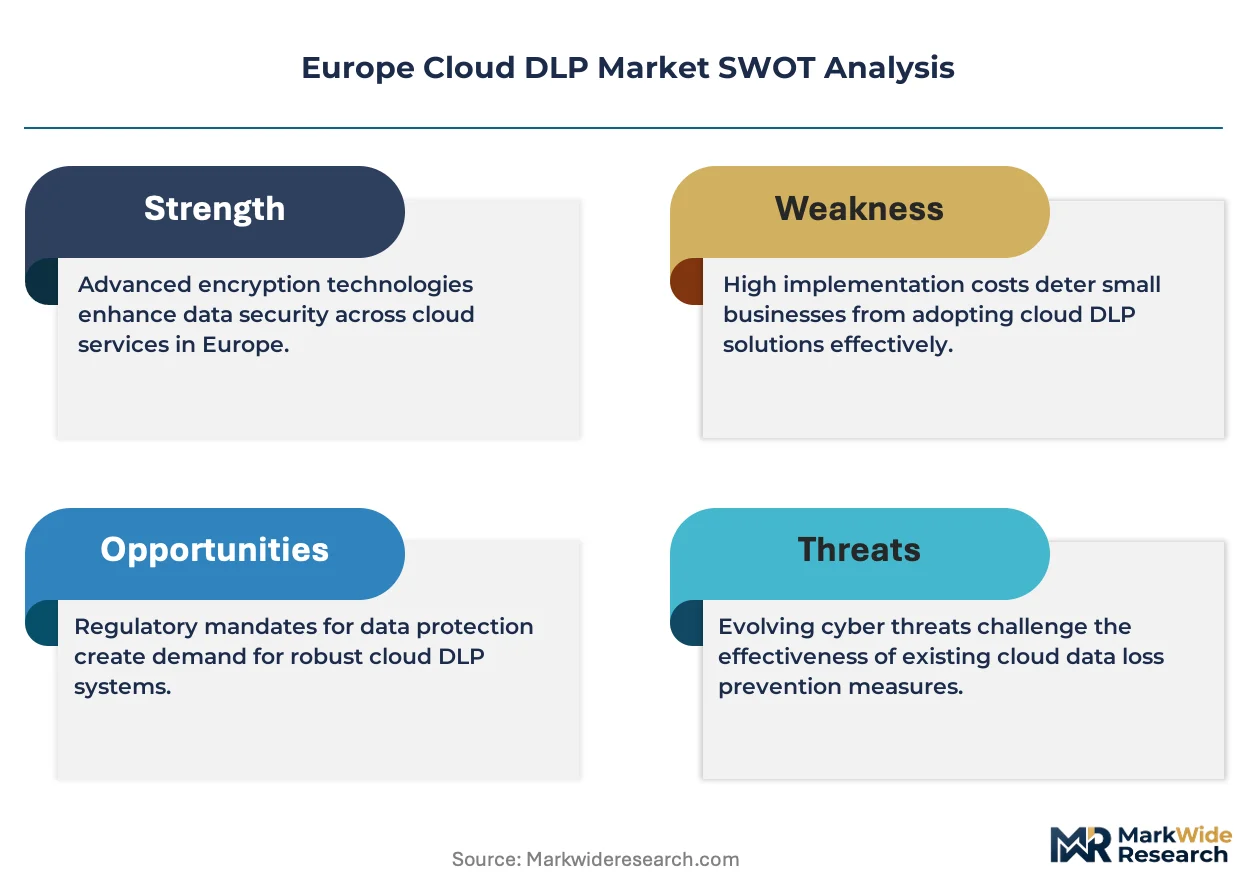
GDPR enforcement by national data protection authorities across France, Germany, and Italy directly shapes product roadmaps, with supervisory fines compelling boards to prioritize DLP investment. The EU AI Act adds compliance complexity for cloud DLP vendors processing automated decision-making data flows, requiring algorithmic transparency documentation. EMA guidelines for pharmaceutical data integrity further tighten requirements for life sciences cloud migrations. Stakeholders must weigh sovereignty certifications against AI-enhanced detection capabilities when selecting platforms for the next wave of European cloud consolidation.
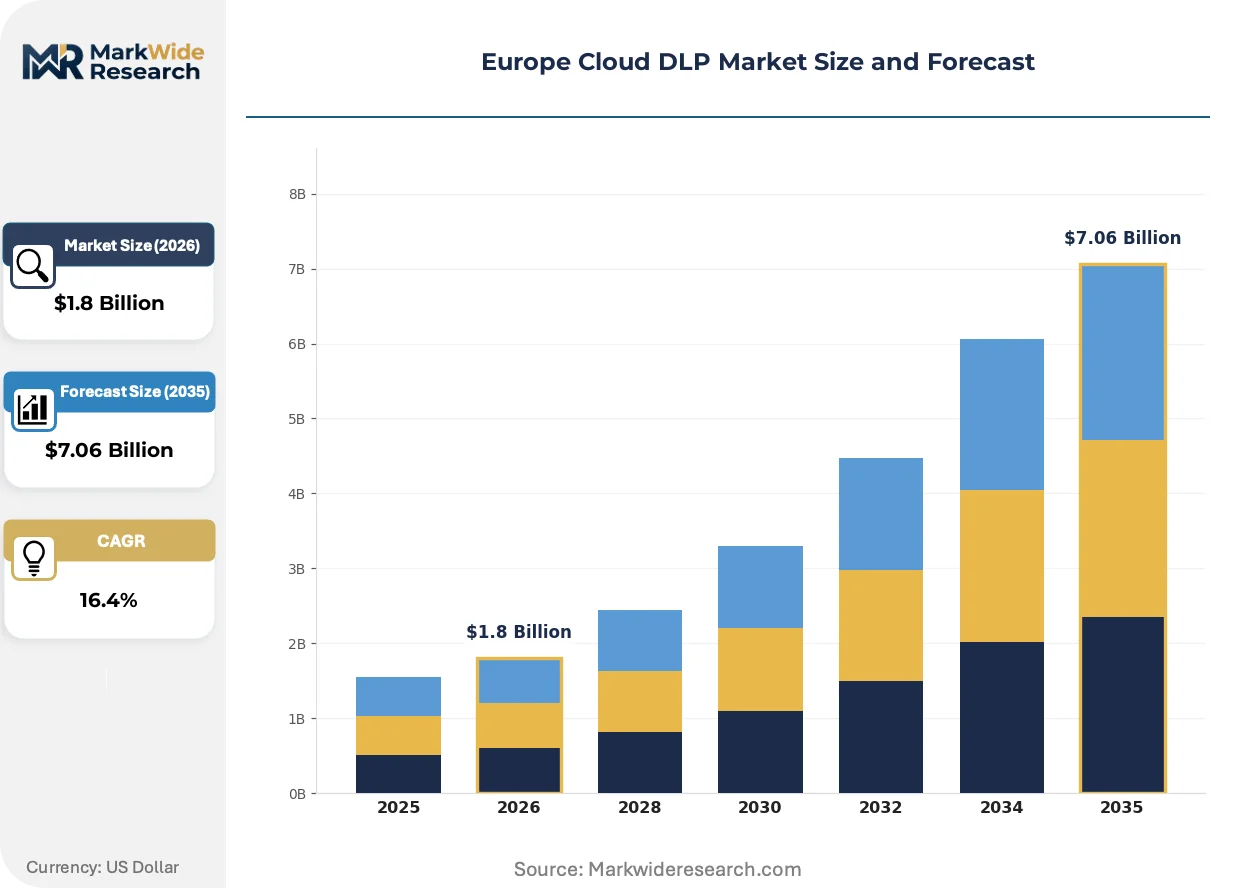
Market Dynamics
GDPR enforcement and the EU AI Act are compressing procurement timelines for cloud DLP platforms as supervisory authorities in France, Germany, and Italy escalate fine activity against data governance failures. Enterprises now face board-level mandates to demonstrate continuous data visibility across hybrid architectures.
Growth Catalysts
- GDPR Article 32 mandates:Security of processing requirements compel financial services firms in Germany and France to deploy automated data exfiltration controls.
- Hybrid cloud migration:United Kingdom enterprises migrating sensitive workloads require sovereignty-compliant DLP policies that span on-premises and Azure environments.
- Machine learning detection:Behavioral analytics engines replace static rule-based systems, enabling real-time classification of unstructured data across SaaS applications.
Market Restraints
- ISO 27001 certification scarcity:Only a handful of vendors meet certification thresholds for enterprise and government contracts, collapsing procurement options.
- Algorithmic transparency requirements:The EU AI Act imposes documentation burdens on ML-enhanced DLP platforms processing automated decision-making data flows.
- Legacy system integration friction:On-premises data loss prevention investments in European banks resist full cloud-native replacement, extending hybrid complexity.
Strategic Opportunities
- Life sciences cloud expansion:EMA guidelines for pharmaceutical data integrity create specialized demand for GxP-validated DLP deployments in Switzerland and the Netherlands.
- Nordic public sector digitization:Swedish and Norwegian government agencies accelerate cloud migration, requiring sovereign-certified DLP for citizen data protection.
- Channel partner ecosystems:Systems integrators with GDPR compliance expertise capture implementation and tuning margins previously retained by vendors.
Industry Challenges
- Cross-border data flow mapping:Schrems II rulings complicate transatlantic cloud architectures, requiring legal-technical coordination that most enterprises lack in-house.
- Skill scarcity in behavioral analytics tuning:Security operations centers struggle to calibrate ML models without false-positive rates that degrade workforce productivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cloud DLP Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Customer Type: Enterprise, SMEs, Government, Educational Institutions Service Type: Managed Services, Professional Services, Consultancy, Training Technology: Machine Learning, Encryption, Data Masking, Data Loss Prevention Suites |
| Companies Covered | Broadcom Inc, Check Point Software Technologies Ltd, Cisco Systems, Inc., Forcepoint, Zscaler, Inc., Microsoft, IBM Corporation, Palo Alto Networks, Inc., Fortinet, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cloud DLP Market Evolving Landscape
Cloud-native data loss prevention architectures are displacing perimeter-centric models as distributed workforces dissolve traditional network boundaries. Three interconnected developments are restructuring competitive positioning and procurement patterns.
Contextual access brokers are fragmenting the DLP technology stack by embedding data protection decisions directly into identity and access management workflows. Financial services institutions in the United Kingdom deploy these brokers to enforce granular policies across Microsoft 365 and Salesforce environments without separate agent infrastructure. The convergence is compressing standalone DLP vendor margins while elevating platform ecosystems.
The EU AI Act's algorithmic transparency requirements are forcing vendors to document training data provenance and decision logic for automated classification engines. Cloud DLP providers processing biometric or behavioral data must now maintain technical documentation accessible to national supervisory authorities. Life sciences firms in Germany and France are prioritizing vendors with pre-built compliance templates for high-risk AI system registration.
Outcome-based security contracts are displacing perpetual licensing in enterprise procurement, with buyers demanding measurable reduction in data exposure incidents. Channel partners with incident response capabilities capture recurring revenue streams previously monopolized by software vendors. This shift concentrates most rapidly among United Kingdom mid-market enterprises lacking dedicated security operations resources.
Europe Cloud DLP Market Segmentation
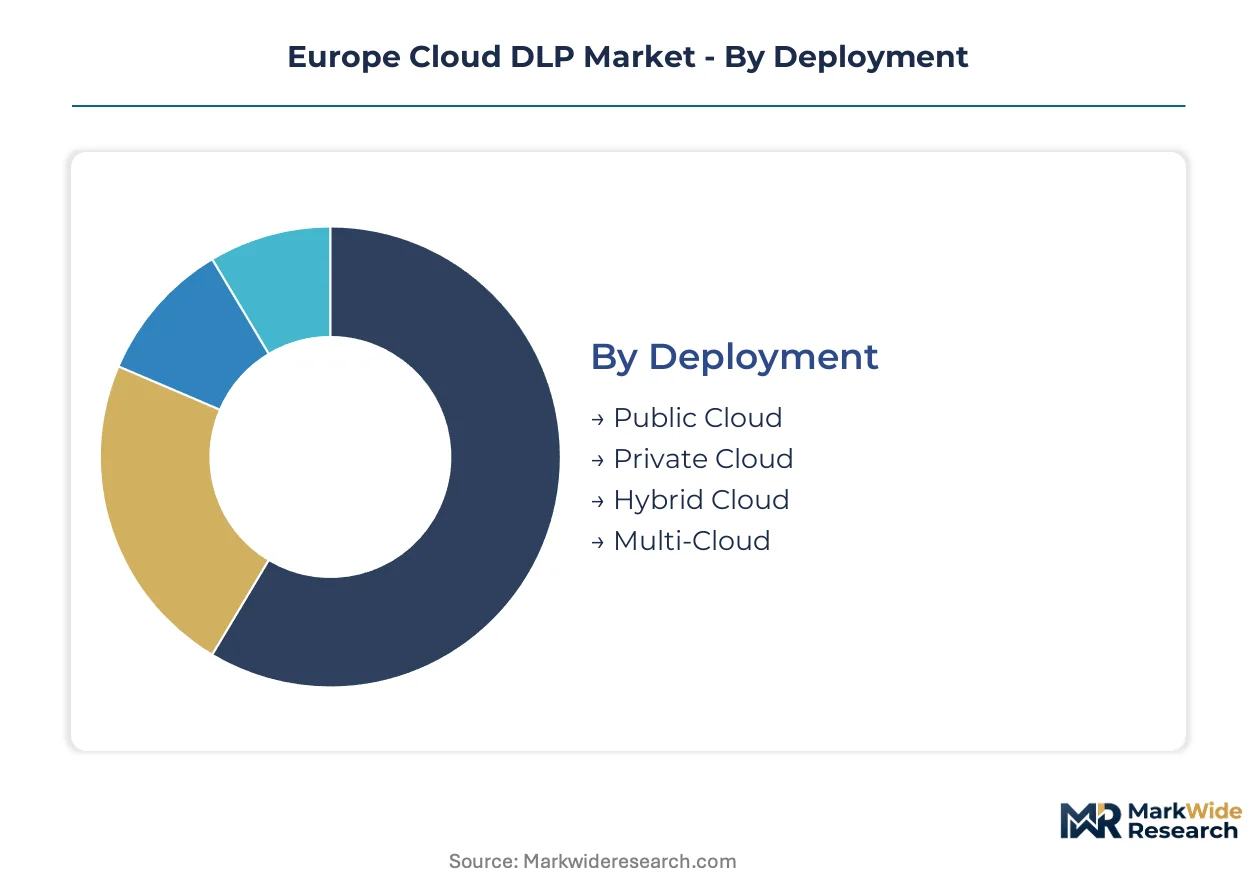
Cloud DLP procurement in Europe fractures across four distinct category axes, each reflecting divergent compliance burdens, technical architectures, and buyer sophistication levels. Understanding these segment boundaries clarifies where vendors must specialize versus where platform breadth wins.
Deployment:
Substitution pressure runs highest in public cloud configurations as native tooling from hyperscalers displaces standalone vendor offerings.
- Public Cloud:Deployments rely on cloud-native API integrations with SaaS platforms like Microsoft 365 and Salesforce. German financial institutions favor these for rapid activation, though they face lock-in risks when GDPR Article 44 cross-border transfer requirements shift.
- Hybrid Cloud:Configurations span on-premises data centers and sovereign cloud regions, generating premium margins as United Kingdom enterprises balance elasticity with data residency mandates under Schrems II rulings.
- Private Cloud:Dedicated infrastructure serves defense contractors and critical national infrastructure operators in France requiring air-gapped environments.
- Multi-Cloud:Architectures distribute policies across Azure, AWS, and Google Cloud simultaneously, demanding vendor-agnostic orchestration layers that few European providers have perfected.
Hybrid Cloud retains volume leadership; Multi-Cloud holds the steepest expansion curve.
Customer Type:
Cost tier stratification separates buyers by procurement sophistication and compliance penalty exposure.
- Enterprise:Multinationals with dedicated CISO functions deploy comprehensive DLP suites across 50,000+ endpoints, typically mandating ISO 27001 certification and EU AI Act algorithmic documentation from vendors.
- Government:Agencies in Sweden and Norway require sovereign-certified deployments with data localization guarantees, often procuring through national security-cleared channels.
- SMEs:Mid-market firms in the Netherlands and Belgium purchase through managed service providers, accepting lighter feature sets for predictable per-user pricing.
- Educational Institutions:Universities across Italy and Spain face constrained IT budgets but rising research data protection obligations under Horizon Europe funding requirements.
Enterprise captures the largest absolute spend; Government segments are climbing fastest as Nordic digitization accelerates.
Service Type:
Margin concentration follows implementation complexity rather than software licensing alone.
- Professional Services:Implementation and tuning engagements command premium day rates, particularly for behavioral analytics calibration in French banking environments where false positives disrupt trading workflows.
- Managed Services:Continuous monitoring and incident response subscriptions attract United Kingdom mid-market buyers lacking internal security operations centers.
- Consultancy:GDPR compliance gap assessments and data flow mapping engagements precede most large DLP procurements in Germany.
- Training:End-user awareness programs and SOC analyst certification courses round out vendor relationships but generate thinner margins.
Professional Services dominates revenue per engagement; Managed Services is expanding most quickly as outcome-based contracts displace perpetual licenses.
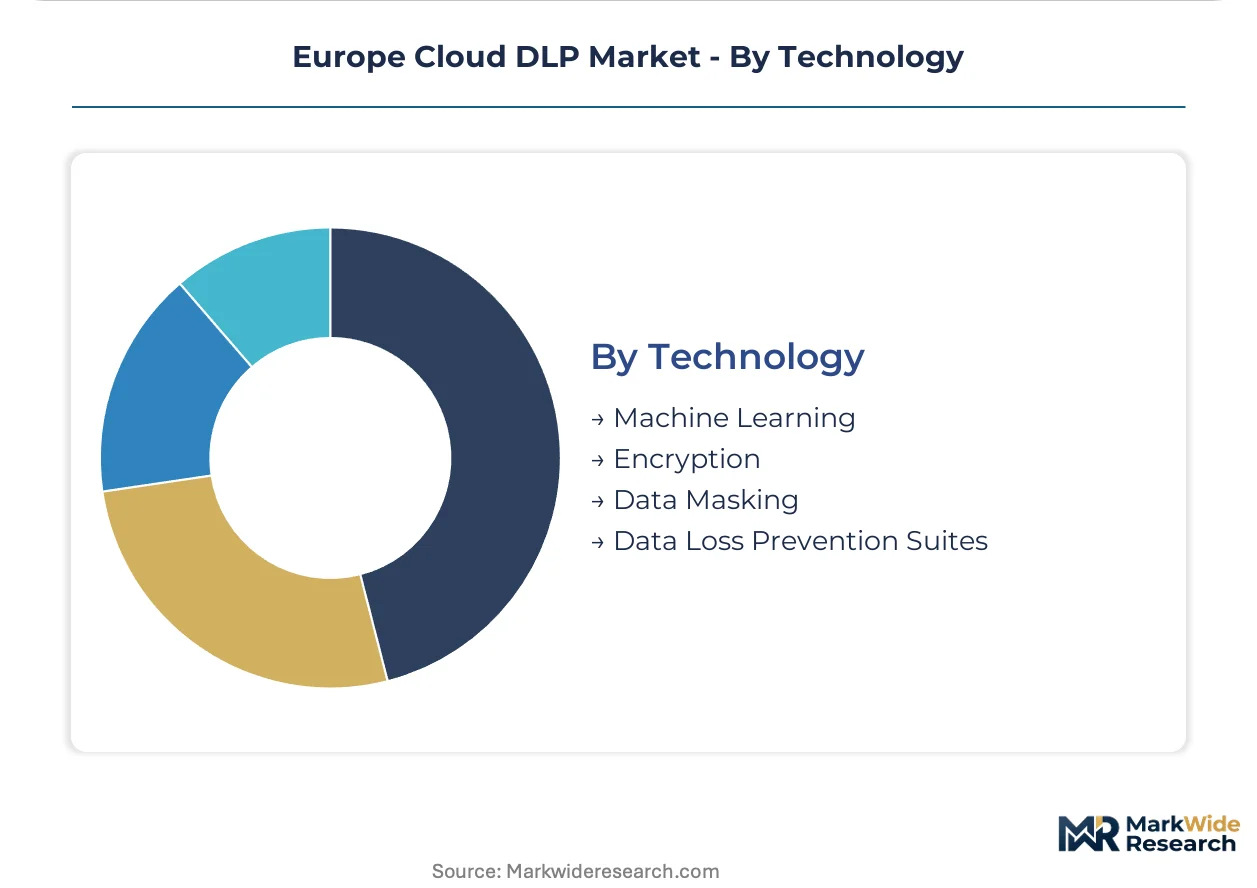
Technology:
Maturity gaps separate established capabilities from emerging detection paradigms.
- Machine Learning:Behavioral analytics engines analyze user activity patterns and data access anomalies in real time, replacing static regex-based rules that overwhelmed French pharmaceutical firms with alert fatigue.
- Data Loss Prevention Suites:Integrated platforms combining endpoint, network, and cloud inspection capabilities serve as the default procurement choice for United Kingdom financial services consolidation projects.
- Encryption:Field-level and tokenization technologies address data-at-rest requirements in Swiss banking and German automotive supply chains.
- Data Masking:Dynamic redaction for non-production environments supports EMA-compliant pharmaceutical development workflows in the Netherlands.
DLP Suites maintain installed base dominance; Machine Learning is gaining share fastest as static detection loses credibility with European regulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR enforcement and the EU AI Act are compressing procurement timelines for cloud DLP platforms as supervisory authorities escalate fine activity. Enterprises now face board-level mandates to demonstrate continuous data visibility across hybrid architectures.
United Kingdom
Financial services firms in London and Edinburgh are migrating sensitive workloads to hybrid Azure environments. The UK Information Commissioner's Office has issued record fines for data governance failures, compelling CISOs to prioritize automated exfiltration controls. Manchester-based technology consultancies are capturing implementation margins for behavioral analytics calibration.
Germany
BaFin banking supervision requirements are accelerating DLP deployment across Frankfurt and Munich financial centers. The Federal Data Protection Authority has intensified GDPR Article 32 enforcement, mandating security of processing documentation. Stuttgart automotive suppliers are integrating cloud DLP with existing on-premises investments to protect engineering data.
France
CNIL supervisory fines have compelled Paris-headquartered multinationals to demonstrate algorithmic transparency for ML-enhanced classification engines. The EU AI Act adds documentation burdens for automated decision-making data flows. Lyon pharmaceutical clusters are prioritizing GxP-validated DLP deployments under EMA guidelines.
Sweden
Swedish government digitization programs are driving sovereign-certified procurement for citizen data protection. The Swedish Authority for Privacy Protection enforces strict data localization for public sector cloud migrations. Stockholm technology agencies require national security-cleared channels for DLP vendor selection.
Netherlands
Amsterdam data center operators are balancing Schrems II cross-border transfer requirements with elasticity demands. The Dutch Data Protection Authority has targeted inadequate data flow mapping in cloud migrations. Eindhoven semiconductor firms are deploying vendor-agnostic orchestration layers across multi-cloud architectures.
Europe Cloud DLP Market Competitive Landscape
Player mix skews toward platform ecosystems and specialized security vendors with ISO 27001 certification. The vendor landscape has collapsed around a handful of providers meeting enterprise and government contract thresholds. Two strategic archetypes dominate: hyperscale cloud platforms with native DLP tooling, and independent cybersecurity vendors with cross-platform orchestration capabilities. Competitive moves center on channel partner ecosystem expansion and outcome-based contract structures displacing perpetual licensing.
Within the platform ecosystem tier, Microsoft leverages its Azure presence across United Kingdom and Nordic public sectors. Palo Alto Networks competes through cloud-native integration capabilities, while Forcepoint occupies a position specializing in human-centric data protection for regulated European industries. These three exemplify the certification-driven consolidation reshaping procurement options for GDPR and EU AI Act compliance.
| Leading Market Players |
|---|
| Broadcom Inc |
| Check Point Software Technologies Ltd |
| Cisco Systems, Inc. |
| Forcepoint |
| Zscaler, Inc. |
| Microsoft |
| IBM Corporation |
| Palo Alto Networks, Inc. |
| Fortinet, Inc. |
| Others |
Value Network & Pricing Analysis
Azure hyperscaler economies in the United Kingdom and Germany compress unit economics for cloud-native DLP deployments while elevating price floors for sovereign-certified alternatives. This scale asymmetry concentrates procurement leverage among platform ecosystems and fragments margin pools for standalone vendors lacking ISO 27001 credentials.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 27001 and EU AI Act algorithmic documentation commanding 40-60% premiums over uncertified alternatives. Subscription SaaS-tiered models dominate enterprise procurement, though outcome-based contracts are displacing perpetual licenses among United Kingdom mid-market buyers. Pricing pressure stems from hyperscaler native tooling bundling, which erodes standalone vendor margins in public cloud configurations. SMEs exhibit highest price sensitivity, while government segments in Sweden and Norway accept premium pricing for sovereign-certified deployments.
Supply Chain Analysis
Implementation lead times for behavioral analytics calibration extend 8-14 weeks in French banking environments where false-positive tolerance is minimal. Software development concentrates in the United States, Israel, and Ireland, with policy engine training data sourced from European regulatory corpora. Single-source vulnerability runs through ML model training pipelines dependent on limited GDPR-compliant data repositories. Distribution runs through systems integrators with GDPR compliance expertise, particularly in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United Kingdom and German enterprises with dedicated CISO functions, compressing vendor margins and elevating certification requirements as table stakes. This procurement consolidation favors platform ecosystems over point solutions.
For Market Incumbents: Secure channel partner exclusivity arrangements with Nordic systems integrators possessing national security clearances, as Swedish and Norwegian government digitization accelerates sovereign-certified procurement. Invest in pre-built EU AI Act compliance templates for high-risk AI system registration, defending against emerging cloud-native entrants lacking regulatory documentation depth.
For New Entrants and Emerging Players: Lead with behavioral analytics specialization for EMA-compliant pharmaceutical workflows in Switzerland and the Netherlands, where GxP-validated DLP deployments face incumbent underservice. Target managed services delivery for United Kingdom mid-market enterprises lacking internal security operations centers, capturing recurring revenue through outcome-based contracts.
For Investors and Strategic Acquirers: Cloud-native specialists with ISO 27001 certification and established Azure co-sell status represent the most defensible acquisition profile, given hyperscaler ecosystem lock-in effects. Monitor GDPR enforcement velocity by France's CNIL and Germany's Federal Data Protection Authority as the primary inflection signal for DLP procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure ecosystem anchoring captures United Kingdom and Nordic public sector procurement mandates. |
| Acquisition of Specialist Firm | Behavioral analytics boutiques fill ML tuning capability gaps in French banking deployments. |
| Strategic Partnership | Systems integrator alliances capture implementation margins previously retained by software vendors. |
| Geographic Expansion | Swiss and Dutch life sciences clusters offer GxP-validated DLP white space beyond saturated financial services. |
| Product Launch | Pre-built EU AI Act compliance templates accelerate high-risk AI system registration for pharmaceutical buyers. |
Research Methodology
A standing panel of CISOs, cloud architects, GDPR compliance officers, and channel partner principals provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against SEC filings, hyperscaler capex disclosures, and national data protection authority enforcement databases. Bottom-up deployment estimates and top-down market sizing triangulated through cross-reference with EMA guidelines and EU AI Act implementation timelines.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment configurations, customer types, service tiers, and technology segments, with CAGRs derived from regression analysis of historical adoption curves and regulatory enforcement velocity. Forecast inputs incorporated Schrems II ruling impacts on cross-border data flows and ISO 27001 certification scarcity effects on vendor landscape concentration.
Underlying assumptions cover sustained GDPR enforcement intensity and EU AI Act implementation timelines, with deviation risk concentrated in regulatory delay or accelerated hyperscaler bundling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Global Data Exfiltration Market
Cybersecurity
Global Managed Detection and Response (MDR) Market
Cybersecurity
Portugal Cybersecurity Market
Cybersecurity
Managed SIEM Service Market
Cybersecurity
United States Virtualization Security Market
Cybersecurity
Cloud Encryption Gateways Market
Cybersecurity
Big Data Security Market
Cybersecurity
Cloud Access Security Broker Market
Cybersecurity
Advanced Malware Detection (AMD) Market
Cybersecurity
France Cybersecurity Market
Cybersecurity
Global Network Security Policy Management Market
Cybersecurity
V2X Cybersecurity Market
Cybersecurity
Global API Security Market
Cybersecurity
Middle East and Africa Cybersecurity Market
Cybersecurity
Cybersecure Vehicle Control Unit Gateway Systems Market
Cybersecurity
Secure Socket Layer (SSL) Certification Market