
 Next-Gen Firewall Market | 2026-2036
Next-Gen Firewall Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Gen Firewall Market Outlook
Multi-source vendor consolidation is pivoting toward integrated platform ecosystems as enterprises reduce point-product sprawl. Palo Alto Networks leverages its hardware-software convergence to anchor high-performance data center deployments. Fortinet competes through proprietary ASIC acceleration that sustains price-performance advantages at scale. Check Point Software Technologies specializes in unified threat management architectures that dominate enterprise accounts across regulated industries.
A next-generation firewall combines deep packet inspection, application awareness, and intrusion prevention within a unified policy engine, typically processing traffic at Layer 7 with throughput measured in gigabits per second to enforce granular access control across hybrid infrastructure. Cloud-based deployment now leads growth trajectories as organizations migrate security stacks to distributed edge environments, while on-premises installations retain dominance in latency-sensitive financial trading floors and classified government networks. Machine Learning and Artificial Intelligence segments command expanding R&D allocation as vendors automate threat correlation and reduce mean-time-to-detection.
FCC guidelines on communications infrastructure security, HIPAA requirements for healthcare data protection, and NIST zero-trust architecture mandates collectively reshape product certification roadmaps and procurement specifications across US federal and commercial buyers. The SEC's cybersecurity disclosure rules further tighten incident-response capabilities that firewall platforms must document. Stakeholders should monitor how regulatory fragmentation between federal agencies and state-level privacy statutes influences vendor consolidation strategies and platform interoperability investments.
Market Dynamics
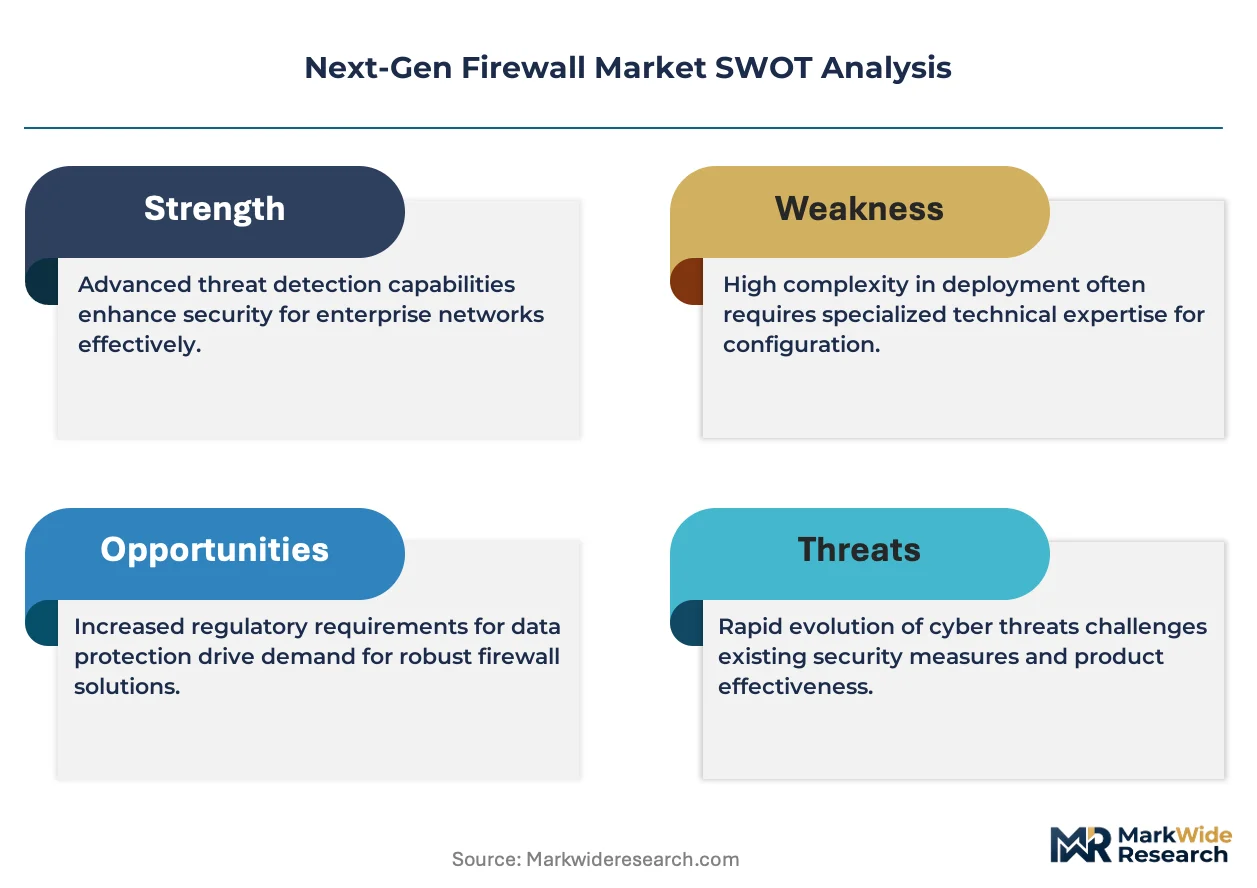
Zero-trust security mandates from federal agencies are compressing enterprise replacement cycles, forcing organizations to retire legacy perimeter defenses ahead of scheduled refresh timelines.
Growth Catalysts
- HIPAA enforcement:Healthcare providers face escalating penalties for data breaches, accelerating procurement of application-aware inspection engines that enforce granular access policies across electronic health record systems.
- Cloud workload migration:Distributed edge architectures require consistent policy enforcement across multi-cloud environments, pulling firewall functionality into software-defined perimeters.
- Artificial intelligence:Machine learning-powered threat correlation reduces false-positive rates and automates incident response, cutting mean-time-to-detection from hours to minutes.
Market Restraints
- Semiconductor supply concentration:Proprietary ASIC fabrication depends on concentrated foundry capacity in Taiwan, creating vulnerability in high-throughput hardware supply chains.
- Skilled analyst shortage:Layer 7 inspection and threat hunting require specialized security operations expertise that remains scarce across mid-market enterprises.
- Encryption complexity:TLS 1.3 and perfect forward secrecy protocols blind traditional deep packet inspection, forcing costly architectural redesigns.
Strategic Opportunities
- Operational technology convergence:Manufacturing and energy sectors need unified IT-OT security platforms that bridge enterprise and industrial control network segmentation.
- Managed security services:Channel partners are building recurring revenue streams by operating firewall-as-a-service offerings for resource-constrained organizations.
- SEC disclosure rules:Public companies must document incident-response capabilities, creating compliance-driven demand for automated reporting and audit trails.
Industry Challenges
- Certificate management at scale:Enterprises struggle to maintain visibility across thousands of encrypted connections without breaking application functionality.
- Policy sprawl remediation:Decades of accumulated firewall rules create technical debt that complicates cloud migration and zero-trust implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Gen Firewall Market |
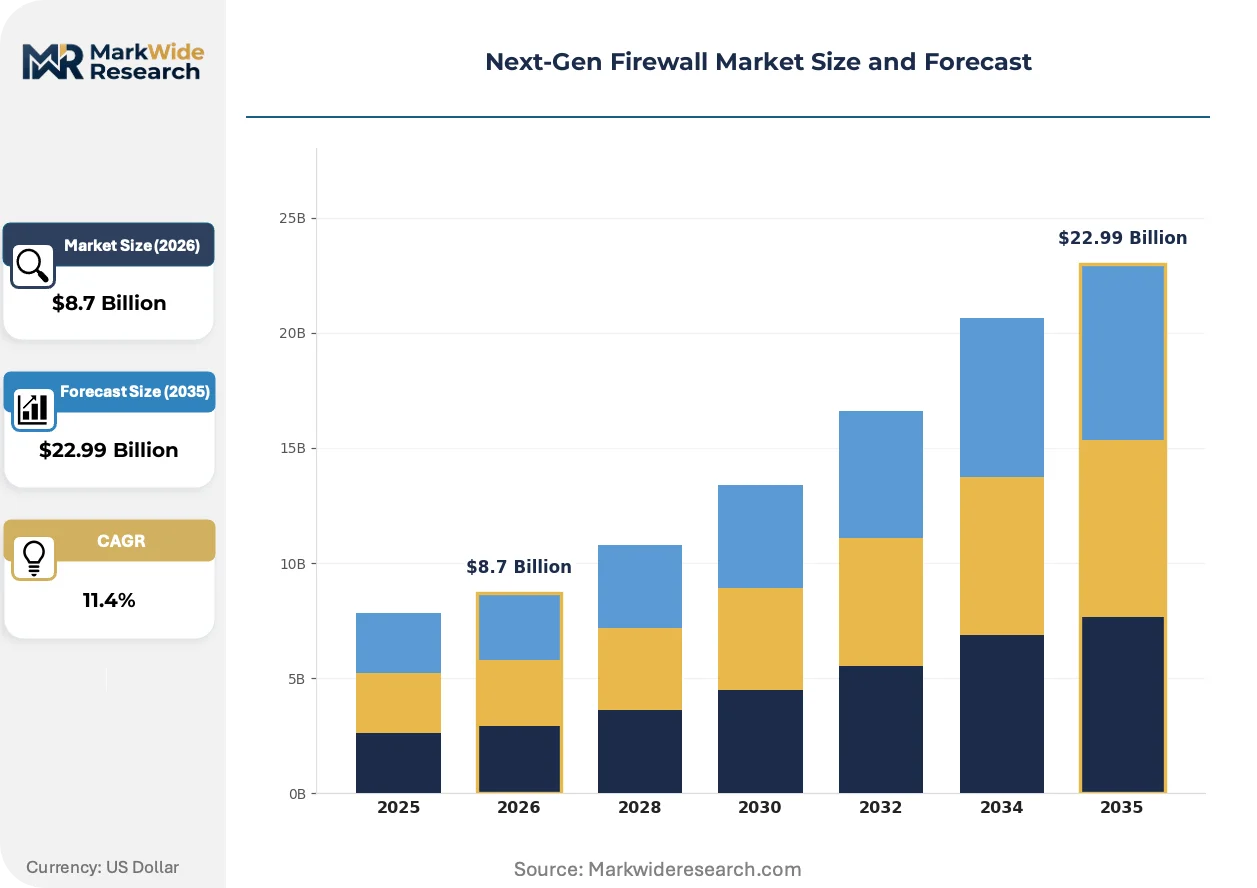
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, Managed Solution: Intrusion Prevention, Threat Intelligence, Application Control, Malware Protection End User: Healthcare, BFSI, Government, Education Technology: Machine Learning, Artificial Intelligence, Firewall as a Service, Sandboxing |
| Companies Covered | Check Point Software Technologies, Sophos, Palo Alto Networks, WatchGuard Technologies, SonicWall, Fortinet, Juniper Networks, Forcepoint, Cisco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Gen Firewall Market Strategic Shifts
Security architecture is fragmenting from centralized appliances toward distributed software agents, rewriting how organizations conceptualize network perimeters and policy enforcement points.
Cloud-native firewall-as-a-service architectures are overtaking hardware-centric deployments in enterprise planning cycles. Financial services firms and SaaS providers now prioritize API-driven policy orchestration over box-centric procurement. This shift is compressing vendor margins on physical appliances while expanding recurring software revenue pools.
NIST zero-trust architecture mandates are reshaping federal procurement specifications and commercial buyer expectations. Organizations must demonstrate continuous verification rather than implicit trust based on network location. Defense contractors and critical infrastructure operators face the most compressed compliance timelines.
Security buying committees now unbundle hardware, software, and managed services into separate procurement streams. Large enterprises negotiate direct platform licenses while outsourcing day-to-day operations to specialized service providers. This bifurcation is most pronounced in healthcare and retail verticals with limited in-house security engineering capacity.
Next-Gen Firewall Market Segmentation
Next-generation firewall procurement decisions hinge on infrastructure maturity, regulatory exposure, and operational technology convergence. Buyers segment requirements across deployment architecture, threat detection capability, industry-specific compliance, and automation sophistication.
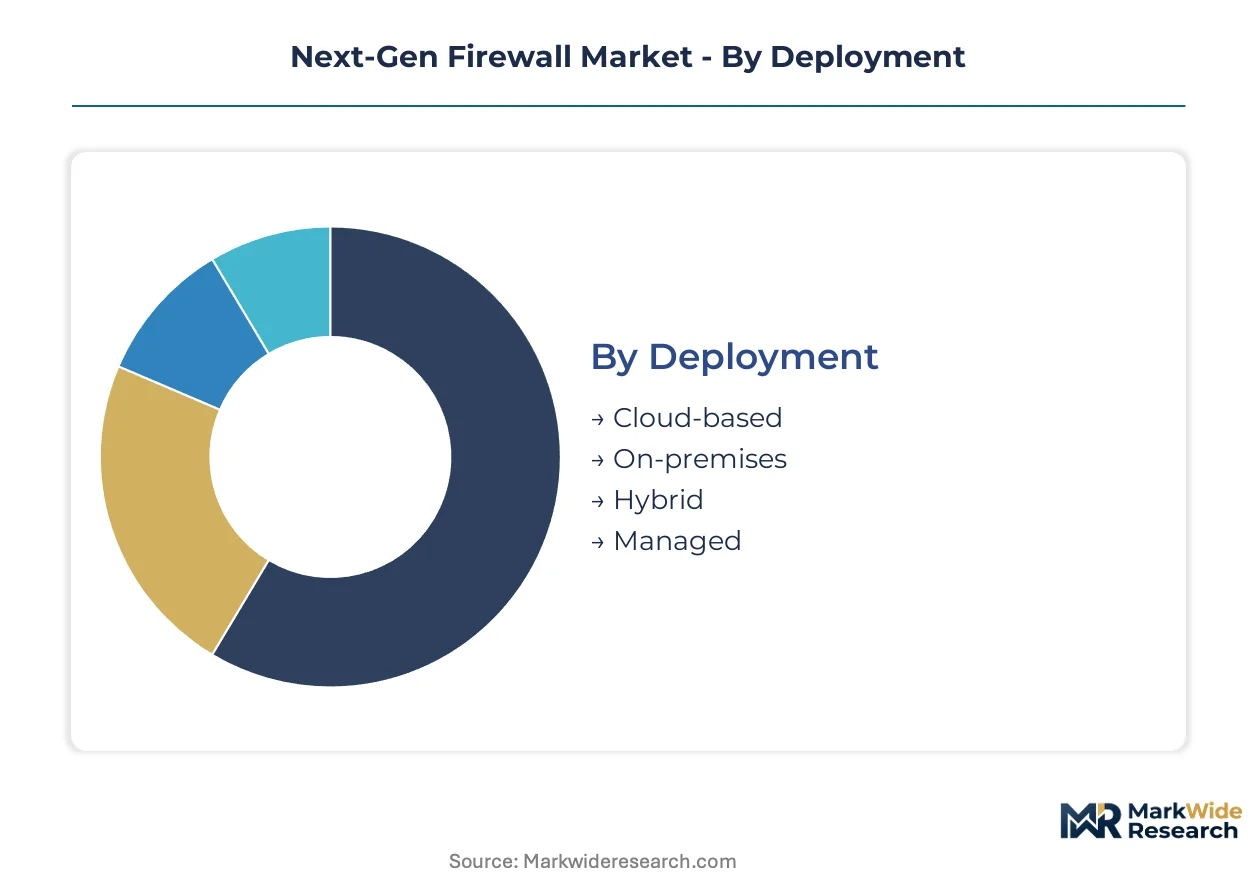
Deployment:
Capital intensity and latency tolerance drive deployment selection across enterprise security architectures.
- Cloud-based:Software-defined perimeters enforce consistent policies across AWS, Azure, and GCP workloads without hardware refresh cycles. Financial services firms in Singapore and SaaS providers in Ireland prioritize API-driven orchestration over physical appliances.
- On-premises:Dedicated appliances process traffic through proprietary ASICs at Layer 7 with sub-millisecond latency. Classified government networks in the United States and high-frequency trading floors in Frankfurt retain hardware dominance for air-gapped environments.
- Hybrid:Split-tunnel architectures route sensitive workloads through on-premises inspection while cloud-native traffic traverses virtualized enforcement points.
- Managed:Channel partners operate firewall-as-a-service offerings, absorbing certificate management and policy tuning for mid-market enterprises with limited security operations centers.
Volume sits with On-premises; growth tilts toward Cloud-based.
Solution:
Threat surface expansion is redirecting budget toward integrated detection engines over standalone prevention tools.
- Intrusion Prevention:Deep packet inspection engines analyze payload signatures against threat intelligence feeds at line rate. Manufacturing facilities in Germany deploy these systems to segment operational technology networks from enterprise IT.
- Threat Intelligence:Real-time indicator feeds from commercial providers and government sources automate blocklist updates. Critical infrastructure operators in Australia subscribe to sector-specific information sharing and analysis centers.
- Application Control:Layer 7 identification distinguishes sanctioned SaaS usage from shadow IT deployments.
- Malware Protection:File reputation scanning and behavioral analysis intercept executable payloads before delivery.
Procurement concentrates on Threat Intelligence; Application Control is climbing the fastest.
End User:
Regulatory penalty structures and data sensitivity determine security spending intensity across vertical markets.
- Healthcare:HIPAA enforcement actions exceeding $5 million per incident accelerate procurement of application-aware inspection for electronic health record systems. Hospital networks in Texas and California dominate North American demand.
- BFSI:PCI-DSS compliance and real-time transaction protection require sub-100-microsecond inspection latency. Payment processors in the Netherlands and retail banks in Brazil anchor procurement volumes.
- Government:NIST zero-trust mandates compress replacement cycles for federal agencies and defense contractors.
- Education:K-12 districts and research universities balance open access policies against ransomware protection.
Healthcare captures the steepest budget expansion; BFSI maintains the largest installed base.
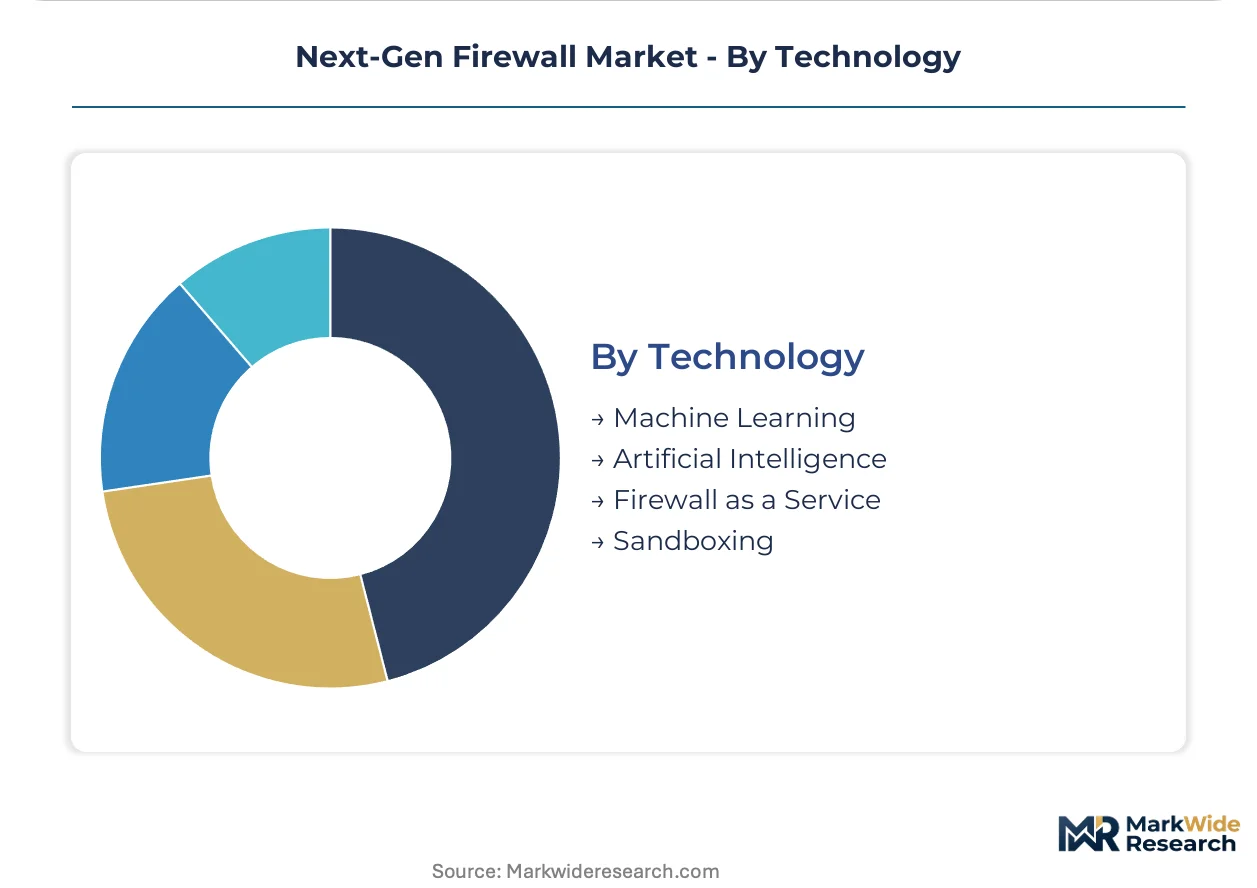
Technology:
Automation sophistication separates premium platforms from commodity inspection tools in vendor evaluations.
- Machine Learning:Behavioral baselines identify anomalous traffic patterns without signature dependencies. Telecommunications carriers in South Korea deploy these engines for DDoS detection at peering points.
- Artificial Intelligence:Natural language processing of threat reports accelerates indicator extraction and policy recommendation. Managed security providers in the United Kingdom leverage AI to reduce analyst alert fatigue.
- Firewall as a Service:Cloud-native delivery eliminates hardware procurement and enables consumption-based pricing.
- Sandboxing:Detonation chambers execute suspicious files in isolated environments before network release.
Artificial Intelligence commands premium pricing; Firewall as a Service is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for next-generation firewall solutions concentrates in the United States, where federal zero-trust mandates and critical infrastructure protection requirements accelerate enterprise replacement cycles ahead of scheduled refresh timelines.
United States
Federal agencies and defense contractors drive procurement volumes under NIST zero-trust architecture mandates and FCC communications infrastructure security guidelines. The SEC's cybersecurity disclosure rules tighten incident-response documentation requirements for public companies. Hospital networks in Texas and California anchor healthcare sector demand as HIPAA enforcement penalties exceed five million dollars per incident.
Germany
Manufacturing facilities and operational technology environments require unified IT-OT security platforms that bridge enterprise and industrial control network segmentation. The country's national cybersecurity regulator enforces critical infrastructure protection standards across energy and automotive sectors. Frankfurt's high-frequency trading floors retain on-premises hardware dominance for sub-millisecond latency requirements.
United Kingdom
Managed security providers leverage artificial intelligence to reduce analyst alert fatigue across resource-constrained mid-market enterprises. GDPR compliance and sector-specific information sharing frameworks reshape procurement specifications for financial services firms in London. Telecommunications carriers deploy machine learning behavioral baselines for DDoS detection at peering points.
Singapore
Financial services firms prioritize API-driven policy orchestration over physical appliances as cloud-native architectures dominate enterprise planning cycles. The country's central bank and financial regulator enforce stringent technology risk management guidelines for banking institutions. SaaS providers and payment processors anchor procurement demand across Southeast Asian regional headquarters.
Australia
Critical infrastructure operators subscribe to sector-specific information sharing and analysis centers for real-time threat intelligence feeds. The country's national cybersecurity center mandates security frameworks for energy, water, and transportation systems. Sydney and Melbourne host concentrated demand from healthcare networks and government agencies modernizing perimeter defenses.
Next-Gen Firewall Market Competitive Environment
Platform consolidation dominates the current landscape as vendors absorb point-product capabilities into integrated ecosystems. The vendor base organizes around three strategic archetypes: hardware-software convergence specialists leveraging proprietary silicon acceleration, unified threat management platforms dominating regulated enterprise accounts, and cloud-native providers delivering firewall-as-a-service consumption models. M&A activity and strategic technology licensing partnerships represent the dominant competitive moves as incumbents acquire machine learning capabilities and cloud orchestration assets.
Within the integrated platform tier, Palo Alto Networks and Fortinet exemplify hardware-software convergence strategies that anchor high-performance data center deployments. Check Point Software Technologies occupies a position within unified threat management architectures that serve regulated industries across healthcare and government verticals. These three companies represent distinct strategic postures: proprietary ASIC acceleration at scale, converged infrastructure platforms, and compliance-centric enterprise penetration.
| Leading Market Players |
|---|
| Check Point Software Technologies |
| Sophos |
| Palo Alto Networks |
| WatchGuard Technologies |
| SonicWall |
| Fortinet |
| Juniper Networks |
| Forcepoint |
| Cisco |
| Others |
Value Chain & Pricing Dynamics
Federal zero-trust procurement mandates compressing enterprise replacement cycles are forcing firewall vendors to absorb certification costs and accelerate R&D timelines, compressing margins on hardware appliances while expanding recurring software revenue pools to offset upfront investment recovery.
Pricing Analysis
Volume concentrates in hardware appliances with compressed margins, while margin expansion sits with cloud-native software subscriptions and managed security services. Three-tier pricing structure across premium, standard, and economy levels reflects throughput capacity, AI-powered threat detection sophistication, and bundled managed services. Cost compression in mid-market hardware tiers is intensifying because proprietary ASIC fabrication depends on concentrated foundry capacity. Healthcare networks with HIPAA exposure show least price sensitivity; resource-constrained K-12 districts exhibit highest.
Supply Chain Analysis
Dual-sourcing requirements from defense contractors and critical infrastructure operators mandate multi-supplier qualification for proprietary ASICs and encryption processors. Manufacturing concentrates in Taiwan, South Korea, and the United States for high-performance silicon. Supply chains draw from specialized foundry capacity, rare earth materials for magnetic components, and memory modules. Single-source vulnerability in Taiwanese foundry capacity creates structural risk. Distribution runs through authorized channel partners and direct enterprise sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where proprietary silicon design and captive threat intelligence feeds represent the decisive upstream levers separating premium platforms from commodity inspection tools.
For Market Incumbents: Hedge against cloud-native displacement by accelerating hardware-software convergence roadmaps and acquiring machine-learning threat correlation assets. Fortify positions through backward integration into custom ASIC design rather than merchant silicon dependence. Channel control through managed security service partnerships defends against pure-play SaaS entrants eroding appliance attach rates.
For New Entrants and Emerging Players: AI-powered certificate management automation offers a technology-first wedge into mid-market enterprises drowning in TLS 1.3 encryption complexity. Manufacturing operational technology convergence presents the most penetrable white-space, with unified IT-OT platforms underserved by incumbent architectures. Go-to-market through industrial system integrators bypasses direct competition with established channel relationships.
For Investors and Strategic Acquirers: The window for entry favors cloud-native firewall-as-a-service specialists with API-first architectures and consumption-based pricing models. Long-term viability hinges on recurring revenue durability and platform integration depth rather than point-product differentiation. Watch NIST zero-trust implementation timelines across federal contractors as the inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary ASIC Development | Custom silicon acceleration sustains price-performance advantages at scale against merchant-chip competitors. |
| Cloud-Native Platform Migration | API-driven policy orchestration captures financial services and SaaS provider procurement shifting from appliances. |
| Managed Security Service Expansion | Channel partners absorb operational burden for resource-constrained healthcare and retail verticals. |
| Threat Intelligence Feed Integration | Real-time indicator automation from government ISACs differentiates platforms in critical infrastructure verticals. |
| IT-OT Convergence Platform Launch | Unified segmentation bridges enterprise and industrial control networks for manufacturing and energy buyers. |
Study Parameters
Multi-period observation of federal procurement timelines, HIPAA enforcement patterns, and cloud workload migration rates anchored the trend analysis, supplemented by interviews with CISOs at hospital networks, security architects at financial services firms, federal procurement officers, channel partners, and managed security service operators. Secondary validation drew from NIST publications, FCC infrastructure security guidelines, SEC cybersecurity disclosure filings, and hyperscaler security stack disclosures. Bottom-up enterprise spending estimates and top-down vendor revenue analysis were triangulated.
Input-output matrix modeling connected deployment architecture shifts, regulatory compliance deadlines, and technology adoption curves to firewall procurement volumes across the projection horizon. Segmentation dimensions included deployment model, solution type, end-user vertical, and automation sophistication tier. CAGRs were derived from regression analysis against historical replacement cycles and policy-mandated acceleration factors. Forecast inputs incorporated semiconductor supply constraints and zero-trust implementation timelines.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwanese foundry capacity, breakthrough quantum encryption protocols, and unanticipated regulatory fragmentation between federal agencies. Forecasts reflect documented assumptions about compliance timeline adherence and supply chain stability. Deviation in NIST mandate enforcement intensity or ASIC fabrication capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Managed SIEM Service Market
Cybersecurity
Singapore Cybersecurity Market
Cybersecurity
New Zealand Cybersecurity Market
Cybersecurity
Global Network Forensics Market
Cybersecurity
Europe Cybersecurity Market
Cybersecurity
Mexico Cybersecurity Market
Cybersecurity
Global Cyber Threat Intelligence Market
Cybersecurity
SSL VPN Market
Cybersecurity
Global Cyber Security in Healthcare Market
Cybersecurity
Africa Cybersecurity Market
Cybersecurity
Network Traffic Analysis Solutions Market
Cybersecurity
Global Distributed Denial of Service (Ddos) Protection Market
Cybersecurity
Global SSH Terminal Market
Cybersecurity
Cyber Security Consulting Market
Cybersecurity
Netherlands Cybersecurity Market
Cybersecurity
Norway Cybersecurity Market