
 Global Digital Forensic Laboratory As a Service Market | 2026-2036
Global Digital Forensic Laboratory As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Forensic Laboratory As a Service Market Foresight
Platform licensing revenue is reshaping competitive economics in forensic services. CACI International Inc leverages its federal contracting depth to anchor long-term laboratory service agreements with US intelligence and defense agencies. SalvationDATA competes through specialized hardware-software bundles for digital evidence extraction in Asian markets. J.S. Held LLC differentiates by extending forensic expertise into legal advisory and expert testimony workflows.
Digital Forensic Laboratory As a Service delivers cloud-accessible forensic investigation infrastructure, combining remote evidence processing with ISO 17025-aligned chain-of-custody protocols to support criminal, civil, and corporate investigations. The primary commercial purpose is eliminating capital-intensive laboratory buildouts while ensuring admissible evidence handling. Forensic Analysis services within the Service Type dimension dominate margin pools due to specialized examiner labor and tool licensing premiums. Hybrid Cloud deployment is expanding fastest as organizations balance evidence sovereignty requirements with elastic compute needs for large-scale data ingestion. AI & Machine Learning technology integration concentrates demand among financial investigators and cybersecurity firms seeking pattern recognition across multimillion-record datasets.
FBI digital evidence protocols, EU GDPR cross-border data transfer rules, and ISO 27001 information security standards collectively shape service architecture, data residency requirements, and client certification prerequisites across jurisdictions. The UK's National Police Chiefs' Council digital forensics standards and Australia's ASD Essential Eight further fragment compliance obligations for multinational providers. Stakeholders must monitor evolving encryption standards and quantum-resistant authentication mandates that will determine next-generation laboratory access and evidence integrity architectures.
Market Dynamics
Platform licensing revenue is compressing traditional hourly billing models while hybrid cloud architectures force providers to reconcile evidence sovereignty mandates with elastic compute economics. The collision between GDPR cross-border transfer rules and FBI digital evidence protocols is fragmenting service architectures across jurisdictions.
Growth Catalysts
- EU AI Act compliance mandates:European forensic providers are embedding algorithmic transparency modules into automated analysis tools to satisfy audit requirements for machine-generated evidence.
- Financial crime investigation units:Pattern recognition demand across multimillion-record datasets is pulling AI-integrated laboratory services into banking and insurance sectors.
- US federal cybersecurity directives:CISA binding operational directives are accelerating cloud-based forensic procurement across defense and intelligence agency supply chains.
Market Restraints
- Specialized examiner labor scarcity:ISO 17025-certified forensic analysts command premium compensation that compresses service margins during scale-up phases.
- Encryption standard evolution:Quantum-resistant authentication mandates under development will force costly re-architecture of laboratory access and evidence integrity systems.
- Data residency fragmentation:Australia's ASD Essential Eight and UK National Police Chiefs' Council standards create incompatible infrastructure requirements for multinational providers.
Strategic Opportunities
- Underpenetrated Asian markets:Hardware-software bundle penetration remains low in Southeast Asian law enforcement agencies lacking capital for laboratory buildouts.
- Legal advisory convergence:Expert testimony workflow integration creates attach-rate expansion for providers extending beyond technical analysis into litigation support.
- ISO 27001 certification arbitrage:Information security standard gaps between corporate and public sector buyers create differentiation openings for dual-certified providers.
Industry Challenges
- Chain-of-custody automation:Maintaining admissible evidence protocols during cloud-native processing requires re-engineering legacy audit trail systems.
- Tool licensing complexity:Proprietary forensic software stacks create vendor lock-in that comples multi-provider laboratory service integration.
- Skill certification throughput:ISO 17025 examiner qualification timelines lag behind demand expansion, constraining service capacity growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Forensic Laboratory As a Service Market |
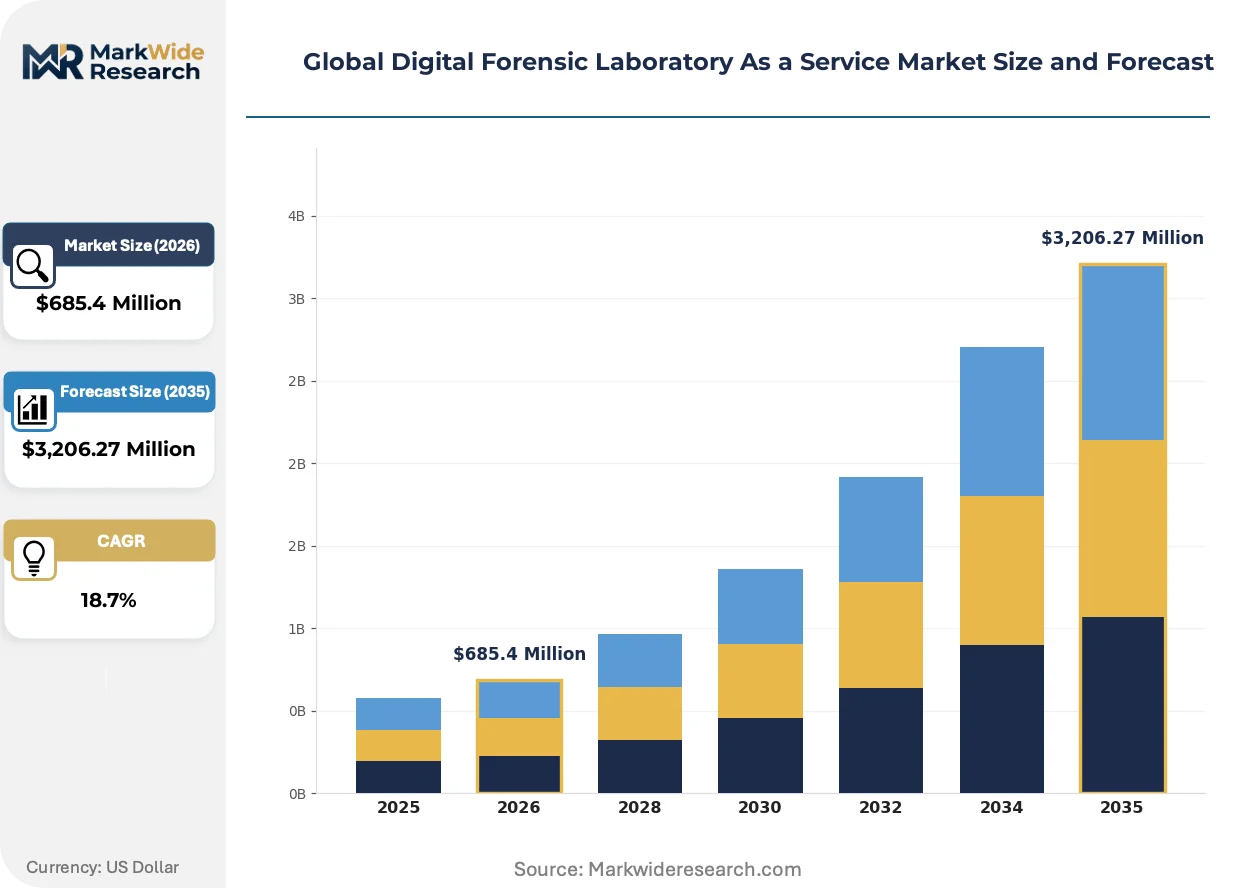
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $3,206.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Acquisition, Evidence Preservation, Forensic Analysis, Reporting, Chain of Custody Management Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-premises, Edge Computing End User Industry: Law Enforcement Agencies, Legal Firms, Cybersecurity Firms, Financial Investigators, Insurance Companies Technology Used: AI & Machine Learning, Blockchain, Big Data Analytics, Cloud Computing, Digital Imaging Tools |
| Companies Covered | CACI International Inc, SalvationDATA, Ten Intelligence Limited, ESF Labs Limited, J.S. Held LLC, The HSI Forensic Laboratory, Computer Forensic Lab, IFF Lab, ADF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Forensic Laboratory As a Service Market Shifts & Advancements
Automated evidence processing pipelines are displacing manual examiner workflows while regulatory pressure on algorithmic accountability intensifies. Three converging developments are restructuring competitive requirements.
Containerized forensic analysis environments are rendering obsolete traditional physical laboratory configurations. Cybersecurity firms and financial investigators are adopting these portable, cloud-native stacks within eighteen-month procurement cycles. The shift is compressing capital requirements for market entry while elevating software engineering capabilities above bench forensics expertise.
GDPR Article 49 derogation frameworks are tightening cross-border evidence transfer permissions for EU-based laboratory services. Providers are responding by establishing jurisdictional data processing nodes that fragment operational scale economies. US federal agencies and multinational corporations now face elevated compliance overhead when commissioning pan-European investigations.
Subscription-based platform access is displacing per-case service contracting among corporate legal departments. General counsel offices in the United States and United Kingdom are consolidating forensic spend under annual laboratory service agreements with guaranteed capacity allocation. The model transfers utilization risk to providers while locking in minimum revenue commitments from buyers.
Global Digital Forensic Laboratory As a Service Market Segmentation
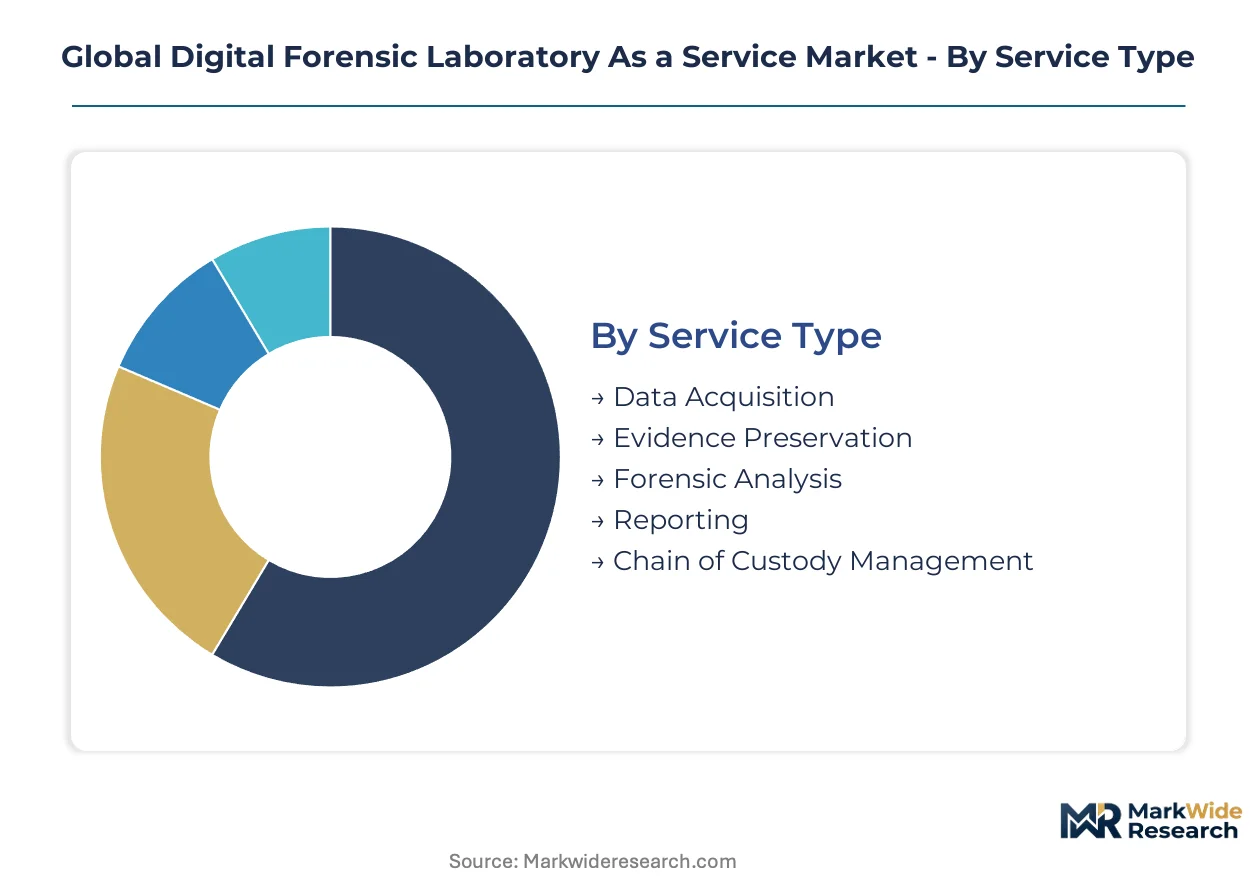
Segmentation in the Digital Forensic Laboratory As a Service market determines procurement cycles, margin structures, and compliance architectures. Service type and deployment model choices directly constrain evidence admissibility and chain-of-custody validity across jurisdictions.
Service Type:
Forensic Analysis commands the longest procurement cycles due to ISO 17025 examiner certification requirements, while Data Acquisition turns over fastest as automated tools displace manual workflows.
- Forensic Analysis:Specialized examination of digital artifacts using licensed software tools and certified examiner labor. Financial investigators and cybersecurity firms concentrate demand here for pattern recognition across multimillion-record datasets, absorbing premium pricing for admissible evidence handling.
- Chain of Custody Management:Audit trail automation ensuring evidentiary integrity from seizure through courtroom presentation. Law enforcement agencies in the United States and United Kingdom drive adoption as GDPR and FBI protocol fragmentation elevates compliance complexity.
- Data Acquisition:Remote or on-site evidence collection with write-blocking and hashing protocols.
- Evidence Preservation:Secure storage maintaining forensic integrity against tampering or degradation.
- Reporting:Structured documentation meeting jurisdictional disclosure and expert testimony standards.
Forensic Analysis dominates installed base. Chain of Custody Management is where expansion concentrates.
Deployment Model:
Cost tier stratification separates capital-intensive On-premises builds from elastic consumption models, with Hybrid Cloud occupying the middle tier balancing sovereignty against scalability.
- Hybrid Cloud:Combines private infrastructure for sensitive evidence processing with public cloud burst capacity for large-scale ingestion. Organizations across Germany, France, and Australia adopt this architecture to satisfy ASD Essential Eight and EU GDPR data residency mandates without sacrificing computational elasticity.
- Private Cloud:Dedicated tenant environments with single-organization isolation and custom security controls. Defense and intelligence agencies in the United States mandate this deployment for classified or controlled unclassified information, accepting higher unit economics for air-gapped assurance.
- Public Cloud:Multi-tenant shared infrastructure with consumption-based pricing.
- On-premises:Physical laboratory equipment maintained within client facilities.
- Edge Computing:Distributed processing nodes for field-deployed or latency-constrained investigations.
Private Cloud anchors high-value contracts. Hybrid Cloud is climbing the fastest as compliance overhead reshapes procurement priorities.
End User Industry:
Application intensity varies sharply: Law Enforcement Agencies require full protocol compliance, while Financial Investigators prioritize throughput velocity over evidentiary formality.
- Law Enforcement Agencies:Police departments and federal investigators requiring courtroom-admissible evidence handling with complete chain-of-custody documentation. Agencies across the United Kingdom, United States, and Australia drive standardization as the UK's National Police Chiefs' Council and FBI protocols set procurement specifications.
- Financial Investigators:Banking and insurance sector units tracing transaction patterns across complex datasets. These users concentrate in New York, London, and Singapore, pulling AI-integrated laboratory services for anti-money laundering and fraud detection workflows.
- Legal Firms:Corporate and litigation practices commissioning discovery and expert testimony support.
- Cybersecurity Firms:Incident response providers requiring rapid evidence processing for breach attribution.
- Insurance Companies:Claims investigation units verifying digital evidence for policy disputes.
Law Enforcement Agencies dominate installed base. Financial Investigators represent the steepest expansion trajectory.
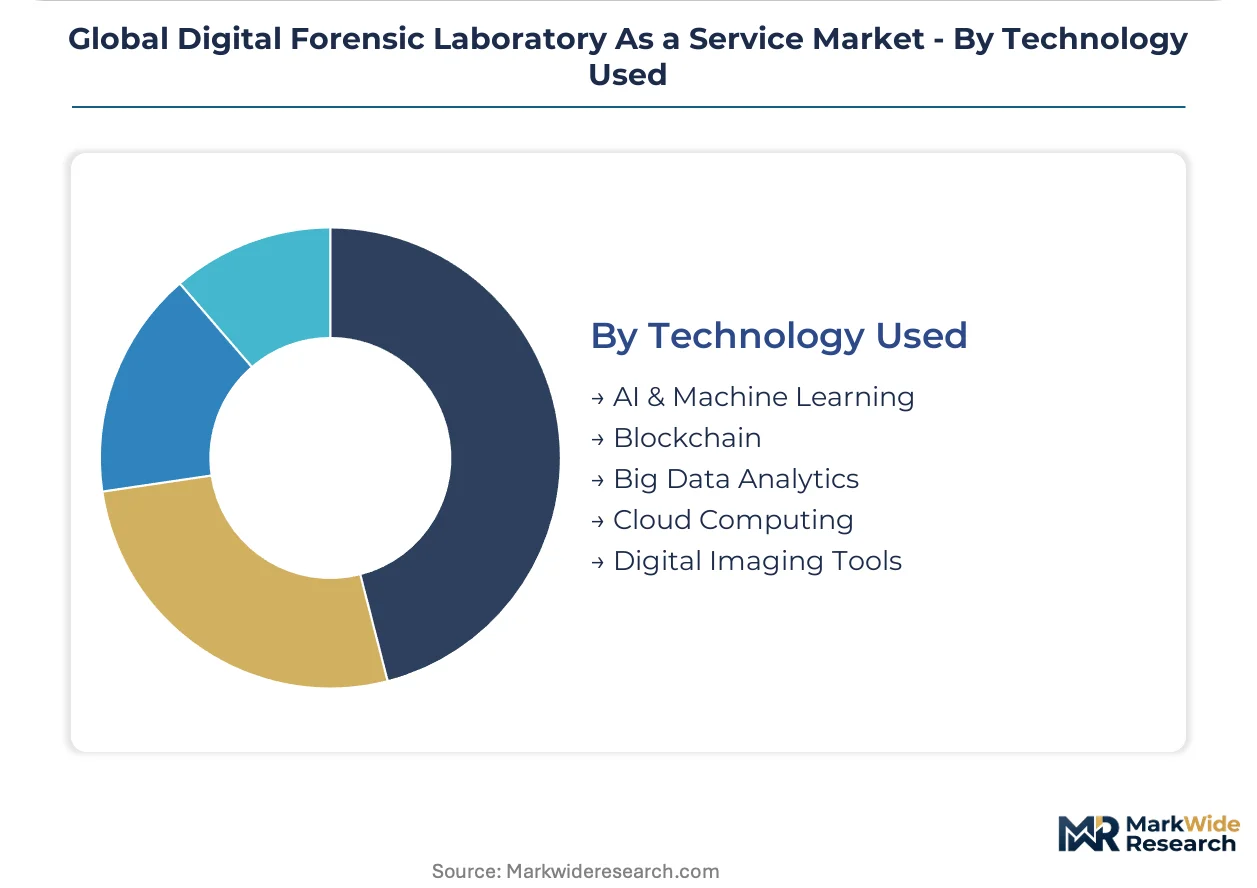
Technology Used:
Maturity gradients separate established Cloud Computing infrastructure from emerging Blockchain integrity mechanisms, with AI & Machine Learning occupying the experimental-to-production transition zone.
- AI & Machine Learning:Automated pattern recognition and anomaly detection across unstructured digital evidence. The EU AI Act is mandating algorithmic transparency modules for machine-generated evidence, concentrating development investment among European providers serving cross-border investigations.
- Cloud Computing:Elastic compute and storage infrastructure enabling remote laboratory access. This technology underpins service delivery economics across all deployment models, with ISO 27001 certification now table stakes for corporate and public sector procurement.
- Blockchain:Distributed ledger integrity verification for tamper-evident audit trails.
- Big Data Analytics:Scalable processing frameworks for petabyte-scale evidence repositories.
- Digital Imaging Tools:Forensic photography and video enhancement for multimedia evidence.
Cloud Computing dominates installed base. AI & Machine Learning is gaining share fastest as regulatory pressure intensifies on automated analysis accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provider infrastructure clusters in the United States, Germany, United Kingdom, Australia, and Singapore, where regulatory fragmentation around evidence handling standards creates localized service architectures.
United States
Federal defense and intelligence agencies drive procurement volume through CISA binding operational directives mandating cloud-based forensic capabilities. FBI digital evidence protocols set chain-of-custody standards that shape service specifications across North American contracts. Washington DC and Northern Virginia host concentrated provider operations serving federal cybersecurity supply chains.
Germany
EU AI Act compliance mandates are forcing algorithmic transparency modules into automated forensic tools used by banking and insurance investigators. GDPR cross-border data transfer rules under Article 49 derogation frameworks constrain pan-European service delivery. Frankfurt's financial services cluster pulls specialized laboratory capacity for anti-money laundering pattern recognition.
United Kingdom
National Police Chiefs' Council digital forensics standards create procurement specifications distinct from EU and US frameworks. Law enforcement agencies balance evidence sovereignty requirements against cloud elasticity needs in hybrid architectures. London's legal and financial services concentration drives demand for expert testimony-integrated laboratory workflows.
Australia
ASD Essential Eight cybersecurity standards fragment infrastructure requirements for multinational providers serving Asia-Pacific investigations. Federal and state police agencies expand cloud-forensic adoption to handle surging digital evidence volumes from cybercrime caseloads. Sydney and Melbourne anchor provider operations targeting government and corporate security buyers.
Singapore
Financial investigators in banking and insurance sectors pull AI-integrated laboratory services for fraud detection across multimillion-record transaction datasets. The country's national cybersecurity regulator enforces information security standards that elevate certification requirements for service procurement. Singapore's position as regional financial hub concentrates demand from Southeast Asian law enforcement agencies lacking capital for laboratory buildouts.
Global Digital Forensic Laboratory As a Service Market Competitive Landscape
Federal contractors and specialized forensic boutiques split the market along capability depth versus geographic breadth lines. Three strategic archetypes dominate: intelligence-agency-aligned systems integrators, hardware-software bundle specialists, and litigation-support-extended advisory firms. Competitive moves concentrate on long-term service agreement anchoring and expert testimony workflow integration.
Among US-based federal contractors, CACI International Inc exemplifies the intelligence-agency-aligned archetype through its contracting depth with defense and security services. J.S. Held LLC occupies the litigation-support-extended position, extending forensic expertise into legal advisory and expert testimony workflows. SalvationDATA represents the hardware-software bundle specialist model, targeting markets where capital constraints prevent laboratory buildouts.
| Leading Market Players |
|---|
| CACI International Inc |
| SalvationDATA |
| Ten Intelligence Limited |
| ESF Labs Limited |
| J.S. Held LLC |
| The HSI Forensic Laboratory |
| Computer Forensic Lab |
| IFF Lab |
| ADF |
| Others |
Supply & Pricing Matrix
Washington DC and Northern Virginia anchor concentrated provider operations serving federal cybersecurity supply chains, with capacity scarcity among ISO 17025-certified examiners translating directly into premium pricing power for specialized forensic analysis services. This geographic clustering creates asymmetric bargaining leverage where defense and intelligence agency procurement absorbs elevated unit economics that corporate legal departments resist.
Pricing Analysis
FBI digital evidence protocols dictate the pricing tier structure across North American contracts, separating courtroom-admissible forensic analysis from commoditized data acquisition. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 17025 certification grade, examiner specialization depth, and chain-of-custody automation integration. Cost compression in standard-tier data acquisition is intensifying because automated tools displace manual examiner workflows. Corporate legal departments exhibit highest price sensitivity, while defense agencies accept premium positioning for air-gapped private cloud assurance.
Supply Chain Analysis
Proprietary forensic software stacks from the United States, United Kingdom, and Germany feed the upstream technology layer, with licensed examiner labor and ISO 17025 certification infrastructure comprising critical service inputs. Cloud computing infrastructure draws from hyperscale providers concentrated in Northern Virginia, Frankfurt, and Sydney, creating single-source vulnerability for evidence processing nodes. Distribution runs through long-term service agreements with guaranteed capacity allocation rather than transactional per-case contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates formidable switching costs. ISO 17025 certification timelines and FBI protocol compliance requirements lock in incumbent relationships while constraining new entrant scale.
For Market Incumbents: Pre-empt containerized forensic environment commoditization by embedding algorithmic transparency modules ahead of EU AI Act enforcement waves. Anchor long-term laboratory service agreements with US intelligence and defense agencies through CISA binding operational directive alignment. Extend forensic expertise into expert testimony workflows to capture litigation support attach-rate expansion before specialized boutiques consolidate this adjacency. For New Entrants and Emerging Players: Establish a beachhead in Southeast Asian law enforcement agencies lacking capital for laboratory buildouts, where hardware-software bundle penetration remains underdeveloped. Target financial investigators in Singapore and London seeking AI-integrated pattern recognition across multimillion-record datasets. Pursue ISO 27001 certification arbitrage to differentiate against public sector providers lacking dual corporate-public credentials. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors litigation-support-extended advisory firms with embedded expert testimony capabilities over pure-play technology vendors. Long-term viability hinges on regulatory compliance architecture durability across fragmented jurisdictional standards. Acquisition target archetype: regional specialists with ISO 17025 examiner benches and established law enforcement agency relationships. The signal to watch is EU AI Act audit requirement implementation velocity as a demand inflection indicator for algorithmic transparency modules.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Containerized forensic environments displace physical laboratory configurations within eighteen-month procurement cycles. |
| Regulatory Compliance Investment | EU AI Act algorithmic transparency modules create differentiation for European providers serving cross-border investigations. |
| Geographic Expansion | Jurisdictional data processing nodes in Germany and Australia satisfy GDPR and ASD Essential Eight residency mandates. |
| Strategic Partnership | Long-term service agreements with guaranteed capacity allocation transfer utilization risk while locking minimum revenue. |
| Acquisition of Specialist Firm | Expert testimony workflow integration extends forensic providers into litigation support with higher margin profiles. |
Research Methodology
Cross-validation between primary interviews with forensic laboratory directors, CISOs at financial institutions, federal procurement officers, and legal technology heads anchors the qualitative findings against secondary validation from CISA binding operational directives, FBI digital evidence protocol documentation, EU AI Act regulatory filings, and ISO 17025 certification body records. Bottom-up service provider capacity modeling triangulates against top-down federal cybersecurity spend allocation analysis.
Calibration against historical procurement cycle data and examiner certification throughput rates shapes the analytical framework across the analysis window. Segmentation dimensions modeled include service type, deployment model, end user industry, and technology integration intensity. CAGRs were derived from elasticity-adjusted demand curves incorporating AI-integrated laboratory service adoption velocity and cloud-native forensic environment displacement rates.
Stress conditions across encryption standard evolution timelines, quantum-resistant authentication mandate implementation, and examiner labor supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory fragmentation persistence and jurisdictional data residency requirement proliferation. Cross-checking against federal procurement database award patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Global Cyber Security in Healthcare Market
Cybersecurity
IT and Telecom Cyber Security Market
Cybersecurity
Network Sandboxing Market
Cybersecurity
Europe Cybersecurity Market
Cybersecurity
Data-Centric Security Market
Cybersecurity
Asia Pacific IoT Security Market
Cybersecurity
Next-Gen Firewall Market
Cybersecurity
Enterprise Firewall Market
Cybersecurity
Micro Segmentation Technology Market
Cybersecurity
Industrial Cybersecurity Market
Cybersecurity
LAMEA Deception Technology Market
Cybersecurity
Advanced Malware Detection (AMD) Market
Cybersecurity
Cyber Deception Market
Cybersecurity
Austria Cybersecurity Market
Cybersecurity
Poland Cybersecurity Market
Cybersecurity
Australia Cybersecurity Market