
 Homomorphic Encryption Market | 2026-2036
Homomorphic Encryption Market Size, Share, and Industry Trends Forecast 2026-2036
Homomorphic Encryption Market Analysis
The EU AI Act is decoupling algorithmic transparency requirements from data minimization mandates, forcing cloud providers to adopt privacy-enhancing computation architectures. IBM Corporation leverages its lattice-based cryptography portfolio to anchor enterprise trust in regulated industries. Microsoft Corporation competes through Azure confidential computing integration, while Duality Technologies specializes in practical fully homomorphic encryption implementations for financial risk modeling.
Homomorphic encryption permits computation on ciphertext without decryption, typically operating over polynomial rings or integer vectors with noise management thresholds to preserve result accuracy. Its primary commercial purpose is enabling secure outsourced computation where data owners retain cryptographic control while third parties perform analytics. Cloud-based deployment leads among segments due to enterprise migration of sensitive workloads, though edge computing configurations are expanding fastest in latency-constrained IoT analytics. Financial services dominates application revenue, yet secure data analysis for cross-border research collaborations represents the emerging margin pool where partially homomorphic schemes currently suffice.
FDA guidelines on multi-party clinical analytics and HIPAA's business associate provisions are shaping healthcare provider procurement specifications for encrypted computation platforms. In Europe, EDPB guidance on supplementary measures for international data transfers and the EU Cybersecurity Act certification framework are creating compliance-driven demand for formally verified implementations. Stakeholders must monitor NIST post-quantum standardization timelines and their interaction with existing homomorphic schemes to determine migration investments before algorithmic obsolescence risk materializes.
Market Dynamics
Post-quantum cryptographic standardization by NIST is forcing enterprise infrastructure teams to evaluate lattice-based schemes against existing partially homomorphic implementations before hardware refresh cycles commit them to obsolete algorithms.
Growth Catalysts
- EU AI Act compliance mandates:European cloud providers must implement privacy-enhancing computation for high-risk AI systems, creating procurement specifications that favor homomorphic encryption architectures.
- Automotive supply chain confidentiality:German industrial engineering firms are piloting encrypted analytics for multi-party quality assurance without exposing proprietary design parameters to competitors.
- FDA multi-party clinical analytics guidance:Healthcare data intermediaries require encrypted computation platforms to satisfy HIPAA business associate provisions while enabling cross-institutional research.
Market Restraints
- Computational overhead:Fully homomorphic encryption operations consume 100-1000x more processing cycles than plaintext equivalents, constraining deployment to batch analytics rather than real-time transactions.
- Lattice parameter standardization lag:NIST's ongoing post-quantum competition leaves security level selections vulnerable to future algorithmic obsolescence, freezing capital allocation.
- Specialized talent scarcity:Cryptographic engineering expertise concentrates at academic institutions and national laboratories, limiting commercial implementation velocity.
Strategic Opportunities
- Edge computing latency constraints:IoT analytics in manufacturing and autonomous systems require encrypted computation at the network periphery, opening demand for hardware-accelerated partially homomorphic schemes.
- EDPB supplementary measures guidance:European data protection authorities are mandating technical safeguards for international transfers, creating compliance-driven procurement for formally verified implementations.
- Secure multi-party computation convergence:Integration of homomorphic encryption with secret-sharing protocols enables new collaborative analytics models in financial risk modeling and fraud detection.
Industry Challenges
- Legacy system integration complexity:Enterprise data warehouses and ERP platforms lack native ciphertext interfaces, requiring expensive middleware development and API reconstruction.
- Formal verification certification timelines:EU Cybersecurity Act evaluation procedures for cryptographic modules extend 18-24 months, delaying product launches and revenue recognition.
- Noise management parameter tuning:Operational teams lack automated tools for calibrating encryption noise budgets to preserve computational accuracy across variable workload patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homomorphic Encryption Market |
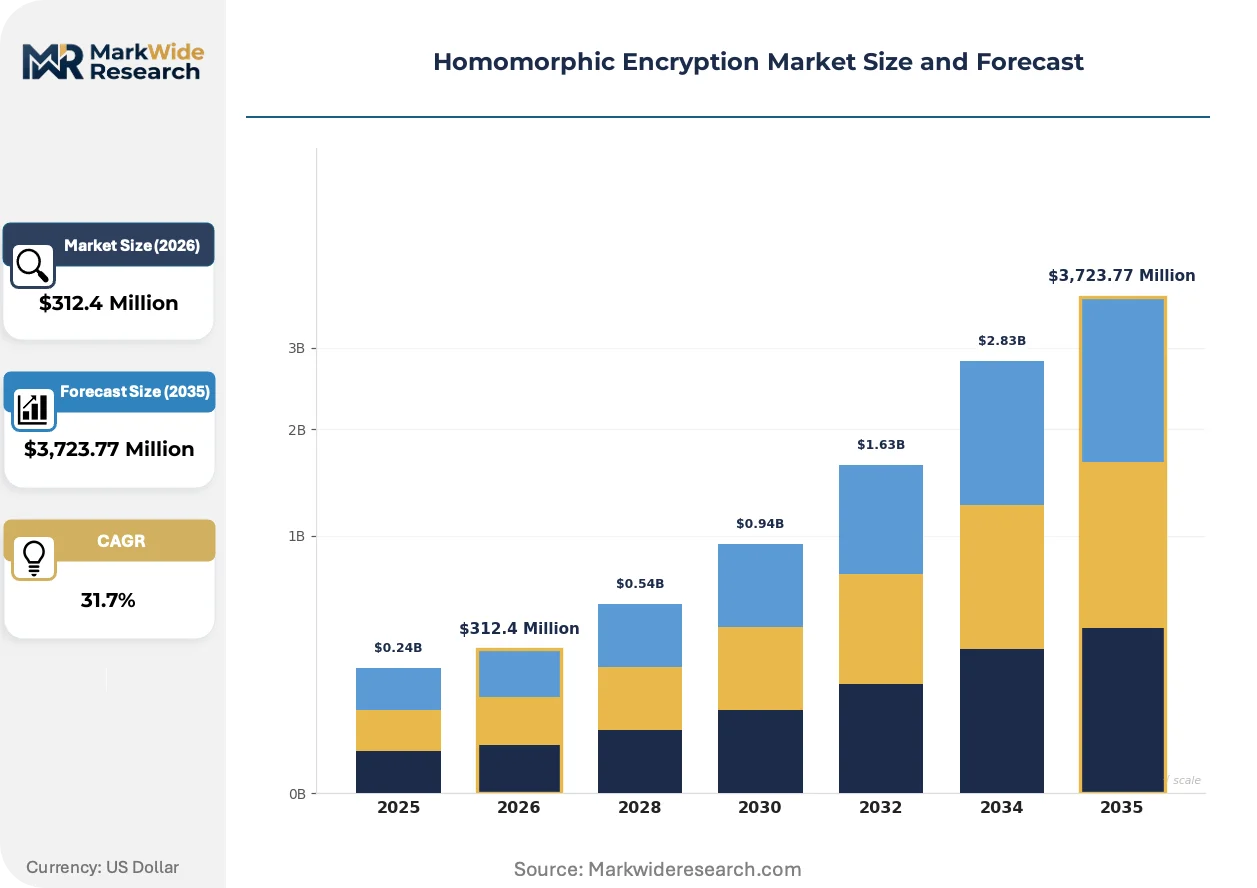
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $3,723.77 Million |
| CAGR (2026 – 2036) | 31.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Healthcare Data, Financial Services, Cloud Computing, Secure Data Analysis Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Edge Computing End User: Government Agencies, Financial Institutions, Healthcare Providers, Research Organizations Technology: Fully Homomorphic, Partially Homomorphic, Leveled Homomorphic, Other Techniques |
| Companies Covered | IBM Corporation, Microsoft Corporation, Google LLC, Duality Technologies, Zama, CryptoExperts SAS, Cosmian, Inpher, Inc., Enveil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homomorphic Encryption Market Emerging Trajectories
Hardware-software co-design is compressing the performance gap between encrypted and plaintext computation, enabling new latency-sensitive applications that were previously restricted to batch processing environments.
Lattice-based cryptography is converging with trusted execution environments to create hybrid confidentiality architectures. Financial services institutions in the United States are deploying these combined stacks for real-time fraud detection. The structural consequence is converging with confidential computing roadmaps from major cloud providers, collapsing the distinction between encryption-at-rest and encryption-in-use.
EDPB guidance on supplementary measures for international data transfers is mandating technical safeguards beyond contractual clauses. Cloud providers serving European enterprises must implement encryption schemes that withstand cryptographic scrutiny by national supervisory authorities. Healthcare and financial services verticals are responding by procuring formally verified implementations rather than experimental prototypes.
Buyer procurement specifications are unbundling security certifications from general software procurement. Enterprise security teams now issue separate RFPs for cryptographic modules with independent evaluation certificates. This pattern is most visible in German automotive supply chains, where Tier-1 suppliers require EAL4+ or Common Criteria certification before integrating encrypted analytics into connected vehicle platforms.
Homomorphic Encryption Market Segmentation
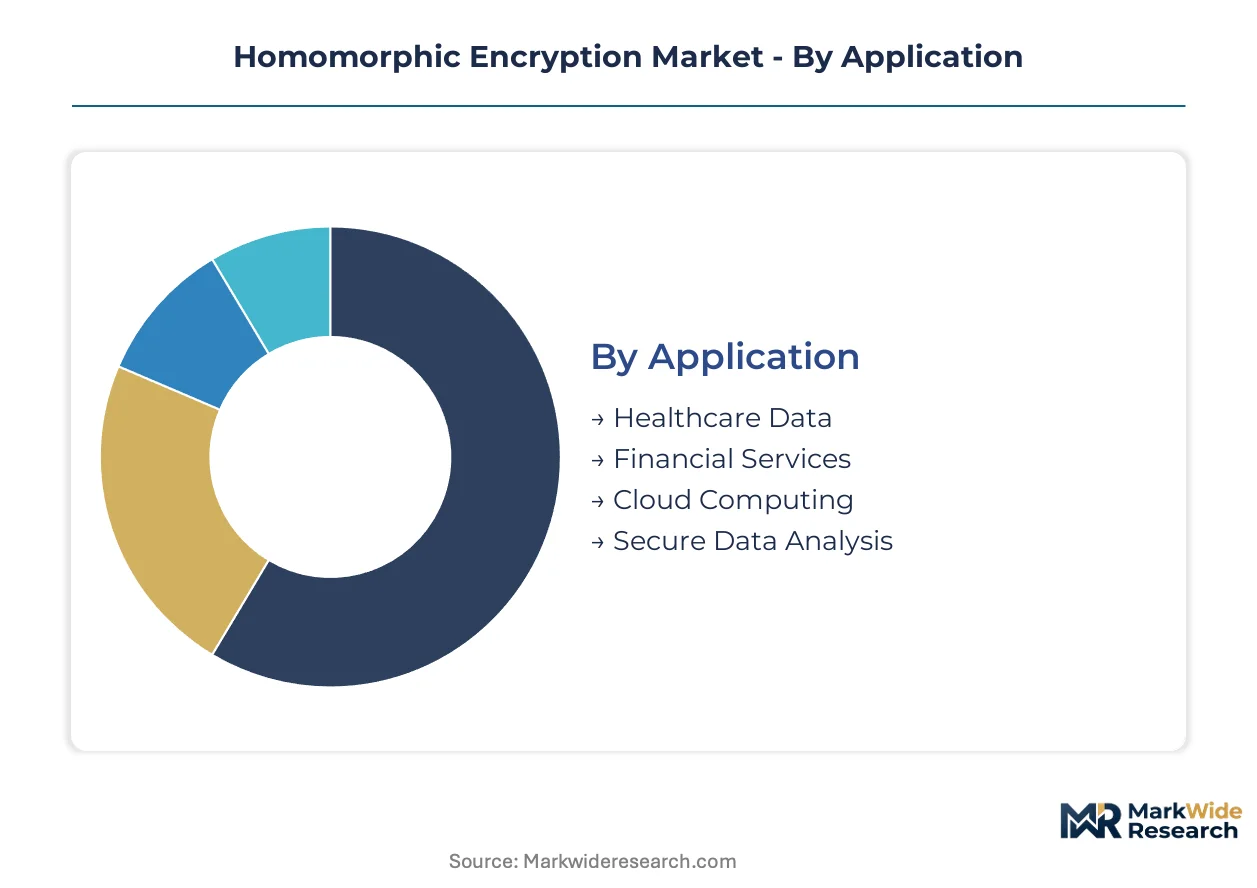
Homomorphic encryption deployments fragment across technical maturity levels and infrastructure investment thresholds. Procurement patterns diverge sharply between organizations seeking immediate compliance utility and those building long-term cryptographic infrastructure.
Application:
Capital intensity concentrates in segments requiring sustained computational overhead and specialized hardware acceleration.
- Healthcare Data:Clinical trial intermediaries deploy encrypted analytics to satisfy HIPAA business associate provisions while enabling cross-institutional research. FDA multi-party analytics guidance drives procurement specifications at academic medical centers in the United States and university hospitals in Germany.
- Financial Services:Real-time fraud detection pipelines demand lattice-based schemes integrated with trusted execution environments. United States banks and German automotive finance units absorb the highest per-deployment infrastructure costs due to latency constraints.
- Cloud Computing:Enterprise migration of sensitive workloads creates demand for privacy-preserving computation architectures.
- Secure Data Analysis:Cross-border research collaborations utilize partially homomorphic schemes for batch processing environments.
Financial Services absorbs the bulk of installed capacity; Healthcare Data is expanding most quickly.
Deployment:
Operational complexity scales with the distribution of cryptographic keys across organizational boundaries.
- Cloud-Based:Enterprise migration of sensitive workloads dominates current revenue. Azure confidential computing integration and AWS Nitro Enclaves enable outsourced computation where data owners retain cryptographic control.
- Edge Computing:Latency-constrained IoT analytics in manufacturing and autonomous systems require hardware-accelerated partially homomorphic schemes. German industrial engineering firms pilot encrypted quality assurance at production facilities.
- On-Premises:Defense and intelligence agencies mandate air-gapped infrastructure for classified workloads.
- Hybrid Solutions:Financial institutions partition workloads between private data centers and regulated cloud regions.
Cloud-Based deployments command the largest share of enterprise spending; Edge Computing climbs the fastest as manufacturing digitization accelerates.
End User:
Procurement authority concentrates in entities with regulatory enforcement exposure and cross-border data transfer obligations.
- Financial Institutions:United States banks and German automotive finance units drive demand for real-time encrypted transaction processing. EDPB supplementary measures guidance mandates technical safeguards beyond contractual clauses for European operations.
- Government Agencies:Defense and intelligence applications require formally verified implementations with extended certification timelines.
- Healthcare Providers:Academic medical centers procure encrypted computation platforms to enable multi-party clinical analytics.
- Research Organizations:Cross-border collaborations utilize partially homomorphic schemes where data utility must decouple from raw data exposure.
Financial Institutions dominate current procurement volume; Government Agencies show the steepest expansion trajectory as post-quantum standardization timelines clarify.
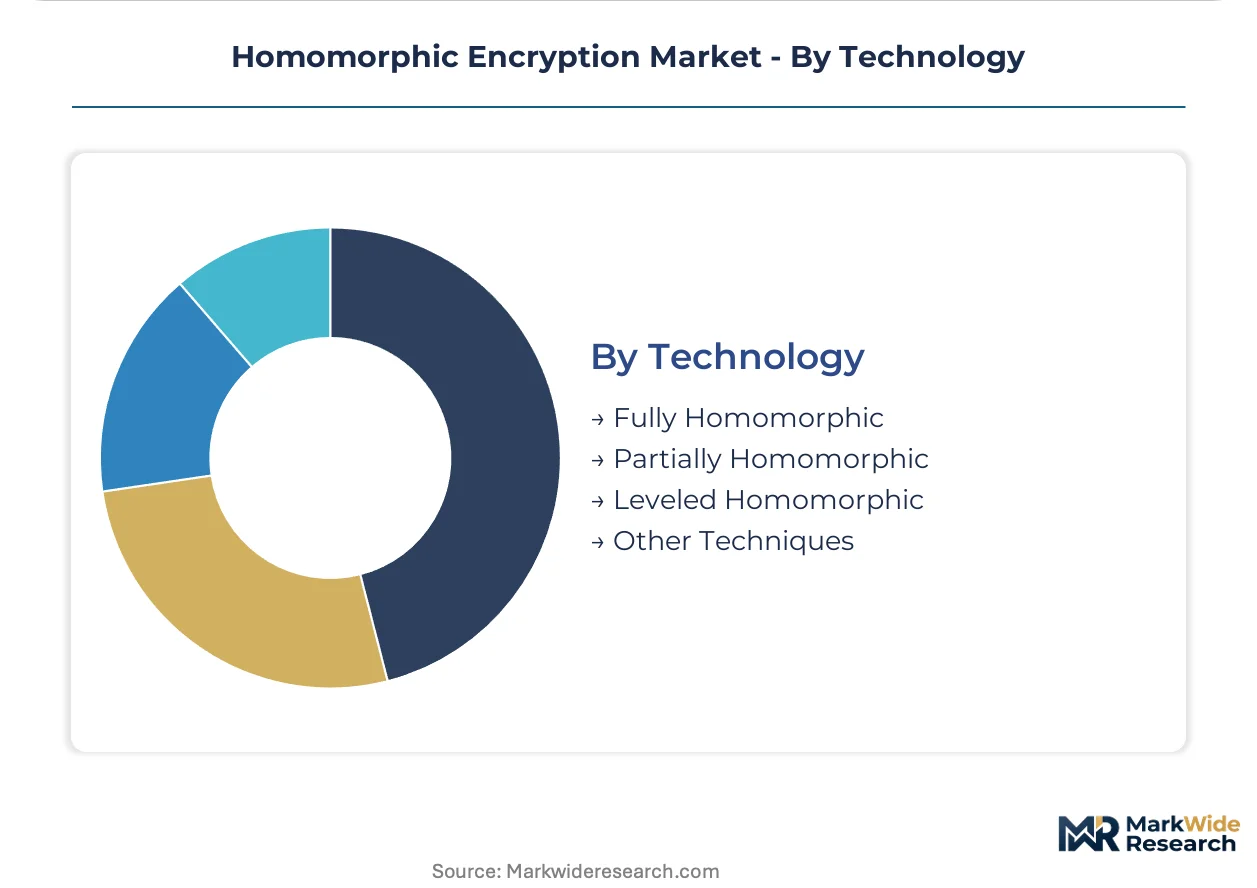
Technology:
Performance trade-offs between computational overhead and functional completeness determine addressable use cases.
- Fully Homomorphic:Arbitrary computation on ciphertext enables secure outsourced analytics without decryption. Noise management thresholds constrain deployment to batch processing at German automotive suppliers and United States healthcare data intermediaries.
- Partially Homomorphic:Limited operation sets (addition or multiplication) suffice for specific analytics pipelines. Cross-border research collaborations and financial risk modeling applications favor this lower-overhead approach.
- Leveled Homomorphic:Predefined computation depth balances flexibility against performance for known workload patterns.
- Other Techniques:Experimental schemes including functional encryption and predicate encryption address niche confidentiality requirements.
Fully Homomorphic captures the premium infrastructure investment; Partially Homomorphic gains share fastest as practical implementations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the highest concentration of homomorphic encryption development activity, with venture-backed cryptography startups clustering alongside cloud provider research divisions. German industrial corridors and United States financial centers drive divergent procurement specifications.
United States
New York-based financial institutions demand real-time fraud detection pipelines with lattice-based schemes integrated into confidential computing stacks. FDA multi-party clinical analytics guidance shapes procurement at academic medical centers in Boston and Baltimore. Seattle and Redmond host cloud provider engineering teams advancing hardware-software co-design for encrypted computation.
Germany
Automotive suppliers in Stuttgart and Munich pilot encrypted quality assurance protocols that shield proprietary design parameters from competitors. EDPB supplementary measures guidance mandates technical safeguards beyond contractual clauses for international data transfers. The Ruhr industrial belt sees Tier-1 suppliers requiring EAL4+ certification before integrating encrypted analytics into connected vehicle platforms.
United Kingdom
London financial services firms absorb the highest per-deployment infrastructure costs due to latency constraints in real-time transaction processing. The UK Information Commissioner's Office aligns enforcement posture with EU AI Act compliance timelines for high-risk AI systems. Cambridge hosts research institutions advancing formally verified implementations for cross-border research collaborations.
France
Paris-based cloud providers serving European enterprises implement encryption schemes that withstand cryptographic scrutiny by CNIL and national supervisory authorities. The EU Cybersecurity Act certification framework creates compliance-driven demand for formally verified cryptographic modules. Grenoble's semiconductor research clusters contribute hardware acceleration expertise for edge computing deployments.
Japan
Tokyo financial institutions evaluate lattice-based schemes against existing partially homomorphic implementations before hardware refresh cycles commit them to obsolete algorithms. METI post-quantum cryptography roadmaps influence enterprise infrastructure planning timelines. Osaka manufacturing conglomerates pilot encrypted IoT analytics for supply chain confidentiality in latency-constrained production environments.
Homomorphic Encryption Market Vendor Landscape
The competitive structure tilts toward diversified technology conglomerates with established cloud infrastructure and specialized cryptography ventures with deep lattice-based expertise. Player concentration spans three tiers: cloud providers integrating confidential computing, pure-play encryption specialists, and semiconductor firms advancing hardware acceleration. Dominant competitive moves include strategic partnerships between cloud platforms and cryptography vendors, plus portfolio diversification into post-quantum algorithm development.
Within the diversified technology tier, IBM Corporation and Microsoft Corporation anchor enterprise trust through lattice-based cryptography portfolios and confidential computing integration. Duality Technologies occupies a position exemplifying the pure-play specialist archetype focused on practical fully homomorphic encryption implementations. These three entities represent the spectrum from infrastructure-scale deployment capability to domain-specific cryptographic engineering depth.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Google LLC |
| Duality Technologies |
| Zama |
| CryptoExperts SAS |
| Cosmian |
| Inpher, Inc. |
| Enveil |
| Others |
Supply Flow & Price Mechanics
EU Cybersecurity Act certification mandates gate both qualified supply and premium-tier pricing access, forcing buyers to pay certification premiums for formally verified implementations while excluding uncertified vendors from regulated procurement channels. This environmental compliance filter concentrates pricing power among lattice-based cryptography specialists with completed evaluation timelines.
Pricing Analysis
Value-based pricing anchored to encrypted transaction throughput dominates procurement contracts for financial services deployments. Three-tier pricing structure across formally verified, operationally tested, and experimental implementations separates EAL4+ certified modules from pre-certified alternatives. Cost compression in pre-certified tiers intensifies because cloud providers bundle encryption into broader confidential computing packages. Healthcare data intermediaries exhibit highest price sensitivity due to constrained IT budgets, while defense agencies absorb premium pricing without volume negotiation.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor foundries fabricating hardware accelerators for lattice-based operations. Cryptographic engineering talent concentrates in the United States, Germany, and Israel, creating geographic dependency for implementation expertise. Raw material dependencies include specialized FPGA arrays, high-performance GPU clusters, and formally verified software libraries. Tariff exposure on semiconductor components threatens hardware-accelerated deployment timelines. Distribution runs through direct enterprise sales teams and cloud provider marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-quantum standardization uncertainty functions as a consolidation mechanism, eliminating vendors lacking lattice-based R&D depth before NIST finalization locks in algorithmic winners.
For Market Incumbents: Cement market position by acquiring pure-play cryptography specialists with completed EU Cybersecurity Act certifications, countering the threat of cloud providers integrating native encryption stacks. Prioritize backward integration into hardware accelerator design to reduce dependency on Taiwan-based foundry capacity. For New Entrants and Emerging Players: Mid-sized German automotive suppliers represent an underserved buyer archetype requiring encrypted quality assurance without full EAL4+ certification budgets. Target edge computing deployments in manufacturing facilities where latency constraints exclude cloud-based alternatives. Pursue partnership-based go-to-market models with industrial automation vendors. For Investors and Strategic Acquirers: NIST post-quantum standardization finalization is the leading indicator that algorithmic obsolescence risk has crystallized, triggering forced migration spending. Position for five-to-ten year viability by targeting vendors with hybrid confidential computing-homomorphic encryption integration capabilities. Watch EDPB enforcement actions on supplementary measures as the signal for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hardware-Software Co-Design Partnership | Lattice-based schemes integrated with AWS Nitro Enclaves compress performance gaps for latency-sensitive workloads. |
| EU Cybersecurity Act Certification | Formally verified implementations unlock procurement at German Tier-1 automotive suppliers requiring EAL4+ standards. |
| Post-Quantum Algorithm Portfolio Diversification | Multi-scheme coverage hedges against NIST standardization outcomes while preserving enterprise trust. |
| Edge Computing Hardware Acceleration | FPGA-based partially homomorphic implementations address IoT analytics latency in Stuttgart manufacturing corridors. |
| Cross-Border Research Collaboration Platform | Partially homomorphic batch processing enables HIPAA-compliant multi-party clinical analytics for academic medical centers. |
Methodological Framework
SEC 10-K filings, EU Cybersecurity Act certification databases, and NIST post-quantum standardization documents formed the secondary backbone, supplemented by hyperscaler capex disclosures and healthcare procurement records. Primary interviews with cryptographic engineering directors, cloud platform security leads, FDA regulatory affairs specialists, and hospital IT procurement managers validated demand assumptions. Bottom-up and top-down triangulation reconciled vendor-reported deployment volumes against enterprise IT spending patterns.
Bottom-up modeling aggregated individual deployment specifications across the projection horizon, while top-down analysis calibrated aggregate spending against regulatory compliance timelines. Segmentation dimensions included technology maturity level, deployment infrastructure type, end-user regulatory exposure, and geographic certification requirements. CAGRs derived from fitted growth curves incorporating NIST standardization milestone probabilities and EU AI Act enforcement phase transitions.
Revisions become necessary when NIST algorithmic selections diverge from lattice-based assumptions or when EDPB supplementary measures guidance shifts technical safeguard requirements. Forecasts reflect documented assumptions about hardware acceleration cost curves and certification timeline compression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Malaysia Cybersecurity Market
Cybersecurity
Global Cyber Data Security Market
Cybersecurity
Global Database Encryption Market
Cybersecurity
Quantum Cryptography Market
Cybersecurity
Big Data Security Market
Cybersecurity
Spear Phishing Solution Market
Cybersecurity
Global Mobile Data Protection Market
Cybersecurity
Mainframe Security Market
Cybersecurity
Threat Hunting Market
Cybersecurity
Israel Cybersecurity Market
Cybersecurity
Internet of Things (IoT) Security Market
Cybersecurity
M2M Network Security Market
Cybersecurity
Network Sandboxing Market
Cybersecurity
Australia Cybersecurity Market
Cybersecurity
Global Digital Forensic Laboratory As a Service Market
Cybersecurity
Web Application Firewall Market