
 Digital Forensics Market | 2026-2036
Digital Forensics Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Forensics Market Intelligence
GDPR's evidence-handling mandates for personal data breaches is rebalancing the cost-of-entry calculus for forensic platform vendors serving European clients. IBM leverages its enterprise security stack to anchor hybrid cloud forensics deployments across regulated industries. Cellebrite specializes in mobile device extraction, sustaining leadership through dedicated hardware-software integration for law enforcement workflows. Magnet Forensics competes on investigator-centric design, extending its reach among mid-sized police departments and corporate security teams.
Digital forensics encompasses the scientific recovery, preservation, and analysis of electronically stored information from computers, networks, mobile devices, and cloud environments using hash-verified imaging, write-blocking hardware, and timeline reconstruction algorithms to establish evidentiary integrity for legal proceedings. Mobile forensics dominates tool-type revenue as encrypted smartphones and IoT endpoints proliferate in criminal investigations, while cloud forensics represents the fastest-expanding category as enterprises migrate evidence repositories to distributed infrastructure. Corporate security teams and law enforcement agencies anchor end-user demand, with incident response applications capturing concentrated margin pools due to urgency-driven procurement and retainer-based service contracts.
The Federal Rules of Evidence in the United States, alongside ISO/IEC 27037 and 27042 standards, shape chain-of-custody requirements that determine which vendors qualify for government contracts. The SEC's cybersecurity disclosure rules and EU GDPR breach-notification timelines are compressing response windows, forcing organizations to pre-position forensic capabilities rather than rely on external mobilization. Stakeholders must evaluate whether their current tooling can satisfy concurrent demands for cloud-native scalability and offline air-gapped integrity as regulatory jurisdictions multiply their evidence standards.
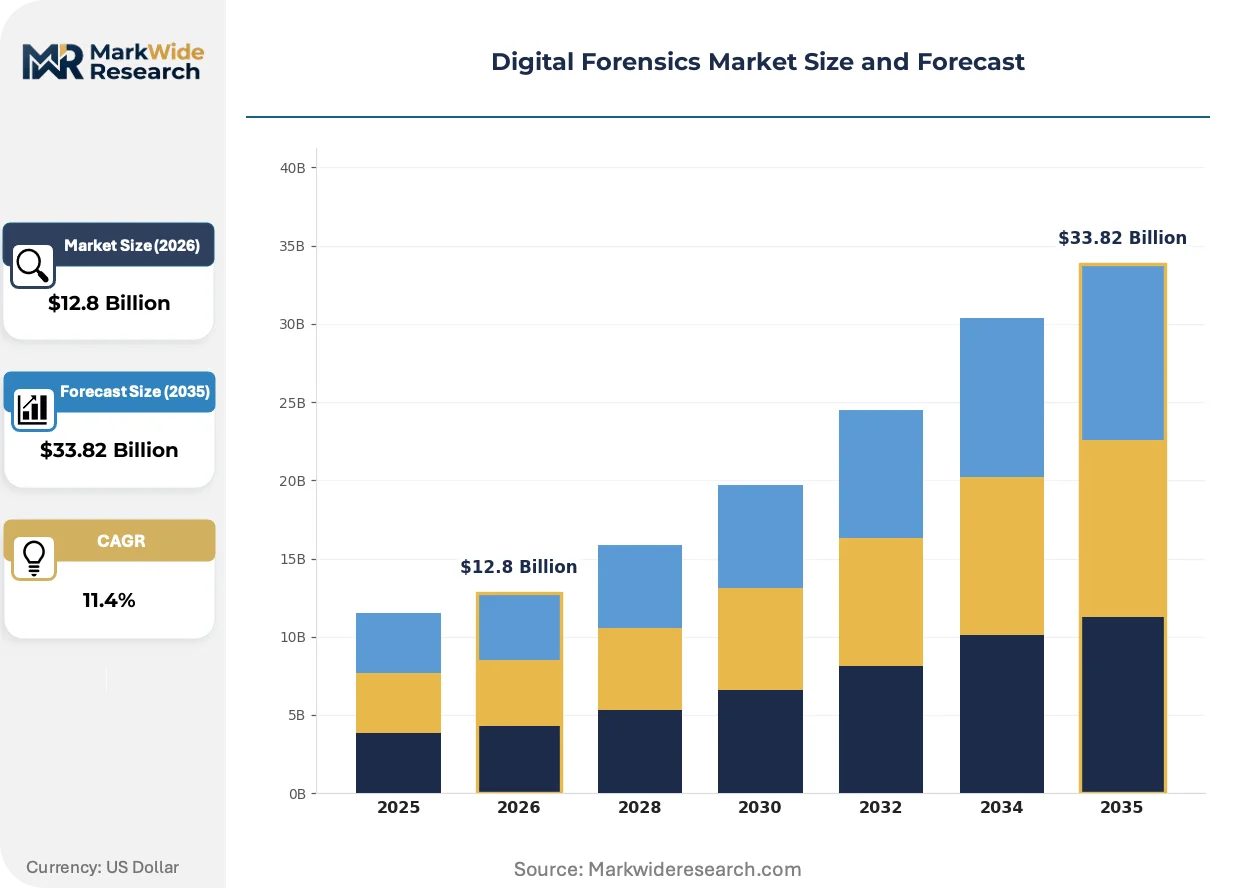
Market Dynamics
Encrypted device proliferation and cloud data dispersion are fragmenting evidence chains, forcing forensic vendors to rebuild tool architectures around distributed data sovereignty requirements rather than centralized laboratory workflows.
Growth Catalysts
- EU AI Act audit mandates:Automated decision systems in European financial and public sectors must maintain forensic-grade logging trails, creating compliance-driven procurement of logging verification tools.
- Smartphone encryption escalation:Law enforcement agencies across multiple jurisdictions face locked-device backlogs exceeding laboratory processing capacity, accelerating hardware-software integration investments.
- SEC cybersecurity disclosure rules:Public companies must document incident response timelines, compressing forensic mobilization windows and driving pre-positioned platform deployments.
Market Restraints
- Specialized talent scarcity:Certified forensic examiners command salary premiums exceeding 40% above comparable IT security roles, constraining service provider expansion.
- Tool certification fragmentation:ISO/IEC 27037, Federal Rules of Evidence, and national cybercrime standards impose overlapping but non-identical validation requirements, multiplying compliance costs.
- Cloud provider data localization:Cross-border evidence requests face jurisdictional delays when data resides in sovereign cloud zones without mutual legal assistance treaties.
Strategic Opportunities
- India digital evidence infrastructure:State police modernization programs and proposed data protection legislation create first-mover positioning for mobile extraction platform vendors.
- IoT endpoint forensics:Connected vehicle black boxes, industrial control systems, and medical device logs represent unaddressed evidence categories with minimal incumbent tooling.
- Managed detection and response convergence:Corporate security teams seek unified platforms combining real-time threat detection with post-incident forensic preservation, collapsing separate procurement cycles.
Industry Challenges
- Adversarial machine learning countermeasures:Deepfake detection and synthetic media authentication require continuous algorithm retraining that strains laboratory technical capacity.
- Legacy system integration friction:Air-gapped evidence archives in defense and intelligence agencies resist cloud-native tool deployment without extensive security accreditation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Forensics Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Disk Forensics, Network Forensics, Mobile Forensics, Database Forensics, Cloud Forensics, Email Forensics Application: Cybercrime Investigation, Fraud Analysis, Data Breach Analysis, Intellectual Property Theft, Incident Response, Insider Threat Detection End User: Law Enforcement Agencies, Corporate Security Teams, Government Agencies, Legal Firms, Private Investigators, Cybersecurity Firms Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | IBM, Cisco Systems, OpenText, Cellebrite, Nuix, Magnet Forensics, Exterro, MSAB, Paraben Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Forensics Market Strategic Shifts & Innovations
Forensic platform architecture is pivoting from laboratory-centric processing to distributed edge collection, with vendors embedding lightweight agents directly into endpoint devices and cloud tenancy boundaries.
Hash-verified containerization is unifying evidence acquisition across mobile, network, and cloud sources into single-chain custody workflows. Mid-sized police departments and corporate security teams are adopting these unified platforms to eliminate manual handoffs between specialized tools. The structural compression of multi-vendor toolchains into integrated suites is reducing training overhead and accelerating case closure timelines.
The EU AI Act's algorithmic accountability requirements are mandating immutable audit trails for automated decision systems in credit scoring, hiring, and public benefits administration. Financial services firms and government agencies must now deploy forensic logging tools capable of reconstructing model inference sequences. European vendors are prioritizing explainability modules that map decision pathways to specific training data subsets.
Corporate security teams are consolidating incident response retainers with forensic platform subscriptions, collapsing the traditional separation between real-time monitoring and post-breach investigation. Mid-market enterprises in the United States are driving this bundling, seeking predictable annual costs over emergency mobilization fees. This preference shift favors vendors offering hybrid cloud deployments with both continuous monitoring and deep forensic imaging capabilities.
Digital Forensics Market Segmentation
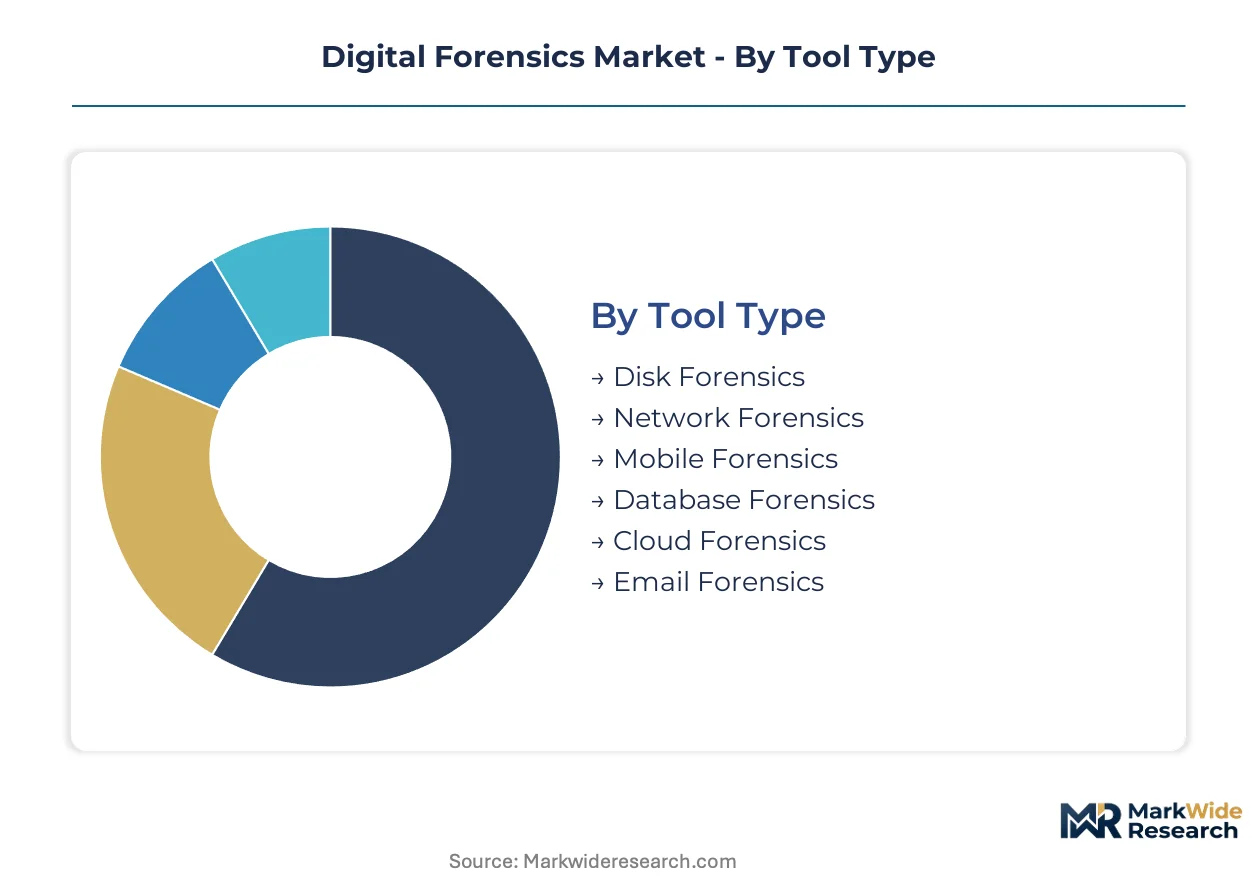
Segmentation in digital forensics reveals divergent technology requirements across evidence sources, use cases, and operational constraints. Tool architecture, deployment models, and end-user workflows vary substantially, creating distinct competitive arenas with limited cross-segment substitution.
Tool Type:
Volume concentration sits with established laboratory platforms, while premium expansion concentrates in distributed and encrypted-source extraction capabilities.
- Mobile Forensics:Specialized hardware-software stacks extract encrypted smartphone data, bypass lock mechanisms, and parse proprietary operating system artifacts. Law enforcement agencies in the United States face device backlogs exceeding laboratory capacity, forcing sustained investment in automated extraction pipelines.
- Cloud Forensics:API-based evidence collection across multi-tenant infrastructure, containerized workloads, and serverless functions requires continuous adaptation to provider-specific logging schemas. Corporate security teams migrating evidence repositories to distributed infrastructure are expanding procurement fastest.
- Disk Forensics:Hash-verified imaging of magnetic and solid-state storage remains foundational for laboratory workflows.
- Network Forensics:Packet capture and flow analysis tools reconstruct communication timelines for intrusion investigations.
- Database Forensics:Transaction log parsing and schema reconstruction for structured data tampering investigations.
- Email Forensics:Header analysis and attachment forensics for business communication compromise cases.
Today's leader: Mobile Forensics. Tomorrow's challenger: Cloud Forensics.
Application:
Incident urgency and regulatory exposure determine procurement priority, with cybercrime and breach response commanding accelerated deployment timelines.
- Incident Response:Real-time evidence preservation under SEC cybersecurity disclosure rules compresses mobilization windows to hours rather than days. United States public companies pre-position these capabilities to meet documentation requirements.
- Cybercrime Investigation:Chain-of-custody protocols for prosecution-ready evidence demand ISO/IEC 27037-compliant tooling. Federal cybercrime task forces and state fusion centers anchor concentrated demand.
- Fraud Analysis:Financial transaction reconstruction for insurance and banking investigations.
- Data Breach Analysis:Scope determination and notification trigger assessment under GDPR timelines.
- Intellectual Property Theft:Departing employee device analysis and cloud access log correlation.
- Insider Threat Detection:Behavioral forensics combining endpoint telemetry with communication pattern analysis.
Incident Response commands current margin pools; Cybercrime Investigation offers the steepest expansion trajectory as encrypted device proliferation accelerates.
End User:
Budget scale and evidence admissibility standards separate regulated government procurement from commercial security operations.
- Law Enforcement Agencies:Federally accredited laboratories require Federal Rules of Evidence-compliant tool validation. United States federal, state, and local agencies sustain the largest installed base through grant-funded modernization cycles.
- Corporate Security Teams:Unified platforms combining detection and forensic preservation are collapsing separate procurement cycles. Mid-market enterprises favor predictable subscription costs over emergency mobilization retainers.
- Government Agencies:Defense and intelligence operations with air-gapped infrastructure requirements.
- Legal Firms:E-discovery adjacent forensic support for civil litigation and regulatory defense.
- Private Investigators:Cost-constrained access to commercial forensic tool licenses.
- Cybersecurity Firms:Managed detection and response providers bundling forensic capabilities into service offerings.
Law Enforcement Agencies dominate current certification-driven procurement; Corporate Security Teams are gaining share fastest as SEC disclosure rules expand addressable demand.
Deployment:
Control requirements and data sovereignty constraints fragment architecture preferences across air-gapped, cloud-native, and transitional hybrid models.
- On-Premise:Air-gapped laboratory environments with write-blocking hardware and isolated evidence storage meet defense and intelligence accreditation requirements. Legacy infrastructure in these sectors resists cloud migration without extensive security review.
- Hybrid:Split workflows with edge collection agents and centralized analysis balance distributed evidence sources with controlled laboratory processing. This architecture is expanding most quickly as organizations navigate concurrent demands for cloud scalability and offline integrity.
- Cloud-Based:Fully managed forensic workspaces with API-native evidence ingestion.
- Managed Services:Outsourced forensic investigation retainers with guaranteed response times.
On-Premise retains the largest installed base; Hybrid deployment is climbing the fastest as evidence chains fragment across distributed infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified forensic examiners concentrate in the United States, Germany, and India, creating talent clusters that anchor regional procurement patterns for mobile and cloud forensics platforms.
United States
Federal cybercrime task forces and state-level fusion centers drive concentrated demand for mobile extraction hardware. SEC cybersecurity disclosure rules compress incident response windows to hours, forcing public companies to pre-position forensic capabilities. The Washington-Baltimore corridor hosts the largest concentration of federally accredited forensic laboratories serving defense and intelligence agencies.
Germany
Automotive and industrial manufacturers in Baden-Württemberg and Bavaria generate enterprise demand for IoT endpoint forensics. The EU AI Act mandates immutable audit trails for automated decision systems in financial and public sectors. Berlin-Brandenburg clusters host compliance-focused vendors developing explainability modules for algorithmic accountability.
United Kingdom
London's financial services sector sustains procurement of fraud analysis and transaction reconstruction platforms. GDPR breach-notification timelines force organizations to maintain 72-hour forensic mobilization capacity. The Thames Valley corridor anchors corporate security teams consolidating detection and forensic preservation into unified subscriptions.
India
State police modernization programs in Maharashtra and Karnataka create first-mover opportunities for mobile extraction vendors. Proposed data protection legislation aligns evidence-handling requirements with emerging compliance frameworks. Bangalore's technology corridor hosts cybersecurity firms bundling forensic capabilities into managed detection and response services.
Japan
Metropolitan police departments in Tokyo and Osaka face encrypted smartphone backlogs exceeding laboratory processing capacity. METI guidelines for critical infrastructure protection mandate forensic-grade logging for industrial control systems. The Kansai region's manufacturing base drives demand for connected vehicle black box analysis tools.
Digital Forensics Market Key Industry Players
The competitive structure tilts toward diversified technology conglomerates with enterprise security stacks. Consolidation pressures favor vendors offering hybrid cloud deployments with both continuous monitoring and deep forensic imaging. Three archetypes dominate: integrated security platforms, mobile extraction specialists, and investigator-centric design houses. M&A activity concentrates on collapsing separate procurement cycles between detection and forensics, while geographic expansion targets India's state police modernization programs.
Within the integrated platform tier, IBM and Cisco Systems exemplify diversified technology conglomerates leveraging enterprise security infrastructure to anchor hybrid cloud forensics deployments. Cellebrite represents the mobile extraction specialist archetype, sustaining positioning through dedicated hardware-software integration for law enforcement workflows. These three companies occupy distinct competitive vectors—enterprise breadth, device-specific depth, and workflow optimization—without direct substitution across procurement contexts.
| Leading Market Players |
|---|
| IBM |
| Cisco Systems |
| OpenText |
| Cellebrite |
| Nuix |
| Magnet Forensics |
| Exterro |
| MSAB |
| Paraben Corporation |
| Others |
Cost & Logistics Intelligence
Hash-verified containerization and lightweight edge-agent deployment are compressing both software delivery costs and vendor consolidation economics, enabling integrated platform vendors to capture margin pools previously fragmented across multi-tool laboratory workflows. This architectural shift simultaneously reduces per-seat licensing overhead for mid-sized police departments while concentrating procurement leverage among hybrid cloud providers serving corporate security teams.
Pricing Analysis
Bundled incident response retainers with forensic platform subscriptions now command premium positioning against unbundled emergency mobilization fees, with three-tier pricing structure across premium, standard, and economy levels differentiating by ISO/IEC 27042 certification grade and after-sales training depth. Price differentiation hinges on Federal Rules of Evidence validation status and cloud-native scalability. Cost compression in standard tiers is intensifying because mid-market enterprises favor predictable annual subscriptions over project-based procurement. Corporate security teams exhibit highest price sensitivity; defense and intelligence agencies with air-gapped requirements show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for mobile extraction hardware, while value-added resellers serve fragmented mid-sized law enforcement agencies. Manufacturing concentrates in the United States, Israel, and Germany for specialized write-blocking hardware and forensic imaging devices. Component sourcing draws from Taiwan for semiconductor fabrication, Japan for precision storage components, and domestic US suppliers for tamper-evident enclosures. Single-source vulnerability in advanced FPGA chips for encryption bypass modules poses structural risk. Distribution runs through federally accredited laboratory procurement frameworks and corporate security vendor consolidation programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in digital forensics rests on collapsing separate detection and forensic procurement cycles into unified subscription bundles, with SaaS delivery economics reducing customer acquisition costs across mid-market corporate security segments.
For Market Incumbents: Anticipate pricing pressure from cloud-native entrants by accelerating backward integration into edge-agent telemetry collection and securing FedRAMP accreditation for hybrid deployments. Threat substitution from MDR providers bundling forensic capabilities demands defensive certification investment in ISO/IEC 27042 validation. Channel control through state police modernization grant programs offers margin protection. For New Entrants and Emerging Players: API-first distribution routes into India's state police modernization programs offer lowest competitive density against entrenched mobile extraction vendors. White-space concentrates in IoT endpoint forensics for connected vehicle black boxes and industrial control system logs. Go-to-market through cybersecurity insurance carriers as forensic investigation partners bypasses direct law enforcement procurement barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among investigator-centric design houses lacking hybrid cloud scale but holding sticky mid-sized police department relationships. Long-term viability favors vendors with concurrent air-gapped and cloud-native deployment architecture. Watch SEC cybersecurity disclosure enforcement intensity as inflection indicator for corporate security segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies real-time detection with post-incident forensic preservation under single subscription economics. |
| Acquisition of Specialist Firm | Adds mobile extraction hardware expertise to cloud-native software vendors seeking law enforcement accreditation. |
| Geographic Expansion | Captures first-mover positioning in India's state police modernization programs before incumbent saturation. |
| Strategic Partnership | Aligns forensic logging tools with EU AI Act compliance requirements for financial services algorithmic accountability. |
| Product Launch | Introduces IoT endpoint forensics capabilities for connected vehicle and medical device evidence categories. |
Research Approach
Coverage spans the United States, Germany, India, and Japan, with primary inputs from each market combining structured interviews with forensic laboratory directors, corporate security procurement officers, federal cybercrime task force leads, and cloud forensics platform engineers alongside secondary validation. Sources include SEC cybersecurity disclosure filings, EU AI Act implementation guidance, state police modernization budget documents, and ISO/IEC 27037 accreditation registries. Bottom-up segment sizing triangulates against top-down regulatory-driven demand estimates.
Rate-of-change decomposition separates volume expansion from value-per-seat growth across the projection horizon, with segmentation modeled by tool type, deployment architecture, end-user budget tier, and evidence source complexity. CAGRs derive from installed base replacement cycles, encrypted device backlog growth rates, and compliance timeline enforcement patterns. Cloud API adaptation velocity and mobile operating system encryption escalation serve as industry-specific forecast inputs.
Regulatory enforcement delays, adversarial machine learning countermeasure breakthroughs, and cloud provider data localization disputes are the dominant revision risks to modeled assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Latin America Cybersecurity Market
Cybersecurity
Egypt Cybersecurity Market
Cybersecurity
Deception Technology Market
Cybersecurity
Africa Cybersecurity Market
Cybersecurity
Global Container and Kubernetes Security Market
Cybersecurity
Global Cyber Threat Intelligence Market
Cybersecurity
Advanced Malware Detection (AMD) Market
Cybersecurity
Data Security Market
Cybersecurity
Cybersecurity Mesh Market
Cybersecurity
Open RAN Security Market
Cybersecurity
Global Mobile Data Protection Market
Cybersecurity
Botnet Detection Market
Cybersecurity
Cloud Siem Market
Cybersecurity
Firewall-As-A-Service (Fwaas) Market
Cybersecurity
ASEAN Cyber Security Market
Cybersecurity
Poland Cybersecurity Market