
 Automotive V2X Market | 2026-2036
Automotive V2X Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive V2X Market Intelligence
China is reconfiguring automotive V2X manufacturing capacity through state-backed 5G corridor projects and domestic chip foundry expansion. Qualcomm Technologies leverages its C-V2X modem portfolio to anchor cellular-based vehicle connectivity across multiple continents. Robert Bosch GmbH sustains integrated hardware-software roadmaps for vehicle-to-infrastructure modules. NXP Semiconductors dominates secure element supply for V2X authentication stacks.
Automotive V2X denotes wireless communication systems enabling direct data exchange between vehicles, infrastructure, pedestrians, and networks, operating across 5.9 GHz ITS spectrum bands with sub-100 millisecond latency requirements for safety-critical messaging. Its primary purpose is collision prevention, traffic flow optimization, and autonomous driving sensor augmentation. Cellular V2X modules capture expanding margin pools as 5G rollouts displace earlier DSRC architectures in new vehicle programs. Traffic management applications lead current deployment volume, while collision avoidance systems represent the fastest-growing application segment as regulators mandate advanced driver assistance integration.
The FCC governs 5.9 GHz spectrum allocation in the United States, while the EU AI Act and CE marking frameworks shape product compliance across European deployments. China's MIIT issues GB standards for connected vehicle cybersecurity and radio transmission protocols. Stakeholders must monitor spectrum reallocation proceedings and cross-border certification reciprocity agreements as these decisions determine market access timelines and product development priorities.
Market Dynamics
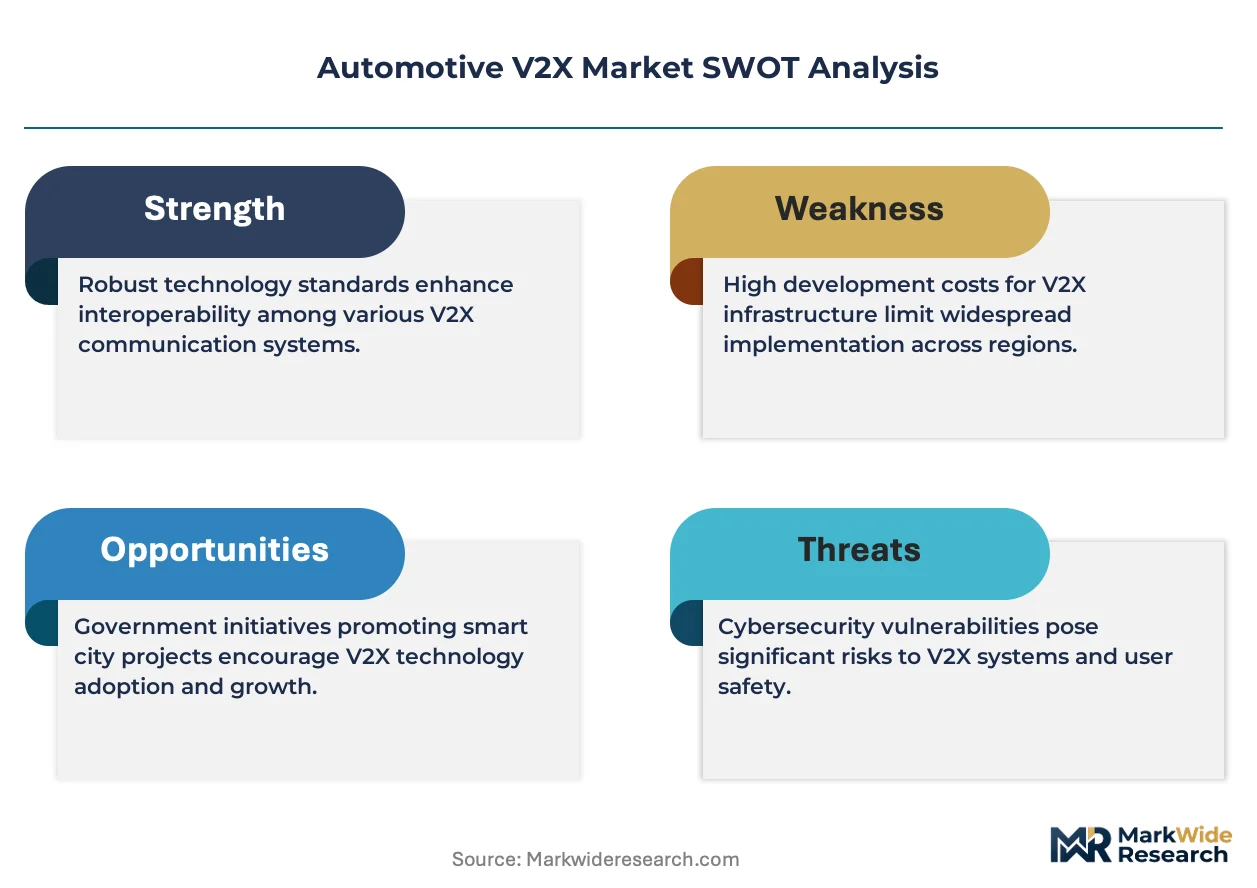
The transition from DSRC to C-V2X architectures is compressing supplier margins while creating first-mover advantages for modem vendors with 5G-ready portfolios. Spectrum reallocation proceedings in multiple jurisdictions are forcing hardware redesigns mid-cycle.
Growth Catalysts
- EU 5G corridor mandates:The European Commission's designated cross-border corridors require C-V2X deployment on trans-European transport networks, creating guaranteed demand pools for roadside unit manufacturers.
- ADAS integration requirements:NHTSA's advancing notice of proposed rulemaking on automatic emergency braking is compelling OEMs to augment camera-radar fusion with V2X sensor inputs for redundant object detection.
- China's MIIT GB standards:Mandatory cybersecurity certification for connected vehicles under GB/T protocols is accelerating domestic module qualification timelines and excluding non-compliant foreign suppliers.
Market Restraints
- Secure element supply concentration:Automotive-grade hardware security module fabrication concentrates among three foundry groups, creating allocation risk during semiconductor demand surges.
- Spectrum coexistence complexity:FCC reconfiguration of the 5.9 GHz band for unlicensed Wi-Fi use reduces available channels for safety-critical messaging, forcing power-output compromises.
- DSRC stranded asset risk:Early deployments of IEEE 802.11p roadside infrastructure in Japan and select US states face technical obsolescence before depreciation cycles complete.
Strategic Opportunities
- Vulnerable road user protection:Pedestrian and cyclist detection via direct device-to-vehicle communication remains underdeployed outside Chinese smart city pilots, offering expansion white space.
- Platooning commercialization:Truck convoy automation using V2X cooperative adaptive cruise control awaits regulatory frameworks from Germany's KBA and US state DOT harmonization.
- Edge-cloud convergence:Integration of roadside unit processing with municipal MEC nodes enables traffic signal optimization services beyond basic safety messaging.
Industry Challenges
- Cross-certification timeline fragmentation:FCC equipment authorization, EU CE marking under the Radio Equipment Directive, and China SRRC approval follow non-harmonized test protocols, extending product launch schedules.
- Embedded systems integration complexity:V2X stack porting to heterogeneous automotive compute architectures requires specialized automotive Ethernet and CAN gateway expertise that remains scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive V2X Market |
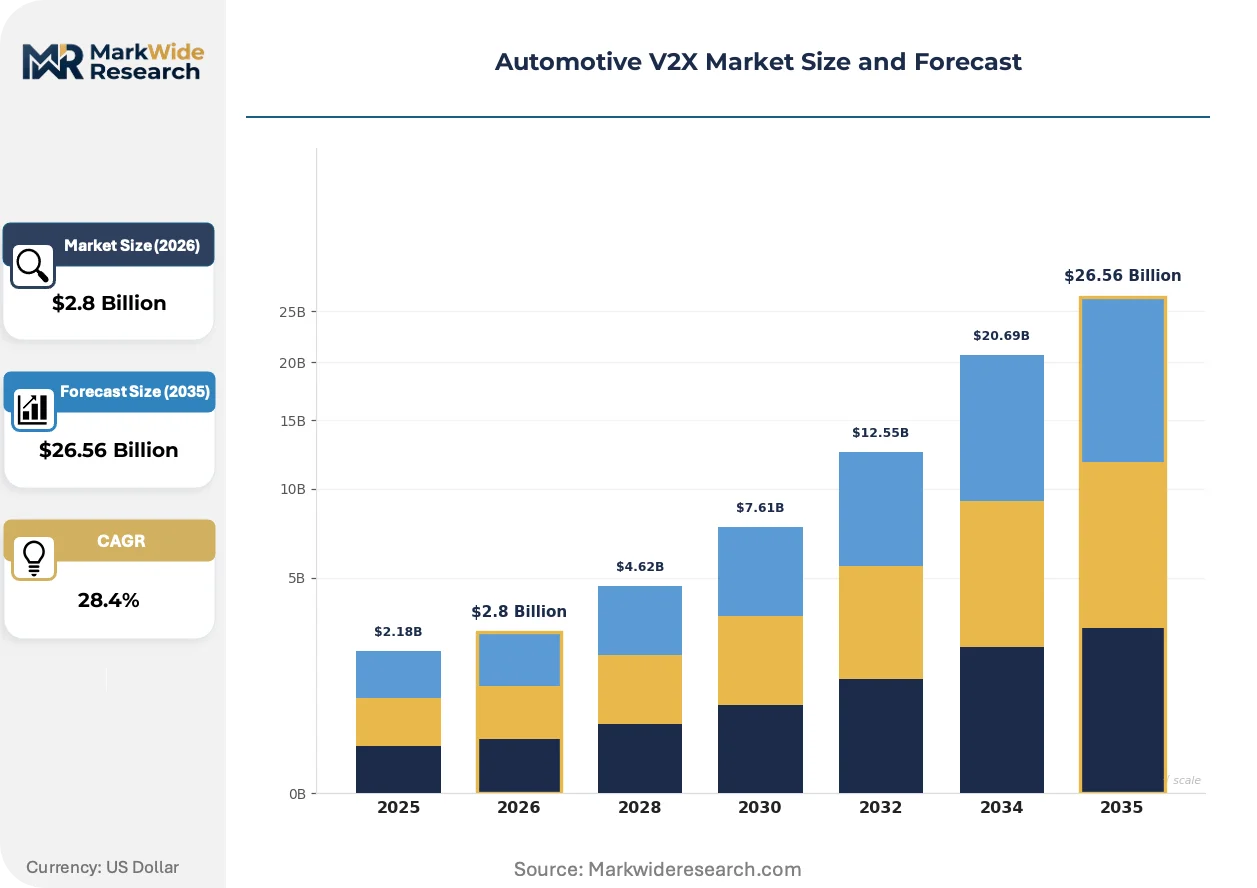
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.56 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dedicated Short Range Communication, Cellular V2X, Vehicle-to-Vehicle, Vehicle-to-Infrastructure Technology: 5G, LTE, C-V2X, DSRC Application: Traffic Management, Emergency Vehicle Notification, Collision Avoidance, Parking Assistance End User: OEMs, Fleet Operators, Transportation Agencies, Automotive Aftermarket |
| Companies Covered | Harman International, Robert Bosch GmbH, Qualcomm Technologies, Autotalks, LG Electronics, Continental, NXP Semiconductors, Infineon Technologies, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive V2X Market Strategic Shifts & Innovations
Cellular-based vehicle connectivity is overtaking earlier radio technologies through modem cost curves and 5G network densification. Three developments are restructuring competitive positions.
Single-chip C-V2X modems with integrated application processors are rendering obsolete discrete DSRC transceiver modules that required separate host controllers. Tier 1 suppliers are qualifying these consolidated designs for 2027 model year platforms. The consolidation is collapsing bill-of-materials differentiation between entry and mid-tier vehicle segments.
The EU AI Act's risk classification framework for autonomous decision-making systems is imposing documentation burdens on V2X-based cooperative perception algorithms. Developers must maintain technical files demonstrating traceability of sensor fusion outputs. German OEMs are front-loading compliance engineering to secure type approval ahead of enforcement deadlines.
Fleet operators are consolidating telematics procurement under mobility-as-a-service contracts that bundle V2X roadside access with vehicle leasing. Municipalities in the United States are responding by offering concession-based deployment models where infrastructure vendors recover capital through per-vehicle transaction fees rather than upfront equipment sales.
Automotive V2X Market Segmentation
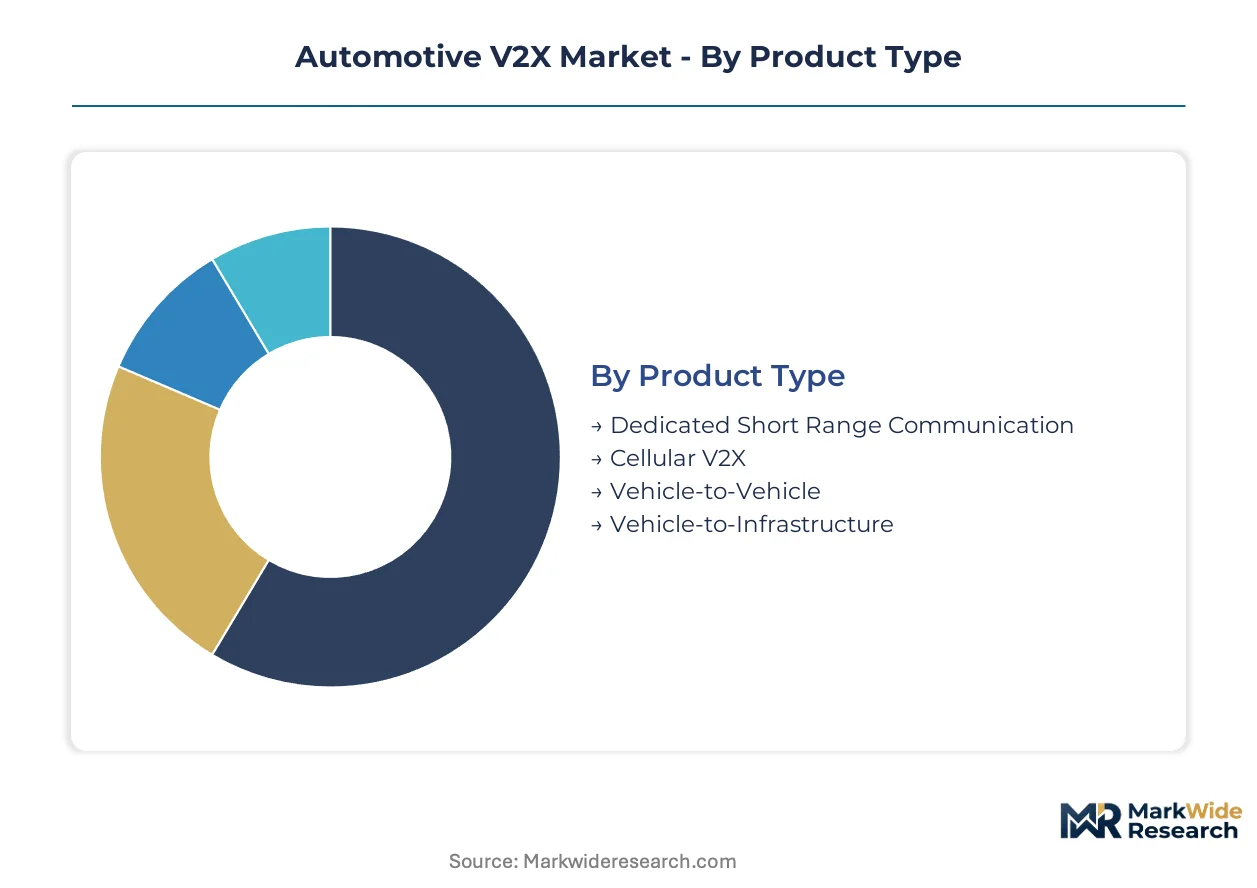
Automotive V2X segmentation reveals how technology choices, deployment models, and buyer economics split the market into distinct competitive arenas. Each dimension carries different margin profiles, certification requirements, and supplier concentration patterns that reshape go-to-market strategy.
Product Type:
Cost tier separates the four product architectures, with integrated cellular modules commanding premium positioning against legacy radio implementations.
- Cellular V2X:Consolidated modem-application processor designs operate across 5G NR and LTE networks with sub-50 millisecond latency for safety messaging. OEMs in Germany and China are standardizing this architecture for 2027 platforms, displacing earlier discrete implementations.
- Vehicle-to-Infrastructure:Roadside unit modules enable traffic signal phase and timing data exchange with municipal systems. United States DOT corridor deployments in Michigan and Arizona are concentrating procurement volume as federal infrastructure funding flows into connected highway programs.
- Dedicated Short Range Communication:IEEE 802.11p-based transceivers retain installed base in Japan and select US state pilot programs facing technical obsolescence risk.
- Vehicle-to-Vehicle:Direct peer-to-peer messaging modules support cooperative awareness in platooning and intersection collision scenarios.
Vehicle-to-Infrastructure commands the established base. The steepest expansion runs through Cellular V2X.
Technology:
Application maturity divides the four radio standards, with 5G-ready protocols capturing new design wins against legacy dedicated short-range implementations.
- C-V2X:3GPP Release 14 and 15 specifications enable PC5 direct communication and Uu network-based modes with unified hardware. FCC spectrum rules and EU 5G corridor mandates are accelerating module qualification timelines across multiple continents.
- 5G:NR-V2X extensions support advanced use cases including sensor sharing and cooperative perception with higher throughput requirements. Chinese MIIT GB standard compliance is filtering supplier qualification to domestic and select international modem vendors.
- LTE:Rel-12/13 eV2A and eV2B implementations provide fallback connectivity in areas lacking 5G network densification.
- DSRC:IEEE 802.11p-based systems face stranded asset risk as spectrum reallocation proceedings reduce available 5.9 GHz channels.
LTE commands the established base. The steepest expansion runs through C-V2X.
Application:
Volume concentration varies across the four use cases, with traffic optimization leading current deployment while safety-critical functions drive fastest growth.
- Traffic Management:Signal phase and timing optimization, queue warning, and speed harmonization applications dominate current roadside unit installation counts. Municipal procurement in the United States and Germany concentrates demand through multi-year smart city contracts.
- Collision Avoidance:Intersection movement assist, left-turn assist, and emergency electronic brake light messaging require sub-100 millisecond latency with functional safety certification. NHTSA advancing rulemaking on automatic emergency braking is compelling OEM integration with camera-radar fusion systems.
- Emergency Vehicle Notification:Preemption and priority signaling applications for ambulance and fire services.
- Parking Assistance:Availability broadcasting and automated valet parking enablement.
Traffic Management commands the established base. Collision Avoidance is climbing the fastest.
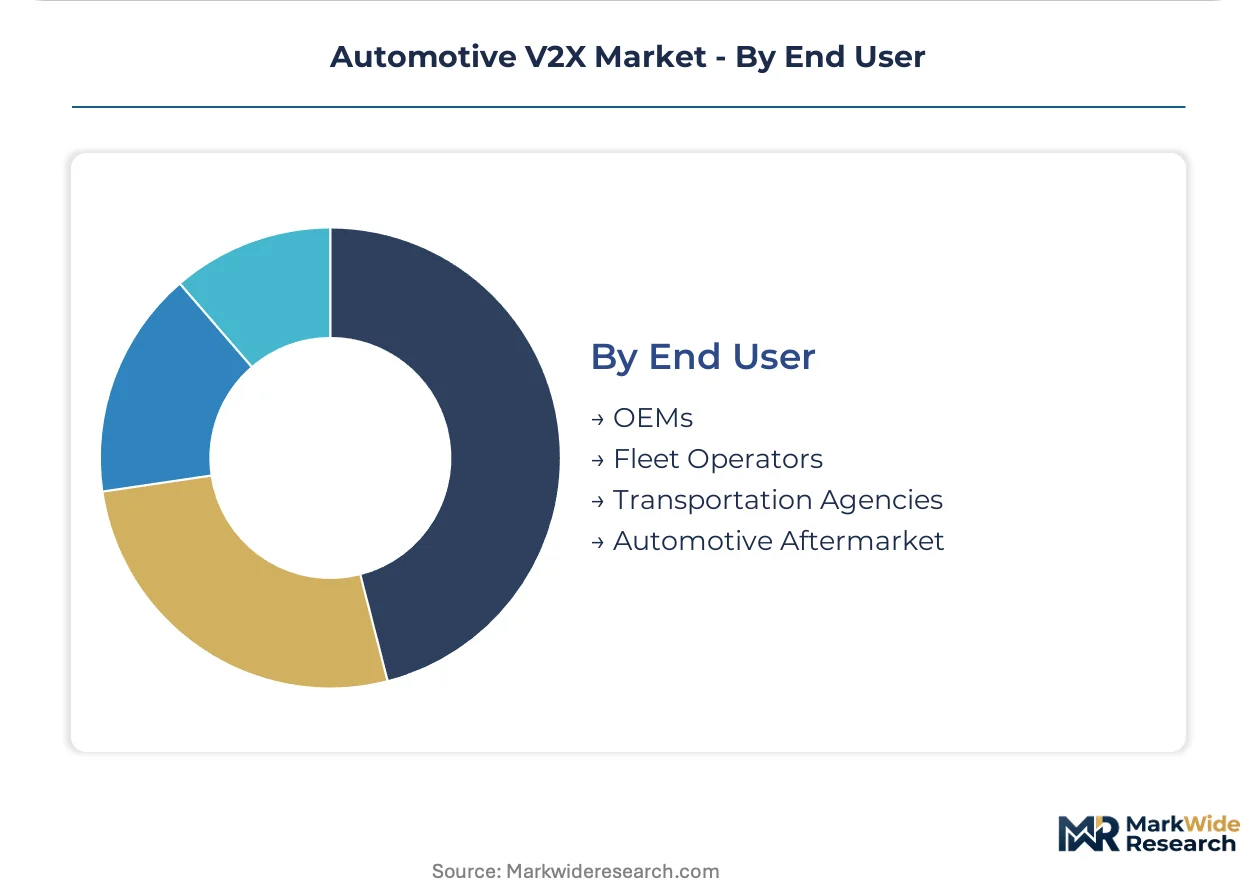
End User:
Customer type determines procurement patterns, with OEM integration timelines running longer than fleet operator or agency deployment cycles.
- OEMs:Passenger and commercial vehicle manufacturers embed V2X stacks into gateway controllers with automotive Ethernet backbone integration. German and Chinese OEMs are front-loading compliance engineering for EU AI Act documentation requirements on cooperative perception algorithms.
- Transportation Agencies:State and municipal DOTs procure roadside units through infrastructure grant programs. United States IIJA funding streams are accelerating deployment velocity on designated alternative fuel corridors.
- Fleet Operators:Trucking and logistics companies pilot platooning and cooperative adaptive cruise control.
- Automotive Aftermarket:Retrofit module installation for vehicle connectivity upgrades.
OEMs command the established base. The steepest expansion runs through Transportation Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 5.9 GHz spectrum corridors along the US Interstate Highway System anchor North American deployment velocity. China's national 5G highway backbone underwrites the largest single-country infrastructure commitment. Germany's trans-European transport network corridors concentrate EU procurement volume.
United States
Michigan's Ann Arbor connected vehicle testbed and Arizona's Sun Corridor generate concentrated roadside unit demand. NHTSA advancing rulemaking on automatic emergency braking compels OEMs to integrate V2X sensor redundancy. The IIJA alternative fuel corridor program channels federal infrastructure funding into designated highway segments.
Germany
The A9 Digital Test Field and A2-A44 5G corridor deployment anchor European module qualification timelines. KBA type approval requirements for cooperative perception algorithms front-load compliance engineering costs. Bavaria's automotive cluster around Ingolstadt and Munich concentrates OEM gateway controller integration programs.
China
Beijing-Tianjin-Hebei and Yangtze River Delta smart city pilots generate the world's largest vulnerable road user protection deployment base. MIIT GB/T cybersecurity certification mandates exclude non-compliant foreign module suppliers. Shenzhen's electronics manufacturing corridor concentrates C-V2X modem foundry expansion.
Japan
DSRC roadside infrastructure on the Shin-Tomei Expressway faces technical obsolescence risk before depreciation cycles complete. METI spectrum allocation proceedings determine 5.9 GHz channel availability for safety-critical messaging. Nagoya's automotive supplier cluster manages the transition from IEEE 802.11p to C-V2X architectures.
South Korea
Seoul Capital Area autonomous vehicle test zones drive V2X stack integration with domestic OEM platforms. The country's national ITS framework mandates sub-50 millisecond latency for intersection collision avoidance. Busan-Ulsan's electronics manufacturing base supplies secure element fabrication for authentication stacks.
Automotive V2X Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the modem and secure element layers. The supplier base concentrates around semiconductor foundries with automotive-grade hardware security module capability. Three archetypes dominate: modem vendors with 3GPP-compliant portfolios, Tier 1 system integrators with gateway controller expertise, and secure element suppliers with GB/T certification access. Competitive moves center on spectrum reallocation readiness and cross-certification timeline compression.
Among modem-centric vendors, Qualcomm Technologies and Autotalks occupy positions anchoring cellular-based vehicle connectivity across multiple continents. Robert Bosch GmbH exemplifies the integrated hardware-software system tier with roadside unit and vehicle gateway module roadmaps. NXP Semiconductors sits within the secure element concentration, supplying authentication stack components for V2X deployment programs.
| Leading Market Players |
|---|
| Harman International |
| Robert Bosch GmbH |
| Qualcomm Technologies |
| Autotalks |
| LG Electronics |
| Continental |
| NXP Semiconductors |
| Infineon Technologies |
| Denso Corporation |
| Others |
Cost & Logistics Intelligence
Shenzhen-Dongguan logistics corridor cost dynamics compress module margins while amplifying price differentiation between automotive-grade certified and uncertified V2X stacks. Supply concentration in East Asian foundry networks feeds downstream tiering as OEMs and transportation agencies face divergent procurement economics.
Pricing Analysis
Volume-discount tiering structures separate multi-million-unit OEM contracts from municipal roadside unit procurements. Three-tier pricing stratifies across ASIL-D certified, ASIL-B compliant, and non-safety-critical implementations. Pricing pressure stems from C-V2X modem commoditization as Qualcomm and MediaTek consolidate application processor integration. Fleet operators exhibit highest price sensitivity due to thin trucking margins; German OEMs absorb premium positioning for cooperative perception liability coverage.
Supply Chain Analysis
Supplier-financing facilities from NXP and Infineon extend 90-day payment terms to Tier 1 integrators facing municipal budget cycle mismatches. Semiconductor fabrication concentrates in Taiwan, South Korea, and China's Yangtze River Delta. Automotive-grade secure element supply draws from silicon carbide substrates and hardware security module IP licensed from ARM TrustZone architectures. Single-source vulnerability concentrates in TSMC's 28nm automotive node capacity. Distribution runs through Bosch and Continental gateway controller programs to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive V2X market fragmentation creates entry niches as transportation agency procurement diverges from OEM integration timelines. The shift from equipment sales to per-vehicle transaction models unbundles legacy supplier relationships.
For Market Incumbents: Insulate modem revenue streams through exclusive roadside unit concession agreements with Michigan DOT and Arizona DOT corridor programs. Lock in ASIL-D certification moats ahead of EU AI Act enforcement deadlines. Backward integration into secure element foundry capacity at Busan-Ulsan clusters reduces allocation risk during semiconductor demand surges.
For New Entrants and Emerging Players: Pursue vulnerable road user protection white space outside Chinese smart city pilots where pedestrian-to-vehicle direct communication remains underdeployed. Target European transportation agencies with C-V2X roadside units under EU 5G corridor mandates. Lead with edge-cloud convergence offerings bundling municipal MEC node integration.
For Investors and Strategic Acquirers: Modem vendors with 3GPP Release 16 readiness and active FCC equipment authorization represent the priority acquisition archetype. Long-term viability hinges on spectrum reallocation agility across 5.9 GHz band configurations. Watch NHTSA automatic emergency braking rulemaking finalization as inflection indicator for collision avoidance module demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| C-V2X Modem Platform Standardization | Consolidated designs displace discrete DSRC transceivers in 2027 model year programs. |
| EU AI Act Compliance Engineering | German OEMs front-load documentation for cooperative perception algorithm traceability. |
| Secure Element Foundry Expansion | Domestic Chinese GB/T certification capacity excludes non-compliant foreign suppliers. |
| Roadside Unit Concession Financing | Municipal per-vehicle transaction models replace upfront equipment sales in US deployments. |
| 5G Corridor Infrastructure Partnership | Federal IIJA funding channels into Michigan and Arizona connected highway segments. |
Research Approach
Cross-validation between OEM platform engineering disclosures and FCC equipment authorization filings anchors the qualitative findings. Primary interviews with Tier 1 supplier procurement officers, OEM gateway controller engineers, municipal DOT program managers, and secure element fabrication specialists combine with secondary validation from 3GPP release documentation, NHTSA rulemaking dockets, MIIT GB standard publications, and vehicle production databases. Bottom-up roadside unit installation counts and top-down C-V2X module revenue estimates triangulate market sizing.
Calibration against historical DSRC deployment trajectories and C-V2X pilot program scale-up patterns shapes the analytical framework across the projection horizon. Segmentation dimensions include product architecture, radio protocol generation, application latency tier, end-user procurement model, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and new vehicle program integration rates. Forecast inputs incorporate 5G network densification timelines and spectrum reallocation proceeding outcomes.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by semiconductor foundries would shift outcomes. Forecasts reflect documented assumptions on regulatory mandate enforcement pacing and cross-certification timeline harmonization. Macroeconomic contraction affecting municipal infrastructure budgets, unilateral spectrum reallocation decisions, or DSRC technical obsolescence acceleration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Transportation Predictive Analytics Market
Smart Transportation Solutions
Parking Space Management Market
Smart Transportation Solutions
Automated Parking Systems Market
Smart Transportation Solutions
Europe Hyperloop Technology Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Road Weather Information Systems (RWIS) Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Automotive Digital Mapping Market
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Europe Bike Sharing Market
Smart Transportation Solutions
Intelligent Traffic Management Market
Smart Transportation Solutions
Fleet Management Solution Market
Smart Transportation Solutions
Ride-Hailing Market