
 Europe Electronic Toll Collection Market | 2026-2036
Europe Electronic Toll Collection Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electronic Toll Collection Market Intelligence
Project finance for large-scale highway concession contracts is narrowing the field of viable competitors to firms with balance sheet capacity and sovereign-backed guarantees. Kapsch TrafficCom leverages its integrated GNSS and DSRC technology stack to anchor multi-country interoperability frameworks. Siemens Mobility sustains competitive positioning through manufacturing scale across signaling and traffic management verticals. Toll Collect GmbH dominates the German heavy-goods vehicle segment with specialized on-board unit deployment expertise.
Electronic toll collection encompasses automated systems that identify vehicles and collect fees without requiring traffic flow interruption, typically employing microwave radio frequency communication at 5.8 GHz or satellite positioning with roadside enforcement cameras for violation processing. The primary commercial purpose centers on revenue generation for infrastructure financing while reducing congestion externalities and enabling distance-based road user charging. DSRC and GNSS technologies lead current installed capacity across European trunk road networks, while video analytics represents the fastest-expanding segment as jurisdictions retrofit existing gantries for plate-based enforcement without mandating on-board units. Cloud-based deployment models are capturing margin pools previously held by on-premises infrastructure, particularly among mid-sized toll operators seeking operational expenditure flexibility.
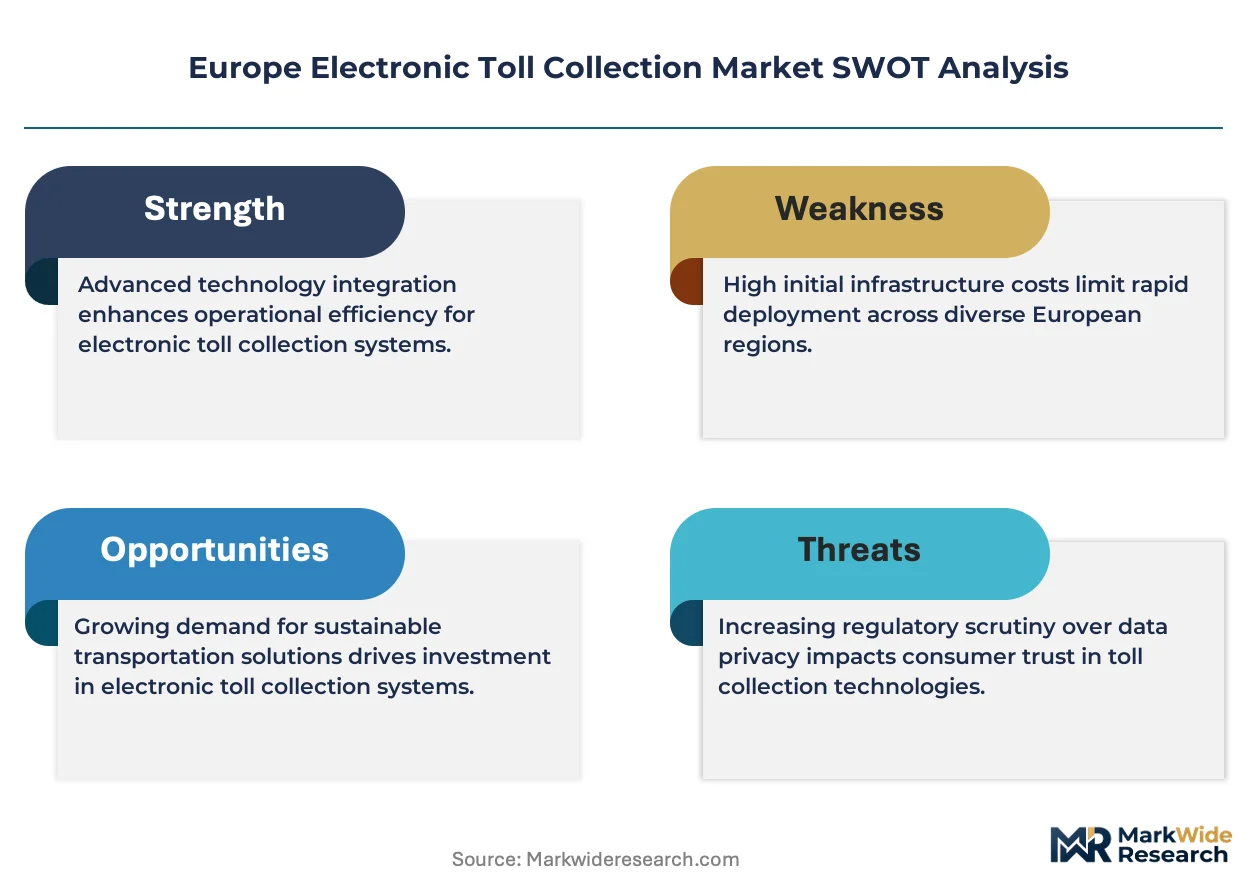
EU Green Deal mobility targets, the F-Gas Regulation affecting roadside equipment refrigerants, and CE marking requirements for radio equipment reshape product standards and cross-border market access for system integrators. ECHA chemical restrictions and national data protection authorities applying GDPR to vehicle movement databases further constrain solution architecture choices. Stakeholders must monitor pending revisions to the Eurovignette Directive and emerging member state congestion pricing pilots to anticipate interoperability mandate timelines and certification burden shifts.
Market Dynamics
The EU Green Deal's mobility decarbonization mandates are forcing interoperability requirements across member states, compressing deployment timelines for multi-lane free-flow tolling systems while reshaping vendor qualification criteria around cross-border certification.
Growth Catalysts
- EU Green Deal mandates:The framework's 55% emissions reduction target by 2030 accelerates distance-based road user charging adoption across freight corridors. Member states retrofit existing infrastructure to capture vehicle emissions data through tolling platforms.
- Germany's heavy-goods vehicle density:The country's position as Europe's largest freight transit hub sustains demand for specialized on-board unit deployment and enforcement camera networks along the A2 and A9 corridors.
- Video analytics retrofit:Jurisdictions deploy plate-based enforcement without mandating on-board units, expanding addressable infrastructure for mid-sized toll operators seeking capex-light deployment paths.
Market Restraints
- DSRC-GNSS interoperability friction:Technical fragmentation between microwave radio frequency and satellite positioning standards forces dual-stack equipment procurement, inflating system integration costs for cross-border operators.
- ECHA chemical restrictions:Roadside equipment manufacturers face reformulation requirements for refrigerants and flame-retardant compounds under REACH Annex XVII, compressing component supplier margins.
- Sovereign-backed financing concentration:Large-scale highway concession contracts narrow viable competitors to firms with balance sheet capacity, excluding specialized technology vendors from turnkey deployment opportunities.
Strategic Opportunities
- Urban congestion pricing pilots:Milan, Stockholm, and London-style schemes are proliferating across Italian and French metropolitan areas, creating demand for geofencing-capable GNSS enforcement without physical gantry infrastructure.
- Cloud-based deployment models:Mid-sized toll operators in Spain and Portugal migrate from on-premises infrastructure to operational expenditure-flexible architectures, capturing margin pools previously held by legacy system integrators.
- F-Gas Regulation retrofit cycle:The 2024-2030 phasedown of hydrofluorocarbon refrigerants forces roadside equipment replacement, opening upgrade windows for video analytics integration and edge computing deployment.
Industry Challenges
- GDPR-compliant vehicle movement databases:National data protection authorities in France, Germany, and Italy impose divergent consent and retention requirements, fragmenting cloud architecture standards across otherwise unified tolling networks.
- Legacy gantry integration complexity:Retrofitting existing microwave-based infrastructure with camera enforcement and edge processing requires bespoke engineering for each installation site, constraining deployment velocity.
- Eurovignette Directive revision uncertainty:Pending amendments to distance-based charging rules for heavy goods vehicles delay procurement decisions among Central European operators awaiting tariff structure clarity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electronic Toll Collection Market |
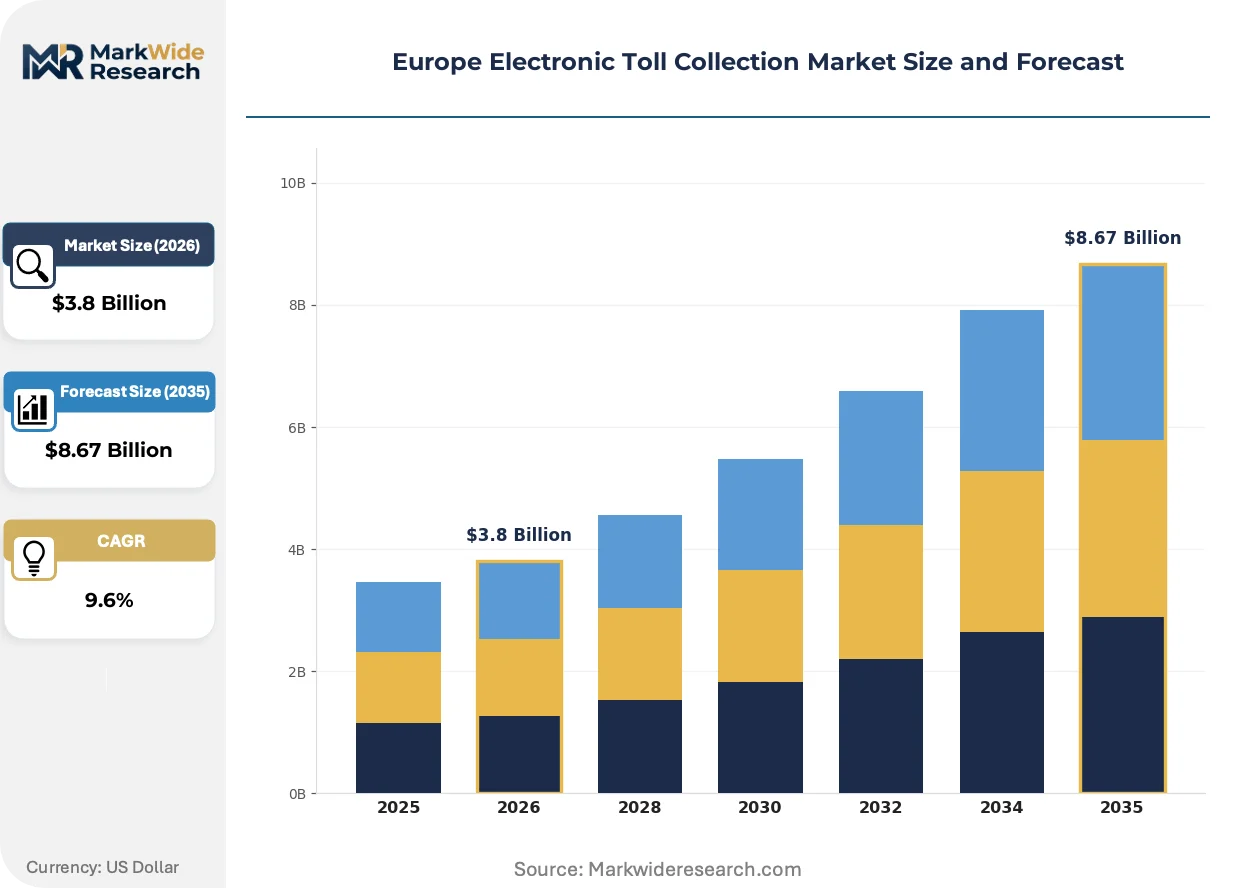
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GNSS, DSRC, RFID, Video Analytics Deployment Model: On-Premises, Cloud-Based, Hybrid, Mobile End User: Government, Transportation Agencies, Toll Operators, OEMs Service Type: Consulting, System Integration, Operation, Maintenance |
| Companies Covered | Conduent Inc., Toll Collect GmbH, Kapsch TrafficCom, Egis Group, TransCore, Siemens Mobility, Q-Free ASA, Neology, Thales Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electronic Toll Collection Market Strategic Shifts & Innovations
Video analytics with automatic number plate recognition is collapsing the traditional on-board unit dependency model, enabling jurisdiction-scale deployment without vehicle fleet equipment mandates. Cloud-native tolling platforms are compressing operational cost structures while regulatory pressure on roadside equipment refrigerants accelerates hardware replacement cycles.
Multi-sensor fusion architectures combining radar, lidar, and high-definition cameras are collapsing the functional role of dedicated roadside DSRC transceivers in enforcement-heavy deployments. French and Italian toll operators lead adoption, replacing legacy 5.8 GHz gantries with computer-vision-dominant systems on urban access routes. The shift compresses capital intensity per lane-kilometer while expanding violation capture rates beyond tag-based identification.
The F-Gas Regulation's phasedown schedule is forcing refrigerant-dependent roadside equipment replacement across Germany, Austria, and Benelux corridor infrastructure. Manufacturers redesign thermal management systems around natural refrigerants or passive cooling, triggering component supply chain requalification. The regulation most affects DSRC roadside units with sealed cooling loops, accelerating procurement timelines for video-analytics-first retrofit programs.
Freight operators and logistics platforms are consolidating toll service procurement through fleet management system integration rather than standalone on-board unit contracts. Large German and Dutch haulage associations negotiate enterprise-grade interoperability credentials directly with toll system aggregators, bypassing traditional equipment leasing channels. This pattern concentrates purchasing power among fleet telematics providers and compresses margins for standalone tag distributors in the heavy-goods vehicle segment.
Europe Electronic Toll Collection Market Segmentation
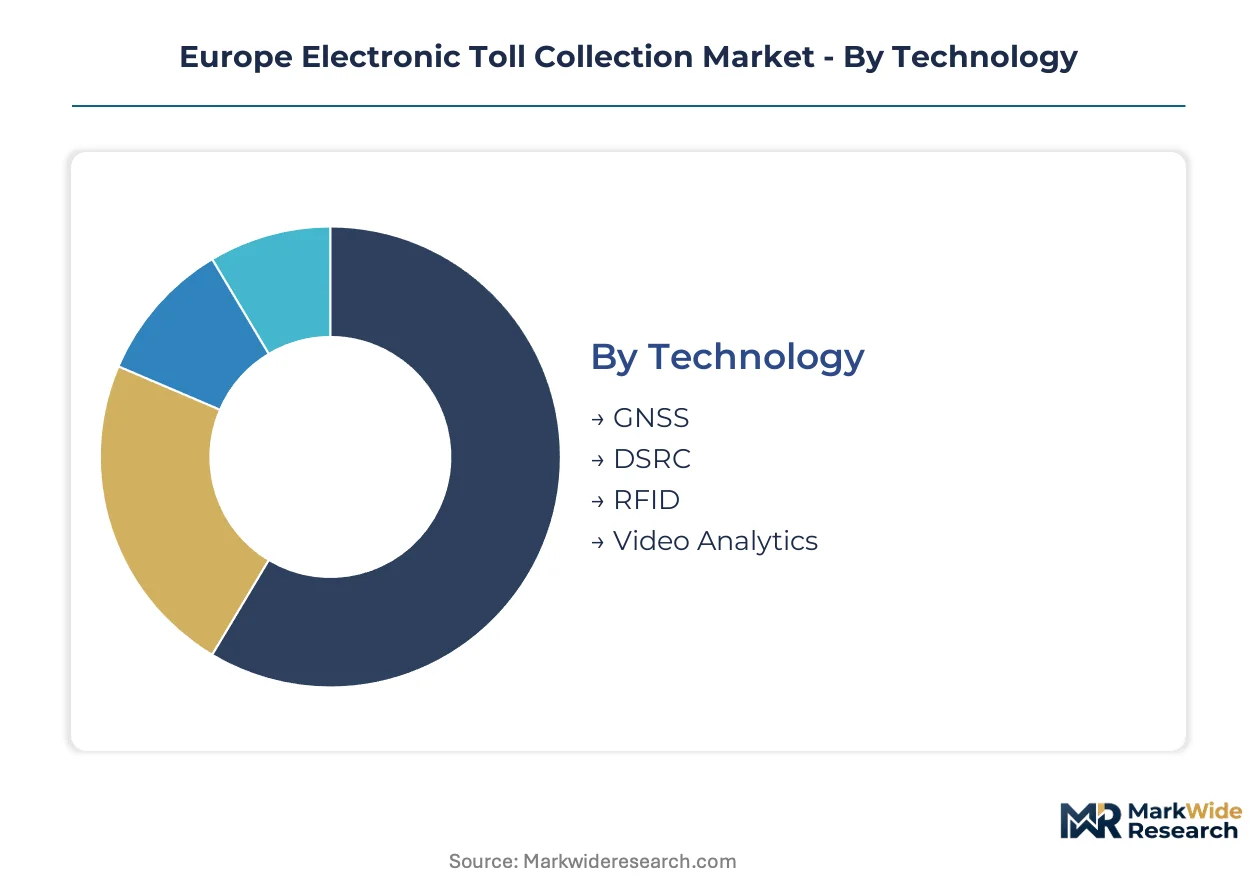
Technology and deployment architecture choices determine aftermarket service intensity across European tolling infrastructure. Maintenance contract duration, spare parts logistics, and software update cycles vary substantially by segment, reshaping vendor revenue stability and customer lifetime value calculations.
Technology:
After-sales-service intensity peaks with roadside equipment requiring refrigerant management, firmware updates, and calibration cycles against evolving enforcement standards.
- GNSS:Satellite positioning systems integrate on-board units with geofencing algorithms for distance-based charging without physical infrastructure. French and Italian operators deploy GNSS-dominant architectures on urban access routes where gantry installation faces spatial constraints.
- DSRC:Dedicated Short-Range Communication operates at 5.8 GHz microwave frequency with roadside transceivers and vehicle-mounted tags. Germany's A2 and A9 freight corridors sustain DSRC demand through proven interoperability with legacy heavy-goods vehicle on-board units and established enforcement protocols.
- RFID:Radio-frequency identification enables low-cost tag-based tolling for closed-system applications with limited cross-border requirements. RFID concentrates in parking integration and campus access control rather than trunk road networks.
- Video Analytics:Automatic number plate recognition systems collapse on-board unit dependency through camera-dominant enforcement. Spain and Portugal operators favor video analytics retrofits for capex-light expansion of existing gantry infrastructure.
By volume, DSRC leads. By growth pace, Video Analytics is ahead.
Deployment Model:
Capital structure preferences across government and private toll operators segment procurement patterns between ownership-heavy and operational expenditure-flexible arrangements.
- On-Premises:Traditional infrastructure ownership with dedicated data centers and physical server installations. German and Austrian federal agencies maintain on-premises requirements for sovereignty-sensitive vehicle movement databases.
- Cloud-Based:Subscription architectures transferring hardware risk to platform providers while enabling elastic capacity scaling. Mid-sized toll operators in Iberia and Benelux migrate fastest to cloud-native tolling platforms.
- Hybrid:Mixed architectures retaining critical enforcement functions on-site while offloading analytics and billing to cloud instances. Hybrid models dominate Eurovignette-compliant cross-border corridors requiring local data residency for violation processing.
- Mobile:Smartphone-based tolling applications eliminating dedicated on-board unit procurement for light vehicle segments. Mobile deployment expands in Italian urban congestion zones with app-store distribution replacing tag distribution logistics.
Cloud-Based deployment shows the steepest expansion trajectory as operational expenditure flexibility displaces capital-intensive procurement cycles.
End User:
Procurement authority concentration varies from centralized transport ministries to fragmented municipal operators, reshaping sales cycle duration and contract negotiation complexity.
- Government:National transport ministries and federal road agencies with sovereign-backed financing capacity. Government procurement in Germany and France anchors multi-billion euro concession frameworks with decade-long service attachments.
- Transportation Agencies:Regional and state-level authorities managing specific corridor segments or metropolitan networks. Italian regional agencies drive urban congestion pricing pilot procurement with localized technical specifications.
- Toll Operators:Private concession holders and public-private partnerships with revenue-risk exposure. Toll Operators in Spain and Portugal prioritize cloud deployment to align technology costs with traffic volume volatility.
- OEMs:Vehicle manufacturers integrating tolling capability into factory-installed telematics systems. German and Dutch commercial vehicle OEMs consolidate fleet interoperability credentials through direct toll system aggregator partnerships.
Government contracts dominate absolute revenue. Toll Operators are gaining share fastest through concession privatization trends.
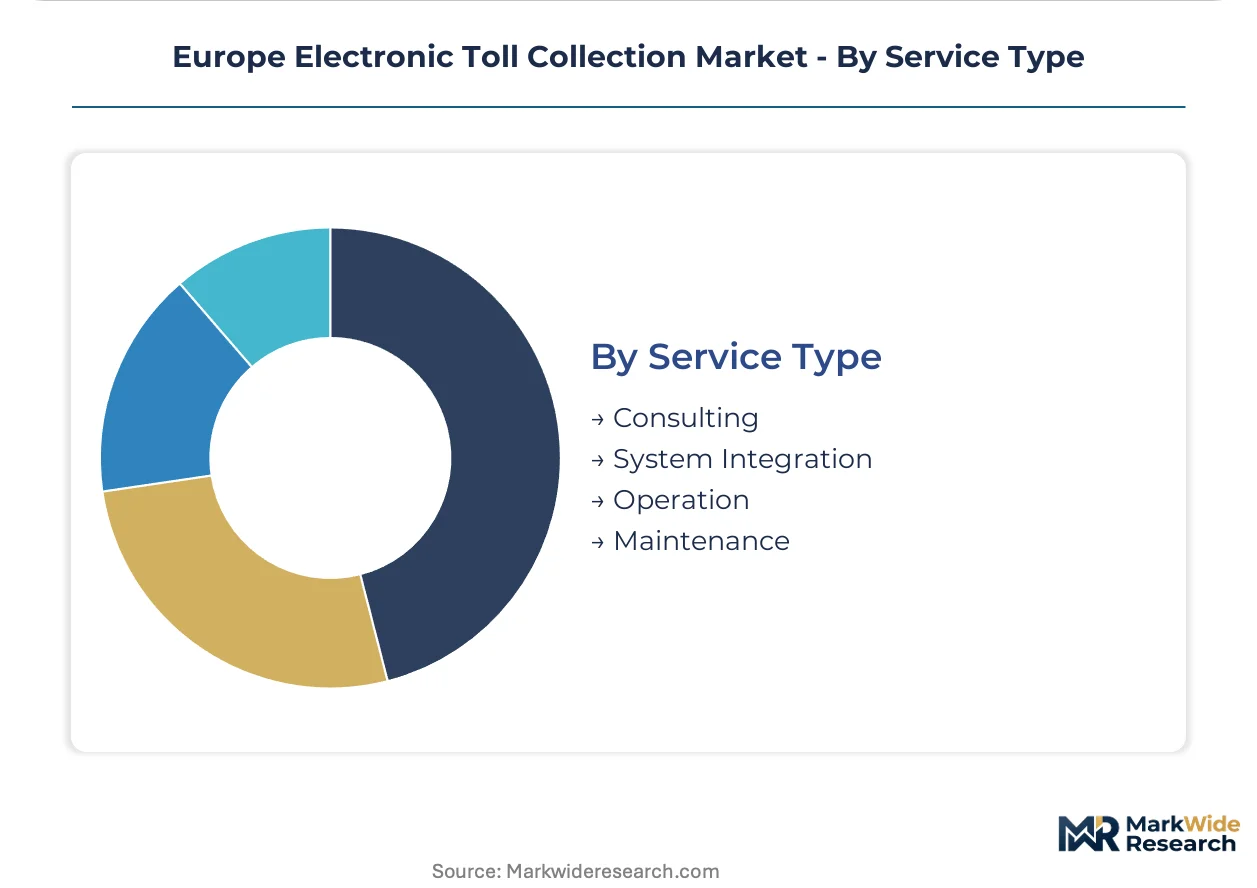
Service Type:
Margin concentration shifts from upfront system integration toward recurring operation and maintenance as installed base maturity extends across European networks.
- Consulting:Regulatory compliance advisory and interoperability framework design for cross-border deployment. Consulting demand concentrates around Eurovignette Directive revision preparation and GDPR-compliant data architecture planning.
- System Integration:Turnkey deployment of roadside equipment, back-office platforms, and enforcement infrastructure. System Integration revenue clusters in Germany's heavy-goods vehicle network expansion and French urban access route retrofit programs.
- Operation:Continuous transaction processing, revenue reconciliation, and customer account management. Operation services expand most quickly under cloud-based deployment models where vendors retain functional responsibility.
- Maintenance:Preventive servicing, refrigerant system replacement under F-Gas Regulation, and hardware lifecycle management. Maintenance contracts lengthen as roadside equipment replacement cycles synchronize with video analytics upgrade windows.
System Integration captures the largest revenue pool. Operation services are climbing the fastest as cloud migration transfers functional responsibility to vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's mobility decarbonization mandates are compressing deployment timelines for multi-lane free-flow tolling systems while forcing cross-border interoperability across member states.
Germany
Germany's A2 and A9 freight corridors sustain concentrated demand for heavy-goods vehicle tolling infrastructure. The Federal Transport Authority enforces distance-based road user charging under the Eurovignette Directive framework. Toll Collect GmbH anchors on-board unit deployment expertise from its Berlin and Munich operational bases.
France
French metropolitan areas are proliferating urban congestion pricing pilots modeled on London and Stockholm schemes. The CNIL applies divergent GDPR consent requirements to vehicle movement databases. Paris and Lyon lead geofencing-capable GNSS enforcement deployment without physical gantry infrastructure.
Italy
Italian regional agencies drive localized procurement for urban access route retrofit programs. ANSFISA certification requirements reshape product standards for cross-border market access. Milan anchors congestion zone expansion with smartphone-based tolling applications replacing tag distribution logistics.
Spain
Spanish toll operators prioritize cloud-native migration to align technology costs with traffic volume volatility. The F-Gas Regulation's refrigerant phasedown forces roadside equipment replacement across Iberian corridor infrastructure. Madrid and Barcelona concentrate video analytics retrofit programs for capex-light gantry expansion.
Netherlands
Dutch haulage associations negotiate enterprise-grade interoperability credentials directly with toll system aggregators. The Benelux corridor sustains hybrid deployment models requiring local data residency for violation processing. Rotterdam and Amsterdam anchor fleet telematics integration bypassing traditional equipment leasing channels.
Europe Electronic Toll Collection Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structure consolidating around sovereign-backed financing capacity and cross-border certification authority. Large-scale highway concession contracts narrow viable competitors to firms with balance sheet depth, excluding specialized technology vendors from turnkey deployment opportunities. Three archetypes dominate: integrated technology stack providers, manufacturing-scale infrastructure builders, and cloud-native platform operators. Competitive moves concentrate on strategic partnerships for interoperability framework anchoring and portfolio diversification into video analytics retrofit services.
Within the integrated technology tier, Kapsch TrafficCom and Siemens Mobility occupy anchor positions. Kapsch TrafficCom exemplifies the GNSS-DSRC dual-stack specialist archetype, while Siemens Mobility represents manufacturing-scale vertical integration across signaling and traffic management. Toll Collect GmbH sits within the specialized on-board unit deployment segment, anchoring heavy-goods vehicle expertise in the German market. These three entities collectively illustrate how vendor qualification criteria now prioritize cross-border certification capacity over point-product innovation.
| Leading Market Players |
|---|
| Conduent Inc. |
| Toll Collect GmbH |
| Kapsch TrafficCom |
| Egis Group |
| TransCore |
| Siemens Mobility |
| Q-Free ASA |
| Neology |
| Thales Group |
| Others |
Cost & Logistics Intelligence
Component manufacturing for roadside DSRC transceivers and GNSS on-board units clusters in Germany, Austria, and the Czech Republic, anchoring margin capture among integrated technology stack providers while compressing specialized vendors into equipment-supply tiers. Cloud-native platform operators bypass this concentration through software-centric delivery, redistributing value toward operational expenditure-flexible architectures.
Pricing Analysis
Certification level under EU Green Deal interoperability mandates and CE marking for radio equipment creates the primary spread between premium and standard system tiers. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with premium tiers bundling cross-border certification and sovereign-backed financing guarantees. Cost compression in mid-sized operator segments is intensifying because cloud deployment alternatives eliminate upfront capital requirements. Government transport ministries exhibit lowest price sensitivity given concession financing capacity, while regional transportation agencies face acute budget constraints driving SaaS migration.
Supply Chain Analysis
Electronics manufacturing services for tolling hardware concentrate among German, Austrian, and Polish contract manufacturers with automotive-tier quality certifications. Critical component inputs include 5.8 GHz microwave transceiver modules, high-definition camera sensors, and edge computing processors for video analytics. Single-source vulnerability runs through specialized refrigerant-dependent thermal management systems facing F-Gas Regulation phasedown. Distribution runs through direct vendor-operator contracts for turnkey deployments and aggregator platforms for fleet-integrated procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's electronic toll collection sector sits in early-cycle expansion as urban congestion pricing pilots and freight corridor retrofit programs accelerate adoption beyond traditional highway concessions. Video analytics and cloud-native deployment models are compressing legacy infrastructure replacement timelines.
For Market Incumbents: Insulate core concession relationships through backward integration into video analytics retrofit services and edge computing deployment. Threat substitution from smartphone-based tolling applications in Italian urban zones demands rapid certification investment for geofencing-capable GNSS enforcement. Priority lever centers on anchoring multi-country interoperability frameworks before regulatory mandates crystallize. For New Entrants and Emerging Players: Mid-sized toll operators in Iberia and Benelux represent the most penetrable entry point given their operational expenditure flexibility requirements and cloud migration urgency. Spanish and Portuguese operators specifically seek capex-light expansion paths for existing gantry infrastructure. Go-to-market angle should emphasize subscription-based video analytics integration with rapid deployment timelines under F-Gas Regulation replacement windows. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed toll system aggregators holding fleet telematics integration capabilities. Long-term viability hinges on consolidation of interoperability credentials across Eurovignette-compliant corridors. Signal to watch is pending Eurovignette Directive revision clarity triggering procurement acceleration among Central European operators.| Strategic Initiative | Industry Significance |
|---|---|
| Video Analytics Retrofit Integration | Collapses on-board unit dependency for Spanish and Portuguese operators seeking capex-light expansion. |
| Cloud-Native Platform Migration | Captures margin pools from legacy system integrators among mid-sized Iberian toll operators. |
| Multi-Country Interoperability Anchoring | Locks in vendor positioning ahead of EU Green Deal cross-border certification mandates. |
| Fleet Telematics System Partnership | Consolidates purchasing power among German and Dutch haulage associations bypassing tag distributors. |
| Edge Computing Deployment | Enables real-time violation processing for French and Italian urban congestion pricing pilots. |
Research Approach
A spread of perspectives from toll system operators, fleet telematics providers, transportation agency procurement officers, and roadside equipment manufacturers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against EU regulatory filings, national transport ministry procurement records, F-Gas Regulation implementation timelines, and GDPR enforcement precedents from CNIL and German data protection authorities. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the analysis window.
Demand-supply balance dynamics shaped the forecast framework, with modeled dimensions spanning technology type, deployment architecture, end-user procurement authority, and service intensity. Segmentation incorporated GNSS-DSRC interoperability requirements, cloud migration velocity, and sovereign-backed financing availability as industry-specific forecast inputs. CAGRs were derived from installed base expansion rates and replacement cycle synchronization with regulatory compliance deadlines.
Practitioners should monitor Eurovignette Directive revision progress, F-Gas Regulation enforcement intensity, and GDPR consent requirement divergence across member states for early signals of forecast revision. Quarterly review of procurement announcement flows, interoperability certification timelines, and fleet telematics partnership disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Europe Passenger Information System Market
Smart Transportation Solutions
Intelligent Traffic Management Market
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Parking Finder Apps Market
Smart Transportation Solutions
Middle East and Africa Passenger Information System Market
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Global Smart Parking Solutions Market
Smart Transportation Solutions
Alternate Transportation Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
E-Scooter Sharing Market
Smart Transportation Solutions
Europe Car Parking Market