
 Data Processing Neuromorphic Chip Market | 2026-2036
Data Processing Neuromorphic Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Data Processing Neuromorphic Chip Market Outlook
The EU AI Act is restructuring compliance burdens for neuromorphic chip vendors selling into European edge-AI deployments. Intel Corporation leverages its Loihi program to sustain research leadership in spiking neural network architectures. BrainChip Holdings Ltd. anchors its competitive position through low-power Akida processors purpose-built for on-device inference.
Data processing neuromorphic chips integrate memristive crossbar arrays with asynchronous digital logic to mimic biological synaptic plasticity, typically operating below one milliwatt per synaptic operation for event-driven computation. Their primary commercial purpose centers on real-time pattern recognition in power-constrained environments where conventional von Neumann architectures face thermal and latency ceilings. Digital chips currently dominate production volumes due to compatibility with existing CMOS foundry infrastructure, while photonic chips represent the fastest-growing category as silicon photonics matures for optical interconnect bandwidth. Edge computing applications command the deepest margin pools because end users in automotive and aerospace sectors pay premiums for deterministic latency guarantees.
FDA scrutiny of AI-enabled medical devices is tightening validation requirements for neuromorphic chips deployed in implantable diagnostics and surgical robotics. The EPA's emerging e-waste rules for embedded electronics are pressuring designers toward recyclable packaging and reduced rare-earth content in analog memristor formulations. NHTSA's evolving autonomous vehicle safety standards are creating compliance gateways that favor chips with explainable inference pathways over black-box accelerators. Stakeholders must monitor which regulatory body moves first on mandatory energy-efficiency labeling for edge-AI hardware, as this will reshape procurement criteria across healthcare, automotive, and consumer electronics supply chains.
Market Dynamics
Edge-AI deployment mandates from automotive and aerospace OEMs are compressing latency requirements below 10 milliseconds, forcing neuromorphic architectures to displace GPU-based inference in power-constrained nodes. This demand pull is restructuring foundry priorities and software toolchain investments across the supply base.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Explainable inference requirements in European edge deployments favor neuromorphic chips with traceable spike-based computation over black-box accelerators, creating procurement preference in Germany's automotive corridor.
- Memristive crossbar integration:Analog synaptic arrays now achieve sub-milliwatt per operation efficiency, enabling always-on pattern recognition in battery-powered medical implants and satellite payloads.
- Dresden-Munich research concentration:Germany's semiconductor cluster anchors EU-funded neuromorphic pilot lines, accelerating tape-out cycles for event-driven processors targeting industrial robotics.
Market Restraints
- TSMC capacity allocation:Advanced node wafers for mixed-signal neuromorphic designs compete with AI GPU demand, stretching lead times for startups lacking volume commitments.
- Analog memristor yield variability:Resistance drift in oxide-based synaptic devices limits batch-to-batch consistency, constraining commercial deployment of large-scale crossbar arrays.
- Spiking neural network software immaturity:The absence of standardized training frameworks comparable to PyTorch or TensorFlow slows enterprise adoption outside research environments.
Strategic Opportunities
- India PLI scheme for semiconductor manufacturing:Domestic packaging and testing incentives attract neuromorphic fabless designers seeking geographic diversification beyond East Asian foundry concentration.
- Photonic-neuromorphic convergence:Silicon photonics integration with electronic spiking arrays enables terabit-scale optical interconnect bandwidth for data center inference accelerators.
- NHTSA autonomous vehicle safety standard evolution:Deterministic latency certification pathways create qualification gateways favoring event-driven chips over probabilistic GPU inference in L4-L5 automotive systems.
Industry Challenges
- Spiking neural network compiler expertise scarcity:The intersection of neuroscience, mixed-signal design, and embedded software engineering concentrates talent at fewer than a dozen academic and corporate labs worldwide.
- FDA 510(k) validation timelines for implantable neuromorphic diagnostics:Biocompatibility testing and long-term reliability studies extend approval cycles beyond typical semiconductor product lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Processing Neuromorphic Chip Market |
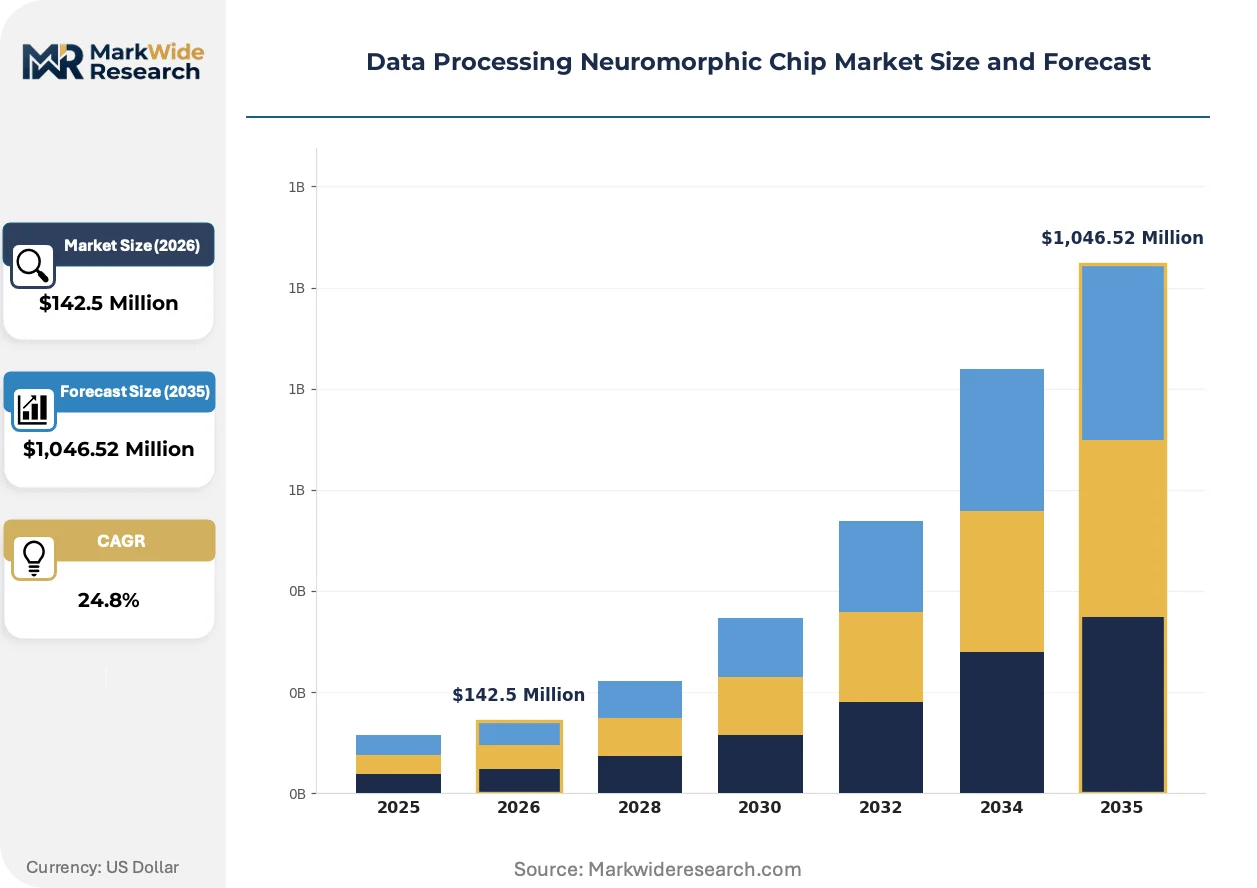
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $1,046.52 Million |
| CAGR (2026 – 2036) | 24.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Chip Type: Digital Chips, Analog Chips, Hybrid Chips, Photonic Chips Application: Robotics, Real-Time Processing, AI Inference, Edge Computing End User: Aerospace, Healthcare, Automotive, Consumer Electronics Connection Type: Wired, Wireless, Bluetooth, Ethernet |
| Companies Covered | Intel Corporation, IBM, Samsung Electronics Co., Ltd., Qualcomm Technologies, Inc., BrainChip Holdings Ltd., Hewlett Packard Enterprise, SK hynix Inc., Sony Corporation, HRL Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Processing Neuromorphic Chip Market Strategic Shifts
Silicon photonics maturation and event-driven architecture refinement are compressing the efficiency-latency tradeoff that previously constrained edge-AI deployment. These technical advances are enabling new application categories previously inaccessible to conventional accelerators.
Memristive analog arrays with integrated CMOS periphery are unifying synaptic storage and computation in single-crossbar architectures. Aerospace satellite operators now specify these devices for on-orbit pattern recognition requiring sub-watt operation. The technology is unifying previously separate memory and processing supply chains into single-die or 3D-stacked configurations.
EPA emerging e-waste regulations for embedded electronics are mandating recyclable packaging and reduced rare-earth content in analog memristor formulations. Designers are reformulating hafnium-oxide synaptic devices toward earth-abundant alternatives. Medical implant manufacturers face the steepest compliance redesign costs given biocompatibility constraints on material substitutions.
Automotive OEM procurement teams now require deterministic latency guarantees with formal verification certificates before qualifying neuromorphic inference engines. Tier-1 suppliers are disintermediating traditional semiconductor distributors to establish direct foundry relationships for traceability documentation. This behavioral shift is most visible in Germany's automotive semiconductor procurement corridors around Stuttgart and Ingolstadt.
Data Processing Neuromorphic Chip Market Segmentation
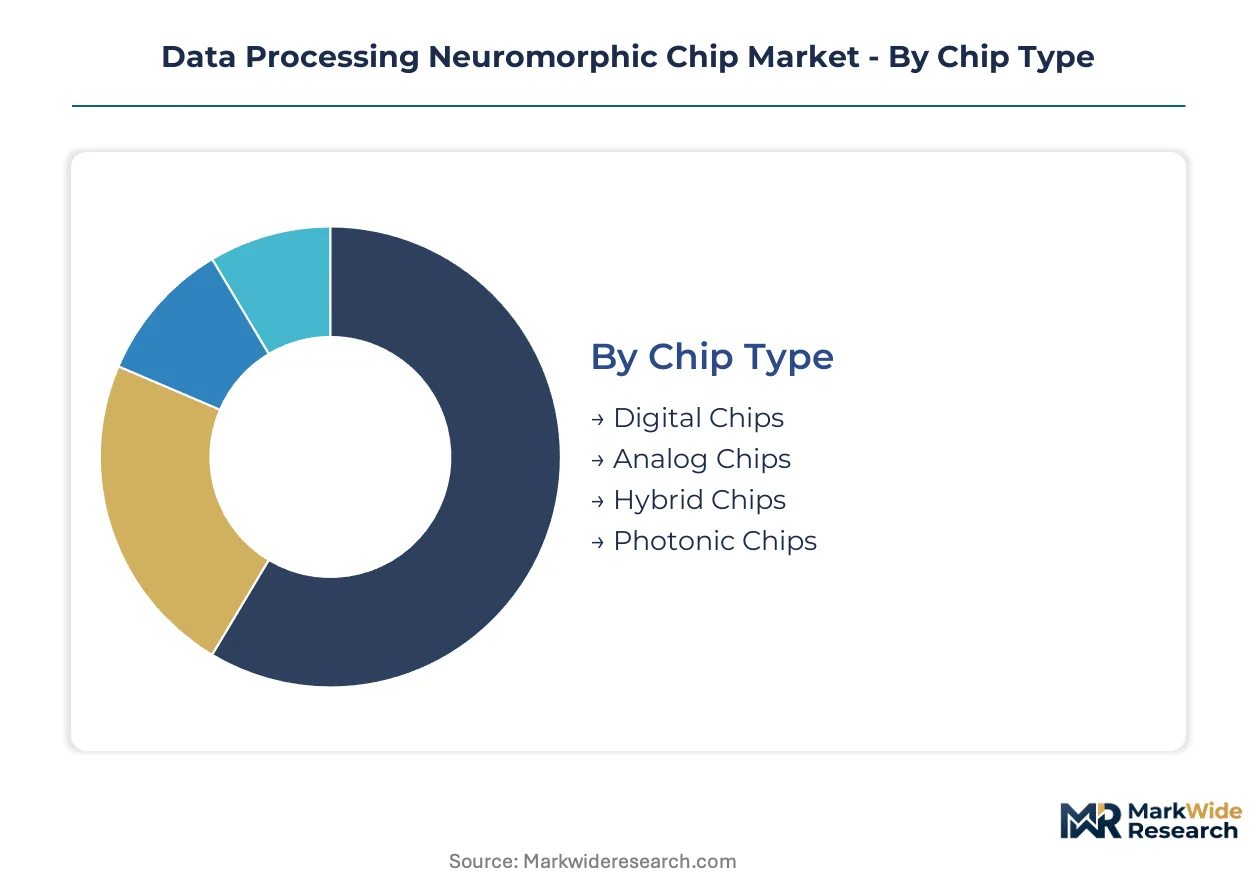
Neuromorphic chip procurement decisions hinge on power budgets, latency floors, and foundry compatibility. Each segmentation dimension reveals distinct buyer priorities across aerospace, automotive, and medical implant deployments.
Chip Type:
Foundry compatibility and power-performance tradeoffs dominate vendor selection.
- Digital Chips:CMOS-compatible architectures leverage existing TSMC and GlobalFoundries capacity for event-driven logic with deterministic timing. Automotive OEMs in Germany's Stuttgart corridor specify these for L4 autonomy subsystems requiring ISO 26262 traceability. Volume sits with Digital Chips; growth tilts toward Photonic Chips.
- Analog Chips:Memristive crossbar arrays execute in-situ matrix multiplication with sub-milliwatt per synaptic operation efficiency. Resistance drift in hafnium-oxide devices constrains batch consistency for FDA-regulated implantable diagnostics.
- Hybrid Chips:Mixed-signal designs integrate digital periphery with analog synaptic cores for medical edge-AI requiring programmable precision.
- Photonic Chips:Silicon photonics spiking arrays enable terabit optical interconnect bandwidth for data center inference accelerators.
Process maturity separates commercial volume from pilot-line prototypes.
Application:
Latency requirements and power envelopes determine architecture fit.
- Edge Computing:Always-on pattern recognition in battery-constrained nodes demands sub-milliwatt standby power. NHTSA deterministic latency mandates favor event-driven chips over GPU inference in automotive sensor fusion modules.
- AI Inference:On-device classification without cloud round-trips protects data sovereignty under EU AI Act transparency requirements. Aerospace satellite operators specify these for on-orbit autonomy with strict thermal budgets.
- Robotics:Closed-loop motor control with sub-10ms feedback loops drives spiking network adoption in industrial automation.
- Real-Time Processing:Microsecond-latency signal conditioning for financial trading and defense applications.
Edge Computing commands the deepest margin pools; Real-Time Processing remains niche.
End User:
Regulatory exposure and certification timelines reshape procurement patterns.
- Automotive:Tier-1 suppliers bypass distributors for direct foundry relationships to secure traceability documentation under evolving NHTSA safety standards. Stuttgart and Ingolstadt procurement corridors lead qualification volumes.
- Healthcare:FDA 510(k) validation cycles for implantable neuromorphic diagnostics extend beyond typical semiconductor lifecycles, favoring established vendors with regulatory affairs capacity.
- Aerospace:Satellite operators specify sub-watt operation for on-orbit pattern recognition with radiation-hardened packaging.
- Consumer Electronics:Cost-sensitive wearables drive demand for lowest-unit-cost digital event-driven cores.
Automotive generates the steepest expansion trajectory; Consumer Electronics anchors unit volume.
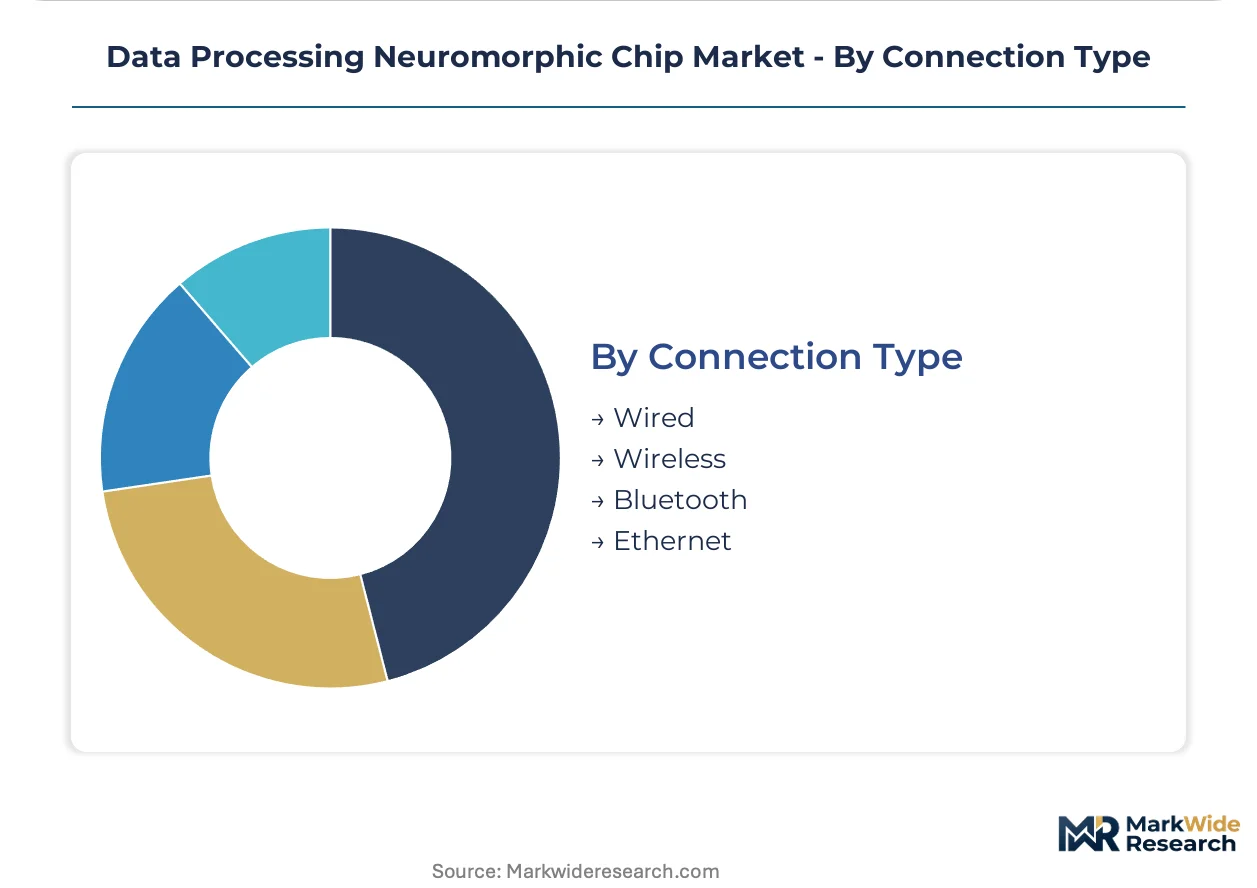
Connection Type:
Interconnect bandwidth and electromagnetic compatibility govern physical layer selection.
- Ethernet:Deterministic time-sensitive networking for industrial robotics and automotive backbone architectures.
- Wireless:Ultra-wideband and 5G NR integration for mobile edge-AI with mobility requirements.
- Bluetooth:Low-energy protocols for medical wearables with smartphone tethering.
- Wired:Galvanically isolated SPI and I2C for implantable devices requiring biocompatibility.
Ethernet dominates industrial deployments; Wireless is gaining share fastest in mobile robotics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for semiconductor manufacturing is attracting neuromorphic fabless designers seeking geographic diversification beyond East Asian foundry concentration.
United States
NHTSA's evolving autonomous vehicle safety standards create compliance gateways favoring explainable inference pathways. FDA scrutiny tightens validation requirements for AI-enabled medical devices with neuromorphic chips in implantable diagnostics. Silicon Valley and Greater Boston anchor R&D clusters for spiking neural network compiler development.
Germany
EU AI Act algorithmic transparency mandates favor traceable spike-based computation in automotive edge deployments. KBA certification requirements intersect with evolving EU Green Deal sustainability standards for embedded electronics. The Dresden-Munich semiconductor corridor concentrates EU-funded neuromorphic pilot lines for industrial robotics.
China
MIIT's dual carbon goals pressure designers toward energy-efficient edge-AI architectures. SAMR standards for algorithmic recommendation systems create compliance frameworks for on-device inference chips. The Yangtze River Delta clusters domestic foundry capacity for mixed-signal neuromorphic tape-outs.
South Korea
MFDS medical device regulations extend validation timelines for implantable neuromorphic diagnostics beyond typical semiconductor lifecycles. METI-aligned export control frameworks shape technology transfer for spiking neural network architectures. The Seoul Capital Area concentrates memory-semiconductor giants diversifying into neuromorphic crossbar arrays.
Japan
PMDA's emerging guidance on AI-enabled surgical robotics creates certification pathways for deterministic latency chips. METI's semiconductor revitalization strategy funds domestic pilot lines for event-driven processors. The Nagoya-Tokyo corridor integrates automotive OEM procurement with neuromorphic sensor fusion development.
Data Processing Neuromorphic Chip Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the neuromorphic chip landscape. The vendor base stratifies into three tiers: diversified memory-semiconductor conglomerates with neuromorphic R&D divisions, established computing hardware vendors with spiking neural network programs, and venture-backed fabless startups targeting edge-AI niches. Strategic moves concentrate on foundry partnership negotiations for advanced node allocation and compiler toolchain acquisitions to address software immaturity barriers.
Within the diversified technology tier, Intel Corporation and IBM occupy positions representing legacy computing vendors with sustained research commitments to neuromorphic architectures. Samsung Electronics Co., Ltd. anchors the memory-semiconductor conglomerate archetype, exemplifying vertical integration strategies spanning foundry capacity through system-level deployment. These three entities represent distinct competitive postures: research leadership through university partnerships, captive manufacturing scale, and cross-divisional technology leverage respectively.
| Leading Market Players |
|---|
| Intel Corporation |
| IBM |
| Samsung Electronics Co., Ltd. |
| Qualcomm Technologies, Inc. |
| BrainChip Holdings Ltd. |
| Hewlett Packard Enterprise |
| SK hynix Inc. |
| Sony Corporation |
| HRL Laboratories |
| Others |
Value Chain & Pricing Dynamics
Spiking neural network compiler expertise concentrated in Silicon Valley and Greater Boston creates labor-cost differentials that widen pricing-tier spreads between premium certified solutions and economy digital alternatives. The scarcity of mixed-signal design talent tethers pricing power to geographic access, with Dresden-Munich corridor vendors commanding premiums for EU AI Act-compliant traceability documentation.
Pricing Analysis
Lead-time-driven pricing angles dominate neuromorphic chip procurement, with automotive OEMs paying premiums for sub-10 millisecond guaranteed delivery against FDA 510(k) validation timelines while spot inventory of digital event-driven cores trades at discounts. A three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-traceable automotive subsystems from consumer wearable digital cores. Cost compression in economy tiers is intensifying because TSMC capacity allocation favors AI GPU commitments over mixed-signal neuromorphic startups. Consumer electronics buyers exhibit highest price sensitivity; aerospace satellite operators show least sensitivity given sub-watt operation mandates.
Supply Chain Analysis
Reverse-logistics flows for analog memristor arrays remain underdeveloped, with hafnium-oxide device refurbishment constrained by resistance drift variability that limits remanufacturing yields. Foundry supply concentrates in Taiwan, South Korea, and the United States, with TSMC and Samsung Electronics anchoring advanced node capacity for mixed-signal designs. Raw material dependencies center on hafnium precursors, silicon photonics substrates, and rare-earth elements for synaptic formulations. Single-source vulnerability around TSMC's 7nm and below nodes creates structural risk for fabless neuromorphic designers lacking volume commitments. Distribution runs through direct foundry relationships that Tier-1 automotive suppliers are establishing to bypass traditional semiconductor distributors for traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
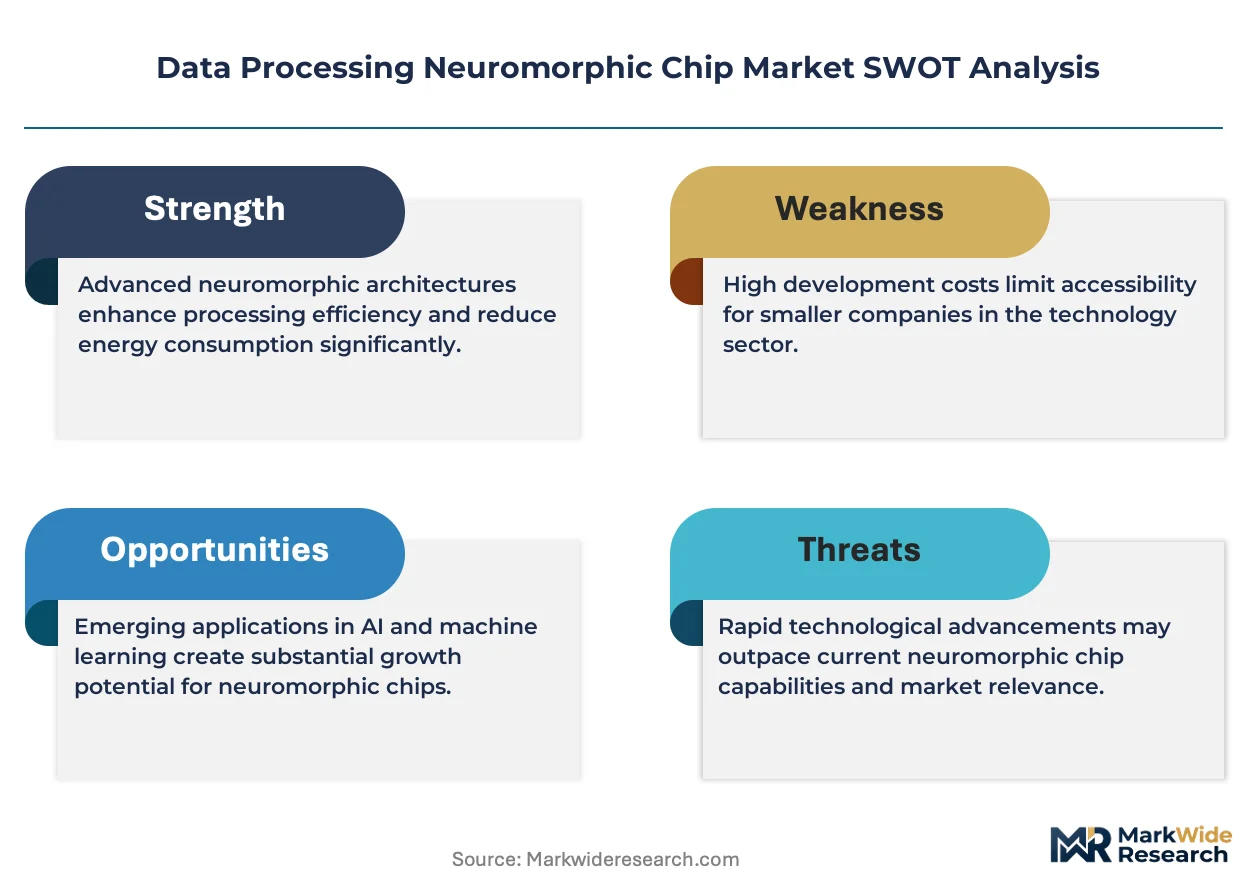
The EU AI Act's algorithmic transparency mandates construct a cost-of-compliance moat that favors established vendors with regulatory affairs capacity over capital-constrained entrants lacking certification infrastructure.
For Market Incumbents: Hedge against analog memristor yield variability by diversifying across digital event-driven architectures and photonic-neuromorphic convergence pathways. Acquire compiler toolchain assets to address spiking neural network software immaturity barriers before emerging fabless startups capture enterprise adoption outside research environments. Capacity expansion in India's PLI scheme corridors provides geographic diversification beyond East Asian foundry concentration.
For New Entrants and Emerging Players: Begin with industrial robotics edge-AI in Germany's automotive corridor, where EU-funded pilot lines accelerate tape-out cycles and procurement teams seek alternatives to GPU-based inference. Target medical implant diagnostics as a white-space opportunity given FDA validation timeline barriers that incumbent semiconductor vendors avoid. A go-to-market angle anchored to NHTSA deterministic latency certification pathways creates qualification gateways that favor event-driven chips over probabilistic accelerators.
For Investors and Strategic Acquirers: Re-rating potential sits with fabless neuromorphic specialists possessing compiler toolchain assets and EU AI Act compliance documentation given tightening algorithmic transparency requirements. Long-term viability in this market hinges on foundry partnership depth and regulatory certification velocity rather than pure technology differentiation. Monitor NHTSA autonomous vehicle safety standard evolution as the inflection indicator for automotive qualification volumes shifting from GPU to neuromorphic inference engines.
| Strategic Initiative | Industry Significance |
|---|---|
| Compiler Toolchain Acquisition | Addresses spiking neural network software immaturity barriers slowing enterprise adoption beyond research labs. |
| EU AI Act Compliance Certification | Creates procurement preference in Germany's automotive corridor under tightening algorithmic transparency mandates. |
| Foundry Partnership Negotiation | Secures advanced node allocation against AI GPU demand stretching lead times for volume-lacking startups. |
| Photonic-Neuromorphic Integration | Enables terabit-scale optical interconnect bandwidth for data center inference accelerators as silicon photonics matures. |
| India PLI Scheme Manufacturing Footprint | Attracts geographic diversification beyond East Asian foundry concentration for packaging and testing incentives. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced against primary interviews with neuromorphic chip design leads, automotive Tier-1 procurement officers, FDA regulatory affairs specialists, and foundry capacity planners. SEC 10-K disclosures from semiconductor conglomerates, EU funding program databases, NHTSA safety standard dockets, and customs import records for hafnium oxide precursors provided validation layers. Bottom-up unit economics from individual chip architectures reconciled with top-down market sizing across application segments.
Data-stream reconciliation between foundry capacity announcements, OEM procurement pipeline disclosures, and regulatory filing timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include chip type, application, end user, and connection type, with additional granularity on certification tier and geographic production cluster. CAGRs derived from installed base growth rates, replacement cycles for implantable diagnostics, and automotive autonomy subsystem penetration curves. Industry-specific forecast inputs encompassed TSMC capacity allocation schedules and EU pilot line funding disbursements.
Underlying measurement precision varies by segment; digital chip volumes carry tighter precision than analog memristor pilot-line outputs given yield variability uncertainties. Forecasts reflect assumptions on regulatory timeline adherence, foundry capacity expansion, and spiking neural network compiler maturity that could revise projections. Practitioners should monitor NHTSA safety standard finalization dates, FDA 510(k) approval velocity for implantable neuromorphic devices, and TSMC advanced node pricing announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
System on Chip (Soc) Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
Consumer Electronics Chip Market
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Multi-Core Processors Market
Chipset and Processors
Tablet Application Processor Market
Chipset and Processors
Neuromorphic Chip Market
Chipset and Processors
Power Over Ethernet (Poe) Chipsets Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Digital Signal Processor Market
Chipset and Processors
Americas Digital Signal Processor Market
Chipset and Processors
Asia Pacific Data Center Processor Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Surgical Chips Market
Chipset and Processors
South Korea Edge AI Processor Market