
 IGCT Market | 2026-2036
IGCT Market Size, Share, and Industry Trends Forecast 2026-2036
IGCT Market Analysis
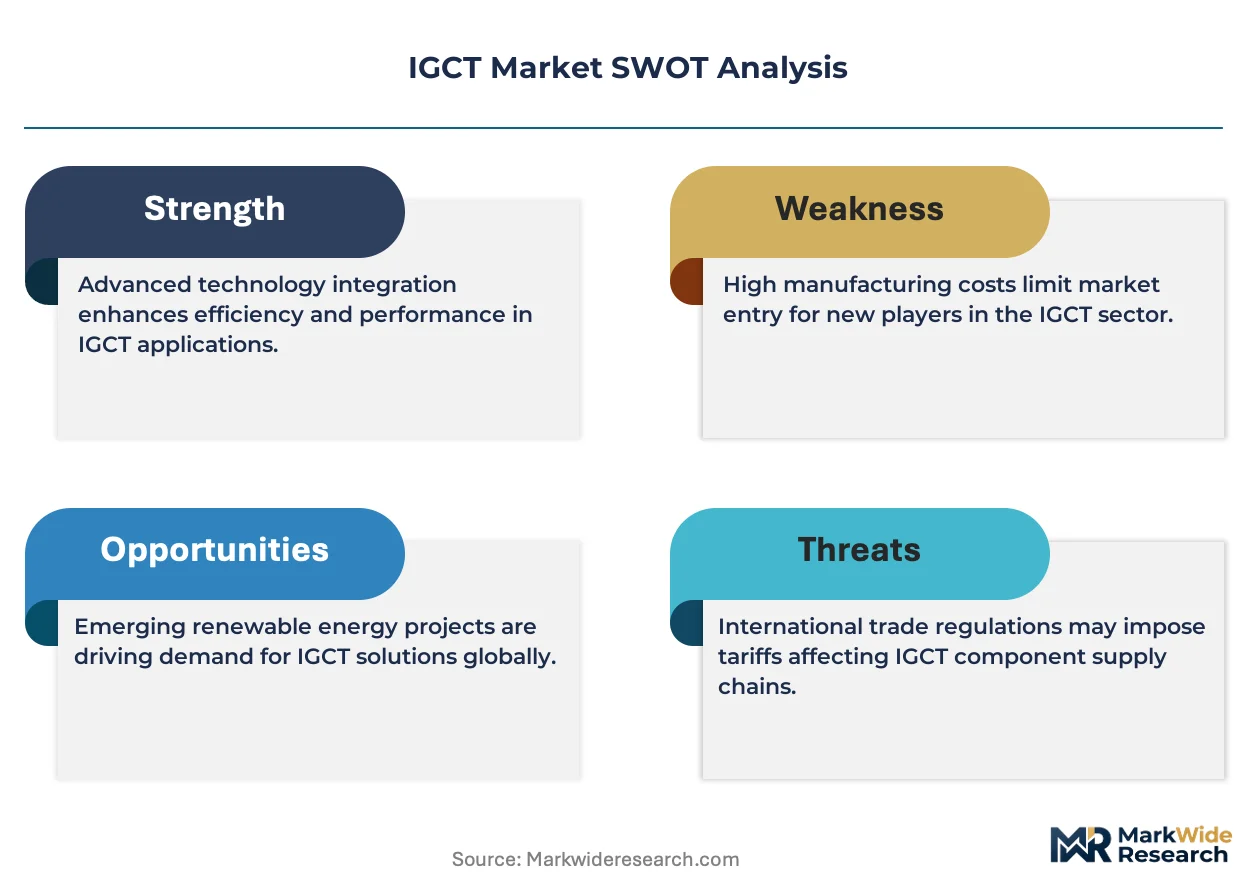
Power electronics engineers with gate-commutated thyristor design expertise is rotating toward renewable energy inverter projects as grid-scale solar and wind deployment accelerates. Siemens Energy leverages its vertical integration in high-voltage power conversion to sustain technology leadership across European rail electrification. Fuji Electric anchors its position through specialized manufacturing scale in industrial motor drives for steel and cement plants. ABB Group competes on geographic dominance, with extensive service networks covering Nordic and Central European heavy industry.
An Integrated Gate-Commutated Thyristor (IGCT) is a high-power semiconductor device combining a gate turn-off thyristor with a monolithically integrated gate unit, capable of blocking voltages exceeding 4.5 kV and conducting currents above 4 kA in a single silicon wafer. Its primary industrial purpose centers on medium-voltage motor drives, grid-connected inverters, and DC circuit breakers where silicon IGBTs reach thermal or switching-frequency limits. IGCT Modules occupy the mature revenue core, with margin pools shifting toward integrated driver-gate assemblies that reduce external component count. Silicon Carbide technology variants represent the fastest-growing segment, as 3.3 kV and above ratings displace conventional silicon in next-generation traction converters.
FDA oversight of medical imaging power supplies and NHTSA electrification mandates for heavy-duty vehicles shape dual demand channels for IGCT-qualified components in the US market. ECHA REACH restrictions on lead-based solder materials are forcing metallurgical redesigns in European IGCT module packaging. China's GB standards from SAMR enforce localized testing protocols for grid-connected power electronics. Stakeholders must monitor how silicon carbide substrate supply constraints reshape qualification timelines for next-generation gate-commutated devices.
Market Dynamics
Silicon carbide substrate scarcity is compressing qualification timelines for next-generation gate-commutated devices, forcing power semiconductor manufacturers to reallocate engineering resources toward alternative packaging architectures.
Growth Catalysts
- Dual carbon goals from MEE:China's tightening efficiency mandates for high-power semiconductors are accelerating IGCT adoption in grid-scale renewable inverters.
- Heavy industry motor drive modernization:Steel and cement plants across Germany are replacing aging thyristor stacks with integrated gate-commutated modules to cut switching losses.
- Traction converter electrification:Rail operators in Japan and France are specifying 3.3 kV+ silicon carbide variants for next-generation locomotive powertrains.
Market Restraints
- Silicon carbide substrate concentration:Wolfspeed and II-VI control over 70% of high-quality SiC wafer supply, creating single-source vulnerability for IGCT-SiC hybrids.
- ECHA REACH solder restrictions:Lead-free metallurgical redesigns are extending module qualification cycles by 8-14 months for European manufacturers.
- IGBT cost-performance parity:6.5 kV silicon IGBTs from Japanese suppliers are capturing medium-voltage drive applications below 2 MW.
Strategic Opportunities
- India's CEA grid code revisions:Central Electricity Authority mandates for fault-ride-through capability in solar inverters favor gate-commutated devices over conventional thyristors.
- DC circuit breaker integration:Hybrid AC-DC microgrids in data centers and semiconductor fabs require fast-switching high-voltage devices.
- Service network unbundling:Independent technical service providers are capturing aftermarket maintenance for legacy ABB and Siemens Energy installations.
Industry Challenges
- Gate driver integration complexity:OEMs lack in-house expertise to optimize dv/dt control for series-connected IGCT strings in 10 kV+ applications.
- Qualification timeline compression:Grid operators are demanding 25-year service life guarantees before silicon carbide field data exists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IGCT Market |
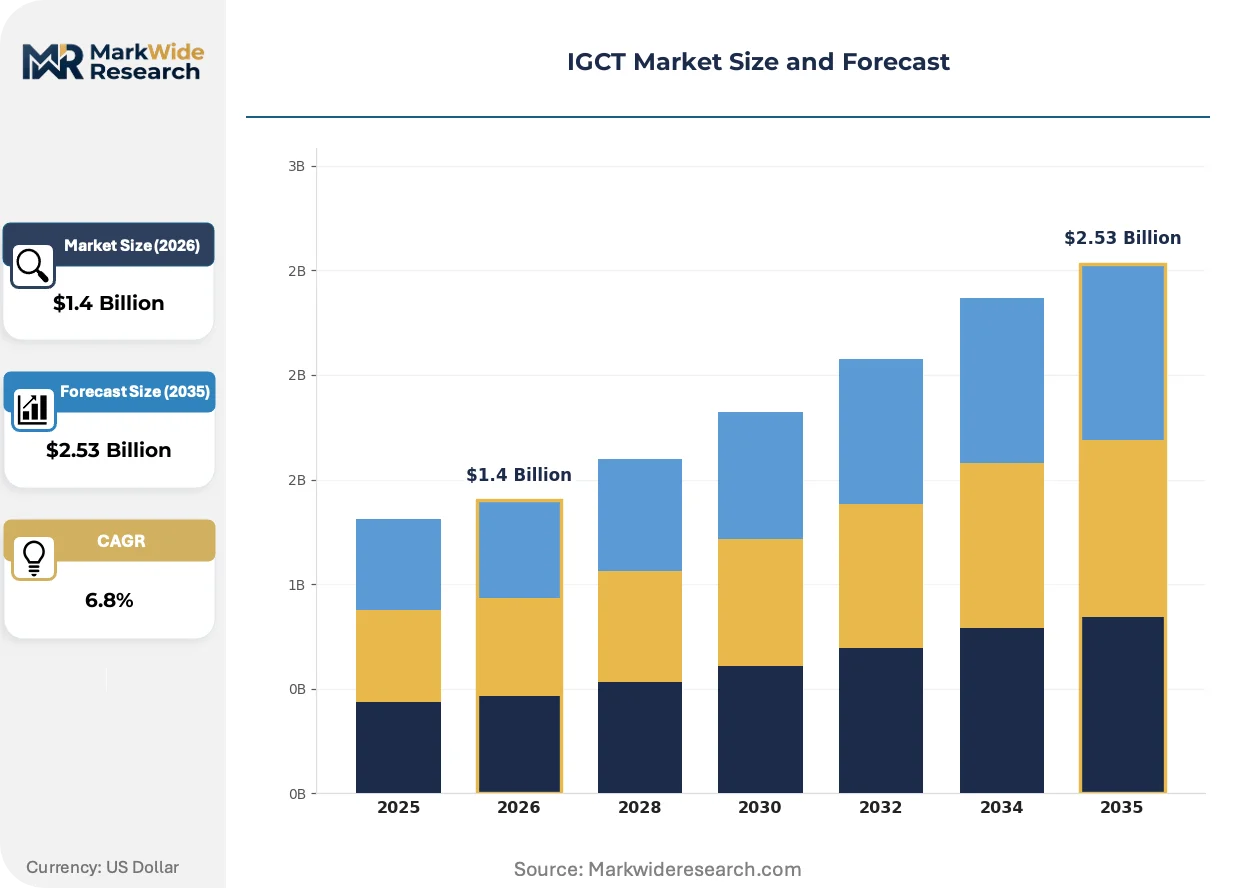
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IGCT Modules, Power Controllers, Circuit Protection, Drivers End User: Industrial Equipment, Automotive Manufacturing, Renewable Energy, Rail Transport Application: Power Electronics, Electric Vehicles, Energy Storage, Motor Drives Technology: Silicon Carbide, Gallium Nitride, Integrated Circuits, Switchgear |
| Companies Covered | Siemens Energy, Fuji Electric, ABB Group, Semikron, CRRC Corporation Limited, Infineon Technologies, Hitachi Energy, IXYS Corporation, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IGCT Market Emerging Trajectories
Active device architectures are displacing passive component stacks across medium-voltage power conversion, compressing system footprints while elevating switching frequencies beyond silicon IGBT thermal limits.
Silicon carbide-enhanced IGCT designs are displacing conventional silicon gate-commutated thyristors in 3.3 kV traction converters. European rail OEMs are specifying these hybrids for 2026+ locomotive platforms. The technology is displacing forced-commutated thyristor bridges that dominated DC-fed metro systems for three decades.
China's GB standards from SAMR now mandate localized electromagnetic compatibility testing for grid-connected power electronics above 1 kV. Foreign IGCT suppliers must establish in-country test facilities or partner with domestic certification bodies. Industrial inverter manufacturers are responding by pre-qualifying modules against both GB and IEC protocols.
Steel mills and cement producers are unbundling power electronics maintenance from original equipment supply contracts. Buyers now procure IGCT modules separately from gate driver assemblies, sourcing technical service through independent regional specialists. Germany's Ruhr industrial cluster exhibits this pattern most acutely, with three major steel groups operating captive repair facilities.
IGCT Market Segmentation
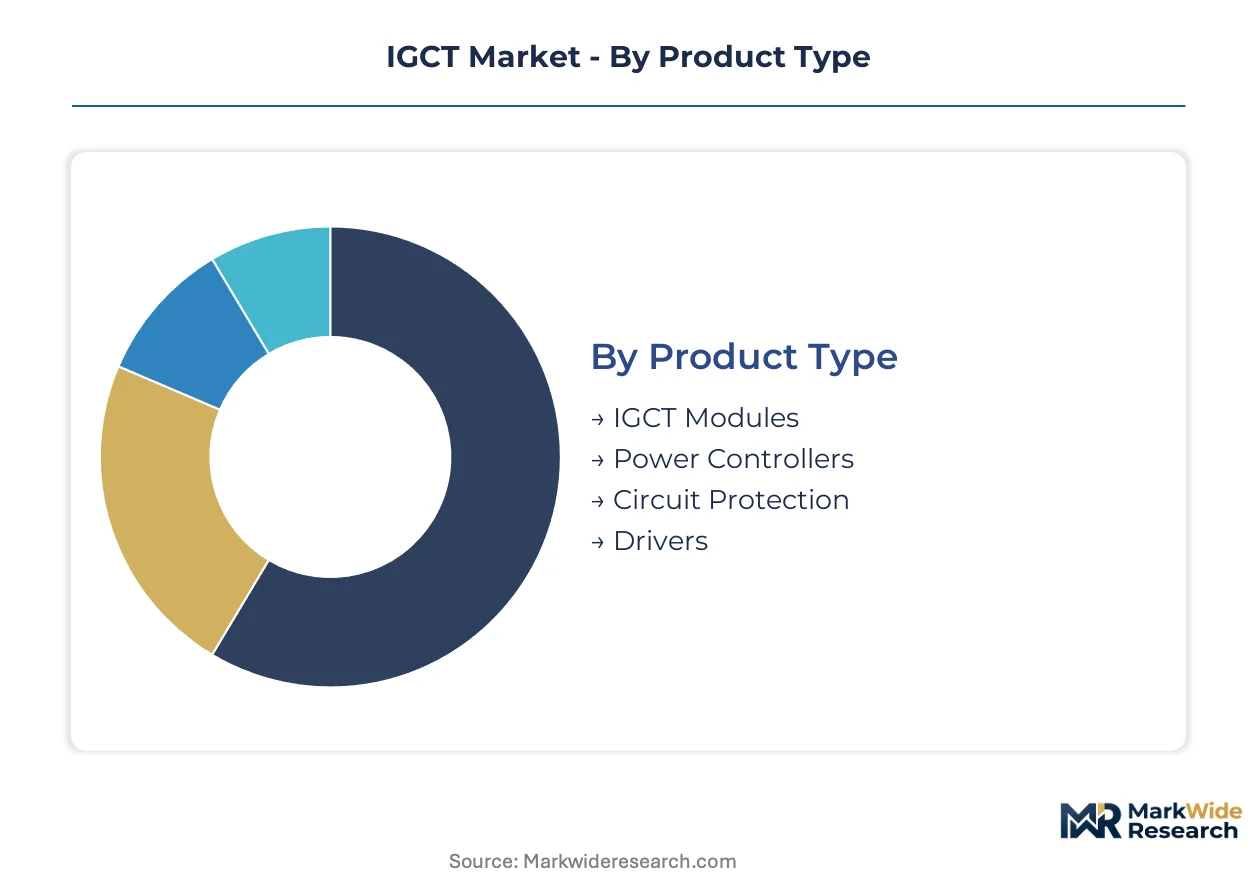
IGCT market segmentation reveals distinct vulnerability profiles across product architectures and end-use applications. Substitution pressures from silicon carbide MOSFETs and advanced IGBT platforms are reshaping competitive boundaries within each category.
Product Type:
IGCT Modules face the most acute substitution threat from silicon carbide-based alternatives in medium-voltage traction applications, while peripheral component segments maintain defensive positioning through system integration complexity.
- IGCT Modules:These monolithic gate-commutated thyristor assemblies integrate the semiconductor die with hard-soldered ceramic substrates, blocking voltages above 4.5 kV. Demand concentrates in Germany's Ruhr industrial cluster where steel producers modernize medium-voltage motor drives to meet ECHA REACH efficiency mandates. Siemens Energy and ABB Group anchor supply relationships for replacement cycles in European heavy industry.
- Power Controllers:Multi-device assemblies incorporating gate units, snubber networks, and thermal management subsystems. Railway electrification projects in Japan and France specify these for 3.3 kV+ traction converters as operators phase out forced-commutated thyristor bridges. METI efficiency standards for next-generation Shinkansen powertrains accelerate qualification timelines.
- Circuit Protection:Fast-acting fault isolation devices for DC microgrids and semiconductor fabrication facilities.
- Drivers:Integrated gate driver assemblies reducing external component count in high-voltage series-connected strings.
IGCT Modules retain volume leadership; Power Controllers hold the steepest expansion curve.
End User:
Cost tier differentiation separates mature industrial replacement demand from emerging automotive electrification requirements with divergent qualification protocols.
- Industrial Equipment:Steel mills, cement plants, and chemical processing facilities constitute the established revenue base. Germany's industrial motor drive modernization programs under EU Green Deal efficiency directives sustain replacement cycles for aging thyristor stacks. Captive repair facilities at ThyssenKrupp and Heidelberg Materials reduce OEM service attachment rates.
- Renewable Energy:Grid-scale solar and wind inverter manufacturers specify gate-commutated devices for fault-ride-through capability. India's CEA grid code revisions favor IGCTs over conventional thyristors in utility-scale installations. China's dual carbon goals from MEE tighten efficiency mandates for high-power semiconductors in grid-connected applications.
- Rail Transport:Locomotive and metro system OEMs in Japan, France, and China.
- Automotive Manufacturing:Heavy-duty commercial vehicle electrification programs subject to NHTSA mandates.
Industrial Equipment dominates current procurement volumes; Renewable Energy is climbing the fastest.
Application:
Application maturity curves diverge sharply between established motor drive platforms and emerging energy storage integration requirements.
- Motor Drives:Medium-voltage variable frequency drives for pumps, compressors, and rolling mills represent the most penetrated application segment. ABB Group's ACS6000 platform and Siemens Energy's SINAMICS GL150 series anchor installed base maintenance demand. Steel producers in Germany's North Rhine-Westphalia region operate captive refurbishment facilities for legacy thyristor-to-IGCT conversions.
- Energy Storage:Battery energy storage system inverters and grid-forming converters for hybrid AC-DC microgrids. Data center operators and semiconductor fabrication facilities in Taiwan and South Korea specify fast-switching high-voltage devices for DC circuit breaker integration. GB standards from SAMR mandate localized electromagnetic compatibility testing for grid-connected power electronics above 1 kV in China.
- Power Electronics:General-purpose conversion equipment for industrial and utility applications.
- Electric Vehicles:Heavy-duty traction inverters for commercial and rail electrification platforms.
Motor Drives maintains installed base dominance; Energy Storage shows the most rapid share gain.
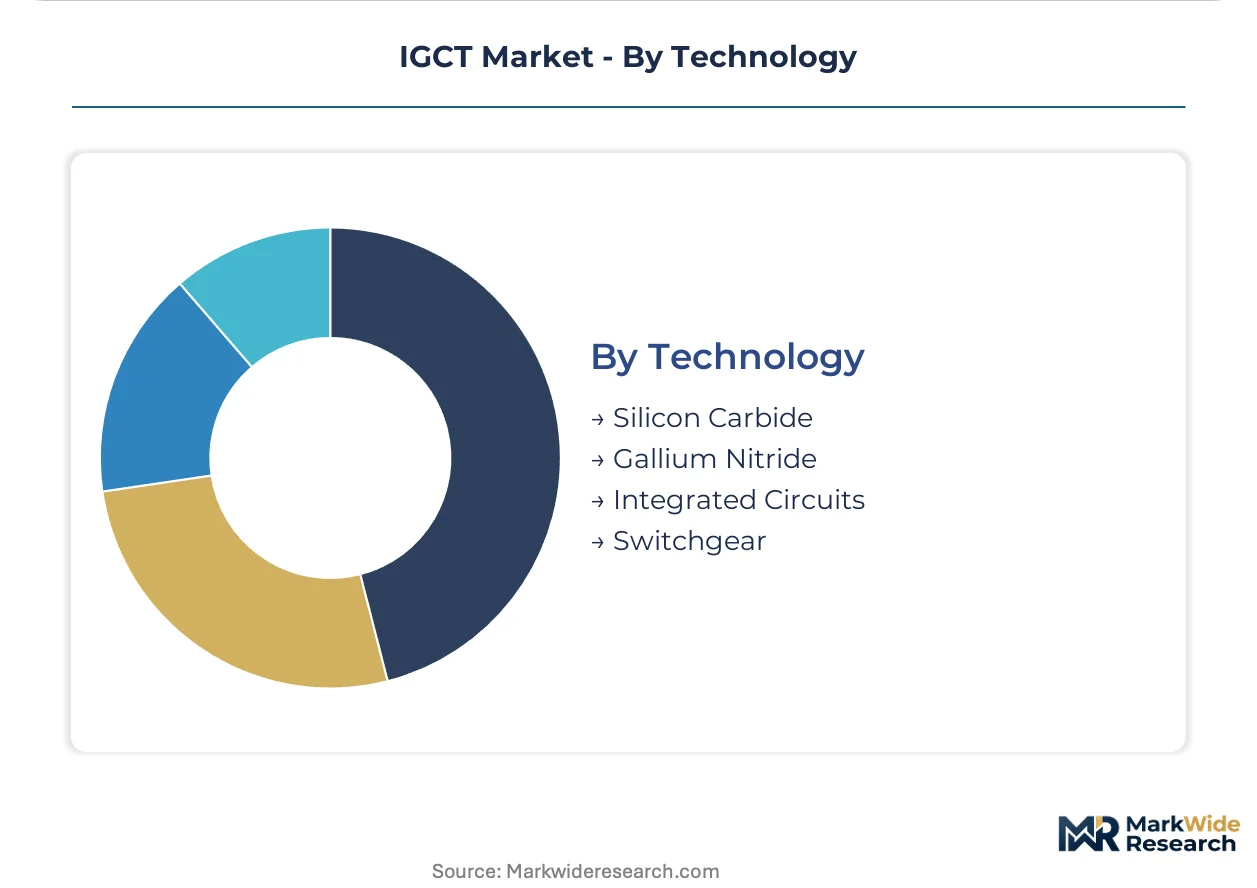
Technology:
Silicon substrate supply concentration is compressing qualification timelines and forcing architectural pivots toward alternative packaging approaches.
- Silicon Carbide:Wide-bandgap semiconductor variants enabling 3.3 kV+ operation with reduced switching losses. European rail OEMs specify SiC-enhanced IGCT designs for 2026+ locomotive platforms to displace conventional silicon in next-generation traction converters. Wolfspeed and II-VI control over 70% of high-quality SiC wafer supply, creating single-source vulnerability for hybrid device manufacturers.
- Integrated Circuits:Monolithic gate driver integration reducing external component count and dv/dt control complexity. OEMs lacking in-house expertise for series-connected IGCT string optimization in 10 kV+ applications drive outsourcing demand for pre-integrated assemblies.
- Gallium Nitride:Emerging wide-bandgap alternative for lower-voltage, higher-frequency applications below IGCT traditional ratings.
- Switchgear:Mechanical and hybrid interrupting devices for fault current management in medium-voltage networks.
Silicon Carbide captures technology investment priority; Integrated Circuits expand most quickly through system simplification value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes IGCTs primarily for industrial motor drive retrofits, while China deploys them for grid-scale renewable integration and Japan targets rail electrification—revealing a three-way consumption split across heavy industry, clean energy infrastructure, and transportation electrification.
Germany
Steel and cement producers in the Ruhr industrial cluster drive IGCT procurement for medium-voltage motor drive modernization. ECHA REACH restrictions on lead-based solder materials extend module qualification cycles by 8-14 months for domestic manufacturers. Siemens Energy and ABB Group anchor supply relationships across North Rhine-Westphalia's heavy industry base, with ThyssenKrupp operating captive refurbishment facilities for legacy thyristor-to-IGCT conversions.
China
Grid-scale solar and wind inverter manufacturers specify gate-commutated devices for fault-ride-through capability in utility-scale installations. SAMR's GB standards mandate localized electromagnetic compatibility testing for grid-connected power electronics above 1 kV, forcing foreign suppliers to establish in-country test facilities. The Yangtze River Delta concentration of power electronics manufacturing hosts CRRC Corporation's traction converter production for domestic rail electrification programs.
Japan
Rail operators specify 3.3 kV+ silicon carbide IGCT variants for next-generation Shinkansen powertrains as METI efficiency standards accelerate qualification timelines. Fuji Electric maintains specialized manufacturing scale for industrial motor drives serving domestic steel and cement plants. The Kansai industrial corridor around Osaka anchors demand for high-power semiconductor modules in heavy process industries.
India
Central Electricity Authority grid code revisions for fault-ride-through capability in solar inverters favor gate-commutated devices over conventional thyristors in utility-scale renewable installations. Domestic inverter manufacturers pre-qualify modules against both Indian and IEC protocols to serve accelerating solar deployment. Gujarat and Rajasthan solar parks concentrate procurement demand for grid-connected power electronics.
United States
NHTSA electrification mandates for heavy-duty commercial vehicles create a secondary demand channel for IGCT-qualified components in traction inverter applications. FDA oversight of medical imaging power supplies shapes qualification requirements for high-reliability semiconductor components. Texas and California industrial clusters exhibit divergent procurement patterns—oilfield equipment modernization in the former, clean energy manufacturing in the latter.
IGCT Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling captive gate driver technology and module packaging capabilities while specialists focus on discrete component supply or regional service networks. The competitive structure rewards backward integration into silicon wafer sourcing and in-house production of ceramic substrate assemblies. Two dominant competitive moves define current positioning: strategic partnerships to secure silicon carbide wafer supply from concentrated substrate producers, and geographic expansion through localized test facilities to satisfy country-specific certification mandates.
Among European integrated power electronics groups, Siemens Energy and ABB Group exemplify the full-stack archetype combining semiconductor module production with system-level drive platforms. Fuji Electric represents the Asia-Pacific industrial specialist model, with concentrated manufacturing scale serving heavy process industries. These three anchors occupy positions that reflect their respective regional demand concentrations—German industrial retrofit cycles, European rail electrification, and Japanese steel and cement plant modernization.
| Leading Market Players |
|---|
| Siemens Energy |
| Fuji Electric |
| ABB Group |
| Semikron |
| CRRC Corporation Limited |
| Infineon Technologies |
| Hitachi Energy |
| IXYS Corporation |
| Mitsubishi Electric |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements for silicon carbide wafers lock in both substrate access and cost visibility for IGCT-SiC hybrid manufacturers, insulating module producers from Wolfspeed and II-VI spot market volatility while binding buyers to volume commitments under China's GB standards and ECHA REACH compliance timelines.
Pricing Analysis
Project-based contracting dominates IGCT procurement for rail electrification and grid-scale inverter deployments, with price differentiation driven by certification grade (IEC versus GB standards) and after-sales service bundling. Cost compression in standard silicon modules is intensifying because 6.5 kV IGBTs from Japanese suppliers are capturing applications below 2 MW. Industrial equipment buyers in Germany's Ruhr cluster exhibit lowest price sensitivity due to captive refurbishment facilities, while renewable energy developers in India and China face acute margin pressure.
Supply Chain Analysis
China and Japan anchor wafer fabrication and module assembly for gate-commutated thyristors, with Germany specializing in ceramic substrate production and gate driver integration. The supply chain draws from silicon carbide wafers, copper-clad ceramic substrates, and lead-free solder materials. Single-source vulnerability concentrates in Wolfspeed and II-VI's 70% control of high-quality SiC supply. Distribution runs through direct OEM relationships for rail and industrial segments, with independent service providers capturing aftermarket maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IGCT market is approaching a platform-economics inflection as gate driver integration and SiC substrate interoperability reshape competitive boundaries, with ecosystem control shifting toward firms that pre-qualify modules against multiple national certification protocols.
For Market Incumbents: Shield installed base relationships by deepening backward integration into ceramic substrate production and establishing captive SiC wafer partnerships before qualification timelines compress further. Siemens Energy and ABB Group must defend against independent service providers unbundling maintenance contracts by embedding predictive diagnostics into gate driver assemblies, converting hardware sales into recurring technical service revenues. For New Entrants and Emerging Players: Aftermarket technical service for legacy thyristor-to-IGCT conversions represents the most penetrable white space, particularly in Germany's North Rhine-Westphalia steel cluster where ThyssenKrupp and Heidelberg Materials operate captive repair facilities. New entrants should target India's CEA-mandated fault-ride-through solar inverter segment with pre-certified driver-module assemblies, bypassing in-house gate driver expertise gaps that constrain OEM adoption. For Investors and Strategic Acquirers: Capital is best deployed toward specialized gate driver integrators with proven 10 kV+ series connection expertise and established GB-IEC dual certification capabilities, as these capabilities are becoming the scarce bottleneck for next-generation traction and grid applications. Watch silicon carbide substrate supply expansion announcements as the inflection signal for hybrid IGCT-SiC qualification timeline normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Captive supply of direct-bonded copper substrates reduces ECHA REACH compliance risk for European module producers. |
| SiC Wafer Supply Partnership | Long-term offtake with Wolfspeed or II-VI locks in substrate access for 3.3 kV+ traction converter programs. |
| Dual Certification Pre-qualification | Simultaneous GB and IEC testing capability opens China's grid-scale renewable inverter procurement to foreign suppliers. |
| Gate Driver Integration Acquisition | Monolithic driver assembly expertise addresses OEM dv/dt control gaps in 10 kV+ series-connected applications. |
| Independent Service Network Buildout | Regional maintenance capabilities capture unbundled aftermarket demand from Germany's Ruhr industrial cluster. |
Methodological Framework
Desk research of customs trade databases, SEC filings from power semiconductor suppliers, and IEC certification registries preceded structured interviews with power electronics procurement managers at rail OEMs, plant engineers at German steel mills, and grid interconnection specialists at Indian solar developers. Primary fieldwork with gate driver manufacturers and SiC substrate distributors validated secondary volume estimates. Bottom-up module shipment data triangulated against top-down inverter installation records.
Variance decomposition across product type, end user, application, and technology dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate blending. Modeled inputs included silicon carbide substrate supply expansion schedules, ECHA REACH qualification timeline assumptions, and CEA grid code revision implementation pace.
Forecasts assume regulatory continuity in ECHA REACH, China's MEE dual carbon mandates, and India's CEA standards; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market
Semiconductor Devices
Global Probe Card Market
Semiconductor Devices
Japan Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Embedded Multimedia Card Market
Semiconductor Devices
Dynamic Electrograph Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
Global Inp Wafer Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
Plastic Transistors Market
Semiconductor Devices
Flip Chip Technology Market
Semiconductor Devices
Europe Microcontroller Market
Semiconductor Devices
APAC Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
Topcon Solar Cell Market