
 1-Methylimidazole Market | 2026-2036
1-Methylimidazole Market Size, Share, and Industry Trends Forecast 2026-2036
1-Methylimidazole Market Outlook
Project finance tied to green chemistry certification programs is fragmenting competitive access in the 1-methylimidazole sector, allowing smaller specialized producers to secure capital previously reserved for integrated majors. BASF leverages its integrated Ludwigshafen complex to sustain captive supply chains for pharmaceutical-grade material. Merck KGaA anchors European demand through its life-sciences distribution network and stringent quality protocols. Jiangxi Jinkai Chemical dominates bulk industrial-grade production through dedicated imidazole derivative facilities in central China.
1-Methylimidazole is a heterocyclic organic compound with the formula C₄H₆N₂, featuring a methyl substituent at the 1-position of the imidazole ring; it serves primarily as a catalyst, solvent, and building block in pharmaceutical synthesis and epoxy curing systems. The reagents segment leads value contribution due to stringent purity requirements in peptide coupling and deprotonation reactions, while the solvents category is expanding fastest as electronics manufacturers adopt greener polar aprotic alternatives to dimethylformamide. Pharmaceutical firms represent the most concentrated end-user margin pool, with research laboratories driving spot-demand volatility through project-based procurement cycles.
REACH registration requirements in Europe and EPA Toxic Substances Control Act oversight in the United States both mandate detailed safety data and exposure assessments for imidazole derivative handlers, elevating compliance costs for non-integrated distributors. China's SAMR enforces GB standards for chemical purity and labeling that directly determine export eligibility for domestic manufacturers serving multinational pharmaceutical clients. Stakeholders must monitor evolving pharmaceutical cGMP audit requirements and dual-use chemical export control lists to anticipate supply chain disruption risks.
Market Dynamics
Pharmaceutical-grade purity specifications are tightening faster than industrial-grade capacity can adapt, forcing a bifurcation between captive integrated supply and merchant market fragmentation.
Growth Catalysts
- Peptide synthesis expansion:Contract development and manufacturing organizations are scaling deprotonation chemistry for GLP-1 analog production, pulling high-purity 1-methylimidazole into multi-ton procurement cycles.
- EU Green Deal compliance:REACH registration deadlines for imidazole derivatives are accelerating carbon footprint disclosure requirements, favoring producers with verified low-emission process routes.
- Azole chemistry clustering:Jiangxi and Shandong provinces in China have concentrated imidazole derivative manufacturing, creating downstream ecosystem density that reduces logistics costs for pharmaceutical intermediates.
Market Restraints
- Ethylene diamine cost volatility:Feedstock price swings for this key imidazole ring precursor compress margin predictability for non-integrated producers without backward chemical control.
- Single-source API risk:Over-reliance on Chinese pharmaceutical intermediate manufacturers exposes European formulators to dual-use chemical export control list disruptions.
- Dimethyl sulfoxide substitution:Electronics manufacturers in South Korea and Taiwan are piloting DMSO-based polar aprotic alternatives for certain etching applications, threatening solvent-grade volume.
Strategic Opportunities
- Bio-based feedstock certification:USDA BioPreferred and EU Ecolabel pathways reward producers developing fermentation-derived imidazole precursors with preferential procurement status.
- Continuous flow manufacturing:Adoption of modular flow chemistry systems by mid-scale pharmaceutical intermediates producers enables rapid grade switching between industrial and pharmaceutical specifications.
- India PLI scheme alignment:Active pharmaceutical ingredient production incentives under India's pharmaceutical promotion program are attracting imidazole derivative investment toward Gujarat and Telangana clusters.
Industry Challenges
- cGMP audit compression:Pharmaceutical customers are consolidating supplier qualification timelines from 18 months to 9 months, straining quality documentation systems at smaller producers.
- Cross-contamination protocol complexity:Multi-purpose reactor facilities face escalating cleaning validation costs when switching between industrial epoxy curing grades and pharmaceutical synthesis grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1-Methylimidazole Market |
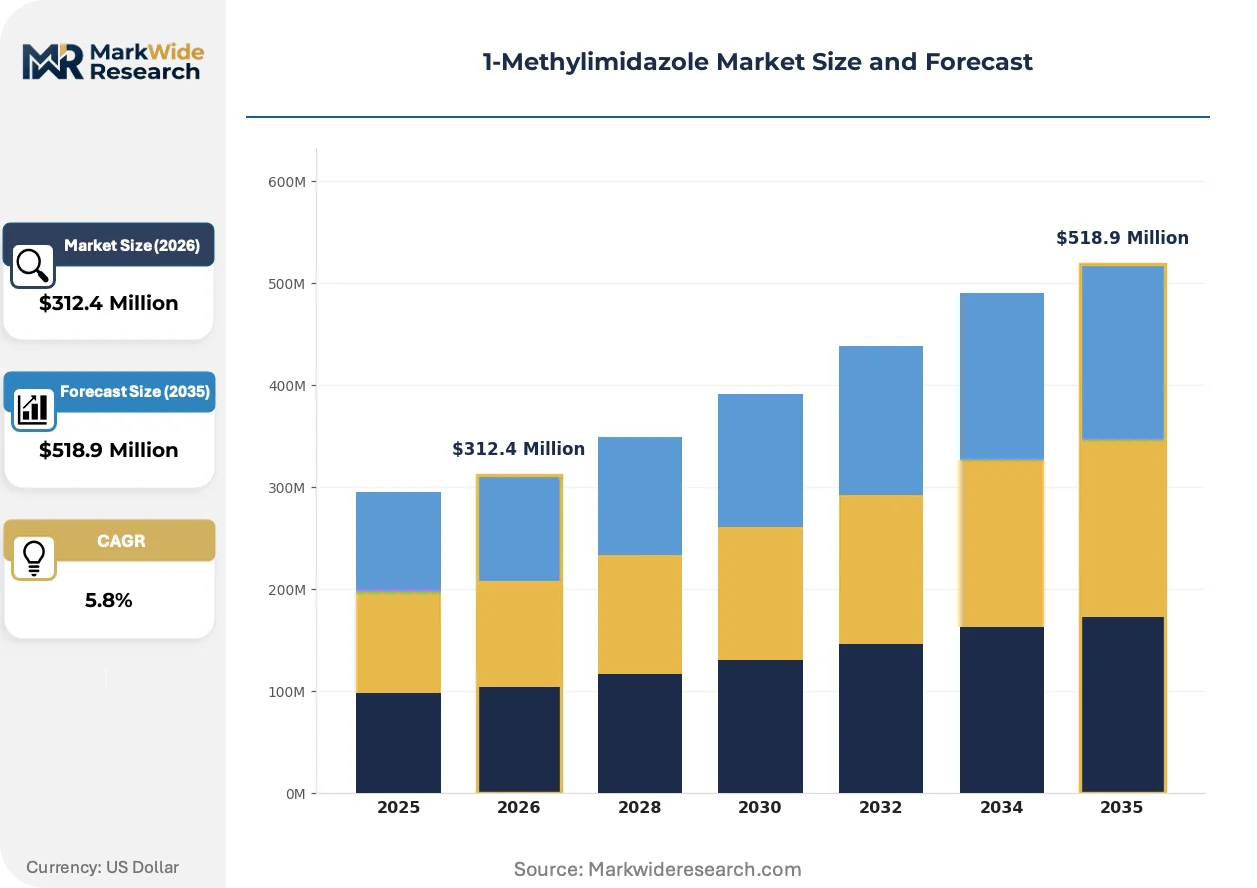
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Solvents, Industrial Chemicals, Specialty Chemicals Application: Pharmaceuticals, Agriculture, Electronics, Petrochemicals End User: Research Laboratories, Chemical Manufacturers, Pharmaceutical Firms, Agrochemical Companies Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Shanghai Holdenchem, Jiangxi Jinkai Chemical, BASF, Changzhou Chongkai Chemical, Ningbo Minghao Medicine Chemical, Merck KGaA, Anhui Wotu Chemical, Chengdu Yuanda Chemical, Tokyo Chemical Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1-Methylimidazole Market Strategic Shifts
Process intensification and regulatory disclosure requirements are converging to reshape how 1-methylimidazole purity grades are certified, distributed, and consumed across end-use verticals.
Membrane separation technology is migrating from batch crystallization as the dominant purification method for pharmaceutical-grade material. European and North American producers are adopting nanofiltration systems to reduce solvent waste volumes by half while meeting EMA impurity specification thresholds. This shift is compressing the cost gap between integrated majors and specialized refiners, enabling mid-scale entrants to compete on quality parity.
REACH authorization requirements for substances of very high concern are expanding disclosure obligations for imidazole derivative handlers across the European supply chain. ECHA's 2024 updated guidance on endocrine disruption screening now triggers additional toxicological testing for certain azole chemistries used in pharmaceutical synthesis. German and Swiss formulators are responding by pre-qualifying alternative suppliers outside the EU to hedge against potential authorization delays.
Spot-market purchasing through digital chemical platforms is displacing traditional three-year offtake agreements for industrial-grade volumes. Chinese commodity traders and Southeast Asian epoxy formulators are aggregating demand through Alibaba Chemical and similar B2B marketplaces, compressing price discovery cycles from quarterly to weekly. This behavioral shift is most pronounced in electronics manufacturing clusters where inventory carrying costs outweigh volume discount incentives.
1-Methylimidazole Market Segmentation
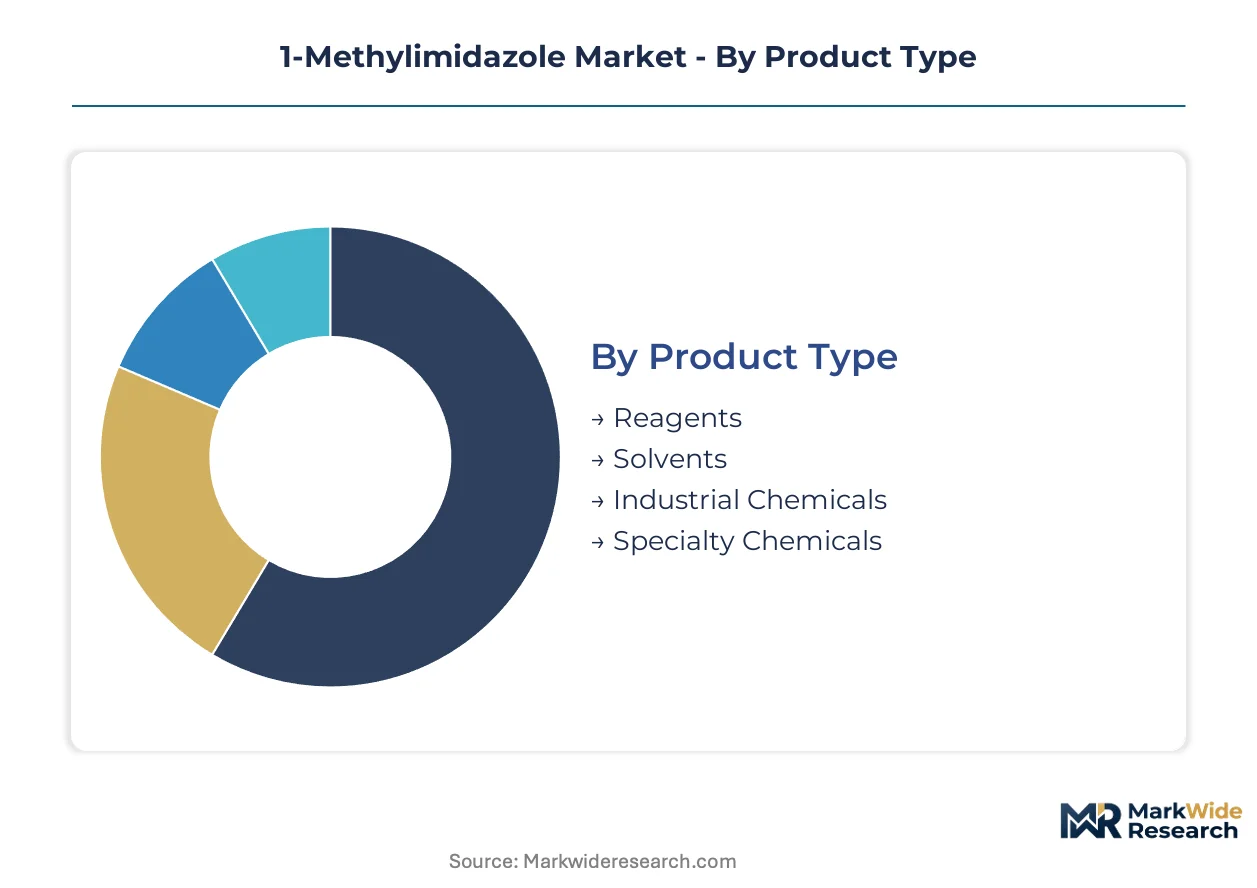
Purity grades and procurement cycles fragment the 1-methylimidazole landscape into distinct commercial tiers. Each segment carries divergent compliance burdens and margin structures that reshape supplier selection criteria.
Product Type:
Use cases span precision synthesis through bulk industrial processing, with purity thresholds determining commercial access.
- Reagents:Pharmaceutical-grade material meeting EMA impurity specifications for peptide coupling and deprotonation reactions. Contract development organizations in Basel and Boston pull multi-ton volumes for GLP-1 analog manufacturing, tightening qualification timelines from 18 months to 9 months.
- Solvents:Polar aprotic alternative to dimethylformamide in electronics etching and pharmaceutical crystallization. South Korean and Taiwanese semiconductor manufacturers are piloting this grade for greener process chemistry, though dimethyl sulfoxide substitution threatens volume stability.
- Industrial Chemicals:Standard-grade material for epoxy curing systems and general synthesis.
- Specialty Chemicals:Custom-formulated derivatives for niche pharmaceutical intermediates.
Established volume favors industrial chemicals; emerging adoption favors reagents.
Application:
End-use sectors impose divergent regulatory and performance requirements on suppliers.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and peptide manufacturing drive the highest purity specifications. European formulators face REACH authorization pressures for azole derivatives, accelerating supplier pre-qualification outside the EU.
- Electronics:Semiconductor etching and display manufacturing utilize solvent-grade material as polar aprotic media. Jiangxi and Shandong manufacturing clusters supply downstream electronics formulators with reduced logistics costs.
- Agriculture:Agrochemical intermediate production for fungicide and pesticide synthesis.
- Petrochemicals:Catalyst and corrosion inhibitor applications in refining operations.
Margin concentration sits with pharmaceuticals; volume scaling favors electronics.
End User:
Procurement sophistication varies sharply across customer categories, from spot-market laboratory purchasing to integrated manufacturing contracts.
- Pharmaceutical Firms:Integrated manufacturers and contract development organizations with multi-year offtake agreements. These buyers mandate cGMP compliance and carbon footprint disclosures under EU Green Deal frameworks.
- Chemical Manufacturers:Intermediate producers serving downstream formulation markets with quarterly volume commitments.
- Research Laboratories:Academic and commercial R&D facilities driving spot-demand volatility through project-based purchasing.
- Agrochemical Companies:Seasonal procurement patterns tied to planting and harvest cycles.
Contract stability favors pharmaceutical firms; price volatility tracks research laboratories.
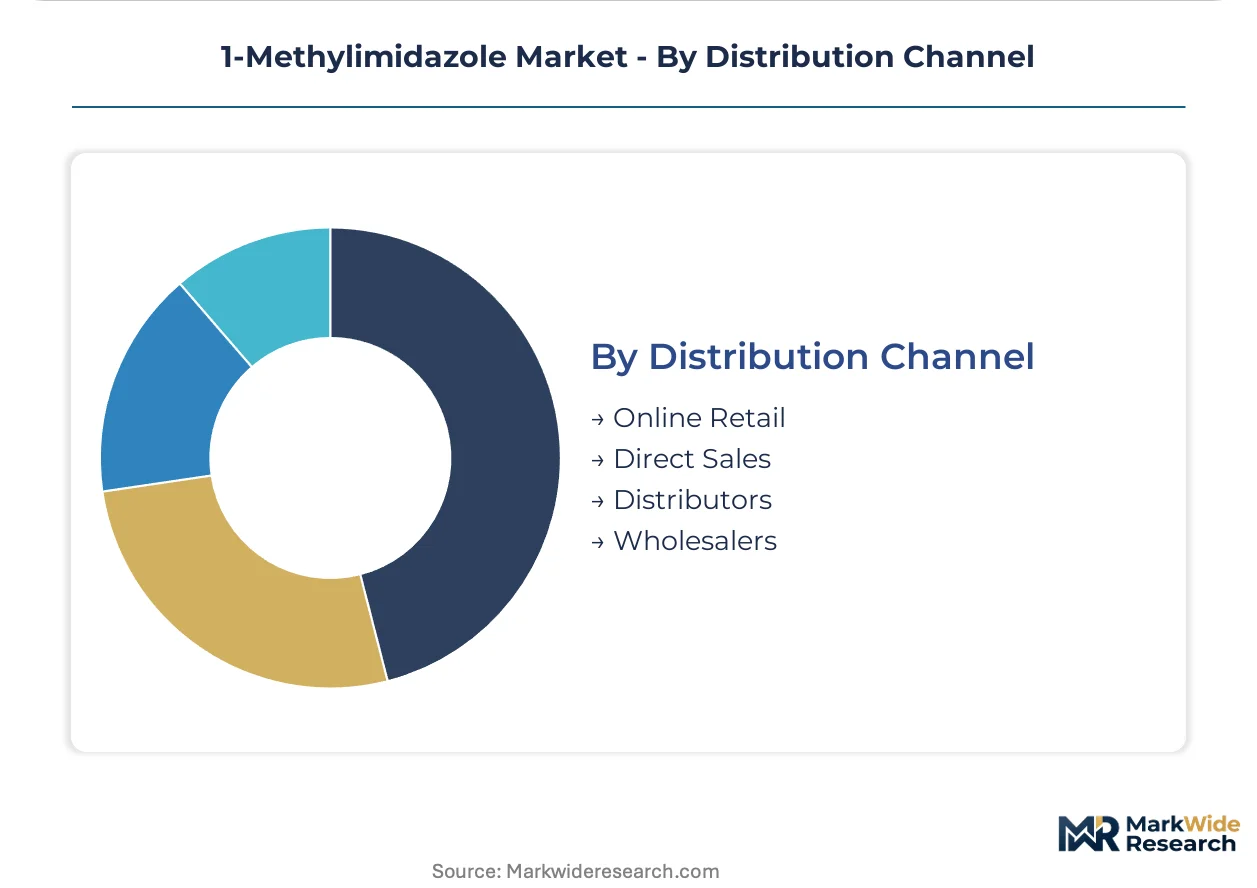
Distribution Channel:
Channel selection reflects order size, urgency, and compliance documentation requirements.
- Distributors:Regional chemical distributors hold inventory for pharmaceutical and industrial accounts requiring rapid fulfillment. These intermediaries face escalating REACH and EPA Toxic Substances Control Act compliance costs for safety data management.
- Direct Sales:Captive supply arrangements between integrated producers and large pharmaceutical manufacturers.
- Online Retail:Digital platforms aggregating spot demand from small laboratories and Southeast Asian epoxy formulators.
- Wholesalers:Bulk commodity traders serving industrial-grade volume purchasers.
Relationship depth favors distributors; transaction velocity climbs fastest through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping procurement geography for 1-methylimidazole, with concentrated Asian production feeding dispersed pharmaceutical formulation centers across Europe and North America. Trade flows now pivot on regulatory alignment rather than pure cost arbitrage.
China
Jiangxi and Shandong provinces host dense azole chemistry manufacturing clusters serving downstream pharmaceutical contract manufacturers. SAMR enforces GB standards for chemical purity and labeling that determine export eligibility for multinational clients. Ningbo and Changzhou chemical parks are expanding dedicated imidazole derivative capacity to capture electronics solvent demand from South Korean semiconductor buyers.
Germany
BASF's integrated Ludwigshafen complex sustains captive supply chains for pharmaceutical-grade material serving European formulators. REACH authorization requirements for imidazole derivatives are tightening carbon footprint disclosure obligations under EU Green Deal frameworks. The country's central pharmaceutical regulator is accelerating endocrine disruption screening protocols that trigger additional toxicological testing for certain azole chemistries.
United States
Contract development organizations in Boston and Research Triangle Park are scaling deprotonation chemistry for GLP-1 analog production, pulling high-purity reagent volumes into multi-ton procurement cycles. EPA Toxic Substances Control Act oversight mandates detailed safety data and exposure assessments for imidazole derivative handlers. Electronics manufacturers in Oregon and Arizona are piloting solvent-grade material as greener polar aprotic alternatives to dimethylformamide.
India
Active pharmaceutical ingredient production incentives under the PLI scheme are attracting imidazole derivative investment toward Gujarat and Telangana clusters. CDSCO cGMP audit requirements are consolidating supplier qualification timelines, straining quality documentation systems at smaller producers. Mumbai and Ahmedabad formulators are pre-qualifying alternative suppliers outside the EU to hedge against potential REACH authorization delays.
Japan
Tokyo Chemical Industry anchors regional distribution networks for research-grade material serving academic and commercial R&D facilities. METI industrial standards govern chemical intermediate specifications for domestic pharmaceutical manufacturers. Osaka-based electronics formulators are testing solvent-grade alternatives to DMSO in semiconductor etching applications, creating demand volatility for industrial-grade volumes.
1-Methylimidazole Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower but defensible positions. The market exhibits moderate concentration, with integrated chemical majors controlling pharmaceutical-grade certification while regional specialists capture industrial-grade volume through cost-optimized production. Three archetypes dominate: captive integrated producers with backward chemical control, specialized refiners leveraging membrane separation technology, and commodity traders aggregating spot demand through digital platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves, with mid-scale entrants securing project finance tied to green chemistry certification programs.
Within the integrated producer tier, BASF and Merck KGaA exemplify the quality-certification archetype through European life-sciences distribution networks. Jiangxi Jinkai Chemical occupies a position representing bulk industrial-grade specialization through dedicated imidazole derivative facilities. Shanghai Holdenchem and Tokyo Chemical Industry sit within the regional distributor archetype, anchoring procurement access for research laboratories and smaller formulators across their respective home markets.
| Leading Market Players |
|---|
| Shanghai Holdenchem |
| Jiangxi Jinkai Chemical |
| BASF |
| Changzhou Chongkai Chemical |
| Ningbo Minghao Medicine Chemical |
| Merck KGaA |
| Anhui Wotu Chemical |
| Chengdu Yuanda Chemical |
| Tokyo Chemical Industry |
| Others |
Value Chain & Pricing Dynamics
Ningbo-to-Rotterdam freight corridors carry imidazole derivative shipments where container rate volatility compresses margin buffers for European distributors while amplifying price differentiation between pharmaceutical-grade and industrial-grade tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels where pharmaceutical-grade certification under EMA specifications commands substantial premiums over epoxy-curing industrial material. Price differentiation rests on purity thresholds and REACH carbon footprint disclosure compliance, with contract development organizations showing lowest price sensitivity due to GLP-1 manufacturing pull. Cost compression in solvent-grade tiers is intensifying because South Korean electronics manufacturers pilot dimethyl sulfoxide substitutes, forcing Chinese producers to absorb freight volatility to retain volume commitments.
Supply Chain Analysis
Ethylene diamine feedstock availability draws from petrochemical complexes in China, Germany, and the United States where imidazole ring precursors face ethylene cost volatility. Raw material dependencies center on formaldehyde, ammonia, and methylating agents sourced through integrated Ludwigshafen complexes or merchant Chinese producers. Single-source vulnerability concentrates in Jiangxi and Shandong manufacturing clusters where SAMR export licensing determines European pharmaceutical access. Distribution runs through captive supply arrangements for pharmaceutical majors and digital B2B platforms aggregating spot demand from Southeast Asian epoxy formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among contract development organizations consolidating supplier panels from twelve to six qualified vendors, compressing qualification timelines and amplifying price leverage for multi-ton pharmaceutical-grade procurement.
For Market Incumbents: Pre-empt membrane separation technology adoption by European specialized refiners through accelerated nanofiltration deployment at existing Ludwigshafen-scale facilities. Lock in backward integration into ethylene diamine precursors to defend margin position against feedstock volatility. Secure cGMP audit pre-qualification status with Boston and Basel CDMOs before nine-month qualification windows become standard. For New Entrants and Emerging Players: Build out continuous flow manufacturing capabilities in Gujarat and Telangana to capture India PLI scheme-aligned API production incentives. Target electronics solvent-grade volume through Alibaba Chemical platform aggregation where spot-market purchasing displaces traditional offtake structures. Lead with USDA BioPreferred certification to secure preferential procurement status from sustainability-mandated pharmaceutical formulators. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical majors with stranded imidazole derivative capacity lacking pharmaceutical-grade certification infrastructure. Mid-scale European refiners with membrane separation technology represent viable acquisition archetypes for platform consolidation. Watch for REACH authorization delays on endocrine disruption screening as signal for supplier pre-qualification acceleration outside EU jurisdiction.| Strategic Initiative | Industry Significance |
|---|---|
| Green Chemistry Certification | USDA BioPreferred and EU Ecolabel pathways unlock preferential procurement from sustainability-mandated pharmaceutical buyers. |
| Continuous Flow Manufacturing | Modular flow chemistry systems enable rapid grade switching between industrial epoxy curing and pharmaceutical synthesis specifications. |
| Backward Feedstock Integration | Captive ethylene diamine production insulates margin predictability from petrochemical price volatility. |
| Membrane Separation Deployment | Nanofiltration adoption halves solvent waste volumes while achieving EMA impurity thresholds for pharmaceutical-grade material. |
| Digital Platform Aggregation | Alibaba Chemical and similar B2B marketplaces compress price discovery cycles from quarterly to weekly for industrial-grade volumes. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plant managers at imidazole derivative facilities, procurement leads at downstream pharmaceutical OEMs, distribution channel partners, and technical R&D directors; alongside secondary validation through customs/trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from integrated producers, and SAMR GB standard documentation. Bottom-up volume estimates from individual manufacturing facilities triangulated against top-down demand aggregation from end-use sector consumption patterns.
Forecast inputs considered grade tier differentiation between reagent, solvent, and industrial chemical specifications; end-use industry segmentation across pharmaceuticals, electronics, agriculture, and petrochemicals; regional production hub clustering in Jiangxi, Shandong, Ludwigshafen, and Gujarat; and packaging format distinctions for bulk tanker versus specialized pharmaceutical container shipments. CAGRs derived from elasticity-adjusted demand projections incorporating REACH regulatory phase-in schedules and GLP-1 manufacturing capacity expansion announcements across the analysis window.
Sensitivities concentrate around ethylene diamine feedstock cost trajectories, REACH authorization timeline delays for azole derivatives, and dual-use chemical export control list modifications affecting Chinese pharmaceutical intermediate shipments. Cross-checking against ECHA substance registration databases and FDA active pharmaceutical ingredient facility inspection records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Paraphenylenediamine (PPD) Market
Chemicals
Fireworks Market
Chemicals
Chromium Trioxide Market
Chemicals
Global Boron Trifluoride Market
Chemicals
Dimethyldichlorosilane Market
Chemicals
Calcium Hydroxide Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Global Oxo Alcohols Market
Chemicals
Global Syringaldehyde Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
3-Iodoaniline Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
Waterborne Curing Agents Market
Chemicals
5 Dinitroaniline Market
Chemicals
Barbituric Acid Market