
 Medicinal Chemistry for Drug Discovery Market | 2026-2036
Medicinal Chemistry for Drug Discovery Market Size, Share, and Industry Trends Forecast 2026-2036
Medicinal Chemistry for Drug Discovery Market Foresight
Hit-to-lead optimization revenue is reshaping how service providers capture value in early-stage drug discovery. Eurofins Scientific leverages its European laboratory network to anchor high-margin integrated discovery programs across multiple therapeutic areas. Charles River Laboratories sustains its competitive position through captive access to genetically modified models that accelerate candidate validation. WuXi Apptec dominates small-molecule chemistry manufacturing scale, extending its reach from discovery through commercial supply.
Medicinal chemistry for drug discovery encompasses the design, synthesis, and optimization of pharmaceutically active compounds through iterative structure-activity relationship studies, typically requiring purity thresholds exceeding 95% for preclinical candidate nomination. Its primary commercial purpose is to transform biological targets into patentable, developable drug candidates with suitable absorption, distribution, metabolism, excretion, and toxicity profiles. Small molecules retain the largest revenue share within product type categories, though RNA-based therapeutics represent the fastest-expanding margin pool as oligonucleotide chemistry matures. Contract Research Organizations within the end-user dimension are capturing disproportionate growth as biotechnology firms outsource synthesis capabilities rather than building internal medicinal chemistry departments.
FDA review standards for new molecular entities, EMA quality guidelines for investigational medicinal products, and REACH chemical safety requirements collectively elevate the compliance burden for discovery-stage compound libraries. These frameworks shape demand by mandating documented synthetic routes, impurity profiling, and environmental fate assessments before human studies commence. Stakeholders must monitor how regulator convergence on green chemistry principles affects solvent selection and waste disposal costs across outsourced synthesis networks.
Market Dynamics
Artificial intelligence integration in molecular design is compressing synthesis timelines while Contract Research Organizations absorb fixed R&D costs previously borne by pharmaceutical developers.
Growth Catalysts
- FDA accelerated approval pathways:Novel chemical entity submissions receive priority review, shortening development cycles and incentivizing investment in differentiated scaffolds.
- RNA-based therapeutic demand:Oligonucleotide chemistry maturation creates new margin pools as developers pursue antisense and siRNA modalities beyond traditional small molecules.
- Green chemistry mandates:REACH chemical safety requirements and EPA solvent guidelines drive adoption of aqueous synthesis routes and biocatalytic transformations.
Market Restraints
- Specialized talent scarcity:Synthetic organic chemists with structure-activity relationship expertise command premium compensation, elevating fixed costs for discovery-stage operations.
- Single-source isotope supply:Deuterium and carbon-14 labeling materials concentrate with limited North American and European suppliers, creating input vulnerability.
- Preclinical purity thresholds:Mandatory 95% compound purity for candidate nomination necessitates repeated chromatographic purification, extending synthesis timelines.
Strategic Opportunities
- India's CRO expansion:CDSCO regulatory harmonization with ICH standards positions Indian synthesis providers to capture outsourced medicinal chemistry from Western biotech firms.
- AI-converged automation:Machine learning-driven retrosynthesis platforms integrated with flow chemistry systems enable unattended multi-step route optimization.
- EU Green Deal alignment:ECHA sustainable chemistry incentives reward solvent recycling and enzymatic catalysis adoption with streamlined authorization pathways.
Industry Challenges
- Computational chemistry skill gaps:Traditional medicinal chemists require retraining in cheminformatics and molecular dynamics simulation to operate AI-augmented design platforms.
- Legacy data integration:Decades of structure-activity relationship records reside in incompatible formats, complicating machine learning training set assembly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medicinal Chemistry for Drug Discovery Market |
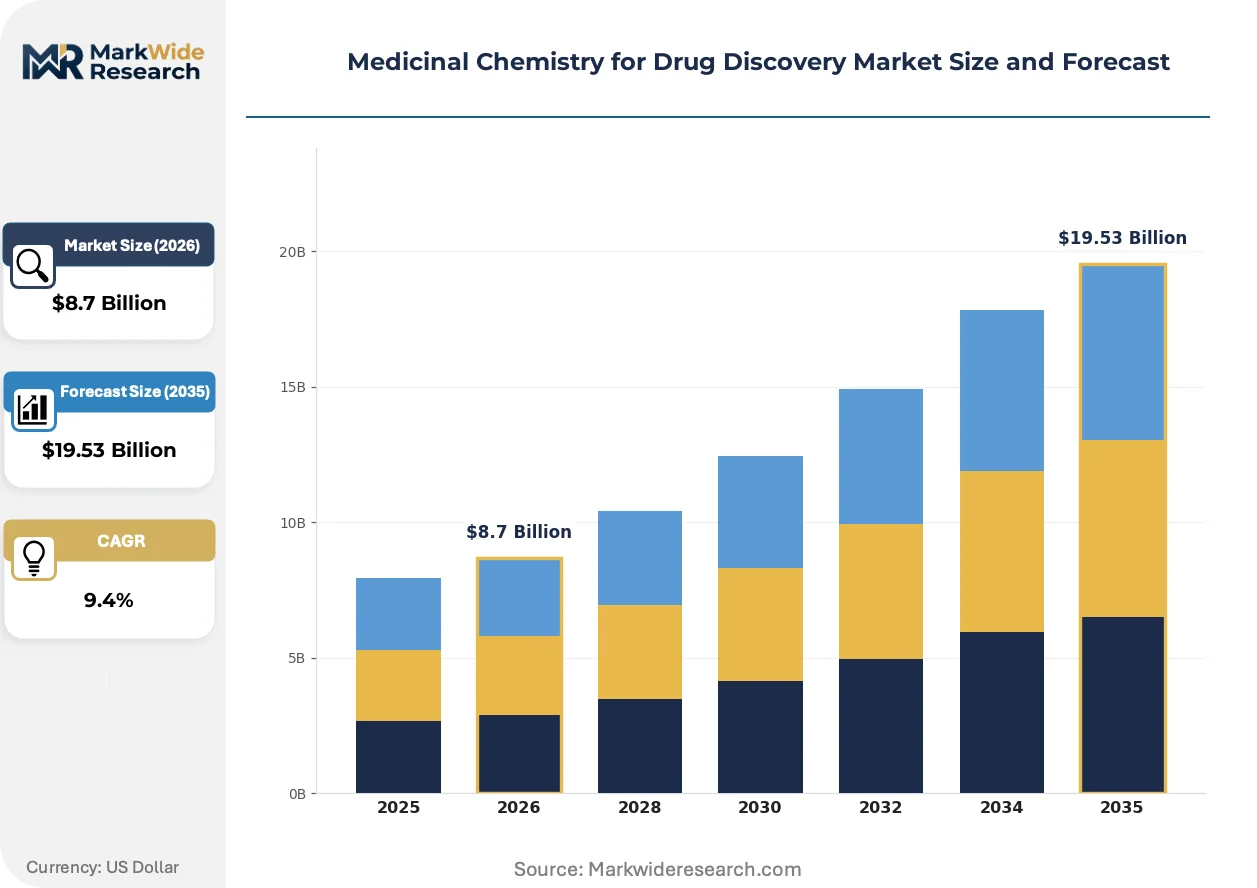
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Biologics, Antibodies, RNA-Based Therapeutics Application: Oncology, Neurology, Cardiovascular, Infectious Diseases End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations Technology: Computational Chemistry, High-Throughput Screening, Molecular Modeling, Structure-Based Drug Design |
| Companies Covered | Eurofins Scientific, Charles River Laboratories, WuXi Apptec, Evotec SE, Thermo Fisher Scientific Inc., Labcorp Drug Development, Certara, Piramal Pharma Solutions, Genscript Biotech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medicinal Chemistry for Drug Discovery Market Shifts & Advancements
Computational platforms are displacing empirical screening while regulatory convergence on environmental fate assessment reshapes synthetic route selection. Three developments define this transformation.
Generative AI models for de novo molecular design are virtualizing traditional hit identification workflows. Mid-cap biotechnology firms deploy these tools to compress library enumeration from months to days. The structural consequence is displacement of high-throughput screening contracts with algorithm-driven synthesis prioritization.
EMA quality guidelines for investigational medicinal products now mandate documented impurity profiling before first-in-human studies. Synthetic route selection must now incorporate forced degradation studies and metabolite identification earlier in discovery. Small-molecule CROs serving European sponsors have reconfigured analytical capabilities to meet these documentation burdens.
Biotechnology sponsors now unbundle discovery chemistry from integrated discovery contracts, awarding synthesis modules to specialized providers while retaining biology in-house. This disintermediation of full-service relationships fragments procurement across multiple vendors. The United States exhibits the most pronounced unbundling as venture-backed firms optimize capital efficiency through milestone-based outsourcing.
Medicinal Chemistry for Drug Discovery Market Segmentation
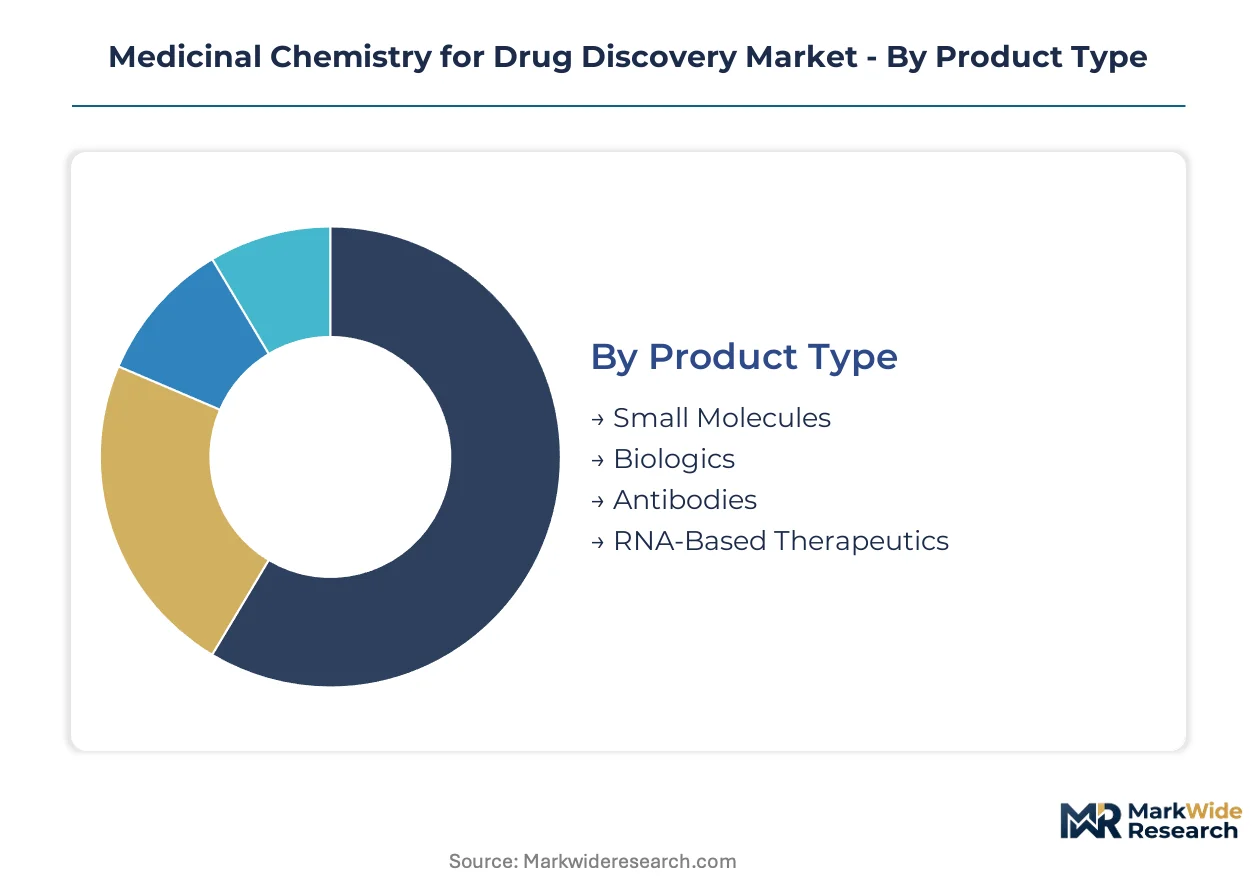
Medicinal chemistry services fragment across molecular modalities, therapeutic targets, and technical approaches. Each segment carries distinct purity requirements, regulatory pathways, and margin structures that reshape procurement decisions.
Product Type:
Mature small-molecule platforms dominate revenue volume while emerging modalities capture margin expansion.
- Small Molecules:Synthetic organic compounds under 900 Daltons remain the workhorse of medicinal chemistry outsourcing. Pharmaceutical sponsors in the United States drive demand for heterocyclic scaffold libraries with documented synthetic routes for FDA submission. Stringent 95% purity thresholds for preclinical nomination extend purification timelines and elevate analytical costs.
- RNA-Based Therapeutics:Antisense oligonucleotides and siRNA constructs represent the steepest expansion trajectory as chemistry suppliers build phosphoramidite synthesis and conjugation capabilities. CDSCO regulatory harmonization in India positions local providers to capture Western biotech outsourcing for these complex modalities.
- Biologics:Peptide and protein therapeutic chemistry requires specialized solid-phase synthesis infrastructure.
- Antibodies:Fragment and conjugate chemistry supports antibody-drug linker development.
Small molecules handle the majority of throughput; RNA-based therapeutics is the fastest mover on share.
Application:
Oncology concentration reflects kinase inhibitor demand while neurology applications accelerate on CNS-penetrant scaffold priorities.
- Oncology:Kinase inhibitor and immune-modulator programs generate the highest medicinal chemistry outsourcing volume. FDA accelerated approval pathways for novel chemical entities in oncology compress development timelines and intensify hit-to-lead optimization cycles. Structure-activity relationship studies for tumor-targeting small molecules require extensive metabolite profiling under EMA quality guidelines.
- Neurology:Blood-brain barrier penetration chemistry commands premium pricing as developers pursue GPCR and ion channel targets for neurodegenerative indications. CNS drug discovery demands specialized lipophilicity optimization and P-glycoprotein efflux mitigation.
- Cardiovascular:Anticoagulant and metabolic syndrome programs sustain steady synthesis demand.
- Infectious Diseases:Antiviral and antibiotic scaffold renewal drives fragment-based lead generation.
Oncology commands the largest project pipeline; neurology is climbing the fastest on outsourcing intensity.
End User:
Cost tier stratification separates integrated pharmaceutical sponsors from capital-constrained biotechnology firms.
- Contract Research Organizations:CROs absorb disproportionate growth as biotechnology firms unbundle discovery chemistry from full-service contracts. Milestone-based outsourcing structures allow venture-backed sponsors to preserve capital while accessing specialized synthesis capabilities. WuXi AppTec and Charles River Laboratories extend captive model access to accelerate candidate validation.
- Pharmaceutical Companies:Large sponsors retain strategic medicinal chemistry for core therapeutic areas while outsourcing peripheral programs. Internal departments focus on differentiated scaffold development and patent strategy.
- Biotechnology Firms:Emerging developers rely entirely on outsourced synthesis for lead optimization.
- Research Institutions:Academic laboratories generate tool compound demand for target validation studies.
Contract Research Organizations process the highest compound volume; biotechnology firms are expanding their outsourcing share most rapidly.
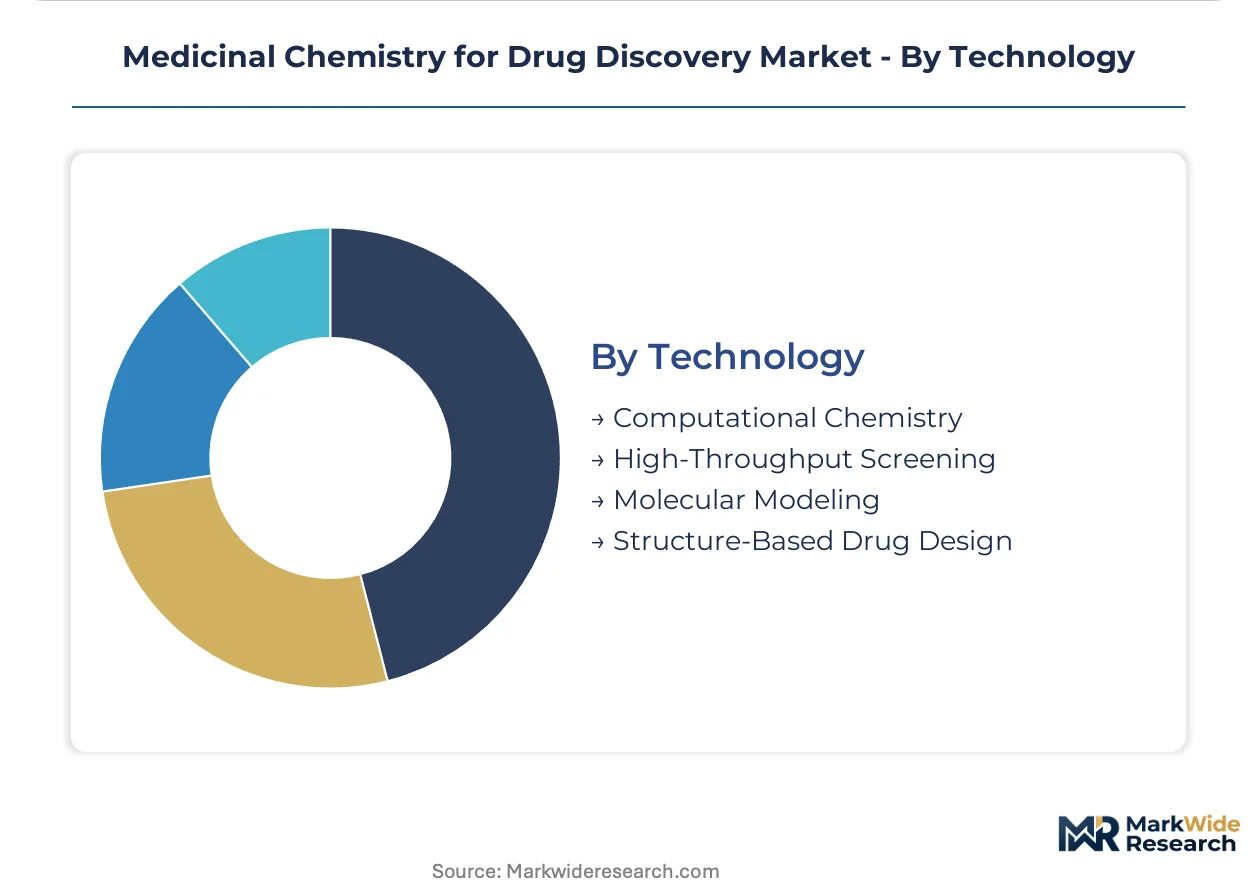
Technology:
Computational integration displaces empirical workflows while screening platforms retain specialized niches.
- Computational Chemistry:Machine learning-driven retrosynthesis and generative molecular design compress library enumeration timelines. AI-augmented platforms require traditional medicinal chemists to acquire cheminformatics and molecular dynamics simulation competencies. Eurofins Scientific deploys European laboratory networks to anchor integrated discovery programs combining computational and experimental capabilities.
- Structure-Based Drug Design:Crystallography-informed scaffold optimization commands premium pricing for difficult targets with resolved protein structures.
- High-Throughput Screening:Empirical library testing contracts face displacement by algorithm-driven synthesis prioritization.
- Molecular Modeling:Docking and free energy perturbation studies support lead optimization decision-making.
Computational chemistry platforms manage the broadest target coverage; structure-based methods are gaining adoption fastest among specialized CROs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States exhibit the lowest price elasticity as FDA accelerated approval pathways compress development timelines, while Indian and Chinese sponsors negotiate aggressively on synthesis costs despite equivalent technical specifications.
United States
FDA priority review vouchers and breakthrough therapy designations drive premium pricing for hit-to-lead optimization services across Boston and San Francisco biotech clusters. The agency's novel chemical entity pathway mandates documented synthetic routes and impurity profiling that elevate compliance costs. Cambridge, Massachusetts anchors the highest concentration of outsourced medicinal chemistry procurement as venture-backed firms unbundle discovery programs.
Germany
EMA quality guidelines for investigational medicinal products and REACH chemical safety requirements shape synthetic route selection for developers targeting European approval. The country's national pharmaceutical regulator enforces stringent environmental fate assessments that extend preclinical documentation timelines. Frankfurt and Munich host specialized CROs serving mid-cap biotechnology sponsors seeking EU market access.
India
CDSCO regulatory harmonization with ICH standards positions Indian synthesis providers to capture Western biotech outsourcing for complex modalities including RNA-based therapeutics. The country's national pharmaceutical regulator has streamlined approval pathways for investigational medicinal products manufactured domestically. Hyderabad and Bangalore clusters specialize in phosphoramidite chemistry and oligonucleotide conjugation capabilities.
China
NMPA conditional approval pathways for innovative chemical entities incentivize investment in differentiated scaffold development despite pricing pressure on standard synthesis services. The national medical products administration mandates pharmacovigilance documentation that elevates vendor qualification burdens. Shanghai and Suzhou industrial parks concentrate flow chemistry automation and biocatalytic transformation capabilities.
Switzerland
Swissmedic accelerated assessment procedures for new molecular entities sustain demand for high-purity preclinical candidate nomination exceeding 95% thresholds. The national pharmaceutical regulator emphasizes quality-by-design principles that shape analytical method development contracts. Basel anchors integrated discovery programs combining computational chemistry with specialized synthesis infrastructure.
Medicinal Chemistry for Drug Discovery Market Competitive Landscape
Capability concentration sits with European and North American specialists possessing integrated biology-chemistry platforms; scale advantage sits with Asia-Pacific providers commanding multi-ton manufacturing infrastructure. The market structures around three tiers: full-service discovery CROs, specialized synthesis boutiques, and technology-integrated platform operators. Consolidation pressure intensifies as biotechnology sponsors unbundle procurement across multiple vendors rather than awarding integrated contracts. Dominant competitive moves include captive access to genetically modified models and backward integration into analytical instrumentation.
Within the full-service discovery tier, Eurofins Scientific, Charles River Laboratories, and WuXi AppTec exemplify divergent geographic and capability positioning. Eurofins Scientific represents European laboratory network consolidation for high-margin integrated programs. Charles River Laboratories occupies a position defined by captive model access accelerating candidate validation timelines. WuXi AppTec anchors Asia-Pacific scale advantages extending from discovery chemistry through commercial supply.
| Leading Market Players |
|---|
| Eurofins Scientific |
| Charles River Laboratories |
| WuXi Apptec |
| Evotec SE |
| Thermo Fisher Scientific Inc. |
| Labcorp Drug Development |
| Certara |
| Piramal Pharma Solutions |
| Genscript Biotech Corporation |
| Others |
Supply & Pricing Matrix
Hyderabad's phosphoramidite synthesis clusters anchor global capacity for RNA-based therapeutic chemistry, translating concentrated technical infrastructure into pricing power for complex oligonucleotide programs. Contract Research Organizations in this hub command premium rates for antisense and siRNA modalities as Western biotech sponsors face limited alternative suppliers with equivalent regulatory track records.
Pricing Analysis
Extended analytical service contracts and milestone-based synthesis modules generate the dominant lifetime value streams in medicinal chemistry outsourcing. Project-based pricing stratifies across premium, standard, and economy tiers differentiated by purity thresholds and regulatory documentation depth. Cost compression in standard small-molecule synthesis is intensifying because Asia-Pacific providers expand aqueous route capabilities. Biotechnology firms exhibit the highest price sensitivity as venture-backed sponsors optimize capital deployment, while large pharmaceutical companies prioritize speed over unit cost for accelerated FDA pathways.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for isotope-labeled reference standards and specialized chromatography consumables. Manufacturing concentration in India, China, and Switzerland feeds global demand for high-purity preclinical candidates and investigational medicinal products. Deuterium and carbon-14 labeling materials, phosphoramidite monomers, and enantioselective catalysts constitute critical input dependencies. Single-source vulnerability for radiolabeled compounds creates procurement fragility. Distribution runs through qualified vendor networks with documented synthetic routes for regulatory submission.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medicinal chemistry for drug discovery sits in early-cycle expansion as artificial intelligence integration in molecular design drives adoption velocity beyond traditional empirical workflows. RNA-based therapeutic demand and green chemistry mandates create sustained tailwinds for specialized capability investment.
For Market Incumbents: Insulate margin position by deepening backward integration into analytical instrumentation and captive isotope supply chains. Consolidate around genetically modified model access to accelerate candidate validation timelines against emerging AI-native platform competitors. Prioritize certification investment for EMA quality guidelines and FDA accelerated approval pathway documentation.
For New Entrants and Emerging Players: Pursue white-space opportunities in India's CDSCO-harmonized regulatory environment for RNA-based therapeutic chemistry outsourcing. Target neurology applications with blood-brain barrier penetration specialization as large CROs underinvest in CNS-penetrant scaffold capabilities. Deploy machine learning-driven retrosynthesis platforms as the primary go-to-market angle for mid-cap biotechnology sponsors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform operators with computational-experimental integration and European regulatory access. Long-term viability hinges on sustained outsourcing intensity from capital-constrained biotechnology firms. Acquisition targets should display phosphoramidite synthesis capabilities or flow chemistry automation infrastructure. Watch FDA novel chemical entity submission volumes as the inflection signal for service provider utilization rates.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Platform Integration | Machine learning retrosynthesis compresses hit-to-lead timelines for biotechnology sponsors. |
| Green Chemistry Certification Program | EMA and EPA solvent guideline alignment streamlines regulatory authorization pathways. |
| Phosphoramidite Capacity Expansion | Antisense oligonucleotide demand outstrips qualified synthesis provider availability. |
| Backward Integration into Isotope Supply | Deuterium and carbon-14 labeling concentration creates input vulnerability for CROs. |
| Regulatory Documentation Service Launch | FDA and EMA impurity profiling mandates elevate compliance burden for discovery-stage sponsors. |
Research Methodology
A spread of perspectives from medicinal chemistry directors, regulatory affairs leads at contract research organizations, biotechnology procurement officers, and pharmaceutical R&D executives converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA novel chemical entity submissions, EMA quality guideline documentation, ClinicalTrials.gov protocol records, and SEC 10-K R&D expenditure disclosures. Bottom-up service provider revenue estimates and top-down pharmaceutical outsourcing budget allocations underwent iterative triangulation.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include molecular modality, therapeutic application, end-user cost tier, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating AI adoption velocity, CRO outsourcing intensity trends, and purity threshold escalation patterns. Forecast inputs encompassed CDSCO regulatory harmonization timelines and REACH chemical safety requirement implementation trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asia-Pacific synthesis providers or rapid FDA guideline revision would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market
Pharmaceutical Ingredients
Biologic Excipients Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Pharmaceutical Propellants Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Moxifloxacin Hcl (CAS 186826-86-8) Market
Pharmaceutical Ingredients
Pemetrexed Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Oridonin Market
Pharmaceutical Ingredients
Global Penicillin Drug Market
Pharmaceutical Ingredients
Antipyretic Analgesic Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Global Glycine Supplement Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
MEK Inhibitors Market
Pharmaceutical Ingredients
Casein and Casein Derivatives Market