
 Aircraft Cleaning Chemicals Market | 2026-2036
Aircraft Cleaning Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Cleaning Chemicals Market Analysis
Maintenance service contracts bundled with chemical replenishment is broadening what suppliers actually sell. PPG Industries Inc. leverages its aerospace coatings heritage to bundle cleaning systems with protective finishes. Henkel AG & Co. KGaA anchors its position through R&D intensity in sustainable surfactant chemistry. Ecolab Inc. competes via channel control across airline catering and ground services networks.
Aircraft cleaning chemicals encompass formulated solutions designed to remove contaminants from airframe surfaces, cabin interiors, turbine components, and flight control systems without degrading aluminum alloys, composites, or sealant materials; these products typically operate within pH ranges of 6-11 and meet flash-point thresholds above 38°C for hangar safety. Their primary purpose centers on preserving aerodynamic efficiency, preventing corrosion-induced airworthiness degradation, and ensuring passenger cabin hygiene standards. Exterior cleaners and de-icing agents represent the most mature revenue pools where pricing pressure from airline procurement departments has compressed margins, while concentrated formulations are gaining fastest as carriers seek to reduce logistics costs and plastic waste from packaging. Application through commercial airlines dominates volume given fleet sizes at legacy carriers, though private jets generate superior per-kilogram margins due to bespoke service expectations and lower price sensitivity.
The FAA mandates VOC content limits under 40 CFR 59 that directly restrict solvent selection in exterior cleaners, while EPA Significant New Alternatives Policy reviews shape acceptable active ingredients in interior disinfectants. REACH registration requirements in Europe force reformulation of legacy alkylphenol ethoxylates, creating compliance costs that favor suppliers with dedicated regulatory affairs teams. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as these compounds currently enable high-performance degreasers but face phase-out timelines that will demand substitute chemistry investments.
Market Dynamics
FAA tightening of VOC limits under 40 CFR 59 is forcing immediate reformulation of exterior cleaners across US commercial aviation, while concentrated chemistry gains traction as airlines consolidate MRO procurement around bulk supply contracts.
Growth Catalysts
- FAA VOC Limits:Regulatory pressure under 40 CFR 59 accelerates bio-based solvent adoption as carriers face ramp operation compliance deadlines.
- Concentrated Formulations:Logistics cost reduction and plastic waste elimination drive airline procurement departments toward high-dilution chemistry systems.
- US MRO Consolidation:Bulk purchasing power at integrated maintenance networks expands volume commitments for chemical suppliers.
Market Restraints
- Petrochemical Feedstock Volatility:Surfactant input costs fluctuate with crude oil derivatives, compressing margin stability for formulated product manufacturers.
- REACH Compliance Burden:European alkylphenol ethoxylate phase-outs impose registration costs that disadvantage smaller suppliers lacking dedicated regulatory affairs infrastructure.
- PFAS Substitution Gap:Pending restrictions on per- and polyfluoroalkyl substances threaten high-performance degreaser efficacy before viable chemistry replacements achieve commercial scale.
Strategic Opportunities
- India Fleet Expansion:IndiGo and Air India's narrow-body growth creates untapped demand for exterior wash programs at emerging maintenance hubs.
- Electrostatic Application Systems:Converging automation hardware with precision dosing chemistry enables material savings and labor reduction in hangar operations.
- EU Green Deal Procurement Mandates:Sustainable chemistry preferences in public-tendered ground handling contracts favor bio-based certification holders.
Industry Challenges
- Surfactant Chemist Talent Scarcity:Specialized formulation expertise for aerospace-compatible bio-solvents remains concentrated at legacy suppliers, constraining new entrant R&D velocity.
- Multi-Jurisdiction Certification Lag:Simultaneous FAA, EASA, and CAAC approvals for reformulated products extend time-to-revenue by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Cleaning Chemicals Market |
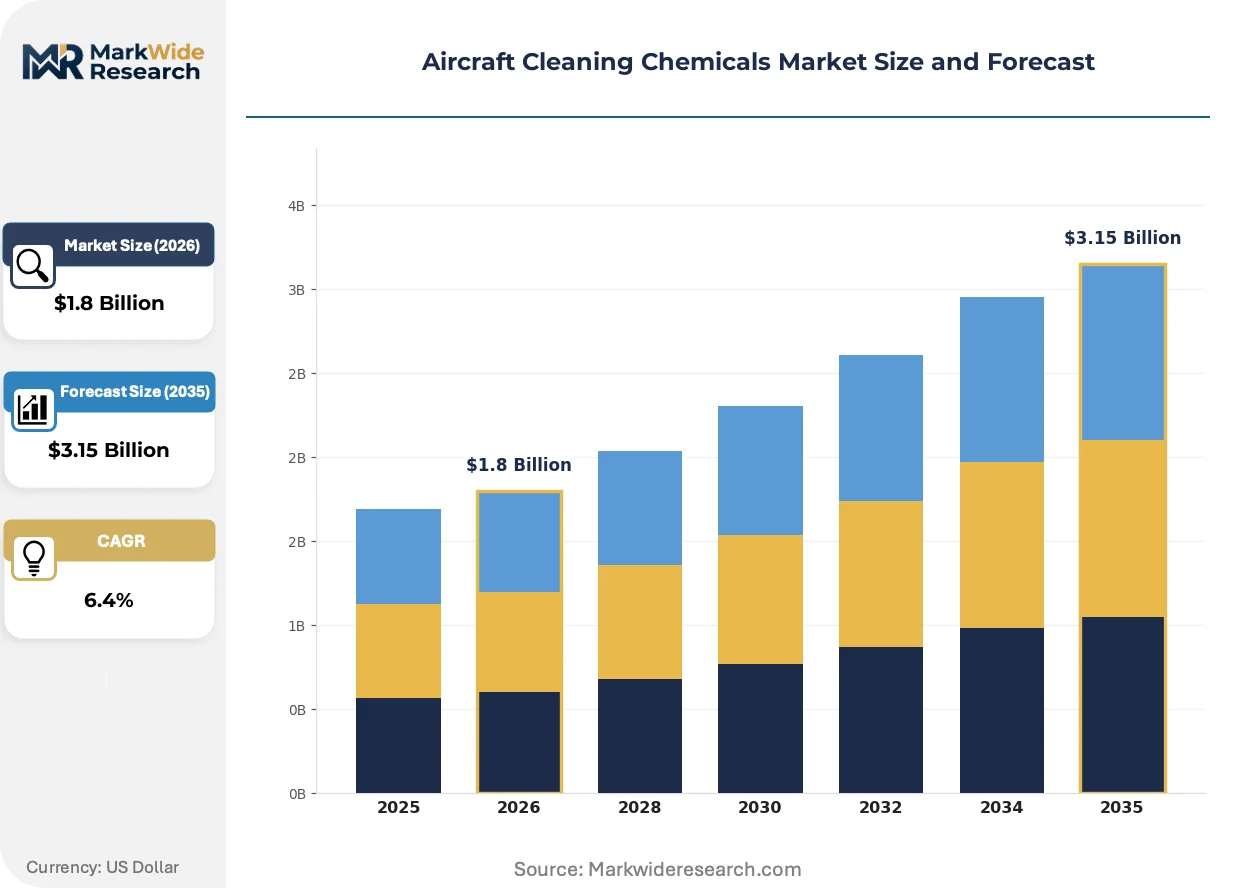
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exterior Cleaners, Interior Cleaners, De-icing Agents, Engine Cleaners Application: Commercial Airlines, Private Jets, Military Aircraft, Helicopters Formulation: Liquid, Powder, Gel, Concentrated Packaging Type: Drums, Bottles, Pails, Sachets |
| Companies Covered | PPG Industries Inc., Illinois Tool Works Inc., Callington Haven Pty Ltd., Arrow Solutions, McGean-Rohco Inc., Nuvite Chemical Compounds, Henkel AG & Co. KGaA, DASIC International Ltd, Ecolab Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Cleaning Chemicals Market Emerging Trajectories
Active chemistry is converging with application hardware as suppliers bundle dosing systems with formulated products, while regulatory pressure on legacy solvents accelerates substitution timelines.
Enzymatic cleaning chemistry is converging with automated spray systems to enable cold-water degreasing of turbine components without thermal energy inputs. Regional carriers with limited hangar infrastructure adopt these systems fastest. The technology is converging with predictive maintenance software to trigger cleaning cycles based on flight-hour accumulation rather than calendar schedules.
EPA Significant New Alternatives Policy reviews are reshaping acceptable active ingredients in interior disinfectants used during cabin turnaround operations. Airlines operating trans-Pacific routes face dual compliance with US and Chinese sanitation standards. Wide-body fleet operators at Delta and United report extended product qualification timelines as they await SNAP determinations on emerging quaternary ammonium alternatives.
Service unbundling now separates chemical supply from application labor in ground handling contracts at major US hubs. Legacy bundled agreements at American and Southwest are giving way to itemized procurement where airlines source chemistry directly. This pattern is most visible at Atlanta and Dallas-Fort Worth, where third-party applicators compete purely on labor efficiency while carriers optimize chemical unit economics through direct supplier negotiation.
Aircraft Cleaning Chemicals Market Segmentation
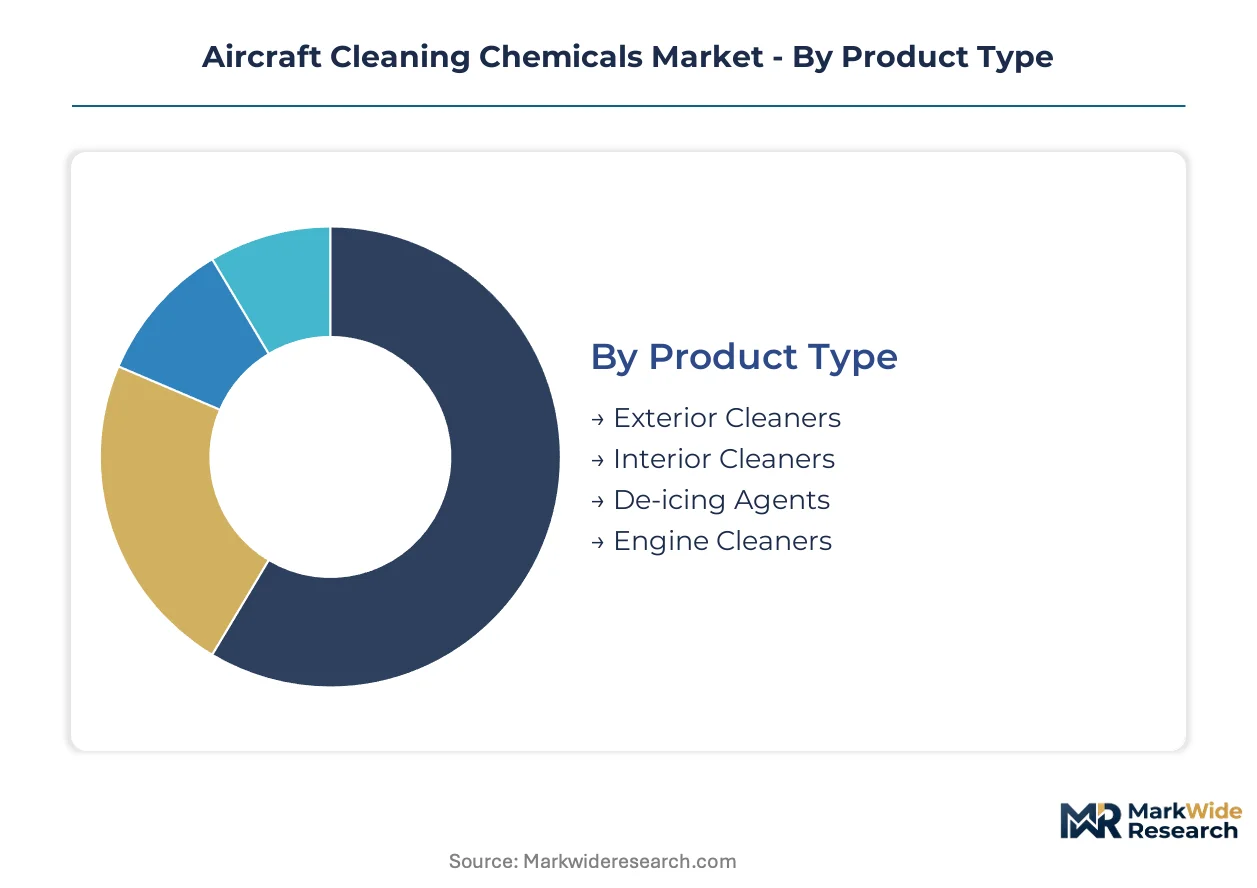
Segmentation in aircraft cleaning chemicals reveals divergent margin structures and procurement patterns across product chemistry and end-use platforms. Each dimension exposes distinct regulatory sensitivities and customer concentration profiles that shape supplier strategy.
Product Type:
Airline procurement departments prioritize chemistry efficacy against specific contaminant types and substrate compatibility when selecting formulations.
- Exterior Cleaners:Formulated solutions remove hydrocarbon deposits, exhaust streaking, and atmospheric oxidation from aluminum skins and composite radomes while maintaining pH neutrality to protect anodized finishes. Demand concentrates at legacy US carriers operating large narrow-body fleets under FAA 40 CFR 59 VOC compliance deadlines, where bulk procurement contracts now specify bio-based solvent content minimums.
- Interior Cleaners:Cabin-grade disinfectants and surface degreasers target food residue, biological contaminants, and passenger contact surfaces without degrading thermoplastic olefin seat covers or polycarbonate window surrounds. Private jet operators in the United States generate superior per-kilogram margins due to bespoke service expectations and lower price sensitivity compared to commercial fleet procurement.
- De-icing Agents:Glycol-based and acetate-formulated fluids prevent ice accretion on flight control surfaces and engine inlets.
- Engine Cleaners:High-alkaline or solvent-based degreasers remove carbon deposits and lubricant residue from turbine hot sections and compressor blades.
Exterior cleaners lead on scale; interior cleaners lead on momentum.
Application:
Platform-specific airworthiness requirements and operating cost structures drive divergent chemical consumption patterns.
- Commercial Airlines:High-frequency turnaround operations at hub airports consume bulk volumes of exterior wash chemicals and cabin disinfectants, with procurement centralized at airline headquarters under sustainability mandates. US network carriers at Atlanta and Dallas-Fort Worth drive concentrated demand for concentrated formulations that reduce plastic waste and logistics costs.
- Private Jets:Low-volume, high-touch service models prioritize premium formulations with rapid dry times and minimal residue for passenger cabin aesthetics. Fractional ownership fleets operated from Teterboro and Van Nuys specify boutique chemical brands that differentiate service levels.
- Military Aircraft:Specialized corrosion prevention and camouflage removal chemistry for tactical platforms.
- Helicopters:Rotor blade leading edge cleaners and transmission degreasers for vertical flight operations.
Commercial airlines dominate volume throughput; private jets dominate margin capture.
Formulation:
Logistics economics and dilution infrastructure availability determine carrier preference between ready-to-use and concentrated chemistry systems.
- Liquid:Ready-to-pour solutions dominate ramp operations where dilution equipment is unavailable and speed of application is critical. Regional carriers with limited hangar infrastructure rely on pre-mixed liquids for exterior washing during quick turns.
- Concentrated:High-dilution ratios of 20:1 to 100:1 enable bulk tanker delivery and on-site blending, eliminating plastic packaging waste and reducing transport costs by over 80 percent. US MRO consolidation at integrated maintenance networks accelerates adoption as procurement departments negotiate multi-year supply contracts.
- Powder:Lightweight solid formulations for remote deployment where liquid transport is impractical.
- Gel:Thickened chemistry for vertical surface cling and extended contact time on soiled substrates.
Liquid formulations lead on installed base; concentrated chemistry leads on adoption velocity.
Packaging Type:
Handling infrastructure and consumption rate determine optimal container format selection across maintenance environments.
- Drums:55-gallon steel and polyethylene containers serve high-throughput MRO facilities with dedicated chemical storage and pumping systems. Major US airline maintenance bases at Charlotte and Chicago consume drum quantities for scheduled C-check cleaning programs.
- Bottles:Trigger-spray and pour-cap containers enable precise application for spot cleaning and detail work. Line maintenance crews at congested gates prefer portable bottles for ad hoc stain removal during minimum ground time intervals.
- Pails:Five-gallon open-head containers for intermediate volume operations without drum handling equipment.
- Sachets:Single-use water-soluble pouches for emergency deployment and remote field operations.
Drums lead on commercial airline procurement volume; bottles lead on flexibility requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates bulk procurement power through MRO consolidation, while Germany anchors European regulatory compliance investments. Fleet expansion in India and aftermarket growth in Brazil are reshaping regional demand patterns.
United States
Legacy carriers at Atlanta and Dallas-Fort Worth drive concentrated demand for exterior wash programs and cabin disinfectants. FAA 40 CFR 59 VOC limits force immediate reformulation of solvent-based cleaners. Chicago and Charlotte maintenance bases consume drum quantities for scheduled C-check cleaning programs.
Germany
Lufthansa Technik's integrated maintenance networks generate sophisticated chemical specification requirements for turbine component cleaning. REACH registration requirements impose compliance costs that favor suppliers with dedicated regulatory affairs teams. Hamburg and Frankfurt hubs concentrate procurement for narrow-body and wide-body fleet maintenance.
India
IndiGo and Air India's narrow-body growth creates untapped demand for exterior wash programs at emerging maintenance hubs. The country's national aviation regulator aligns with ICAO standards while enforcing local environmental clearance for chemical storage facilities. Delhi and Mumbai maintenance clusters are expanding hangar capacity to accommodate fleet growth.
United Kingdom
Heathrow and Gatwick ground handling operations prioritize rapid-turnaround cabin disinfection chemistry for high-frequency short-haul fleets. UK REACH divergence from EU regulations creates parallel compliance pathways for active ingredient registration. London maintenance bases specialize in premium private jet detailing services with bespoke formulation requirements.
Brazil
GOL and LATAM fleet utilization rates sustain steady consumption of de-icing agents and exterior cleaners for tropical humidity corrosion prevention. ANVISA reviews active ingredients in cabin disinfectants alongside environmental licensing for chemical distributors. São Paulo and Rio de Janeiro maintenance hubs serve as distribution nodes for South American airline procurement.
Aircraft Cleaning Chemicals Market Vendor Landscape
Top-tier vendors anchor concentrated supply relationships with legacy carriers, while mid-tier specialists compete on regulatory agility and formulation customization. The market structure favors incumbents with established aerospace certification portfolios and multi-jurisdiction approval capabilities. Three archetypes dominate: diversified chemicals conglomerates with aerospace divisions, dedicated aviation maintenance chemistry specialists, and industrial cleaning formulators adapting product lines for aircraft compatibility. M&A activity targets regional distributors with FAA and EASA approval portfolios, while capacity expansion concentrates in US Gulf Coast and German chemical manufacturing clusters.
Within the diversified chemicals tier, PPG Industries Inc. and Henkel AG & Co. KGaA exemplify players leveraging broad formulation expertise across coatings and adhesives into adjacent cleaning chemistry. Ecolab Inc. occupies a position representing channel control strategies that bundle chemical supply with service delivery infrastructure. These three companies anchor competitive positioning through distinct vectors: aerospace heritage, sustainable surfactant R&D intensity, and ground services network integration respectively.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| Illinois Tool Works Inc. |
| Callington Haven Pty Ltd. |
| Arrow Solutions |
| McGean-Rohco Inc. |
| Nuvite Chemical Compounds |
| Henkel AG & Co. KGaA |
| DASIC International Ltd |
| Ecolab Inc. |
| Others |
Supply Flow & Price Mechanics
Specialized surfactant chemist concentration in Germany's Rhineland chemical corridor creates labor-cost differentials that widen pricing-tier spreads between premium bio-based formulations and commodity solvent blends. US Gulf Coast production clusters leverage feedstock proximity to compress standard-tier margins while FAA compliance investments sustain premium pricing for 40 CFR 59-certified chemistry.
Pricing Analysis
Capacity additions in US Gulf Coast petrochemical corridors are reshaping price floors for standard-grade exterior cleaners while REACH compliance investments in Europe sustain premium tiers for alkylphenol ethoxylate-free formulations. Three-tier pricing structure across premium, standard, and economy levels separates bio-certified aviation chemistry from legacy solvent blends and bulk undifferentiated commodities. Pricing pressure stems from airline procurement consolidation at integrated MRO networks demanding volume discounts on concentrated formulations. Commercial fleet operators exhibit highest price sensitivity due to bulk consumption economics, while private jet operators accept premium markups for rapid-dry cabin aesthetics.
Supply Chain Analysis
Reverse-logistics flows for empty drum returns and spent solvent recovery create cost recovery opportunities that subsidize forward distribution economics for concentrated chemistry systems. Manufacturing concentration centers on Germany, the United States, and China, with surfactant synthesis anchored in the Rhineland and Gulf Coast corridors. Raw material dependencies include palm-derived fatty alcohols, petroleum-based glycol ethers, and specialty amine neutralizers. Single-source vulnerability persists for aerospace-certified bio-solvent precursors where limited fermentation capacity constrains alternative supply. Distribution runs through integrated MRO procurement networks and third-party ground handling service providers at major hub airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play between REACH compliance costs in Europe and feedstock-access advantages on the US Gulf Coast, with regulatory divergence creating sustainable margin premiums for dual-certified suppliers.
For Market Incumbents: Lock in multi-year supply contracts with consolidated US MRO networks before bio-based formulation patents expire and generic competitors erode premium positioning. Deepen backward integration into specialty surfactant production to insulate margin structures from petrochemical feedstock volatility. Prioritize CAAC approval investments to capture IndiGo and Air India fleet expansion chemistry demand. For New Entrants and Emerging Players: Begin with enzymatic cold-water degreasing systems for regional carriers lacking thermal infrastructure, where application-hardware bundling creates switching costs against established solvent suppliers. Target India's emerging maintenance hubs at Delhi and Mumbai for exterior wash program contracts. Pursue EU Green Deal certification to access public-tendered ground handling contracts with sustainable chemistry mandates. For Investors and Strategic Acquirers: Diversified chemicals conglomerates with aerospace divisions represent the most active acquirer category in this space, seeking regulatory approval portfolios to shortcut 18-24 month FAA-EASA certification timelines. Long-term viability hinges on PFAS substitution chemistry investments as pending restrictions threaten legacy degreaser revenue streams. Monitor EPA SNAP determination timelines for quaternary ammonium alternatives as inflection indicators for interior disinfectant reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Synthesis | Captive supply of bio-based alkyl polyglucosides insulates Henkel and PPG from palm oil price volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous FAA, EASA, and CAAC approvals compress competitor entry timelines by 18-24 months. |
| Electrostatic Application System Partnership | Hardware-chemistry bundling at Delta and United maintenance bases locks in material-throughput commitments. |
| Concentrated Formulation Capacity Expansion | Bulk tanker delivery infrastructure at Atlanta and Dallas-Fort Worth eliminates plastic packaging waste costs. |
| PFAS-Free Chemistry R&D Program | Preemptive substitution investments address pending EPA restrictions on per- and polyfluoroalkyl substances. |
Methodological Framework
Bottom-up airline fleet modeling reconciled against top-down chemical manufacturer production tracking forms the analytical core of this study. Primary interviews with MRO procurement directors, airline sustainability officers, surfactant R&D chemists, and ground handling operations managers combined with secondary validation against FAA 40 CFR 59 filings, EPA SNAP determinations, ECHA REACH registrations, and customs trade data for glycol ether and fatty alcohol imports. Triangulation across these sources reconciles volume assumptions with supply-side capacity disclosures.
Historical trendline analysis of exterior wash program frequency, cabin disinfection cycles per flight hour, and concentrated formulation adoption rates established baseline consumption coefficients across the projection horizon. Segmentation modeling incorporated product chemistry tier, end-use platform, formulation concentration ratio, and regional regulatory cluster dimensions. CAGRs were derived from fleet expansion schedules, MRO consolidation patterns, and bio-based substitution elasticity estimates. Industry-specific inputs included turbine component cleaning cycle intervals and private jet detailing service intensity benchmarks.
Several conditions sit outside the modeled scope, including military aircraft chemistry demand, helicopter rotor maintenance programs, and emergency de-icing fluid spot market volatility. Forecasts reflect assumptions about FAA VOC limit enforcement timelines and REACH alkylphenol ethoxylate phase-out adherence. Practitioners should monitor EPA SNAP determination announcements, CAAC certification reciprocity agreements, and Indian environmental clearance processing delays for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Fine Chemicals Market
Chemicals
Latin America Construction Chemicals Market
Chemicals
Rocket Propellant Chemicals Market
Chemicals
Xanthates Market
Chemicals
Asia-Pacific Gamma Butyrolactone Market
Chemicals
Roofing Chemical Market
Chemicals
Non PVC Plasticizers Market
Chemicals
P-Hydroxybenzoic Acid (PHBA) Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
Diethyl Sulfate Market
Chemicals
Asia-Pacific Construction Chemicals Market
Chemicals
North America Methanol Market
Chemicals
5 Dinitroaniline Market
Chemicals
Global Commodity Chemicals Market
Chemicals
Monoisopropanolamine (MIPA) Market
Chemicals
Flooring Chemicals Market