
 Triisopropanolamine (TIPA) Market | 2026-2036
Triisopropanolamine (TIPA) Market Size, Share, and Industry Trends Forecast 2026-2036
Triisopropanolamine (TIPA) Market Analytics
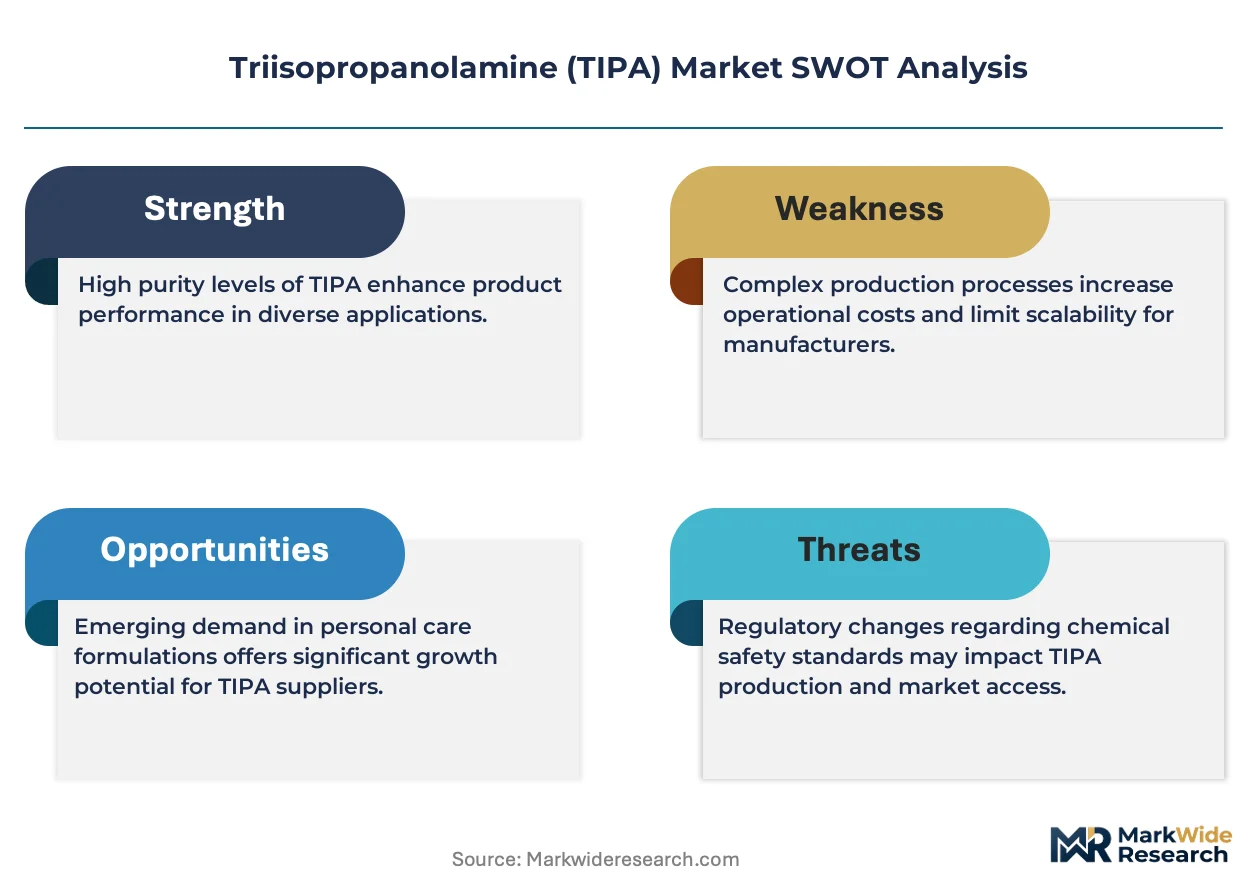
REACH registration thresholds for amine-based intermediates are expanding the cost-of-entry calculus for TIPA producers serving European coatings and detergent channels. BASF leverages integrated ethylene oxide and amine production assets to sustain margin structures across multiple alkanolamine grades. DowDuPont anchors its position through controlled access to propylene oxide feedstock streams in North American Gulf Coast corridors. Huntsman competes on specialized high-purity TIPA variants for pharmaceutical and personal care applications where residual impurity limits are most stringent.
Triisopropanolamine is a tertiary alkanolamine with the molecular formula C9H21NO3, synthesized through the catalytic amination of isopropanol with ammonia under elevated temperature and pressure; its hydroxyl and amine functional groups confer chelating, neutralizing, and emulsifying properties that make it valuable in cement grinding aids, metalworking fluids, and cosmetic formulations. TIPA grades within the Product Type category command the deepest margin pools due to their superior performance in reducing cement particle agglomeration compared to mono- and di-substituted analogues. Surfactant and Coatings applications are absorbing disproportionate volume growth as waterborne formulation technologies displace solvent-based systems across industrial and architectural end uses.
EPA oversight under the Toxic Substances Control Act governs new chemical notifications for modified TIPA derivatives in U.S. industrial channels, while REACH Annex XIV authorization requirements constrain certain amine catalyst uses in European consumer-facing products. China's SAMR enforces GB standards for chemical purity in domestically distributed personal care and detergent inputs, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor the trajectory of green chemistry procurement mandates from major cement and coatings formulators, as these specifications will determine which purification and certification investments yield sustainable competitive position.
Market Dynamics
Construction chemistry standards tightening across major cement-producing regions are forcing TIPA producers to reformulate grinding aid compositions, elevating purity specifications and compressing margins for commodity-grade suppliers.
Growth Catalysts
- Cement grinding aid demand:China's infrastructure buildout and India's housing expansion are consuming record volumes of high-purity TIPA for particle dispersion in Portland cement manufacturing.
- REACH Annex XIV authorization:European restrictions on competing amine catalysts are redirecting coatings formulators toward TIPA as a compliant alternative in waterborne systems.
- Metalworking fluid reformulation:Synthetic cutting fluid manufacturers are substituting ethanolamines with TIPA to achieve extended sump life and reduced cobalt leaching in aerospace machining operations.
Market Restraints
- Propylene oxide feedstock volatility:Gulf Coast propylene oxide supply disruptions transmit directly to TIPA production economics, squeezing margin structures for non-integrated producers.
- Monoethanolamine substitution threat:Cost-conscious cement additive blenders in emerging markets are reverting to MEA formulations despite inferior grinding efficiency.
- ECHA registration cost burden:REACH data requirements for 1,000+ tonnage bands are deterring mid-scale Asian exporters from European market entry.
Strategic Opportunities
- Pharmaceutical-grade TIPA:FDA-compliant high-purity variants for parenteral drug formulations command 3-4x commodity margins with limited qualified suppliers.
- Personal care surfactant channels:Korean and Japanese cosmetic formulators are specifying TIPA for mild amphoteric surfactant synthesis in premium skincare lines.
- EU Green Deal chemistry mandates:Renewable feedstock certification schemes are creating preferential procurement pathways for bio-based TIPA producers.
Industry Challenges
- Specialized amination engineering talent:Catalytic process optimization for selective tri-substitution requires expertise concentrated among retiring European and North American specialists.
- Multi-jurisdiction certification timelines:Simultaneous EPA PMN, REACH registration, and China NMPA filing processes extend commercialization cycles by 18-24 months for new TIPA derivatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triisopropanolamine (TIPA) Market |
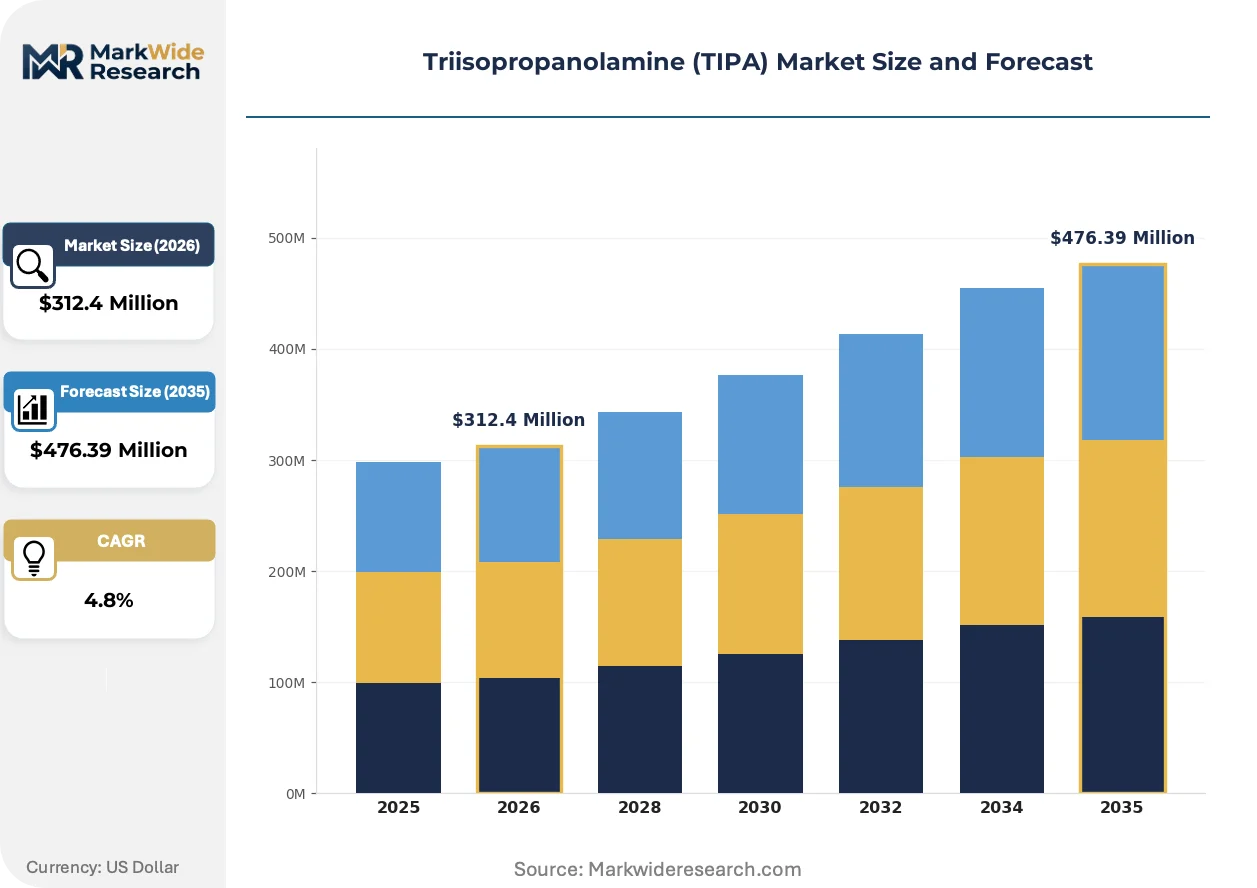
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TPA, TIPA, IPTA, DIPA Application: Detergents, Personal Care, Coatings, Surfactants End Use Industry: Agriculture, Pharmaceuticals, Cosmetics, Textile Distribution Channel: Online, Wholesale, Retail, Direct Sales |
| Companies Covered | BASF, DowDuPont, Huntsman, Ashland, Nanjing Hongbaoli, Changzhou Yuping Chemical, Horizon Chemical, Eastman Chemical Company, INEOS Group Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triisopropanolamine (TIPA) Market Evolving Landscape
Process intensification and green chemistry certification are converging to reshape how TIPA manufacturers compete on cost, compliance, and carbon footprint simultaneously.
Continuous flow amination reactor technology is electrifying conventional batch production economics. German and Dutch engineering firms are deploying modular skid-mounted systems that halve solvent usage and enable real-time purity monitoring. This platform is compressing capital requirements for entry-scale producers while raising the bar for quality consistency in pharmaceutical-grade supply.
REACH Annex XVII restrictions on N-nitrosamine formation in cosmetic applications are forcing TIPA suppliers to demonstrate sub-ppm impurity profiles. ECHA guidance documents issued in 2023 have triggered reformulation investments across European personal care contract manufacturers. The response has concentrated sourcing decisions toward integrated producers with in-house analytical capabilities.
Buyer consolidation among multinational cement additive houses is compressing supplier negotiation cycles. Procurement teams at BASF, Dow, and regional champions are unbundling technical service from material supply, forcing TIPA vendors to compete on delivered cost alone in commodity segments. This pattern is most visible in China, where domestic grinding aid formulators have consolidated from 200+ entities to under 50 major accounts.
Triisopropanolamine (TIPA) Market Segmentation
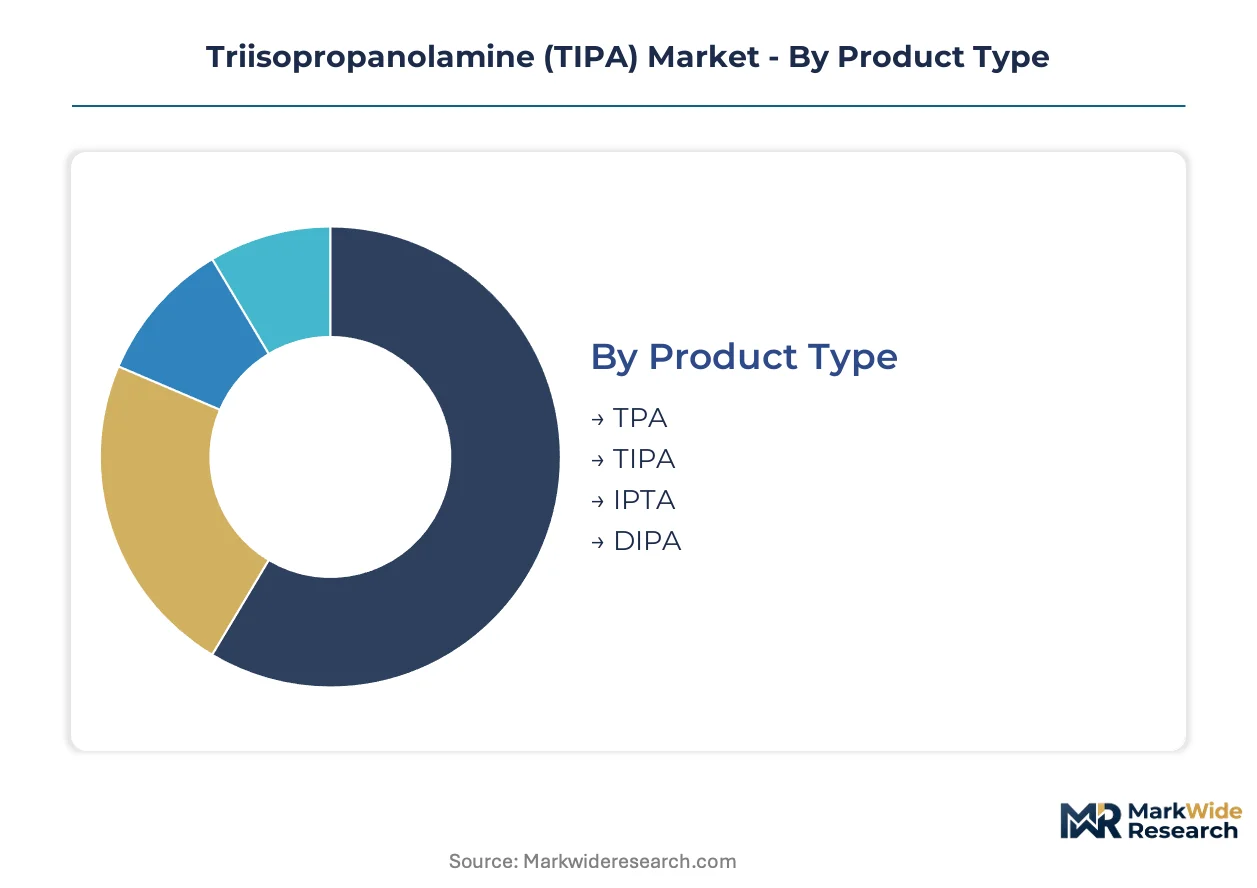
Segmentation in the TIPA market reveals how capital requirements, regulatory thresholds, and end-use performance demands fragment supply strategies across distinct customer clusters. Understanding these divisions exposes where margin pools concentrate and which purification investments yield sustainable differentiation.
Product Type:
Capital intensity varies sharply across amination stages, with tri-substituted variants demanding the most sophisticated catalytic engineering and quality assurance infrastructure.
- TIPA:Full tri-substitution delivers superior chelating capacity for cement particle dispersion, commanding premium positioning in construction chemistry formulations where grinding efficiency standards are tightening most visibly in China and India.
- DIPA:Di-substituted grades occupy mid-tier metalworking and surfactant applications; residual monoamine content constrains their deployment in pharmaceutical and personal care channels where FDA and EMA impurity limits apply.
- TPA:Technical-grade mono-substituted material serves cost-sensitive industrial neutralization with lower purity thresholds.
- IPTA:Isopropanolamine variants address niche emulsifier synthesis in specialty coatings with limited volume traction.
TIPA absorbs the bulk of installed capacity; DIPA is expanding most quickly as metalworking fluid formulators seek ethanolamine alternatives.
Application:
Customer procurement patterns split between specification-driven industrial buyers and formulation-flexible consumer goods manufacturers.
- Cement Grinding Aids:The largest volume sink, where TIPA reduces electrostatic agglomeration in Portland cement milling; Chinese infrastructure buildout and Indian housing expansion are absorbing record shipments.
- Surfactants:Waterborne system displacement of solvent-based coatings is redirecting volume toward amphoteric surfactant synthesis for architectural and industrial finishes.
- Coatings:REACH Annex XIV restrictions on competing amine catalysts are redirecting European formulators toward TIPA-compliant alternatives.
- Personal Care:Korean and Japanese cosmetic manufacturers specify high-purity grades for mild surfactant synthesis in premium skincare lines.
- Detergents:Concentrated liquid formulations utilize TIPA as a pH buffer and hydrotrope in household and industrial cleaning products.
Cement grinding aids dominate current offtake; surfactant applications are climbing the fastest as waterborne technology gains share.
End Use Industry:
Regulatory jurisdiction determines which purity certifications gate market access, with pharmaceutical and cosmetic channels imposing the steepest compliance burdens.
- Construction:Cement additive houses in China, India, and Vietnam specify TIPA for clinker grinding efficiency; procurement consolidation from 200+ domestic formulators to under 50 major accounts is compressing supplier negotiation leverage.
- Pharmaceuticals:Parenteral drug formulations demand FDA-compliant high-purity variants with 3-4x commodity margins and limited qualified supplier pools.
- Cosmetics:ECHA Annex XVII N-nitrosamine guidance is forcing sub-ppm impurity demonstrations across European personal care contract manufacturing.
- Textile:Fiber processing and dye leveling applications utilize TIPA as a pH regulator and dispersant with moderate purity requirements.
- Agriculture:Pesticide emulsifier and adjuvant formulations represent a price-sensitive outlet for technical-grade material.
Construction channels anchor volume consumption; pharmaceutical applications deliver the steepest margin expansion trajectory.
Distribution Channel:
Supply chain configuration tracks customer scale and technical service requirements, with direct relationships dominating specification-intensive segments.
- Direct Sales:Integrated producers maintain captive relationships with multinational cement additive houses and pharmaceutical contract manufacturers requiring technical support and certificate-of-analysis documentation.
- Wholesale:Regional distributors aggregate demand from mid-scale coatings and detergent formulators across fragmented European and Asian markets.
- Online:E-procurement platforms serve small-batch researchers and specialty chemical traders with standardized technical-grade material.
- Retail:Limited traction for consumer-facing TIPA products; primarily serves hobbyist and artisanal formulator niches.
Direct sales capture the majority of value; wholesale channels are gaining share fastest as regional coatings formulators consolidate purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the dominant share of TIPA consumption as cement grinding aid formulators scale capacity to serve infrastructure and housing construction. Indian demand is accelerating fastest among major economies as clinker production expands to meet urbanization targets. Regulatory divergence across major jurisdictions is fragmenting compliance pathways for multinational suppliers.
China
Cement additive manufacturers in Jiangsu and Shandong provinces consume record TIPA volumes for Portland cement particle dispersion. SAMR enforces GB standards for chemical purity in domestically distributed personal care and detergent inputs. The Yangtze River Delta cluster hosts integrated alkylolamine producers serving both local construction chemistry houses and export-oriented surfactant manufacturers.
India
Housing expansion and commercial infrastructure buildout are driving clinker grinding capacity additions across Gujarat and Maharashtra. BIS certification requirements for construction chemicals are elevating purity specifications for imported TIPA grades. The Delhi-Mumbai Industrial Corridor concentration of cement plants is absorbing disproportionate volumes of high-purity material for premium-grade cement production.
United States
Metalworking fluid reformulation in aerospace machining centers is substituting ethanolamines with TIPA for extended sump life. EPA oversight under the Toxic Substances Control Act governs new chemical notifications for modified TIPA derivatives in industrial channels. Gulf Coast propylene oxide supply corridors anchor integrated production economics for domestic alkanolamine manufacturers.
Germany
Waterborne coatings formulators are redirecting volume toward TIPA as REACH Annex XIV restrictions constrain competing amine catalysts. ECHA registration thresholds for amine-based intermediates are expanding the cost-of-entry calculus for suppliers serving European coatings and detergent channels. The North Rhine-Westphalia chemical cluster maintains specialized amination engineering expertise for pharmaceutical-grade production.
Japan
Cosmetic formulators specify high-purity TIPA grades for mild amphoteric surfactant synthesis in premium skincare lines. METI guidelines on green chemistry procurement are creating preferential pathways for bio-based feedstock certification. The Kansai region's personal care contract manufacturers are consolidating sourcing decisions toward integrated producers with in-house analytical capabilities.
Triisopropanolamine (TIPA) Market Competitive Landscape
Chinese producers anchor the volume-driven tier; European and North American specialists hold premium-grade positioning. The vendor base splits between integrated petrochemical majors with captive ethylene oxide and propylene oxide feedstock, and regional specialists competing on purification technology. Strategic archetypes include backward-integrated commodity suppliers, pharmaceutical-grade purity specialists, and regional construction-chemistry focused blenders. Capacity expansion and strategic partnerships dominate competitive moves as producers seek to secure feedstock access and regional market presence.
Within the integrated petrochemical tier, BASF and DowDuPont exemplify archetypes of feedstock-anchored competitiveness, while Huntsman occupies a position emphasizing specialized high-purity variants. Among Asia-Pacific-based suppliers, Nanjing Hongbaoli and Changzhou Yuping Chemical represent regional specialists serving domestic cement additive and surfactant channels. These company patterns illustrate how geographic feedstock access and end-use certification requirements stratify competitive positioning across the TIPA value chain.
| Leading Market Players |
|---|
| BASF |
| DowDuPont |
| Huntsman |
| Ashland |
| Nanjing Hongbaoli |
| Changzhou Yuping Chemical |
| Horizon Chemical |
| Eastman Chemical Company |
| INEOS Group Holdings |
| Others |
Value Network & Pricing Analysis
Sovereign-backed Chinese alkylolamine producers and family-owned German purification specialists anchor divergent pricing disciplines across the TIPA value chain, with feedstock integration determining margin resilience against propylene oxide volatility.
Pricing Analysis
Short lead-time premiums separate urgent pharmaceutical-grade orders from contracted cement-additive volumes. Three-tier pricing structure across pharmaceutical, industrial, and technical grades reflects certification burden and purity thresholds. Cost compression in commodity grinding-aid segments intensifies as Chinese procurement consolidation eliminates supplier negotiation leverage. Cement additive blenders exhibit highest price sensitivity; parenteral drug formulators accept substantial premiums for FDA-compliant documentation.
Supply Chain Analysis
Single-source vulnerability sits with Gulf Coast propylene oxide corridors that feed North American integrated producers. Manufacturing gravity centers on China, Germany, and the United States for differentiated grades. Propylene oxide, isopropanol, and catalytic amination expertise constitute critical input dependencies. Tariff exposure on Chinese technical-grade exports to Europe fragments regional sourcing strategies. Distribution runs through direct sales for specification-intensive pharmaceutical and cement-additive accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous flow amination technology is displacing legacy batch reactor platforms, compressing capital barriers for entrants while raising quality-consistency thresholds for incumbent certification maintenance.
For Market Incumbents: Cement backward integration into propylene oxide feedstock through Gulf Coast corridor partnerships or Chinese joint ventures to defend margin structures against monoethanolamine substitution threats. Prioritize pharmaceutical-grade certification investments to capture 3-4x commodity margin pools before European REACH Annex XIV authorization deadlines redirect coatings formulator sourcing.
For New Entrants and Emerging Players: Enter via modular continuous-flow reactor deployments serving Korean and Japanese cosmetic surfactant channels where METI green-chemistry procurement creates preferential bio-based certification pathways. Target Indian cement grinding-aid demand acceleration through BIS-certified technical partnerships with Gujarat and Maharashtra clinker producers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor European amination-engineering specialists with retiring technical talent and captive pharmaceutical-grade analytical capabilities. Long-term viability hinges on feedstock integration depth and multi-jurisdiction certification infrastructure completion. Monitor EPA PMN filing velocity for modified TIPA derivatives as inflection signal for innovation-cycle competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Gulf Coast propylene oxide corridor control insulates margin structures from feedstock volatility. |
| Green Manufacturing Transition | Bio-based feedstock certification unlocks METI preferential procurement pathways in Japanese cosmetic channels. |
| Capacity Expansion | Jiangsu and Shandong province additions capture Chinese infrastructure buildout cement-additive demand. |
| Long-term Supply Agreement | Direct sales relationships with consolidated cement additive houses secure volume commitments against spot competition. |
| Joint Venture | European-Asian pharmaceutical-grade partnerships accelerate EMA and NMPA dual-filing timelines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with catalytic process engineers, cement additive procurement leads, pharmaceutical contract manufacturing directors, and surfactant R&D heads combined with ECHA guidance documents, EPA TSCA notifications, SAMR GB standard publications, and SEC chemical-sector disclosures. Bottom-up volume estimates triangulated against top-down construction chemistry and personal care market sizing.
Granularity-level modeling applied product-type substitution dynamics, end-use industry purity requirements, and regional regulatory cluster divergence across the projection horizon. Segment-level CAGRs derived from cement grinding intensity indices, waterborne coatings displacement curves, and pharmaceutical parenteral formulation growth patterns. Forecast inputs incorporated REACH Annex XIV authorization timelines and Chinese dual-carbon policy implementation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under propylene oxide supply disruption scenarios and accelerated ethanolamine substitution in emerging-market cement channels. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Glycine Market
Chemicals
Potassium Alum Market
Chemicals
Acetophenone Market
Chemicals
Resorcinol Market
Chemicals
Flatting Agents Market
Chemicals
Acetic Ether Market
Chemicals
Carcinogenic Chemical Alternatives Market
Chemicals
Desalination Chemicals Market
Chemicals
Ferric Fluoride Market
Chemicals
Peroxyacetic Acid Market
Chemicals
Guanidine Carbonate Market
Chemicals
Aromatic Polyamine Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Flooring Chemicals Market
Chemicals
Zinc Chemicals Market
Chemicals
Bakers Ammonia Market